
 Anti-Aging Cosmetics Market | 2026-2036
Anti-Aging Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Aging Cosmetics Market Intelligence
Asset-light contract manufacturing and brand licensing is fragmenting competitive barriers in anti-aging cosmetics, allowing digital-native entrants to scale without fixed production investments. L'Oréal S.A. leverages its integrated dermatological research network to sustain pipeline depth across prescription-adjacent skincare. Estée Lauder Companies Inc. anchors its premium positioning through controlled airport retail and travel-exclusive distribution. Shiseido Company, Limited differentiates via biotech-derived active ingredient platforms developed through its Tokyo-based innovation centers.
Anti-aging cosmetics comprise topical formulations incorporating retinoids, peptides, antioxidants, and hyaluronic acid at clinically tested concentrations, manufactured through emulsion stabilization and liposome encapsulation processes to deliver dermal penetration and collagen stimulation. These products serve consumers seeking measurable wrinkle reduction, skin brightening, and firming outcomes without procedural intervention. Serums command the highest margin pool due to concentrated active loading and premium positioning, while creams retain the largest volume footprint across mass and prestige tiers. Online retailers represent the fastest-growing distribution channel, reshaping how hydration and age spot removal products reach home users through algorithmic personalization and subscription replenishment models.
The FDA oversees cosmetic safety labeling and active ingredient thresholds in the United States, while REACH governs chemical substance registration and hazard communication across European manufacturing. China's NMPA implements pre-market registration requirements for cosmetics containing novel ingredients, directly shaping which biotech actives enter the country's formal sales channels. Dermatologists and beauty clinics must monitor evolving regulatory divergence between these frameworks when selecting supplier portfolios and treatment-grade product lines for patient recommendation.
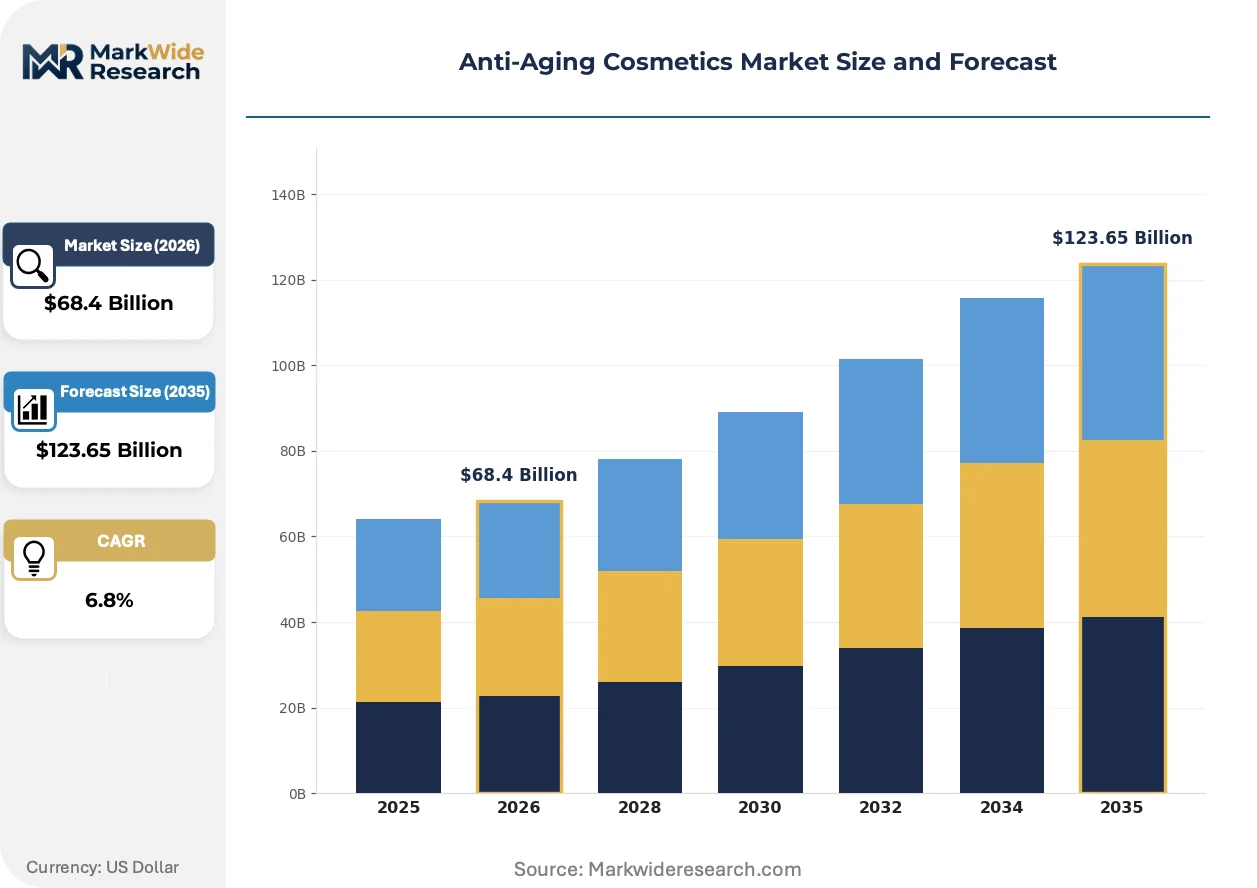
Market Dynamics
Contract manufacturing proliferation is collapsing capital barriers for digital-native entrants, fragmenting competitive concentration while biotech-derived actives command premium positioning through clinically validated dermal penetration claims.
Growth Catalysts
- EU Green Deal chemical mandates:REACH reformulation requirements accelerate sustainable ingredient substitution across European supply chains, opening procurement windows for bio-based active suppliers.
- Cross-border e-commerce infrastructure:China customs streamlining enables direct-to-consumer import channels for prestige skincare, bypassing traditional distributor markups.
- Liposome encapsulation advances:Nano-delivery systems improve retinoid stability and epidermal penetration, expanding addressable populations with sensitive skin profiles.
Market Restraints
- Novel ingredient registration timelines:China's NMPA pre-market approval processes extend 18-24 months for biotech-derived actives, delaying revenue recognition for innovators.
- Peptide synthesis concentration:Active pharmaceutical ingredient suppliers cluster in South Korea and Switzerland, creating single-source vulnerability for mid-tier formulators.
- Hyaluronic acid price volatility:Fermentation feedstock costs fluctuate with agricultural commodity cycles, compressing margin predictability for volume manufacturers.
Strategic Opportunities
- Men's grooming penetration:Underdeveloped male anti-aging routines in Germany and Japan present first-mover positioning for gender-neutral serum formulations.
- Dermatology clinic channel expansion:Medical spa integration of prescription-adjacent skincare creates high-margin professional recommendation engines.
- Subscription replenishment algorithms:Machine learning-driven personalization engines lock in recurring revenue through predictive consumption modeling.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise in emulsion stabilization and active compatibility commands premium compensation, constraining R&D scaling.
- Multi-jurisdiction labeling compliance:Divergent FDA, REACH, and NMPA disclosure requirements force SKU proliferation and inventory fragmentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Aging Cosmetics Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Serums, Lotions, Masks, Oils Application: Wrinkle Reduction, Skin Brightening, Hydration, Firming, Age Spot Removal End User: Beauty Clinics, Dermatologists, Spas, Home Users, Salons Distribution Channel: Online Retailers, Specialty Stores, Pharmacies, Department Stores, Direct Sales |
| Companies Covered | L'Oréal S.A., Estée Lauder Companies Inc., Procter & Gamble Company, Unilever PLC, Beiersdorf AG, Shiseido Company, Limited, Revlon, Inc., Coty Inc., Johnson & Johnson Services, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Aging Cosmetics Market Strategic Shifts & Innovations
Biotechnology convergence with cosmetic formulation is redefining efficacy claims and procurement priorities across prestige and mass market tiers.
Microbiome-targeted skincare is collapsing the traditional barrier between dermatological therapeutics and cosmetic maintenance. Home users seeking measurable outcomes without procedural intervention drive adoption of bacterial lysate and postbiotic formulations. This convergence compresses the historical separation between prescription-grade and over-the-counter positioning.
REACH authorization restrictions on endocrine-disrupting preservatives force accelerated clean-label reformulation across European manufacturing bases. Suppliers must validate alternative preservation systems through stability testing protocols. Prestige serums containing novel natural antimicrobials face compressed development timelines to maintain shelf presence.
Algorithmic skin diagnostics via smartphone imaging reshape how consumers match active concentrations to individual concerns. Chinese cross-border platforms deploy AI-driven recommendation engines that bypass traditional counter consultation. This disintermediation concentrates data advantage with direct-to-consumer brands possessing proprietary skin aging databases.
Anti-Aging Cosmetics Market Segmentation
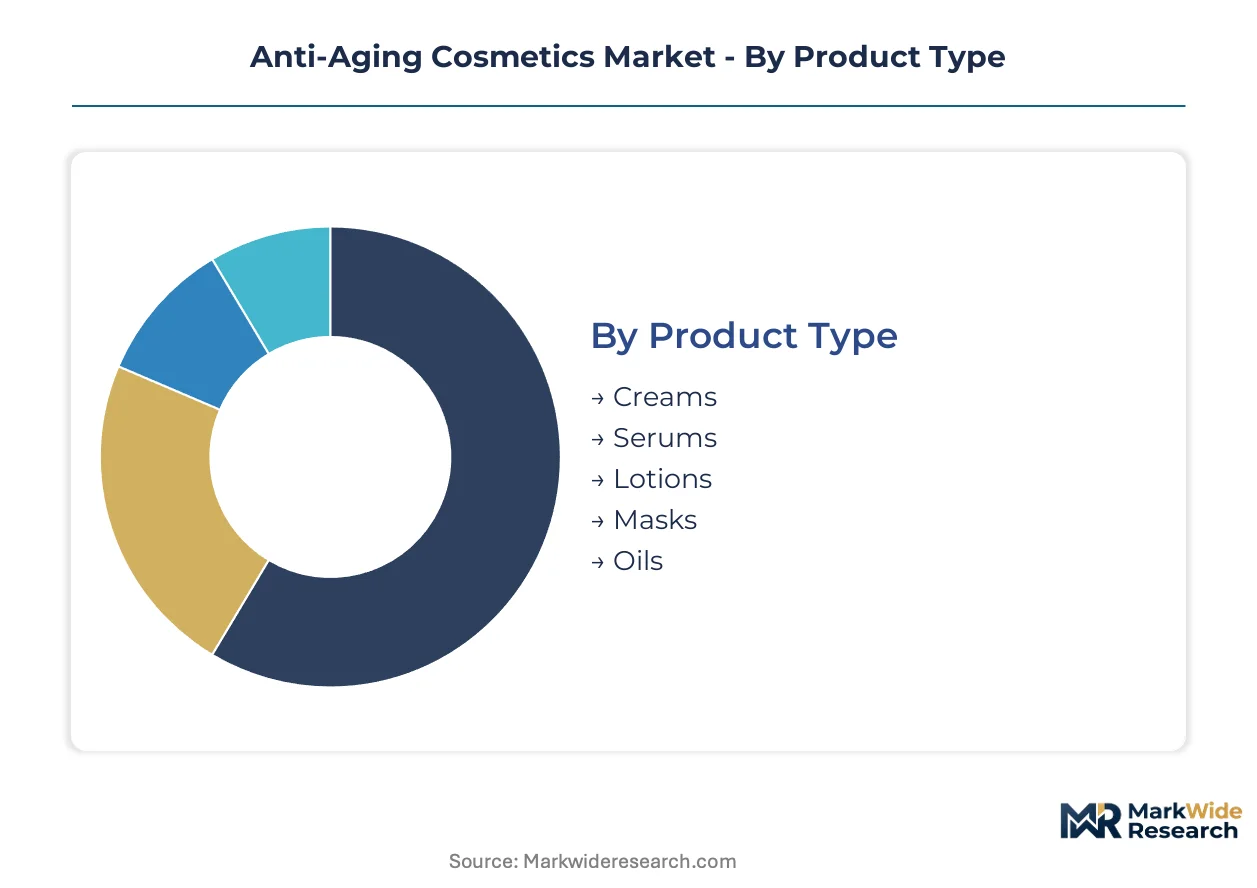
Anti-aging cosmetics segmentation reveals how formulation chemistry, clinical positioning, and channel economics intersect to capture distinct consumer willingness-to-pay thresholds. Product concentration levels and delivery mechanisms determine margin architecture, while end-user setting shapes regulatory classification and recommendation authority.
Product Type:
Formulation viscosity and active loading density create a use-case spectrum spanning daily maintenance to intensive correction protocols.
- Serums:Water-based formulations with 15-30% active peptide or retinoid concentration enable dermal penetration through low-molecular-weight carriers. Demand concentrates in Chinese cross-border e-commerce channels where algorithmic personalization matches concentration levels to skin aging profiles.
- Creams:Emulsion-stabilized vehicles combining humectants with occlusive barriers deliver sustained hydration for mature skin barriers. Mass-market volume leadership in European pharmacy chains reflects EU Green Deal reformulation timelines accelerating preservative system transitions.
- Lotions:Lower viscosity emulsions suit body-wide application and humid climate preferences across Southeast Asian markets.
- Masks:Occlusive delivery systems for periodic intensive treatment, popular in Korean beauty-influenced routines.
- Oils:Lipid-based formulations targeting barrier repair and massage application in professional spa settings.
The dominant share belongs to creams, while serums are closing the gap fastest through premium positioning and direct-to-consumer subscription models.
Application:
Clinical outcome specificity determines pricing tier and channel placement across cosmetic and dermatology-adjacent positioning.
- Wrinkle Reduction:Retinoid and peptide formulations targeting collagen synthesis command the highest price-per-gram through clinically validated before-and-after protocols. Dermatology clinic recommendations in Germany and Japan drive professional channel attachment for prescription-adjacent positioning.
- Hydration:Hyaluronic acid and ceramide combinations address barrier dysfunction in aging skin. Volume concentration in North American mass retail reflects demographic aging and pharmacy accessibility.
- Skin Brightening:Niacinamide and vitamin C derivatives targeting melanin regulation, with regulatory restrictions varying by jurisdiction.
- Firming:Elastin-supporting actives for jawline and décolletage concerns, popular in European prestige positioning.
- Age Spot Removal:Hydroquinone-adjacent and botanical alternatives for solar lentigines, requiring careful regulatory navigation across FDA, REACH, and NMPA frameworks.
Wrinkle reduction captures the largest revenue pool, though hydration applications are expanding most quickly through male grooming penetration and routine simplification trends.
End User:
Recommendation authority and setting economics segment the market between professional intervention and self-directed maintenance.
- Home Users:Self-directed consumers purchasing through retail or direct channels represent the volume expansion frontier. Algorithmic skin diagnostics and subscription replenishment models from Chinese cross-border platforms are collapsing traditional counter consultation dependencies.
- Dermatologists:Medical professionals prescribing or recommending treatment-grade formulations create high-trust conversion pathways. Integration with aesthetic procedure practices in South Korea and Switzerland drives attachment to biotech-derived active platforms.
- Beauty Clinics:Medical spa environments blending cosmetic and therapeutic positioning for premium service bundling.
- Spas:Experience-driven consumption emphasizing ritual and relaxation over measurable outcome claims.
- Salons:Hair and beauty service providers extending into skincare through treatment add-ons and retail attachment.
Home users dominate absolute volume, while dermatologist channels are gaining share fastest through prescription-adjacent credibility and procedure bundling.
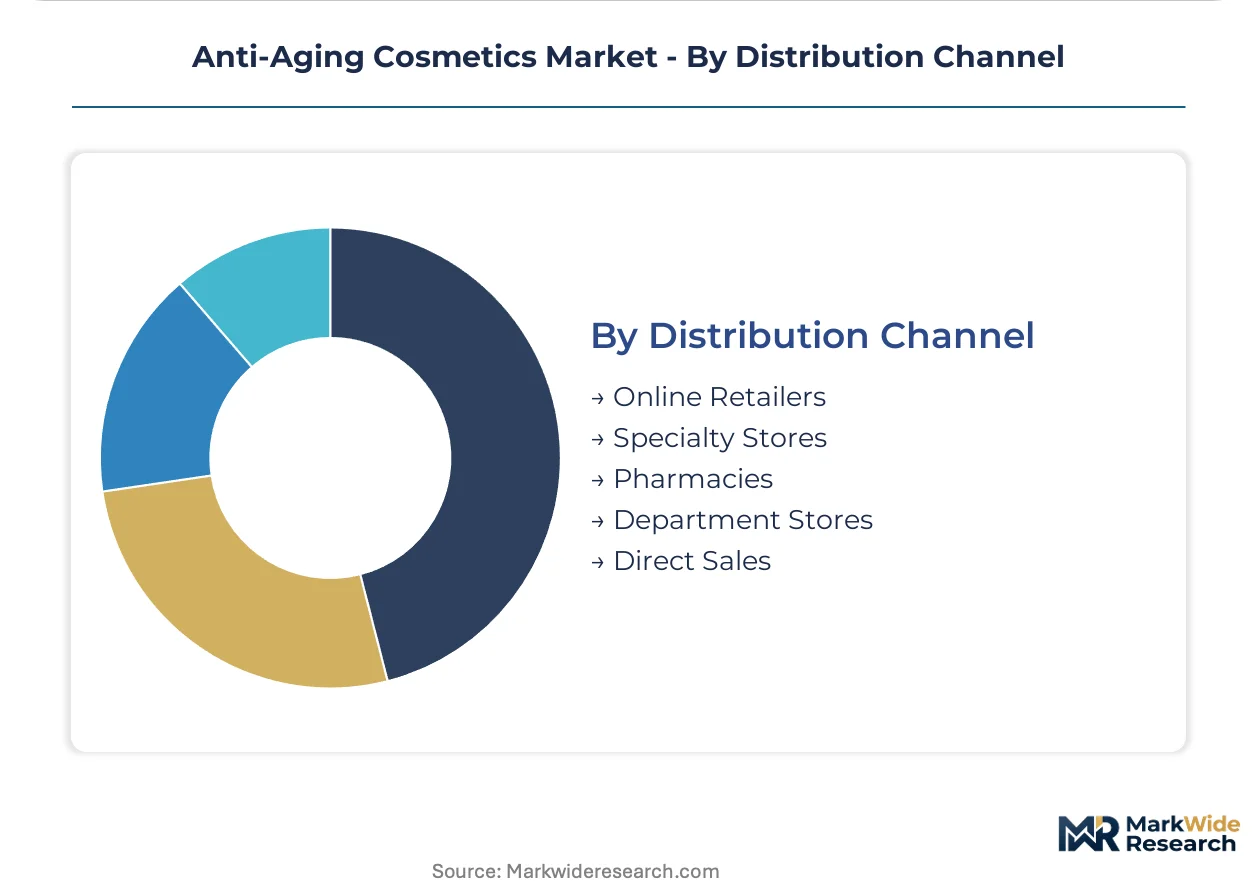
Distribution Channel:
Channel economics and data ownership reshape competitive advantage through customer relationship control.
- Online Retailers:Algorithmic personalization and subscription replenishment engines capture recurring revenue through predictive consumption modeling. Chinese platforms leverage skin aging databases to bypass traditional distributor markups and concentrate data advantage.
- Specialty Stores:Curated assortments with consultation services maintain relevance in prestige positioning through experiential differentiation.
- Pharmacies:Trust-based accessibility for mass-market and dermocosmetic tiers, particularly strong in European regulatory environments.
- Department Stores:Legacy prestige positioning through counter-based consultation, facing pressure from direct-to-consumer displacement.
- Direct Sales:Network marketing and brand-owned channels retaining customer relationship control for established heritage brands.
Online retailers are expanding most rapidly, though pharmacies retain structural importance in European markets where regulatory credibility shapes purchase decisions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal chemical mandates and China's NMPA registration reforms are restructuring procurement geography across anti-aging cosmetics supply chains. Regulatory divergence between REACH, FDA, and NMPA frameworks fragments formulation standardization while creating arbitrage opportunities for agile manufacturers.
United States
FDA oversight of cosmetic safety labeling and active ingredient thresholds shapes domestic formulation protocols. The Inflation Reduction Act's domestic manufacturing incentives accelerate reshoring investments for peptide synthesis and fermentation-based active production. New Jersey and California clusters concentrate contract manufacturing capacity serving prestige brand portfolios.
China
Cross-border e-commerce infrastructure expansion drives direct-to-consumer import volume through Shanghai and Hangzhou logistics hubs. NMPA pre-market registration requirements for novel biotech actives extend 18-24 month approval timelines, delaying revenue recognition for innovators. Domestic brands capture premium spending through algorithmic personalization engines deployed on Tmall and Douyin platforms.
Germany
REACH reformulation mandates accelerate sustainable ingredient substitution across European manufacturing bases. The country's pharmacy distribution network maintains structural importance for dermocosmetic credibility and trust-based accessibility. Bavaria-based innovation clusters develop bio-based preservative alternatives to maintain shelf presence under tightened authorization restrictions.
Japan
Shiseido's Tokyo-based biotech research anchors domestic active ingredient platform development. METI standards for cosmetic manufacturing quality shape export competitiveness across Asian markets. Osaka-Kobe industrial corridors concentrate fermentation capacity for hyaluronic acid and ceramide production serving regional formulators.
South Korea
MFDS regulatory frameworks for functional cosmetics enable faster clinical claim validation than FDA or NMPA pathways. Seoul-based peptide synthesis suppliers create concentration risk for mid-tier global formulators dependent on single-source procurement. Gangnam district medical spa density drives prescription-adjacent skincare attachment and professional recommendation conversion.
Anti-Aging Cosmetics Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented tier structures. Prestige conglomerates leverage dermatological research networks and airport retail exclusivity to defend margin pools. Mass-market multinationals deploy scale economics and pharmacy channel penetration for volume capture. Digital-native entrants exploit contract manufacturing proliferation to bypass fixed production investments. Dominant competitive moves include biotech active platform licensing and algorithmic subscription engine deployment.
Among integrated research-to-retail conglomerates, L'Oréal S.A. and Estée Lauder Companies Inc. occupy positions exemplifying dermatological credibility and travel-exclusive distribution control. Shiseido Company, Limited represents the biotech-derived active platform archetype through Tokyo-centered innovation infrastructure.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Estée Lauder Companies Inc. |
| Procter & Gamble Company |
| Unilever PLC |
| Beiersdorf AG |
| Shiseido Company, Limited |
| Revlon, Inc. |
| Coty Inc. |
| Johnson & Johnson Services, Inc. |
| Others |
Cost & Logistics Intelligence
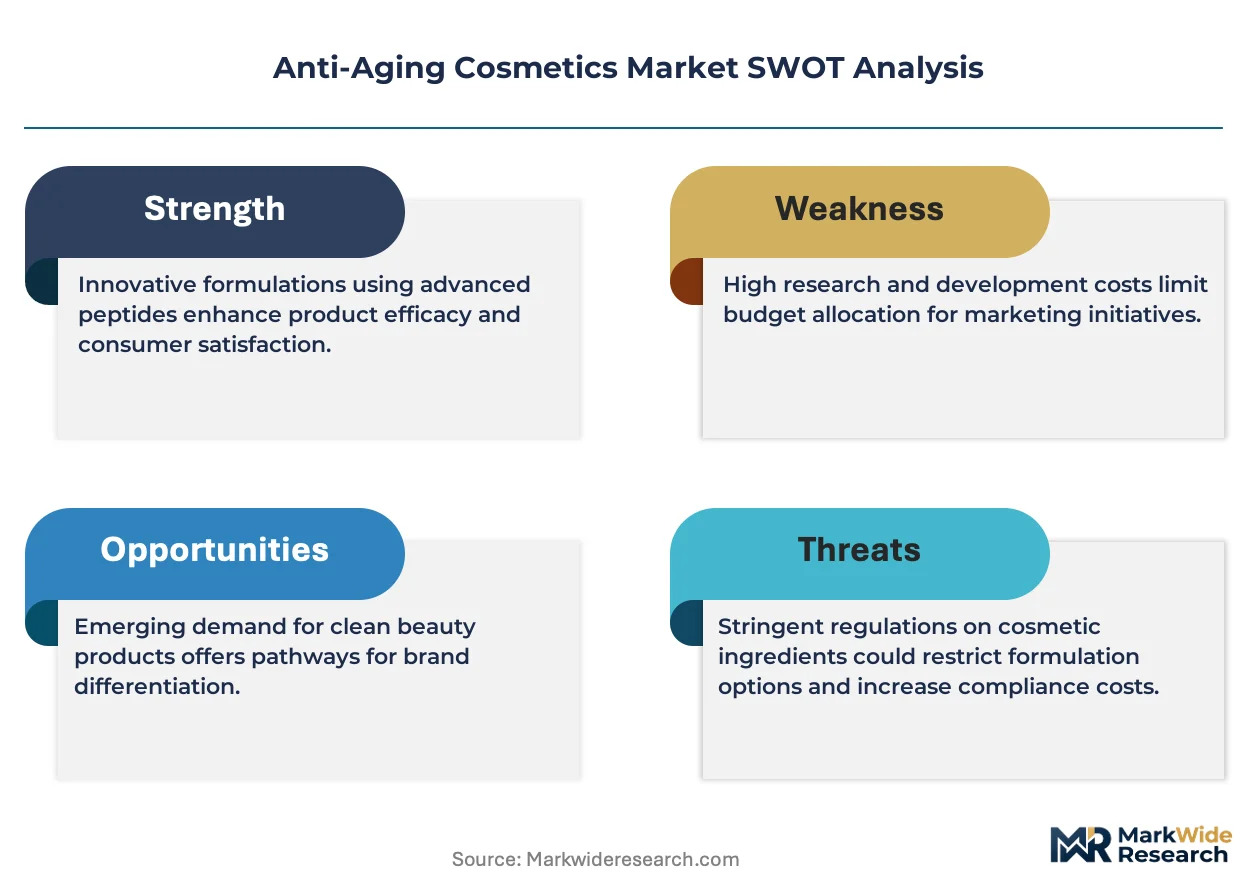
Peptide synthesis suppliers cluster in South Korea and Switzerland, anchoring margin capture for downstream formulators while compressing pricing power for mid-tier brands dependent on single-source procurement. This concentration forces pricing stratification between biotech-active premium tiers and commodity-hyaluronic-acid mass segments.
Pricing Analysis
Certification level creates the primary spread, with NMPA-registered biotech actives commanding substantial premiums over REACH-compliant standard formulations. Three-tier pricing structure across premium, standard, and economy levels reflects active concentration, encapsulation technology, and dermatological endorsement depth. Pricing pressure stems from hyaluronic acid feedstock volatility tied to agricultural commodity cycles. Mass-market pharmacy channels exhibit highest price sensitivity, while dermatology clinic professional lines maintain inelastic demand through procedure bundling.
Supply Chain Analysis
Fermentation feedstock for hyaluronic acid and ceramide production centers on Japan's Osaka-Kobe corridor and Chinese biotechnology parks. Active pharmaceutical ingredient synthesis draws from South Korean peptide specialists and Swiss precision chemistry houses. Single-source vulnerability concentrates in Seoul-based oligopeptide suppliers serving global formulators. Distribution runs through contract manufacturing networks enabling asset-light brand scaling without captive production investment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from algorithmic direct-to-consumer platforms collapsing traditional consultation-dependent purchase journeys. Defense requires securing data-advantaged customer relationships before disintermediation accelerates.
For Market Incumbents: Insulate prescription-adjacent credibility through dermatology clinic channel deepening and biotech active platform exclusivity agreements. Accelerate backward integration into fermentation capacity for hyaluronic acid and ceramide production to reduce feedstock cost volatility exposure. Prioritize subscription algorithm development to lock recurring revenue against Chinese cross-platform disintermediation.
For New Entrants and Emerging Players: Male grooming white space in Germany and Japan represents the most penetrable entry point for gender-neutral serum formulations with simplified routine positioning. Algorithmic skin diagnostics capability enables bypass of heritage brand counter consultation dependencies. Direct-to-consumer subscription models with predictive replenishment engines offer the strongest go-to-market angle against established pharmacy distribution.
For Investors and Strategic Acquirers: Capital is best deployed toward contract manufacturing specialists with validated liposome encapsulation capabilities and multi-jurisdiction regulatory filing expertise. Long-term viability hinges on bio-based preservative innovation addressing REACH authorization restrictions. Monitor NMPA novel ingredient approval velocity as inflection indicator for biotech active platform revenue recognition timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Biotech Active Platform Licensing | Tokyo-centered innovation infrastructure accelerates peptide-derived formulation pipelines for prestige positioning. |
| Subscription Algorithm Deployment | Machine learning-driven personalization engines concentrate data advantage with direct-to-consumer brands. |
| Dermatology Clinic Channel Expansion | Medical spa integration creates high-margin professional recommendation engines for treatment-grade lines. |
| Clean-Label Reformulation Investment | Bio-based preservative alternatives maintain shelf presence under tightened REACH authorization restrictions. |
| Cross-Border E-Commerce Infrastructure | Shanghai and Hangzhou logistics hubs enable direct-to-consumer import bypassing traditional distributor markups. |
Research Approach
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and retail audit databases. Cosmetic chemists, dermatology clinic procurement managers, contract manufacturing executives, and cross-border platform operators provided structured input. NMPA registration databases, REACH authorization lists, FDA cosmetic labeling guidance, and Nielsen retail tracking supplied validation anchors. Bottom-up volume modeling triangulates against top-down expenditure flow analysis.
Forecast inputs incorporate formulation chemistry segmentation, channel economics, and regulatory approval velocity across the projection horizon. Product type, application specificity, end-user setting, and distribution mechanism dimensions structure the analytical framework. CAGRs derive from trend extrapolation adjusted for substitution effects and policy intervention timelines. Biotech active pipeline depth and algorithmic personalization adoption curves inform industry-specific trajectory assumptions.
Practitioners should monitor NMPA novel ingredient registration timelines, REACH authorization restriction expansions, and hyaluronic acid feedstock commodity cycles for early signals. Cross-checking against customs import volume data and retail sell-through metrics is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
Hair Removal Spray Market
Beauty & Personal Care
Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Hair Removal Wax Warmer Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
Deodorant & Anti-Perspirant Market
Beauty & Personal Care
North America Setting Spray Market
Beauty & Personal Care
Salon Service Market
Beauty & Personal Care
UV Nail Gel Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
South America Hair Styling Products Market
Beauty & Personal Care
China Electric Face Cleanser Market
Beauty & Personal Care
US Cosmetics Market
Beauty & Personal Care
Personal Care Shower and Bath Market