
 Middle East and Africa Hair Conditioner Market | 2026-2036
Middle East and Africa Hair Conditioner Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Hair Conditioner Market Foresight
A widening capital-intensity divergence between multinational and regional players is rotating competitive dynamics toward manufacturing scale and laboratory capacity. L'Oréal leverages integrated R&D centers in Dubai to sustain formulation leadership for textured hair needs. Procter & Gamble anchors shelf presence through dominant supermarket partnerships across Nigeria and Kenya. Henkel AG & Co. KGaA differentiates via specialized salon-distribution networks in Morocco and Egypt.
Middle East and Africa hair conditioner comprises cationic surfactant-based formulations, typically incorporating fatty alcohols, silicones, and hydrolyzed proteins, designed to reduce friction, restore lipid barriers, and manage porosity in chemically treated or naturally coarse hair. Rinse-out conditioners occupy the largest volume share due to habitual daily-wash practices in humid coastal climates, while leave-in formats represent the fastest-expanding margin pool as heat-styling frequency rises among urban women. Natural and herbal ingredient types command premium positioning through halal-certification alignment and prophetic-medicine consumer narratives, whereas synthetic segments compete on price in mass-market supermarket channels.
South Africa's national pharmaceutical regulator enforces cosmetic safety assessments that shape import documentation burdens for Asian suppliers. Saudi Arabia's SFDA mandates Arabic-label ingredient disclosure, directly affecting packaging localization costs and batch-compliance timelines. The UAE's MOHAP maintains accelerated registration pathways for products manufactured under ISO-certified facilities, creating tiered market-access conditions. Stakeholders must monitor evolving Gulf harmonization talks between SFDA and MOHAP, as unified standards would consolidate compliance investments but eliminate fragmented regulatory arbitrage opportunities.
Market Dynamics
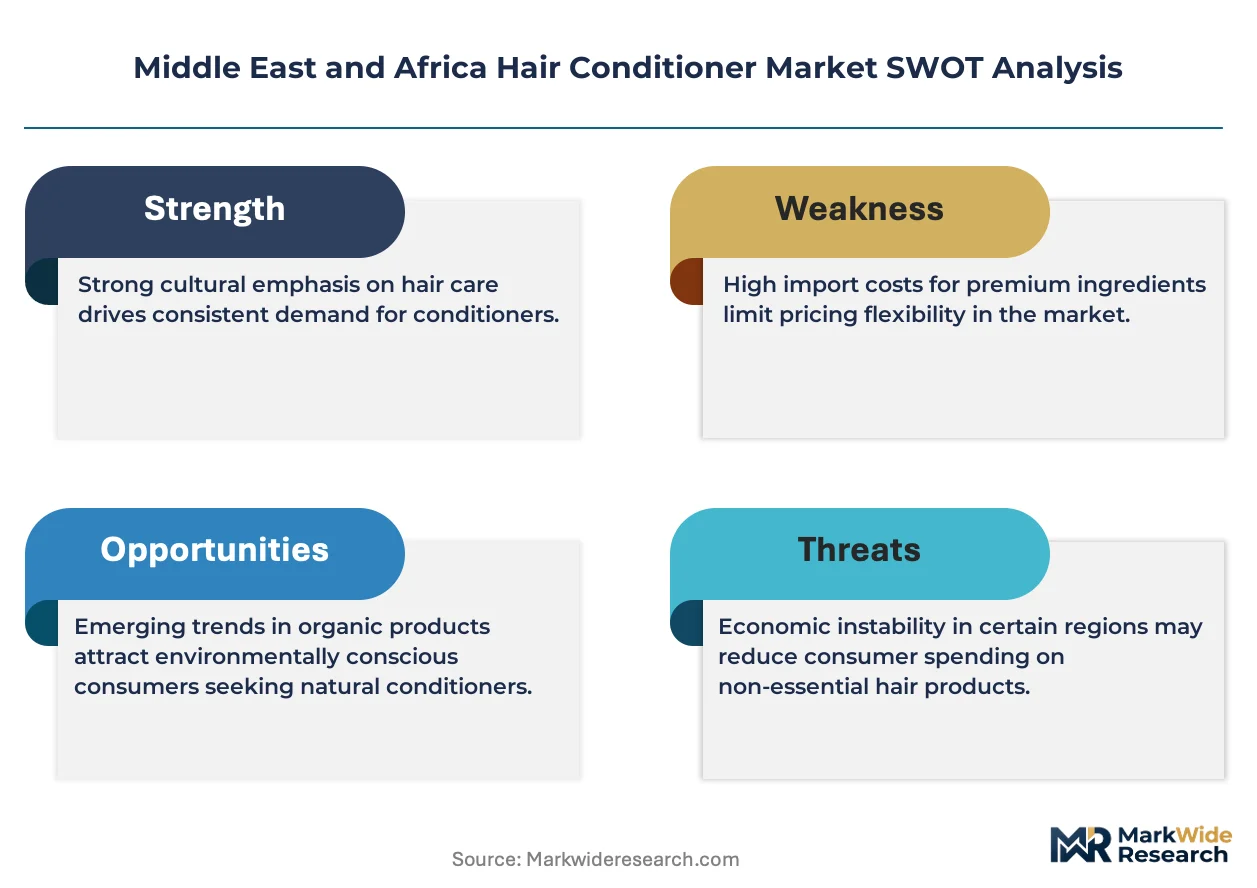
Ingredient-disclosure mandates from Saudi Arabia's SFDA and South Africa's national pharmaceutical regulator are forcing reformulation investments across the value chain, compressing margins for import-dependent distributors while rewarding laboratory-capable manufacturers.
Growth Catalysts
- SFDA cosmetic standards:Arabic-label mandates accelerate packaging localization, creating captive demand for regional manufacturing facilities with in-house printing and compliance capabilities.
- Salon professional segment expansion:Formal grooming culture deepening across Gulf cities drives premium leave-in conditioner adoption through specialized distribution networks.
- Prophetic-medicine narratives:Consumer alignment with halal-certified natural ingredients commands price premiums in Saudi Arabia and UAE retail channels.
Market Restraints
- Silicone price volatility:Petrochemical feedstock fluctuations disrupt cationic surfactant cost structures for mass-market rinse-out formulations.
- Import documentation burdens:South Africa's cosmetic safety assessments create batch-compliance delays for Asian suppliers without established local testing partnerships.
- Heat-styling substitution:Protective hairstyle adoption among urban Nigerian and Kenyan women reduces daily conditioner consumption frequency.
Strategic Opportunities
- MOHAP accelerated registration:UAE's ISO-certified facility pathway enables faster market access for manufacturers with integrated Dubai-based R&D centers.
- Leave-in format white space:Heat-styling frequency rises among urban women across Cairo and Casablanca, expanding margin pools beyond habitual rinse-out volumes.
- Gulf harmonization talks:Unified SFDA-MOHAP standards would consolidate compliance investments while eliminating fragmented regulatory arbitrage for scale players.
Industry Challenges
- Formulation chemist scarcity:Textured-hair expertise concentrated in multinational R&D centers limits regional player access to porosity-management innovation.
- Halal certification timelines:Multi-month audit cycles for prophetic-medicine positioning delay product launches in Saudi premium channels.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Hair Conditioner Market |
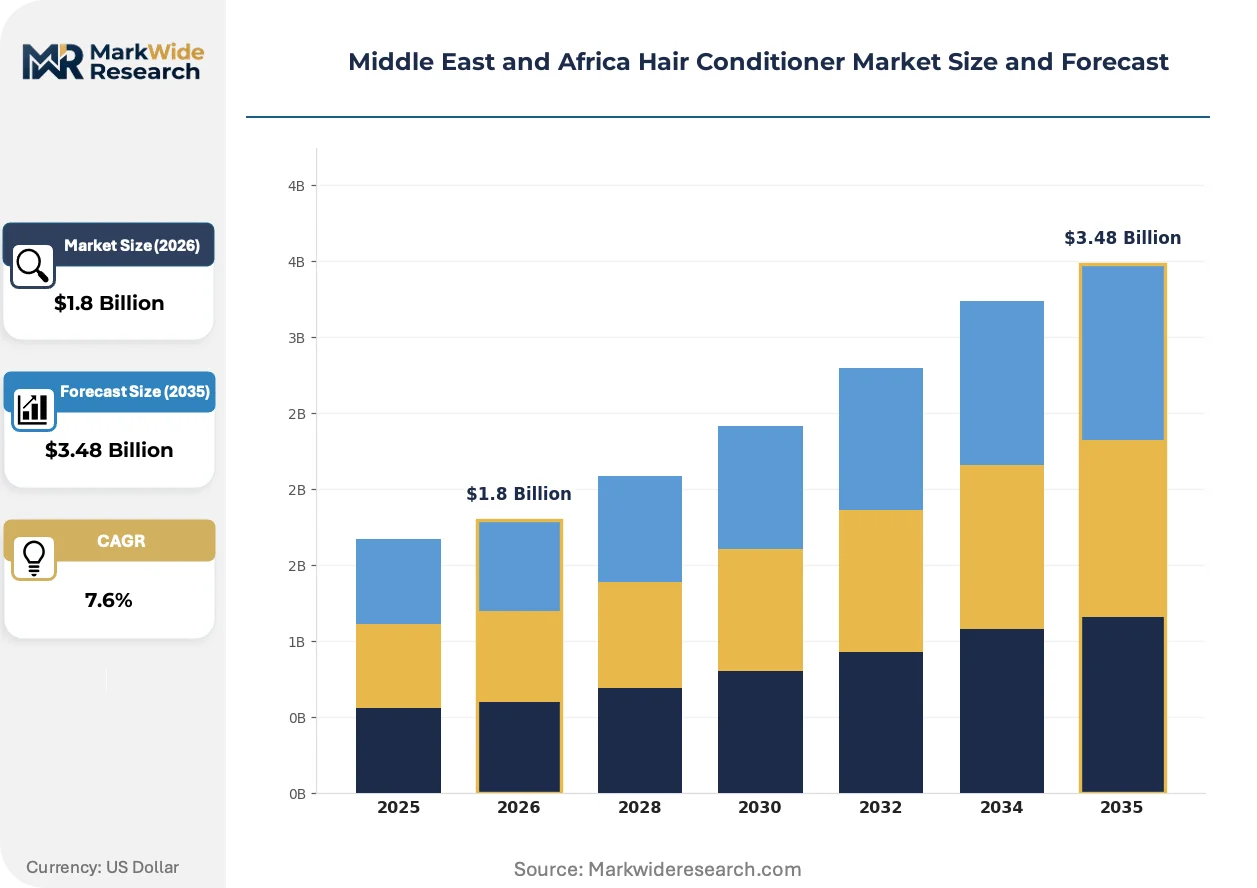
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Leave-in, Rinse-out, Deep Conditioning, Treatment Ingredient Type: Natural, Organic, Synthetic, Herbal End User: Men, Women, Children, Salon Professionals Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | L'Oréal, Procter & Gamble, Henkel AG & Co. KGaA, Johnson & Johnson, Unilever, Coty Inc., Shiseido Co., Ltd., Kao Corporation, Amway, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Hair Conditioner Market Shifts & Advancements
Formulation science and distribution architecture are converging to reshape competitive positioning, with laboratory capacity and regulatory navigation emerging as decisive capabilities rather than mere operational requirements.
Micro-encapsulation technology for time-release conditioning agents is miniaturizing active ingredient delivery systems. Salon professionals across Dubai and Abu Dhabi are adopting these formats for chemical-treatment aftercare. The technology is compressing traditional rinse-out application windows while enabling premium pricing for specialized service protocols.
MOHAP's ISO-certified facility recognition pathway is tightening documentation standards for import registration. Manufacturers without captive Dubai production face extended batch-review timelines. Regional distributors are responding by consolidating supplier relationships toward vertically integrated multinationals with established UAE manufacturing footprints.
Supermarket partnership concentration is shifting procurement leverage toward dominant retail networks in Nigeria and Kenya. Local distributors without direct manufacturer relationships are losing shelf placement to integrated supply chains. This consolidation is most visible in mass-market synthetic segments where price competition compresses intermediary margins.
Middle East and Africa Hair Conditioner Market Segmentation
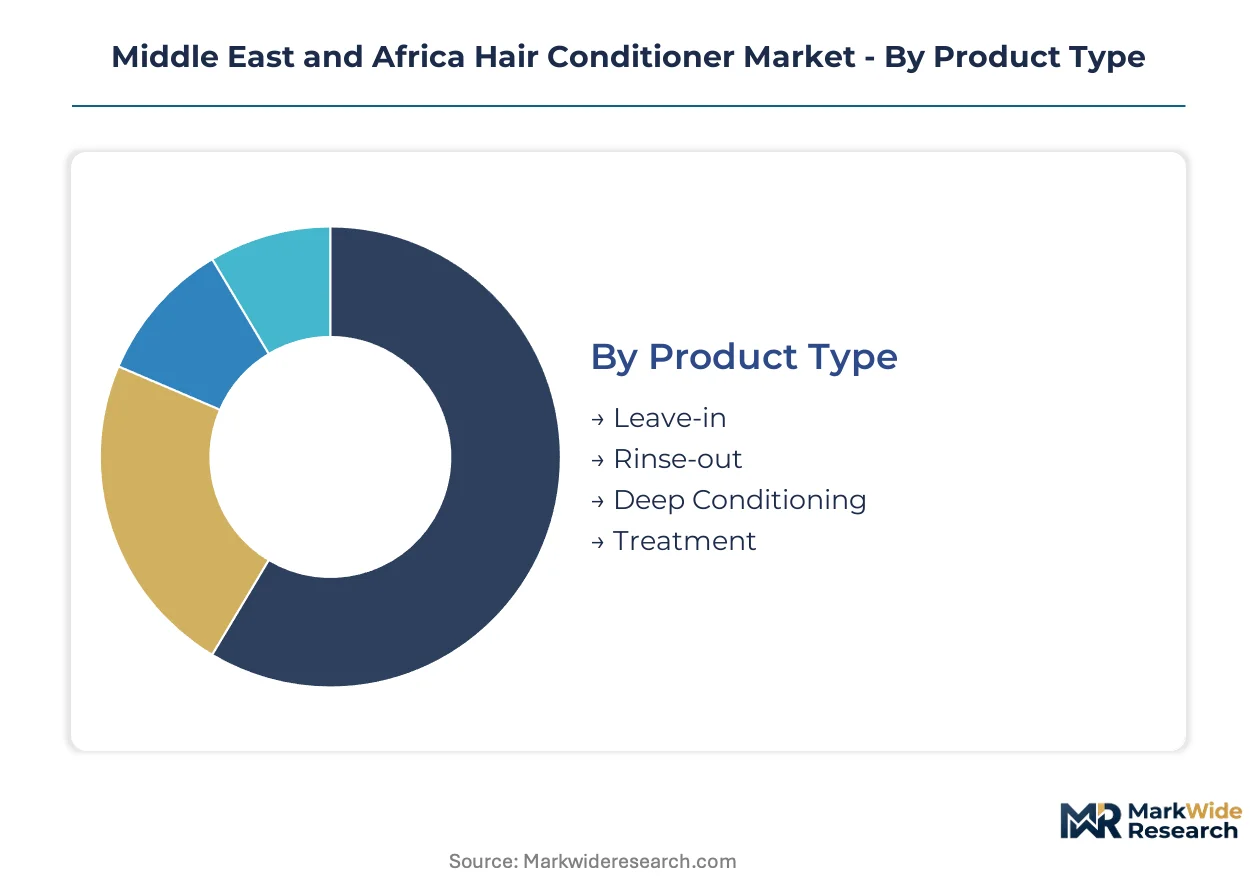
Segmentation in the Middle East and Africa hair conditioner market reveals how formulation chemistry, retail infrastructure, and cultural grooming practices intersect to create distinct profit pools. Understanding these divisions exposes where substitution threats and margin compression concentrate.
Product Type:
Rinse-out formats face the most acute substitution pressure from waterless cleansing alternatives and co-wash routines spreading through urban Nigerian and Kenyan salons.
- Leave-in:Lightweight cationic emulsions designed for heat-styling protection without water activation. Demand concentrates among urban women in Cairo and Casablanca where flat-iron frequency climbs and salon aftercare protocols command premium positioning.
- Rinse-out:Standard fatty-alcohol and silicone-based formulations for daily friction reduction. Volume leadership rests with humid coastal cities across Gulf states where habitual washing patterns sustain mass-market consumption despite water-scarcity concerns.
- Deep Conditioning:Intensive protein-reconstruction treatments for chemically damaged hair.
- Treatment:Medicated or bond-repair formulations addressing specific porosity disorders.
Rinse-out retains volume leadership; leave-in holds the steepest expansion curve.
Ingredient Type:
Cost tier stratification separates premium positioning from commodity competition, with certification requirements creating artificial scarcity at the top.
- Natural:Plant-derived emollients and hydrolyzed proteins without petrochemical silicones. Halal-certification alignment in Saudi Arabia and UAE retail channels supports price premiums through prophetic-medicine consumer narratives.
- Herbal:Traditional botanical extracts marketed through regional ethnobotanical heritage. Moroccan argan oil and Egyptian black seed oil formulations anchor specialty-store placement in North African urban centers.
- Organic:Certified chemical-free ingredients meeting international agriculture standards.
- Synthetic:Petrochemical-derived silicones and quaternary ammonium compounds competing on price in Nigerian and Kenyan supermarket channels where import documentation burdens squeeze distributor margins.
Synthetic commands absolute volume; natural captures the steepest margin expansion.
End User:
Application intensity varies dramatically across demographic clusters, with professional channels offering the most defensible pricing power.
- Salon Professionals:Bulk-format professional lines requiring technical training for chemical-treatment aftercare. Formal grooming culture deepening across Dubai and Abu Dhabi drives specialized distribution network expansion.
- Women:Primary household purchasers across all product formats. South Africa's rising middle-class consumption concentrates demand through established retail infrastructure serving textured-hair needs.
- Men:Beard-conditioning crossovers and simplified two-in-one formulations.
- Children:Tear-free mild surfactant systems for delicate scalp barriers.
Women retain volume leadership; salon professionals climb the fastest.
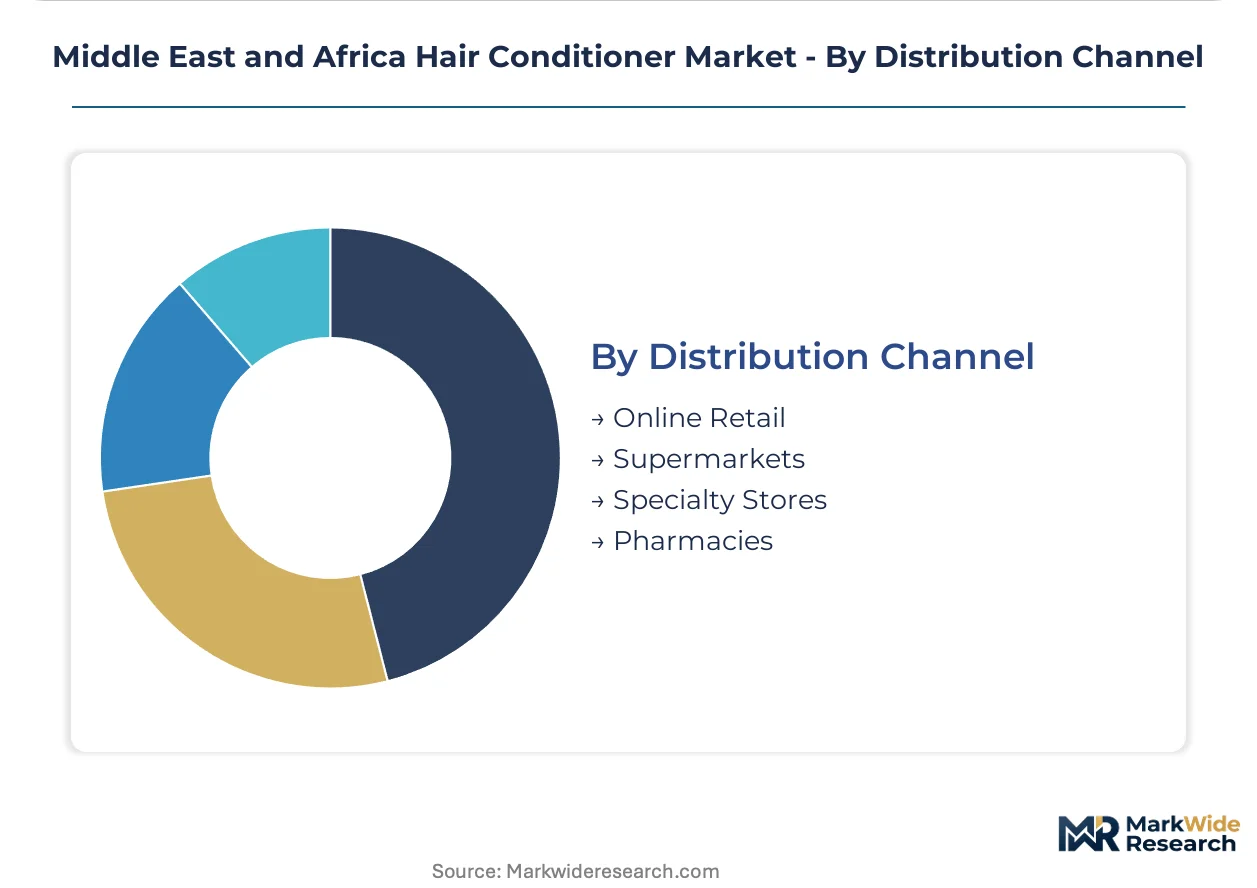
Distribution Channel:
Customer acquisition economics diverge sharply between physical and digital routes, with regulatory compliance costs favoring integrated supply chains.
- Supermarkets:Dominant shelf-space allocation in Nigeria and Kenya where Procter & Gamble anchors presence through exclusive partnerships. Procurement leverage consolidation squeezes intermediary distributors without direct manufacturer relationships.
- Online Retail:Direct-to-consumer platforms bypassing import documentation delays. SFDA Arabic-label mandates create fulfillment complexity that rewards regional warehousing investments.
- Specialty Stores:Curated natural and herbal assortments in premium mall locations.
- Pharmacies:Medicated treatment formats requiring pharmacist consultation.
Supermarkets retain volume leadership; online retail gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import-dependent distributors across the Middle East and Africa face mounting compliance costs as regulatory divergence between Gulf and sub-Saharan markets reshapes trade flows. Export-oriented manufacturers with captive regional production capture margin advantages unavailable to pure traders.
Saudi Arabia
SFDA cosmetic standards mandate Arabic-label ingredient disclosure, accelerating packaging localization investments. Prophetic-medicine consumer narratives command price premiums for halal-certified natural formulations. Riyadh's retail infrastructure concentrates demand for salon professional segments as formal grooming culture deepens.
United Arab Emirates
MOHAP maintains accelerated registration pathways for ISO-certified manufacturing facilities, creating tiered market-access conditions. Dubai-based integrated R&D centers sustain formulation leadership for textured hair needs. Abu Dhabi's specialized distribution networks drive premium leave-in conditioner adoption through salon channels.
South Africa
The national pharmaceutical regulator enforces cosmetic safety assessments that shape import documentation burdens for Asian suppliers. Rising middle-class consumption concentrates demand through established retail infrastructure. Johannesburg's supermarket partnerships anchor shelf presence for mass-market synthetic segments.
Nigeria
Protective hairstyle adoption among urban women reduces daily conditioner consumption frequency. Supermarket procurement leverage consolidation squeezes intermediary distributors without direct manufacturer relationships. Lagos retail networks dominate volume distribution for rinse-out formulations competing on price.
Egypt
Heat-styling frequency rises among urban women across Cairo, expanding margin pools for leave-in formats beyond habitual rinse-out volumes. Regulatory alignment with Gulf harmonization talks would consolidate compliance investments for scale players. Alexandria's import channels face batch-compliance delays without established local testing partnerships.
Middle East and Africa Hair Conditioner Market Competitive Landscape
Concentration sits with multinational consumer goods conglomerates possessing integrated laboratory capacity and regulatory navigation expertise. Three strategic archetypes dominate: R&D-anchored formulators with textured-hair specialization, scale-driven mass-market suppliers leveraging supermarket partnerships, and niche players exploiting halal-certification premiums. Competitive moves center on backward integration into regional manufacturing and strategic consolidation of distributor relationships.
Within the multinational tier, L'Oréal, Procter & Gamble, and Henkel AG & Co. KGaA exemplify divergent scale strategies. L'Oréal occupies a position anchored by Dubai-based integrated research centers. Procter & Gamble represents supermarket partnership concentration across Nigerian and Kenyan mass-market channels. Henkel AG & Co. KGaA sits within specialized salon-distribution networks in North African markets.
| Leading Market Players |
|---|
| L'Oréal |
| Procter & Gamble |
| Henkel AG & Co. KGaA |
| Johnson & Johnson |
| Unilever |
| Coty Inc. |
| Shiseido Co., Ltd. |
| Kao Corporation |
| Amway |
| Others |
Supply & Pricing Matrix
Long-term capacity reservation agreements with ISO-certified UAE manufacturers lock in supply access while insulating distributors from SFDA-mandated packaging localization cost spikes. These contracts anchor price visibility for salon professional segments across Dubai and Abu Dhabi, where Arabic-label compliance timelines otherwise disrupt margin planning.
Pricing Analysis
Salon professional buyers anchor three-tier pricing stratification across premium leave-in, standard rinse-out, and economy synthetic formats. Price differentiation hinges on halal-certification grade and volume scale, with natural ingredient tiers commanding premiums through prophetic-medicine positioning. Cost compression in mass-market synthetic segments intensifies as Nigerian supermarket procurement leverage consolidates. Price sensitivity concentrates among import-dependent distributors facing South African cosmetic safety assessment documentation burdens, while integrated multinationals with captive Dubai R&D absorb compliance costs with minimal margin erosion.
Supply Chain Analysis
Inventory lead times for cationic surfactant feedstocks stretch when petrochemical volatility disrupts silicone supply from Saudi Arabia and South Korean specialty chemical producers. Raw material dependencies center on fatty alcohols from Malaysian palm derivatives, hydrolyzed proteins from European suppliers, and quaternary ammonium compounds from Chinese manufacturers. Single-source vulnerability concentrates in halal-certification audit cycles, where multi-month delays bottleneck Saudi premium channel access. Distribution runs through supermarket partnerships in Nigeria and Kenya, specialized salon networks in Morocco and Egypt, and direct-to-consumer platforms bypassing import documentation hurdles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through supermarket procurement leverage consolidation across Nigeria and Kenya, fragmenting intermediary distributor margins while rewarding integrated supply chains with direct manufacturer relationships.
For Market Incumbents: Fortify formulation leadership by deepening Dubai-based R&D capacity for textured-hair porosity management, countering substitution threats from waterless cleansing alternatives spreading through Nigerian salons. Secure backward integration into regional manufacturing with in-house Arabic-label printing capabilities, neutralizing SFDA compliance timeline risks that compress margins for import-dependent competitors. For New Entrants and Emerging Players: Specialized salon-distribution service gaps in Cairo and Casablanca offer white-space entry points where heat-styling frequency climbs faster than incumbent leave-in supply expansion. Target the medicated treatment format segment through pharmacist consultation channels in South Africa, leveraging the national pharmaceutical regulator's safety assessment framework as a competitive moat against unvalidated Asian imports. For Investors and Strategic Acquirers: Regional contract manufacturers with captive halal-certification relationships and ISO-certified UAE production footprints represent priority acquisition targets. Long-term viability hinges on Gulf harmonization between SFDA and MOHAP standards, where unified compliance would eliminate fragmented regulatory arbitrage. Monitor prophetic-medicine narrative intensity in Saudi retail channels as an inflection signal for natural ingredient premium sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Regional Manufacturing | Captive Arabic-label printing capabilities compress SFDA compliance timelines for Saudi market access. |
| Halal Certification Acceleration Program | Multi-month audit cycle reduction unlocks prophetic-medicine premium positioning in UAE retail channels. |
| Salon Professional Distribution Expansion | Specialized network control in Dubai and Abu Dhabi captures leave-in format margin expansion from heat-styling frequency growth. |
| Micro-encapsulation Technology Licensing | Time-release conditioning agent patents differentiate chemical-treatment aftercare protocols for premium service tiers. |
| Direct-to-Consumer Platform Launch | Bypassing South African import documentation delays captures online retail share fastest among urban middle-class segments. |
Research Methodology
Desk research of customs trade records, SFDA regulatory filings, and Nielsen retail audit data preceded structured interviews with salon chain procurement directors, cosmetic formulation chemists, and supermarket category buyers across Dubai, Lagos, and Johannesburg. Primary fieldwork with distribution channel partners and halal-certification auditors combined with secondary validation through MOHAP registration databases and South African pharmaceutical regulator safety assessment protocols. Bottom-up segment sizing triangulated against top-down market value reconstructions.
Variance decomposition across product type, ingredient certification tier, end-user application intensity, and distribution channel structure shaped the analytical framework over the projection horizon. CAGRs derived from modeled volume and value trajectories incorporated salon professional segment expansion rates, prophetic-medicine narrative adoption curves, and regulatory harmonization probability weights. Forecast inputs included petrochemical feedstock price correlation matrices and ISO-certified facility registration velocity across Gulf markets.
Material uncertainties — Gulf regulatory harmonization delays, silicone supply volatility, and protective hairstyle substitution acceleration — sit outside the modeled envelope. Forecasts reflect assumptions about compliance investment continuity and middle-class consumption trajectory stability. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Color Protection Shampoo Market
Beauty & Personal Care
Beard Grooming Products Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market
Beauty & Personal Care
Face Steaming Devices Market
Beauty & Personal Care
Spain Sustainable Personal Care Market
Beauty & Personal Care
Stretch Mark Removal Products Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Loofah Bath Sponge Market
Beauty & Personal Care
China Antibacterial Soap Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
Hair Serums Ingredient Market
Beauty & Personal Care
Shower Gel Market
Beauty & Personal Care
Cosmetics Foundation Market
Beauty & Personal Care
Europe Hair Styling Products Market