
 Body Firming Creams Market | 2026-2036
Body Firming Creams Market Size, Share, and Industry Trends Forecast 2026-2036
Body Firming Creams Market Analysis
Postpartum women seeking skin elasticity restoration is redrawing demand composition in the body firming creams sector. Cosmax leverages captive R&D infrastructure in South Korea to develop peptide-delivery systems for this demographic. Kolmar Korea anchors its competitive stance through manufacturing scale across multiple Asian markets. Intercos differentiates via vertical control over emulsion technology and color cosmetic adjacencies.
Body firming creams are topical cosmetic formulations containing 2-5% active concentrations of retinol, caffeine, or peptide complexes, manufactured through high-shear emulsification processes to achieve dermal penetration thresholds for temporary skin tightening and cellulite appearance reduction. Cream-based delivery vehicles occupy the largest volume share due to consumer familiarity and occlusion properties that enhance active absorption. Peptide ingredient types are recording the fastest trajectory as clinical substantiation for collagen signaling improves and dermatologist endorsement expands. Natural extract formulations sustain premium positioning in clean beauty channels despite higher raw material variability.
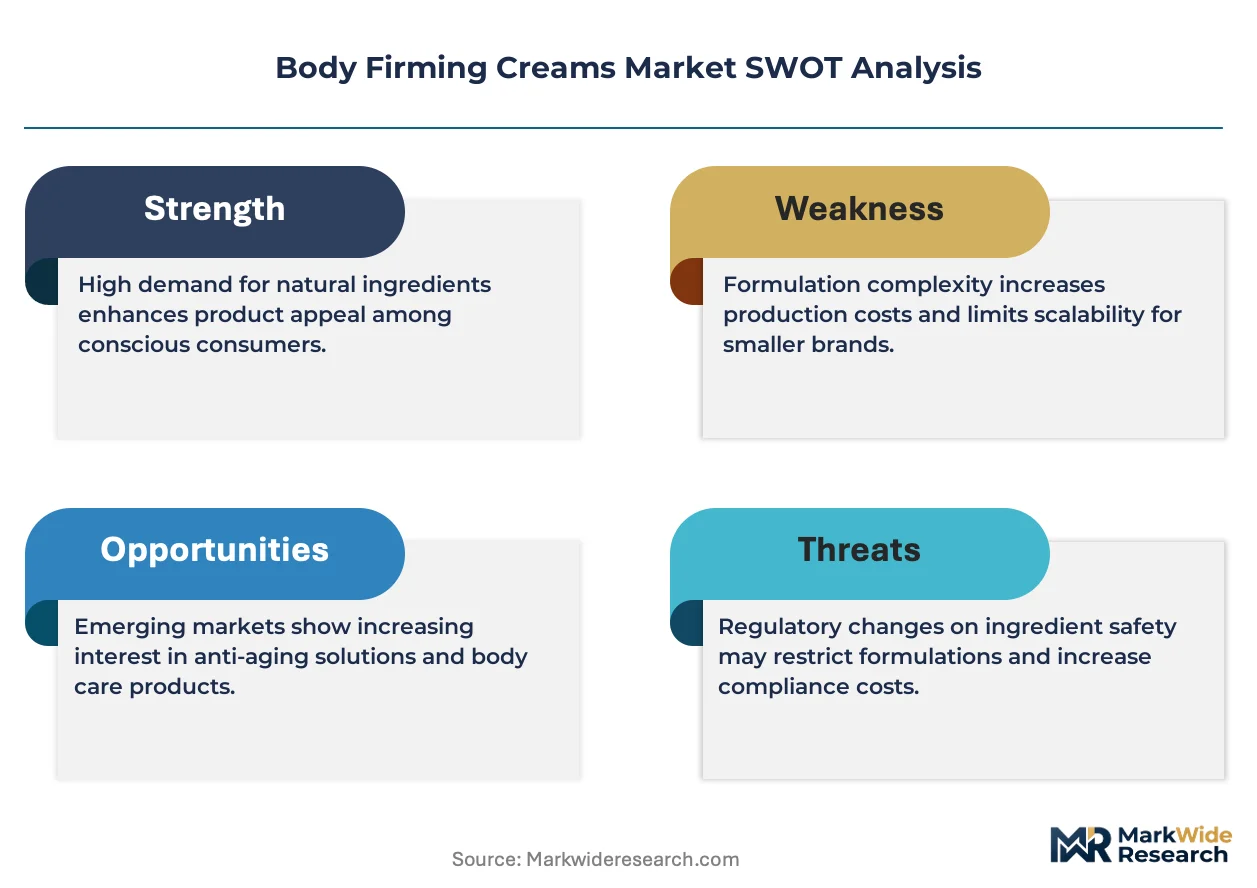
FDA oversight of cosmetic versus drug claims boundaries shapes how manufacturers position firming efficacy language on packaging and in professional channels. The EU Cosmetics Regulation (EC) No 1223/2009 and REACH compliance requirements for preservative systems and fragrance allergens determine market access for imported formulations into European retail networks. Stakeholders must monitor evolving substantiation standards for biome-friendly and microbiome-targeted claims as next-generation positioning territory.
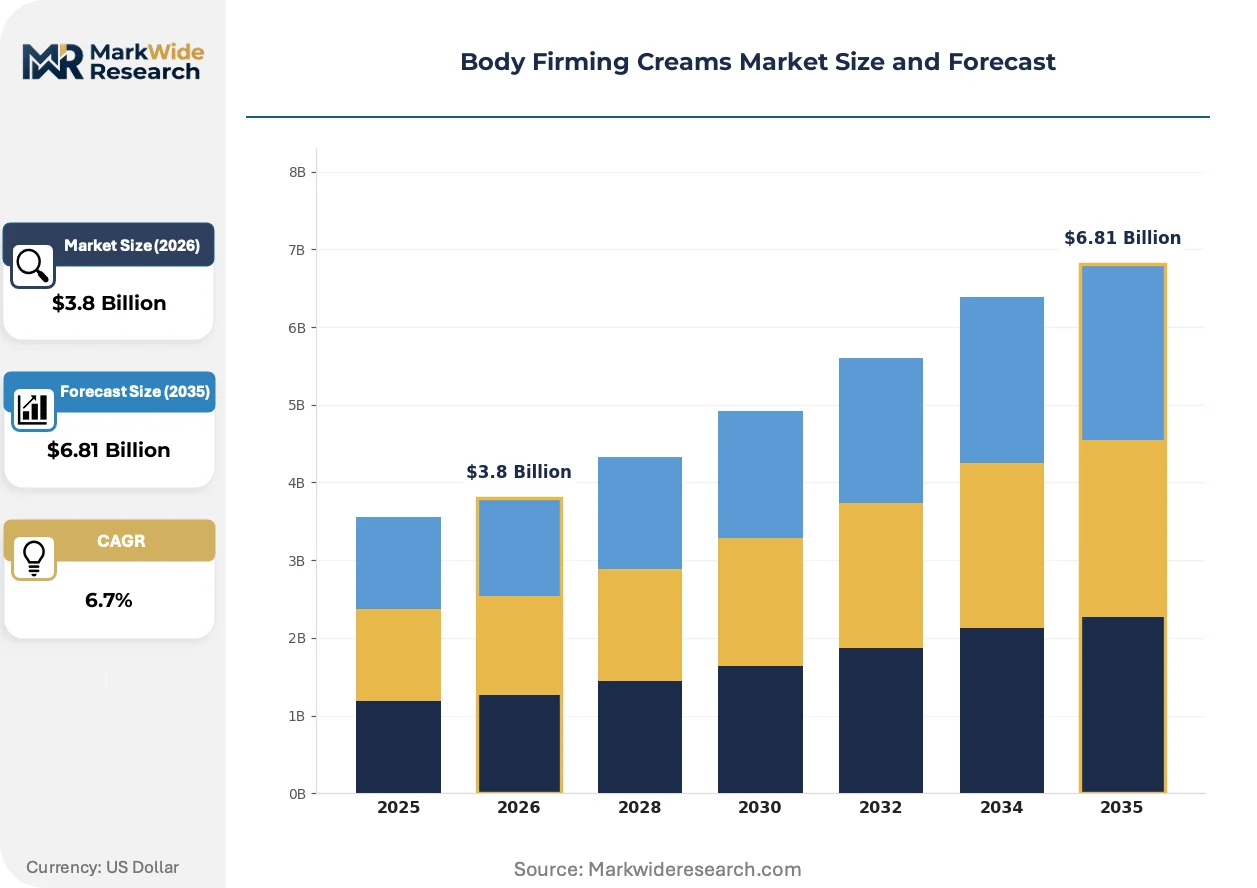
Market Dynamics
Postpartum recovery regimens are compressing product development cycles as manufacturers race to capture new mothers seeking skin elasticity restoration before competing alternatives reach shelf.
Growth Catalysts
- EU Cosmetics Regulation (EC) No 1223/2009:Tightening safety assessment requirements for topical firming actives are elevating barrier to entry for non-compliant imports, protecting incumbent positions.
- Peptide-delivery systems:Clinical substantiation for collagen signaling is expanding dermatologist endorsement channels and professional retail penetration.
- United States demand concentration:Premium dermatological brands command strong consumer loyalty through professional channel relationships and medical spa distribution.
Market Restraints
- Retinol raw material volatility:Pharmaceutical-grade retinol supply concentrates among three specialty chemical producers, creating input cost exposure.
- High-shear emulsification capex:Manufacturing scale requires specialized equipment that smaller formulators cannot access without contract manufacturing dependence.
- REACH compliance friction:Preservative system and fragrance allergen documentation demands extend European market entry timelines for Asian imports.
Strategic Opportunities
- Microbiome-targeted claims:Biome-friendly positioning represents next-generation territory as substantiation standards evolve and early movers capture premium shelf space.
- Clean beauty channel expansion:Natural extract formulations sustain premium pricing in specialty retail despite higher raw material variability.
- Professional channel deepening:Medical spa and dermatology clinic distribution offers margin protection against mass retail price compression.
Industry Challenges
- Cosmetic-drug claim boundary navigation:FDA oversight of firming efficacy language requires legal review of packaging and professional channel positioning.
- Emulsion technology talent scarcity:Formulation chemists with dermal penetration expertise command premium compensation and limited geographic mobility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Body Firming Creams Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Gels, Lotions, Serums Ingredient Type: Retinol, Peptides, Caffeine, Natural Extracts End User: Women, Men, Seniors, Athletes Packaging Type: Tubes, Jars, Bottles, Sachets |
| Companies Covered | Skinlys, Lady Burd, Cosmax, Dynamic Blending, Oxygen Development, Rysun, Kolmar Korea, SBLC Cosmetics, Intercos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Body Firming Creams Market Emerging Trajectories
Active delivery mechanisms and claim substantiation protocols are reconfiguring competitive advantage in body firming formulations, separating clinically validated platforms from commodity positioning.
Peptide complex technology is decomposing traditional retinol-centric formulation strategies. Postpartum women and aging skin segments are adopting peptide-based regimens at accelerating pace through dermatologist recommendation. This convergence is compressing market share for legacy retinol-dominant portfolios that lack comparable clinical trial investment.
REACH documentation requirements for preservative systems are extending reformulation cycles for European market access. Manufacturers must revalidate entire ingredient decks when supplier changes trigger new safety assessments. Natural extract formulations face the steepest compliance burden due to botanical variability and trace contaminant testing protocols.
Medical spa channel preference is displacing traditional department store discovery for premium body firming purchases. Aesthetic practitioners now curate retail assortments for take-home maintenance, capturing recurring revenue streams. This shift concentrates in United States coastal metropolitan markets where medical spa density exceeds national averages.
Body Firming Creams Market Segmentation
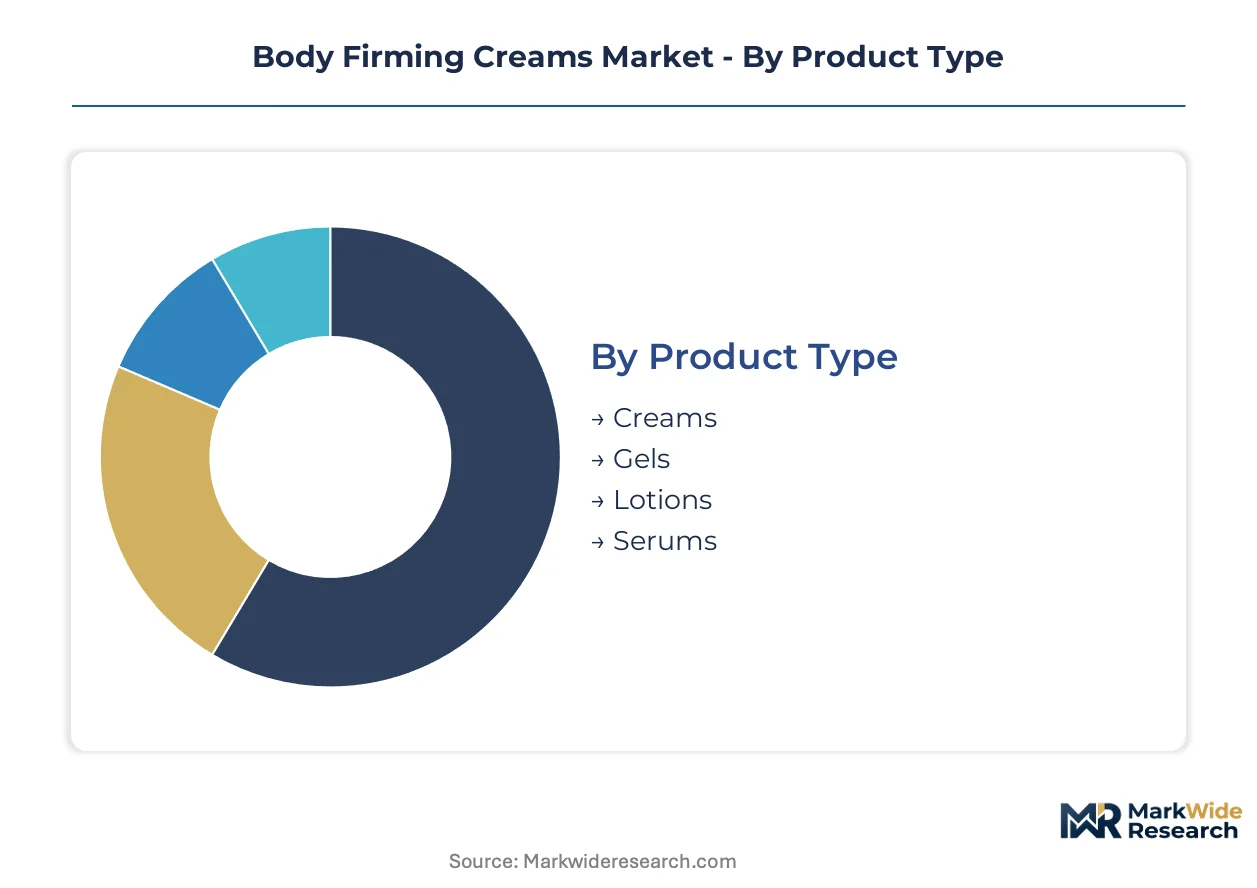
Segmentation in body firming creams determines manufacturing configuration, regulatory pathway, and channel strategy. Formulation chemistry and delivery vehicle selection drive substitution risk across adjacent personal care categories.
Product Type:
Creams face intensifying substitution pressure from serums in professional dermatology channels, while gels compete with body oils in athletic recovery applications.
- Creams:Occlusive emulsion bases containing 2-5% active concentrations achieve superior transepidermal penetration through sustained skin contact. Postpartum women in the United States favor cream vehicles for nighttime recovery regimens, driving premium positioning through medical spa distribution.
- Serums:Lightweight, water-based formulations with higher actives density penetrate faster but require complementary moisturization. Dermatology clinics in coastal metropolitan markets are displacing department store discovery with serum-forward take-home protocols.
- Gels:Quick-absorbing hydroalcoholic bases suit pre-activity application and warm-climate usage.
- Lotions:Lower viscosity emulsions target daily maintenance and price-sensitive mass retail placement.
Creams anchor the volume base while serums gain share at the steepest rate.
Ingredient Type:
Cost tier stratification separates pharmaceutical-grade synthetics from botanical alternatives, with peptide complexes commanding the highest per-kilogram input costs.
- Peptides:Short-chain amino acid sequences signal collagen synthesis through fibroblast activation. Clinical substantiation from South Korean R&D facilities is expanding dermatologist endorsement and professional channel penetration.
- Retinol:Vitamin A derivatives accelerate cell turnover but require stabilization against oxidation and photodegradation. Supply concentration among three specialty chemical producers in Germany and Switzerland creates formulation cost volatility.
- Caffeine:Lipolytic stimulant with temporary microcirculation effects, common in mass-market cellulite positioning.
- Natural Extracts:Botanical sourcing from Centella asiatica and green tea faces steep REACH documentation burdens for European market access.
Retinol formulations dominate current revenue while peptide complexes expand most quickly through clinical validation.
End User:
Application context varies sharply across life-stage demographics, with postpartum recovery representing the highest-engagement usage occasion.
- Women:Spanning postpartum, menopausal, and preventive aging applications with the broadest product repertoire. New mothers seeking skin elasticity restoration compress product development cycles as manufacturers race to capture regimen adoption.
- Seniors:Thinning dermis and reduced collagen density drive demand for intensive peptide protocols. Medical spa channel deepening in Florida and Arizona concentrates this segment through aesthetic practitioner curation.
- Men:Emerging category with simplified positioning around athletic recovery and abdominal definition.
- Athletes:Pre-competition tightening and post-training recovery applications favor gel and serum vehicles.
Women sustain the volume base while seniors climb the fastest through professional channel migration.
Packaging Type:
Supply concentration in tube manufacturing creates margin pressure for smaller formulators lacking captive production.
- Tubes:Laminated aluminum and plastic multi-layer structures dominate mass retail and travel-size segments. European tube converters face extended lead times due to REACH-compliant adhesive and barrier layer documentation.
- Jars:Wide-mouth glass and acrylic containers signal premium positioning in medical spa and specialty retail. Airless pump jars reduce preservative load for natural extract formulations targeting clean beauty channels.
- Bottles:Pump and flip-cap dispensers serve high-volume family and gym-bag usage contexts.
- Sachets:Single-use foil pouches enable trial sampling and hotel amenity distribution.
Tubes anchor the volume base while jars capture expanding share through professional channel premiumization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Busan anchors South Korea's cosmetics export infrastructure, enabling peptide-delivery system manufacturers to reach medical spa channels across the Pacific Rim within 72-hour cold-chain windows.
United States
Postpartum recovery regimens and medical spa channel deepening drive demand concentration along coastal metropolitan corridors. FDA oversight of cosmetic-drug claim boundaries shapes packaging language and professional channel positioning. Miami and Los Angeles aesthetic practitioner clusters curate take-home retail assortments, displacing traditional department store discovery.
South Korea
Captive R&D infrastructure for peptide-delivery systems serves the postpartum skin elasticity restoration segment. MFDS registration requirements for functional cosmetics create compliance moats around clinical substantiation investments. Seoul Capital Area manufacturing complexes supply contract formulation services to premium dermatological brands entering Asian markets.
Germany
Pharmaceutical-grade retinol supply concentration among specialty chemical producers creates formulation cost volatility for European brands. REACH documentation demands for preservative systems and fragrance allergens extend market entry timelines for imported formulations. Frankfurt-Rhine-Main logistics hubs distribute compliant batches to medical spa networks across Central Europe.
France
Clean beauty channel expansion sustains premium positioning for natural extract formulations despite botanical variability challenges. ANSM safety assessment protocols for topical firming actives align with EU Cosmetics Regulation tightening. Île-de-France formulation houses develop biome-friendly positioning as next-generation claim territory.
Japan
Preventive aging applications among seniors drive intensive peptide protocol adoption through aesthetic practitioner channels. METI standards for quasi-drug classification influence firming efficacy claim substantiation investments. Kansai region emulsion technology specialists command premium compensation due to formulation chemistry talent scarcity.
Body Firming Creams Market Vendor Landscape
Listed leaders compete with private specialists across manufacturing scale and clinical validation depth. The vendor base separates into three tiers: multinational conglomerates with captive R&D infrastructure, mid-scale contract manufacturers with regional formulation expertise, and boutique specialists serving clean beauty channels. Strategic moves concentrate on peptide-delivery system licensing and medical spa channel deepening.
Within the R&D-integrated tier, Cosmax exemplifies captive infrastructure deployment for peptide-delivery development. Kolmar Korea occupies a position representing manufacturing scale across multiple Asian markets. Intercos anchors the vertical control archetype through emulsion technology ownership and adjacent color cosmetic capabilities.
| Leading Market Players |
|---|
| Skinlys |
| Lady Burd |
| Cosmax |
| Dynamic Blending |
| Oxygen Development |
| Rysun |
| Kolmar Korea |
| SBLC Cosmetics |
| Intercos |
| Others |
Supply Flow & Price Mechanics
Sixty-to-ninety-day lead times for pharmaceutical-grade retinol from German and Swiss specialty chemical producers concentrate pricing power among incumbent formulators while compressing margin buffers for smaller competitors dependent on spot-market sourcing. This inventory compression dynamic reinforces tiered pricing separation between dermatologist-endorsed premium peptide protocols and mass-market caffeine-based alternatives.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies by clinical substantiation depth and channel positioning. Premium tiers command dermatologist endorsement premiums through peptide-delivery system patents, while standard tiers compete on retinol concentration claims and economy tiers trade caffeine-based temporary tightening at mass retail price points. Pricing pressure stems from raw material volatility in vitamin A derivative supply chains, with pharmaceutical-grade retinol input costs transmitting directly to mid-tier formulations. Medical spa channels exhibit lowest price sensitivity due to practitioner curation and take-home protocol bundling, whereas mass retail buyers demonstrate highest elasticity to promotional discounting.
Supply Chain Analysis
Strait of Malacca transit underwrites South Korean peptide-delivery system exports to Pacific Rim medical spa networks, creating logistics vulnerability for cold-chain-dependent active formulations. Manufacturing gravity centers on South Korea for captive R&D infrastructure, Germany for pharmaceutical-grade retinol synthesis, and Italy for emulsion technology specialists. Raw material dependencies span peptide complexes from Seoul Capital Area biotech facilities, retinol precursors from Basel and Frankfurt chemical producers, and botanical extracts facing REACH documentation burdens. Single-source vulnerability concentrates in high-shear emulsification equipment where three European OEMs control specialized manufacturing scale. Distribution runs through medical spa procurement networks in coastal United States metropolitan markets, bypassing traditional department store intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through medical spa channel consolidation along United States coastal corridors, with aesthetic practitioner networks consolidating retail assortment curation and displacing fragmented department store discovery.
For Market Incumbents: Compound clinical validation investments in peptide-delivery systems to defend against retinol-centric commodity substitution threatening legacy portfolios. Deepen vertical integration into captive emulsion technology production to offset formulation chemist talent scarcity and protect margin structure from contract manufacturing dependence. Prioritize medical spa channel control in Miami and Los Angeles aesthetic practitioner clusters where take-home protocol bundling sustains premium positioning. For New Entrants and Emerging Players: Clean beauty channel under-service by incumbent dermatological brands creates entry space for natural extract formulations with biome-friendly positioning despite higher raw material variability. Target postpartum recovery regimens in secondary United States metropolitan markets where medical spa density remains below coastal saturation levels. Pursue direct-to-practitioner sampling programs to bypass traditional retail slotting fee barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational conglomerate cosmetic divisions seeking to divest non-core body care assets amid portfolio rationalization pressures. Long-term viability favors peptide-delivery system specialists with captive South Korean R&D infrastructure and professional channel penetration depth. Watch FDA cosmetic-drug claim boundary enforcement intensity as inflection indicator for regulatory compliance cost escalation and incumbent protection effects.| Strategic Initiative | Industry Significance |
|---|---|
| Peptide-Delivery System Patent Expansion | Cosmax and Kolmar Korea leverage MFDS functional cosmetic registrations to block competitor clinical substantiation claims. |
| Medical Spa Channel Deepening | Aesthetic practitioner curation in Los Angeles and Miami corridors displaces department store discovery for premium positioning. |
| Backward Integration into Retinol Synthesis | German and Swiss pharmaceutical-grade producers face margin pressure from vertical integration moves by scale formulators. |
| Biome-Friendly Formulation Repositioning | ANSM and EU Cosmetics Regulation tightening creates first-mover advantage for substantiated microbiome-targeted claims. |
| Clean Beauty Channel Expansion | Natural extract formulations command premium shelf space in specialty retail despite REACH documentation burdens. |
Methodological Framework
Initial hypotheses were tested against primary input from formulation chemists, medical spa procurement directors, dermatology clinic administrators, and retail category buyers, then refined through secondary validation against FDA cosmetic registration databases, EU Cosmetics Regulation (EC) No 1223/2009 safety assessment filings, MFDS functional cosmetic approvals, and customs trade records for peptide complex and retinol precursor imports. Bottom-up segment sizing triangulated with top-down market reconstruction across product type, ingredient category, end-user demographic, and packaging format dimensions.
Variance-decomposition across the projection horizon disaggregates growth drivers by peptide complex adoption rates, medical spa channel penetration depth, postpartum demographic engagement intensity, and regulatory compliance cost transmission effects. Segmentation modeling incorporated formulation chemistry tiers, delivery vehicle preferences, professional versus mass retail channel splits, and geographic regulatory cluster differentiation. CAGRs derived from patient-level regimen adherence curves and practitioner protocol renewal rates, cross-referenced with raw material input cost trajectories and cold-chain logistics capacity expansion.
Underlying assumptions cover sustained dermatologist endorsement expansion for peptide protocols, with deviation risk concentrated in FDA cosmetic-drug claim boundary enforcement intensity and REACH documentation timeline extensions for botanical extract formulations. Practitioners should keep alternative scenarios live as EU Cosmetics Regulation amendment cycles and South Korean export logistics capacity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Europe Lip Care Products Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
Organic Beauty and Personal Care Ingredients Market
Beauty & Personal Care
North America Beauty Devices Market
Beauty & Personal Care
False Eyelashes Market
Beauty & Personal Care
Kids Shampoo Market
Beauty & Personal Care
Beauty Tools Market
Beauty & Personal Care
Online Cosmetics Market
Beauty & Personal Care
South Korea Dermocosmetics Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Pore Strips Market
Beauty & Personal Care
Salon Products Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Cosmetic Serum Market