
 Oil Control Shampoo Market | 2026-2036
Oil Control Shampoo Market Size, Share, and Industry Trends Forecast 2026-2036
Oil Control Shampoo Market Analytics
The gap between premium scalp-therapy formulations and mass-market commodity bottles is realigning how manufacturers allocate R&D budgets and shelf-space negotiations. Procter & Gamble leverages its dermatological testing infrastructure to command pharmacy and professional salon channels. Unilever sustains volume leadership through emerging-market distribution density and local brand portfolios. L'Oréal S.A. differentiates via its Kérastase and L'Oréal Professionnel lines that occupy the high-margin salon segment.
Oil control shampoo denotes a surfactant-based cleansing preparation containing sebum-regulating actives such as salicylic acid, zinc pyrithione, or clay derivatives, formulated to pH ranges between 4.5 and 5.5 to maintain scalp barrier integrity while removing excess lipids. Its primary commercial purpose spans consumer daily hygiene and professional trichological scalp management in salon and clinical settings. Sulfate-free formulations represent the fastest-expanding product type as consumers with sensitive or color-treated hair reject harsher anionic surfactants. Online retail channels are capturing disproportionate growth momentum, particularly through subscription models and direct-to-consumer dermatological brands that bypass traditional wholesale markups.
The US FDA oversees cosmetic labeling and safety substantiation under the Federal Food, Drug, and Cosmetic Act, while the EU's REACH and Cosmetic Product Regulation mandate exhaustive ingredient safety dossiers that filter out non-compliant suppliers. India's BIS and CDSCO are tightening import quality checks and local manufacturing standards for personal care actives, raising compliance costs for entrants. Stakeholders must monitor evolving regulatory divergence between permissive and precautionary jurisdictions to anticipate reformulation timelines and geographic launch sequencing.
Market Dynamics
Clean-label ingredient mandates from ECHA's REACH framework are forcing reformulation cycles across surfactant chemistry, compressing R&D timelines while opening premium positioning for compliant suppliers.
Growth Catalysts
- Humid climate demand:India's urban centers generate concentrated need for sebum-regulating formulations as heat and pollution intensify scalp oil production.
- REACH compliance premium:EU ingredient safety dossiers filter out non-compliant suppliers, rewarding manufacturers with pre-certified clean-label portfolios.
- Salon channel professionalization:Trichology clinics and high-end salons now specify pH-balanced, sulfate-free actives for client scalp treatments.
Market Restraints
- Surfactant input volatility:Coconut-derived mild surfactants face price instability from agricultural commodity swings and shipping bottlenecks.
- Supplier concentration in specialty actives:Zinc pyrithione and salicylic acid production clusters in Chinese chemical manufacturing zones.
- Regulatory divergence friction:India's BIS import quality checks and CDSCO manufacturing standards create compliance cost asymmetries versus permissive jurisdictions.
Strategic Opportunities
- Subscription direct-to-consumer models:Dermatological brands bypass wholesale markups through recurring delivery platforms.
- Southeast Asia urbanization:Vietnam and Indonesia present underpenetrated demand as middle-class consumers adopt specialized hair care routines.
- EU Green Deal chemical transition:Biodegradable surfactant incentives accelerate bio-based formulation R&D.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in scalp microbiome-compatible actives remains concentrated in Western European and Japanese R&D hubs.
- Legacy sulfate inventory:Mass-market brands face write-down pressure as retailers delist non-compliant SKUs ahead of regulatory deadlines.
- Multi-jurisdiction dossier management:Divergent safety substantiation requirements between FDA, REACH, and BIS stretch regulatory affairs capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil Control Shampoo Market |
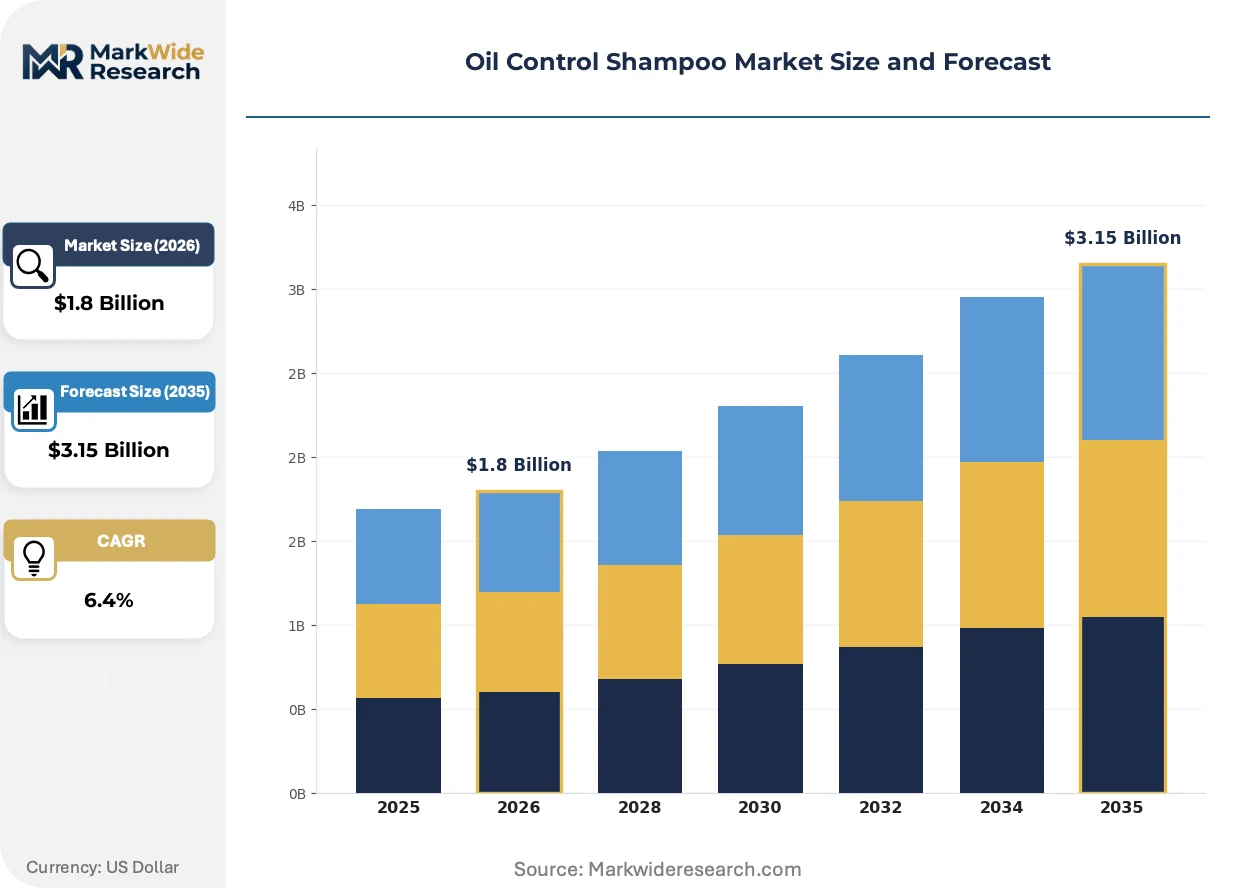
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Daily Shampoo, Clarifying Shampoo, Dry Shampoo, Sulfate-Free Shampoo Customer Type: Men, Women, Teens, Salons Application: Oily Scalp, Dandruff Treatment, Hair Smoothing, Daily Care Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Pharmacies |
| Companies Covered | Procter & Gamble, Unilever, L'Oréal S.A., Henkel AG & Co. KGaA, Johnson & Johnson, Kao Corporation, Shiseido Company, Limited, Beiersdorf AG, AmorePacific, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil Control Shampoo Market Evolving Landscape
Formulation science is pivoting toward scalp barrier preservation rather than aggressive lipid stripping, with pH optimization and microbiome compatibility now central to product architecture decisions.
Prebiotic-infused surfactant systems are consolidating technical credibility among dermatologist-recommended brands. Salon professionals and trichology clinics specify these formulations for sensitive scalp protocols. The technology is consolidating supplier power toward biotech ingredient houses with clinical validation capabilities.
REACH's extended safety data requirements for cosmetic actives are compressing the approved ingredient list for sebum regulators. Manufacturers must resubmit dossiers for legacy preservatives and stabilizers. Salon-exclusive and pharmacy-channel brands absorb compliance costs more readily than mass-market lines.
Subscription-based replenishment models are displacing supermarket impulse purchases among millennial and Gen-Z buyers. Direct-to-consumer dermatological brands capture recurring revenue through personalized scalp assessment tools. This shift concentrates most visibly in US and UK metropolitan markets where delivery infrastructure and digital payment penetration support auto-replenishment adoption.
Oil Control Shampoo Market Segmentation
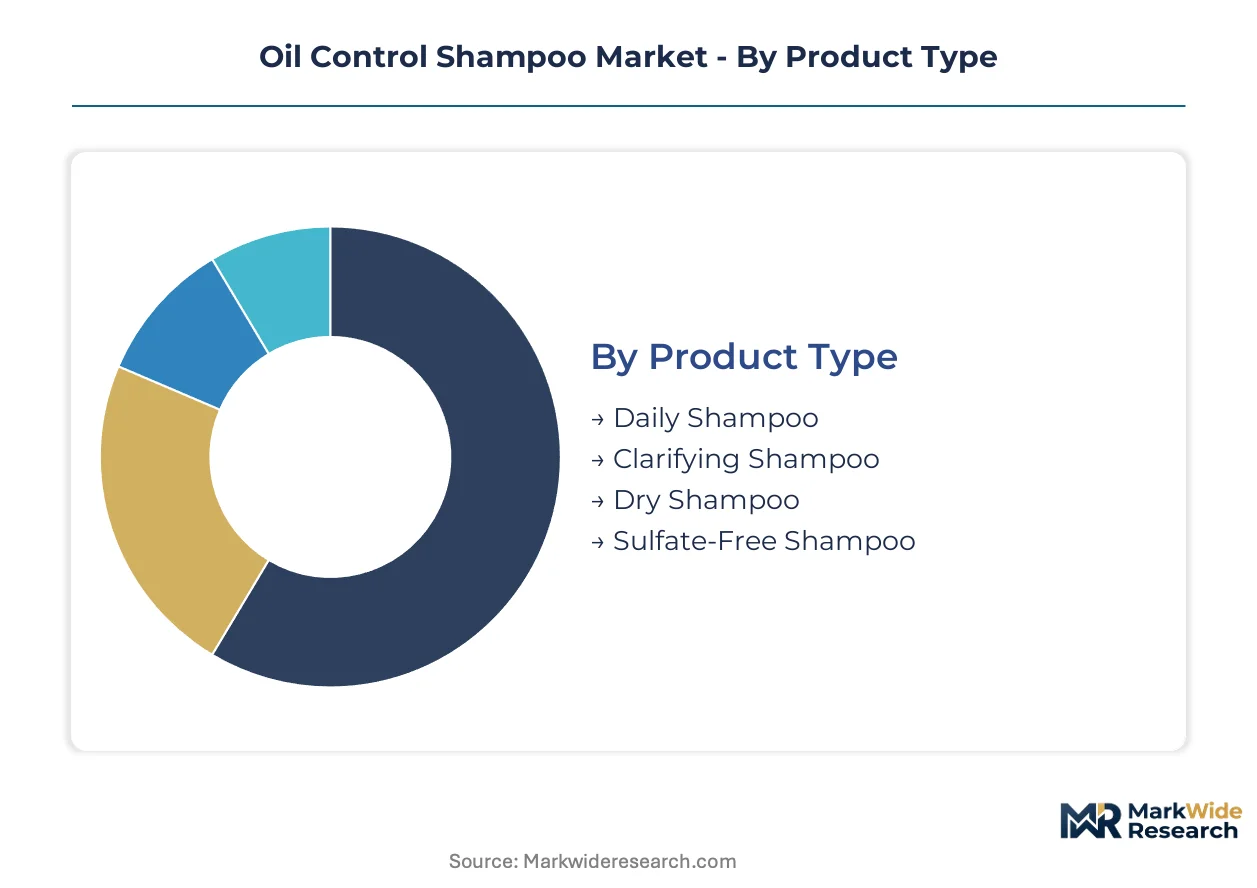
Segmentation in oil control shampoo markets reveals divergent compliance burdens and channel economics. Manufacturers must align formulation architectures with distinct certification requirements across salon, retail, and clinical entry points.
Product Type:
REACH dossier requirements and FDA cosmetic substantiation rules apply unevenly across formulation chemistries, with sulfate-free variants demanding the most extensive safety documentation.
- Sulfate-Free Shampoo:Formulations replace sodium lauryl sulfate with coconut-derived glucosides or amino acid surfactants to preserve color-treated hair and sensitive scalps. Demand clusters in US and UK metropolitan subscription channels where consumers pay premiums for dermatologist-recommended protocols.
- Clarifying Shampoo:High-strength chelating agents and apple cider vinegar derivatives strip accumulated silicones and hard water minerals. Salon professionals in humid Indian cities specify these for pre-treatment scalp preparation ahead of chemical services.
- Daily Shampoo:Mild sebum regulators at pH 4.5-5.5 for routine lipid management without barrier disruption.
- Dry Shampoo:Starch and clay-based aerosol or powder formats for waterless oil absorption between washes.
Leading the category by volume: Daily Shampoo. Growing fastest: Sulfate-Free Shampoo.
Customer Type:
Procurement authority and price sensitivity diverge sharply between institutional buyers and individual consumers, reshaping packaging formats and unit economics.
- Salons:Professional-only liter bottles with concentrated actives require trichology training for proper application. Indian salon chains and US trichology clinics drive specification of pH-balanced, prebiotic-infused protocols.
- Women:Primary household purchasers across all distribution channels, with elevated willingness to pay for multi-benefit formulations addressing oil, volume, and color preservation simultaneously.
- Men:Simplified routines favor 2-in-1 conditioning variants or medicated formats with visible scalp benefits.
- Teens:Price-conscious segment responsive to influencer marketing and social commerce discovery.
Highest margin concentration: Salons. Steepest volume expansion: Women.
Application:
Clinical positioning versus cosmetic positioning determines whether products navigate drug-device regulatory boundaries or remain in cosmetic classification.
- Oily Scalp:Core indication for sebum-regulating zinc pyrithione or salicylic acid formulations at therapeutic concentrations. Indian urban demand surges as heat and pollution intensify lipid overproduction.
- Dandruff Treatment:Antifungal actives including ketoconazole and climbazole require OTC or prescription pathways in FDA jurisdictions. Pharmacy channel placement demands substantiation dossiers beyond cosmetic-grade requirements.
- Hair Smoothing:Keratin-compatible formulations that cleanse without stripping straightening treatments.
- Daily Care:Maintenance-focused variants balancing mild cleansing with conditioning agents.
Revenue concentration: Oily Scalp. Regulatory complexity peak: Dandruff Treatment.
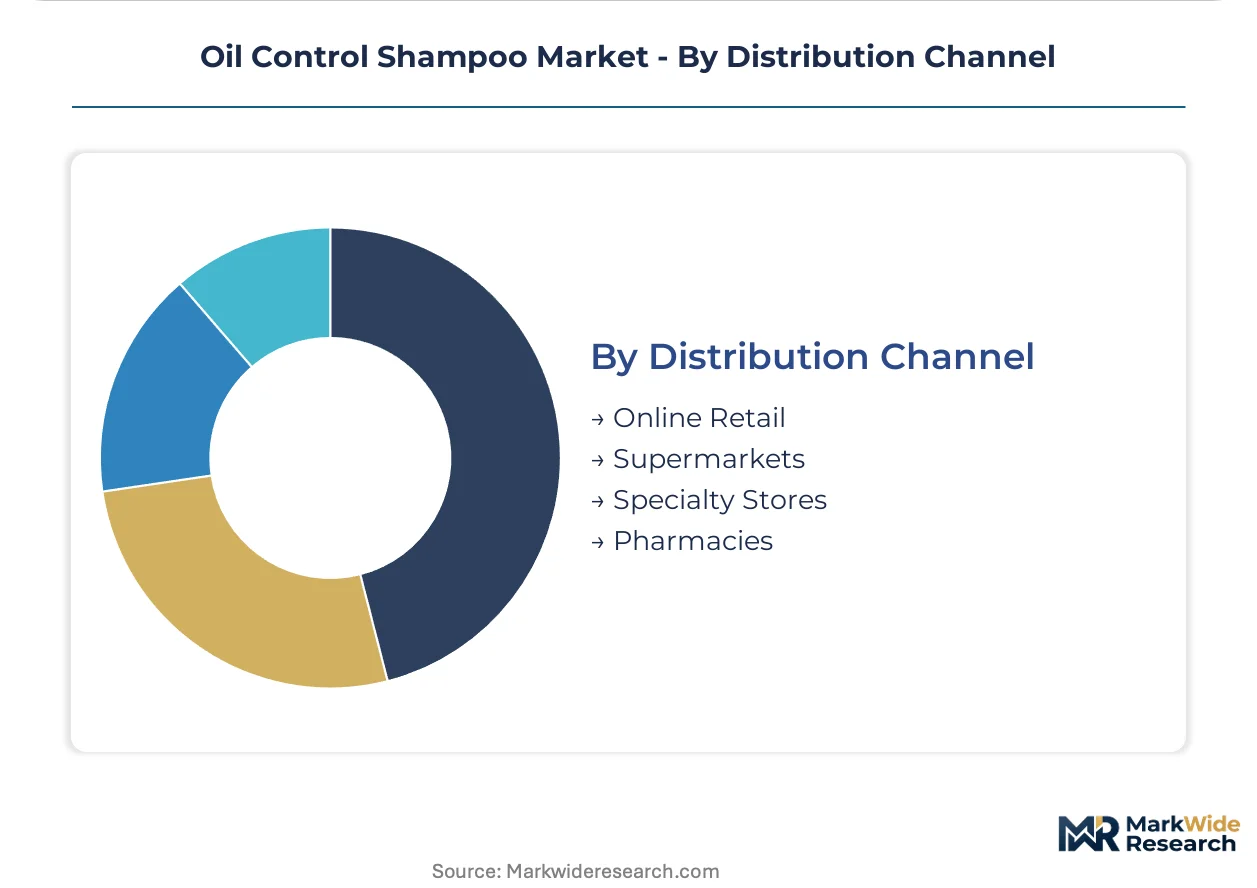
Distribution Channel:
Channel selection determines margin structure, with direct-to-consumer models capturing recurring revenue while traditional retail faces delisting pressure from clean-label mandates.
- Online Retail:Subscription platforms and DTC dermatological brands bypass wholesale markups through personalized scalp assessments and auto-replenishment. UK and US metro markets show highest penetration.
- Pharmacies:Clinically positioned brands leverage pharmacist recommendation authority. EU pharmacy chains increasingly require REACH-compliant ingredient transparency as standard listing condition.
- Specialty Stores:Curated assortments in beauty retailers and trichology clinics.
- Supermarkets:Mass-market volume channel facing SKU rationalization as retailers delist non-compliant formulations ahead of regulatory deadlines.
Margin leadership: Online Retail. Volume foundation: Supermarkets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors the oil control shampoo industry's commercial gravity through its humid coastal climate and dense network of trichology clinics prescribing sebum-regulating formulations. The city's salon chains and pharmacy retailers stock concentrated liter formats for professional scalp treatments. This concentration pattern repeats across four additional national markets where climate conditions and regulatory frameworks reshape local demand.
United States
New York and Los Angeles metro areas drive subscription-based direct-to-consumer adoption for sulfate-free dermatological brands. FDA cosmetic labeling requirements under the Federal Food, Drug, and Cosmetic Act mandate safety substantiation for sebum-regulating actives. Pharmacy chains in California and Texas increasingly require pH-balanced formulation documentation as standard listing conditions.
India
Bangalore and Chennai generate concentrated demand for clarifying pre-treatment formulations ahead of chemical hair services. BIS import quality checks and CDSCO manufacturing standards raise compliance costs for specialty actives like zinc pyrithione. Salon chains in Maharashtra and Gujarat specify professional-grade pH protocols for humid climate scalp management.
Germany
Düsseldorf and Hamburg host formulation R&D clusters developing REACH-compliant surfactant alternatives. ECHA's extended safety data requirements compress approved ingredient lists for sebum regulators. Pharmacy retailers in Bavaria and North Rhine-Westphalia demand exhaustive ingredient transparency as mandatory shelf placement criteria.
Japan
Tokyo and Osaka metropolitan markets sustain premium positioning for scalp microbiome-compatible formulations. METI standards and PMDA cosmetic oversight emphasize barrier-preserving pH optimization. R&D facilities in Kanagawa Prefecture concentrate expertise in prebiotic-infused surfactant systems for sensitive scalp protocols.
Brazil
São Paulo's tropical humidity drives volume demand for daily sebum-regulating shampoos. ANVISA cosmetic regulations mandate ingredient disclosure standards that filter out non-compliant suppliers. Manufacturing clusters in Rio de Janeiro and Minas Gerais serve as distribution hubs for Latin American salon channel expansion.
Oil Control Shampoo Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation certification tiers, with dermatologist-recommended brands commanding pharmacy and salon channels while mass-market lines face supermarket delisting pressure. The vendor base stratifies between multinational consumer goods conglomerates with dermatological testing infrastructure, regional specialists with local brand portfolios, and direct-to-consumer dermatological startups with subscription platforms. Two dominant competitive moves define current positioning: portfolio diversification into scalp-therapy extensions and geographic expansion through emerging-market distribution partnerships.
Within the multinational conglomerate tier, Procter & Gamble, Unilever, and L'Oréal S.A. represent three distinct strategic archetypes. Cincinnati-based Procter & Gamble exemplifies pharmacy-channel leverage through dermatological testing infrastructure. London-headquartered Unilever occupies the emerging-market volume position via distribution density and local brand portfolios. French S.A.-structured L'Oréal anchors the high-margin salon segment through professional-only lines. These three entities collectively demonstrate how regulatory compliance capabilities, channel access, and geographic footprint determine tier placement.
| Leading Market Players |
|---|
| Procter & Gamble |
| Unilever |
| L'Oréal S.A. |
| Henkel AG & Co. KGaA |
| Johnson & Johnson |
| Kao Corporation |
| Shiseido Company, Limited |
| Beiersdorf AG |
| AmorePacific |
| Others |
Value Network & Pricing Analysis
Captive surfactant sourcing from coconut-derived glucoside suppliers in Southeast Asia anchors both supply security and premium pricing power for REACH-compliant manufacturers. This backward integration choice insulates formulators from agricultural commodity swings while justifying tiered pricing premiums across salon and pharmacy channels.
Pricing Analysis
Outcome-based pricing tied to scalp barrier restoration anchors the salon and pharmacy tiers. Three-tier pricing structure across premium, standard, and economy levels separates dermatologist-recommended protocols from mass-market commodity bottles. Price differentiation rests on certification grade—REACH dossier completeness and pH-balanced formulation documentation—rather than surfactant chemistry alone. Cost compression in the supermarket tier is intensifying because retailers delist non-compliant SKUs ahead of regulatory deadlines, making price-sensitive teens and mass-market households the most vulnerable segments while salon professionals absorb premiums for trichology-validated actives.
Supply Chain Analysis
Single-source vulnerability sits with zinc pyrithione and salicylic acid production clusters in Chinese chemical manufacturing zones. Coconut-derived mild surfactants draw from Indonesia and the Philippines, while specialty prebiotic actives source from Western European biotech houses. Tariff exposure on imported actives compounds regulatory friction as India's BIS and CDSCO tighten import quality checks. Distribution runs through layered wholesale networks for mass-market SKUs, whereas direct-to-consumer subscription platforms bypass traditional markups entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
ECHA's REACH framework operates as a cost-of-compliance moat, filtering out undercapitalized entrants while rewarding manufacturers with pre-certified clean-label portfolios and established dossier management capabilities.
For Market Incumbents: Cement pharmacy-channel authority through dermatological testing infrastructure investments that validate pH-balanced, prebiotic-infused formulations. Deepen captive supply of coconut-derived glucosides to buffer agricultural commodity volatility. Counter direct-to-consumer dermatological startups by acquiring subscription platform capabilities or forging exclusive salon distribution partnerships. For New Entrants and Emerging Players: Trichology clinics and high-end salon chains represent the most penetrable channel anchor for REACH-compliant specialty formulations. White-space targets include humid-climate urban centers in Vietnam and Indonesia where middle-class consumers adopt specialized scalp care routines. A subscription-based auto-replenishment model with personalized scalp assessment tools offers the cleanest go-to-market angle against entrenched mass-market brands. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by multinational consumer goods conglomerates seeking dermatological credibility and salon-channel access. Long-term viability favors biotech ingredient houses with clinical validation capabilities and clean-label portfolios that absorb REACH compliance costs more readily than commodity surfactant blenders. Watch for inflection signals in BIS import quality check enforcement intensity, which will accelerate supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Clean-Label Portfolio Repositioning | REACH dossier completeness secures pharmacy listings ahead of regulatory delisting waves. |
| Subscription Platform Launch | DTC dermatological brands capture recurring revenue through personalized scalp assessment tools. |
| Salon Channel Exclusive Distribution | Professional-only liter formats with concentrated actives command premium margins. |
| Southeast Asia Distribution Partnership | Vietnam and Indonesia present underpenetrated humid-climate demand for sebum-regulating formulations. |
| Prebiotic Surfactant R&D Investment | Scalp microbiome-compatible actives consolidate technical credibility among trichology clinics. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with formulation chemists, salon chain procurement directors, pharmacy retail buyers, and regulatory affairs specialists at multinational consumer goods firms combined with ECHA dossier databases, FDA cosmetic substantiation filings, and BIS import quality check records. Bottom-up volume modeling across product type, customer segment, application, and distribution channel triangulated against top-down market sizing from customs records and retail audit data.
Segment-level granularity modeled formulation chemistry, channel economics, and geographic regulatory clusters across the projection horizon. CAGRs derived from trend extrapolation of salon professional adoption rates, subscription platform penetration curves, and REACH compliance cost absorption patterns. Industry-specific forecast inputs included trichology clinic specification trends and humid-climate urbanization trajectories in target emerging markets.
Caveats apply where regulatory enforcement intensity shifts, agricultural commodity volatility in coconut-derived surfactants, or supply chain disruptions in Chinese specialty active manufacturing could materially shift the outlook. Forecasts reflect assumptions about clean-label mandate adoption timelines and salon channel professionalization rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Heated Eyelash Curlers Market
Beauty & Personal Care
Kids Shampoo Market
Beauty & Personal Care
Rice Shampoo Bar Market
Beauty & Personal Care
North America Setting Spray Market
Beauty & Personal Care
Anti-Aging Beauty Device Market
Beauty & Personal Care
Men's Personal Care Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Nail Polish Remover Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
ASEAN Organic Cosmetics Market
Beauty & Personal Care
Australia Facial Care Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Europe Sustainable Personal Care Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Portable Atomizer Market