
 Facial Epilator Market | 2026-2036
Facial Epilator Market Size, Share, and Industry Trends Forecast 2026-2036
Facial Epilator Market Foresight
Subscription-based blade replacement programs and app-connected skin-sensing software is repositioning facial epilators from one-time hardware purchases into recurring-revenue beauty systems. Braun leverages its German engineering heritage to sustain premium positioning across European pharmacy channels. Philips anchors its portfolio with rechargeable cordless platforms that integrate IPL tracking algorithms. Emjoi specializes in compact travel-format devices that occupy budget-tier retail shelf space in North American drugstore chains.
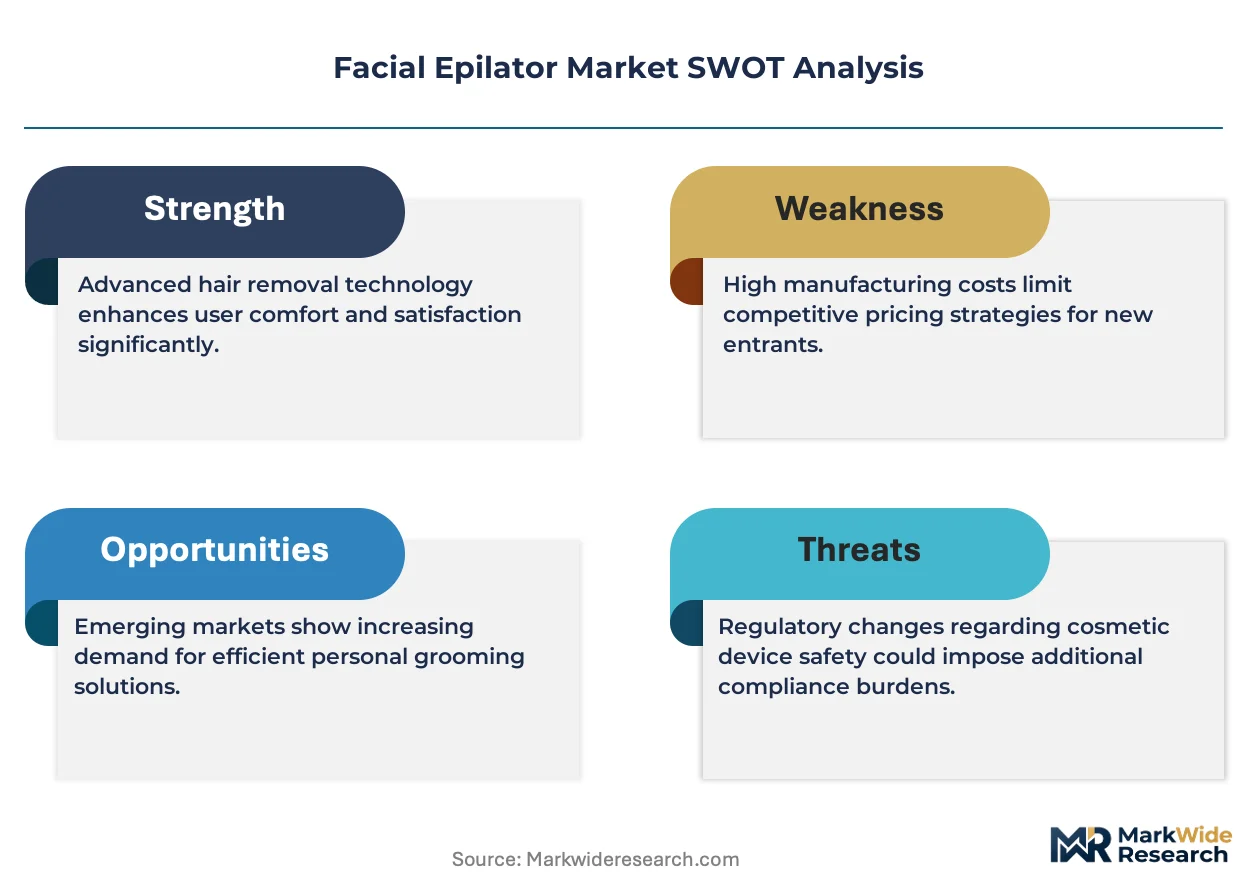
A facial epilator is a mechanical or energy-based hair removal device designed for facial skin, typically employing rotating tweezer discs, pulsating coils, or directed light energy operating at wavelengths between 600-1200 nanometers to extract or disable individual follicles. These devices serve both consumer household grooming routines and professional aesthetic treatments where precision and reduced irritation relative to waxing or threading command priority. Cordless rechargeable units now lead volume shipments as lithium-ion battery density improvements enable salon-grade motor torque in palm-sized housings. The professional and beauty clinic end-user segment captures the fastest expansion as med-spas bundle epilation into broader facial rejuvenation service menus. Laser and thermolysis technologies concentrate margin pools at premium price tiers where FDA 510(k) clearance and CE MDR certification create regulatory moats against unbranded competitors.
The FDA Center for Devices and Radiological Health classifies laser-based facial epilators as Class II medical devices requiring 510(k) premarket notification, while the EU MDR and REACH frameworks mandate biocompatibility testing and restricted substance documentation for all devices contacting skin. These regulatory layers elevate compliance costs for new entrants but reinforce quality differentiation for established manufacturers with dedicated regulatory affairs teams. Stakeholders must monitor evolving state-level laser practitioner licensing requirements in the United States and accumulating ECHA guidance on nickel release from stainless steel tweezer components. The decisive variable ahead is whether at-home IPL devices achieve parity with professional diode-laser efficacy without triggering stricter medical device reclassification.
Market Dynamics
Subscription blade-replacement programs and app-integrated skin-sensing software are converting facial epilators from single-transaction hardware into recurring-revenue beauty platforms, restructuring manufacturer cash flows and retail partnerships.
Growth Catalysts
- EU Medical Device Regulation:The EU MDR's tightened biocompatibility requirements for skin-contact devices elevate compliance costs for unbranded competitors, reinforcing quality differentiation for established manufacturers with dedicated regulatory affairs teams.
- Med-spa service bundling:Professional beauty clinics are expanding adoption of rechargeable cordless units as they integrate precision epilation into broader facial rejuvenation treatment menus.
- Lithium-ion battery density improvements:Advances in portable power systems now enable salon-grade motor torque within palm-sized housings, erasing performance gaps between professional and at-home devices.
Market Restraints
- FDA 510(k) clearance timelines:The FDA Center for Devices and Radiological Health's premarket notification requirements for laser-based systems extend commercialization cycles and elevate legal compliance expenditures.
- Nickel release constraints:Accumulating ECHA guidance on stainless steel tweezer components threatens supply continuity for manufacturers dependent on conventional metal formulations.
- Waxing and threading persistence:Traditional mechanical hair removal methods retain cost advantages and cultural familiarity across price-sensitive consumer segments.
Strategic Opportunities
- South Korean beauty tech convergence:The country's advanced semiconductor and optics ecosystem enables integration of IPL tracking algorithms with consumer electronics manufacturing scale.
- Travel-format device expansion:Compact portable units targeting airline carry-on compliance open distribution through duty-free retail and hospitality amenity channels.
- State-level laser practitioner licensing:Evolving United States regulatory frameworks create certified training program revenue streams and professional-grade device upgrade cycles.
Industry Challenges
- Photonics engineering talent scarcity:The specialized skill set required for safe 600-1200 nanometer wavelength system design concentrates in Germany, the United States, and South Korea, constraining product development velocity elsewhere.
- CE MDR technical documentation:The expanded clinical evidence requirements for Class IIa and IIb skin-contact devices extend certification timelines and documentation burdens.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Facial Epilator Market |
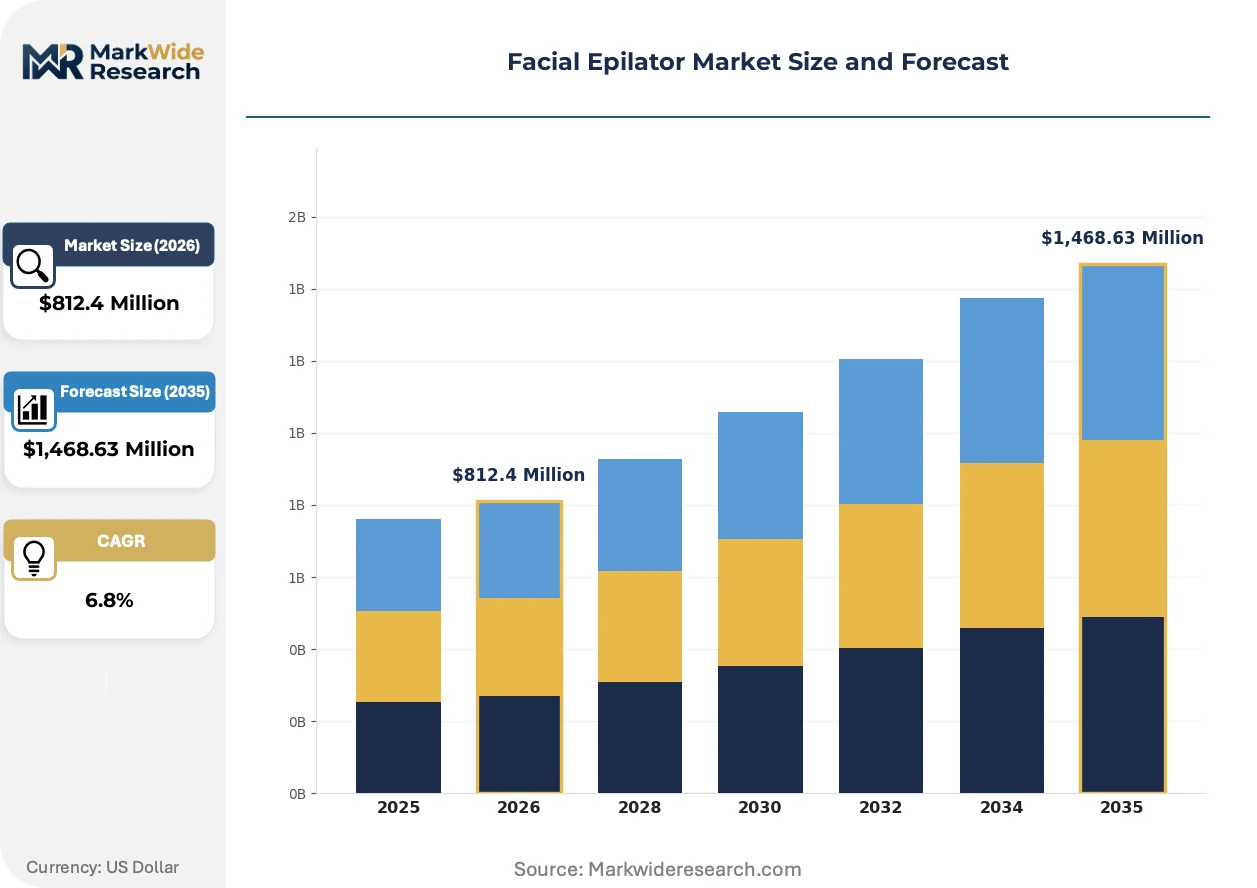
| Market Size in 2026 | $812.4 Million |
| Market Size in 2035 | $1,468.63 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Corded, Cordless, Rechargeable, Disposable Technology: Rotary, Pulsating, Laser, Thermolysis End User: Household, Professional, Spa, Beauty Clinics Price Tier: Budget, Mid-Range, Premium, Luxury |
| Companies Covered | Spectrum Brands Holdings, Tria Beauty, Braun, Epilady, Emjoi, Philips, Syneron Candela, Bellabe, P&G, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Facial Epilator Market Shifts & Advancements
Intelligent hardware-software integration and wavelength-specific energy delivery systems are redefining efficacy benchmarks and safety protocols across both consumer and professional facial epilation segments.
Intense Pulsed Light platforms with real-time melanin-sensing feedback loops are electrifying the premium at-home segment. These systems automatically calibrate energy output based on individual skin tone readings, reducing adverse event risk. Med-spa chains in Germany and South Korea are piloting comparable professional-grade diode-laser variants that compress treatment session duration while maintaining follicle disablement rates.
REACH framework amendments on restricted substances in electrical equipment are forcing reformulation of housing polymers and adhesive compounds used in tweezer-disc assemblies. Manufacturers with pre-existing European regulatory infrastructure are accelerating biocompatibility testing documentation to maintain market access. The professional clinic segment faces the most acute compliance pressure given its higher device utilization rates and stricter liability exposure.
Beauty appliance procurement through pharmacy and drugstore channels is fragmenting as direct-to-consumer subscription models capture recurring blade and cartridge revenue. Traditional retailers in North American and European markets are responding with exclusive colorway partnerships and bundled skincare product offerings. Germany's pharmacy channel retains the strongest resistance to this shift due to regulatory restrictions on promotional pricing and consultation requirements for laser-classified devices.
Facial Epilator Market Segmentation
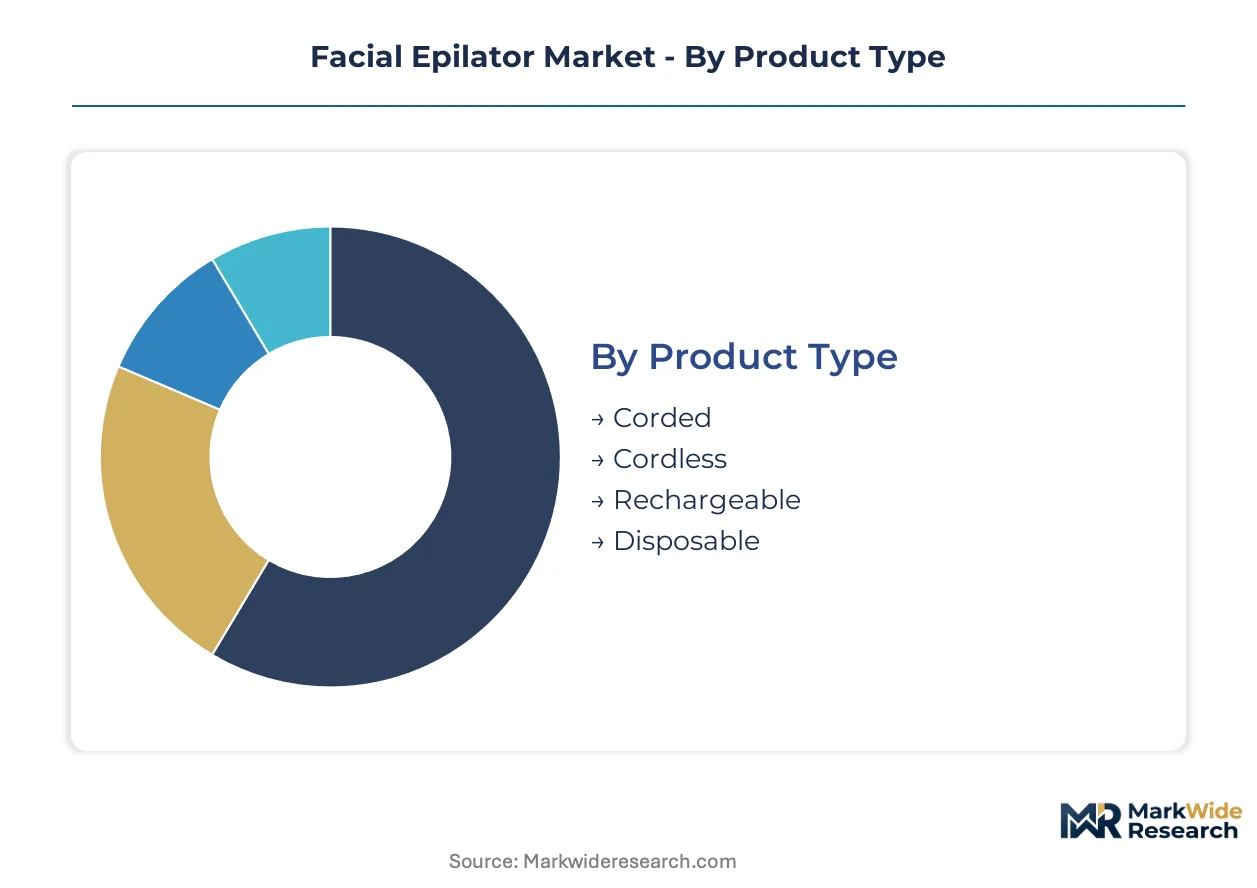
Facial epilator purchasing decisions hinge on power source reliability, treatment precision requirements, and regulatory compliance thresholds. Each segmentation axis reveals distinct margin structures and channel strategies that manufacturers must navigate.
Product Type:
Power autonomy dictates where devices compete—corded units anchor professional settings while battery innovations unlock mobility.
- Corded:Delivers uninterrupted salon-grade torque for extended treatment sessions. Demand concentrates in German and South Korean professional beauty clinics where electrical infrastructure reliability supports tethered operation.
- Cordless:Lithium-ion density advances now match corded performance in palm-sized housings. Med-spa chains in the United States are expanding cordless adoption to enable flexible treatment room configurations.
- Rechargeable:USB-C charging compatibility and rapid-cycle batteries dominate pharmacy channel placements across European markets.
- Disposable:Single-use spring-coil mechanisms target travel retail and airline amenity programs with minimal price points.
Rechargeable units lead on scale; cordless platforms lead on momentum.
Technology:
Energy delivery mechanisms separate efficacy tiers and regulatory classification burdens.
- Rotary:Rotating tweezer discs mechanically extract follicles through coordinated plucking action. German pharmacy channels favor rotary systems for their established safety profiles under EU MDR documentation requirements.
- Pulsating:Electromagnetic coil arrays generate rapid thermal disruption of follicle structures. Household demand in South Korea concentrates here due to compact form factors enabled by semiconductor miniaturization.
- Laser:Diode systems operating at 600-1200 nanometers require FDA 510(k) clearance and CE MDR Class IIa certification.
- Thermolysis:Radiofrequency-based follicle disablement commands premium pricing in United States med-spa chains.
Rotary mechanisms dominate unit volumes; laser platforms command margin concentration.
End User:
Usage environment determines durability specifications, liability exposure, and service revenue potential.
- Household:Consumer-grade housings with simplified interfaces and reduced power output. United States direct-to-consumer subscription models are capturing recurring blade revenue from this base.
- Professional:Clinic-grade devices with extended duty cycles and serviceable component architecture. German beauty clinics drive demand for professional units with integrated IPL tracking algorithms.
- Spa:Aesthetic treatment centers bundling epilation with facial rejuvenation protocols.
- Beauty Clinics:Medical-aesthetic hybrid facilities requiring full FDA 510(k) or CE MDR Class IIb documentation.
Household users generate the highest shipment volumes; beauty clinics show the steepest expansion trajectory.
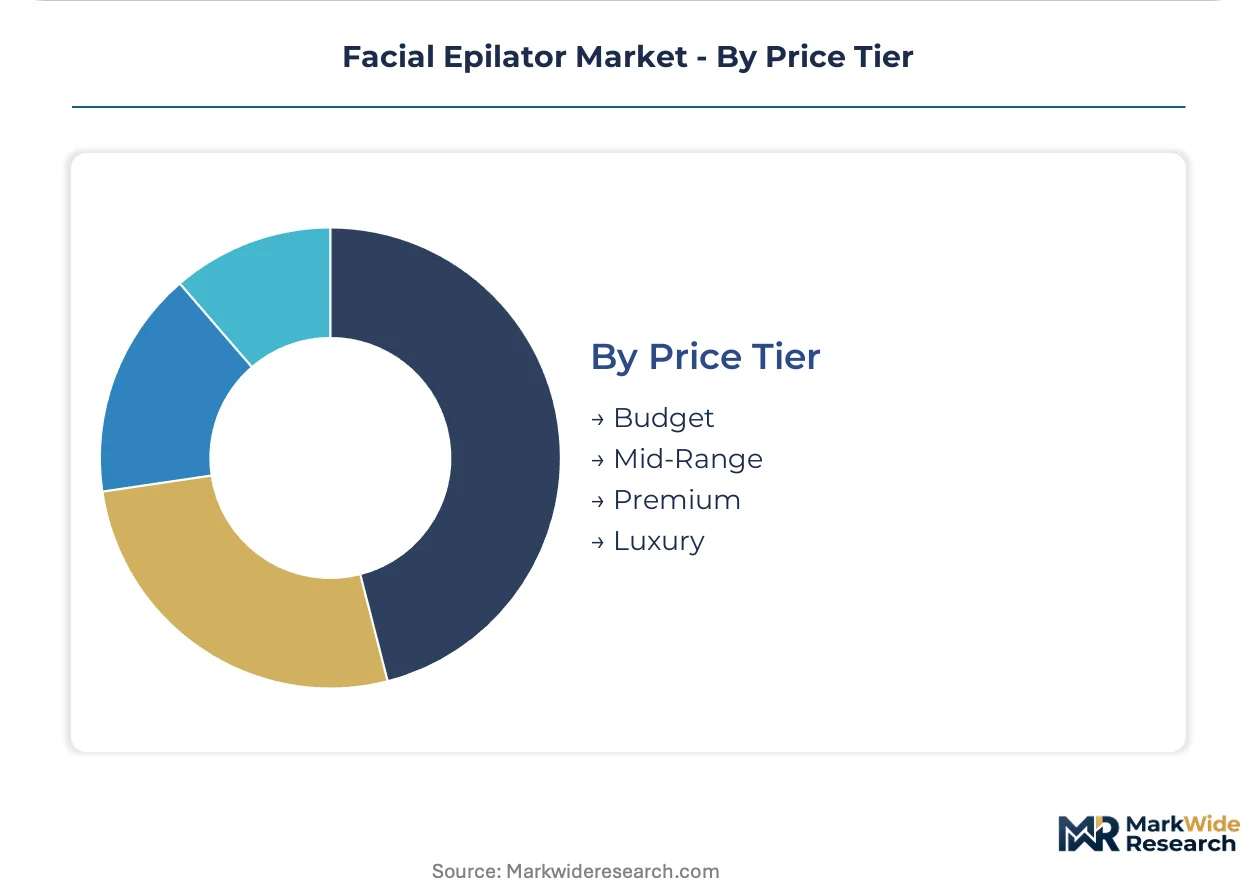
Price Tier:
Certification grade and component sourcing separate pricing strata more than raw feature counts.
- Budget:Spring-coil or basic rotary mechanisms with plastic housings. North American drugstore chains and Emjoi's travel-format positioning concentrate demand here.
- Mid-Range:Rechargeable lithium-ion platforms with replaceable tweezer heads. European pharmacy channels favor this tier for its balance of performance and regulatory documentation accessibility.
- Premium:IPL and entry laser systems with melanin-sensing feedback loops.
- Luxury:Professional-grade diode lasers with full medical device certification and training program bundling.
Mid-range products anchor revenue stability; luxury tiers capture expanding clinic procurement budgets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands the steepest premium-tier penetration for facial epilators, while the United States drives the largest absolute volume through subscription-enabled direct-to-consumer channels. South Korea's semiconductor-optics cluster enables the fastest hardware-software integration cycles among manufacturing origins.
Germany
Pharmacy channel dominance and consumer willingness to pay for engineering-certified devices sustain premium pricing. The EU MDR's biocompatibility documentation requirements filter out unbranded competitors. The Stuttgart-Munich corridor concentrates engineering talent for precision motor and tweezer-disc manufacturing.
United States
Med-spa chains drive professional-grade cordless adoption for flexible treatment room configurations. FDA 510(k) clearance timelines extend commercialization cycles for laser-classified entrants. California's aesthetic device cluster in Orange County anchors professional distribution and training program development.
South Korea
Semiconductor miniaturization enables compact pulsating-coil devices with integrated IPL tracking algorithms. The MFDS maintains alignment with FDA laser classification standards for streamlined export certification. Seoul's Gangnam district concentrates beauty-tech R&D and med-spa pilot programs for next-generation devices.
United Kingdom
Post-Brexit regulatory divergence from EU MDR creates dual certification burdens for market access. The MHRA's transitional arrangements for legacy CE-marked devices expire through 2028. London's West End aesthetic clinic cluster sustains demand for professional-grade rechargeable platforms.
Japan
Household demand concentrates on compact travel-format devices with minimal skin irritation profiles. METI's electrical appliance safety standards exceed baseline IEC requirements for battery thermal management. Osaka's precision manufacturing base supplies high-tolerance tweezer-disc assemblies to German and US brands.
Facial Epilator Market Competitive Landscape
Top-tier vendors anchor the premium-laser and IPL segments, while mid-tier rechargeable specialists and budget travel-format fabricators fill volume tiers. The market structure reflects regulatory certification moats more than manufacturing scale advantages. Three archetypes dominate: German engineering heritage brands, Dutch-Korean electronics conglomerates with semiconductor integration capabilities, and North American direct-to-consumer subscription platforms. Competitive moves concentrate on exclusive pharmacy channel partnerships and app-integrated hardware-software bundling.
Among heritage engineering specialists, Braun exemplifies the pharmacy-channel premium archetype with sustained positioning across European markets. Philips represents the rechargeable cordless platform standard with semiconductor-enabled feature integration. Emjoi occupies the budget-tier travel-format position within North American drugstore distribution. These three anchors illustrate how certification infrastructure and channel relationships separate sustainable positioning from commodity competition.
| Leading Market Players |
|---|
| Spectrum Brands Holdings |
| Tria Beauty |
| Braun |
| Epilady |
| Emjoi |
| Philips |
| Syneron Candela |
| Bellabe |
| P&G |
| Others |
Supply & Pricing Matrix
Lithium-ion battery cell costs cascade through facial epilator pricing tiers, with cylindrical 18650 and pouch cell sourcing from South Korean and Chinese suppliers determining margin floors for cordless rechargeable platforms before pharmacy channel markups apply.
Pricing Analysis
Capacity additions in South Korea's battery manufacturing corridor are reshaping price floors for cordless rechargeable units, compressing mid-range tier spreads against premium laser-classified devices. Three-tier pricing structure across premium, standard, and economy levels separates FDA 510(k)-cleared diode lasers from CE MDR Class IIa rotary systems and unbranded spring-coil disposables. Price differentiation hinges on certification grade and after-sales service bundling, with professional training programs commanding 40-60 point markups over household equivalents. Pricing pressure stems from nickel release compliance costs under accumulating ECHA guidance, forcing mid-tier manufacturers toward plastic tweezer-disc alternatives. Budget-tier buyers in North American drugstore channels exhibit highest price sensitivity; German pharmacy consumers demonstrate lowest sensitivity due to consultation requirements and engineering heritage premiums.
Supply Chain Analysis
Freight cost volatility from Asia-Europe container routes is elevating landed costs for precision motor assemblies and optical components, compressing margins on entry-laser devices assembled in China for European export. Manufacturing concentrates in China for plastic housings and circuit boards, Germany for precision tweezer-disc machining, and South Korea for semiconductor-enabled IPL sensors. Raw material dependencies span rare-earth magnets for motor torque, optical-grade sapphire for laser windows, and medical-grade polymers for biocompatible housings. Single-source vulnerability concentrates in German-engineered precision motors, where Stuttgart-Munich corridor capacity constraints threaten supply continuity for professional-grade platforms. Distribution runs through pharmacy and drugstore channels in Europe, direct-to-consumer subscription platforms in the United States, and duty-free retail for travel-format disposables.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The facial epilator market functions as a stable compounder, with recurring blade replacement subscriptions and app-integrated hardware converting one-time purchases into annuity-like revenue streams that smooth cyclical exposure.
For Market Incumbents: Hedge against unbranded competitors exploiting EU MDR documentation gaps by accelerating biocompatibility testing investments and locking exclusive pharmacy channel partnerships in Germany. Defensive consolidation moves should prioritize backward integration into precision motor manufacturing to reduce Stuttgart-Munich corridor dependency, while channel control investments in professional training programs reinforce switching costs against emerging diode-laser entrants from South Korea.
For New Entrants and Emerging Players: Begin with travel-format disposable devices targeting airline amenity and duty-free retail channels, where regulatory barriers are lowest and procurement cycles are shortest. The most penetrable white space sits in compact pulsating-coil devices for South Korean household demand, enabled by Seoul's semiconductor miniaturization ecosystem. A direct-to-consumer subscription go-to-market angle—pairing hardware with recurring blade or cartridge revenue—bypasses entrenched pharmacy channel gatekeepers in European markets.
For Investors and Strategic Acquirers: Consolidation pressure builds where regulatory certification moats widen against capital-constrained competitors unable to sustain FDA 510(k) or CE MDR compliance expenditures. Over a 5-10 year viability window, acquisition targets should profile as mid-tier rechargeable specialists with established European regulatory infrastructure but limited brand equity, offering bolt-on scale to incumbent platforms. The signal to watch is state-level laser practitioner licensing expansion in the United States, which would trigger professional-grade device upgrade cycles and certified training program revenue inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| CE MDR Class IIa Certification Pathway | Accelerates European pharmacy channel access while filtering out unbranded competitors under biocompatibility documentation requirements. |
| Direct-to-Consumer Subscription Launch | Captures recurring blade replacement revenue and reduces dependency on traditional retail channel gatekeepers. |
| IPL Tracking Algorithm Integration | Leverages South Korean semiconductor ecosystem to differentiate premium at-home devices with real-time melanin-sensing feedback loops. |
| Professional Training Program Partnership | Builds switching costs among med-spa chains while creating certified upgrade cycles for state-level laser practitioner licensing expansion. |
| Backward Integration into Precision Motors | Reduces single-source vulnerability from Stuttgart-Munich corridor capacity constraints and secures salon-grade torque supply for cordless platforms. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with regulatory affairs leads at laser device manufacturers, pharmacy channel buyers in Germany and the United States, med-spa operations directors, and biomedical engineers at battery suppliers with secondary validation against FDA 510(k) filings, EU MDR technical documentation databases, ECHA nickel release guidance, and customs trade data for lithium-ion cell imports. Bottom-up shipment modeling and top-down category sizing triangulated volume estimates across the analysis window.
Historical reference periods anchored the projection horizon through comparable-period growth rate analysis, with segmentation modeling across power source configuration, energy delivery technology, end-user environment, and price tier certification grade. CAGRs derived from fitted trend extrapolation adjusted for regulatory inflection points and channel shift dynamics. Industry-specific forecast inputs incorporated lithium-ion battery density improvement curves and evolving state-level laser practitioner licensing frameworks.
Several conditions sit outside the modeled scope, including potential FDA reclassification of at-home IPL devices to Class III medical devices, abrupt ECHA restrictions on housing polymer formulations, and geopolitical disruptions to rare-earth magnet supply chains. Forecasts reflect assumptions about regulatory stability and battery cost trajectories that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Beard Grooming Products Market
Beauty & Personal Care
Magnetic Eyelashes Market
Beauty & Personal Care
Hand Soap in Retail Market
Beauty & Personal Care
Anti-Aging Beauty Device Market
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Switzerland Cosmetics Market
Beauty & Personal Care
Bar Soap Market
Beauty & Personal Care
Nail Buffers Market
Beauty & Personal Care
Global Organic Personal Care Products Market
Beauty & Personal Care
Natural Cosmetics Market
Beauty & Personal Care
Slimming Cream Market
Beauty & Personal Care
Sunless Tanners Market
Beauty & Personal Care
Pre-Shave Care Market
Beauty & Personal Care
Middle East and Africa Beauty and Personal Care Products Market
Beauty & Personal Care
Underarm Antiperspirant and Deodorant Market