
 Organic Beauty and Personal Care Ingredients Market | 2026-2036
Organic Beauty and Personal Care Ingredients Market Size, Share, and Industry Trends Forecast 2026-2036
Organic Beauty and Personal Care Ingredients Market Analytics
Specialized green-chemistry formulation talent is bifurcating the competitive landscape, as multinationals with captive expertise pull away from commodity-dependent peers. BASF SE leverages its integrated biotechnology platforms to secure consistent plant-derived feedstock supplies for emollient production. Croda International Plc anchors its position through specialized lipid chemistry R&D facilities in the United Kingdom and Singapore. Evonik Industries AG competes by extending its fermentation-derived active ingredient portfolio into high-margin skin care applications.
Organic beauty and personal care ingredients comprise functionally active substances derived from certified organic agricultural or biotechnological sources, typically processed without petrochemical solvents and meeting thresholds for residual synthetic content below specified certification limits. These materials serve primarily as performance-active or functional bases in formulated consumer products where label transparency and environmental provenance drive purchasing decisions. Plant-based source materials dominate volume flows, though biotechnological origin segments are expanding fastest as precision fermentation reduces land-use intensity and batch-to-batch variability. Certification stratification creates distinct margin pools, with COSMOS and USDA Organic tiers commanding formulation premiums while uncertified natural claims face tightening regulatory scrutiny and consumer skepticism.
EMA guidelines on cosmetic ingredient safety assessments, REACH registration requirements for novel botanical extracts, and USDA National Organic Program certification standards collectively elevate compliance costs while restricting market access for uncredentialed suppliers. Formulators must now document full supply chain organic integrity from soil to finished good, a burden that favors vertically integrated ingredient houses with captive agricultural partnerships. Stakeholders should monitor emerging biotechnology regulatory pathways in Brussels and Washington, as these frameworks will determine whether fermentation-derived actives qualify for organic-equivalent positioning in premium formulations.
Market Dynamics
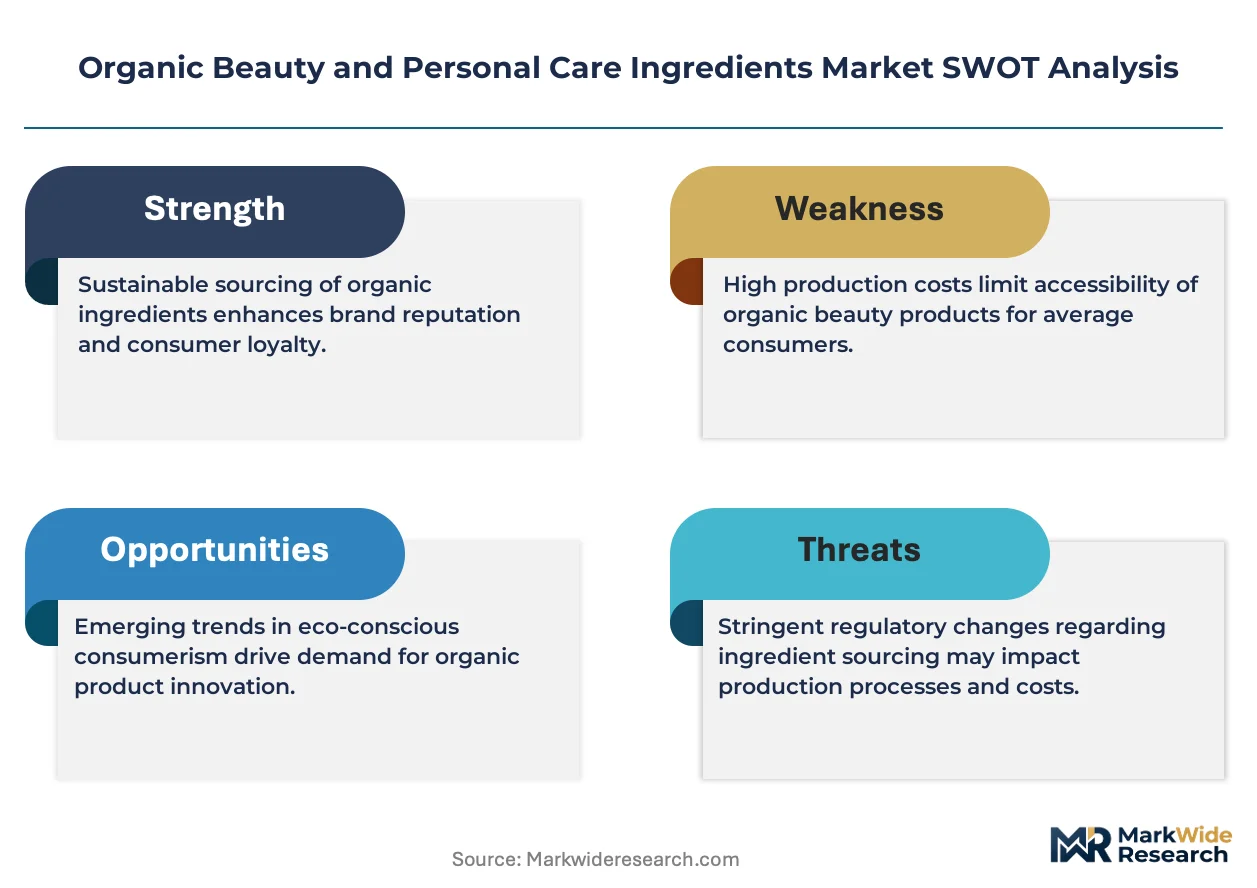
Certification stratification is fragmenting supplier tiers as COSMOS and USDA Organic thresholds force formulators to document full agricultural provenance, elevating vertically integrated houses with captive organic partnerships above commodity traders.
Growth Catalysts
- EU Green Deal implementation:REACH tightening on synthetic petrochemicals redirects formulation budgets toward botanical substitutes, accelerating procurement of certified organic emollients and active extracts.
- Precision fermentation advancement:Biotechnology platforms reduce land-use intensity and batch-to-batch variability in active ingredient production, expanding supply reliability for high-margin skin care applications.
- German mass-market adoption:COSMOS-certified ingredient procurement has become a baseline requirement for personal care lines, creating volume anchors that validate premium pricing tiers.
Market Restraints
- Organic feedstock cost volatility:Climate-sensitive agricultural outputs expose formulators to harvest variability, compressing margins when conventional petrochemical alternatives remain price-stable.
- European supply concentration:Certification infrastructure and auditor capacity cluster in Germany, France, and Italy, creating bottlenecks for Asia-Pacific and Latin American suppliers seeking COSMOS equivalence.
- Biotechnology regulatory ambiguity:EMA and USDA National Organic Program have not established clear pathways for fermentation-derived actives to qualify for organic-equivalent positioning.
Strategic Opportunities
- Southeast Asia penetration:Indonesia and Vietnam present underdeveloped demand for certified organic personal care, with local formulators currently relying on uncertified natural claims vulnerable to tightening ASEAN cosmetic directives.
- Men's grooming vertical:Male-oriented skin care lines remain underindexed for organic certification, offering first-mover positioning before segment standards crystallize.
- Direct-to-brand ingredient supply:Bypassing traditional distributor networks allows integrated houses to capture margin and enforce chain-of-custody documentation demanded by ESG-focused retailers.
Industry Challenges
- Green-chemistry talent scarcity:Formulation expertise in plant-derived lipid chemistry and bioprocess engineering concentrates at a handful of multinationals, constraining mid-tier competitors.
- Certification timeline compression:USDA Organic and COSMOS audit cycles extend 18-24 months, delaying product launches and freezing working capital in pre-certified inventory.
- Legacy system integration:ERP and supply chain traceability platforms at established personal care brands require costly retrofitting to capture field-to-finished-good organic integrity data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organic Beauty and Personal Care Ingredients Market |
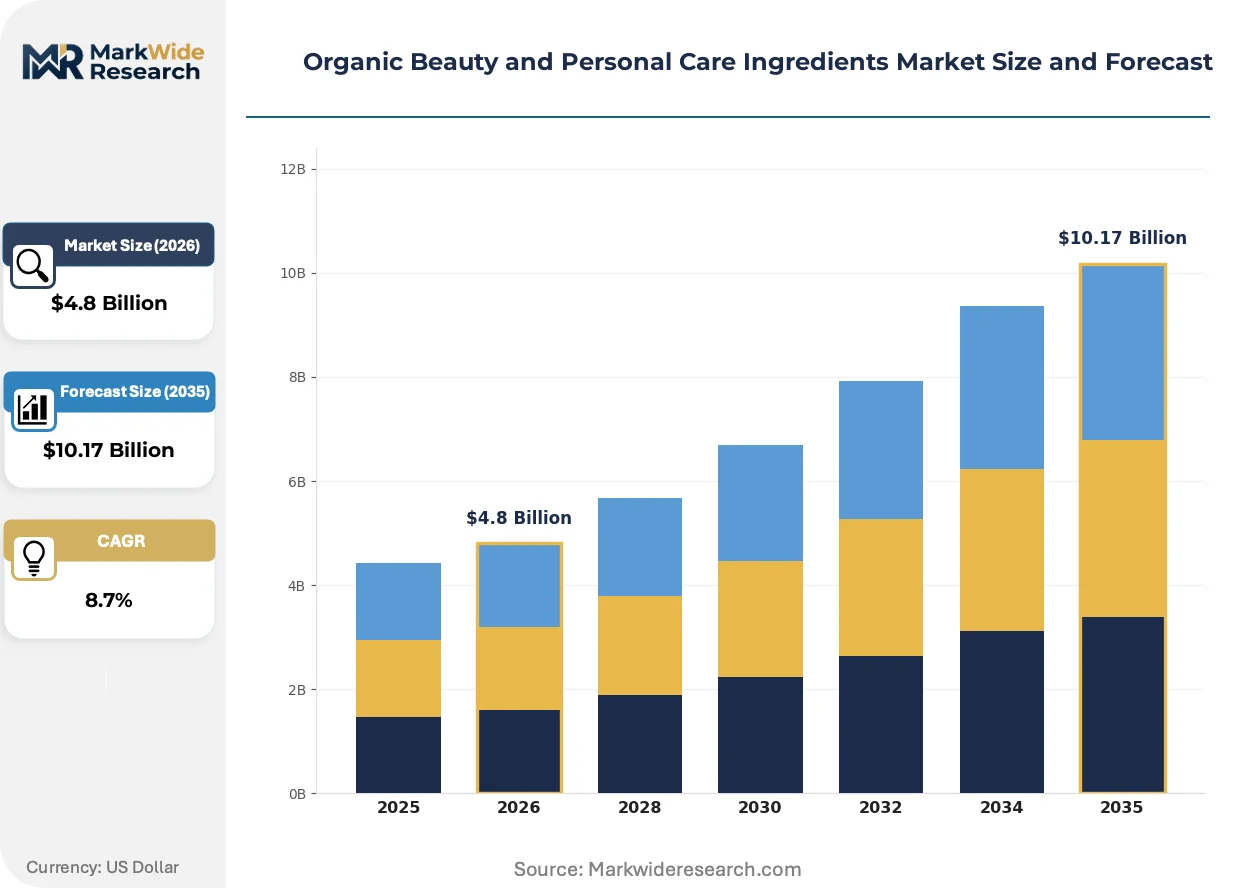
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Emollients, Surfactants, Preservatives, Thickeners Application: Skin Care, Hair Care, Makeup, Fragrances Source: Plant-Based, Animal-Derived, Mineral-Based, Biotechnological Certification: USDA Organic, COSMOS, Ecocert, Others |
| Companies Covered | BASF SE, Croda International Plc, Evonik Industries AG, Clariant AG, Cargill, Incorporated, Ashland Inc., Symrise AG, The Lubrizol Corporation, Givaudan SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organic Beauty and Personal Care Ingredients Market Evolving Landscape
Biotechnology-derived actives and blockchain-enabled supply chain verification are converging to redefine competitive positioning, separating integrated houses with documented provenance from commodity suppliers reliant on paper-based organic claims.
Precision fermentation for squalane and hyaluronic acid is supplanting traditional plant extraction methods in premium skin care formulations. Mid-tier and prestige brands in South Korea and Japan are adopting biotech-derived actives at accelerated procurement cycles. This shift compresses demand for land-intensive agricultural inputs while elevating suppliers with captive fermentation capacity.
REACH registration requirements for novel botanical extracts are tightening documentation burdens on European formulators. The industrial consequence is a withdrawal from experimental plant sourcing toward established, pre-registered ingredient portfolios. Small-batch indie brands face the steepest compliance costs, consolidating procurement toward larger integrated houses.
Clean-label transparency mandates from retailers are shortening supplier qualification cycles and unbundling traditional distributor relationships. Specialty beauty retailers in Germany and France now require direct blockchain-verified provenance documentation. This channel shift is most visible in Paris and Berlin, where Sephora and Douglas have implemented supplier scorecards prioritizing COSMOS certification over price competitiveness.
Organic Beauty and Personal Care Ingredients Market Segmentation
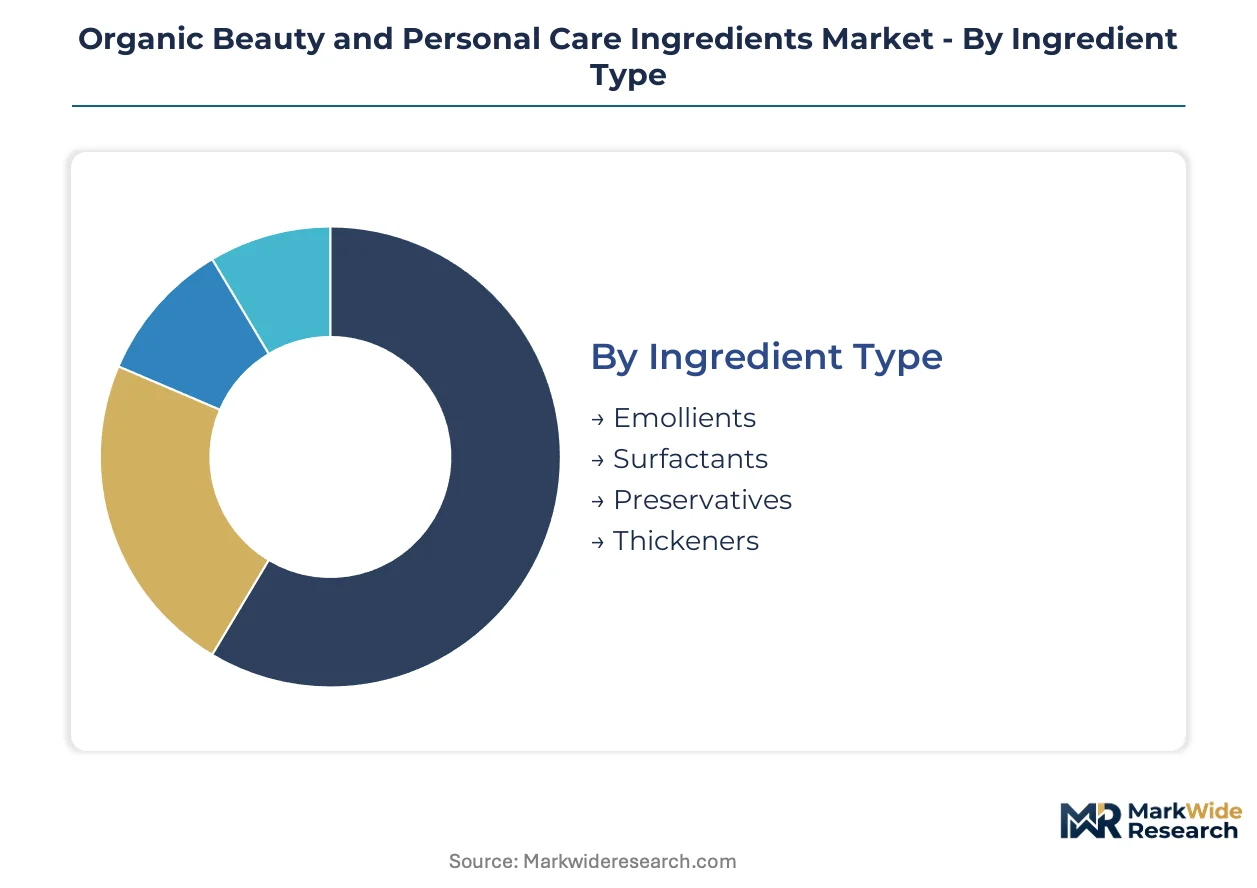
Segmentation in organic beauty ingredients reveals how certification tiers and source technologies fragment procurement strategies. Formulators must balance COSMOS compliance costs against biotechnological consistency when selecting ingredient portfolios.
Ingredient Type:
Surfactants face the most acute substitution pressure as sulfate-free mandates from German retailers force reformulation of legacy cleansing products.
- Emollients:Plant-derived oils and butters processed without petrochemical solvents provide skin conditioning in premium moisturizers. German mass-market lines anchor procurement volumes here as COSMOS-certified shea and jojoba oils become baseline requirements.
- Surfactants:Sugar-based alkyl polyglucosides and amino acid derivatives replace sulfates in cleansers and shampoos. South Korean formulators are accelerating adoption of fermented surfactant alternatives to meet clean-label export standards.
- Preservatives:Organic acids and plant extracts with antimicrobial properties substitute for parabens and formaldehyde releasers.
- Thickeners:Xanthan gum and cellulose derivatives from certified organic fermentation provide rheology control.
Emollients anchor the volume base while surfactants gain share at the steepest rate.
Application:
Cost tier stratification separates prestige skin care from mass-market hair care, with certification premiums widening the gap.
- Skin Care:Serums and facial moisturizers command the highest ingredient premiums due to concentrated active loading and visible efficacy claims. French prestige brands in Paris cluster demand for biotech-derived hyaluronic acid and fermented actives.
- Hair Care:Shampoos and conditioners drive volume but face compressed margins as mass-market lines delay organic certification investments.
- Makeup:Color cosmetics present formulation challenges for organic pigments and binders, limiting certified product availability.
- Fragrances:Essential oil blends and organic alcohol bases serve niche natural perfume segments.
Skin Care captures the margin premium while Hair Care moves the largest tonnage.
Source:
Supply concentration in European agricultural zones creates vulnerability for plant-based segments.
- Plant-Based:Cold-pressed oils and aqueous extracts from certified organic cultivation dominate current supply flows. German and French agricultural partnerships anchor procurement security for major formulators.
- Biotechnological:Precision fermentation produces squalane, ceramides, and peptides with batch-to-batch consistency. Singapore-based bioprocess facilities are expanding capacity to serve Asian skin care manufacturers.
- Animal-Derived:Beeswax and lanolin from certified organic animal husbandry serve niche balm and ointment applications.
- Mineral-Based:Zinc oxide and iron oxides from certified mining operations provide colorant and UV protection functions.
Plant-Based sources dominate current volumes while Biotechnological origin climbs the fastest.
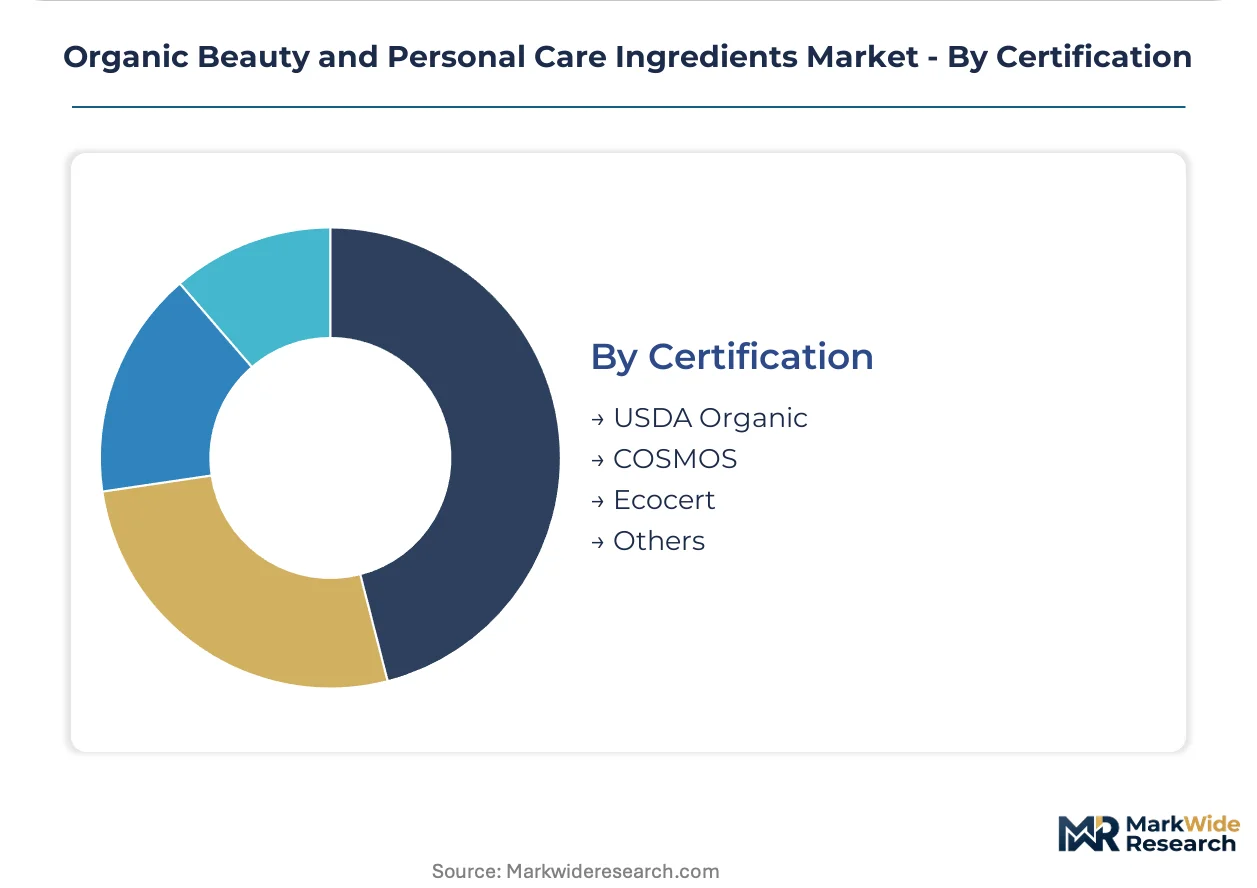
Certification:
Margin pools stratify sharply between audited organic tiers and uncertified natural claims facing regulatory tightening.
- COSMOS:The European standard mandates full supply chain organic integrity from soil to finished good. German retailers now require COSMOS certification as a baseline for shelf placement, concentrating auditor demand in Berlin and Hamburg.
- USDA Organic:The US standard restricts synthetic processing aids and sets residual content thresholds. North American prestige brands leverage USDA certification for export positioning in Asian markets.
- Ecocert:The French-origin standard provides European equivalence with slightly modified processing allowances.
- Others:National organic programs and private standards serve regional markets with varying stringency.
COSMOS anchors European procurement decisions while USDA Organic expands most quickly in Asian export channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
REACH protocols under the EU Green Deal anchor European procurement decisions, redirecting formulation budgets toward certified botanical substitutes across multiple geographies.
Germany
Mass-market personal care lines now mandate COSMOS-certified ingredient procurement as a baseline shelf requirement. The country's national chemical regulator enforces stringent documentation for novel botanical extracts through extended REACH registration timelines. Berlin and Hamburg concentrate auditor capacity, creating bottlenecks for suppliers seeking certification equivalence.
France
Prestige skin care brands in Paris drive concentrated demand for biotech-derived hyaluronic acid and fermented actives. ANSM guidelines on cosmetic ingredient safety assessments elevate compliance burdens for experimental plant sourcing. The Île-de-France region anchors formulation R&D clusters where clean-label transparency mandates from specialty retailers reshape supplier qualification.
United States
USDA National Organic Program certification standards restrict synthetic processing aids for North American prestige brands targeting Asian export channels. FDA oversight of cosmetic ingredient safety intersects with state-level clean beauty legislation in California. The Northeast corridor houses integrated ingredient houses with captive agricultural partnerships securing supply chain integrity.
South Korea
Mid-tier and prestige brands accelerate procurement cycles for biotech-derived actives in serums and facial moisturizers. MFDS cosmetic safety regulations tighten documentation requirements for imported organic claims. Seoul-based formulators leverage precision fermentation platforms to reduce land-use intensity in active ingredient production.
Singapore
Bioprocess facilities expand fermentation capacity to serve Asian skin care manufacturers seeking batch-to-batch consistency. The country's national pharmaceutical regulator monitors emerging biotechnology pathways for organic-equivalent positioning. Jurong Island clusters lipid chemistry R&D operations supporting regional emollient supply security.
Organic Beauty and Personal Care Ingredients Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with captive biotechnology platforms and agricultural partnerships separating the upper stratum from commodity-dependent competitors. Three archetypes dominate: multinational chemical conglomerates with fermentation-derived active portfolios, specialized lipid chemistry houses with regional R&D footprints, and agricultural processors leveraging backward integration into certified organic cultivation. Competitive moves concentrate on strategic partnerships with ESG-focused retailers and direct-to-brand supply contracts that bypass traditional distribution.
Among German-based chemical conglomerates, BASF SE and Evonik Industries AG exemplify the integrated leader archetype through captive biotechnology platforms. Croda International Plc represents the specialized lipid chemistry tier with documented regional R&D positioning. These three anchors illustrate how formulation expertise in plant-derived chemistry and bioprocess engineering concentrates competitive advantage.
| Leading Market Players |
|---|
| BASF SE |
| Croda International Plc |
| Evonik Industries AG |
| Clariant AG |
| Cargill, Incorporated |
| Ashland Inc. |
| Symrise AG |
| The Lubrizol Corporation |
| Givaudan SA |
| Others |
Value Network & Pricing Analysis
COSMOS certification requirements in Germany gate both supplier qualification and price differentiation simultaneously, compressing uncertified competitors into commodity tiers while elevating integrated houses with documented organic provenance to premium positioning. Formulators face stark cost stratification between certified botanical inputs and conventional petrochemical alternatives, with audit timelines and agricultural volatility feeding directly into procurement economics.
Pricing Analysis
German mass-market lines pay 15-40% premiums for COSMOS-certified emollients compared to uncertified natural alternatives, with price differentiation driven by certification grade and volume scale. Three-tier pricing structure across COSMOS-certified, USDA Organic, and uncertified natural tiers separates prestige skin care from mass-market hair care. Pricing pressure stems from climate-driven harvest variability in organic feedstocks, compressing margins when petrochemical substitutes remain cost-stable. Indie brands exhibit highest price sensitivity, while prestige French houses absorb premiums for biotech-derived actives with minimal volume negotiation.
Supply Chain Analysis
Germany, France, and Italy anchor European certification infrastructure and auditor capacity, with COSMOS equivalence bottlenecks forcing Asia-Pacific suppliers into extended qualification timelines. Raw material dependencies center on shea butter from West African organic cooperatives, jojoba oil from Argentinian cultivation, and fermentation feedstocks for biotech-derived squalane. Single-source vulnerability concentrates in German auditor capacity for COSMOS certification, where 18-24 month timelines freeze working capital. Distribution runs through direct-to-brand contracts bypassing traditional distributors, as Sephora and Douglas mandate blockchain-verified provenance documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise in plant-derived lipid chemistry and precision fermentation concentrates competitive advantage at a handful of integrated multinationals, leaving mid-tier competitors exposed to talent scarcity and certification backlogs.
For Market Incumbents: Shield margin pools by deepening captive agricultural partnerships in Germany and France, securing COSMOS-certified feedstock priority allocation before audit bottlenecks worsen. Accelerate bioprocess engineering hiring in Singapore and Seoul to capture precision fermentation capacity expansion. Certification investment in blockchain-enabled traceability platforms defends against ESG-focused retailer scorecards that now prioritize provenance documentation over price competitiveness. For New Entrants and Emerging Players: Anchor in Indonesia and Vietnam's underdeveloped certified organic personal care markets, where local formulators rely on uncertified natural claims vulnerable to tightening ASEAN cosmetic directives. Target men's grooming verticals before organic certification standards crystallize, offering first-mover positioning in male-oriented skin care lines. Direct-to-brand ingredient supply contracts bypass entrenched distributor networks and capture margin through chain-of-custody documentation demanded by European retailers. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision fermentation capacity, as batch-to-batch consistency requirements elevate bioprocess facility costs above traditional extraction infrastructure. Long-term viability favors integrated houses with captive biotechnology platforms and documented organic supply chains over commodity traders dependent on spot agricultural procurement. Watch for EMA and USDA National Organic Program clarity on fermentation-derived actives qualifying for organic-equivalent positioning as the critical inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Captive agricultural partnerships in Germany and France secure COSMOS-certified feedstock priority against audit bottlenecks. |
| Precision Fermentation Capacity Expansion | Singapore-based bioprocess facilities reduce land-use intensity and batch variability for Asian skin care manufacturers. |
| Blockchain-Enabled Provenance Verification | Sephora and Douglas supplier scorecards now mandate documented chain-of-custody for shelf placement eligibility. |
| Direct-to-Brand Supply Contracting | Bypassing traditional distributors captures margin and enforces ESG documentation demanded by specialty retailers. |
| Men's Grooming Certification First-Mover | Male-oriented skin care lines remain underindexed for organic standards, offering pre-crystallization positioning. |
Research Methodology
The analysis maps emollient, surfactant, preservative, and thickener ingredient categories, each validated through procurement directors at personal care formulators, certification auditors at COSMOS and USDA-accredited bodies, and biotechnology R&D leads. Primary interviews with brand managers at German mass-market lines, supply chain planners at integrated chemical houses, and regulatory affairs specialists at EMA and FDA intersected with secondary validation through REACH registration databases, customs trade flows for organic feedstocks, and SEC filings from listed ingredient suppliers. Bottom-up volume builds triangulated against top-down market sizing across certification tiers.
Consistency checks against external benchmarks validated projections across the analysis window, with segmentation modeling by ingredient type, application, source technology, and certification standard. Growth trajectories derived from demand elasticity analysis for COSMOS-certified versus uncertified inputs, precision fermentation capacity expansion timelines, and retailer clean-label mandate adoption curves. Industry-specific inputs included organic agricultural yield volatility indices and biotechnology regulatory pathway uncertainty discounts.
Material uncertainties — EMA and USDA biotechnology classification decisions, climate-driven organic feedstock harvest variability, and ASEAN cosmetic directive enforcement timing — sit outside the modeled envelope. Forecasts reflect documented assumptions on certification adoption rates and fermentation cost curves. Recalibration cycles align with material shifts in regulatory clarity, retailer mandate implementation, and precision fermentation capacity commissioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Japan Aromatherapy Products Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
Private Label Cosmetics Market
Beauty & Personal Care
Natural and Organic Personal Care Market
Beauty & Personal Care
Hair and Nail Accessories Market
Beauty & Personal Care
Global Beauty and Personal Care Products Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Global Organic Personal Care and Cosmetic Products Market
Beauty & Personal Care
Elastomer Gel in Personal Care Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Gua Sha Tools Market
Beauty & Personal Care
Japan Beauty and Personal Care Products Market
Beauty & Personal Care
North America Cosmetics Market