
 US Skincare Market | 2026-2036
US Skincare Market Size, Share, and Industry Trends Forecast 2026-2036
US Skincare Market Outlook
The US skincare market is rebalancing between prestige formulations with clinical positioning and mass-market essentials competing on accessibility. L'Oréal leverages its dermatological brand portfolio to anchor the professional channel, while The Estée Lauder Companies sustains premium positioning through heritage equity and specialty retail control. Procter & Gamble competes at scale in daily-use cleansers and moisturizers through pharmacy and grocery distribution.
US skincare encompasses topical preparations formulated with active ingredients, emollients, and stabilizers designed to cleanse, protect, or improve skin condition, manufactured through emulsification, compounding, and sterile filling processes for consumer and clinical applications. Moisturizers and serums concentrate margin pools as consumers prioritize targeted treatment over basic hygiene, while sunscreens gain structural importance under rising dermatologist advocacy and UV awareness campaigns. Online retail extends fastest among distribution channels, though specialty stores retain higher basket values and brand discovery functions.
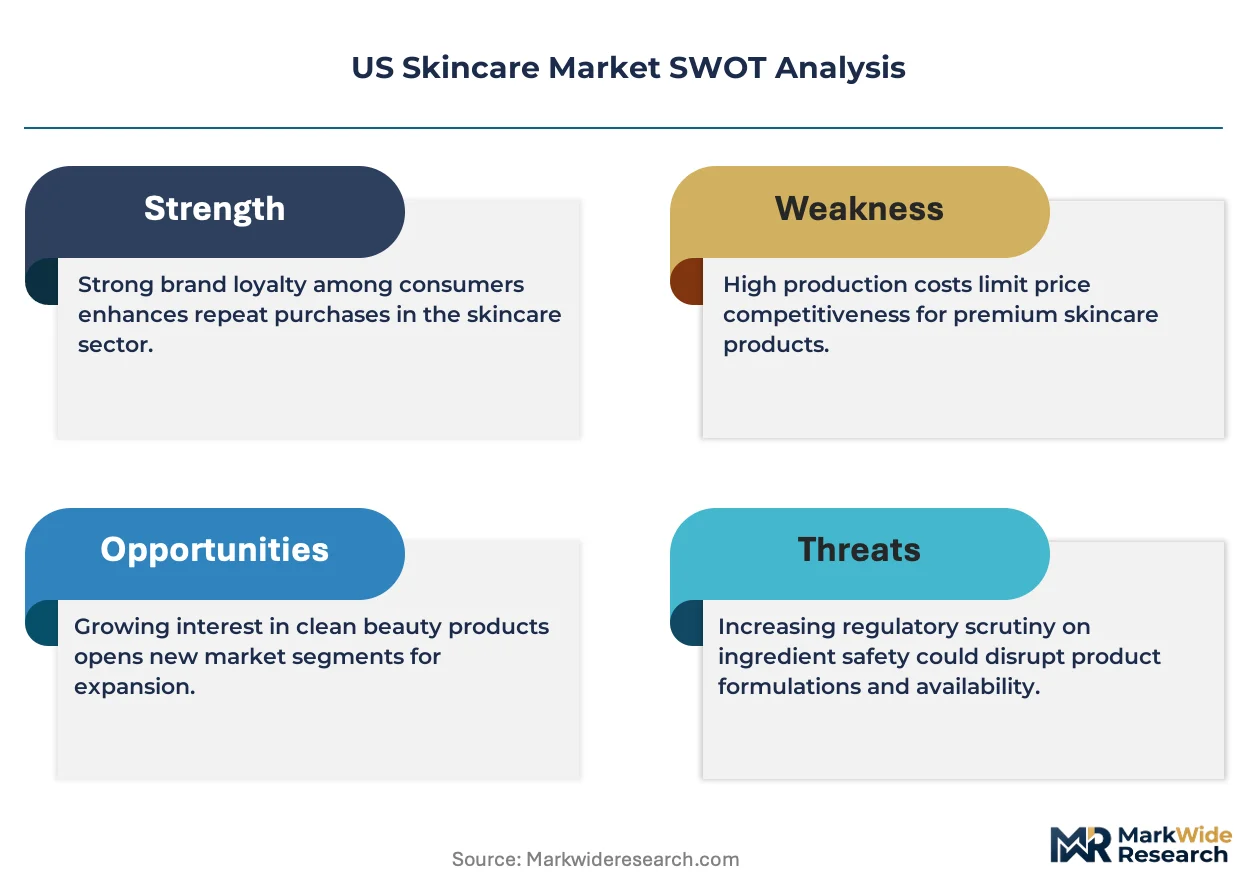
FDA, the Modernization of Cosmetics Regulation Act, and state-level California Safe Cosmetics Program collectively tighten ingredient disclosure, adverse event reporting, and substantiation standards for product claims. These frameworks elevate compliance costs for smaller entrants while advantaging established players with in-house regulatory infrastructure and toxicology capabilities. Stakeholders must monitor enforcement patterns around fragrance allergen labeling and per- and polyfluoroalkyl substance restrictions to anticipate reformulation timelines and supply chain adjustments.
Market Dynamics
Regulatory tightening under the Modernization of Cosmetics Regulation Act is restructuring competitive economics by forcing adverse event reporting, substantiation protocols, and fragrance allergen disclosure that smaller formulators cannot absorb.
Growth Catalysts
- Men's Grooming Normalization:Shifting social norms around male skincare routines are expanding addressable demand beyond traditional female-centric marketing and product development.
- Clean Beauty State Mandates:California's Safe Cosmetics Program drives ingredient transparency requirements that cascade into national formulation standards as brands avoid state-specific SKUs.
- Clinical-Retail Channel Blur:Dermatologist endorsement and medical spa distribution are elevating efficacy claims and justifying premium positioning for active-ingredient products.
Market Restraints
- Per- and Polyfluoroalkyl Substance Bans:Emerging state-level restrictions on PFAS in cosmetics force reformulation of long-wear and waterproof products with limited replacement chemistries.
- Biotechnology Input Concentration:Peptide and biotech-derived active suppliers cluster in Switzerland and South Korea, creating single-source vulnerability for premium anti-aging lines.
- Toxicology Testing Bottlenecks:FDA's new substantiation requirements exceed domestic laboratory capacity, extending product launch timelines for mid-tier brands without in-house capabilities.
Strategic Opportunities
- Texas and Florida Expansion:Underpenetrated Sun Belt markets with younger demographic profiles and lower clean beauty saturation offer whitespace for mass-premium positioning.
- Microbiome-Friendly Formulations:Prebiotic and postbiotic ingredient science creates differentiation in the sensitive skin segment where barrier repair claims command price premiums.
- Direct-to-Consumer Subscription Models:Replenishment-based ecommerce reduces customer acquisition costs and builds predictable revenue streams outside retail margin structures.
Industry Challenges
- Cosmetic Chemist Talent Scarcity:Formulation expertise bridging naturals chemistry and clinical efficacy claims commands premium compensation that strains emerging brand burn rates.
- Packaging Sustainability Compliance:California's extended producer responsibility laws and plastic reduction mandates require capital-intensive material transitions with uncertain consumer willingness to absorb costs.
- Clinical Trial Design Complexity:Substantiating cosmetic claims without crossing into drug classification demands sophisticated FDA regulatory navigation that delays marketing timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Skincare Market |
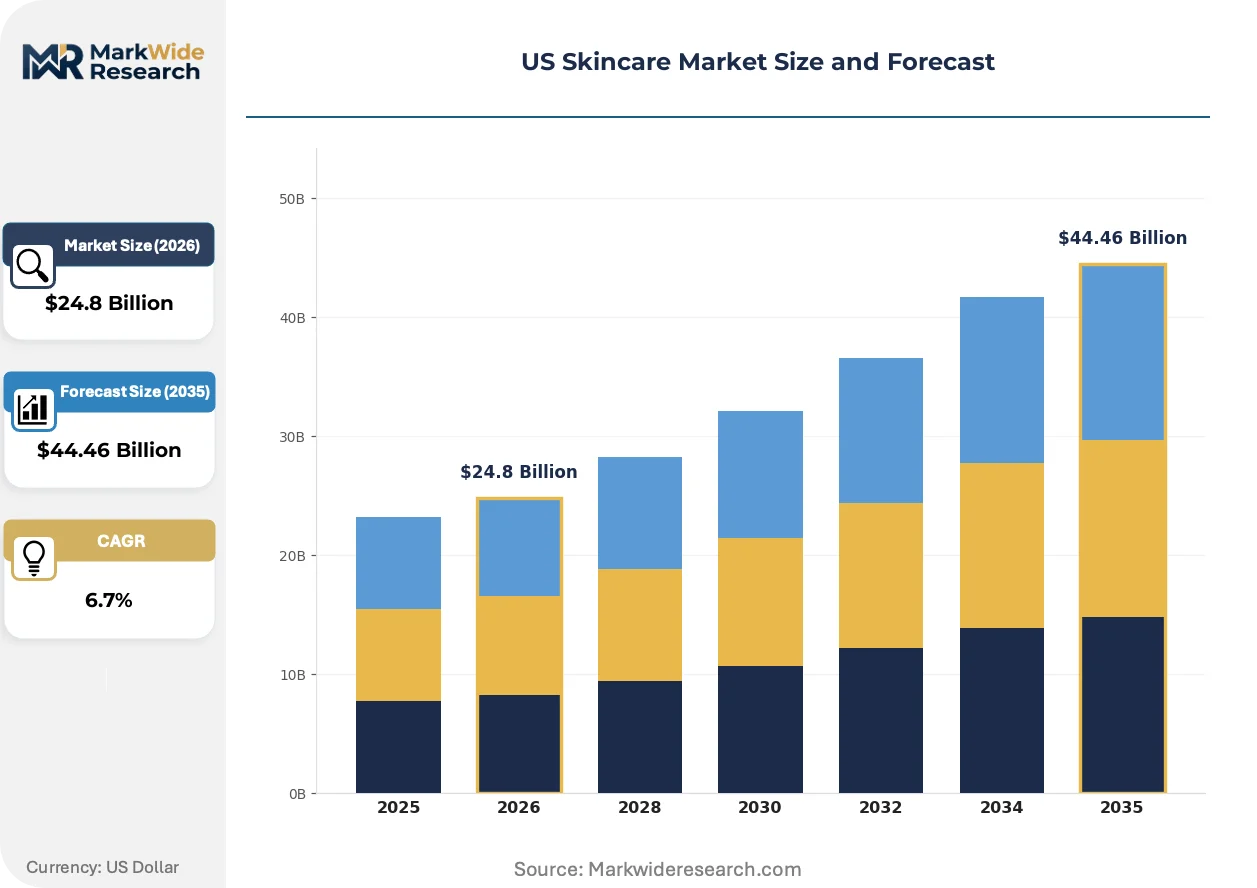
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $44.46 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Cleansers, Sunscreens, Serums End User: Women, Men, Teens, Seniors Distribution Channel: Online Retail, Specialty Stores, Pharmacies, Department Stores Ingredient Type: Natural, Organic, Synthetic, Herbal |
| Companies Covered | L'Oréal, Procter & Gamble, Unilever, The Estée Lauder Companies, Shiseido, Beiersdorf, Johnson & Johnson, Kenvue, Galderma, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Skincare Market Strategic Shifts
Biotechnology-derived ingredients and algorithmic personalization are compressing the gap between mass-market accessibility and clinical-grade efficacy claims.
Peptide engineering is consolidating around signal peptides, carrier peptides, and neurotransmitter-inhibiting peptides that target collagen synthesis and wrinkle formation with measurable biomarker outcomes. Prestige and masstige brands alike are incorporating these bioactives as consumers demand proof-of-efficacy beyond traditional moisturizer benefits. The technology is consolidating formulation development around biotech suppliers with patented peptide libraries, squeezing independent compounders.
FDA's Modernization of Cosmetics Regulation Act mandates adverse event reporting, serious adverse event documentation within 15 days, and facility registration with Good Manufacturing Practice compliance. This regulatory architecture elevates compliance infrastructure as a competitive moat favoring established players with dedicated regulatory affairs departments. Small and mid-sized brands face existential documentation burdens or reliance on contract manufacturers with certified quality systems.
Algorithmic skin analysis through smartphone imaging and questionnaire-based diagnostic tools is displacing in-person dermatologist consultations for initial product selection. Sephora and Ulta Beauty deploy these technologies in-store and via app, capturing preference data that feeds private label development and brand partnership negotiations. California and New York metro consumers show highest adoption of diagnostic-driven purchasing, though accuracy limitations persist for melanin-rich skin tones.
US Skincare Market Segmentation
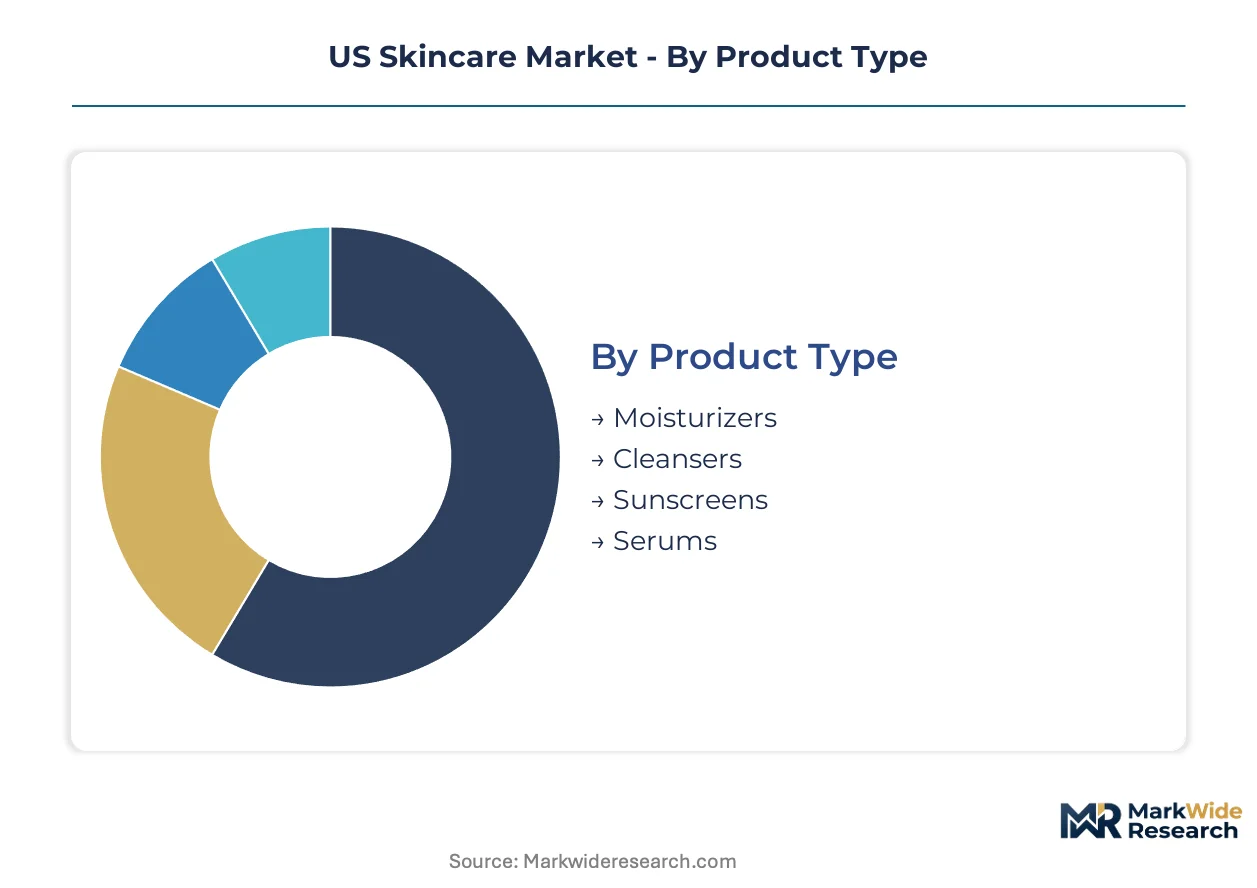
Segmentation in the US skincare market reveals how formulation technology, channel strategy, and demographic targeting create distinct margin architectures. Each axis carries different regulatory burdens and customer acquisition economics that shape competitive positioning.
Product Type:
Formulation chemistry and active ingredient concentration define the technical differentiation axis across topical preparations.
- Moisturizers:Emulsion-based formulations combining humectants, occlusives, and emollients dominate daily-use frequency. California clean beauty brands concentrate innovation here as consumers prioritize barrier repair claims over basic hydration.
- Cleansers:Surfactant systems range from sulfate-based foaming agents to non-ionic micellar technologies. Demand concentrates in pharmacy and grocery channels where Procter & Gamble competes on accessibility and household penetration.
- Sunscreens:Mineral and chemical UV filter systems face reformulation pressure under FDA's pending monograph updates and state-level PFAS restrictions.
- Serums:High-concentration active delivery vehicles featuring peptides, antioxidants, and acids command premium positioning through dermatologist endorsement.
Moisturizers lead on scale; serums lead on momentum.
End User:
Demographic targeting determines marketing spend allocation and product development priorities across the addressable population.
- Women:Historically dominant segment with established purchasing patterns across prestige and mass channels. Marketing investment concentrates on anti-aging and preventive care positioning.
- Men:Social normalization of grooming routines expands addressable demand beyond traditional female-centric development. This segment climbs the fastest as dedicated men's skincare lines proliferate through direct-to-consumer and specialty retail.
- Teens:Acne-focused formulations with salicylic acid and benzoyl peroxide drive purchase frequency through pharmacy and online channels.
- Seniors:Mature skin concerns around elasticity loss and age spot correction create demand for clinical-grade actives and medical spa distribution.
Women anchor current revenue; men represent the steepest expansion trajectory.
Distribution Channel:
Channel selection governs margin capture, brand discovery mechanics, and customer data ownership.
- Online Retail:Direct-to-consumer platforms and marketplace presence enable subscription replenishment models. Sephora and Ulta Beauty deploy algorithmic skin analysis tools that capture preference data for private label development.
- Specialty Stores:Sephora, Ulta Beauty, and independent beauty retailers retain higher basket values and discovery functions through in-person consultation and sampling programs.
- Pharmacies:CVS, Walgreens, and Rite Aid concentrate mass-market daily-use products where convenience and price accessibility drive selection.
- Department Stores:Macy's and Nordstrom sustain prestige brand positioning through heritage equity and gift-with-purchase programming.
Specialty stores lead on basket value; online retail gains share fastest.
Ingredient Type:
Raw material sourcing and substantiation protocols create compliance differentiation under tightening FDA and California disclosure requirements.
- Natural:Plant-derived actives and minimally processed botanicals face batch-to-batch variability challenges that complicate stability testing and shelf-life claims.
- Organic:USDA certification and state-level organic program compliance add documentation burdens that smaller formulators struggle to absorb.
- Synthetic:Laboratory-engineered molecules including peptides and biotech-derived actives deliver reproducible efficacy profiles that support clinical substantiation.
- Herbal:Traditional botanical preparations from Ayurvedic and Traditional Chinese Medicine systems attract niche positioning in Los Angeles and San Francisco wellness markets.
Synthetic ingredients lead on formulation stability; natural ingredients gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cosmetic chemists and formulation scientists cluster in California and New York, anchoring US skincare innovation capacity in coastal metro areas where clean beauty startups and established R&D centers compete for specialized talent.
California
Los Angeles and San Francisco host the densest concentration of direct-to-consumer brands and clean beauty formulators. The California Safe Cosmetics Program mandates ingredient disclosure thresholds that cascade into national formulation standards. Santa Monica and Venice incubate microbiome-friendly startups while South San Francisco biotech parks supply peptide engineering capabilities.
New York Metro
Prestige brand headquarters and specialty retail buying offices concentrate in Manhattan, driving trend translation from runway to mass market. New York State's environmental regulations on packaging waste complement municipal sustainability procurement rules. Brooklyn and Queens manufacturing districts handle small-batch production for emerging labels seeking Made-in-USA positioning.
Texas
Houston and Dallas represent underpenetrated expansion territory with younger demographics and lower clean beauty saturation. State-level business incentives attract distribution center investment from national brands. Austin's tech workforce sustains algorithmic personalization startups targeting the Sun Belt consumer base.
Florida
Miami and Tampa Bay demographics skew toward anti-aging and sun protection demand given UV exposure patterns. The state's lack of income tax attracts remote skincare entrepreneurs from coastal hubs. Orlando's medical tourism infrastructure supports medical spa distribution channels for clinical-grade product lines.
Illinois
Chicago anchors Midwest distribution logistics with rail and air cargo connectivity serving pharmacy and grocery retail networks. The Illinois Environmental Protection Act governs manufacturing discharge standards for local production facilities. Suburban Schaumburg and Naperville host contract manufacturers serving mid-tier brands without coastal R&D infrastructure.
US Skincare Market Competitive Environment
Top-tier vendors anchor prestige positioning through heritage equity and dermatological endorsement, while mid-tier formulators compete on clean beauty differentiation and direct-to-consumer agility. The market structure concentrates around conglomerates with multi-brand portfolios spanning mass to clinical price points. Strategic archetypes include biotech-integrated formulators, clean beauty pure-plays, and pharmacy-channel scale operators. Competitive moves center on regulatory compliance infrastructure investment and algorithmic personalization technology licensing.
Within the dermatological-portfolio tier, L'Oréal and Galderma occupy positions bridging clinical credibility with retail accessibility. Among heritage prestige houses, The Estée Lauder Companies exemplifies specialty retail control and gift-with-purchase programming dominance. These entities represent contrasting approaches to FDA's Modernization of Cosmetics Regulation Act compliance—built regulatory affairs departments versus outsourced toxicology partnerships.
| Leading Market Players |
|---|
| L'Oréal |
| Procter & Gamble |
| Unilever |
| The Estée Lauder Companies |
| Shiseido |
| Beiersdorf |
| Johnson & Johnson |
| Kenvue |
| Galderma |
| Others |
Value Chain & Pricing Dynamics
Prestige-mass bifurcation in US skincare creates divergent margin architectures where clinical-grade peptide formulations command ingredient-premium pricing while mass-market surfactant systems compete on per-unit cost compression. This tier divergence manifests in supply chain configurations: prestige brands anchor formulation partnerships with Swiss and South Korean biotech suppliers, whereas mass operators source commodity emollients through contract manufacturers in New Jersey and Illinois.
Pricing Analysis
Bundled dermatologist-consultation services separate premium serum pricing from unbundled mass-market cleanser transactions. Three-tier pricing structure across prestige, masstige, and mass levels reflects certification grade differentiation under FDA's Modernization of Cosmetics Regulation Act. Pricing pressure stems from California's extended producer responsibility laws forcing packaging cost absorption. Teens and young men exhibit highest price sensitivity; seniors seeking medical spa distribution show least.
Supply Chain Analysis
Dual-sourcing requirements for peptide actives mandate multi-supplier qualification across Switzerland, South Korea, and domestic biotech parks. Raw material dependencies center on hyaluronic acid fermentation feedstocks, mineral UV filters, and sustainable surfactant alternatives. Single-source vulnerability concentrates in patented signal peptide libraries. Distribution runs through Sephora and Ulta Beauty for prestige discovery, pharmacy chains for mass replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in US skincare rests on biotechnology input cost curves flattening as domestic peptide engineering capacity scales, alongside premium-tier shift toward subscription-based replenishment models that capture lifetime value.
For Market Incumbents: Extend regulatory affairs infrastructure as a competitive moat against FDA's adverse event reporting mandates. Deepen backward integration into California biotech corridors to secure peptide supply. Channel control through medical spa partnerships defends positioning against direct-to-consumer challengers. For New Entrants and Emerging Players: Direct-to-consumer algorithmic personalization offers the lowest customer acquisition cost route into underpenetrated Texas and Florida Sun Belt markets. Target male grooming segments where brand loyalty remains unformed. White-space exists in microbiome-friendly formulations for sensitive skin. For Investors and Strategic Acquirers: Consolidation pressure builds where mid-tier brands lack FDA compliance infrastructure to absorb Modernization of Cosmetics Regulation Act documentation burdens. Long-term viability favors targets with captive toxicology capabilities and California manufacturing presence. Watch enforcement patterns around PFAS restrictions as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Compliance Infrastructure Buildout | FDA facility registration and GMP certification create defensible positioning against smaller competitors. |
| Direct-to-Consumer Subscription Launch | Replenishment models bypass retail margin structures and capture recurring revenue in men's grooming. |
| Biotech Peptide Partnership | Patented signal peptide access differentiates clinical claims and supports premium pricing tiers. |
| Sun Belt Geographic Expansion | Texas and Florida distribution centers access younger demographics with lower clean beauty saturation. |
| Sustainability Repositioning | California extended producer responsibility compliance preempts national packaging regulation cascades. |
Study Parameters
Multiple input streams — executive interviews with cosmetic chemists and regulatory affairs directors, retail audit data from Nielsen and Circana, FDA facility registration databases — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged formulation scientists at California clean beauty startups, procurement leads at pharmacy chains, and medical spa distribution managers. Secondary validation drew from SEC 10-K filings, customs import records for peptide actives, and state-level Safe Cosmetics Program disclosure data.
Data-stream reconciliation across product type, end-user demographic, distribution channel, and ingredient sourcing origin enabled segment-level modeling. Volume and value outputs reflect analytical framework application across the projection horizon. CAGRs were derived from trend extrapolation and adoption curve analysis. Forecast inputs incorporated FDA enforcement probability assessments and California regulatory cascade timelines.
The model assumes a particular technology adoption path; alternative pathways for algorithmic skin analysis accuracy improvements would alter the outlook. Forecasts reflect assumptions around men's grooming normalization velocity and biotech supplier capacity expansion. Deviation in FDA adverse event reporting enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Global Bath Salts Market
Beauty & Personal Care
Luxury Beauty Devices Market
Beauty & Personal Care
Herbal Haircare Products Market
Beauty & Personal Care
Mass Beauty & Personal Care Products Market
Beauty & Personal Care
Hair Serums Ingredient Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Salon Service Market
Beauty & Personal Care
Bangladesh Shampoo Market
Beauty & Personal Care
North America Cosmetics Market
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Body Glitters Market
Beauty & Personal Care
Hair Removal Wax Warmer Market
Beauty & Personal Care
Hair Removal Products Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Luxury Cosmetics Market