
 Europe Halal Cosmetics Market | 2026-2036
Europe Halal Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Halal Cosmetics Market Insights
European halal-certified production capacity is broadening as specialized manufacturers respond to certification complexity. Inglot Cosmetics leverages its Polish manufacturing base to serve halal-compliant color cosmetics across Central Europe. PHB Ethical Beauty sustains a vegan-halal dual positioning that anchors its shelf presence in British health retailers. Najel SAS dominates traditional Aleppo soap exports from France, competing on heritage formulation credentials.
Europe halal cosmetics comprise personal care and beauty formulations manufactured without alcohol, porcine derivatives, or non-halal animal substances, verified by accredited Islamic certification bodies and compliant with EU Cosmetic Regulation 1223/2009 on ingredient safety. Skincare leads product type revenue due to repeat-purchase frequency and premium positioning around natural ingredient claims. Online sales represent the fastest-growing application channel as direct-to-consumer halal verification tools reduce buyer uncertainty. Organic ingredient sourcing commands margin concentration among ethically motivated purchasers willing to pay certification premiums.
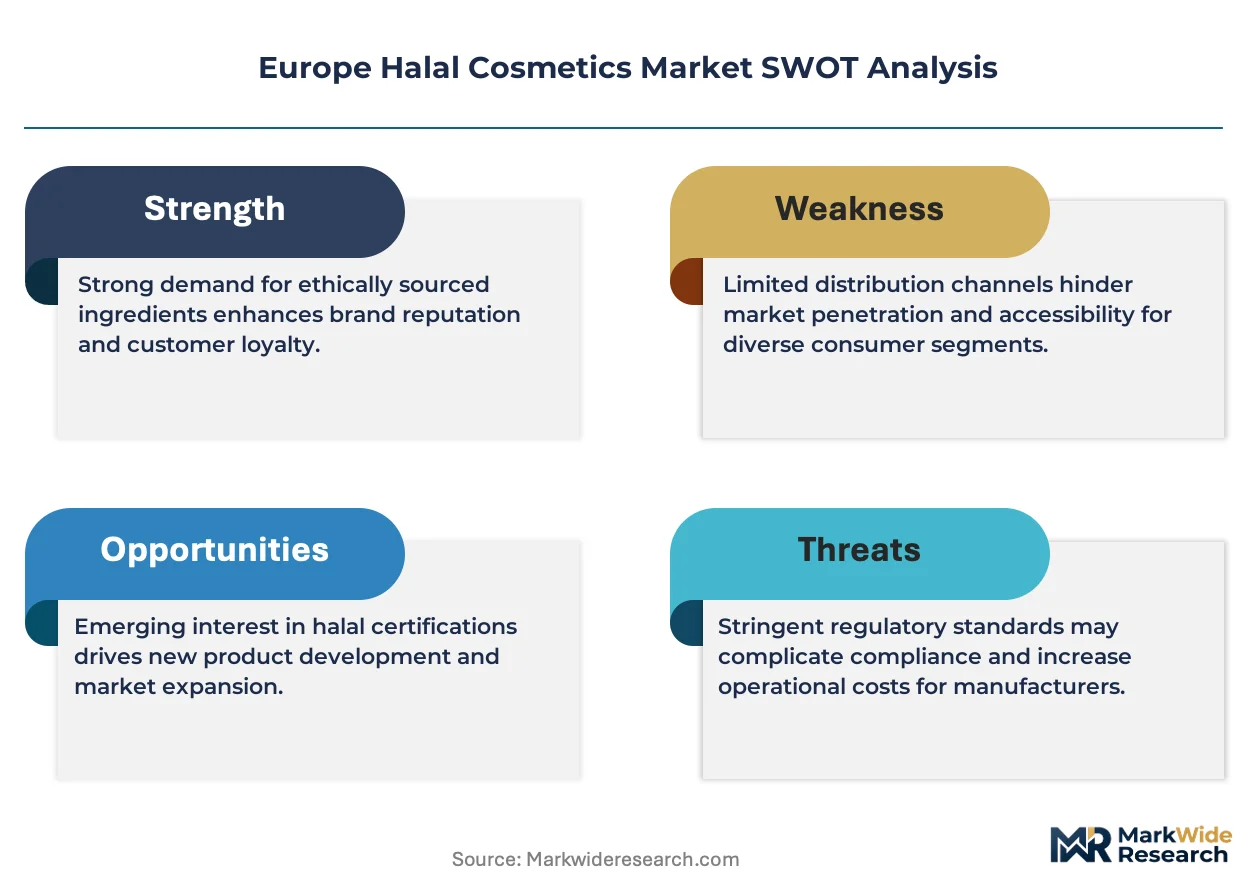
EMA guidelines on cosmetic ingredient safety interact with national halal certification from bodies such as Halal Control in Germany and the Halal Food Council of Europe in Belgium, creating a dual-compliance threshold for market access. REACH chemical registration requirements and the EU Green Deal's sustainable packaging mandates are reshaping formulation and container specifications. Stakeholders must monitor divergence between member-state halal accreditation standards and emerging EU-level cosmetic sustainability rules.
Market Dynamics
REACH chemical registration requirements and the EU Green Deal's sustainable packaging mandates are compressing formulation timelines while elevating certification costs for halal-compliant manufacturers seeking dual compliance with Islamic accreditation bodies and EU Cosmetic Regulation 1223/2009.
Growth Catalysts
- EMA ingredient safety guidelines:Alignment between pharmaceutical-grade cosmetic standards and halal verification protocols reduces duplicate testing burdens for manufacturers serving both medical and consumer channels.
- Ethically conscious non-Muslim consumers:Vegan-halal positioning captures demand from buyers seeking cruelty-free formulations without alcohol or porcine derivatives, expanding addressable population beyond religious observance.
- France:Established halal certification partnerships with major retail chains create distribution infrastructure that lowers market entry barriers for compliant brands.
Market Restraints
- Halal certification cost structure:Annual audit fees and supply chain verification expenses impose disproportionate burdens on small and mid-sized manufacturers relative to revenue scale.
- Ingredient sourcing concentration:Dependence on specialized palm-derived emulsifiers and plant-based alternatives from Southeast Asian suppliers exposes formulators to shipping cost volatility and currency fluctuation.
- REACH registration timelines:Extended chemical safety assessment periods delay new halal-compliant ingredient introductions, compressing product development windows against consumer trend cycles.
Strategic Opportunities
- Germany:Underdeveloped halal color cosmetics penetration relative to skincare creates whitespace for specialized pigment formulators meeting both Halal Control standards and EU colorant restrictions.
- Direct-to-consumer verification tools:Blockchain-based halal certification tracking reduces buyer uncertainty and enables premium pricing capture through transparent supply chain disclosure.
- EU Green Deal packaging mandates:Biodegradable container requirements align with halal ethical positioning, allowing combined sustainability-halal certification marketing to command margin premiums.
Industry Challenges
- Dual compliance expertise scarcity:Formulation chemists possessing simultaneous competency in Islamic jurisprudence-based ingredient screening and EU Cosmetic Regulation toxicology requirements command compensation premiums that strain R&D budgets.
- Certification body fragmentation:Divergent halal accreditation standards across Halal Food Council of Europe, Halal Control, and national bodies create redundant audit cycles and label confusion at retail.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Halal Cosmetics Market |
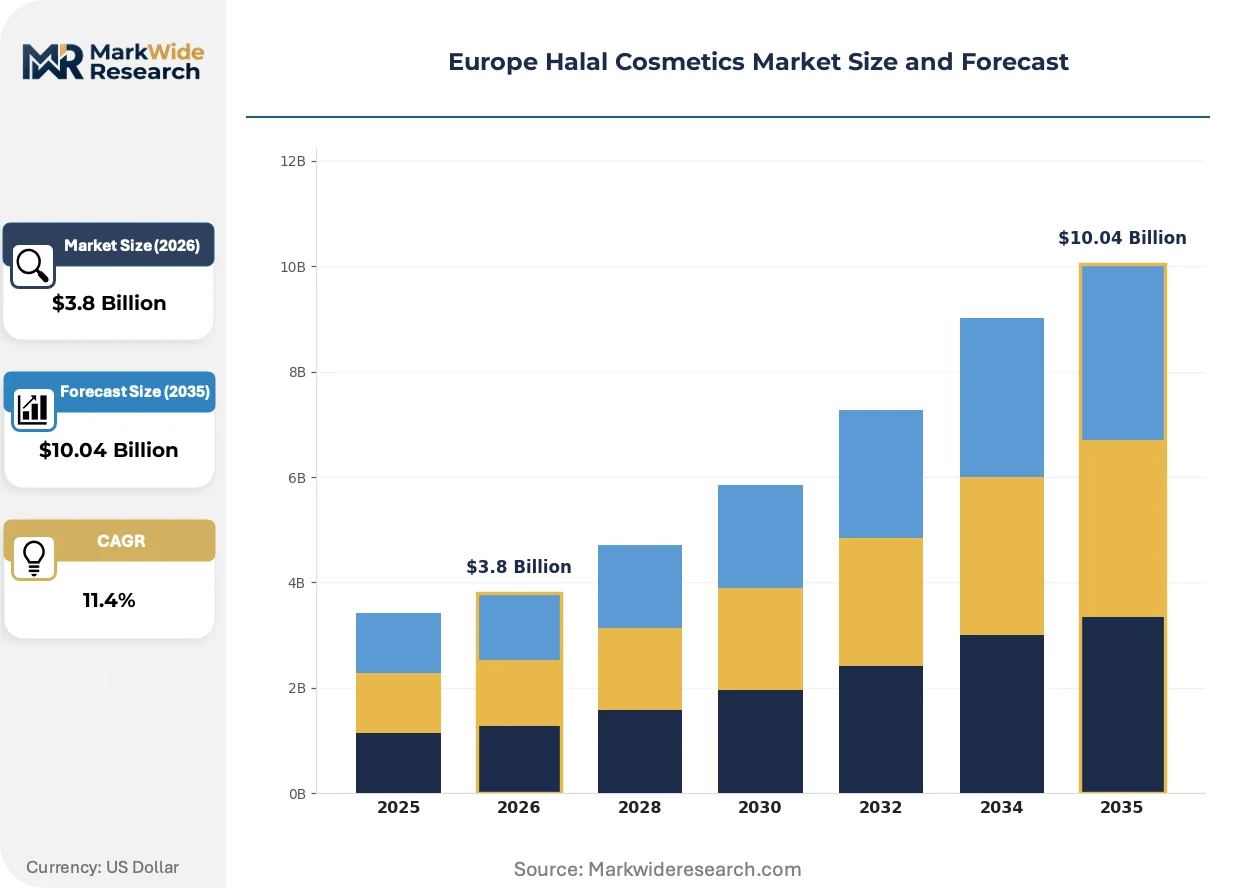
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Fragrance Application: Personal Care, Spa Treatments, Retail Shelf, Online Sales End User: Individuals, Salons, Cosmetic Brands, Distributors Ingredient Source: Natural, Organic, Synthetic, Others |
| Companies Covered | Inglot Cosmetics, PHB Ethical Beauty, Najel SAS, Amara Cosmetics, Clara International, Iba Cosmetics, IVY Beauty Corporation, Paragon Technology and Innovation, Sampure Minerals, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Halal Cosmetics Market Trends and Innovations
Formulation science is advancing through biotechnology-derived alternatives to conventional cosmetic ingredients, while regulatory transparency requirements and shifting channel economics are restructuring how halal verification reaches end consumers.
Plant-based biotechnology is converging with traditional halal formulation requirements. Precision fermentation produces squalane and ceramides without animal-derived precursors, satisfying both vegan positioning and Islamic dietary law compliance. Premium skincare brands in France and the United Kingdom are accelerating adoption of these bio-identical molecules to replace conventional animal-sourced emollients. This convergence is compressing the cost gap between synthetic and bio-derived halal ingredients, enabling mass-market price positioning previously restricted to luxury segments.
CSRD sustainability disclosure rules are mandating granular supply chain reporting for cosmetic manufacturers operating in EU member states. The directive requires documented ingredient provenance and environmental impact metrics that overlap substantively with halal certification audit trails. Mid-sized halal cosmetics producers in Germany and Belgium are leveraging this regulatory overlap to consolidate compliance costs rather than maintaining parallel documentation systems. Skincare and color cosmetics categories face the steepest documentation burdens due to complex multi-ingredient formulations.
Certification-driven purchasing is displacing brand loyalty in online channels. Muslim consumers in the United Kingdom increasingly filter e-commerce searches by accredited halal status rather than manufacturer name, reducing incumbent brand equity value. Direct-to-consumer platforms with integrated halal verification badges are capturing traffic from generalist retailers lacking specialized filtering tools. This behavioral shift concentrates demand in France and Germany where certification database integration with major e-commerce platforms is most advanced.
Europe Halal Cosmetics Market Segmentation
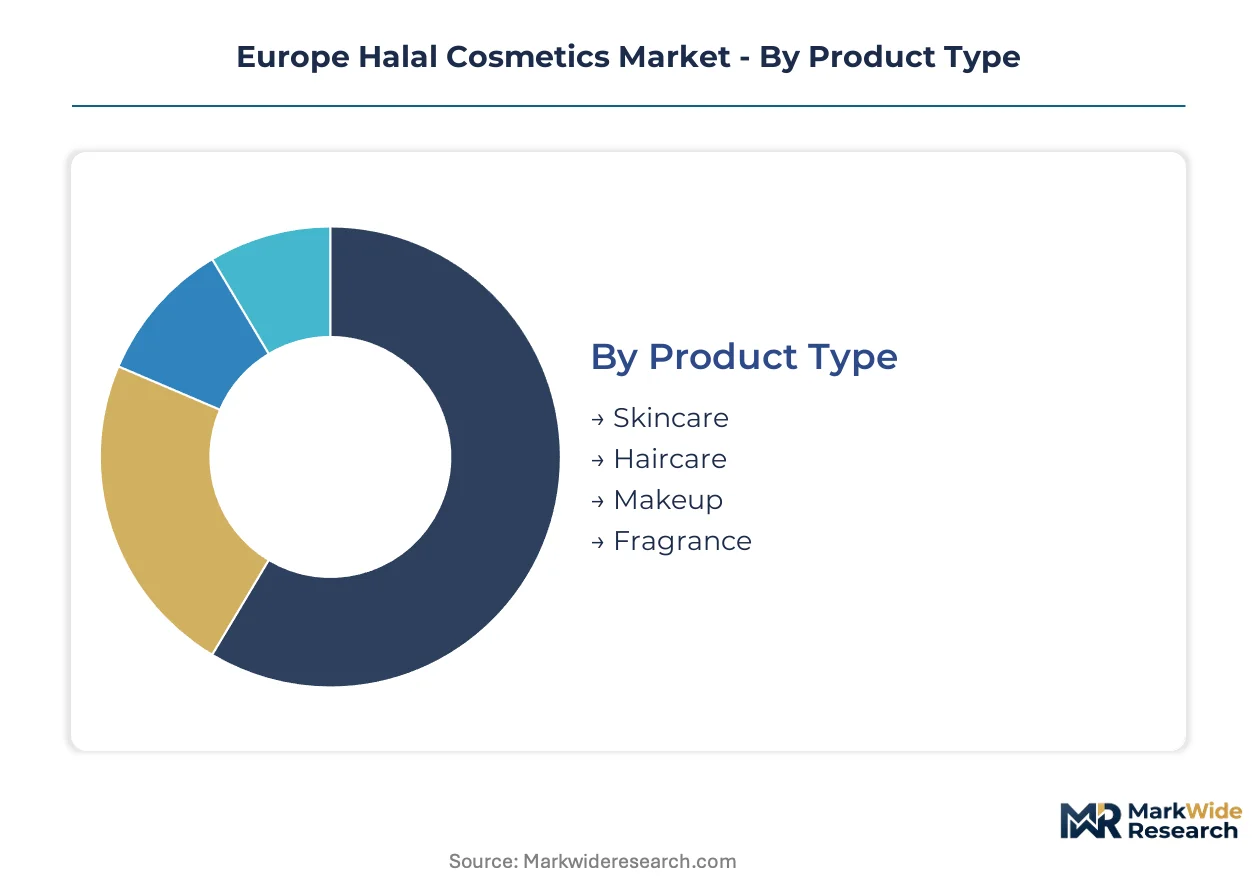
Segmentation in European halal cosmetics reveals divergent compliance burdens and margin structures across product categories. Certification complexity and channel economics create distinct competitive arenas that reward specialized positioning over mass-market breadth.
Product Type:
Buyers differentiate primarily by repurchase frequency and the technical difficulty of maintaining halal integrity through complex supply chains.
- Skincare:Formulations rely on plant-derived emollients and alcohol-free preservation systems verified under EU Cosmetic Regulation 1223/2009. Demand concentrates in France and the United Kingdom where premium natural positioning commands certification premiums from ethically conscious consumers.
- Haircare:Shampoo and conditioner formulations exclude porcine-derived keratin and non-halal animal proteins, substituting with plant-based alternatives. German consumers drive volume through mass-market halal-compliant brands stocked in mainstream retail chains.
- Makeup:Pigment sourcing from halal-verified suppliers limits color palette breadth compared to conventional cosmetics.
- Fragrance:Alcohol-free solvent systems using oil-based carriers satisfy Islamic jurisprudence requirements.
Skincare leads volumes today; makeup is gaining share fastest as color cosmetics certification standards mature.
Application:
Channel selection determines the transparency tools available to verify halal claims and the price premiums achievable.
- Personal Care:Daily-use formulations for home application dominate unit economics through repeat purchase cycles. British health retailers anchor distribution for dual-certified vegan-halal brands targeting non-Muslim ethically motivated buyers.
- Online Sales:Direct-to-consumer platforms integrate blockchain-based certification tracking that reduces buyer uncertainty. French e-commerce operators lead platform development with halal verification badges filtering search results.
- Spa Treatments:Professional service applications require bulk supply agreements with certified manufacturers.
- Retail Shelf:Physical store placement demands compliance with both halal body standards and EU Green Deal packaging mandates.
Retail shelf placement anchors current revenue; online sales are climbing the fastest as verification technology diffuses.
End User:
Procurement scale and technical sophistication determine whether buyers conduct independent supply chain audits or rely on third-party certification.
- Individuals:Direct consumers prioritize certification badge visibility over brand heritage when filtering e-commerce searches. United Kingdom platforms report the highest search-filter utilization rates for accredited halal status.
- Cosmetic Brands:Mid-sized European manufacturers source halal-certified base formulations from specialized toll producers to avoid capital investment in dedicated production lines.
- Salons:Professional service providers require bulk halal certification documentation for client transparency.
- Distributors:Wholesale intermediaries consolidate shipments from multiple halal-certified manufacturers to achieve logistics economies.
Individual consumers drive absolute volumes; cosmetic brands are expanding most quickly as private-label halal lines proliferate.
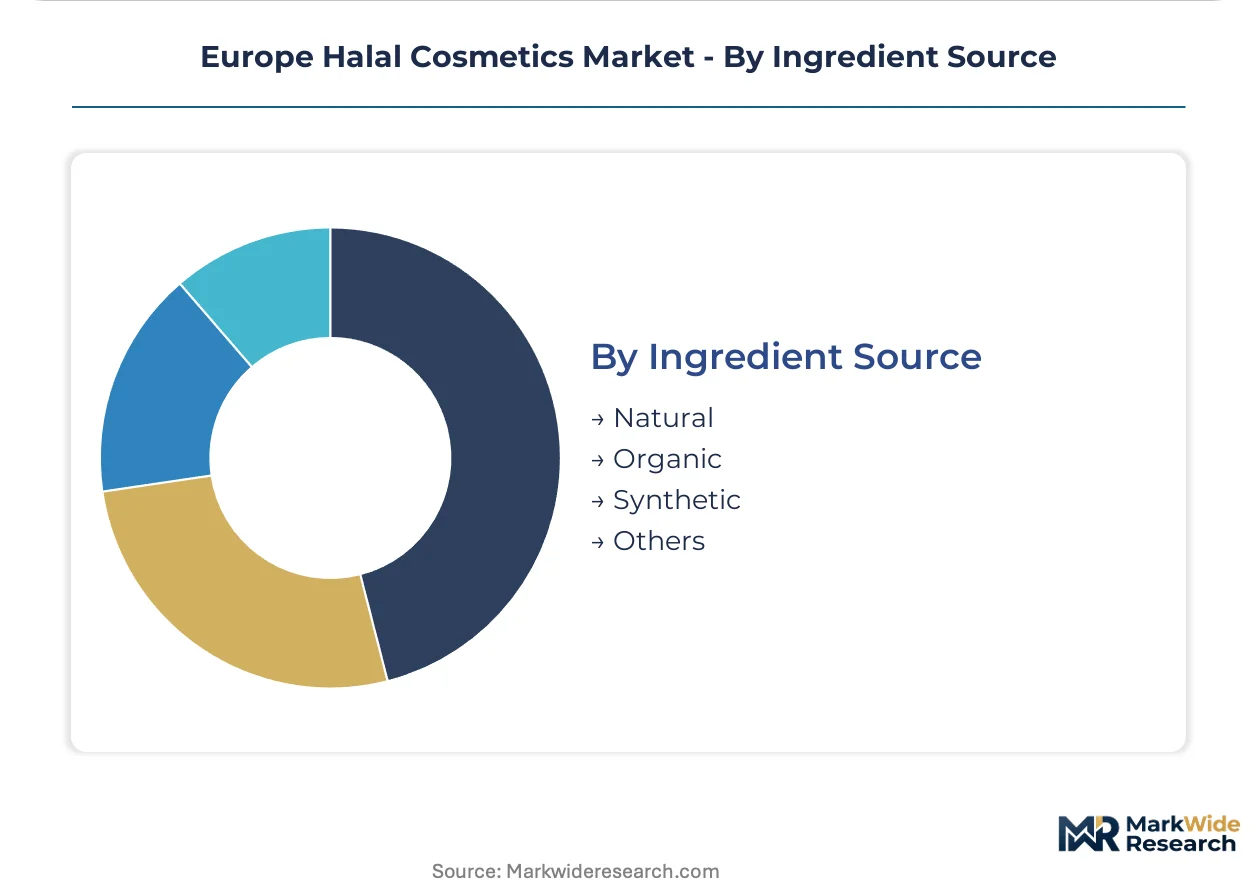
Ingredient Source:
Raw material provenance dictates both certification pathway complexity and the sustainability credentials marketable under CSRD disclosure rules.
- Natural:Plant-derived ingredients from verified halal supply chains avoid animal-derived contamination risks. German and Belgian producers leverage CSRD-mandated supply chain documentation to consolidate compliance costs with halal audit requirements.
- Organic:Certified organic status overlaps partially with halal requirements through prohibition of certain animal-derived inputs. French premium skincare brands command dual-certification price premiums in Paris and Lyon retail clusters.
- Synthetic:Laboratory-derived molecules bypass agricultural supply chain complexity but require REACH registration verification.
- Others:Biotechnology-derived ingredients including precision-fermentation squalane satisfy both vegan and halal positioning.
Natural ingredients lead volumes today; biotechnology-derived alternatives are gaining share fastest as production scales reduce cost premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Halal cosmetics production is migrating toward jurisdictions where REACH compliance costs and halal certification fees create favorable operating economics. Manufacturers are clustering in member states with established Islamic accreditation infrastructure and streamlined chemical registration pathways.
France
Paris and Lyon retail corridors anchor the highest concentration of dual-certified organic-halal skincare brands. ANSM cosmetic safety guidelines intersect with Halal Food Council of Europe standards to create unified compliance frameworks. Marseille serves as the primary import hub for Aleppo soap derivatives distributed across Western Europe.
Germany
Halal Control certification partnerships with mainstream drugstore chains expand distribution access for mid-market haircare formulations. ECHA registration requirements impose stricter documentation burdens than southern European jurisdictions. Düsseldorf and Cologne host specialized toll manufacturers serving private-label halal color cosmetics lines.
United Kingdom
London health retailers sustain demand for vegan-halal dual positioning among ethically motivated non-Muslim consumers. MHRA cosmetic ingredient guidance aligns with Islamic dietary law interpretations on alcohol-free preservation systems. Birmingham manufacturing clusters produce halal-compliant base formulations for export to Commonwealth markets.
Belgium
Brussels-based halal certification bodies coordinate EU-wide accreditation standards that reduce cross-border audit redundancy. CSRD sustainability disclosure mandates overlap with supply chain documentation required for Islamic compliance. Antwerp logistics hubs consolidate shipments from Southeast Asian palm-derived ingredient suppliers.
Poland
Warsaw and Krakow manufacturing zones leverage lower REACH registration cost structures to serve Central European halal color cosmetics demand. Polish producers specialize in pigment formulation meeting both EU colorant restrictions and Halal Control standards. Regional distribution networks extend certified products into Baltic and Nordic markets.
Europe Halal Cosmetics Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue biotechnology-derived ingredient positioning and direct-to-consumer verification platforms. The vendor base stratifies across heritage soap manufacturers, vegan-halal dual-certification specialists, and toll producers serving private-label demand. Three archetypes dominate: heritage formulation exporters, dual-certification niche players, and specialized toll manufacturers. Competitive moves concentrate on strategic partnerships with halal certification bodies and portfolio diversification into alcohol-free fragrance categories.
Within the heritage formulation tier, Najel SAS exemplifies Aleppo soap production anchored in French distribution infrastructure. Among dual-certification specialists, PHB Ethical Beauty occupies a position representing vegan-halal convergence for British health retail channels. At the scale-driven end, Inglot Cosmetics sits within Polish manufacturing clusters serving Central European color cosmetics demand through streamlined REACH compliance pathways.
| Leading Market Players |
|---|
| Inglot Cosmetics |
| PHB Ethical Beauty |
| Najel SAS |
| Amara Cosmetics |
| Clara International |
| Iba Cosmetics |
| IVY Beauty Corporation |
| Paragon Technology and Innovation |
| Sampure Minerals |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap specialists in French Aleppo soap production and Polish color cosmetics manufacturing anchor supply-side discipline through generational capital structures that resist short-term margin compression. Their ownership patterns sustain premium pricing power against private-equity-rolled competitors chasing volume scale.
Pricing Analysis
Retailer markup layers in British health retail and French pharmacy channels absorb certification premiums before reaching end consumers. Three-tier pricing structure across premium, standard, and economy levels stratifies by dual-certification status—organic-halal combinations command the widest spreads. Pricing pressure stems from REACH registration cost pass-throughs pressuring mid-market formulators. Individual consumers through e-commerce filters show highest price sensitivity; spa and salon bulk buyers exhibit lowest.
Supply Chain Analysis
Regional distribution centers in Antwerp and Marseille consolidate hub-and-spoke patterns for Southeast Asian palm-derived emulsifiers and Syrian olive oil feedstocks. Manufacturing concentrates in France, Germany, and Poland. Formulators draw from specialized plant-based alternatives and biotechnology-derived squalane. Single-source vulnerability runs through Aleppo soap precursor supply from conflict-affected regions. Distribution runs through certified toll manufacturers serving private-label demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe halal cosmetics represents a late-cycle quality story as Muslim and ethically conscious non-Muslim consumers shift demand toward premium dual-certified formulations with transparent supply chain documentation.
For Market Incumbents: Cement certification body partnerships with Halal Control and Halal Food Council of Europe to lock in audit efficiency against emerging biotechnology-derived ingredient specialists. Defend shelf position in French pharmacy channels through exclusive organic-halal dual-label SKUs. Prioritize backward integration into precision-fermentation squalane production to capture margin from vegan-halal convergence. For New Entrants and Emerging Players: The gap between premium organic-halal skincare and economy mass-market haircare offers whitespace for mid-priced color cosmetics with blockchain verification badges. Target German drugstore chains where halal color cosmetics penetration lags skincare. Deploy direct-to-consumer platforms with integrated certification tracking as the primary go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among Polish toll manufacturers with streamlined REACH compliance pathways and underutilized pigment formulation capacity. Long-term viability hinges on CSRD-mandated supply chain disclosure convergence with halal audit requirements. Watch biotechnology-derived ingredient cost parity with conventional emollients as the inflection signal for mass-market scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Investment | Organic-halal convergence captures margin premiums in French and British retail clusters. |
| Blockchain Verification Platform | Transparent supply chain tracking reduces buyer uncertainty in German e-commerce channels. |
| Biotechnology Ingredient Adoption | Precision-fermentation squalane satisfies vegan-halal positioning for ethically motivated consumers. |
| REACH Compliance Streamlining | Polish manufacturing bases serve Central European demand with lower registration burdens. |
| Private-Label Toll Manufacturing | Specialized production capacity captures volume from mid-sized brands avoiding capital investment. |
Research Methodology
Bottom-up personal care application modeling reconciled against top-down halal-certified production capacity tracking forms the analytical core. Primary interviews with brand managers at dual-certification specialists, category buyers at British health retailers, halal certification auditors at Halal Control and Halal Food Council of Europe, and formulation chemists at Polish toll manufacturers combined with secondary validation. Secondary sources include ECHA REACH registration databases, CSRD sustainability disclosure filings, customs records for Southeast Asian palm-derived ingredient imports, and ANSM cosmetic safety guidance documents. Triangulation across these sources validates volume and value estimates.
Historical trendline analysis of certification penetration rates and channel shift patterns informs the projection framework. Segmentation dimensions modeled include product type, application channel, end-user archetype, and ingredient source provenance. CAGRs derive from fitted growth curves across these segments. Industry-specific forecast inputs incorporate REACH registration timeline delays and CSRD documentation burden impacts on mid-sized producer economics.
The model assumes a particular technology adoption path; alternative pathways for biotechnology-derived ingredient cost reduction would alter the outlook. Forecasts reflect assumptions around certification body harmonization and EU Green Deal packaging mandate implementation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Post-Shave Care Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
Cosmetics and Personal Care Stores Market
Beauty & Personal Care
Global Organic Hair Color Market
Beauty & Personal Care
Global Hot Air Brushes Market
Beauty & Personal Care
Curling Irons Market
Beauty & Personal Care
US Cosmetics Market
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Soap Market
Beauty & Personal Care
Cosmetics and Personal Care Products Direct Selling Market
Beauty & Personal Care
Cosmetic Oil Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Luxury Personal Care and Cosmetics Market