
 Personalized Beauty Devices Market | 2026-2036
Personalized Beauty Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Personalized Beauty Devices Market Outlook
Subscription-based leasing for high-frequency skincare tools is reconfiguring capital deployment across the competitive landscape. L'Oréal Group leverages its dermatology partnerships to anchor professional-grade distribution in European aesthetic clinics. Foreo AB differentiates through direct-to-consumer channel control and minimalist hardware design. Koninklijke Philips N.V. sustains manufacturing scale across Asian electronics corridors, competing on component sourcing reliability.
Personalized beauty devices combine sensor-integrated hardware with algorithm-driven treatment protocols, typically operating at frequencies between 1-3 MHz for RF modalities or wavelengths of 415-660 nm for LED arrays, with primary purpose being customized cosmetic intervention outside clinical settings. Skincare tools dominate installed base owing to repeat purchase cycles and software upgradeability, while LED therapy represents the fastest-expanding technology segment as clinics adopt multi-wavelength platforms for rosacea and post-inflammatory hyperpigmentation protocols. Hair growth applications remain concentrated in male-pattern baldness protocols within dermatology clinics, though individual consumers increasingly acquire home-use laser caps with companion app diagnostics.
FDA pre-market notification requirements for RF and microcurrent devices shape product development timelines and clinical substantiation budgets for US market entry. EMA medical device regulation and REACH substance restrictions for nickel-containing electrodes constrain European formulation and material choices. Stakeholders must monitor evolving classification boundaries between wellness and medical-grade claims, as regulatory reclassification would trigger new conformity assessment obligations across multiple jurisdictions.
Market Dynamics
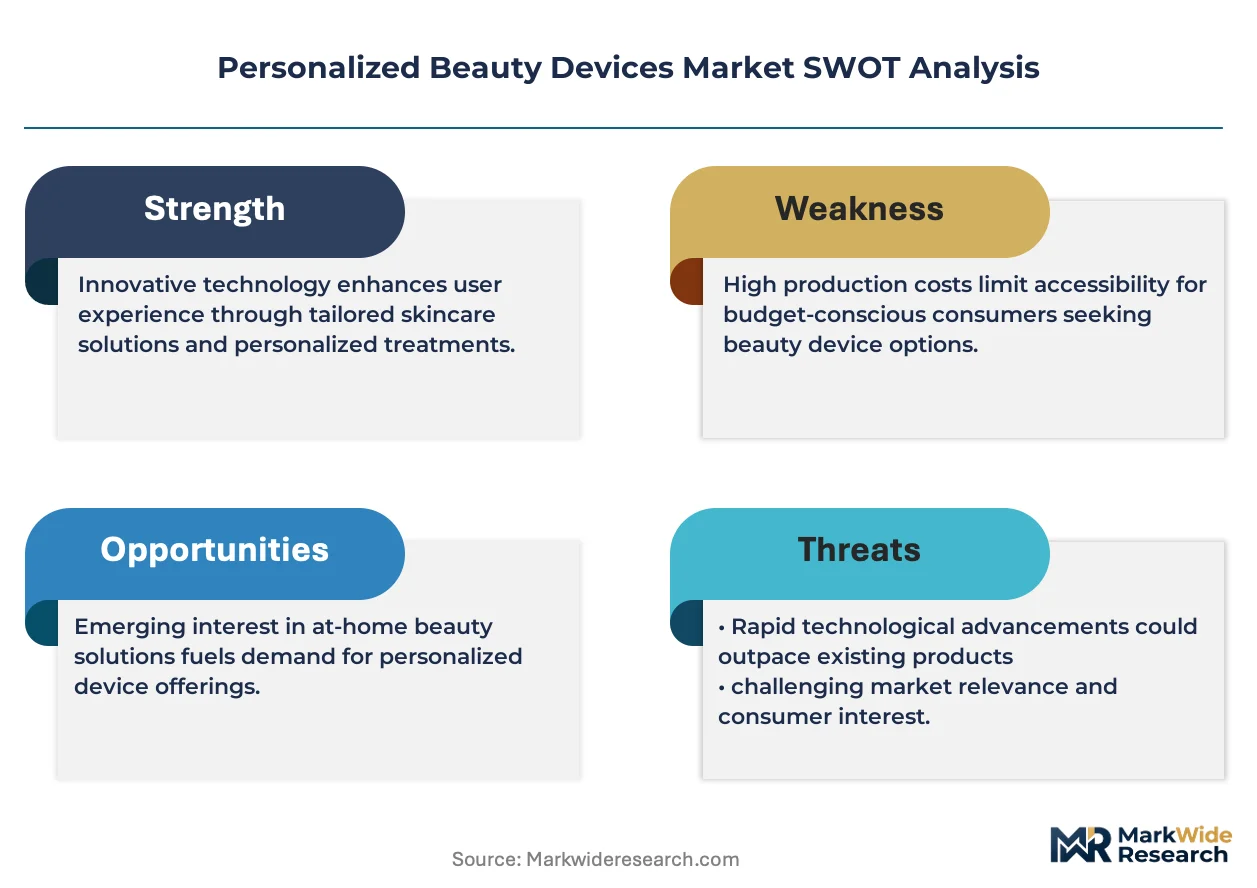
RF and microcurrent platforms face tightening FDA pre-market documentation requirements, compressing development timelines and forcing manufacturers to front-load clinical substantiation budgets before US commercialization.
Growth Catalysts
- EMA Medical Device Regulation:Harmonized conformity assessment across EU member states accelerates multi-country clinic procurement of LED therapy systems by reducing redundant certification cycles.
- WeChat subscription integration:Tier-one Chinese beauty salons bundle skin analysis hardware with recurring service models, locking in predictable hardware refresh revenue streams.
- Multi-wavelength LED arrays:Dermatology clinics in Seoul adopt rosacea and post-inflammatory hyperpigmentation protocols, expanding professional-grade device utilization rates.
Market Restraints
- Nickel electrode sourcing:REACH substance restrictions constrain European formulation choices for microcurrent device contacts, forcing costly material substitutions.
- Clinical validation costs:FDA clearance pathways for at-home RF devices require expanded pre-market documentation, extending payback periods for R&D investment.
- Optical component concentration:LED array manufacturing clusters in specific Asian electronics corridors create single-source vulnerability for wavelength-specific diodes.
Strategic Opportunities
- Home-use laser caps:Male-pattern baldness protocols are migrating from dermatology clinics to individual consumers, opening direct-to-consumer channels with companion app diagnostics.
- Software upgradeability:Skincare tools with sensor-integrated hardware enable recurring revenue through algorithm-driven treatment protocol updates without hardware replacement.
- Classification boundary monitoring:Stakeholders tracking wellness versus medical-grade claim distinctions can preempt regulatory reclassification triggers across multiple jurisdictions.
Industry Challenges
- Algorithm validation talent:Shortage of engineers capable of integrating 1-3 MHz RF modalities with skin-type-specific dosing algorithms delays product pipeline velocity.
- Legacy salon infrastructure:Independent beauty establishments lack technical staff to maintain sensor-calibrated devices, creating service gap vulnerability for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Personalized Beauty Devices Market |
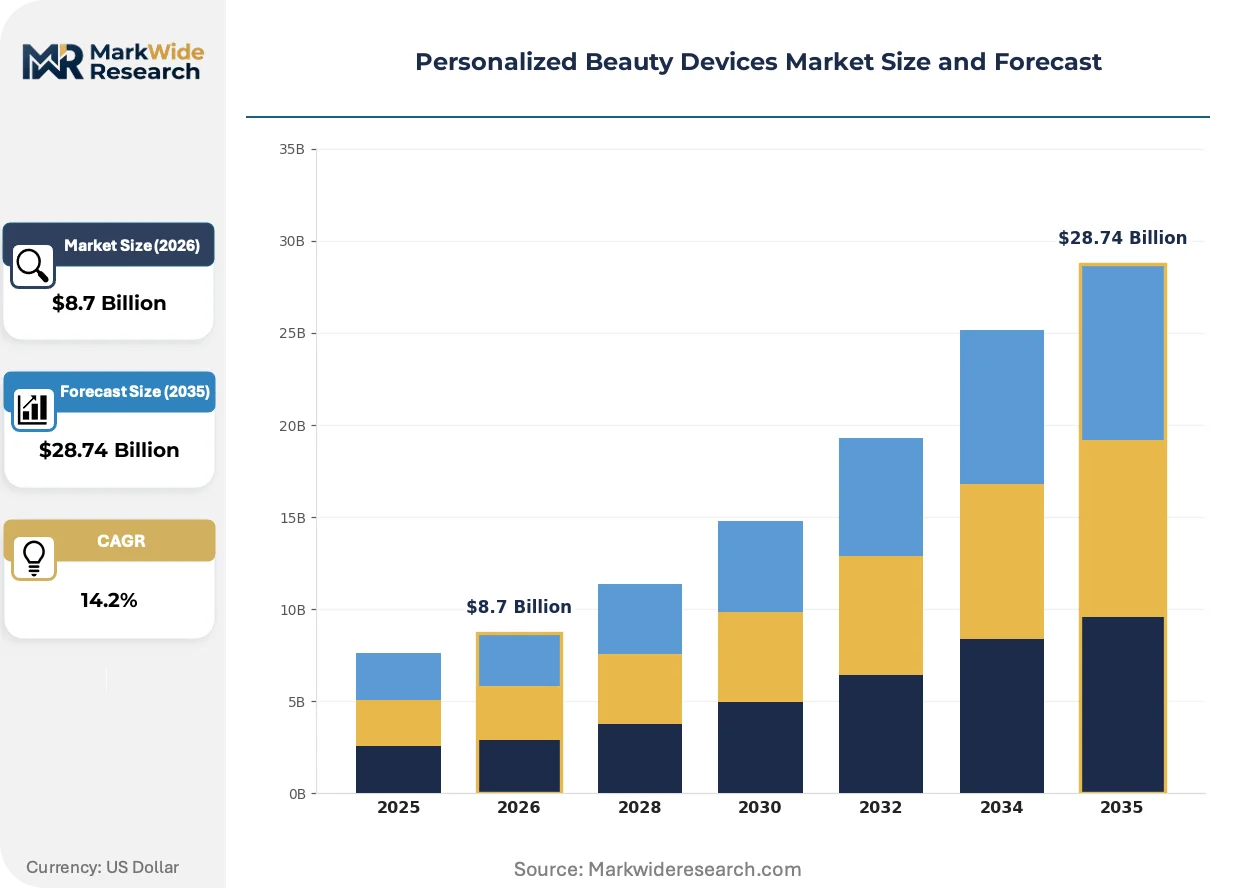
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Skincare Tools, Hair Care Devices, Makeup Tools, Cleansing Gadgets Technology: RF Technology, LED Therapy, Ultrasound, Microcurrent End User: Beauty Salons, Individual Consumers, Dermatology Clinics, Wellness Centers Application: Anti-Aging, Acne Treatment, Skin Tightening, Hair Growth |
| Companies Covered | Foreo AB, Unilever PLC, L'Oréal Group, Estée Lauder Companies Inc., Koninklijke Philips N.V., Procter & Gamble, Amorepacific Corporation, Johnson & Johnson, Shiseido Company, Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Personalized Beauty Devices Market Strategic Shifts
Algorithm-driven personalization protocols are compressing the gap between professional clinic outcomes and at-home device efficacy, reshaping capital allocation across hardware and software development functions.
Sensor-integrated hardware combining real-time skin impedance measurement with dynamic frequency adjustment is rendering obsolete static-output RF devices that rely on user-selected intensity levels. Dermatology clinics in Tokyo are piloting these adaptive systems for customized post-procedure maintenance protocols. The structural consequence is collapsing the premium tier for non-adaptive professional devices as efficacy differentiation narrows.
REACH substance restrictions for nickel-containing electrodes are forcing European manufacturers toward biocompatible alloy substitutions and ceramic contact alternatives. Industrial consequence includes reformulated supply chains and extended material qualification timelines. Microcurrent device producers serving EU aesthetic clinics are responding by dual-sourcing electrode substrates from Swiss and Japanese specialty metal suppliers.
Subscription-based leasing for high-frequency skincare tools is replacing outright equipment purchase in China's tier-one salon networks. Device-as-a-service models bundle hardware, maintenance, and software updates into monthly fees, compressing customer acquisition costs while extending lifetime value capture. This procurement evolution is most visible in Shanghai and Shenzhen where capital-light expansion strategies dominate independent salon formation.
Personalized Beauty Devices Market Segmentation
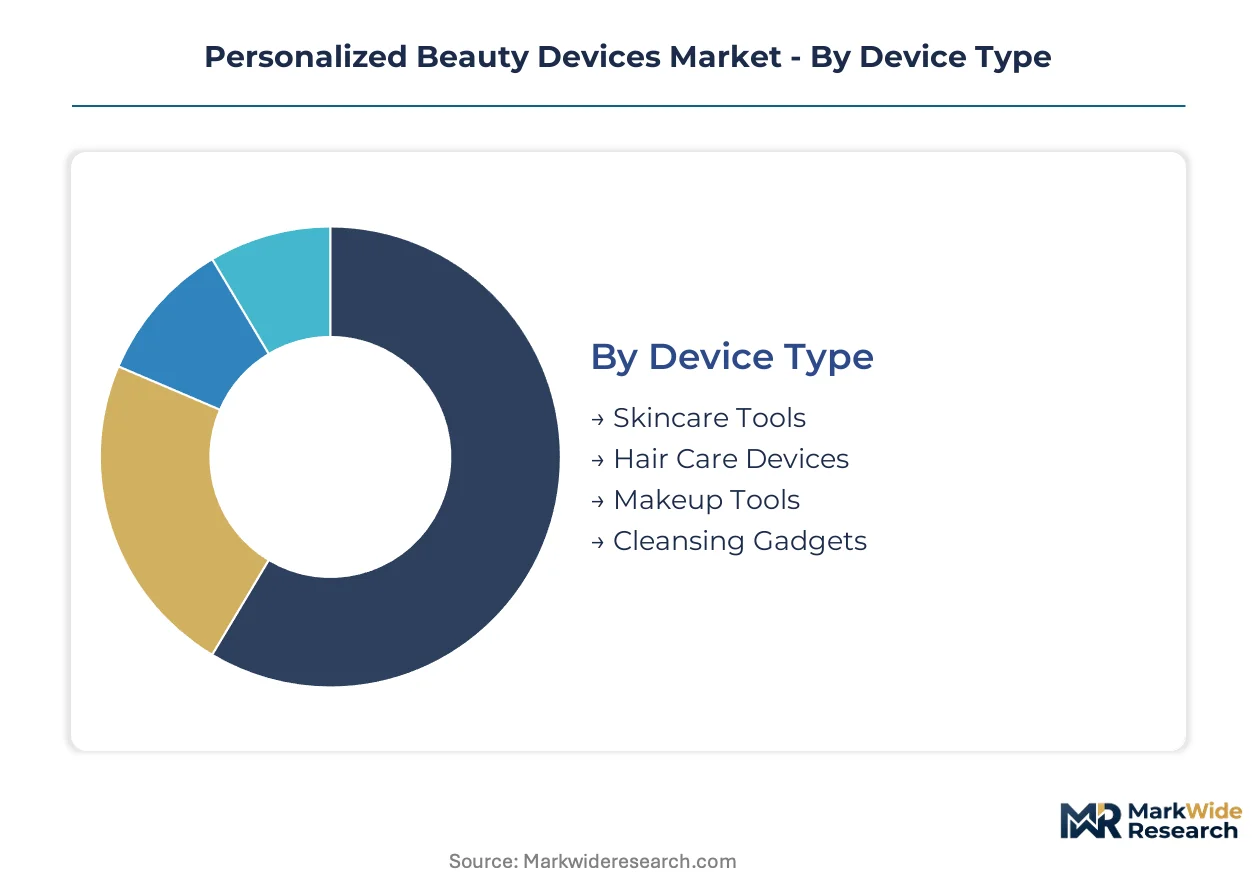
Personalized beauty devices fragment across hardware specifications, treatment modalities, and procurement channels that reshape how manufacturers allocate R&D budgets and distribution resources. Each segmentation axis reveals distinct margin profiles and regulatory exposure that determine competitive viability.
Device Type:
Mature hardware categories with established repeat purchase cycles dominate installed base economics, while emerging form factors test subscription and software-upgrade revenue models.
- Skincare Tools:Sensor-integrated hardware operating at 1-3 MHz RF frequencies enables algorithm-driven protocol customization with companion app diagnostics. Demand concentrates in China's tier-one cities where beauty salons bundle skin analysis hardware with WeChat-based subscription services, locking in predictable refresh revenue.
- Hair Care Devices:Home-use laser caps with wavelength-specific diode arrays are migrating male-pattern baldness protocols from dermatology clinics to individual consumers. Seoul and Tokyo clinics expand procurement of professional-grade platforms while direct-to-consumer channels capture individual purchasers seeking clinic-comparable outcomes.
- Makeup Tools:Color-matching sensors and AI-driven application guidance represent emerging personalization frontiers with limited clinical validation requirements.
- Cleansing Gadgets:Sonic and silicone-based facial cleansing devices hold mature market positions with compressed margin structures and shorter replacement cycles.
Skincare tools retain volume leadership; hair care devices hold the steepest expansion curve.
Technology:
Cost tier stratification separates professional-grade platforms requiring clinical substantiation from consumer-accessible devices with wellness-grade claims.
- RF Technology:Radiofrequency platforms at 1-3 MHz face tightening FDA pre-market documentation requirements that compress development timelines and front-load clinical validation budgets. EMA medical device regulation and REACH substance restrictions for nickel-containing electrodes constrain European formulation choices and force material substitutions.
- LED Therapy:Multi-wavelength arrays operating at 415-660 nm represent the fastest-expanding technology segment as dermatology clinics in Seoul and Tokyo adopt rosacea and post-inflammatory hyperpigmentation protocols. Optical component concentration in specific Asian electronics corridors creates single-source vulnerability for wavelength-specific diodes.
- Ultrasound:High-frequency sound wave platforms for product penetration and cellular stimulation occupy mid-tier pricing with moderate regulatory exposure.
- Microcurrent:Low-level electrical stimulation devices for facial toning face REACH substance restrictions on electrode materials and algorithm validation talent shortages.
LED therapy commands the steepest expansion trajectory; RF technology maintains premium pricing power despite regulatory friction.
End User:
Customer type determines procurement modality, with institutional buyers favoring capital expenditure and individual consumers shifting toward subscription and leasing structures.
- Beauty Salons:China's tier-one salon networks are replacing outright equipment purchase with subscription-based leasing for high-frequency skincare tools, compressing customer acquisition costs while extending lifetime value capture through bundled maintenance and software updates.
- Individual Consumers:Direct-to-consumer channels with companion app diagnostics are capturing male-pattern baldness and anti-aging segments previously concentrated in clinical settings.
- Dermatology Clinics:Seoul and Tokyo facilities expand procurement of LED therapy and microcurrent platforms for professional-grade treatment protocols.
- Wellness Centers:Hybrid service providers integrate beauty devices with broader health optimization offerings, creating cross-selling opportunities with lower regulatory scrutiny.
Beauty salons anchor procurement volume; individual consumers are expanding most quickly as channel control shifts toward direct-to-consumer models.
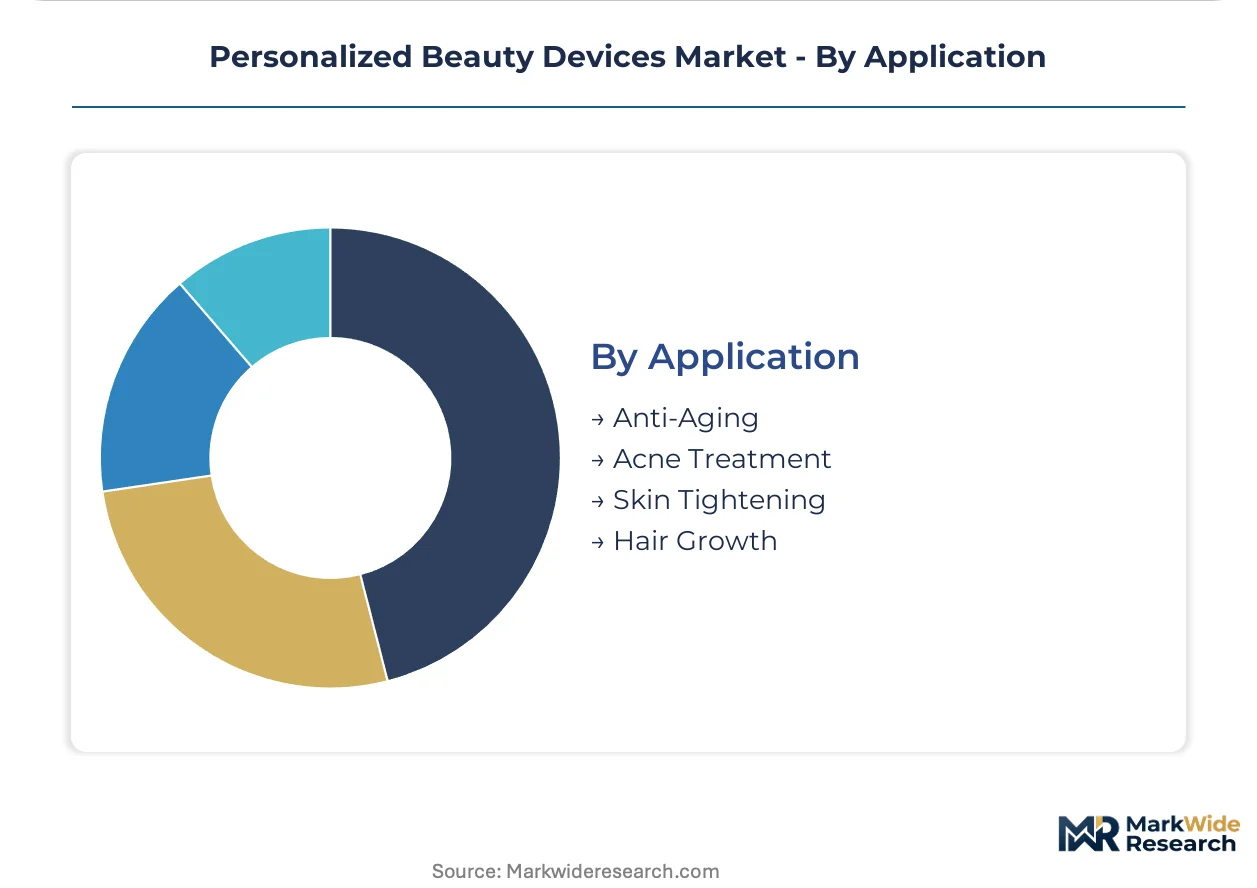
Application:
Application focus determines clinical validation intensity and regulatory classification risk, with therapeutic claims triggering medical-grade conformity obligations.
- Anti-Aging:RF and microcurrent modalities for wrinkle reduction and skin laxity command premium pricing but face evolving classification boundaries between wellness and medical-grade claims across FDA and EMA jurisdictions.
- Acne Treatment:Blue-light LED therapy at 415 nm wavelengths targets bacterial reduction with lower regulatory barriers than hormonal or pharmaceutical interventions.
- Skin Tightening:Collagen induction protocols using RF and ultrasound platforms require temperature monitoring and safety interlocks that differentiate professional from home-use devices.
- Hair Growth:Laser and LED-based follicle stimulation for male-pattern baldness concentrates in dermatology clinics but migrates toward home-use caps with diagnostic app integration.
Anti-aging retains revenue concentration; hair growth is climbing the fastest as home-use devices capture clinic-proven protocols.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Trade flows in personalized beauty devices tilt toward net imports in Western markets while Asian manufacturing clusters supply component assemblies and finished systems. Korea and Japan maintain trade surpluses in professional-grade LED and microcurrent platforms. Chinese producers dominate upstream diode and sensor module exports.
United States
FDA pre-market notification requirements for RF and microcurrent devices compress development timelines and front-load clinical validation budgets. The agency's tightening documentation standards for at-home RF systems force manufacturers to expand safety substantiation files before commercialization. Device distribution concentrates in California and New York metro corridors where dermatology clinics and medi-spa chains anchor professional-grade procurement.
China
Tier-one cities including Shanghai, Beijing, and Shenzhen drive demand through beauty salons bundling skin analysis hardware with WeChat-based subscription services. NMPA medical device classification rules shape product claim boundaries between wellness and therapeutic categories. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta produce wavelength-specific LED diodes and RF module assemblies for domestic and export markets.
South Korea
Seoul dermatology clinics expand procurement of multi-wavelength LED therapy systems for rosacea and post-inflammatory hyperpigmentation protocols. MFDS medical device regulations harmonize with international standards to accelerate export certification. The Seoul Capital Area hosts concentrated R&D activity in adaptive RF platforms combining real-time skin impedance measurement with dynamic frequency adjustment.
Japan
Tokyo aesthetic clinics pilot sensor-integrated hardware for customized post-procedure maintenance protocols. METI industrial standards and PMDA medical device oversight create dual compliance frameworks for products crossing wellness-medical claim boundaries. The Kanto region anchors domestic manufacturing of high-precision optical components for LED arrays and microcurrent electrode assemblies.
Germany
EMA medical device regulation and REACH substance restrictions for nickel-containing electrodes constrain formulation choices for microcurrent device contacts. ECHA compliance requirements force costly material substitutions toward biocompatible alloys and ceramic alternatives. Industrial concentration in Baden-Württemberg and Bavaria supports precision electronics manufacturing for professional-grade platform components.
Personalized Beauty Devices Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying wavelength-calibrated diodes, RF transducers, and sensor modules. Market structure fragments across three tiers: multinational consumer electronics conglomerates with captive distribution, mid-scale device specialists with direct-to-consumer channel control, and contract manufacturers serving private-label salon equipment. Strategic archetypes include software-hardware bundlers capturing recurring revenue through algorithm updates, clinical-grade platform builders targeting dermatology procurement, and subscription-leasing operators capitalizing on China's salon-as-a-service transition. Dominant competitive moves encompass backward integration into optical component sourcing and strategic partnerships with dermatology chains for clinical validation data.
Among the named participants, L'Oréal Group and Koninklijke Philips N.V. occupy positions reflecting contrasting scale advantages: the former leverages dermatology partnerships to anchor professional-grade distribution in European aesthetic clinics, while the latter sustains manufacturing scale across Asian electronics corridors. Foreo AB exemplifies the direct-to-consumer archetype through channel control and minimalist hardware design, sitting within the mid-tier specialist category rather than the conglomerate tier. These three entities represent distinct strategic postures without implying specific market share figures or operational claims.
| Leading Market Players |
|---|
| Foreo AB |
| Unilever PLC |
| L'Oréal Group |
| Estée Lauder Companies Inc. |
| Koninklijke Philips N.V. |
| Procter & Gamble |
| Amorepacific Corporation |
| Johnson & Johnson |
| Shiseido Company, Limited |
| Others |
Value Chain & Pricing Dynamics
The Yangtze River Delta manufacturing corridor anchors wavelength-specific LED diode production, concentrating component sourcing leverage among Chinese suppliers and compressing margin capture for downstream device assemblers in Europe and North America. This geographic concentration enables tier-one Chinese beauty salons to extract favorable subscription-leasing terms while forcing European manufacturers to absorb REACH compliance costs for nickel-free electrode substitutions.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with FDA-cleared professional-grade RF platforms commanding substantial premiums over wellness-grade consumer devices. Price differentiation rests on certification tier and software upgradeability, with subscription-based models in Shanghai and Shenzhen compressing upfront hardware margins. Pricing pressure stems from algorithm validation talent shortages delaying premium product launches. Individual consumers exhibit highest price sensitivity, while dermatology clinics prioritize clinical substantiation over unit cost.
Supply Chain Analysis
Optical-grade gallium arsenide substrates and precision RF transducers feed from concentrated Asian electronics corridors spanning China, South Korea, and Japan, with wavelength-calibrated diodes requiring single-source qualification timelines. Raw material dependencies include rare-earth phosphors for LED arrays, biocompatible electrode alloys, and sensor-grade silicon wafers. Single-source vulnerability for 415-660 nm wavelength-specific diodes creates supply interruption exposure. Distribution runs through direct-to-consumer channels and professional clinic procurement networks, with subscription-leasing operators in China's tier-one cities capturing recurring revenue streams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where hardware-software bundling and WeChat-integrated subscription models are displacing transactional equipment sales, with interoperability between salon management systems and device diagnostics determining ecosystem lock-in.
For Market Incumbents: Build algorithm-update moats through captive dermatology partnerships that generate proprietary clinical validation datasets for FDA submissions. Consolidate position by acquiring sensor module specialists in the Seoul Capital Area to secure impedance-measurement hardware. Defend against direct-to-consumer entrants by tightening professional-channel exclusivity for adaptive RF platforms. For New Entrants and Emerging Players: India's tier-two urban centers offer underpenetrated white space for home-use laser caps with localized app diagnostics. Target wellness centers in Southeast Asia seeking hybrid beauty-health service integration. Pursue private-label manufacturing for European salon equipment distributors lacking in-house R&D capabilities. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among software-hardware bundlers capturing algorithm-driven protocol updates, positioning these archetypes for superior cash flow quality across extended holding periods. Acquisition targets should display clinical validation data assets and FDA submission pipelines. Watch for MFDS harmonization announcements as signals accelerating Korean platform exports.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Validation Partnership | Dermatology chain collaborations generate FDA-submission datasets for adaptive RF platforms. |
| Backward Integration into Optics | Captive diode sourcing mitigates single-source vulnerability for wavelength-specific LED arrays. |
| Subscription Platform Launch | WeChat-integrated leasing models lock in predictable hardware refresh revenue from Shanghai salons. |
| Algorithm Update Infrastructure | Cloud-based protocol delivery enables recurring revenue without hardware replacement cycles. |
| REACH-Compliant Material Transition | Ceramic electrode alternatives secure EU market access under ECHA substance restrictions. |
Study Parameters
Cross-validation between executive interviews and regulatory filing analysis anchors the qualitative findings across this study. Primary discussions with dermatology clinic procurement managers, biomedical engineers at device manufacturers, GPO contracts administrators, and WeChat platform integration specialists combined with secondary review of FDA 510(k) submissions, MFDS medical device registrations, NMPA classification rulings, and EMA MDR technical documentation. Bottom-up installed base estimates and top-down market sizing triangulate volume figures.
Calibration against historical CAGRs from adjacent medical aesthetic device categories refined projection parameters across the analysis window. Segmentation modeling incorporated device type, technology modality, end-user procurement channel, and application focus dimensions. RF frequency specifications, LED wavelength distributions, and software upgrade attachment rates served as industry-specific forecast inputs alongside regulatory approval velocity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by algorithm-native entrants or sudden EMA reclassification of wellness claims would shift outcomes substantially. Cross-checking against hospital procurement database benchmarks and salon equipment leasing registries is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Hair Removal Products Market
Beauty & Personal Care
Brazil Sustainable Personal Care Market
Beauty & Personal Care
United Kingdom Hair Care Market
Beauty & Personal Care
Brazil Beauty and Personal Care Products Market
Beauty & Personal Care
Shaving Foam Market
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Frizz Control Shampoo Market
Beauty & Personal Care
Organic Beauty and Personal Care Ingredients Market
Beauty & Personal Care
Body Glitters Market
Beauty & Personal Care
Body Care Products Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Global Probiotic Cosmetic Products Market
Beauty & Personal Care
Private Label Cosmetics Market
Beauty & Personal Care
Vanity Mirror Market
Beauty & Personal Care
Men's Skincare Products Market