
 North America Hair Removal Wax Market | 2026-2036
North America Hair Removal Wax Market Size, Share, and Industry Trends Forecast 2026-2036
North America Hair Removal Wax Market Analytics
Plant-derived polymer technology is tilting formulation chemistry away from petroleum-based resins toward sugar-cane and tree-rosin bases. Church & Dwight leverages its mass-retail distribution network to sustain household penetration across drugstore channels. GiGi anchors professional supply through specialized wax warmers and educator-certified training programs. Sally Hansen competes in the at-home segment with microwaveable strip formats that reduce application complexity.
North America hair removal wax comprises thermoplastic compositions—typically colophonium, microcrystalline wax, or sucrose-based matrices—applied at 40–55°C to adhere to hair shafts for mechanical extraction. The primary commercial purpose centers on semi-permanent depilation across facial, body, bikini, and underarm zones with regrowth intervals of three to six weeks. Hard wax formulations now lead margin pools due to lower strip material costs and reduced skin-irritation liability in sensitive-area applications. Natural and organic formulation segments attract fastest-growing demand as clean-beauty certifications reshape procurement criteria for spa and clinic buyers.
Health Canada and the FDA govern cosmetic safety labeling, while state-level cosmetology boards in California, New York, and Texas enforce practitioner licensing and salon sanitation protocols that indirectly standardize equipment and consumable quality tiers. The Personal Care Products Council coordinates industry self-regulation on ingredient transparency ahead of anticipated federal fragrance-disclosure mandates. Stakeholders must monitor how bioplastic packaging regulations and extended producer responsibility laws in Canadian provinces and select U.S. states reshape supply chain cost structures and brand positioning requirements.
Market Dynamics
Clean-label formulation mandates from Health Canada and the FDA are compressing product development cycles and forcing raw-material substitutions across professional and retail wax segments. These disclosure requirements now determine supplier qualification thresholds and procurement veto rights.
Growth Catalysts
- Health Canada Ingredient Disclosure Rules:Transparency mandates for fragrance allergens and resin sources are accelerating reformulation toward plant-derived bases. Spa chains now require full material documentation as a procurement precondition.
- Hard Wax Technology:Stripless application methods reduce consumable costs and skin-irritation liability in Brazilian and facial services. Med-spa operators are converting treatment rooms to hard-wax protocols.
- California Salon Density:Los Angeles and San Francisco metro areas concentrate high-service-tier demand. Disposable income levels in these clusters support premium waxing studio expansion.
Market Restraints
- Colophonium Price Volatility:Portuguese and Brazilian pine resin supply faces climate-induced harvest fluctuations. Formulators absorb margin compression or reformulate with synthetic alternatives.
- Licensed Esthetician Shortage:Texas and Florida cosmetology boards report pipeline gaps for certified waxing practitioners. Salon operators delay location expansion due to staffing constraints.
- At-Home Device Substitution:IPL and laser hair removal systems capture repeat-purchase dollars from former waxing households. Drugstore wax kit volumes compress in urban markets with high med-spa penetration.
Strategic Opportunities
- Canadian Province EPR Laws:Extended producer responsibility frameworks in British Columbia and Ontario create first-mover positioning for recyclable wax warmer and strip packaging. Brands that pre-comply capture provincial procurement preferences.
- Men's Grooming Services:Dedicated back and chest waxing protocols remain underdeveloped outside major metros. Barbershop-waxing studio hybrid formats in Texas and Florida test male-focused service menus.
- Sugar-Cane Polymer Convergence:Bioplastic feedstock technology from packaging suppliers enables fully bio-based wax matrices. Formulation chemists partner with agricultural processors for captive sucrose supply.
Industry Challenges
- Cross-State Licensing Reciprocity:California, New York, and Texas maintain non-uniform continuing-education requirements. Multi-state spa chains face compliance fragmentation and training cost duplication.
- Wax Warmer Calibration Standardization:Temperature control inconsistencies across equipment brands create liability exposure. Manufacturers lack consensus on ISO thermal-performance testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Hair Removal Wax Market |
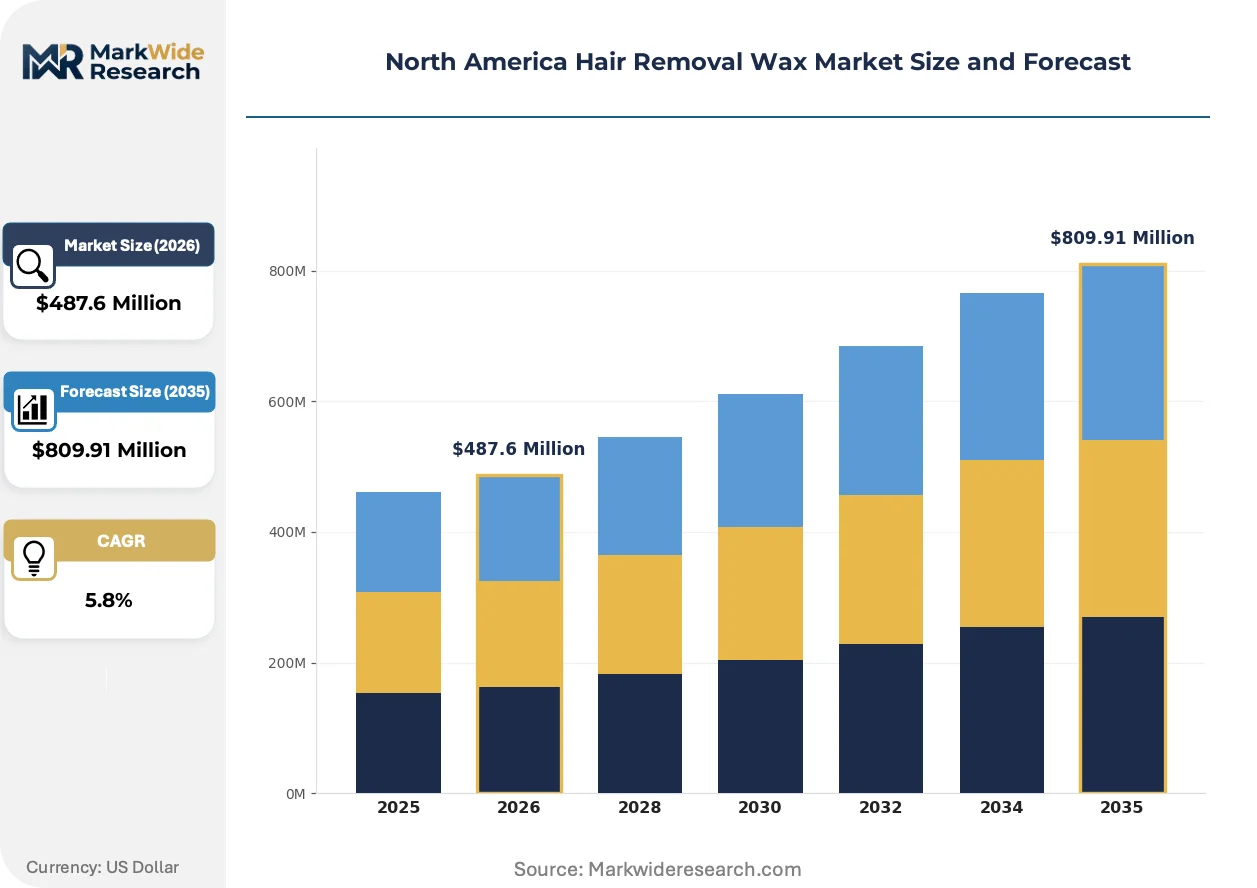
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $809.91 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soft Wax, Hard Wax, Sugar Wax, Cold Wax Formulation: Natural, Synthetic, Organic, Herbal Application Area: Facial, Body, Bikini Line, Underarm End User: Household, Salons, Beauty Clinics, Spa |
| Companies Covered | American International Industries, Church & Dwight, GiGi, FILO BIANCO, Parissa Laboratories, Perron Rigot, Sally Hansen, Reckitt Benckiser Group, Sue Ismiel and Daughters, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Hair Removal Wax Market Evolving Landscape
Formulation chemistry and service delivery models are undergoing simultaneous transformation. Plant-derived materials, regulatory disclosure systems, and buyer procurement preferences are the three active forces compressing legacy petroleum-based supply chains.
Smart temperature-monitoring systems embedded in professional wax warmers is digitizing service consistency and liability documentation. High-volume waxing studios in Florida and Texas are deploying these units to log treatment temperatures for insurance and regulatory audit trails. The data layer is compressing technician training variance and enabling outcome-based service guarantees.
FDA fragrance allergen disclosure proposals are forcing preemptive label redesign across retail wax strips and professional bulk formulations. Manufacturers now map supply chains to ingredient lot codes to satisfy anticipated batch-traceability mandates. The professional segment faces the heaviest compliance burden due to salon liability exposure and Health Canada cross-border shipment requirements.
Subscription-based waxing memberships are displacing per-service pricing in urban Texas and California markets. Consumers pre-commit to monthly appointments at locked rates, while studios secure predictable capacity utilization. The model concentrates demand in dense metro corridors where commute friction previously suppressed visit frequency.
North America Hair Removal Wax Market Segmentation
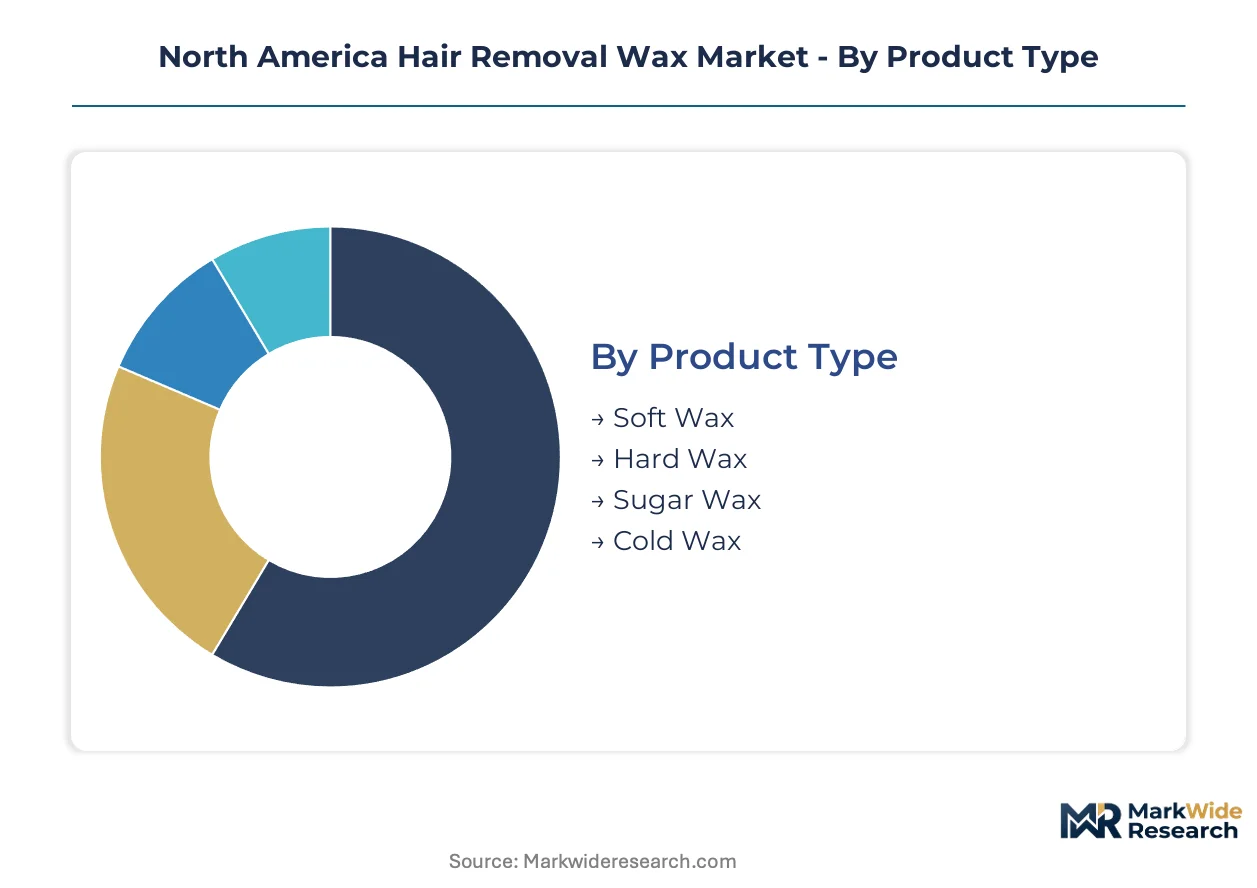
Product differentiation in North American hair removal wax tracks formulation chemistry, service delivery context, and body-zone sensitivity requirements. Segmentation discipline reveals where margin pools concentrate and which technology platforms warrant R&D allocation.
Product Type:
Cost tier separates the four product formats, with consumable economics and technician labor intensity driving salon procurement decisions.
- Hard Wax:Thermoplastic polymer matrices polymerize at room temperature for stripless removal, eliminating fabric strip costs. Los Angeles and Miami med-spa chains are converting Brazilian and facial treatment rooms to hard-wax protocols for reduced skin-irritation liability.
- Soft Wax:Low-viscosity resins require fabric or paper strips for mechanical extraction, maintaining dominance in high-volume leg and back services. Texas salon operators absorb higher consumable costs through faster service throughput and lower technician training thresholds.
- Sugar Wax:Water-soluble sucrose-lemon matrices permit ambient-temperature application and simplified cleanup. Home-use kits in California and Florida test microwaveable jar formats.
- Cold Wax:Pre-coated strip systems target travel and emergency-use occasions. Drugstore channels in urban Canadian markets stock pocket-format SKUs.
Hard wax holds installed capacity. Sugar wax is rotating up the share rankings.
Formulation:
Application context—professional service versus at-home use—determines which formulation chemistry commands price premiums.
- Natural:Tree-rosin and beeswax bases without petroleum derivatives satisfy Health Canada disclosure requirements. Spa procurement committees in Vancouver and Toronto mandate natural certification for vendor qualification.
- Organic:USDA-certified agricultural inputs attract premium service tiers in California and New York. Supply chain documentation burdens compress margin for smaller formulators.
- Synthetic:Microcrystalline wax and hydrocarbon resins deliver batch consistency at lowest unit cost. Mass retail channels in Florida and Texas rely on synthetic formulations for price-competitive kit positioning.
- Herbal:Botanical additives—aloe, chamomile, tea tree—target post-treatment inflammation reduction. Niche professional lines in Arizona and Colorado test regional ingredient sourcing.
Synthetic formulations anchor volume throughput. Organic certification is climbing the fastest.
Application Area:
Customer type—med-spa professional versus home user—shapes product format and sensitivity-grade requirements across body zones.
- Bikini Line:Hard-wax specialization dominates for coarse hair and minimized ingrown risk. Brazilian service menus in Texas and Florida drive premium wax consumption per appointment.
- Facial:Precision application demands low-temperature hard wax or sugar variants for eyebrow and lip zones. California aesthetician licensing requirements elevate product quality thresholds.
- Body:Leg, arm, and back services consume highest wax volumes through soft-wax strip methods. Salon density in Chicago and Atlanta supports bulk professional purchasing.
- Underarm:Sensitive-skin formulations with reduced resin content address odor-zone irritation concerns. Deodorant-waxing bundle trials test in New York metro markets.
Body applications hold installed capacity. Bikini line services are rotating up the share rankings.
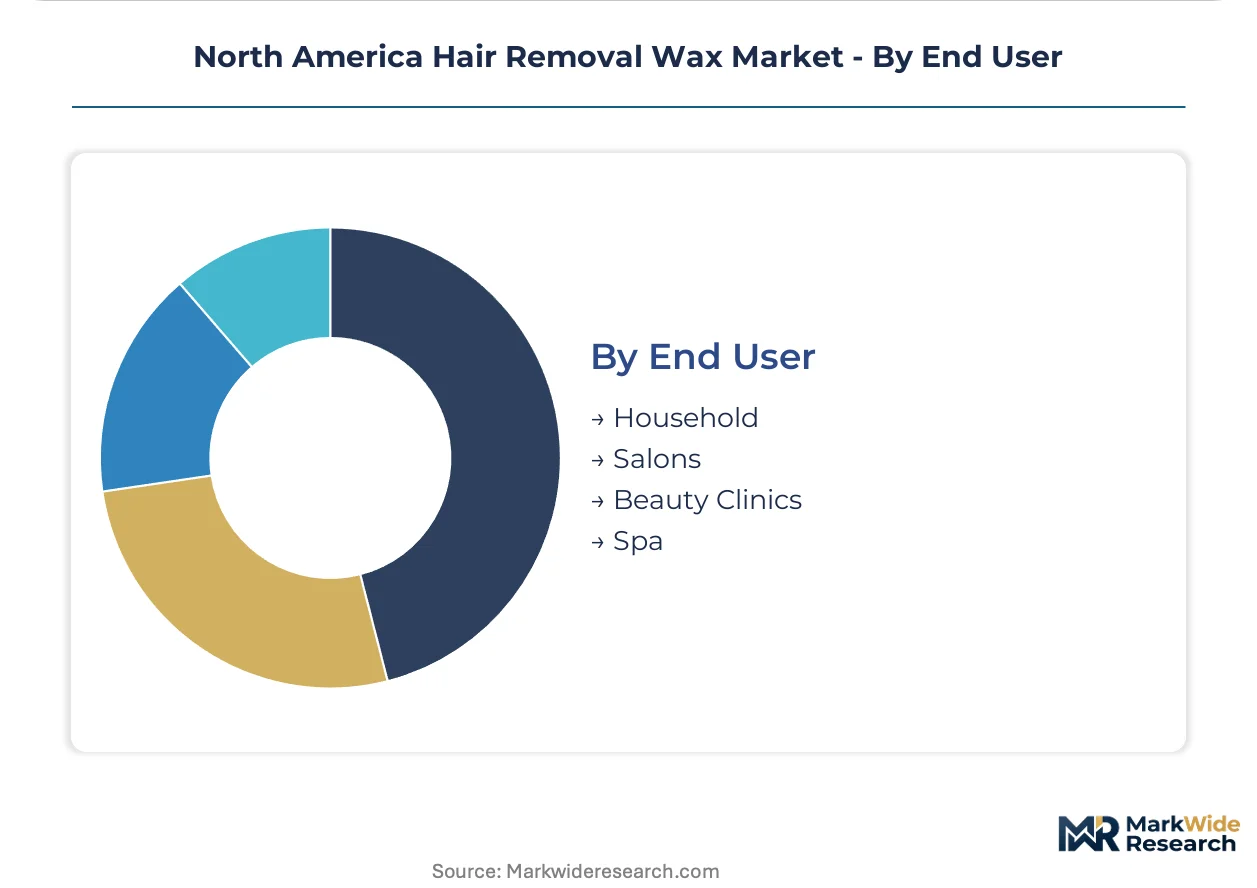
End User:
Volume scale and repeat-purchase frequency segment the four customer channels, with professional accounts driving formulation innovation and home users compressing price points.
- Salons:Independent and chain operators purchase bulk professional formulations with educator-certified training attachments. California cosmetology board sanitation protocols standardize equipment quality tiers.
- Spa:Resort and destination spa channels in Florida and Arizona command premium wax SKUs with extended treatment rituals. Procurement committees require full ingredient traceability.
- Beauty Clinics:Med-spa hybrids combining waxing with laser and injectable services demand hard-wax technology for reduced downtime. Texas medical board oversight elevates liability documentation requirements.
- Household:Microwaveable jar and pre-coated strip formats dominate drugstore and e-commerce channels. IPL device substitution compresses repeat purchase frequency in urban Canadian markets.
Salon channels hold installed capacity. Spa and clinic consolidation is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Med-spa chains and dedicated waxing studios concentrate professional-grade demand across three distinct national markets, each governed by divergent regulatory disclosure standards and salon-density economics.
United States
California, Texas, and Florida dominate service-tier revenue through elevated salon density and disposable income clusters. FDA cosmetic safety labeling governs ingredient disclosure, while state cosmetology boards in California and Texas enforce practitioner licensing that standardizes equipment procurement. Los Angeles and Miami med-spa chains are converting treatment rooms to hard-wax protocols for reduced liability exposure.
Canada
Vancouver and Toronto spa procurement committees now mandate natural certification as a vendor qualification threshold. Health Canada fragrance allergen transparency rules accelerate reformulation toward plant-derived bases. Extended producer responsibility frameworks in British Columbia and Ontario reshape packaging supply chain cost structures for early-compliant brands.
Mexico
Mexico City metro area supports emerging waxing studio expansion through growing middle-class service demand. The country's national health regulator oversees cosmetic safety standards that increasingly align with North American disclosure trends. Border-state salon operators in Nuevo León and Baja California absorb cross-border product flows from Texas distributors.
North America Hair Removal Wax Market Competitive Landscape
Channel-controlling players compete with product-specialist players across mass retail, professional supply, and direct-to-consumer vectors. Market structure tilts toward consolidation at the retail tier while fragmenting across professional educator networks and regional spa distributors. Two strategic archetypes dominate: mass-market conglomerates leveraging drugstore distribution density, and professional-grade specialists anchoring supply through certified training attachments. Competitive moves concentrate on portfolio diversification into natural formulation segments and backward integration into captive resin supply.
Among North American consumer goods conglomerates, Church & Dwight and Reckitt Benckiser Group occupy positions defined by mass-retail channel control and household penetration scale. Within the professional specialist tier, American International Industries and GiGi exemplify educator-certified training program models that lock in salon procurement loyalty. Parissa Laboratories and Sue Ismiel and Daughters represent the natural-formulation archetype, anchoring clean-beauty positioning for spa and clinic buyers demanding full ingredient traceability.
| Leading Market Players |
|---|
| American International Industries |
| Church & Dwight |
| GiGi |
| FILO BIANCO |
| Parissa Laboratories |
| Perron Rigot |
| Sally Hansen |
| Reckitt Benckiser Group |
| Sue Ismiel and Daughters |
| Others |
Value Network & Pricing Analysis
Brazilian and Portuguese pine resin harvests concentrate colophonium supply in two climate-vulnerable regions, directing margin capture toward formulators with synthetic substitution capabilities and long-term resin offtake contracts. Health Canada disclosure mandates now elevate procurement documentation costs, compressing margins for mid-tier suppliers lacking captive supply arrangements.
Pricing Analysis
Cost-plus contracts with colophonium price indexation dominate professional bulk purchasing, linking wax formulation costs to quarterly resin commodity benchmarks. Three-tier pricing structure across premium organic-certified, standard natural-grade, and economy synthetic tiers separates spa procurement committees from mass retail channels. Pricing pressure stems from IPL device substitution in urban Canadian and California markets, eroding repeat-purchase frequency for at-home wax kits. Household buyers exhibit highest price sensitivity, while med-spa operators absorb premium formulations for liability reduction.
Supply Chain Analysis
Pine resin feedstock draws primarily from Portugal, Brazil, and select southeastern U.S. pine belt regions, with microcrystalline wax sourcing concentrated in Texas and Louisiana petrochemical corridors. Beeswax and sugar-cane polymer inputs rest on agricultural supply from Florida, California, and Mexican cane processors. Single-source vulnerability in Portuguese colophonium exposes formulators to climate-induced harvest shortfalls. Distribution runs through professional beauty distributors in Texas and California, mass retail drugstore networks, and direct e-commerce fulfillment for home-use kits.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
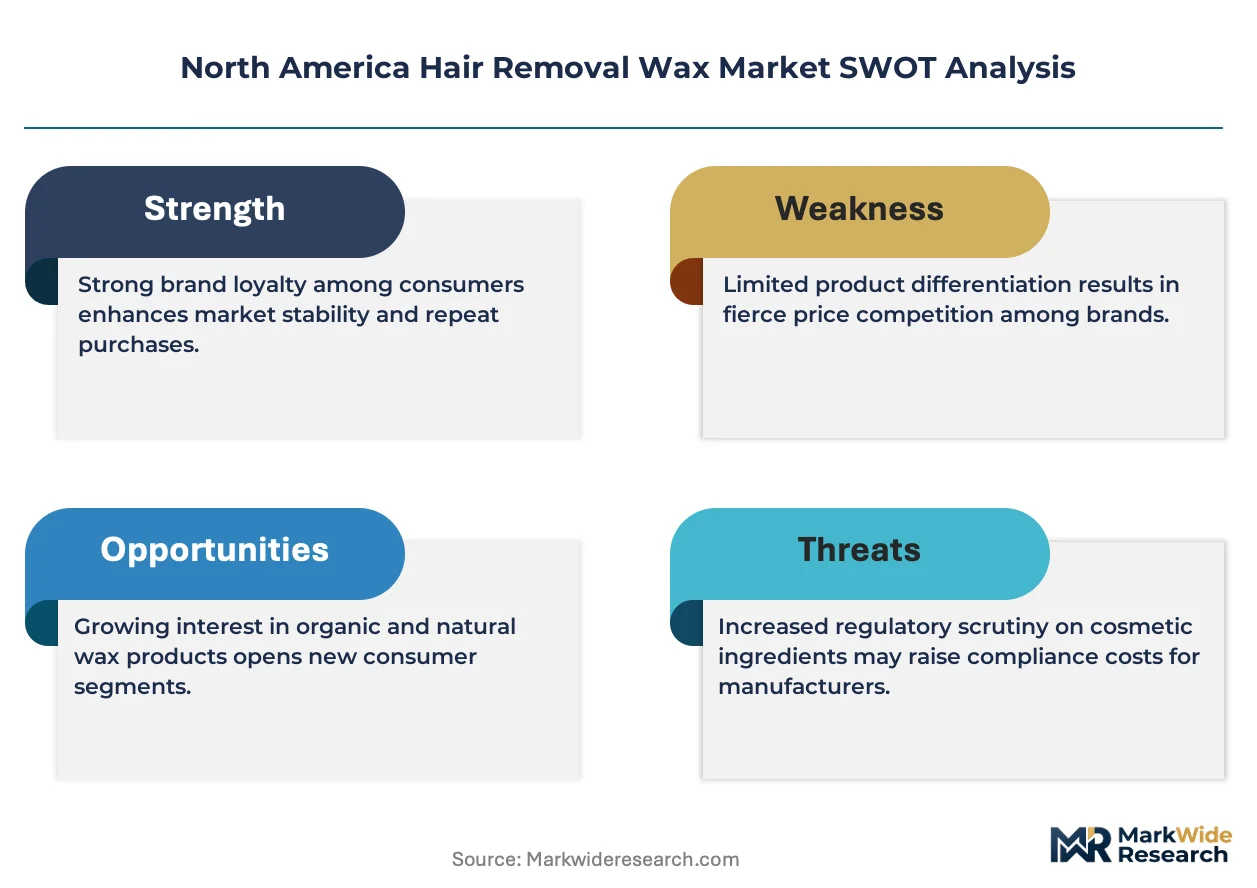
This market functions as a defensive-moat story anchored in regulatory entrenchment: Health Canada and FDA disclosure requirements create compliance barriers that favor incumbents with established documentation infrastructure and certified training networks.
For Market Incumbents: Insulate professional supply relationships through backward integration into captive resin supply or long-term Brazilian and Portuguese offtake agreements. Expand educator-certified training programs to lock in salon procurement loyalty against emerging natural-formulation specialists. Counter IPL substitution threat by positioning hard-wax protocols as med-spa standard-of-care for sensitive-area services.
For New Entrants and Emerging Players: Build out men's grooming service formats in Texas and Florida barbershop-waxing studio hybrids, where back and chest protocols remain underdeveloped outside major metros. Target Canadian province EPR pre-compliance as a provincial procurement wedge, capturing first-mover positioning in British Columbia and Ontario recyclable packaging mandates. Lead with sugar-cane polymer formulations to differentiate from petroleum-based incumbents.
For Investors and Strategic Acquirers: Capital is best deployed toward professional-grade specialists with captive educator networks and Health Canada documentation infrastructure already in place. Long-term viability over a multi-year horizon hinges on clean-label certification depth and resin supply security rather than retail brand recognition. Watch for colophonium price spike duration as the inflection signal: sustained elevation above indexation bands would accelerate synthetic substitution R&D and reshape competitive economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Supply | Captive Portuguese and Brazilian colophonium offtake locks in formulation cost predictability against climate volatility. |
| Educator-Certified Training Program Expansion | GiGi-style certification networks create switching costs that bind salon procurement to incumbent supply. |
| EPR Pre-Compliance Packaging Redesign | Early alignment with British Columbia and Ontario extended producer responsibility laws captures provincial procurement preferences. |
| Men's Grooming Service Format Development | Barbershop-waxing studio hybrids in Texas and Florida address underpenetrated male back and chest segments. |
| Sugar-Cane Polymer Formulation Investment | Bioplastic feedstock convergence enables fully bio-based wax matrices with Health Canada disclosure advantages. |
Research Methodology
A spread of perspectives from waxing studio operators, professional distributor procurement managers, Health Canada regulatory consultants, and med-spa chain clinical directors converged on the working assumptions underlying this analysis. Primary field engagement combined with secondary validation against FDA cosmetic labeling guidance documents, Health Canada ingredient disclosure advisories, state cosmetology board sanitation protocols, and beauty industry trade association publications. Bottom-up service-tier volume estimates triangulated against top-down retail channel shipment data.
Demand-supply-balance framing anchored the analytical approach across the analysis window, with segmentation modeled across product type, formulation chemistry, application area, and end-user channel dimensions. CAGRs were derived from fitted growth curves applied to professional service visit frequency and retail kit velocity inputs. Key forecast drivers included licensed esthetician pipeline gaps in Texas and Florida, IPL device household penetration rates in urban Canadian markets, and hard-wax protocol conversion rates in Los Angeles and Miami med-spa chains.
The forecast holds incumbent behavior within observed patterns; aggressive moves by natural-formulation specialists or sugar-cane polymer technology partners would shift outcomes through accelerated clean-label substitution. Cross-checking against state-level cosmetology board licensing data and provincial EPR implementation timelines is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
North America Bath and Shower Products Market
Beauty & Personal Care
Anti-Aging Beauty Device Market
Beauty & Personal Care
Mexico Beauty and Personal Care Market
Beauty & Personal Care
Makeup Egg Market
Beauty & Personal Care
Nail Strengtheners Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
Saudi Arabia Body Care and Personal Hygiene Market
Beauty & Personal Care
Face Steaming Devices Market
Beauty & Personal Care
Global Body Wash and Shower Gel Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Beard Straightener Market
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
South Korea Beauty Fridges Market
Beauty & Personal Care
Shaving and Hair Removal Products Market
Beauty & Personal Care
UK Sustainable Personal Care Market
Beauty & Personal Care
India Herbal Shampoo Market