
 Spain Dermocosmetics Market | 2026-2036
Spain Dermocosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Dermocosmetics Market Insights
EU REACH compliance is repositioning the cost-of-entry calculus for new dermocosmetic formulations in Spain. L'Oréal España SA leverages its Barcelona-based innovation hub to sustain rapid regulatory certification cycles. ISDIN anchors its competitive position through deep specialization in photoprotection products developed under dermatological supervision. Freshly Cosmetics SL differentiates via direct-to-consumer channel control and clean-label positioning that navigates evolving EU ingredient restrictions.
Dermocosmetics denote dermatologically tested skincare formulations containing active pharmaceutical or biologically functional ingredients at concentrations sufficient to exert measurable physiological effects on skin structure or function, typically manufactured under GMP conditions with validated stability protocols. These products serve the primary commercial purpose of bridging cosmetic aesthetics with clinically demonstrable skin health outcomes, distributed through channels that provide professional guidance. Moisturizers and serums occupy the largest margin pools due to higher per-unit pricing and repeat purchase frequency, while sunscreens represent the fastest-growing product type driven by rising melanoma awareness and Spanish outdoor lifestyle patterns. The anti-aging application segment leads absolute value contribution, though acne treatment shows accelerating growth among teen and young adult demographics.
Spain's national pharmaceutical regulator, AEMPS, enforces marketing authorization requirements for dermocosmetics with pharmacological claims, while the EU Cosmetics Regulation mandates comprehensive safety assessment dossiers through the Cosmetic Products Notification Portal. BIS-equivalent conformity assessment for imported raw materials adds procedural layers for non-EU suppliers seeking Spanish market access. Stakeholders must monitor forthcoming EU microplastic restrictions and evolving endocrine disruptor classifications that will force reformulation investments across multiple product lines.
Market Dynamics
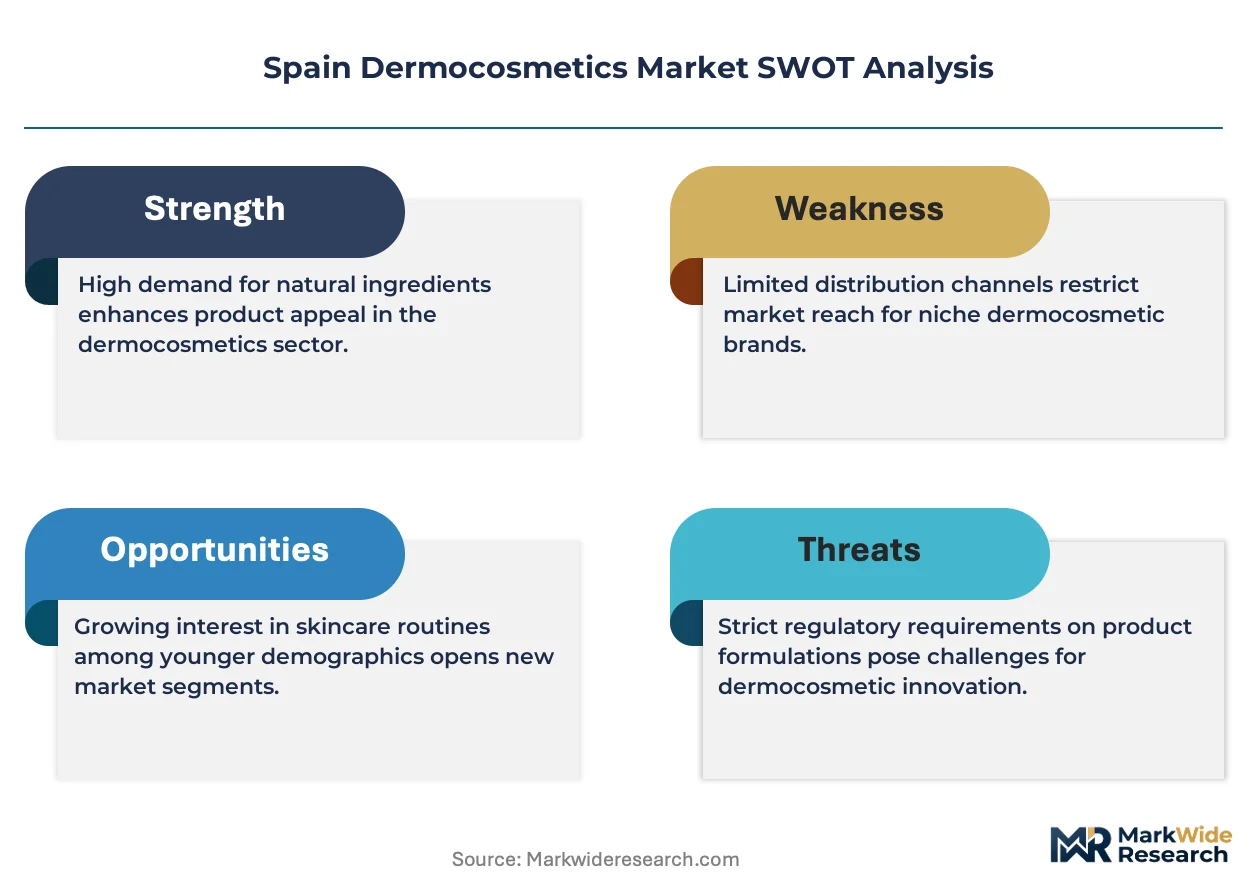
Pharmacy-led distribution concentration is restructuring competitive access in Spain's dermocosmetics sector, as pharmacist consultation becomes the decisive purchase trigger for clinical-grade skincare formulations. This channel gatekeeping forces brands to invest heavily in professional education and sampling infrastructure.
Growth Catalysts
- EU Cosmetics Regulation (EC) No 1223/2009:Ingredient disclosure mandates are elevating consumer trust in dermatologically tested products, channeling demand toward pharmacy-verified brands with complete safety dossiers.
- Melanoma awareness campaigns:Spanish outdoor lifestyle patterns and rising skin cancer education are expanding daily photoprotection routines beyond seasonal beach use into year-round urban skincare.
- Barcelona-Madrid urban corridor:Concentrated affluence among consumers aged 35-55 is normalizing premium clinical-grade routines as standard hygiene practice rather than discretionary luxury.
Market Restraints
- EU REACH compliance costs:Reformulation expenses for endocrine disruptor reclassifications are compressing margins for mid-tier brands without scale economies in regulatory affairs.
- API import dependency:Non-EU raw material suppliers face BIS-equivalent conformity assessments that extend procurement cycles and create inventory volatility for Spanish manufacturers.
- Pharmacy channel gatekeeping:Limited shelf space and pharmacist preference for established relationships create structural barriers for new market entrants regardless of product efficacy.
Strategic Opportunities
- Andalusian and Basque regional expansion:Underpenetrated pharmacy networks in Seville and Bilbao offer first-mover advantages for brands with established Madrid-Barcelona infrastructure.
- Direct-to-consumer platform development:Subscription-based personalization services can bypass pharmacy margin splits while capturing repeat purchase data for formulation refinement.
- EU Green Deal alignment:Biodegradable packaging mandates and microplastic restrictions create positioning space for brands with preemptive sustainable supply chain investments.
Industry Challenges
- Dermatological supervision capacity:Limited availability of credentialed professionals for product co-development creates bottlenecks in photoprotection and acne treatment line extensions.
- Cosmetic Products Notification Portal timelines:Safety assessment dossier preparation consumes 12-18 months for novel active ingredients, delaying competitive response to formulation trends.
- Cross-channel pricing coherence:Pharmacy MAP agreements conflict with DTC promotional flexibility, risking partner relationship erosion during platform expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Dermocosmetics Market |
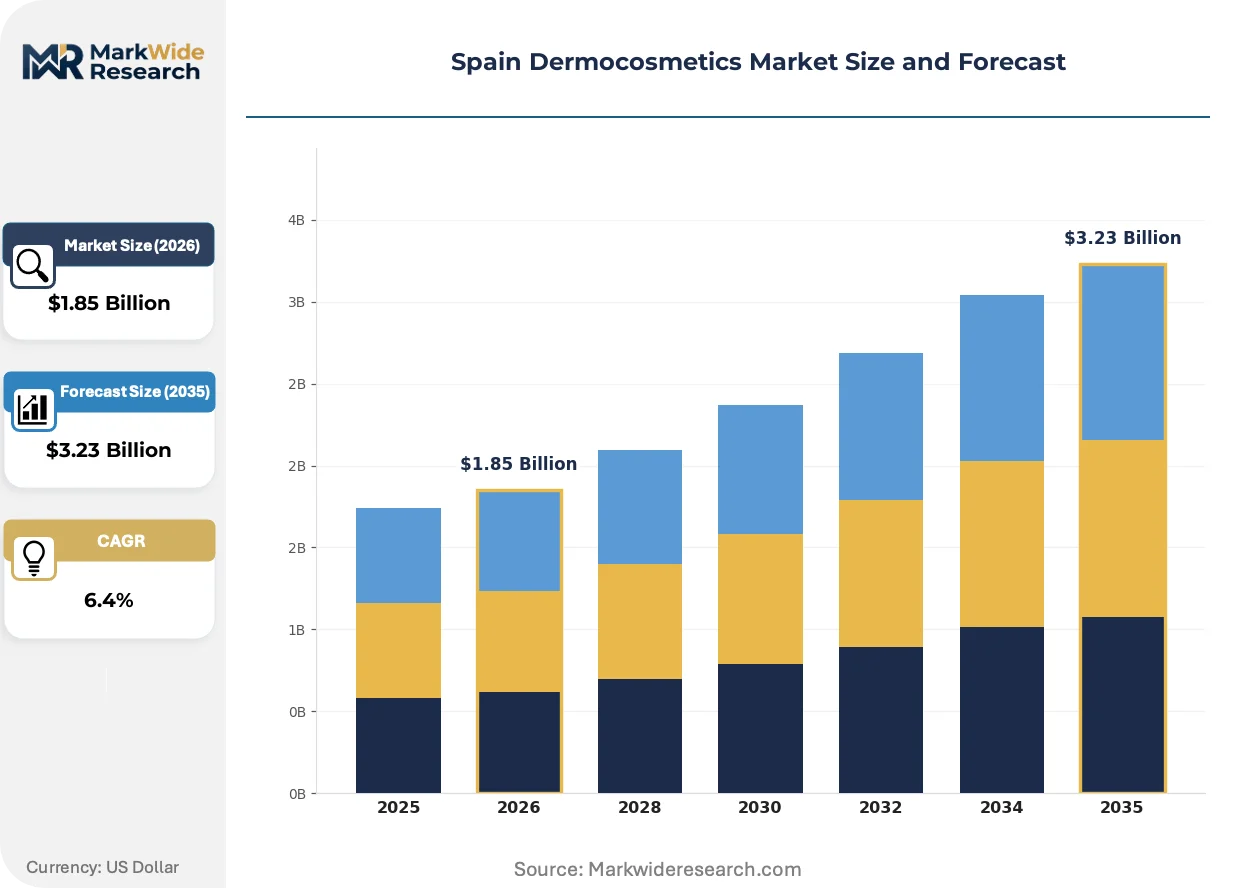
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Cleansers, Sunscreens Application: Anti-Aging, Hydration, Acne Treatment, Skin Repair End User: Women, Men, Teens, Healthcare Professionals Distribution Channel: Pharmacies, Online Retail, Supermarkets, Specialty Stores |
| Companies Covered | Unilever España SA, Henkel Ibérica SA, L'Oréal España SA, Mercadona SA, Freshly Cosmetics SL, Beiersdorf SA Spain, Estée Lauder SA, ISDIN, Pierre Fabre Ibérica SA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Dermocosmetics Market Trends and Innovations
Biometric skin analysis tools are reshaping how Spanish consumers select dermocosmetic regimens, shifting purchase authority from pharmacist recommendation toward data-driven self-diagnosis. This technology convergence is compressing the traditional consultation-to-transaction pathway.
Artificial intelligence-powered skin imaging is automating the matching of active ingredient concentrations to individual barrier function profiles. Madrid-based dermatology clinics are deploying these diagnostic platforms to streamline patient triage and product recommendation workflows. The technology is automating routine assessments previously requiring extended pharmacist or clinician consultation time.
AEMPS marketing authorization requirements for pharmacological claims are tightening the evidentiary threshold for anti-aging and acne treatment positioning. Brands must now submit clinical trial data comparable to medical device standards before deploying efficacy messaging. Spanish manufacturers with in-house dermatological research capabilities are capturing shelf space from imports unable to satisfy documentation demands.
Spanish consumers are consolidating skincare routines around multi-functional products that replace separate moisturizer, serum, and sunscreen applications. Pharmacy chains in Barcelona are responding with curated regimen simplification displays that emphasize step reduction over ingredient complexity. This behavioral pivot favors formulations with proven photoprotection-actives compatibility over single-benefit legacy products.
Spain Dermocosmetics Market Segmentation
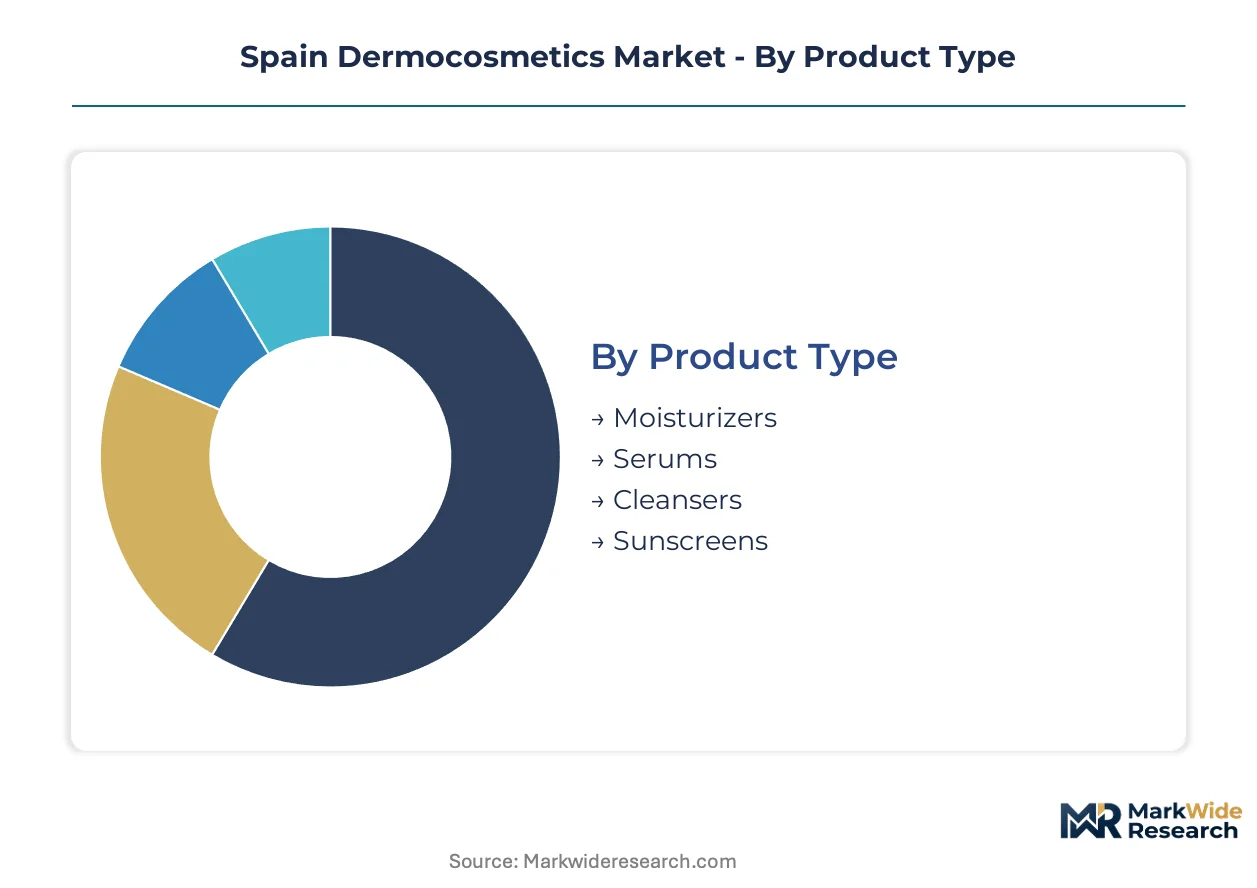
Dermocosmetic segmentation in Spain reflects the tension between clinical validation requirements and consumer accessibility preferences. Product positioning must navigate AEMPS marketing authorization thresholds while serving distinct demographic routines across Madrid-Barcelona urban corridors and emerging regional markets.
Product Type:
Standardization dominates photoprotection formulations where EU REACH compliance costs favor scale, while moisturizers and serums permit greater customization in active ingredient concentrations.
- Moisturizers:Barrier-repair formulations with ceramides and niacinamide at therapeutic concentrations. Demand clusters among consumers aged 35-55 in Barcelona's pharmacy networks, driven by dermatologist-prescribed routines for post-procedure skin recovery.
- Serums:High-actives concentrates requiring stability protocols and validated delivery systems. Madrid urban professionals are normalizing multi-serum layering as standard hygiene practice, compressing the legacy cleanse-tone-moisturize sequence.
- Cleansers:pH-balanced surfactant systems with prebiotic adjuncts for microbiome support.
- Sunscreens:Photostable filters meeting AEMPS authorization for daily-use claims; Basque Country pharmacies report year-round adoption beyond seasonal beach demand.
Most installed capacity flows through Moisturizers. Expansion is steepest in Sunscreens.
Application:
Margin concentration favors anti-aging where per-unit pricing absorbs clinical trial documentation costs, while acne treatment segments serve volume through younger demographics with lower reimbursement thresholds.
- Anti-Aging:Retinoid and peptide formulations requiring dermatological supervision for concentration titration. Barcelona-Madrid corridor consumers aged 40-55 treat these as non-discretionary maintenance, not luxury expenditure.
- Hydration:Hyaluronic acid and glycerin-based systems for compromised barrier function. Andalusian pharmacies report rising demand among outdoor workers facing dehydration from agricultural and construction exposure.
- Acne Treatment:Benzoyl peroxide and adapalene combinations; teen segments in Valencia and Seville drive volume despite lower per-transaction value.
- Skin Repair:Post-inflammatory hyperpigmentation and barrier restoration for procedural aftercare.
Anti-Aging commands the highest revenue per unit. Acne Treatment is gaining share fastest among under-25 consumers.
End User:
Gender-based customization is fragmenting as male-specific lines launch, though healthcare professional channels maintain stricter standardization for institutional procurement.
- Women:Core demographic for multi-step regimen complexity and premium positioning across all age cohorts.
- Men:Simplified two-step systems gaining traction in Bilbao and Madrid urban centers; pharmacy chains are dedicating discrete shelf space to bypass stigma-driven browsing avoidance.
- Teens:Price-sensitive acne-focused demand concentrated in online retail with parental proxy purchasing.
- Healthcare Professionals:Institutional procurement for clinic dispensing; AEMPS authorization requirements create vendor concentration around established dermatology partnerships.
Women account for the majority of current transaction volume. Men represent the steepest expansion trajectory as social normalization accelerates.
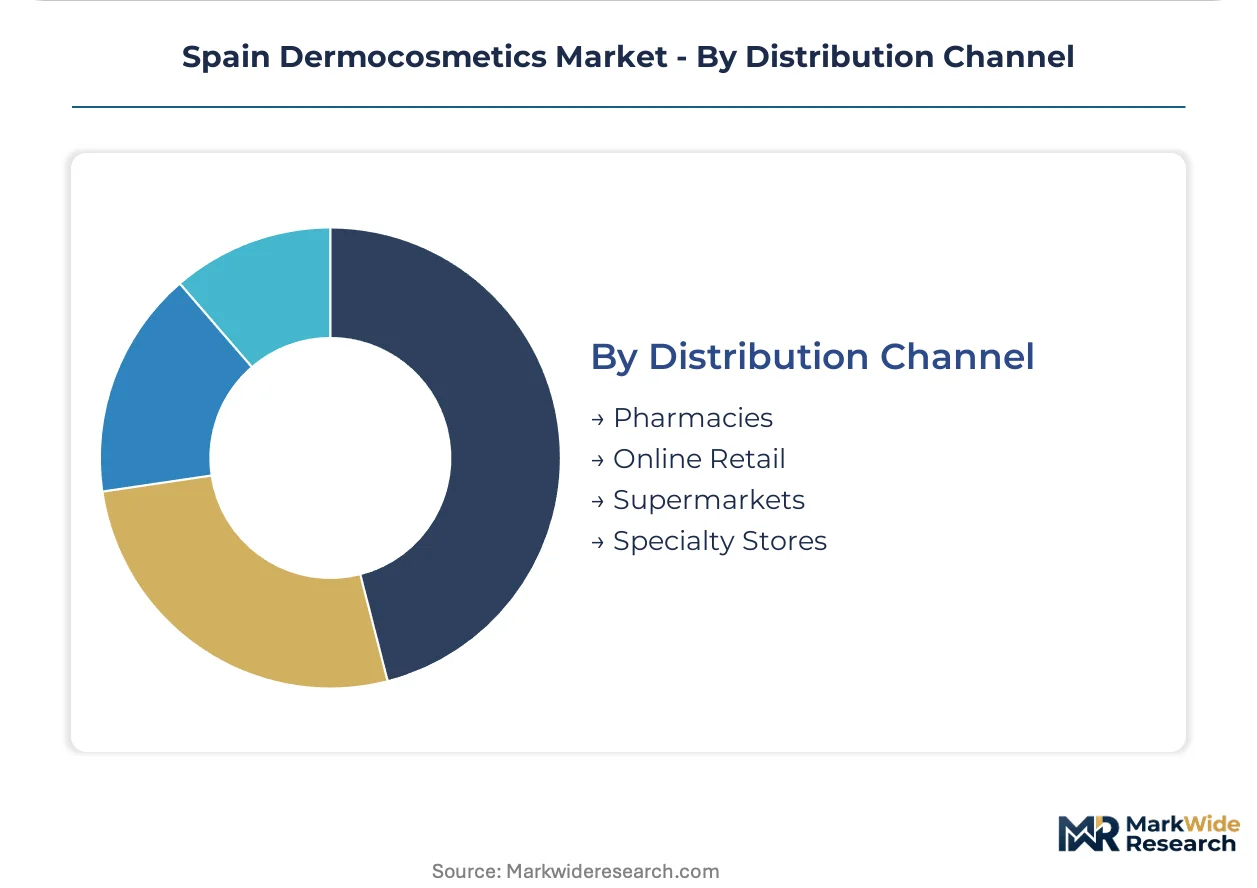
Distribution Channel:
Channel selection determines pricing architecture and consultation depth, with pharmacy gatekeeping creating structural barriers to price transparency.
- Pharmacies:Pharmacist consultation remains the decisive purchase trigger for first-time clinical-grade adoption; AEMPS-verified claims provide differentiation against general cosmetics.
- Online Retail:Subscription personalization and repeat replenishment bypassing pharmacy margin splits; Freshly Cosmetics SL and direct-to-consumer specialists dominate this channel.
- Supermarkets:Mass-market dermocosmetic hybrids with reduced active concentrations; price competition limits clinical credibility.
- Specialty Stores:Sephora and Douglas locations in Madrid and Barcelona offering diagnostic technology integration for regimen curation.
Pharmacies retain the highest trust coefficient for new patient acquisition. Online Retail is climbing the fastest as subscription models capture loyalty.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Spain's dermocosmetics sector concentrates specialized formulation chemists and dermatological researchers in its Mediterranean urban corridor. This talent density anchors production and innovation capacity across five distinct sub-regional markets.
Madrid
Pharmacy network density in the capital region sustains the highest per-capita dermocosmetic consumption nationwide. AEMPS regulatory proximity accelerates marketing authorization timelines for brands maintaining headquarters or liaison offices here. The Madrid-Barcelona logistics corridor enables rapid distribution to secondary markets while serving as the primary entry point for international brands seeking Spanish market access.
Catalonia
Barcelona's innovation infrastructure supports clinical-grade formulation development with proximity to dermatology research institutes. EU REACH compliance expertise concentrates in this region, reducing regulatory certification cycles for new active ingredient introductions. The metropolitan area hosts specialized manufacturing facilities serving both domestic pharmacy channels and export markets across Southern Europe.
Basque Country
Bilbao and San Sebastián pharmacies report accelerating male-specific dermocosmetic adoption as social normalization advances. Regional health authorities emphasize melanoma prevention campaigns that expand year-round photoprotection demand beyond traditional seasonal patterns. Industrial chemistry capabilities from the region's materials science heritage support contract manufacturing for mid-tier brands lacking in-house production.
Andalusia
Seville and Málaga represent underpenetrated expansion opportunities with pharmacy network gaps relative to population density. Agricultural and construction worker demographics drive functional hydration product demand for occupational skin stress conditions. EU Green Deal alignment investments in sustainable packaging are positioning regional distributors for forthcoming microplastic restriction compliance.
Valencia
Teen and young adult demographics in this coastal region concentrate acne treatment volume through parental proxy purchasing channels. Pharmacy chains here are piloting biometric skin analysis integration to streamline consultation-to-transaction pathways. The port infrastructure supports raw material import efficiency for manufacturers dependent on non-EU active pharmaceutical ingredient suppliers.
Spain Dermocosmetics Market Competitive Landscape
The competitive structure tilts toward multinational scale players with established pharmacy channel relationships and regulatory affairs infrastructure. Mid-tier domestic specialists occupy differentiation positions through clean-label positioning or direct-to-consumer channel control. Two strategic archetypes dominate: consolidated beauty conglomerates leveraging portfolio breadth and agile domestic independents exploiting regulatory responsiveness. Capacity expansion and professional education investments constitute the primary competitive moves, as shelf space access requires sustained pharmacist relationship cultivation.
Among Spain-based specialists, Freshly Cosmetics SL exemplifies the direct-to-consumer archetype with channel control that bypasses pharmacy margin structures. L'Oréal España SA occupies the multinational scale position with regulatory certification infrastructure concentrated in its Barcelona innovation hub. ISDIN represents the dermatological specialization archetype, anchoring competitive position through photoprotection focus developed under clinical supervision protocols. These three entities collectively illustrate the strategic segmentation between scale, specialization, and channel independence that structures competitive rivalry.
| Leading Market Players |
|---|
| Unilever España SA |
| Henkel Ibérica SA |
| L'Oréal España SA |
| Mercadona SA |
| Freshly Cosmetics SL |
| Beiersdorf SA Spain |
| Estée Lauder SA |
| ISDIN |
| Pierre Fabre Ibérica SA |
| Others |
Pricing and Supply Chain Analysis
Niacinamide and ceramide feedstock indices cascade through Spanish dermocosmetic manufacturing into three distinct pricing tiers, with pharmacy-channel premiums absorbing EU REACH compliance costs while direct-to-consumer models compress margins through subscription bundling.
Pricing Analysis
Pharmacist consultation bundling separates premium clinical-grade formulations from unbundled mass-market alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects AEMPS authorization status and dermatological supervision depth. Cost compression in the mid-tier is intensifying because REACH reformulation expenses disproportionately burden brands lacking L'Oréal-scale regulatory infrastructure. Teen acne segments exhibit highest price sensitivity, while Barcelona-Madrid professionals aged 40-55 treat anti-aging serums as non-discretionary maintenance expenditure.
Supply Chain Analysis
Single-source vulnerability sits with Indian and Chinese active pharmaceutical ingredient suppliers facing BIS-equivalent conformity assessments. Spanish manufacturing draws from German specialty chemical houses for photostable filters, French peptide synthesis specialists, and Swiss packaging innovators. Tariff exposure on non-EU raw materials creates inventory volatility for mid-tier brands without captive supply arrangements. Distribution runs through pharmacy networks with established AEMPS-verified claims, though Freshly Cosmetics-style direct-to-consumer platforms are capturing repeat replenishment volume.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's dermocosmetics sector functions as a stable compounder, with pharmacy-channel trust dynamics and recurring replenishment patterns generating predictable cash flow visibility across economic cycles.
For Market Incumbents: Anchor shelf space access through sustained pharmacist education investments and sampling infrastructure that reinforces AEMPS-verified positioning against direct-to-consumer disintermediation. Deepen dermatological supervision partnerships to accelerate photoprotection line extensions before microplastic restrictions force reformulation. Prioritize backward integration into Barcelona-based formulation chemistry to compress regulatory certification cycles for novel active ingredients. For New Entrants and Emerging Players: Capture Andalusian pharmacy network gaps in Seville and Málaga where agricultural worker demographics drive functional hydration demand underserved by Madrid-Barcelona incumbents. Deploy biometric skin analysis platforms to streamline consultation-to-transaction pathways and bypass established pharmacist relationship barriers. Pursue clean-label positioning with preemptive EU Green Deal alignment to differentiate against legacy brands facing sustainable packaging transition costs. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic mid-cap specialists possessing direct-to-consumer channel control and regulatory responsiveness agility. The five-to-ten year viability window favors acquisition targets with established AEMPS dossier libraries and dermatology clinic dispensing relationships. Monitor EU endocrine disruptor reclassification timelines as inflection indicators for reformulation investment intensity and competitive shakeout velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacist Education Infrastructure | Sustained professional sampling programs secure shelf space access against DTC competitors in AEMPS-regulated channels. |
| Dermatological Supervision Partnerships | Clinical co-development protocols accelerate photoprotection and acne treatment line extensions with validated efficacy claims. |
| Direct-to-Consumer Platform Buildout | Subscription personalization captures repeat purchase data while bypassing pharmacy margin splits in Madrid-Barcelona corridors. |
| EU Green Deal Supply Chain Alignment | Biodegradable packaging investments position brands ahead of forthcoming microplastic restriction enforcement. |
| Regional Pharmacy Network Expansion | First-mover infrastructure in Andalusia and Basque Country exploits underpenetrated Seville-Bilbao corridors. |
Research Methodology
Direct dialogue with pharmacy chain procurement directors, dermatology clinic dispensing managers, AEMPS regulatory affairs specialists, and dermocosmetic brand marketing executives grounded the qualitative foundation. Secondary validation drew from AEMPS marketing authorization filings, EU Cosmetics Regulation safety assessment dossiers, Spanish customs import records for active pharmaceutical ingredients, and pharmacy retail audit data. Bottom-up prescription volume modeling and top-down category spend estimates were triangulated to cross-validate market sizing.
Segment-level projections across moisturizers, serums, cleansers, and sunscreens were generated through the analysis window, with application splits for anti-aging, hydration, acne treatment, and skin repair calibrated against demographic cohort penetration rates. CAGRs were derived from historical pharmacy channel growth patterns, EU regulatory timeline impacts on formulation turnover, and melanoma awareness campaign intensity assumptions. Pricing elasticity parameters incorporated pharmacy MAP agreement structures and DTC subscription discounting norms.
EU REACH reformulation timelines, AEMPS authorization backlog fluctuations, and raw material import tariff adjustments are the dominant revision risks for forecast trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Cosmetic Wax Market
Beauty & Personal Care
Oil Control Shampoo Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
United Kingdom Dermocosmetics Market
Beauty & Personal Care
Personal Care Ingredients Market
Beauty & Personal Care
At-Home Beauty Devices Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Luxury Hair Care Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
Europe Professional Beauty Services Market
Beauty & Personal Care
Europe Male Grooming Products Market
Beauty & Personal Care
Makeup Setting Spray Market