
 UK Vegan Cosmetics Market | 2026-2036
UK Vegan Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
UK Vegan Cosmetics Market Insights
Leaping Bunny certification is redrawing competitive boundaries in the UK vegan cosmetics sector. L'Oreal SA leverages its extensive R&D infrastructure to navigate complex ingredient compliance across European and UK regulatory frameworks. Unilever PLC anchors its market position through broad distribution networks spanning supermarkets and specialty retail channels. e.l.f. Beauty, Inc. competes aggressively on price while maintaining vegan formulation integrity.
UK vegan cosmetics comprise beauty and personal care products formulated without animal-derived ingredients or animal testing, typically incorporating plant-based emollients, synthetic peptides, and mineral pigments to achieve functional parity with conventional alternatives. Skincare dominates current value generation due to higher per-unit pricing and repeat purchase frequency among established consumers. Makeup represents the fastest-expanding category as Generation Z buyers prioritize ethical alignment in color cosmetics. The formulation type dimension reveals that cruelty-free claims now function as a baseline expectation rather than a premium differentiator.
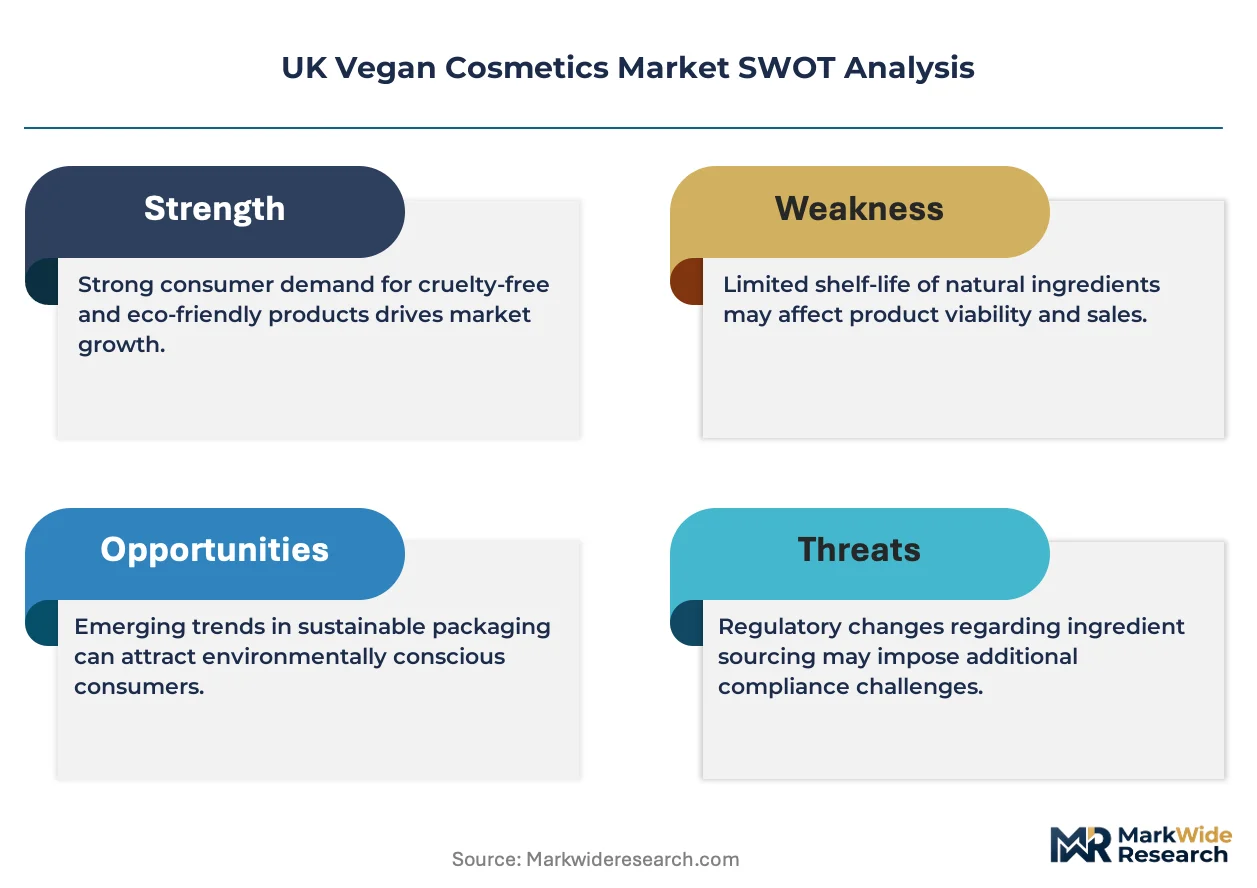
The UK's retained EU Cosmetics Regulation, enforced by the Office for Product Safety and Standards, mandates rigorous safety assessments that effectively filter out non-compliant entrants. The Competition and Markets Authority monitors greenwashing claims, pressuring brands to substantiate vegan and cruelty-free assertions with verified supply chain documentation. Stakeholders must track evolving divergence between UK and EU chemical safety standards as regulatory misalignment risks fragmenting product portfolios.
Market Dynamics
Leaping Bunny certification requirements are compressing formulation timelines while fragmenting supplier bases as brands scramble to document cruelty-free supply chains before the Office for Product Safety and Standards intensifies post-Brexit enforcement.
Growth Catalysts
- Retained EU Cosmetics Regulation:The UK's adoption of stringent ingredient safety assessments is filtering out non-compliant competitors and elevating formulation standards across domestic manufacturers.
- Generation Z buyer concentration:Ethical alignment in color cosmetics is accelerating repeat purchase frequency among digital-native consumers in Greater London and the South East.
- Plant-based emollient innovation:Synthetic peptide alternatives to animal-derived collagen are achieving functional parity in premium skincare formulations.
Market Restraints
- Specialty ingredient supply concentration:Mineral pigment suppliers cluster in Germany and France, exposing UK formulators to Brexit-related customs friction and extended lead times.
- Greenwashing liability expansion:Competition and Markets Authority substantiation requirements are forcing brands to maintain costly verified supply chain documentation.
- Petrochemical-derived substitute threat:Conventional synthetic emollients retain cost advantages over plant-based alternatives in mass-market price tiers.
Strategic Opportunities
- Underpenetrated Northern England:Manchester and Leeds present whitespace for premium vegan cosmetics where specialty retail density lags London benchmarks.
- Regulatory divergence arbitrage:Emerging gaps between UK and EU chemical safety standards may allow UK-only formulations with faster approval timelines.
- Direct-to-consumer channel maturation:Subscription box services targeting young professional women are compressing customer acquisition costs outside traditional retail markups.
Industry Challenges
- Formulation chemist scarcity:Expertise in plant-based emulsion stability and synthetic peptide integration commands premium compensation in a shallow talent pool.
- Leaping Bunny certification timelines:The 12-18 month supply chain audit process delays product launches and strains working capital for emerging brands.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Vegan Cosmetics Market |
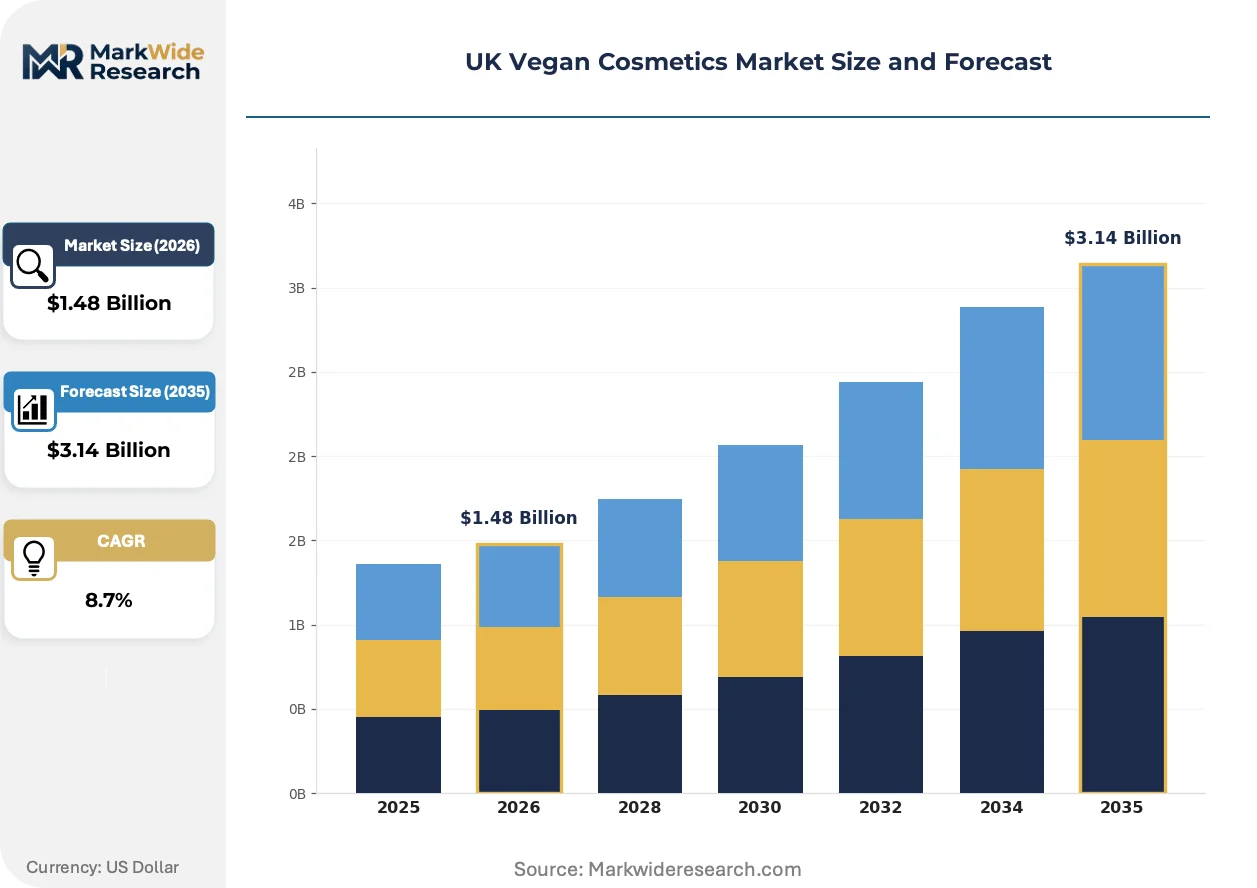
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $3.14 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Haircare, Makeup, Bath & Body, Fragrances Formulation Type: Cruelty-Free, Organic, Natural, Paraben-Free, Sulfate-Free Distribution Channel: Specialty Stores, Online Retailers, Pharmacies, Supermarkets, Beauty Salons Consumer Segment: Millennials, Generation Z, Professionals, Eco-Conscious Shoppers |
| Companies Covered | Coty Inc., Pacifica Beauty, LLC, L'Oreal SA, MuLondon, Urban Decay, Unilever PLC, Estee Lauder Companies, Beauty Without Cruelty, e.l.f. Beauty, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Vegan Cosmetics Market Trends and Innovations
Biotechnology-derived actives are displacing conventional botanical extraction in high-performance vegan skincare, while regulatory transparency mandates and channel fragmentation are simultaneously elevating formulation costs and compressing go-to-market timelines.
Precision fermentation for collagen alternatives is miniaturizing production economics. Specialist biotech firms supply lab-grown elastin to premium skincare brands at scale points previously reserved for mass-market petrochemicals. Indie beauty labels in Shoreditch and Brighton are adopting these inputs faster than established players, collapsing the historical gap between niche positioning and industrial-grade supply security.
The Office for Product Safety and Standards is intensifying post-market surveillance of vegan claims under retained EU Cosmetics Regulation frameworks. Manufacturers must now maintain batch-level traceability documentation from raw material to finished good. Small-to-mid-sized brands in the South East are consolidating compliance functions or outsourcing to specialized regulatory consultancies to manage audit frequency.
Young professional women are unbundling discovery from purchase, treating social platforms as primary research channels before completing transactions through brand-direct websites. Department store beauty halls in Greater London are responding with experiential formats that prioritize sampling and education over immediate conversion. This behavior is most pronounced among Generation Z entrants who treat Leaping Bunny certification as a non-negotiable filter rather than a premium signal.
UK Vegan Cosmetics Market Segmentation
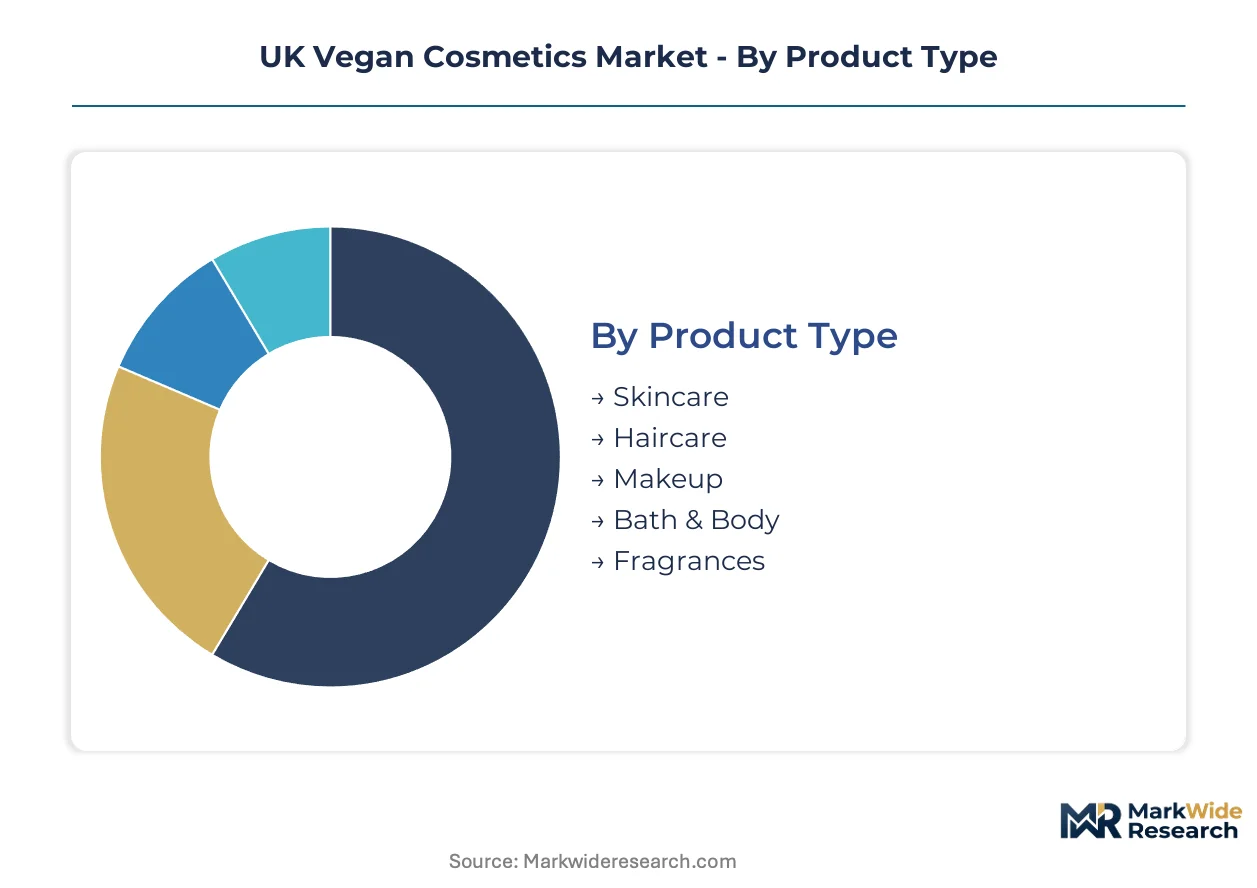
Segmentation in the UK vegan cosmetics market reveals how regulatory compliance costs and certification requirements reshape competitive positioning across product tiers. Understanding these divides enables stakeholders to allocate R&D investment toward segments where formulation complexity aligns with margin protection.
Product Type:
The Office for Product Safety and Standards enforces retained EU Cosmetics Regulation safety assessments most stringently for leave-on formulations, elevating compliance burdens for skincare relative to rinse-off categories.
- Skincare:Serums, moisturizers, and treatments formulated with plant-based emollients and synthetic peptides command premium pricing in Greater London. The Office for Product Safety and Standards mandates extended stability testing for leave-on products, compressing margins for non-compliant entrants.
- Makeup:Color cosmetics incorporating mineral pigments and vegan emulsion systems are expanding most quickly among Generation Z buyers in urban centers. Leaping Bunny certification functions as a non-negotiable filter for first-time purchasers, accelerating brand switching toward verified labels.
- Haircare:Shampoos and conditioners utilizing sulfate-free surfactant alternatives face formulation stability challenges that extend development timelines.
- Bath & Body:Wash-off products encounter lower regulatory scrutiny but compete intensely on price in supermarket channels.
- Fragrances:Synthetic musk replacements and botanical extracts require complex supply chain documentation under retained EU allergen disclosure rules.
Established volume favors Skincare; emerging adoption favors Makeup.
Formulation Type:
Cost tier differentiation separates mass-market accessible claims from premium-positioned certifications that demand verified supply chain investment.
- Cruelty-Free:Formulations documented through Leaping Bunny's 12-18 month audit process command shelf space in specialty retail. The Competition and Markets Authority's greenwashing enforcement pressures brands to maintain batch-level traceability or face liability exposure.
- Organic:Soil Association or equivalent certification requires minimum organic content thresholds that constrain preservative selection and extend stability testing. Demand concentrates among Eco-Conscious Shoppers in the South East willing to absorb 40-60% price premiums.
- Natural:Plant-derived ingredient claims without formal certification face heightened scrutiny from the Competition and Markets Authority.
- Paraben-Free:Alternative preservation systems using phenoxyethanol or sodium benzoate require reformulation expertise that concentrates among established manufacturers.
- Sulfate-Free:Gentler surfactant alternatives achieve functional parity in premium tiers but retain cost disadvantages in mass-market positioning.
Certification density peaks with Organic; volume accessibility peaks with Cruelty-Free.
Distribution Channel:
Channel selection determines margin structure through markup layers and customer acquisition cost profiles across the UK.
- Specialty Stores:Curated beauty retailers in Greater London and Brighton provide discovery environments where Leaping Bunny certification receives visual prominence. These outlets absorb 40-50% wholesale margins but deliver pre-qualified ethical buyers with elevated lifetime value.
- Online Retailers:Direct-to-consumer platforms and third-party marketplaces are compressing customer acquisition costs through subscription models targeting young professional women. The channel bypasses traditional retail markups while demanding sophisticated digital marketing capabilities.
- Pharmacies:Boots and Superdrug locations provide credibility signaling for sensitive-skin formulations but require mass-market price positioning.
- Supermarkets:Tesco and Sainsbury's shelf space prioritizes price-competitive SKUs with simplified certification claims.
- Beauty Salons:Professional-only distribution channels sustain premium pricing through service bundling and practitioner recommendation.
Margin protection favors Specialty Stores; scale efficiency favors Online Retailers.
Consumer Segment:
Generational and occupational divides shape purchasing frequency, price sensitivity, and information-seeking behavior across UK regions.
- Millennials:Urban professionals aged 28-43 demonstrate established repeat purchase patterns in premium skincare. This segment concentrates in Greater London and exhibits lower price elasticity for products with verified cruelty-free documentation.
- Generation Z:Digital-native buyers aged 18-27 treat ethical alignment as a baseline hygiene factor rather than premium signal. Social platforms serve as primary research channels before transaction completion through brand-direct websites.
- Professionals:Time-constrained buyers in Manchester and Leeds prioritize convenience and multi-functionality over extensive product exploration.
- Eco-Conscious Shoppers:Values-driven purchasers across age cohorts demand comprehensive transparency including packaging sustainability and carbon footprint disclosure.
Loyalty concentration sits with Millennials; growth velocity sits with Generation Z.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Post-Brexit regulatory divergence is reshaping formulation standards across UK sub-regions while the retained EU Cosmetics Regulation maintains baseline safety requirements enforced by the Office for Product Safety and Standards.
London and the South East
Premium retail density and digital-native consumer bases concentrate demand for Leaping Bunny-certified products in Greater London. The Competition and Markets Authority intensifies greenwashing enforcement in this region, pressuring brands to maintain verified supply chain documentation. Shoreditch and Brighton host indie beauty labels adopting biotechnology-derived actives faster than established players.
Midlands
Manufacturing heritage in Birmingham and Nottingham supports contract formulation facilities serving national distribution networks. The Office for Product Safety and Standards operates regional inspection capacity from its Birmingham base, accelerating compliance timelines for local producers. Leicester's textile chemistry expertise transfers into synthetic peptide development for skincare applications.
North England
Manchester and Leeds present whitespace for premium vegan cosmetics where specialty retail density lags London benchmarks. Young professional women in these cities demonstrate price elasticity similar to southern counterparts but with fewer dedicated discovery environments. The region's university research clusters in Sheffield and Manchester feed formulation talent into regional brands.
Scotland
Edinburgh and Glasgow sustain independent beauty retailers prioritizing organic and cruelty-free positioning. Scotland's devolved environmental regulations occasionally anticipate UK-wide standards, creating early-mover advantages for compliant brands. The country's botanical extraction heritage supports natural ingredient supply chains for premium fragrance and skincare.
Wales
Cardiff and Swansea exhibit growing demand for vegan cosmetics among university-educated demographics. Welsh Government sustainable procurement guidelines favor cruelty-free suppliers in public sector contracts, creating institutional demand channels. The region's pharmaceutical manufacturing base in South Wales provides adjacent formulation expertise.
UK Vegan Cosmetics Market Competitive Landscape
Listed leaders compete with private specialists across certification tiers and channel access. The UK vegan cosmetics market exhibits moderate consolidation with multinational conglomerates controlling mass-market shelf space while indie labels capture premium positioning through specialty retail. Three archetypes dominate: scale-driven multinationals with R&D infrastructure, mid-tier specialists leveraging certification speed, and indie innovators adopting biotechnology inputs early. Competitive intensity manifests through portfolio diversification into adjacent wellness categories and direct-to-consumer channel expansion bypassing traditional retail markups.
Within the multinational tier, L'Oreal SA and Unilever PLC occupy positions defined by broad distribution networks and regulatory navigation capabilities. Among specialist independents, MuLondon exemplifies the mid-tier archetype built on verified cruelty-free positioning and regional retail penetration. e.l.f. Beauty, Inc. represents the value-tier vector where price aggression meets maintained formulation integrity, compressing margins for comparable-positioned competitors.
| Leading Market Players |
|---|
| Coty Inc. |
| Pacifica Beauty, LLC |
| L'Oreal SA |
| MuLondon |
| Urban Decay |
| Unilever PLC |
| Estee Lauder Companies |
| Beauty Without Cruelty |
| e.l.f. Beauty, Inc. |
| Others |
Pricing and Supply Chain Analysis
Batch-scale fermentation capacity for synthetic peptides anchors cost structures across premium and mass-market tiers, compressing price floors for plant-based collagen alternatives while elevating entry barriers for brands lacking captive biotech partnerships or long-term offtake agreements with German and French mineral pigment suppliers.
Pricing Analysis
Certification level creates the primary spread between mass-market accessible and premium-positioned SKUs. Leaping Bunny's 12-18 month audit timeline stratifies pricing across cruelty-free verified, organic-certified, and uncertified natural claims. Pricing pressure stems from e.l.f. Beauty's price aggression in color cosmetics, forcing mid-tier brands toward subscription models to preserve margin. Generation Z buyers exhibit highest price sensitivity, while Millennials in Greater London absorb premiums for verified supply chain documentation.
Supply Chain Analysis
Port congestion at Rotterdam and Calais elevates inbound logistics costs for UK formulators sourcing mineral pigments from Germany and France. Synthetic peptide production concentrates in Switzerland and the Netherlands, while botanical extraction capabilities cluster in Scotland and Provence. Single-source vulnerability runs through German pigment suppliers exposed to Brexit customs friction. Distribution runs through specialty retailers in Greater London and direct-to-consumer platforms bypassing traditional wholesale markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK vegan cosmetics market operates as a defensive-moat business where Leaping Bunny certification entrenchment and batch-level traceability requirements create switching costs that protect incumbent positions against price-aggressive challengers.
For Market Incumbents: Shield market position by deepening backward integration into synthetic peptide production through partnerships with Swiss biotech specialists, and accelerate Leaping Bunny certification for portfolio extensions before the Office for Product Safety and Standards intensifies post-Brexit enforcement timelines. The threat of regulatory divergence between UK and EU chemical safety standards demands proactive compliance investment to avoid portfolio fragmentation. For New Entrants and Emerging Players: Lead with direct-to-consumer subscription models targeting young professional women in Manchester and Leeds, where specialty retail whitespace meets price elasticity comparable to southern markets. Precision fermentation-derived actives provide the most penetrable innovation angle, collapsing the historical gap between niche positioning and industrial-grade supply security without requiring legacy R&D infrastructure. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among indie beauty labels with established Leaping Bunny certification and captive subscription bases in Greater London. Long-term viability over the next decade hinges on regulatory navigation capabilities rather than scale alone. Acquisition targets should demonstrate batch-level traceability systems and biotech input partnerships. The signal to watch is divergence timing between UK and EU chemical safety standards, which would favor UK-only formulation specialists with faster approval pipelines.| Strategic Initiative | Industry Significance |
|---|---|
| Leaping Bunny Certification Acceleration | Compresses go-to-market timelines ahead of Office for Product Safety and Standards enforcement intensification. |
| Precision Fermentation Partnership | Secures lab-grown elastin supply at scale points previously reserved for mass-market petrochemical alternatives. |
| Direct-to-Consumer Subscription Launch | Bypasses 40-50% specialty retail markups while capturing young professional women in underpenetrated Northern England cities. |
| Backward Integration into Biotech Inputs | Captures margin compression from synthetic peptide suppliers through captive production or exclusive offtake structures. |
| Regulatory Divergence Arbitrage Positioning | Exploits emerging gaps between UK and EU chemical safety standards for faster formulation approval timelines. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of regulatory filings, trade customs data, and retail audit databases through structured interviews with formulation chemists, specialty retail buyers, brand managers at indie and multinational cosmetics companies, and regulatory affairs specialists navigating retained EU Cosmetics Regulation compliance. Secondary validation drew from Office for Product Safety and Standards enforcement notices, Competition and Markets Authority greenwashing case records, Leaping Bunny certification registries, and Nielsen retail tracking data. Bottom-up demand modeling triangulated against top-down market sizing across certification tiers and regional penetration rates.
Segmentation dimensions modeled include product type, formulation certification level, distribution channel, and consumer demographic archetype across the projection horizon. CAGRs were derived from growth rate convergence analysis applied to historical adoption curves and projected regulatory enforcement intensification. Industry-specific forecast inputs incorporated Leaping Bunny certification pipeline data and precision fermentation capacity expansion announcements from Swiss and Dutch biotech suppliers.
Forecasts assume regulatory continuity in retained EU Cosmetics Regulation frameworks and Office for Product Safety and Standards enforcement protocols; material policy shifts toward divergent UK chemical safety standards would require re-modeling of formulation approval timelines and portfolio fragmentation risks. Practitioners should keep alternative scenarios live as post-Brexit regulatory alignment negotiations evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Eyelash Curler Market
Beauty & Personal Care
Global Massage Oil Market
Beauty & Personal Care
Cosmetics and Toiletries Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
North America Setting Spray Market
Beauty & Personal Care
Cosmetics Foundation Market
Beauty & Personal Care
United States Beauty and Personal Care Products Market
Beauty & Personal Care
France Dermocosmetics Market
Beauty & Personal Care
Makeup Brushes Market
Beauty & Personal Care
Private Label Cosmetics Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
Men's Skincare Products Market
Beauty & Personal Care
Beauty Products Market
Beauty & Personal Care
US Color Cosmetics Market
Beauty & Personal Care
US Personal Care Contract Manufacturing Market
Beauty & Personal Care
Deodorant and Antiperspirants Market