
 UK Sustainable Personal Care Market | 2026-2036
UK Sustainable Personal Care Market Size, Share, and Industry Trends Forecast 2026-2036
UK Sustainable Personal Care Market Insights
The gap between premium certified-organic formulations and mass-market green-positioned lines is expanding. L'Oréal leverages its scale to secure bulk bio-based ingredient contracts that smaller rivals cannot match. Unilever sustains broad distribution across Tesco, Boots, and direct channels while reformulating legacy brands to meet stricter biodegradability standards. Coty specializes in prestige vegan makeup, occupying a narrower but higher-margin niche than conglomerate competitors.
UK sustainable personal care encompasses cosmetics and hygiene products formulated with renewable, minimally processed ingredients, packaged in recyclable or refillable materials, and manufactured through cold-process or waterless methods to reduce energy intensity. These products serve consumers seeking reduced dermal chemical exposure and lower lifecycle environmental impact. Natural skincare leads product type value generation, while biodegradable deodorants represent the fastest-expanding segment as aluminum-free and compostable formats gain shelf space. Online retail dominates distribution channel growth, though health and wellness shops capture the highest customer lifetime value through consultative selling and loyalty programs.
The UK Environment Agency enforces packaging waste regulations that mandate minimum recycled content thresholds, while the Competition and Markets Authority scrutinizes green claims under its Green Claims Code to prevent consumer deception. DEFRA's extended producer responsibility framework shifts end-of-life costs onto brands, accelerating investment in domestic recycling infrastructure and refill station networks. Stakeholders must monitor whether forthcoming chemical hazard classifications under UK REACH divergence from EU standards will force reformulation of preservatives and fragrance compounds already certified elsewhere.
Market Dynamics
The UK Plastic Packaging Tax and DEFRA's extended producer responsibility framework are compressing margins for imported formulations while accelerating domestic refill infrastructure investment across England and Scotland.
Growth Catalysts
- Plastic Packaging Tax thresholds:The UK's GBP 200 per tonne levy on packaging below 30% recycled content pushes brands toward bio-based polymers and aluminum alternatives. Reformulation investments now prioritize domestically sourced post-consumer resins.
- Generation Z urban concentration:London and Manchester post-secondary clusters generate concentrated demand for waterless and solid-format personal care. Student housing proximity stores report accelerated turnover of shampoo bars and refillable deodorants.
- Cold-process manufacturing:Energy-intensive thermal processing is giving way to ambient-temperature emulsification. Scottish contract manufacturers are retrofitting facilities to serve indie brands seeking carbon footprint reductions for export to EU markets.
Market Restraints
- Bio-based surfactant supply concentration:UK formulators depend on coconut-derived inputs from Southeast Asian processors. Shipping volatility and currency exposure compress gross margins on natural cleansing products.
- Preservative approval divergence:UK REACH divergence from EU chemical hazard classifications creates regulatory friction. Brands face dual certification costs for phenoxyethanol alternatives already approved under ECHA guidelines.
- Aluminum substrate cost inflation:Refillable tin and aluminum packaging faces input price pressure from energy-intensive smelting. Premium deodorant and skincare brands absorb margin compression or risk volume loss to plastic alternatives.
Strategic Opportunities
- Scottish Highlands ingredient sourcing:Underpenetrated seaweed and botanical extraction operations offer traceable supply chains. Local distilleries provide ethanol for natural perfumery with provenance marketing potential.
- Subscription channel infrastructure:Direct-to-consumer refill models bypass shelf-space constraints at Boots and Superdrug. Automated replenishment algorithms lock in predictable lifetime value versus transactional retail.
- NHS procurement pilot programs:Sustainable hygiene product mandates in hospital and care home supply contracts create institutional demand. Biodegradable hand washes and aluminum-free antiperspirants qualify for green procurement frameworks.
Industry Challenges
- Green chemistry talent scarcity:Formulation chemists with natural preservation and emulsion stability expertise command premium compensation. Universities in Leeds and Nottingham are expanding cosmetic science programs but graduate supply lags demand.
- Compostability certification timelines:TÜV and OK Compost HOME approvals require 12-18 month validation cycles. Product launches miss seasonal windows when biodegradability claims await laboratory verification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Sustainable Personal Care Market |
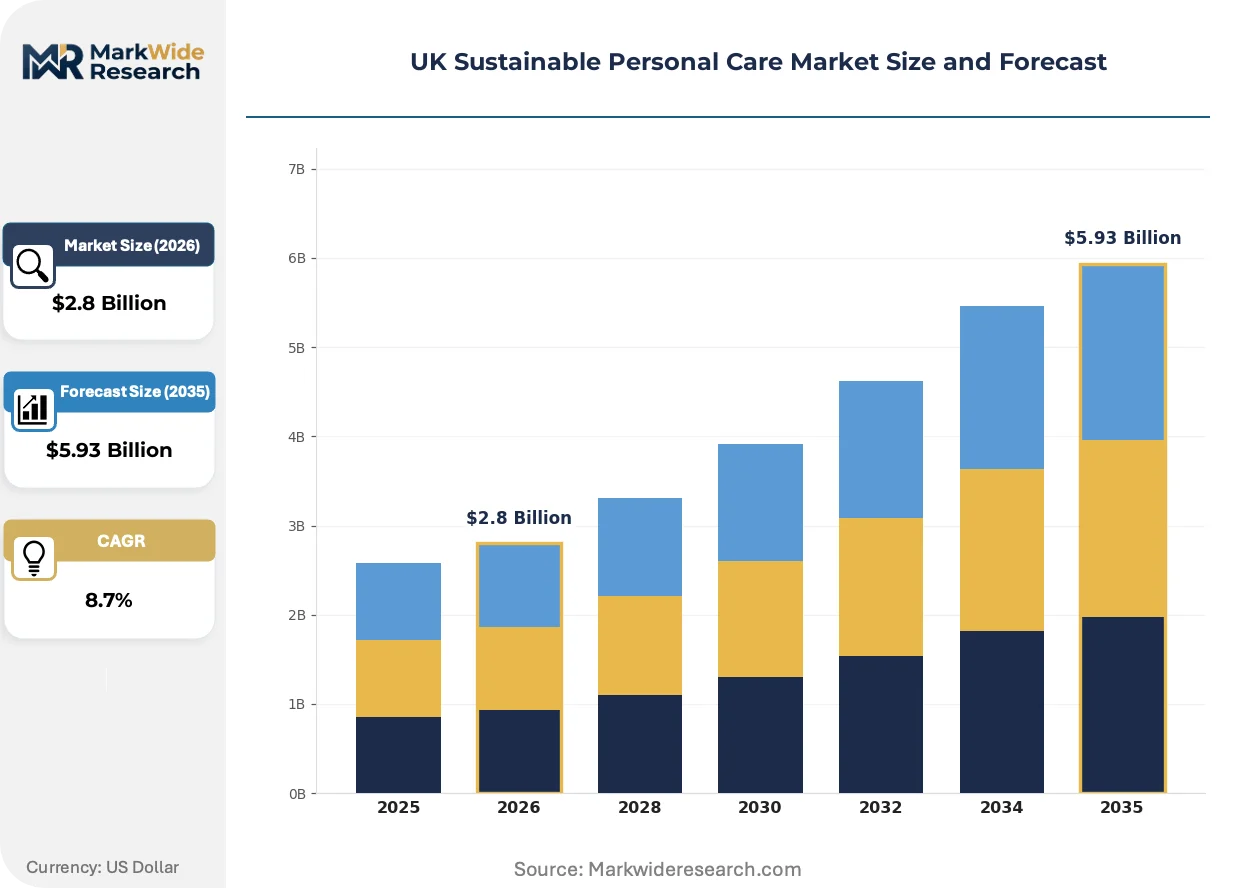
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.93 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Skincare, Organic Haircare, Biodegradable Deodorants, Vegan Makeup, Eco-friendly Body Wash Application: Daily Hygiene, Anti-aging Care, Hair Nourishment, Sensitive Skin Treatment, UV Protection Consumer Demographic: Millennials, Generation Z, Eco-conscious Adults, Wellness Enthusiasts, Ethical Shoppers Distribution Channel: Online Retail, Specialty Stores, Department Stores, Health & Wellness Shops, Subscription Boxes |
| Companies Covered | Estée Lauder Companies, Kao Corporation, L'Oréal, Coty, The Colgate-Palmolive Company, Unilever, Johnson & Johnson, L'Occitane, The Procter & Gamble Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Sustainable Personal Care Market Trends and Innovations
Waterless formulation technology and solid-format delivery systems are compressing packaging intensity while regulatory scrutiny of green claims forces substantiation investments.
Bio-fermented actives are integrating into premium skincare lines as alternatives to petrochemical-derived retinoids and peptides. Indie brands in Brighton and Bristol adopt small-batch biotechnology partnerships. The technology is integrating supply chains vertically, with brands acquiring captive fermentation capacity to secure ingredient provenance and margin control.
DEFRA's Green Claims Code enforcement is intensifying substantiation requirements for carbon-neutral and plastic-free marketing. The Competition and Markets Authority has issued enforcement notices against vague biodegradability assertions. Natural deodorant and oral care segments face highest compliance costs as they rebalance packaging claims against laboratory test data.
Refill station networks are displacing conventional retail for core hygiene categories. Loop and independent zero-waste shops in London, Edinburgh, and Bristol capture recurring purchase patterns through deposit-return packaging systems. Urban consumers in the South East show highest adoption rates for consolidated shopping trips combining grocery and personal care refills.
UK Sustainable Personal Care Market Segmentation
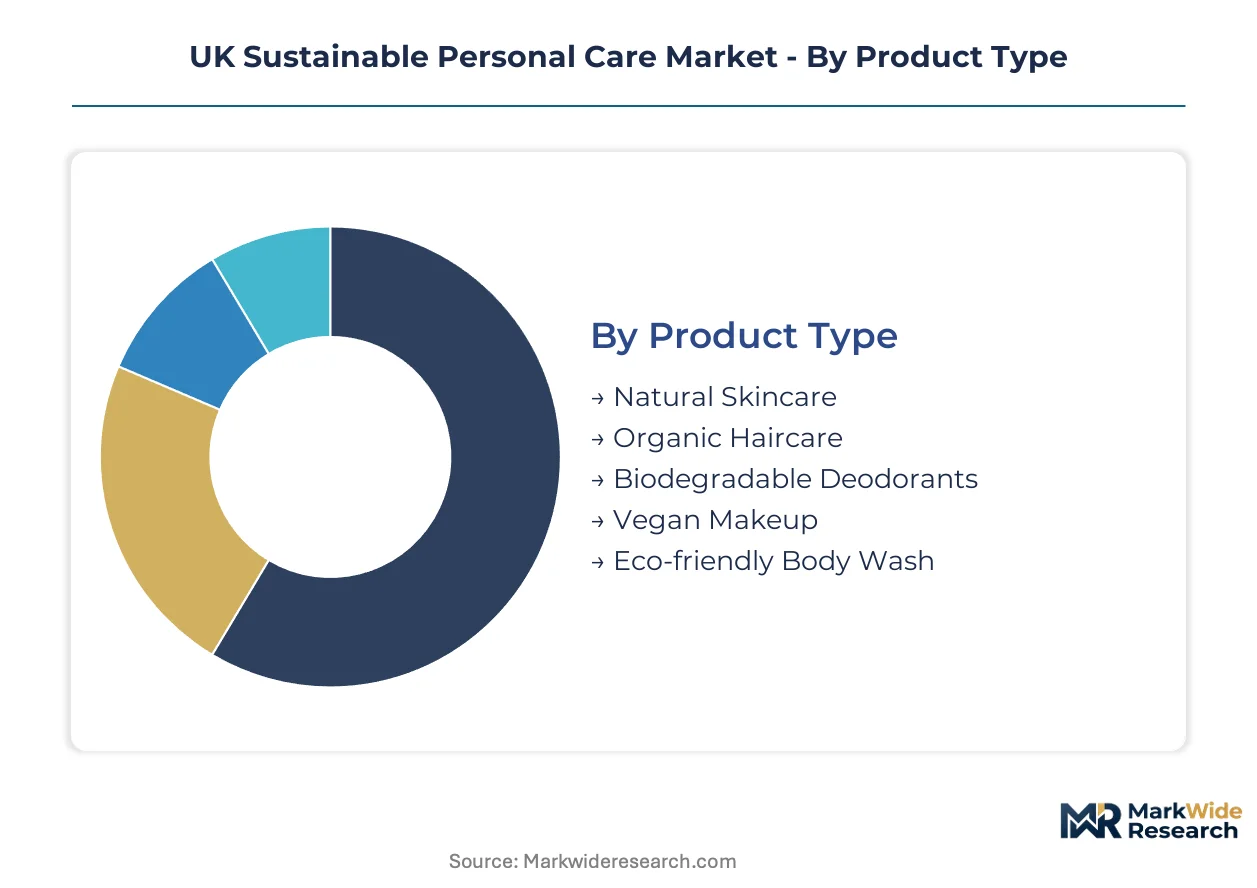
Segmentation in the UK sustainable personal care market reveals how refill infrastructure, generational purchasing power, and channel specialization concentrate value capture. Understanding these divides exposes where formulation investments and distribution partnerships generate disproportionate returns.
Product Type:
Replacement cycles vary dramatically across personal care categories, with daily-use items demanding faster repurchase than treatment-oriented formats.
- Natural Skincare:Formulations rely on cold-pressed botanical oils and bio-fermented actives rather than petrochemical emollients. London and South East urban consumers drive premium pricing for certified-organic serums and waterless balms, with refillable glass packaging now standard at specialty retailers.
- Biodegradable Deodorants:Aluminum-free and compostable stick formats utilize tapioca starch and magnesium hydroxide for moisture absorption. Manchester and Bristol post-secondary clusters show accelerated adoption of solid-format refills, though aluminum substrate cost inflation compresses margins on tin-container alternatives.
- Organic Haircare:Sulphate-free cleansers and silicone-free conditioners target scalp microbiome balance.
- Vegan Makeup:Synthetic mica and plant-derived pigments replace carmine and lanolin in colour cosmetics.
- Eco-friendly Body Wash:Concentrated gel and solid bar formats reduce water content and shipping weight.
Natural Skincare sits at the top of the volume ranking, with Biodegradable Deodorants climbing the fastest.
Application:
Cost tier stratification separates mass-market hygiene from premium therapeutic positioning, with price multiples of 4-8x between entry and clinical-grade offerings.
- Daily Hygiene:Basic cleansing and moisturising routines utilise standardised surfactant bases with minimal active concentrations. Boots and Superdrug shelf placement prioritises price accessibility over certification depth, though refill pouches now penetrate this mass channel.
- Anti-aging Care:Bio-fermented retinol alternatives and peptide complexes command formulation premiums. Edinburgh and Glasgow consumers over 35 demonstrate willingness to pay for provenance-marked Scottish seaweed extracts in premium serums.
- Hair Nourishment:Scalp treatments and bond-repair masks target chemical-damage recovery.
- Sensitive Skin Treatment:Minimal-ingredient formulations exclude fragrance and common allergens.
- UV Protection:Mineral-only sunscreens using non-nano zinc oxide address coral-reef safety concerns.
Daily Hygiene generates the highest absolute volume, while Anti-aging Care shows the steepest expansion trajectory.
Consumer Demographic:
Customer type fragmentation maps directly onto channel preference, with subscription loyalty strongest among digitally native cohorts.
- Generation Z:University-adjacent consumers in Leeds, Sheffield and Brighton prioritise TikTok-discovered indie brands with transparent supply chains. Solid-format adoption rates exceed older demographics by significant margins, with shampoo bars and toothpaste tablets now dorm-room staples.
- Millennials:Parent-age purchasers in London commuter belts balance efficacy claims with child-safe ingredient profiles. Health and wellness shop consultations drive discovery, with lifetime value concentrated in loyalty-program members.
- Eco-conscious Adults:Established professionals with disposable income for premium certification.
- Wellness Enthusiasts:Cross-category purchasers integrating personal care with nutrition and fitness regimes.
- Ethical Shoppers:Purchase decisions weighted toward fair-trade and cruelty-free credentials.
Millennials constitute the largest spending base, with Generation Z gaining share fastest through digital-native discovery patterns.
Distribution Channel:
Geographic concentration of refill infrastructure privileges urban England and Scotland, with rural penetration lagging 3-4 years behind metro adoption curves.
- Online Retail:Direct-to-consumer platforms leverage automated replenishment algorithms to lock in predictable repurchase cycles. Brighton and Bristol indie brands utilise subscription bundling to offset customer acquisition costs, with return rates lowest among prepaid annual plans.
- Health & Wellness Shops:Consultative selling environments in London, Edinburgh and Manchester generate highest customer lifetime value. Staff training on ingredient provenance justifies 15-25% price premiums over mass retail for identical formulations.
- Specialty Stores:Curated assortments emphasise local and B Corp-certified brands.
- Department Stores:Prestige counters target gift purchasers and occasion-based buying.
- Subscription Boxes:Discovery-oriented curation exposes consumers to unfamiliar formats.
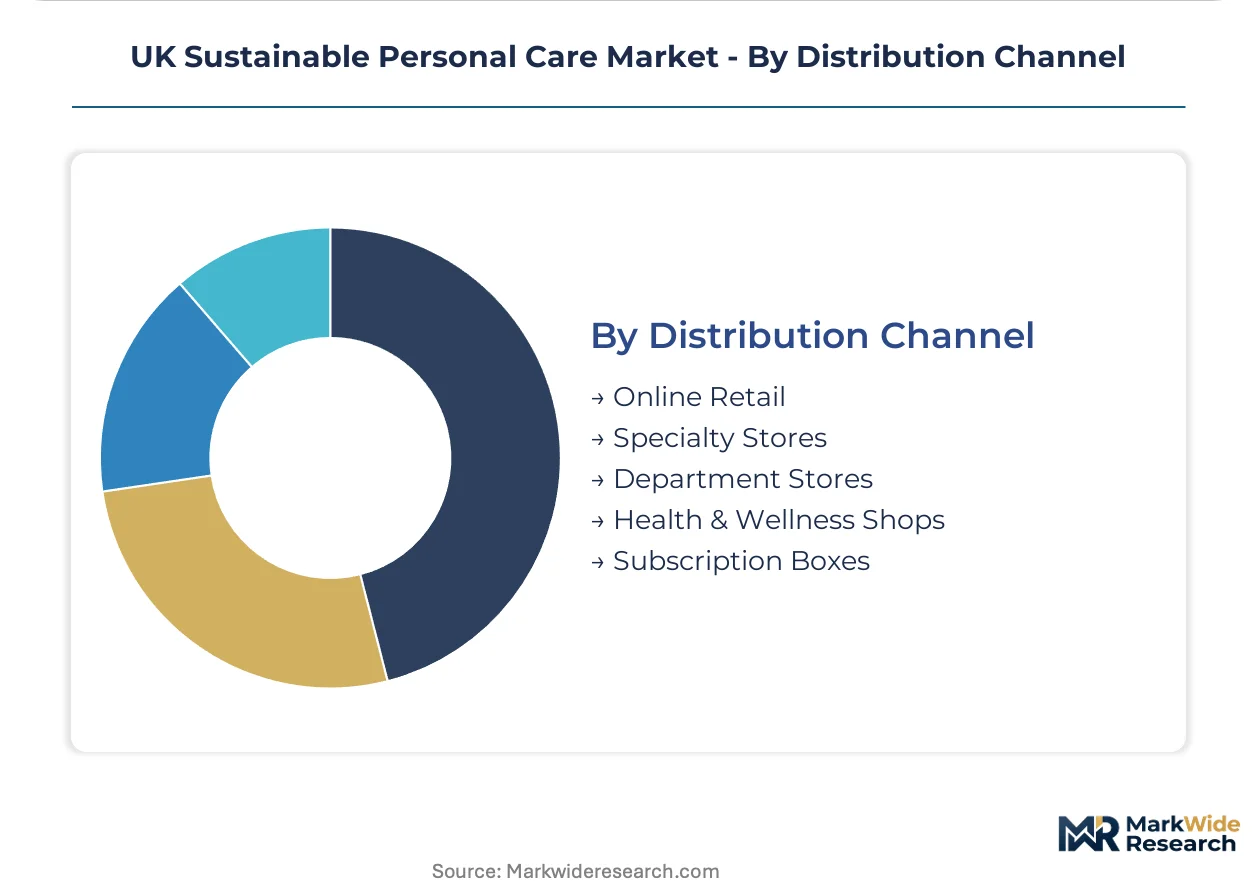
Online Retail dominates absolute growth, with Health & Wellness Shops expanding most quickly through consultative service differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation chemists and cosmetic science graduates from Leeds and Nottingham universities anchor England's product development pipeline, while Scottish Highlands botanical extraction operations supply traceable seaweed and plant-derived inputs to domestic brands.
London and the South East
Urban millennials and Generation Z consumers concentrate demand for certified-organic serums and waterless balms. The UK Environment Agency enforces packaging waste regulations mandating minimum recycled content thresholds. Specialty retailers in Brighton and Bristol operate refill station networks that capture recurring purchase patterns through deposit-return systems.
Scotland
Edinburgh and Glasgow consumers over 35 demonstrate willingness to pay for provenance-marked seaweed extracts in premium anti-aging serums. DEFRA's extended producer responsibility framework shifts end-of-life costs onto brands operating across the Scottish market. Contract manufacturers in Glasgow are retrofitting facilities for cold-process emulsification to serve indie brands exporting to EU markets.
Manchester and the North West
Post-secondary student clusters generate concentrated demand for solid-format deodorants and shampoo bars. The UK Plastic Packaging Tax applies its GBP 200 per tonne levy on packaging below 30% recycled content to all formulations sold through regional retail channels. University-adjacent stores report accelerated turnover of refillable personal care products in student housing corridors.
Midlands
Nottingham and Leicester cosmetic science programs expand graduate supply to address green chemistry talent scarcity. The Competition and Markets Authority scrutinizes green claims under its Green Claims Code to prevent consumer deception. Manufacturing facilities in the region prioritize domestically sourced post-consumer resins for bio-based polymer packaging.
Wales
Eco-conscious adult consumers with disposable income for premium certification drive demand for B Corp-accredited brands. UK REACH divergence from EU chemical hazard classifications creates regulatory friction for preservative formulations. Local distillation operations provide ethanol for natural perfumery with provenance marketing potential.
UK Sustainable Personal Care Market Competitive Landscape
Top-tier vendors anchor mass-market distribution through supermarket and pharmacy chains, while indie specialists and regional formulators occupy premium niche positions. The market structure reflects consolidation at the conglomerate level alongside fragmentation among sustainability-focused entrants. Three archetypes dominate: multinational CPG conglomerates with reformulated legacy portfolios, prestige beauty houses emphasizing vegan and organic credentials, and direct-to-consumer indie brands leveraging subscription and refill models. Competitive moves concentrate on securing bulk bio-based ingredient contracts and building captive refill infrastructure.
Within the multinational tier, L'Oréal and Unilever exemplify scale-driven positioning through broad retail penetration and reformulation investments. Coty occupies a narrower prestige niche focused on vegan makeup lines with higher-margin positioning. Among conglomerate players, The Procter & Gamble Company and Johnson & Johnson represent established hygiene and personal care portfolios adapting to stricter biodegradability standards.
| Leading Market Players |
|---|
| Estée Lauder Companies |
| Kao Corporation |
| L'Oréal |
| Coty |
| The Colgate-Palmolive Company |
| Unilever |
| Johnson & Johnson |
| L'Occitane |
| The Procter & Gamble Company |
| Others |
Pricing and Supply Chain Analysis
Cold-process manufacturing retrofits across Scottish contract facilities simultaneously compress energy costs and concentrate formulation expertise in domestic hubs. This production-method transition reshapes cost economics by eliminating thermal processing while tightening supply concentration among England and Scotland-based manufacturers serving both UK and EU export markets.
Pricing Analysis
Bundled subscription services versus unbundled transactional retail purchases split pricing architectures across the UK sustainable personal care market. Three-tier pricing structure across premium certified-organic, standard natural-positioned, and economy mass-market tiers reflects certification depth and provenance marketing intensity. Pricing pressure stems from aluminum substrate cost inflation in refillable packaging formats. Generation Z consumers in university clusters exhibit highest price sensitivity, while established professionals in London commuter belts accept 15-25% premiums for consultative retail experiences.
Supply Chain Analysis
Single-source vulnerability sits with Southeast Asian coconut-derived surfactant processors that UK formulators draw from for natural cleansing bases. Bio-based polymer feedstocks and aluminum packaging substrates anchor supply concentration in Indonesia, the Philippines, and domestic UK post-consumer resin operations. Regulatory friction from UK REACH divergence compounds sourcing complexity for preservative alternatives. Distribution runs through Boots and Superdrug mass retail alongside direct-to-consumer subscription platforms with automated replenishment algorithms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK sustainable personal care market reads as a late-cycle quality story where Millennial and Generation Z demand shifts toward certified-organic specifications and refillable formats reward sustained formulation investment over price competition.
For Market Incumbents: Hedge margin compression from aluminum substrate inflation by securing captive bio-based polymer contracts and expanding cold-process manufacturing capacity in Scottish contract facilities. DEFRA's extended producer responsibility framework threatens legacy packaging portfolios, making domestic refill infrastructure investment the priority defensive lever against indie subscription competitors. For New Entrants and Emerging Players: Begin with white-space capture in NHS procurement pilot programs for sustainable hygiene products, where institutional demand for biodegradable hand washes and aluminum-free antiseptics remains underpenetrated. Scottish Highlands seaweed extraction partnerships offer traceable supply chain differentiation with provenance marketing potential unavailable to mass-market incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among regional formulators with captive Scottish botanical sourcing and established refill station networks in Brighton, Bristol, and Edinburgh. Long-term viability across the analysis window hinges on UK REACH compliance positioning and cold-process technical capabilities. Watch for inflection signals in compostability certification timelines as TÜV and OK Compost HOME approval backlogs create launch-window arbitrage for validated brands.| Strategic Initiative | Industry Significance |
|---|---|
| Refill Infrastructure Expansion | Deposit-return packaging systems in London and Edinburgh capture recurring purchase patterns with higher lifetime value than transactional retail. |
| Scottish Highlands Sourcing Partnerships | Seaweed and botanical extraction operations provide traceable supply chains with provenance marketing differentiation against mass-market competitors. |
| Cold-Process Manufacturing Retrofit | Ambient-temperature emulsification reduces energy intensity while qualifying products for EU export markets seeking carbon footprint reductions. |
| Subscription Channel Buildout | Automated replenishment algorithms lock in predictable repurchase cycles and offset customer acquisition costs for direct-to-consumer brands. |
| NHS Procurement Qualification | Green procurement framework compliance opens institutional demand channels for biodegradable hygiene products in hospital and care home supply contracts. |
Research Methodology
Multiple input streams — formulation chemist interviews, retailer category buyer consultations, customs and trade data analysis, and regulatory filing review — were reconciled to construct market estimates. Primary fieldwork captured perspectives from brand managers at multinational CPG conglomerates, indie founder-operators in Brighton and Bristol, Boots and Superdrug procurement leads, and Scottish contract manufacturing facility directors. Secondary validation drew from UK Environment Agency packaging waste compliance records, DEFRA extended producer responsibility guidance documents, Competition and Markets Authority Green Claims Code enforcement notices, and Nielsen retail audit data. Bottom-up product-level volume builds were cross-checked against top-down category expenditure estimates.
Data-stream reconciliation across the projection horizon employed segmented demand modeling by product type, consumer demographic, application tier, and distribution channel. CAGRs were derived from trend extrapolation of refill infrastructure penetration rates, generational cohort spending evolution, and regulatory cost pass-through assumptions. Industry-specific forecast inputs incorporated UK Plastic Packaging Tax threshold compliance timelines and cold-process manufacturing capacity expansion schedules across Scottish facilities.
Several conditions sit outside the modeled scope, including unforeseen UK REACH divergence severity, abrupt aluminum commodity price shocks, and subscription channel customer acquisition cost inflation beyond historical patterns. Forecasts reflect documented assumptions about regulatory enforcement intensity and generational purchasing power transfer velocity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Deodorant Roll-Ons Market
Beauty & Personal Care
Coffee Beauty Products Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
In-Wash Scent Booster Market
Beauty & Personal Care
Facial Steamer Market
Beauty & Personal Care
Switzerland Haircare Market
Beauty & Personal Care
India Herbal Shampoo Market
Beauty & Personal Care
Mass Beauty & Personal Care Products Market
Beauty & Personal Care
Facial Oil Market
Beauty & Personal Care
Nail Care Market
Beauty & Personal Care
Global Personal Care Market
Beauty & Personal Care
Lip Care Market
Beauty & Personal Care
Nail Lamps Market
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
Beauty Oils Market
Beauty & Personal Care
Global Cosmetics Market