
 Europe Cosmetics Market | 2026-2036
Europe Cosmetics Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Cosmetics Market Analysis
Buyer concentration among digital-native consumers is realigning how cosmetics brands allocate marketing spend and inventory. L'Oréal S.A. leverages its multi-brand architecture to capture value across prestige and masstige tiers simultaneously. Unilever PLC anchors its European position through sustainability-certified personal care lines with transparent supply chains. Beiersdorf AG differentiates via dermatological credibility and pharmacy channel dominance in German-speaking markets.
Europe cosmetics encompass formulated preparations applied to the human body for cleansing, beautifying, or altering appearance, typically containing emulsifiers, active ingredients, and preservatives at controlled pH levels between 4.5 and 7.0. These products serve consumer grooming needs and professional salon services across retail and institutional channels. Skincare leads value generation due to higher per-unit pricing and repeat purchase frequency in anti-aging and hydration subcategories. Online Retail captures the fastest expansion as direct-to-consumer platforms disintermediate traditional wholesale relationships. Premium and Organic price tiers concentrate margin pools where clean-label certification commands measurable price premiums over conventional formulations.
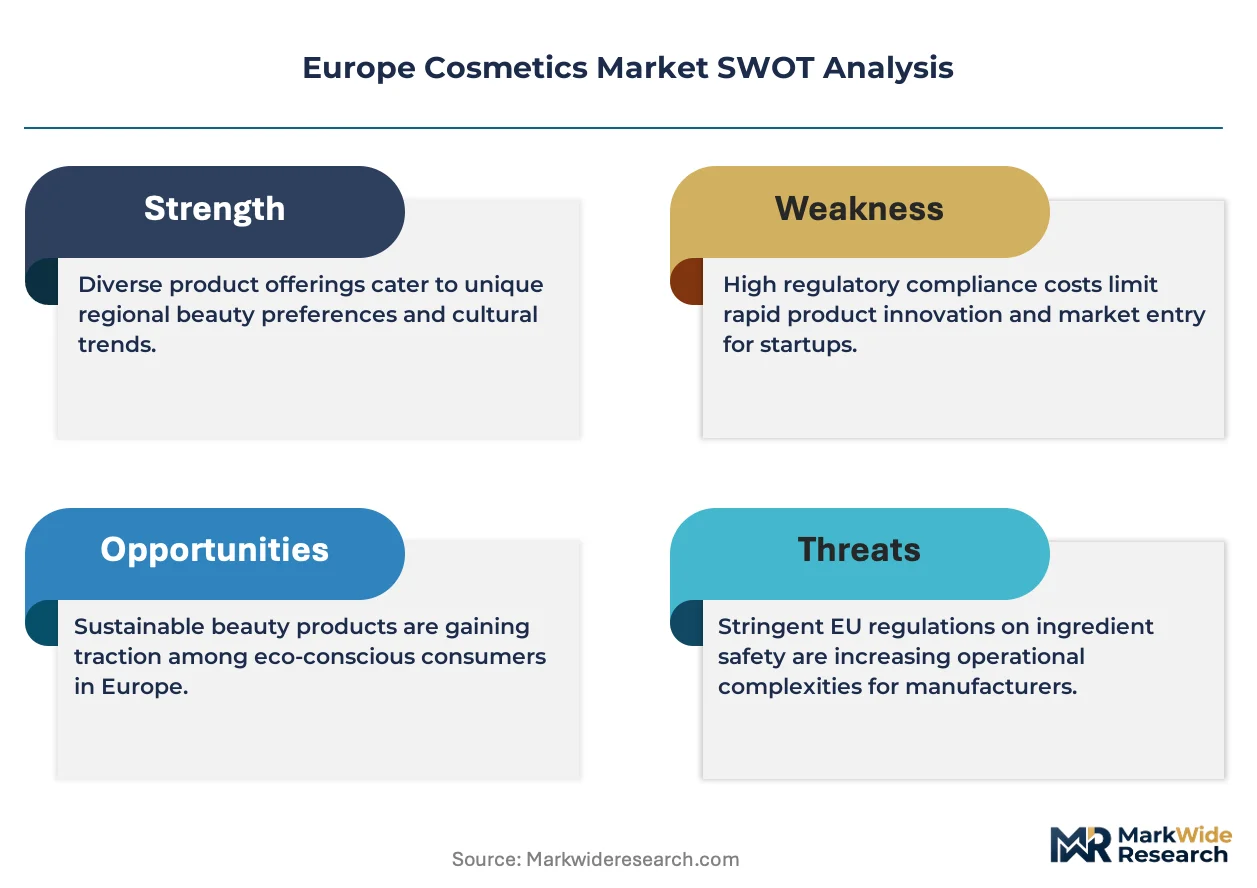
EMA cosmetic ingredient oversight, REACH chemical registration requirements, and the EU Green Deal sustainability framework collectively shape product formulation standards and market access conditions across member states. ECHA substance restrictions force reformulation cycles that favor suppliers with advanced R&D capabilities and regulatory compliance infrastructure. Stakeholders must monitor evolving CSRD disclosure mandates and their downstream impact on ingredient sourcing transparency claims.
Market Dynamics
REACH chemical registration requirements and the EU Green Deal sustainability framework are forcing accelerated reformulation cycles across European cosmetics supply chains, compressing product development timelines while elevating compliance infrastructure costs.
Growth Catalysts
- Clean-label certification systems:EU Green Deal carbon accounting mandates and CSRD disclosure requirements create measurable price premiums for transparent supply chains, pulling investment into certified organic ingredient sourcing.
- France:Heritage brand concentration in Paris and Lyon anchors premium positioning, with millennial and Gen Z consumer cohorts driving repeat purchase frequency in anti-aging skincare subcategories.
- Biotechnology-derived actives:Lab-grown collagen and fermented hyaluronic acid processes reduce agricultural land dependency while meeting ECHA substance safety thresholds for novel cosmetic ingredients.
Market Restraints
- Petrochemical feedstock volatility:Surfactant and emulsifier input costs fluctuate with crude oil derivatives, compressing margin pools for masstige tier producers lacking backward integration into specialty chemical production.
- Supplier concentration in Germany:Pharmaceutical-grade packaging and airless pump systems rely on a narrow base of Mittelstand manufacturers, creating single-source vulnerability for scale-up brands.
- Microplastic restriction timelines:ECHA's proposed glitter and microbead phase-outs force immediate reformulation of color cosmetics, straining R&D bandwidth ahead of enforcement deadlines.
Strategic Opportunities
- Poland and Romania:Underpenetrated pharmacy channel distribution in Eastern European markets offers first-mover positioning for dermatological credibility brands seeking expansion beyond saturated Western European retail.
- Refill station retail formats:Circular economy business models aligned with EU Green Deal waste reduction targets enable direct consumer relationships while bypassing traditional wholesale margin structures.
- AI-driven personalization:Convergence of skin diagnostic hardware and algorithmic formulation matching creates subscription revenue models for bespoke skincare regimens targeting specific phototype and microbiome profiles.
Industry Challenges
- Toxicology assessment capacity:ECHA's expanding substance restriction lists outpace available safety testing laboratory throughput in Europe, extending new product notification timelines.
- Legacy ERP integration:CSRD-compliant supply chain traceability requirements force mid-tier brands to replace fragmented ingredient sourcing databases with unified platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Cosmetics Market |
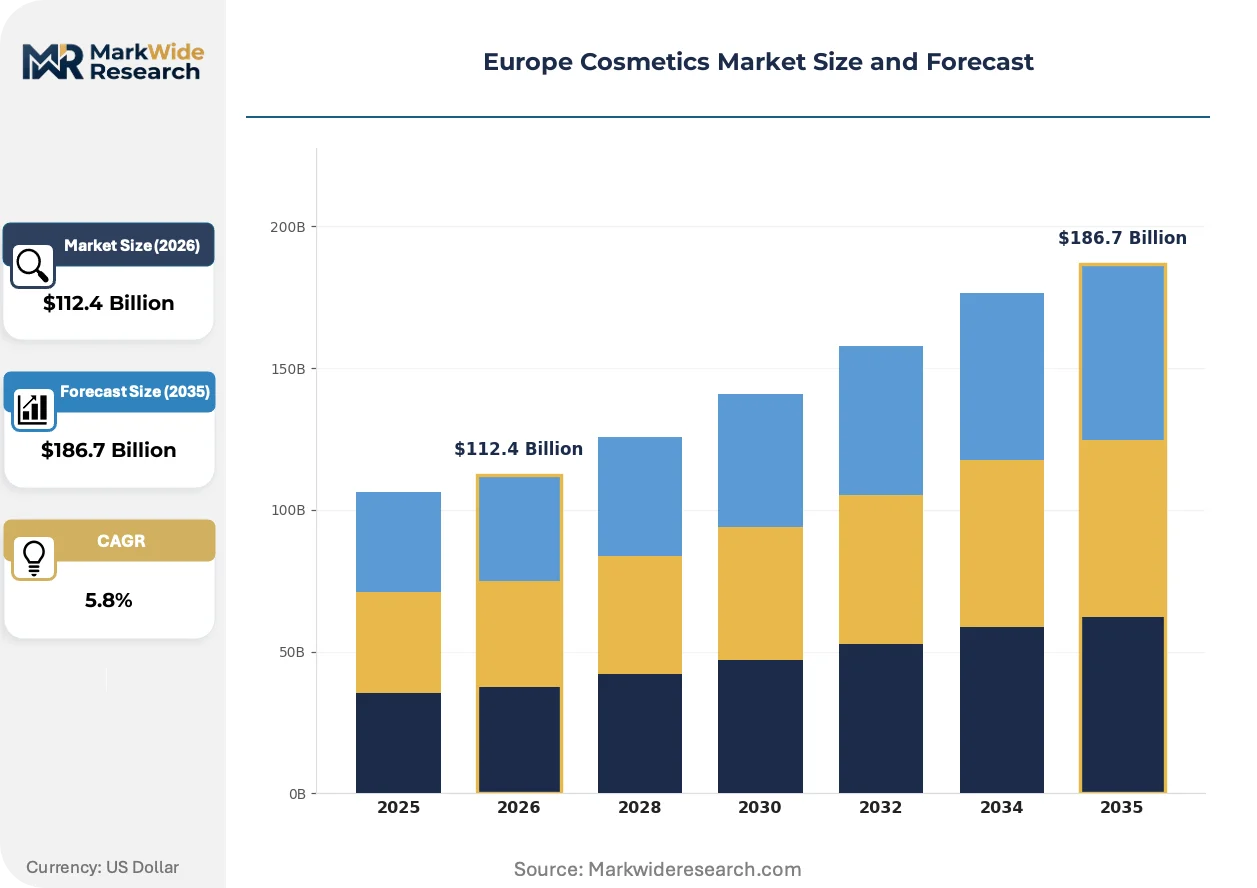
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $186.7 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Fragrance, Haircare Distribution Channel: Online Retail, Drugstores, Department Stores, Salons Customer Type: Individuals, Professionals, Retailers, Wholesalers Price Tier: Premium, Mid-range, Economy, Organic |
| Companies Covered | L'Oréal S.A., Unilever PLC, Procter & Gamble Co, Beiersdorf AG, The Estée Lauder Companies Inc., Coty Inc., Shiseido Co., Ltd., Kao Corporation, Johnson & Johnson Services, Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Cosmetics Market Emerging Trajectories
Biotechnology and artificial intelligence are converging to reshape how European cosmetics brands develop, manufacture, and distribute products, compressing innovation cycles while fragmenting traditional channel hierarchies.
Precision fermentation for cosmetic actives is absorbing capital allocation previously directed toward botanical extraction facilities. Biotechnology startups in the Netherlands and Denmark are scaling collagen and squalane production using engineered yeast strains. This shift is absorbing demand for conventional agricultural supply chains while reducing water and land use intensity per kilogram of active ingredient produced.
CSRD disclosure mandates now require granular Scope 3 emissions reporting across ingredient sourcing tiers. The European Commission's sustainability reporting standards force cosmetics brands to audit subcontractor environmental performance or risk greenwashing liability. Small and mid-sized suppliers in Italy and Spain face consolidation pressure as larger brands consolidate purchasing relationships to simplify compliance documentation.
Direct-to-consumer subscription models are displacing department store counter relationships for prestige skincare categories. German and French millennial buyers now initiate product discovery through algorithmic social feeds rather than in-person consultation. This behavioral pivot concentrates marketing spend into performance advertising channels while compressing customer acquisition cost tolerance for traditional wholesale-dependent brands.
Europe Cosmetics Market Segmentation
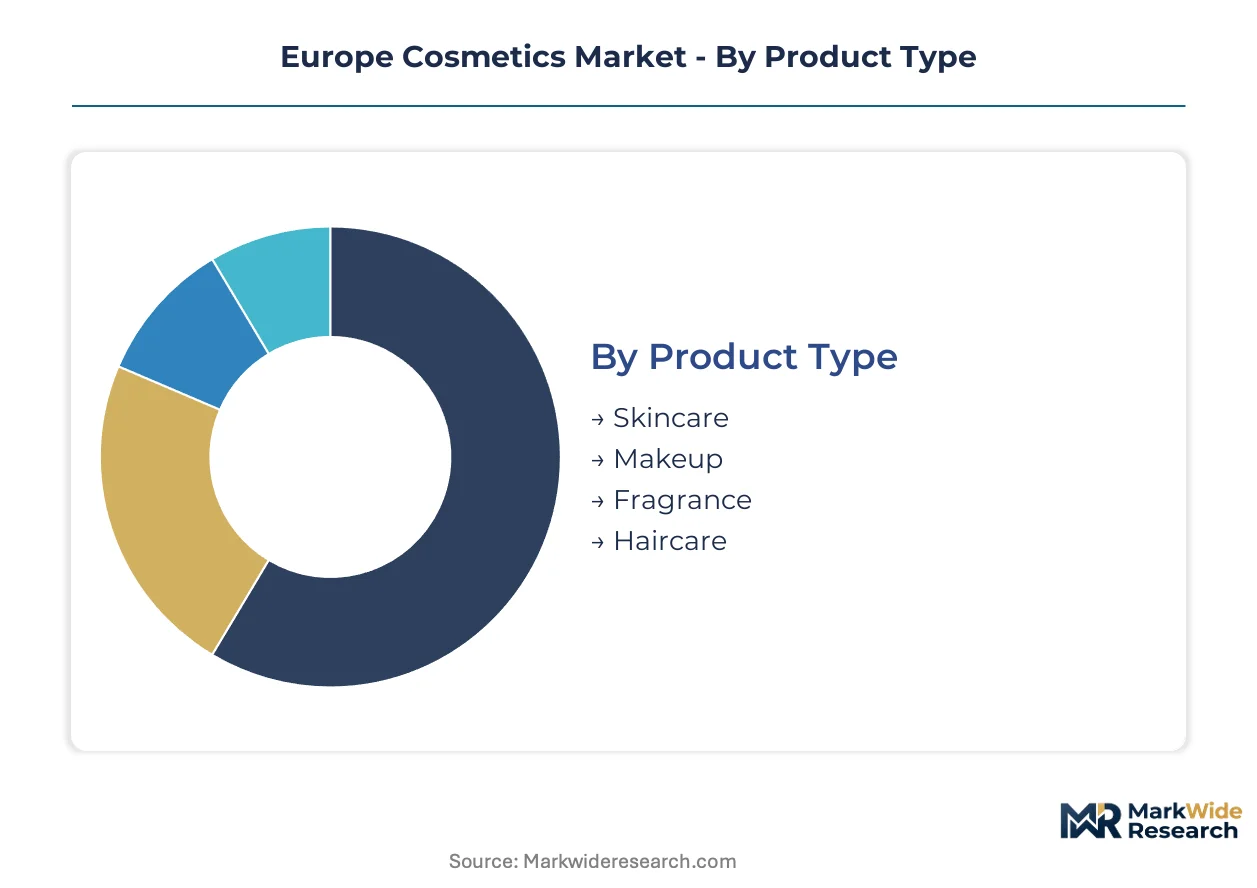
Segmentation in the Europe cosmetics market reveals how formulation complexity and channel access fragment purchasing behavior across consumer cohorts. Distinct margin pools align with certification tiers and professional versus personal use cases, forcing brands to architect multi-pronged portfolio strategies rather than single-position plays.
Product Type:
Standardization dominates mass-market formulations while customization concentrates in professional-grade and dermatological segments across this category.
- Skincare:Emulsions, serums, and creams formulated with active concentrations between 2% and 15% target cellular renewal and barrier function. Demand clusters in France and Germany where pharmacy-channel credibility commands repeat purchase loyalty among millennial buyers seeking anti-aging solutions.
- Makeup:Color cosmetics incorporating pigment dispersions and film-forming polymers serve aesthetic alteration needs. Italian heritage manufacturing anchors premium colorant supply, though ECHA microplastic restrictions are forcing reformulation of glitter and long-wear foundations ahead of enforcement timelines.
- Fragrance:Alcohol-based parfum and eau de toilette formulations rely on synthetic and botanical aromatic compounds. Grasse concentration in France sustains artisanal extraction capabilities for luxury positioning.
- Haircare:Surfactant-based cleansing and conditioning systems address scalp health and fiber integrity. German-speaking markets favor silicone-free positioning aligned with clean-label certification trends.
Leading the category by volume: Skincare. Growing fastest: Professional-grade skincare with clinical positioning.
Distribution Channel:
Margin capture varies sharply by channel control, with direct relationships enabling subscription economics unavailable to wholesale-dependent competitors.
- Online Retail:Direct-to-consumer platforms and algorithmic personalization engines disintermediate traditional wholesale markups. German and French millennial discovery patterns now originate in social feeds rather than physical retail, compressing customer acquisition cost tolerance for legacy department store brands.
- Drugstores:Pharmacy and parapharmacy networks in Germany, France, and Italy provide dermatological credibility endorsement. Beiersdorf and L'Oréal leverage this channel for masstige positioning with healthcare-adjacent trust transfer.
- Department Stores:Counter-based consultation and sampling infrastructure sustains prestige fragrance and color cosmetics. Foot traffic erosion in Paris and Milan flagship locations is accelerating channel investment into experiential retail formats.
- Salons:Professional-only formulations with higher active concentrations serve licensed estheticians and hairdressers. Eastern European underpenetration in Poland and Romania offers expansion runway for credential-based distribution models.
Climbing the fastest: Online Retail. Maintaining highest per-transaction value: Department Stores in heritage European capitals.
Customer Type:
Volume scale concentrates in institutional procurement while margin expansion tracks individual premiumization and professional credential requirements.
- Individuals:End consumers purchasing for personal grooming and aesthetic maintenance. Repeat subscription models in German and French markets are displacing episodic department store purchasing for core skincare regimens.
- Professionals:Licensed estheticians, makeup artists, and salon operators requiring bulk formats and wholesale pricing. Regulatory recognition of cosmetology credentials varies across EU member states, fragmenting market access requirements.
- Retailers:Multi-brand independent and chain operators curating assortment for local demographic profiles. CSRD disclosure mandates are forcing consolidation of supplier relationships to simplify Scope 3 emissions auditing.
- Wholesalers:Distribution intermediaries serving fragmented pharmacy and salon networks in Southern and Eastern Europe. Margin compression from direct-to-consumer brand expansion is threatening traditional intermediary economics.
Driving absolute volume: Individuals. Expanding most quickly: Professional procurement with credential-verified access tiers.
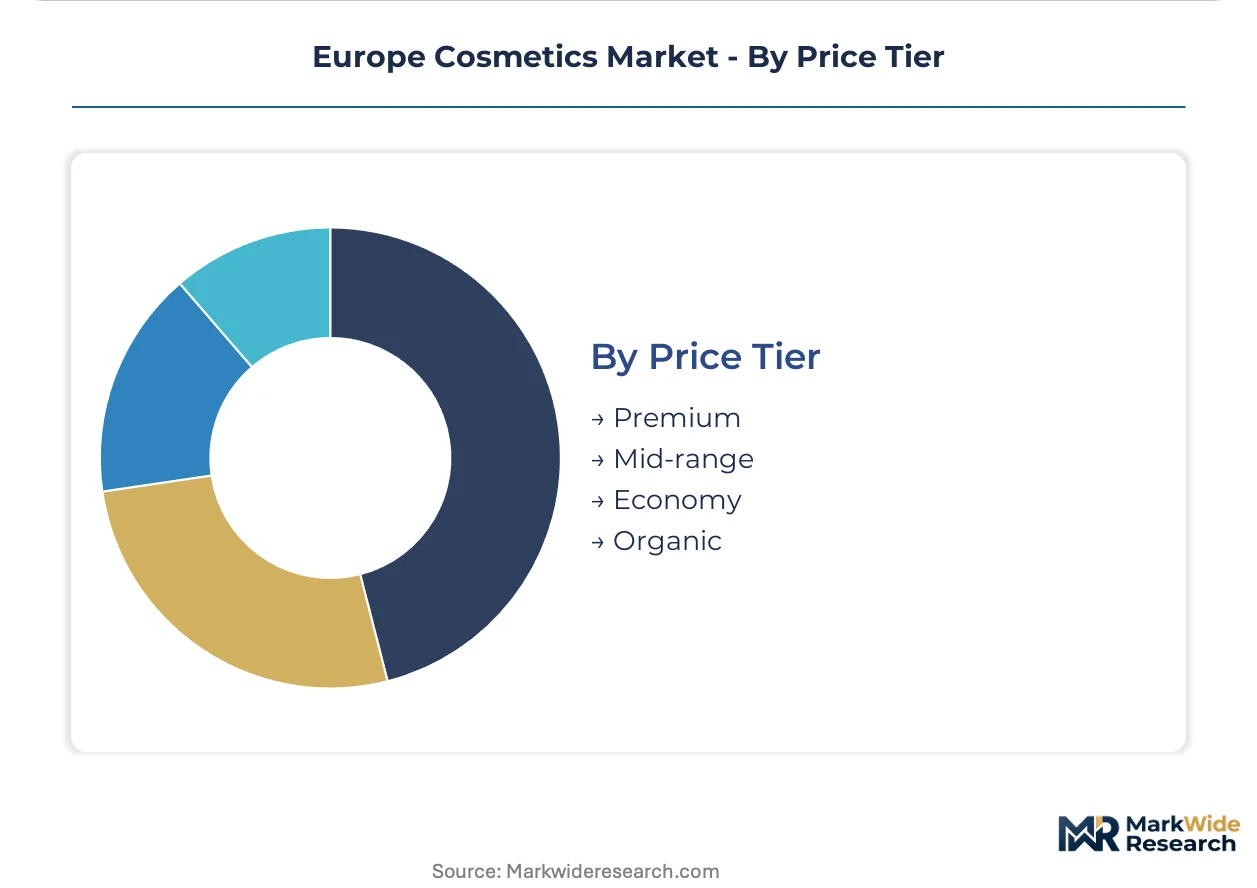
Price Tier:
Certification overhead and ingredient transparency claims stratify pricing power across conventional and clean-label positioning.
- Premium:Heritage brand positioning with Paris and Milan design association, advanced delivery system technology, and limited distribution scarcity. French millennial and Gen Z cohorts sustain repeat purchase frequency for anti-aging subcategories with clinical efficacy claims.
- Mid-range:Masstige positioning bridging mass-market accessibility with prestige aspiration cues. L'Oréal multi-brand architecture captures this tier through pharmacy channel dominance and scaled manufacturing efficiency.
- Economy:High-volume, low-margin formulations serving price-sensitive segments through hypermarket and discount retail. Petrochemical feedstock volatility in surfactant inputs compresses margin pools for producers lacking backward integration into specialty chemical production.
- Organic:EU Green Deal-aligned certification with mandatory ingredient disclosure and carbon accounting documentation. Clean-label premiums measurable over conventional formulations are pulling investment into certified organic sourcing infrastructure.
Holding largest revenue share: Premium. Gaining share fastest: Organic with CSRD-compliant supply chain verification.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Grasse in southeastern France anchors the continent's aromatic compound extraction infrastructure, while Hamburg and Rotterdam harbor facilities concentrate surfactant and emulsifier feedstock processing for northern European formulation networks.
France
Heritage brand headquarters in Paris and Lyon drive premium skincare demand among millennial buyers seeking anti-aging solutions. ANSM cosmetic safety oversight enforces stringent ingredient disclosure requirements that elevate compliance costs for new market entrants. Grasse maintains artisanal extraction capabilities for luxury fragrance positioning while biotechnology startups in the Île-de-France region scale lab-grown active ingredient production.
Germany
Pharmacy-channel dominance in German-speaking markets sustains dermatological credibility positioning for masstige skincare brands. KBA and BfArM regulatory frameworks intersect with REACH chemical registration requirements, forcing accelerated reformulation cycles. Hamburg harbor facilities and North Rhine-Westphalia chemical clusters concentrate surfactant manufacturing and pharmaceutical-grade packaging supply for European distribution.
Italy
Heritage color cosmetics manufacturing in Milan and Florence anchors premium pigment dispersion capabilities for luxury positioning. ECHA microplastic restriction timelines are forcing immediate reformulation of glitter and long-wear foundations ahead of enforcement deadlines. Emilia-Romagna packaging machinery specialists supply airless pump systems to scale-up brands across the continent.
United Kingdom
London-based direct-to-consumer platforms disintermediate traditional wholesale relationships for prestige skincare discovery among Gen Z buyers. Post-Brexit regulatory divergence from EU REACH standards creates dual compliance burdens for cross-channel formulation distribution. Southeast England logistics hubs service subscription-model fulfillment for algorithmic personalization brands targeting phototype-specific regimens.
Poland
Underpenetrated pharmacy channel distribution in Warsaw and Kraków offers first-mover positioning for dermatological credibility brands expanding beyond saturated Western European retail. EU Green Deal carbon accounting mandates pull investment into certified organic ingredient sourcing infrastructure. Poznań manufacturing zones attract contract formulation facilities serving Eastern European market development.
Europe Cosmetics Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue biotechnology-derived actives and circular economy refill formats. The market exhibits tiered concentration with heritage conglomerates anchoring premium positioning alongside specialized dermatological players. Three archetypes dominate: multi-brand portfolio architects, pharmacy-channel credibility specialists, and direct-to-consumer platform operators. Competitive moves center on M&A consolidation of biotechnology startups and capacity expansion into precision fermentation facilities for lab-grown collagen and squalane production.
Within the heritage conglomerate tier, L'Oréal S.A. and Unilever PLC exemplify multi-brand architectures capturing value across prestige and masstige segments simultaneously. Beiersdorf AG occupies a dermatological credibility position anchored in pharmacy channel dominance. These three entities represent distinct strategic postures: Paris-based portfolio diversification, London-anchored sustainability-certified supply chain transparency, and Hamburg-centered pharmacy-adjacent trust transfer.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Unilever PLC |
| Procter & Gamble Co |
| Beiersdorf AG |
| The Estée Lauder Companies Inc. |
| Coty Inc. |
| Shiseido Co., Ltd. |
| Kao Corporation |
| Johnson & Johnson Services, Inc. |
| Others |
Supply Flow & Price Mechanics
Digital-native millennial and Gen Z buyer concentration in France and Germany anchors subscription-based pricing models that displace episodic department store purchasing. REACH compliance costs and biotechnology-derived active ingredient premiums stratify pricing power across clean-label certified and conventional formulation tiers.
Pricing Analysis
Volume scale concentrates in economy-tier surfactant formulations while margin expansion tracks premium and organic certification tiers. Price differentiation rests on EU Green Deal carbon accounting documentation and dermatological credibility endorsements through pharmacy channels. Cost compression in masstige tiers intensifies because petrochemical feedstock volatility squeezes producers lacking backward integration into specialty chemical production. Economy-tier hypermarket buyers exhibit highest price sensitivity; prestige heritage brand purchasers in Paris and Milan show lowest elasticity.
Supply Chain Analysis
Regional distribution centers in Hamburg and Rotterdam harbor facilities anchor hub-and-spoke patterns serving northern European formulation networks. Geographic supply concentration centers on Germany for pharmaceutical-grade packaging, France for aromatic compound extraction, and Italy for colorant dispersion capabilities. Raw material dependencies draw from biotechnology fermentation facilities in the Netherlands and Denmark, surfactant feedstocks in North Rhine-Westphalia chemical clusters, and artisanal botanical extraction in Grasse. Single-source vulnerability in Mittelstand airless pump manufacturers creates structural risk. Distribution runs through pharmacy networks in German-speaking markets and direct-to-consumer platforms displacing traditional wholesale relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology-derived active ingredient capacity constraints prop pricing premiums for CSRD-compliant supply chains, creating supply-constrained conditions that favor incumbent consolidation and specialized entrant positioning.
For Market Incumbents: Lock in precision fermentation capacity through offtake agreements with Netherlands and Denmark biotechnology startups before scale-up brands exhaust available supply. Secure pharmacy channel shelf space in underpenetrated Polish and Romanian markets to preempt emerging dermatological credibility entrants. Backward integration into captive squalane and collagen production reduces agricultural land dependency exposure. For New Entrants and Emerging Players: Pharmacy chain partners in Warsaw and Kraków offer first-mover positioning for clean-label certified skincare lines seeking expansion beyond saturated Western European retail. Refill station retail formats aligned with EU Green Deal waste reduction targets enable direct consumer relationships while bypassing wholesale margin structures. AI-driven skin diagnostic hardware convergence creates subscription revenue models for bespoke regimen positioning. For Investors and Strategic Acquirers: The window for entry favors biotechnology startups with scaled precision fermentation capabilities and CSRD-compliant supply chain documentation infrastructure. Long-term viability over the coming decade hinges on regulatory compliance moats rather than brand equity alone. Watch ECHA substance restriction list expansion velocity as inflection indicator for reformulation cycle intensity and R&D bandwidth requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Netherlands and Denmark facilities reduce agricultural land dependency for collagen and squalane actives. |
| Pharmacy Channel Expansion | Polish and Romanian underpenetration offers first-mover positioning for dermatological credibility brands. |
| Refill Station Retail Format | Circular economy models aligned with EU Green Deal targets bypass traditional wholesale margin structures. |
| CSRD Compliance Infrastructure | Granular Scope 3 emissions auditing capability separates compliant suppliers from consolidation pressure. |
| AI-Driven Personalization Platform | Algorithmic formulation matching creates subscription economics for phototype-specific skincare regimens. |
Methodological Framework
Independent corroboration across regulatory affairs directors at heritage conglomerates, pharmacy chain category buyers in Germany and France, and biotechnology startup R&D leads underwrites the qualitative findings. Secondary validation draws from ECHA substance restriction notifications, EU Green Deal implementation guidance, ANSM cosmetic safety filings, and REACH registration databases. Bottom-up segment sizing triangulates against top-down macroeconomic anchoring.
Rate-of-change decomposition separates volume drivers from pricing power shifts across the projection horizon. Segmentation dimensions modeled include product type, distribution channel, customer type, and price tier with regional regulatory cluster overlays. CAGRs derive from historical trajectory analysis adjusted for REACH reformulation cycle acceleration and CSRD disclosure mandate implementation. Forecast inputs incorporate biotechnology capacity buildout timelines and pharmacy channel penetration rates in Eastern European markets.
Caveats apply where ECHA substance restriction timeline acceleration or petrochemical feedstock volatility spikes could materially shift the outlook. Forecasts assume continued EU Green Deal policy continuity and stable biotechnology fermentation yield scaling. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Cosmetics and Personal Care Products Direct Selling Market
Beauty & Personal Care
Plant-Based Skincare Products Market
Beauty & Personal Care
Premium Cosmetics Market
Beauty & Personal Care
Europe and Asia Pacific Herbal Beauty Products Market
Beauty & Personal Care
Hair Removal Wax Market
Beauty & Personal Care
Electric Nail Files Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
United Kingdom Hair Care Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Global Lash Extension Market
Beauty & Personal Care
Oil Control Lotion Market
Beauty & Personal Care
Europe Beauty and Personal Care Products Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Europe Shampoo Market
Beauty & Personal Care
Global Personal Care Market
Beauty & Personal Care
Hair Color Spray Market