
 Germany Beauty Industry Market | 2026-2036
Germany Beauty Industry Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Beauty Industry Market Insights
Bavaria is narrowing its gap with North Rhine-Westphalia as Germany's second-largest beauty manufacturing corridor after new cold-process emulsion facilities came online. Beiersdorf AG anchors its competitive position through captive dermatological research infrastructure in Hamburg. L'Oréal S.A. extends its color cosmetics dominance via specialized manufacturing lines serving the DACH region. Henkel AG & Co KGaA differentiates through concentrated professional haircare formulations developed at its Düsseldorf innovation campus.
The Germany Beauty Industry encompasses the formulation, manufacture, and distribution of topical preparations including emulsions, anhydrous balms, surfactant-based cleansers, and alcoholic fragrance solutions, typically requiring stability testing across pH ranges of 4.0 to 8.5 and preservative efficacy validation. Its primary commercial purpose centers on personal appearance enhancement, skin health maintenance, and olfactory identity expression through repeated consumer purchase cycles. Skincare commands the largest value pool as German consumers prioritize barrier-repair ceramide formulations and microbiome-friendly actives over basic moisturization. Online Retail represents the fastest-expanding distribution channel, though Pharmacies retain the highest margin capture through consultation-linked dermocosmetic sales.
REACH compliance through ECHA governs ingredient authorization and substitution timelines for all cosmetic substances placed on the German market. The EU Green Deal's packaging waste directives and Germany's national VerpackG extended producer responsibility framework are reshaping primary and secondary packaging specifications across the value chain. Stakeholders must monitor forthcoming EU microplastic restrictions and their downstream reformulation cost implications.
Market Dynamics
REACH chemical safety standards through ECHA are forcing systematic reformulation across color cosmetics, compressing product development timelines while elevating R&D spend requirements for German manufacturers.
Growth Catalysts
- Clean-label demand:Millennial and Gen Z consumers in Berlin, Munich, and Hamburg prioritize microbiome-friendly actives and barrier-repair ceramide formulations, pulling investment toward dermatological validation infrastructure.
- VerpackG extended producer responsibility:Germany's national packaging waste framework accelerates circular packaging innovation, creating first-mover advantages for domestic suppliers with closed-loop material capabilities.
- Cold-process emulsion technology:New manufacturing facilities in Bavaria reduce energy intensity and thermal degradation of heat-sensitive actives, improving yield rates for premium skincare lines.
Market Restraints
- Ingredient authorization timelines:ECHA's substance evaluation and authorization procedures extend new active introduction cycles, delaying product pipeline commercialization by 18-36 months.
- Specialty chemical concentration:Supply of palm-derived emollients and silicone alternatives concentrates among Southeast Asian and Chinese producers, exposing German formulators to input cost volatility and logistics disruption.
- Preservative system limitations:Microplastic restrictions and clean-label preferences constrain traditional preservative options, narrowing the viable stability window for aqueous formulations.
Strategic Opportunities
- Pharmacy channel expansion:Consultation-linked dermocosmetic sales in German Apotheken capture premium margins, rewarding brands with clinical validation and pharmacist training programs.
- AI-driven personalization:Convergence of skin diagnostic imaging and algorithmic formulation matching enables mass-customized skincare at scale, differentiating direct-to-consumer propositions.
- Professional haircare segment:Concentrated salon-grade formulations developed at Düsseldorf-area innovation campuses address underpenetrated independent stylist networks across eastern German states.
Industry Challenges
- Preservative efficacy validation:ISO 11930 and alternative microbiological testing protocols demand specialized laboratory capacity that mid-tier manufacturers lack in-house.
- Cross-functional talent scarcity:Formulation chemists with simultaneous expertise in green chemistry, regulatory affairs, and scale-up manufacturing command compensation premiums that strain SME cost structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Beauty Industry Market |
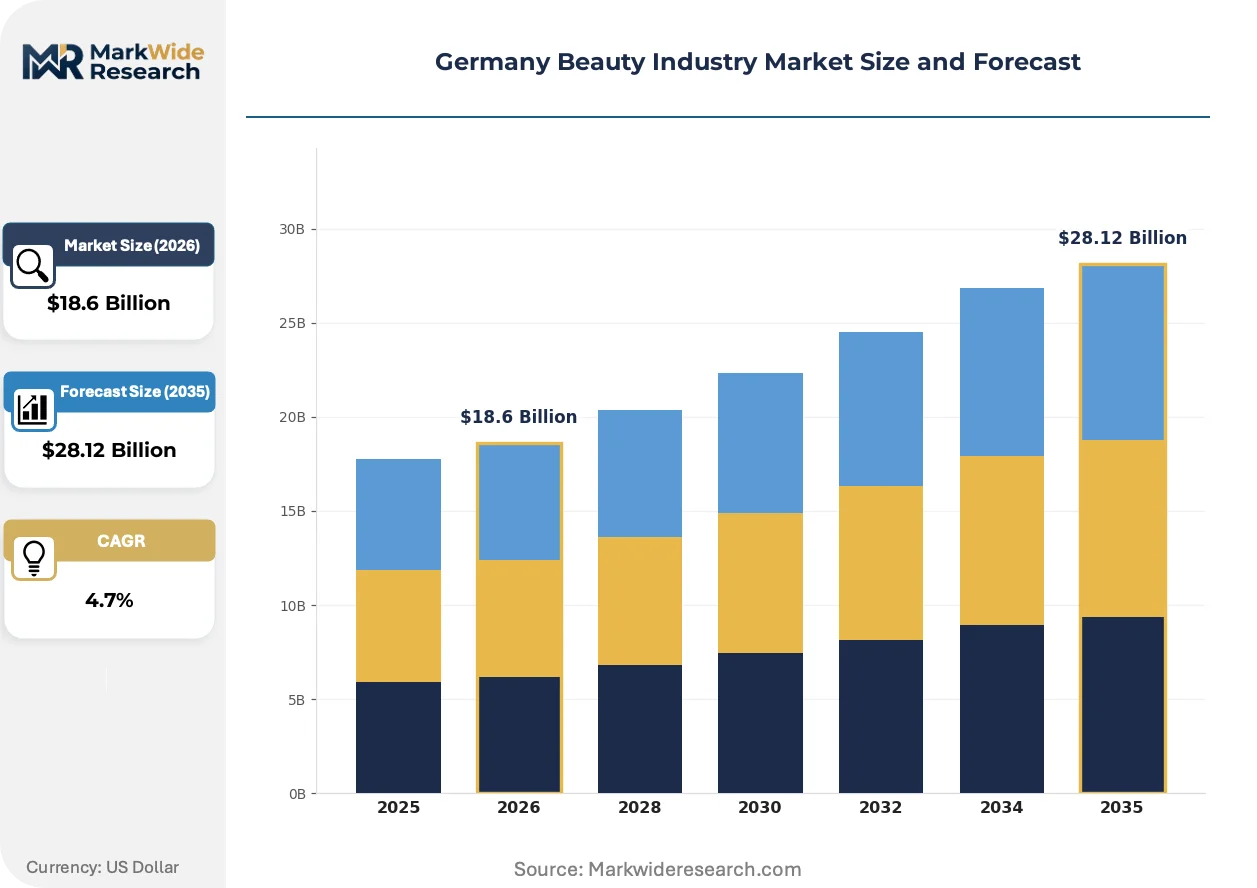
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $28.12 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Skincare, Makeup, Haircare, Fragrance Distribution Channel: Specialty Stores, Online Retail, Supermarkets, Pharmacies Customer Type: Women, Men, Teenagers, Professionals Price Tier: Premium, Mass, Luxurious, Budget |
| Companies Covered | Procter & Gamble Company, Coty Inc, Beiersdorf AG, Weleda AG, The Estee Lauder Companies Inc, L'Oréal S.A., Henkel AG & Co KGaA, dm-drogerie markt, Unilever PLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Beauty Industry Market Trends and Innovations
Formulation science, regulatory compliance architecture, and distribution channel economics are converging to reshape competitive advantage in German beauty manufacturing. Technology investments now prioritize traceability and personalization over traditional scale economies.
Biotechnology-derived actives from precision fermentation processes are displacing petrochemical and plant-extraction sources for peptides, ceramides, and hyaluronic acid precursors. Mid-sized German brands with captive biotech partnerships are compressing raw material qualification cycles. This shift is digitizing supply chain provenance tracking from strain bank to finished good.
ECHA's forthcoming microplastic restriction proposals under REACH Annex XVII are accelerating biodegradable glitter and film-forming polymer substitution programs. Color cosmetics manufacturers face the steepest compliance burden given decorative product reliance on synthetic microspheres. German formulators are responding with cellulose-based alternatives and mineral pigment dispersions requiring new milling equipment.
Subscription-based replenishment models with algorithmic skin assessment are displacing transactional retail purchasing among urban German consumers aged 25-40. Direct-to-consumer platforms capture recurring revenue while pharmacy consultation services defend high-margin dermocosmetic positioning. This channel bifurcation is most pronounced in Hamburg and Berlin metropolitan clusters where digital-native brands compete against established Apotheken networks.
Germany Beauty Industry Market Segmentation
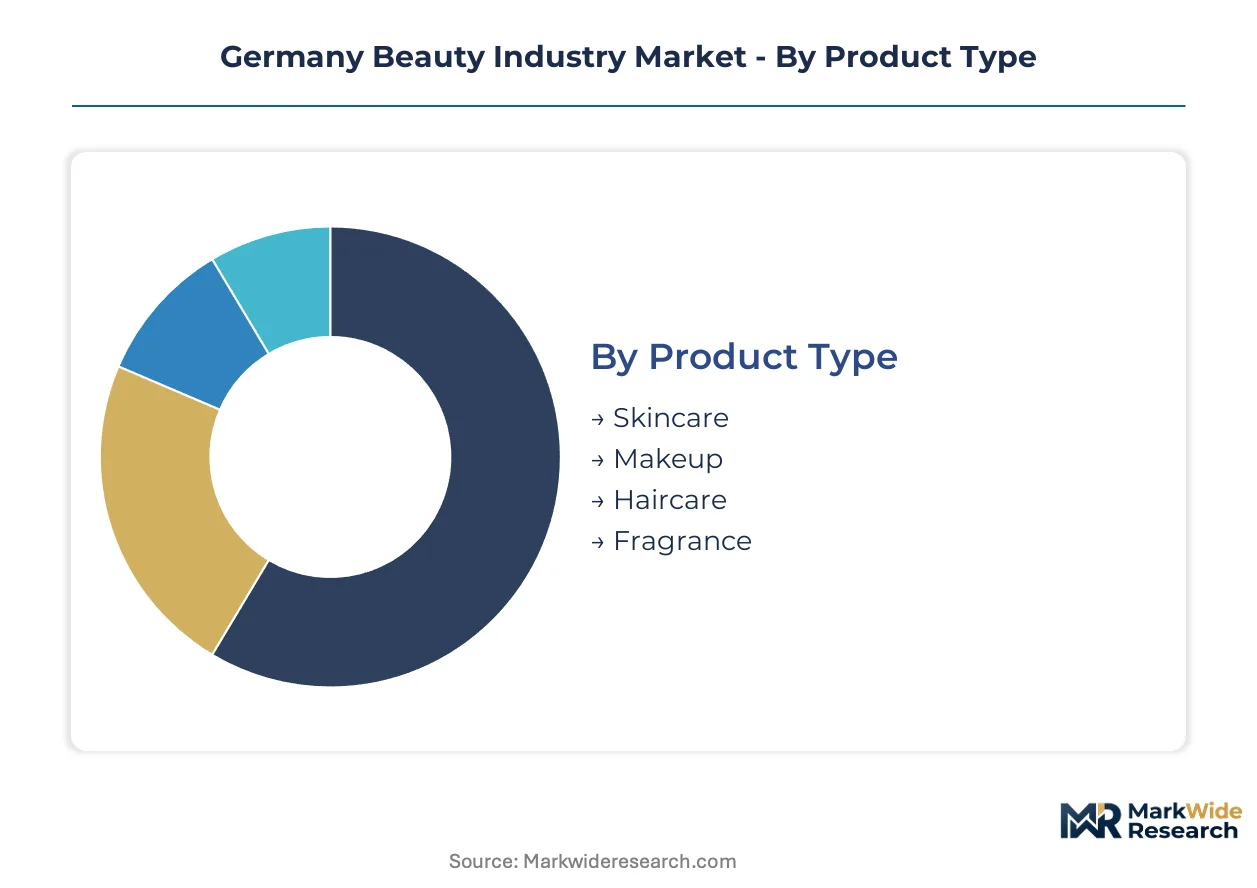
German beauty market segmentation reveals divergent margin profiles and regulatory exposure across product categories. Channel and customer stratification determines where clean-label premiums translate into sustainable pricing power versus commodity compression.
Product Type:
Mature emulsion science dominates established categories while biotechnology-derived actives reshape emerging formulations.
- Skincare:Emulsion-based moisturizers, serums, and barrier-repair formulations requiring stability validation across pH 4.0-8.5. Demand clusters in Berlin and Munich for microbiome-friendly ceramide products driven by REACH-compliant preservative systems.
- Makeup:Color cosmetics face acute reformulation pressure from ECHA microplastic restrictions under REACH Annex XVII. Bavarian cold-process facilities now supply cellulose-based glitter alternatives to replace synthetic microspheres.
- Haircare:Concentrated professional formulations anchor Henkel's Düsseldorf innovation campus output.
- Fragrance:Alcoholic solutions with olfactory identity positioning for repeat purchase cycles.
Skincare retains volume leadership; makeup holds the steepest expansion curve as clean-label color cosmetics gain share fastest.
Distribution Channel:
Margin capture stratifies sharply between consultation-linked services and algorithmic direct-to-consumer platforms.
- Specialty Stores:Curated brand environments with trained staff driving trial conversion for premium skincare lines.
- Online Retail:Subscription-based replenishment with skin diagnostic imaging and algorithmic formulation matching. Urban consumers aged 25-40 in Hamburg and Berlin metropolitan clusters favor this channel for recurring revenue capture.
- Supermarkets:Mass-market volume throughput with compressed margins and limited dermatological validation.
- Pharmacies:German Apotheken networks defend the highest margin capture through pharmacist consultation and dermocosmetic positioning. Clinical validation requirements reward brands with training infrastructure investment.
Pharmacies retain margin leadership; online retail climbs the fastest as subscription models displace transactional purchasing.
Customer Type:
Demographic targeting determines formulation complexity and channel access investment priorities.
- Women:Core volume base across all product categories with established purchase frequency patterns.
- Men:Emerging segment for simplified barrier-repair regimens and fragrance solutions with lower SKU complexity requirements.
- Teenagers:Acne-targeted formulations with social media-influenced brand discovery and price sensitivity constraining premium positioning.
- Professionals:Salon-grade haircare and clinical skincare with professional endorsement dependencies and concentrated Düsseldorf-area supply.
Women retain volume leadership; professionals represent the steepest expansion curve as independent stylist networks expand.
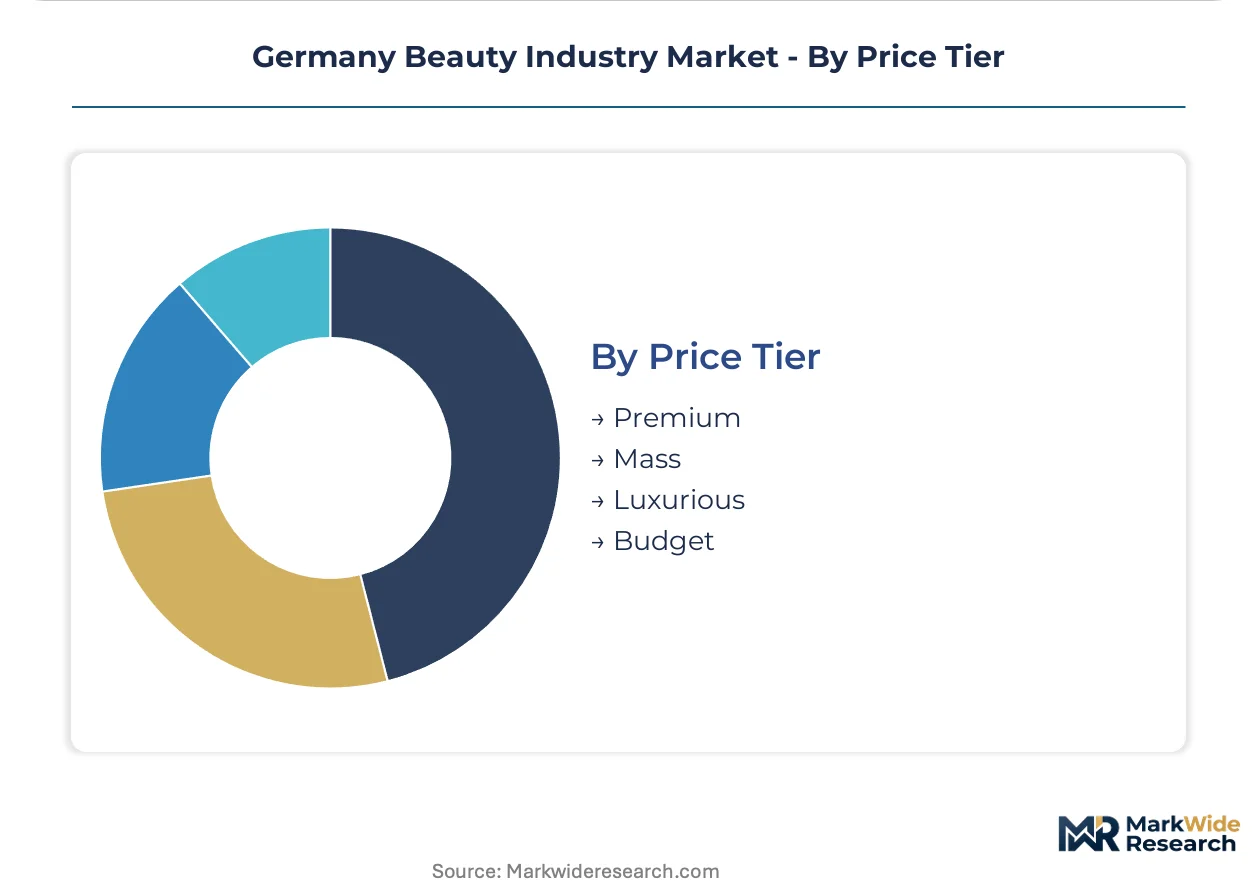
Price Tier:
Cost stratification aligns with regulatory compliance burden and dermatological validation depth.
- Premium:Mid-tier positioning with clean-label claims and ECHA-compliant ingredient transparency. Cold-process emulsion technology from Bavarian facilities supports this tier's energy-efficient production narrative.
- Mass:Volume-driven formulations with standardized preservative systems and supermarket distribution economics.
- Luxurious:Highest validation tier with captive dermatological research infrastructure and pharmacy channel exclusivity. Beiersdorf's Hamburg facilities anchor this segment's clinical credibility.
- Budget:Price-constrained formulations with compressed R&D cycles and limited stability testing protocols.
Mass retains volume leadership; premium gains share fastest as millennial and Gen Z consumers prioritize clean-label credentials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation expertise clusters along Germany's western and southern industrial corridors, with cold-process emulsion facilities narrowing Bavaria's manufacturing gap against North Rhine-Westphalia. Metropolitan demand concentrates in Berlin, Munich, and Hamburg where millennial and Gen Z consumers prioritize microbiome-friendly actives.
Bavaria
New cold-process emulsion facilities in Bavaria reduce energy intensity for heat-sensitive actives, improving yield rates for premium skincare lines. ECHA's REACH chemical safety standards govern ingredient authorization timelines for all substances placed on the Bavarian market. Manufacturing investment concentrates around Munich metropolitan clusters serving clean-label demand from affluent urban consumers.
North Rhine-Westphalia
Professional haircare formulation development anchors demand in Düsseldorf-area innovation campuses serving independent stylist networks. Germany's VerpackG extended producer responsibility framework accelerates circular packaging innovation among North Rhine-Westphalia suppliers. Henkel's captive research infrastructure in Düsseldorf exemplifies concentrated R&D investment in concentrated salon-grade products.
Hamburg
Dermocosmetic consultation services in Hamburg Apotheken capture premium margins through pharmacist-linked clinical validation. EU Green Deal packaging waste directives reshape primary and secondary specifications for Hamburg-based distributors. Beiersdorf's dermatological research infrastructure anchors the city's position in barrier-repair ceramide development.
Baden-Württemberg
Precision fermentation biotechnology partnerships in Baden-Württemberg compress raw material qualification cycles for peptides and hyaluronic acid precursors. ECHA's forthcoming microplastic restrictions under REACH Annex XVII accelerate biodegradable glitter substitution programs in regional color cosmetics facilities. Stuttgart-area manufacturing serves pharmacy channel expansion with clinical validation infrastructure.
Berlin-Brandenburg
Subscription-based replenishment models with algorithmic skin assessment displace transactional retail purchasing among Berlin's 25-40 age demographic. Germany's national packaging waste framework creates first-mover advantages for direct-to-consumer platforms with closed-loop material capabilities. Digital-native brands in Berlin metropolitan clusters compete against established Apotheken networks for dermocosmetic positioning.
Germany Beauty Industry Market Competitive Landscape
Diversified multinational conglomerates and specialized regional formulators split the market between scale-driven mass distribution and consultation-linked premium positioning. Three archetypes dominate: captive dermatological research houses, professional haircare innovation campuses, and algorithmic direct-to-consumer platforms. Consolidation pressure concentrates among mid-tier manufacturers lacking ISO 11930 microbiological testing capacity. Competitive moves center on pharmacy channel training infrastructure and AI-driven personalization technology licensing.
Within the diversified multinational tier, Procter & Gamble Company and Unilever PLC represent scale-driven mass-market archetypes with standardized preservative systems and supermarket distribution economics. L'Oréal S.A. and The Estee Lauder Companies Inc occupy positions bridging mass and premium tiers through specialized manufacturing lines and clinical validation depth. Among German-origin entities, Beiersdorf AG exemplifies the captive research archetype with Hamburg-based dermatological infrastructure, while Henkel AG & Co KGaA anchors professional haircare concentration through Düsseldorf innovation campuses. Coty Inc represents fragrance-focused positioning within the alcoholic solutions segment. Regional specialists including Weleda AG and dm-drogerie markt occupy distinct niches in clean-label formulations and pharmacy-adjacent retail respectively.
| Leading Market Players |
|---|
| Procter & Gamble Company |
| Coty Inc |
| Beiersdorf AG |
| Weleda AG |
| The Estee Lauder Companies Inc |
| L'Oréal S.A. |
| Henkel AG & Co KGaA |
| dm-drogerie markt |
| Unilever PLC |
| Others |
Pricing and Supply Chain Analysis
Southeast Asian palm-derived emollient concentration funnels margin capture toward German brands with long-term offtake agreements and cold-process manufacturing capabilities. REACH compliance costs and VerpackG packaging obligations stratify pricing power between mass-market formulators and pharmacy-channel dermocosmetic specialists.
Pricing Analysis
ECHA's REACH chemical safety standards dictate the pricing tier structure across German beauty manufacturing, with authorization timelines and substitution costs elevating premium positioning for ECHA-compliant brands. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-exclusive dermocosmetics from mass retail and budget supermarket lines. Price differentiation hinges on clinical validation depth and dermatological endorsement density. Cost compression in the mass tier intensifies because supermarket buyers demand volume discounts without formulation premiumization. Teenage consumers exhibit highest price sensitivity, while pharmacy-linked professionals accept premium positioning for consultation-validated barrier-repair formulations.
Supply Chain Analysis
Tariff exposure between Southeast Asian palm producers and German formulators dominates supply chain risk calculus for emollient-dependent skincare lines. Raw material sourcing draws from Indonesia and Malaysia for palm derivatives, China for silicone alternatives, and domestic Bavarian facilities for cold-process emulsion actives. Single-source vulnerability concentrates in precision fermentation feedstocks for biotechnology-derived peptides and ceramides. Distribution runs through pharmacy Apotheken networks for premium dermocosmetics, direct-to-consumer platforms for subscription replenishment, and dm-drogerie markt for clean-label mass market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional talent scarcity in green chemistry, regulatory affairs, and scale-up manufacturing compresses competitive timelines for mid-tier German beauty manufacturers. Formulation chemists commanding compensation premiums strain SME cost structures while rewarding incumbents with captive training infrastructure.
For Market Incumbents: Harden pharmacy channel control through pharmacist training program expansion and clinical validation investment to defend margin position against algorithmic direct-to-consumer platforms. Deepen backward integration into precision fermentation partnerships in Baden-Württemberg to secure biotechnology-derived active supply. ECHA's forthcoming microplastic restrictions threaten color cosmetics portfolios lacking cellulose-based glitter substitution capabilities. For New Entrants and Emerging Players: Pursue underpenetrated independent stylist networks across eastern German states with concentrated professional haircare formulations and salon-grade education programs. White-space opportunity concentrates in subscription-based replenishment with AI-driven skin diagnostic imaging for Berlin and Hamburg metropolitan clusters aged 25-40. Go-to-market angle: algorithmic personalization at mass-market price points with closed-loop packaging compliance. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier manufacturers lacking ISO 11930 microbiological testing capacity and captive dermatological research infrastructure. Long-term viability across the analysis window favors targets with pharmacy channel training programs and REACH-compliant preservative system portfolios. Signal to watch: ECHA authorization timeline acceleration for novel biotechnology-derived actives as inflection indicator for raw material cost compression.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacy Channel Training Program | Pharmacist consultation services in German Apotheken defend premium margin capture against digital-native competitors. |
| Precision Fermentation Partnership | Biotechnology-derived active sourcing from Baden-Württemberg compresses raw material qualification cycles for ceramide formulations. |
| Closed-Loop Packaging Transition | VerpackG compliance creates first-mover advantages for domestic suppliers with circular material capabilities. |
| AI-Driven Personalization Platform | Algorithmic skin assessment and formulation matching enables mass-customized skincare at direct-to-consumer scale. |
| Cold-Process Emulsion Scale-Up | Bavarian manufacturing investment reduces energy intensity for heat-sensitive actives in premium skincare lines. |
Research Methodology
A spread of perspectives from brand managers at multinational conglomerates, pharmacy category buyers, formulation chemists at innovation campuses, and supply planners at packaging converters converged on the working assumptions underlying this analysis. Primary interviews with these stakeholders combined with secondary validation from ECHA substance registration databases, German customs trade records, Nielsen retail audit data, and SEC filings of listed beauty manufacturers. Bottom-up channel volume estimates and top-down macroeconomic sizing were triangulated to establish market boundaries.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation modeled by product type, distribution channel, customer demographic, and price tier. End-use industry clustering, regional manufacturing hub concentration, and regulatory compliance burden shaped the dimensional structure. CAGRs were derived from trend extrapolation of historical volume trajectories adjusted for REACH reformulation cycle impacts and VerpackG packaging transition timelines. Forecast inputs included pharmacy consultation service expansion rates and subscription replenishment model adoption curves.
Sensitivities concentrate around ECHA authorization timeline delays, Southeast Asian palm derivative supply disruptions, and microplastic restriction implementation schedules. Forecasts reflect assumptions about clean-label demand persistence and cold-process technology yield improvements. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Cosmetic Wax Market
Beauty & Personal Care
Global Cosmetics Market
Beauty & Personal Care
Beauty Pillowcases Market
Beauty & Personal Care
North America Bath and Shower Products Market
Beauty & Personal Care
Mens Intimate Care Products Market
Beauty & Personal Care
North America Setting Spray Market
Beauty & Personal Care
United States Male Grooming Products Market
Beauty & Personal Care
DIY Face Mask Machine Market
Beauty & Personal Care
Body Mist Market
Beauty & Personal Care
Facial Care Market
Beauty & Personal Care
Herbal Cosmetics Market
Beauty & Personal Care
Colombia Hair Care Market
Beauty & Personal Care
Global Shampoo Bars Market
Beauty & Personal Care
Electric Facial Cleansing Brush Market
Beauty & Personal Care
Premium Cosmetics Market