
 Implantable Collamer Lens Market | 2026-2036
Implantable Collamer Lens Market Size, Share, and Industry Trends Forecast 2026-2036
Implantable Collamer Lens Market Foresight
Post-operative monitoring subscription bundles is hardening into a core revenue stream for manufacturers seeking recurring revenue beyond the initial lens sale. STAAR Surgical Company leverages its proprietary Collamer composition and direct surgeon training networks to sustain premium positioning in the refractive channel. Carl Zeiss Meditec anchors its competitive stance through integrated diagnostic-to-surgery workflows that lock in clinic loyalty. Alcon competes across the broader vision correction portfolio, using its cataract infrastructure to cross-sell refractive solutions.
An implantable Collamer lens is a biocompatible, collagen copolymer phakic intraocular lens designed for implantation in the posterior chamber without removal of the patient's natural crystalline lens, typically featuring a central optical zone and proprietary hydrophilic surface properties that promote aqueous humor flow. The device corrects moderate to severe myopia and astigmatism in patients who fall outside acceptable parameters for laser corneal reshaping. Toric ICL variants command the strongest margin pools due to customized astigmatic correction requirements and limited manufacturing competition. Ambulatory surgical centers represent the fastest-growing end user channel as outpatient refractive volumes shift away from hospital-based settings toward specialized, high-throughput eye care facilities.
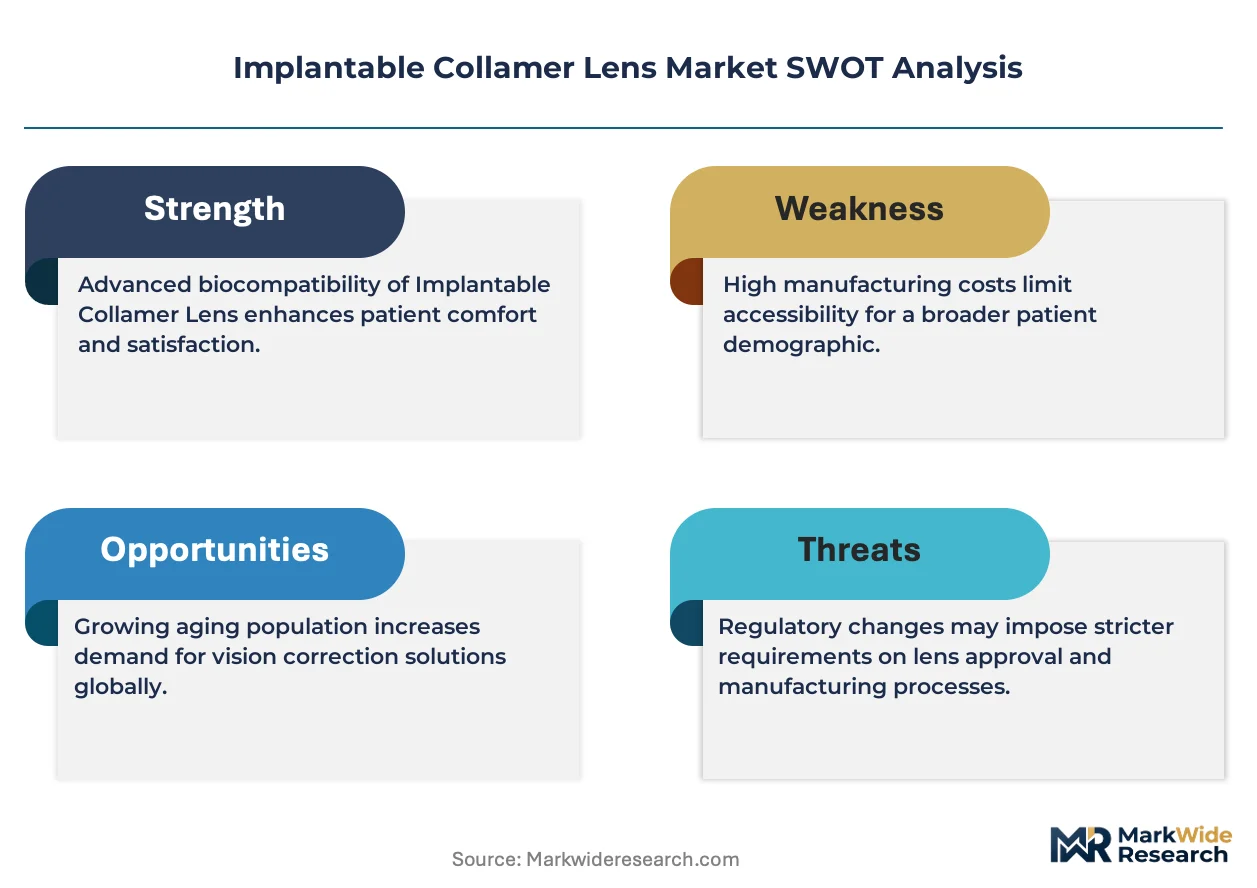
FDA PMA oversight and EU MDR conformity assessment both mandate extensive clinical safety databases and post-approval surveillance for phakic intraocular lenses, effectively filtering market access to well-capitalized developers with established regulatory track records. ISO 13485 quality management systems and biocompatibility testing under ISO 10993 further shape product development timelines and manufacturing compliance costs. Stakeholders must weigh reimbursement policy trajectories against direct-to-consumer marketing investments as private-pay refractive procedures face macroeconomic sensitivity and evolving vision insurance carve-outs.
Market Dynamics
Refractive surgery demand is fragmenting across patient age cohorts as myopia prevalence accelerates among adolescents and young professionals, forcing manufacturers to recalibrate lens sizing protocols and surgeon training curricula for anatomically distinct eyes.
Growth Catalysts
- EU MDR harmonization:Streamlined conformity assessment pathways for established phakic ICL designs are compressing time-to-market for next-generation toric variants across Germany, France, and Spain.
- Ambulatory surgical center expansion:Outpatient eye care facilities in the United States are installing dedicated refractive suites, expanding procedure throughput without hospital infrastructure overhead.
- Collamer material biocompatibility:Proprietary collagen copolymer compositions with intrinsic UV filtration are reducing post-operative complication rates and extending eligible patient demographics.
Market Restraints
- PMMA raw material concentration:Optical-grade polymethyl methacrylate supply chains cluster among German and Japanese specialty chemical producers, exposing lens manufacturers to input cost volatility.
- FDA PMA pathway duration:Pre-market approval mandates for phakic intraocular lenses impose 18-36 month clinical trial requirements that filter market access to well-capitalized developers.
- LASIK substitution threat:Wavefront-guided excimer laser platforms continue capturing mild-to-moderate myopia corrections at lower per-procedure price points.
Strategic Opportunities
- India refractory myopia segment:Urban ophthalmology chains in Mumbai and Delhi are building dedicated ICL service lines for patients exceeding -8.00 diopter thresholds.
- Post-operative monitoring subscriptions:Remote anterior segment imaging and IOP tracking bundles are creating recurring revenue streams beyond initial device sales.
- Japan PMDA fast-track designation:Breakthrough device pathways for novel toric ICL geometries are accelerating regulatory timelines for astigmatism-dominant patient populations.
Industry Challenges
- Surgeon certification bottlenecks:Manufacturer-specific training protocols for posterior chamber implantation techniques are constraining qualified operator pools and procedure volume scaling.
- ISO 10993 biocompatibility testing timelines:Extended cytotoxicity and sensitization study durations are compressing product development schedules and delaying pipeline launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Implantable Collamer Lens Market |
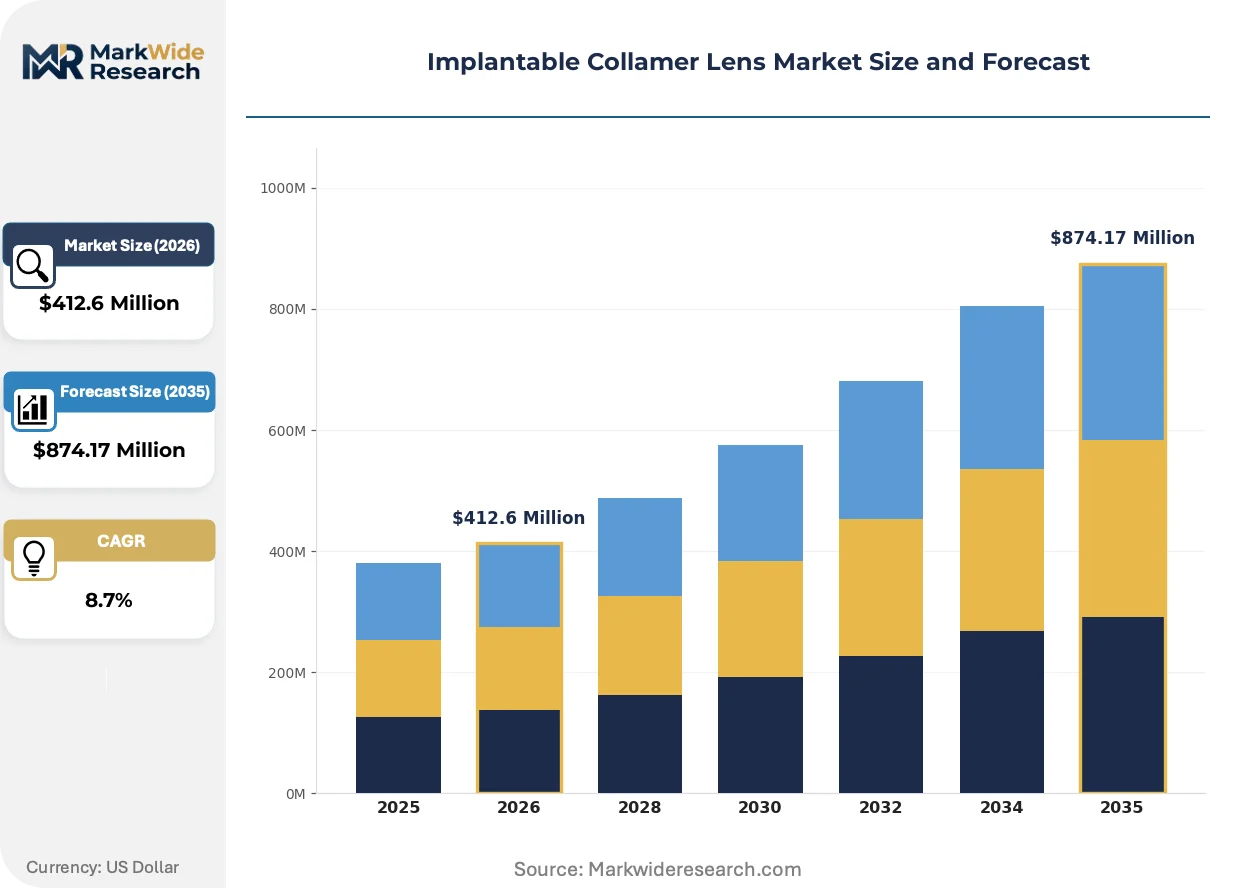
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $874.17 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multifocal ICL, Toric ICL, Standard ICL, Extended Depth of Field ICL End User: Ophthalmology Clinics, Hospitals, Ambulatory Surgical Centers, Eye Care Centers Material: Collamer, Silicone, PMMA, Hydrogel Distribution Channel: Direct Sales, Online Sales, Wholesalers, Distributors |
| Companies Covered | STAAR Surgical Company, Carl Zeiss Meditec, Bausch + Lomb, Alcon, Johnson & Johnson, Rayner Intraocular Lenses Limited, Hoya Surgical Optics, Aurolab, Abbott, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Implantable Collamer Lens Market Shifts & Advancements
Digital diagnostic-to-surgery workflows are compressing pre-operative assessment cycles while automated lens sizing algorithms are reducing human measurement error rates. These converging capabilities are redefining clinical efficiency benchmarks and patient throughput economics.
Central vault measurement technology is rewriting pre-operative planning protocols by enabling precise aqueous humor flow modeling between the ICL and crystalline lens. High-volume refractive clinics in South Korea and Brazil are adopting swept-source OCT-based sizing systems to reduce post-operative vault-related complications. This precision instrumentation is compressing revision surgery rates and extending manufacturer warranty exposure windows.
FDA's evolving PMA supplement requirements for design modifications are forcing developers to maintain living clinical safety databases rather than discrete trial submissions. The agency's heightened scrutiny of biocompatibility documentation is extending review cycles for material formulation changes. European manufacturers with established MDR technical files are responding by front-loading clinical evidence generation to preempt regulatory queries.
Direct-to-consumer financing platforms are displacing traditional insurance-mediated payment pathways for elective refractive procedures. Third-party patient lending services in the United States are bundling ICL procedures into 24-48 month installment structures, reducing upfront cost barriers for millennial and Gen Z demographics. This payment model innovation is most visible in coastal metropolitan markets where disposable income volatility intersects with strong aesthetic vision correction demand.
Implantable Collamer Lens Market Segmentation
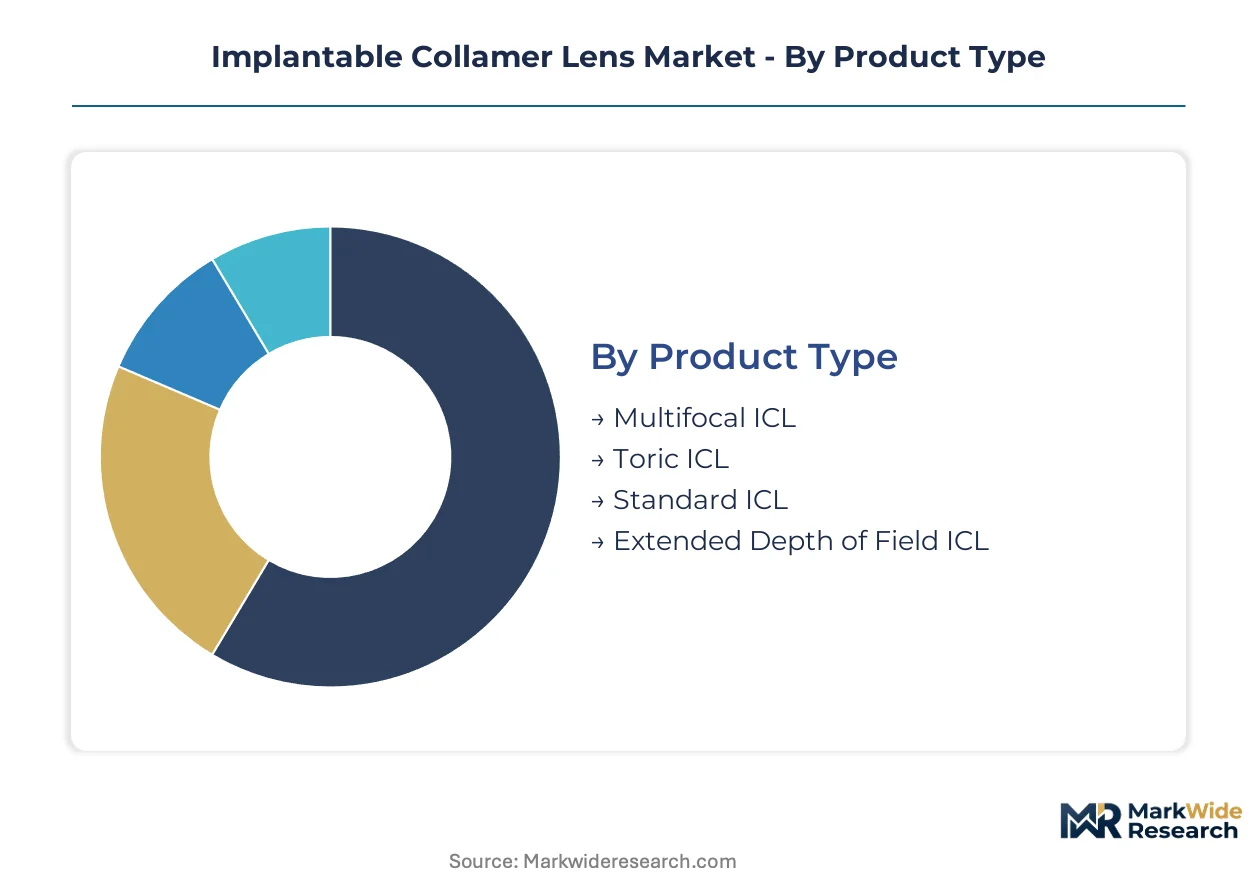
Implantable Collamer lens manufacturers segment their portfolios across optical design, clinical setting, material composition, and procurement pathway to align technical specifications with reimbursement economics and surgeon workflow preferences. Each segmentation axis carries distinct margin profiles and regulatory compliance burdens that shape competitive positioning.
Product Type:
Supply concentration tilts heavily toward toric variants where proprietary manufacturing know-how limits qualified producers and sustains premium pricing power.
- Toric ICL:Custom-manufactured with cylindrical power correction for astigmatism-dominant eyes, requiring precise axis alignment during implantation. Demand concentrates in South Korea and Brazil where swept-source OCT-based sizing protocols have reduced vault-related complications and extended warranty coverage. The segment commands the strongest margin pools due to limited manufacturing competition and individualized production runs.
- Standard ICL:Spherical-only correction for moderate-to-severe myopia without astigmatic component, featuring simpler inventory management and faster surgeon onboarding. United States ophthalmology clinics absorb the highest volumes as direct-to-consumer financing platforms reduce upfront cost barriers for millennial demographics seeking elective vision correction.
- Multifocal ICL:Diffractive optic designs addressing presbyopia-correcting applications in phakic patients.
- Extended Depth of Field ICL:Aspheric profiles extending functional vision range through controlled spherical aberration manipulation.
Toric ICL absorbs the bulk of installed capacity; Ambulatory Surgical Centers are expanding most quickly as outpatient refractive volumes shift from hospital infrastructure.
End User:
Cost tier differentiation separates high-throughput specialized facilities from capital-intensive hospital systems with heavier overhead structures.
- Ambulatory Surgical Centers:Dedicated refractive suites with streamlined patient throughput and lower per-procedure overhead than hospital settings. United States outpatient eye care facilities are installing specialized equipment to capture shifting volumes from hospital-based settings, supported by third-party patient lending services bundling procedures into installment structures.
- Ophthalmology Clinics:Integrated diagnostic-to-surgery workflows with direct surgeon training relationships and premium positioning in private-pay markets. Germany and Spain are seeing concentrated demand as EU MDR harmonization compresses time-to-market for next-generation toric variants.
- Hospitals:Academic medical centers and tertiary referral facilities handling complex anterior segment pathology alongside routine refractive cases.
- Eye Care Centers:Retail-oriented vision correction chains with standardized protocols and higher patient acquisition marketing spend.
Ophthalmology Clinics absorb the bulk of installed capacity; Ambulatory Surgical Centers are climbing the fastest as procedure economics favor outpatient specialization.
Material:
Volume concentration tracks biocompatibility performance and regulatory approval status across regional markets with divergent material acceptance histories.
- Collamer:Proprietary collagen copolymer composition with intrinsic UV filtration and hydrophilic surface properties promoting aqueous humor flow. STAAR Surgical's direct surgeon training networks sustain premium positioning in the refractive channel where post-operative complication rates influence referral patterns.
- PMMA:Rigid polymethyl methacrylate with established optical clarity but requiring larger incision sizes. Supply chains cluster among German and Japanese specialty chemical producers, exposing manufacturers to input cost volatility and extended ISO 10993 biocompatibility testing timelines.
- Silicone:Flexible elastomeric alternatives with different refractive index characteristics and folding properties.
- Hydrogel:Water-absorbing polymers with alternative biocompatibility profiles for specific patient anatomies.
Collamer absorbs the bulk of installed capacity; Silicone is gaining share fastest in markets seeking alternative biocompatibility profiles.
Distribution Channel:
Customer type segmentation separates manufacturer-direct relationships from intermediated procurement with varying service and training bundles.
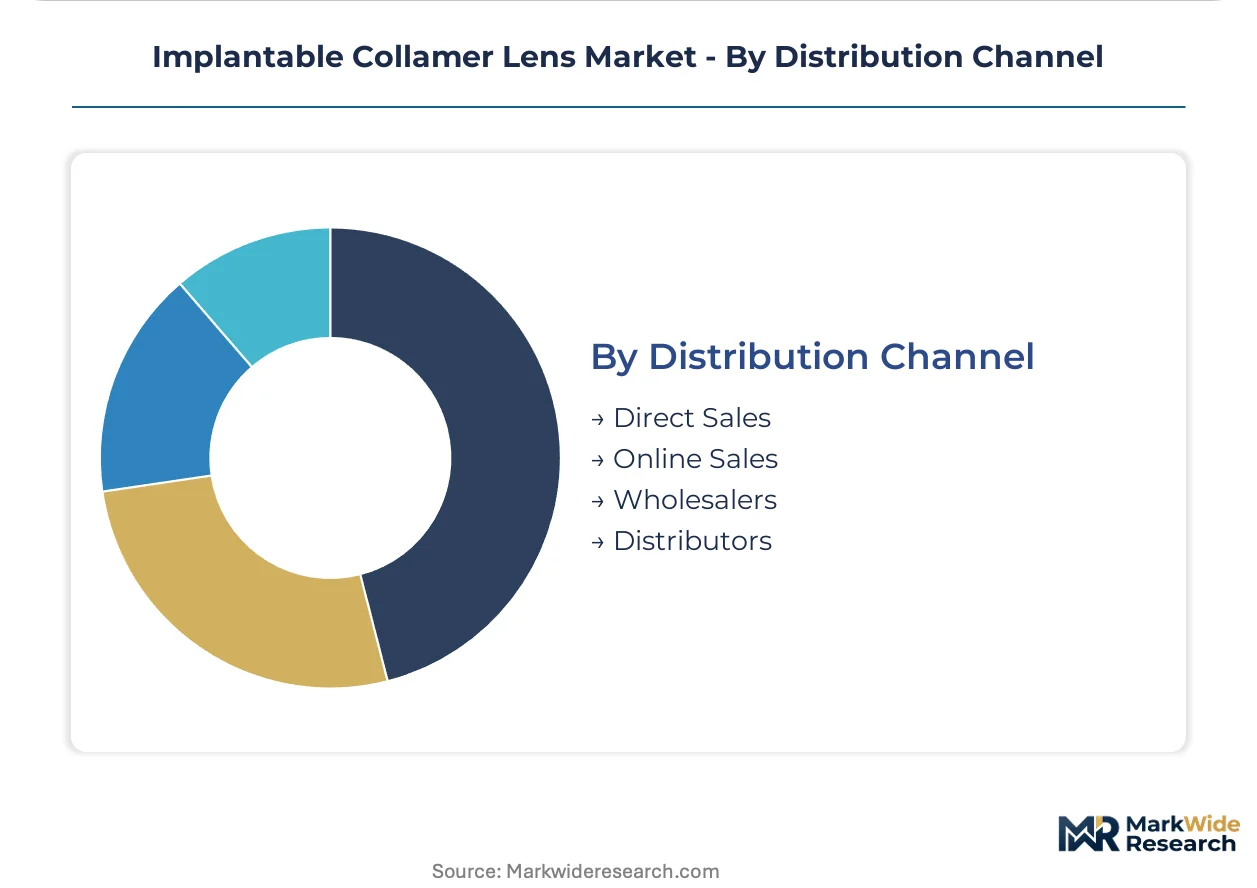
- Direct Sales:Manufacturer-employed field forces delivering surgeon certification programs, inventory consignment, and case support. Carl Zeiss Meditec anchors clinic loyalty through integrated diagnostic-to-surgery workflows that lock in recurring equipment and consumable purchases alongside lens supply.
- Distributors:Regional medical device specialists with established ophthalmology relationships and localized regulatory handling. Alcon leverages its cataract infrastructure to cross-sell refractive solutions through existing surgeon accounts and consolidated procurement contracts.
- Wholesalers:Broad-line medical supply intermediaries with limited technical support capabilities.
- Online Sales:Emerging direct-to-practice procurement platforms with standardized product configurations and reduced service overlays.
Direct Sales absorbs the bulk of installed capacity; Online Sales is expanding most quickly as procurement digitization reduces transaction friction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing concentration for implantable Collamer lenses tilts toward established optical device hubs in Germany and Switzerland, while consumption gravity pulls toward high-disposable-income markets in the United States and South Korea where premium refractive procedures command strong private-pay spending.
United States
Direct-to-consumer financing platforms and third-party patient lending services are dismantling upfront cost barriers for millennial and Gen Z demographics seeking elective vision correction. FDA PMA oversight mandates 18-36 month clinical trial requirements that filter market access to well-capitalized developers with established regulatory track records. Ambulatory surgical centers in California and Florida are installing dedicated refractive suites to capture shifting volumes from hospital-based settings.
Germany
Ophthalmology clinics in Bavaria and Baden-Württemberg are consolidating demand as EU MDR harmonization compresses time-to-market for next-generation toric variants. EMA and national BfArM oversight maintain stringent biocompatibility documentation requirements that extend review cycles for material formulation changes. The Stuttgart-Munich corridor anchors specialized diagnostic-to-surgery workflow providers serving cross-border patient flows from France and Switzerland.
South Korea
High-volume refractive clinics in Seoul and Busan are adopting swept-source OCT-based sizing systems to reduce post-operative vault-related complications. MFDS fast-track designations for novel toric ICL geometries are accelerating regulatory timelines for astigmatism-dominant patient populations. The Pangyo Techno Valley cluster hosts precision instrumentation manufacturers supplying anterior segment imaging equipment to regional ophthalmology chains.
India
Urban ophthalmology chains in Mumbai and Delhi are building dedicated ICL service lines for patients exceeding -8.00 diopter thresholds outside acceptable LASIK parameters. CDSCO medical device rules mandate local clinical investigation data for Class C and D implantable devices, extending registration timelines for imported lens systems. The Chennai-Bangalore corridor is emerging as a manufacturing hub for optical-grade polymethyl methacrylate intermediates.
Japan
PMDA breakthrough device pathways for customized astigmatic correction geometries are compressing approval timelines relative to standard pharmaceutical and medical safety bureau reviews. METI industrial policy supports domestic production of high-value-added ophthalmic devices through targeted R&D subsidies. The Tokyo-Osaka corridor concentrates specialized refractive surgery centers catering to presbyopia-correcting applications in aging professional demographics.
Implantable Collamer Lens Market Competitive Landscape
Capital-heavy producers with integrated manufacturing footprints compete with asset-light designers reliant on contract foundries for optical-grade polymer processing. The vendor base stratifies across three tiers: proprietary material specialists commanding premium positioning, diversified vision care conglomerates cross-selling through established surgeon accounts, and regional distributors handling localized regulatory compliance. Dominant competitive moves include backward integration into collagen copolymer supply chains and strategic partnerships with diagnostic equipment manufacturers to lock in clinic loyalty through integrated workflows.
Within the proprietary material tier, STAAR Surgical Company and Carl Zeiss Meditec exemplify divergent archetypes—one anchored in direct surgeon training networks and proprietary Collamer composition, the other in integrated diagnostic-to-surgery ecosystems. Alcon occupies a position representing diversified vision care portfolio breadth, leveraging cataract infrastructure to cross-sell refractive solutions through consolidated procurement contracts. These three entities collectively illustrate how competitive positioning in the implantable Collamer lens market depends on controlling either the material science layer, the clinical workflow layer, or the distribution scale layer.
| Leading Market Players |
|---|
| STAAR Surgical Company |
| Carl Zeiss Meditec |
| Bausch + Lomb |
| Alcon |
| Johnson & Johnson |
| Rayner Intraocular Lenses Limited |
| Hoya Surgical Optics |
| Aurolab |
| Abbott |
| Others |
Supply & Pricing Matrix
Captive supply of optical-grade collagen copolymer anchors premium positioning for proprietary material specialists while exposing asset-light competitors to input cost volatility and extended ISO 10993 biocompatibility testing timelines. This integration choice separates manufacturers with surgeon training network leverage from those competing on price in standardized spherical lens segments.
Pricing Analysis
Margin tightening in standard spherical ICLs reflects LASIK substitution pressure and inventory commoditization as ambulatory surgical centers consolidate procurement volumes. Three-tier pricing structure across premium toric, standard spherical, and economy PMMA legacy tiers separates manufacturers by customization depth and regulatory certification burden. Toric variants command pricing power through individualized axis alignment and limited qualified producers, while price sensitivity concentrates among millennial demographics financing procedures through third-party installment platforms.
Supply Chain Analysis
Returns and refurbishment flows remain minimal given implantable device classification, though explant analysis programs feed design iteration cycles for vault optimization. Optical-grade polymethyl methacrylate supply chains cluster among German and Japanese specialty chemical producers, drawing from rigid polymer feedstocks and precision molding equipment. Single-source vulnerability in collagen copolymer precursor supply creates concentration risk for non-integrated manufacturers. Distribution runs through manufacturer-direct field forces delivering surgeon certification and inventory consignment to high-throughput refractive clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swept-source OCT-based sizing systems are displacing manual biometry workflows, compressing revision rates and extending warranty exposure windows for legacy measurement protocols.
For Market Incumbents: Lock in clinic loyalty through integrated diagnostic-to-surgery workflows that bundle anterior segment imaging equipment with lens supply contracts. Deepen backward integration into collagen copolymer supply chains to defend margin position against PMMA raw material volatility. Prioritize FDA PMA supplement readiness for design modifications to preempt regulatory query cycles.
For New Entrants and Emerging Players: The premium-to-economy price-point gap in toric ICL customization opens white-space opportunity in mid-tier spherical correction for price-sensitive urban ophthalmology chains. Target India refractory myopia segments exceeding -8.00 diopter thresholds where LASIK exclusion criteria create addressable demand. Deploy direct-to-practice online procurement platforms with reduced service overlays to bypass incumbent field force infrastructure.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified vision care conglomerates seeking refractive portfolio expansion. Long-term viability hinges on regulatory track record durability and surgeon training network density rather than manufacturing scale alone. Monitor FDA PMA pathway duration trends and EU MDR technical file approval velocities as inflection indicators for capital deployment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Surgeon Certification Program Expansion | Manufacturer-specific training protocols constrain qualified operator pools and protect installed base from price competition. |
| Post-operative Monitoring Subscription Launch | Remote IOP tracking bundles create recurring revenue streams beyond initial device sales in private-pay markets. |
| Collagen Copolymer Backward Integration | Captive supply of proprietary material reduces biocompatibility testing timeline exposure and input cost volatility. |
| Ambulatory Surgical Center Partnership | Dedicated refractive suite installations capture shifting volumes from hospital infrastructure with lower per-procedure overhead. |
| Japan PMDA Fast-track Designation Pursuit | Breakthrough device pathways compress approval timelines for novel toric geometries in astigmatism-dominant populations. |
Research Methodology
Multi-period observation of refractive procedure volumes, regulatory submission timelines, and surgeon training network expansion anchored the trend analysis, supplemented by interviews with refractive surgery directors, ophthalmology clinic procurement managers, biomedical engineers, and GPO contracts specialists. Secondary validation drew from FDA PMA filings, EMA MDR technical documentation, MFDS approval databases, and hospital procurement contract disclosures. Bottom-up demand modeling across patient demographic cohorts triangulated against top-down manufacturer capacity and revenue estimates.
Input-output matrices mapped procedure volume drivers through optical design, clinical setting, material composition, and procurement pathway dimensions across the projection horizon. CAGRs were derived from segmented growth rate reconciliation against macroeconomic refractive surgery demand indicators. Industry-specific forecast inputs incorporated myopia prevalence trajectories among adolescent and young professional cohorts alongside ambulatory surgical center installation rates.
Inputs from regulatory filing databases and hospital procurement systems were available through the study window; gaps in real-time surgeon training completion rates and explant revision frequencies introduce uncertainty bands around market penetration assumptions. Practitioners should monitor FDA PMA supplement review cycle durations and EU MDR notified body capacity constraints for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Cardiac Rhythm Management (CRM) Devices Batteries Market
Medical Devices
Arthroscopy Visualization Systems Market
Medical Devices
Global Prosthetic Heart Valve Market
Medical Devices
Soft Tissue Market
Medical Devices
Clinical Trinocular Microscopes Market
Medical Devices
Global Breast Pumps Market
Medical Devices
Asia-Pacific Medical Suction Device Market
Medical Devices
Fluidics for Preclinical Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Vortex Mixer Market
Medical Devices
India Clear Aligners Market
Medical Devices
Dual Balloon Angioplasty Catheter Market
Medical Devices
Cardiac Poc Testing Devices Market
Medical Devices
Medical Machine Battery Market
Medical Devices
Flow Cytometry Products Market
Medical Devices
Tissue Embedding Center Market