
 Europe Surgical Microscopes Market | 2026-2036
Europe Surgical Microscopes Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Surgical Microscopes Market Insights
Equipment leasing and managed service contracts are reshaping competitive dynamics in Europe's surgical microscope sector, lowering capital barriers for mid-tier hospitals. Carl Zeiss Meditec AG leverages its captive optics manufacturing to sustain margin control across premium installations. Leica Microsystems anchors its position through specialized fluorescence imaging modules for neuro-oncology procedures. Olympus Corporation competes by extending its endoscopy service networks into integrated microscope-maintenance contracts.
Europe surgical microscopes are precision optical instruments employing apochromatic lens systems with motorized zoom ranges and integrated LED or fiber optic illumination for real-time tissue visualization during microsurgical procedures. These systems achieve resolutions below one micrometer with working distances of 200-400 millimeters, enabling surgeons to execute sutures and dissections at capillary scale. Digital documentation systems now represent the fastest-growing technology segment as hospitals mandate video archiving for training and liability protocols, while robot-assisted microscopes capture expanding share in neurosurgery despite premium positioning. Optical microscopes remain the mature volume base across ambulatory surgical centers where budget constraints dominate procurement committees.
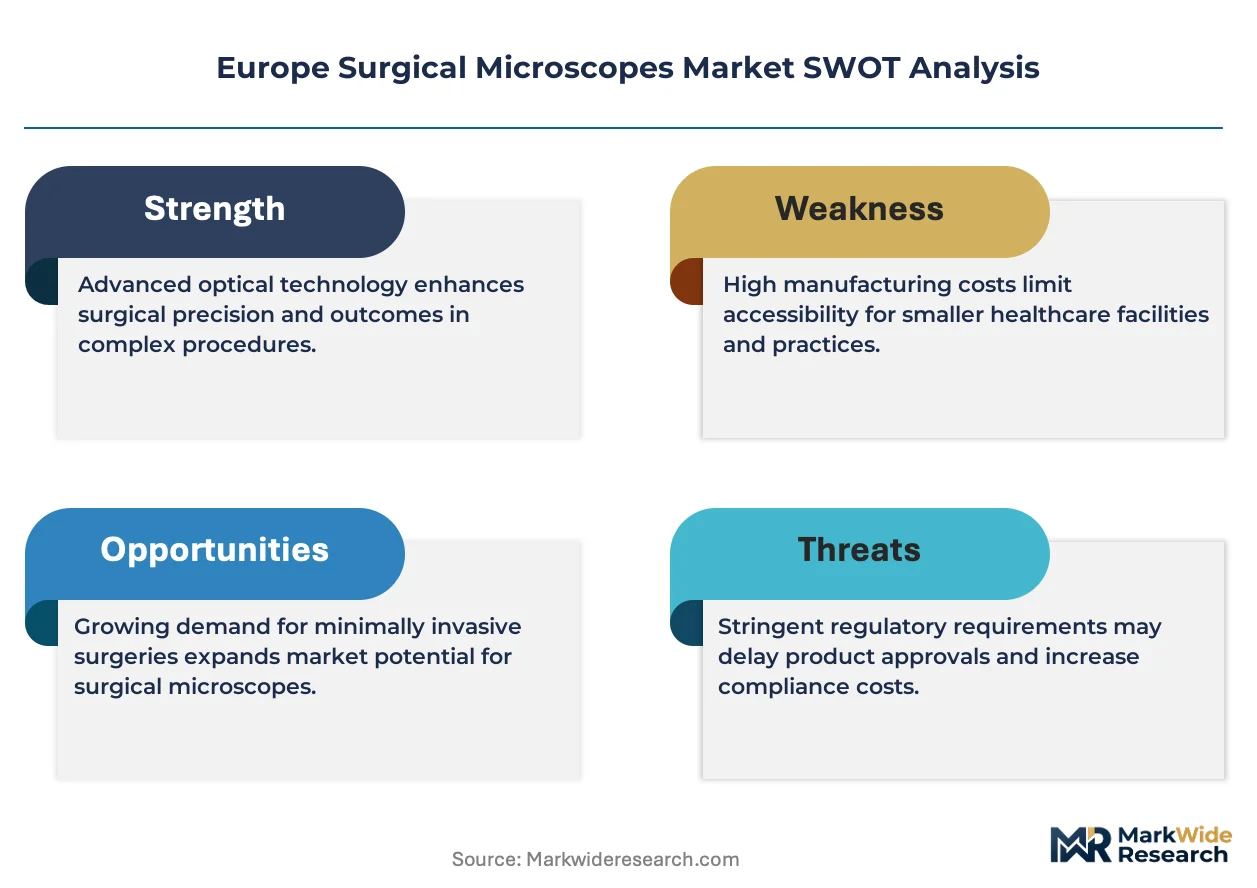
EMA device oversight and the EU MDR framework impose stringent clinical evidence requirements on Class IIa and IIb surgical microscopes, extending certification timelines and favoring established manufacturers with regulatory affairs infrastructure. CE marking under MDR Annex IX now demands annual surveillance audits that smaller competitors struggle to fund, concentrating market access among firms with dedicated European compliance teams. Stakeholders must monitor how notified body capacity constraints affect product registration pipelines and whether emerging AI-assisted image guidance triggers additional software classification under the EU AI Act.
Market Dynamics
Robot-assisted microscopes are restructuring capital allocation across European neurosurgical suites, compelling manufacturers to rebalance R&D spending between optical refinement and mechatronics integration.
Growth Catalysts
- EU MDR compliance mandates:Tightened clinical evidence requirements for Class IIb devices are filtering out marginal competitors and consolidating procurement around established suppliers with dedicated regulatory affairs teams.
- Digital documentation protocols:Hospital liability frameworks and surgical training accreditation standards now require video archiving capabilities, accelerating replacement cycles for legacy optical systems lacking integrated capture modules.
- German university hospital expansion:Centralized healthcare budgets in Baden-Württemberg and Bavaria are funding dedicated neurosurgical robotics programs, creating concentrated demand pockets for advanced microscope platforms.
Market Restraints
- Notified body capacity constraints:Limited EU MDR-designated auditors are extending product registration timelines to 18-24 months, freezing commercialization pipelines for mid-tier manufacturers lacking pre-existing CE portfolios.
- Apochromatic lens supply concentration:Precision optical glass fabrication concentrates among German and Japanese specialty suppliers, exposing assemblers to input cost volatility and single-source dependency risks.
- Fluorescence module technical limitations:Current indocyanine green imaging systems suffer from photobleaching artifacts during prolonged neurovascular procedures, restricting clinical confidence in real-time perfusion assessment.
Strategic Opportunities
- Poland and Czech Republic hospital modernization:EU cohesion funds are upgrading surgical infrastructure in Central European member states, creating first-mover advantages for vendors establishing localized service networks.
- EU AI Act software classification pathway:Emerging AI-assisted image guidance modules may trigger favorable regulatory treatment as assistive rather than autonomous devices, opening compliance arbitrage for early filers.
- Managed service contract penetration:Equipment leasing with bundled maintenance is lowering capital barriers for mid-tier French and Italian hospitals previously excluded from premium microscope procurement.
Industry Challenges
- Mechatronics engineering talent scarcity:Integration of robotic positioning with optical stability requires rare cross-disciplinary expertise in surgical instrumentation and precision motion control, constraining development velocity.
- Legacy system interoperability:Hospital information system integration demands for PACS connectivity and EMR data exchange are complicating deployments and extending commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Surgical Microscopes Market |
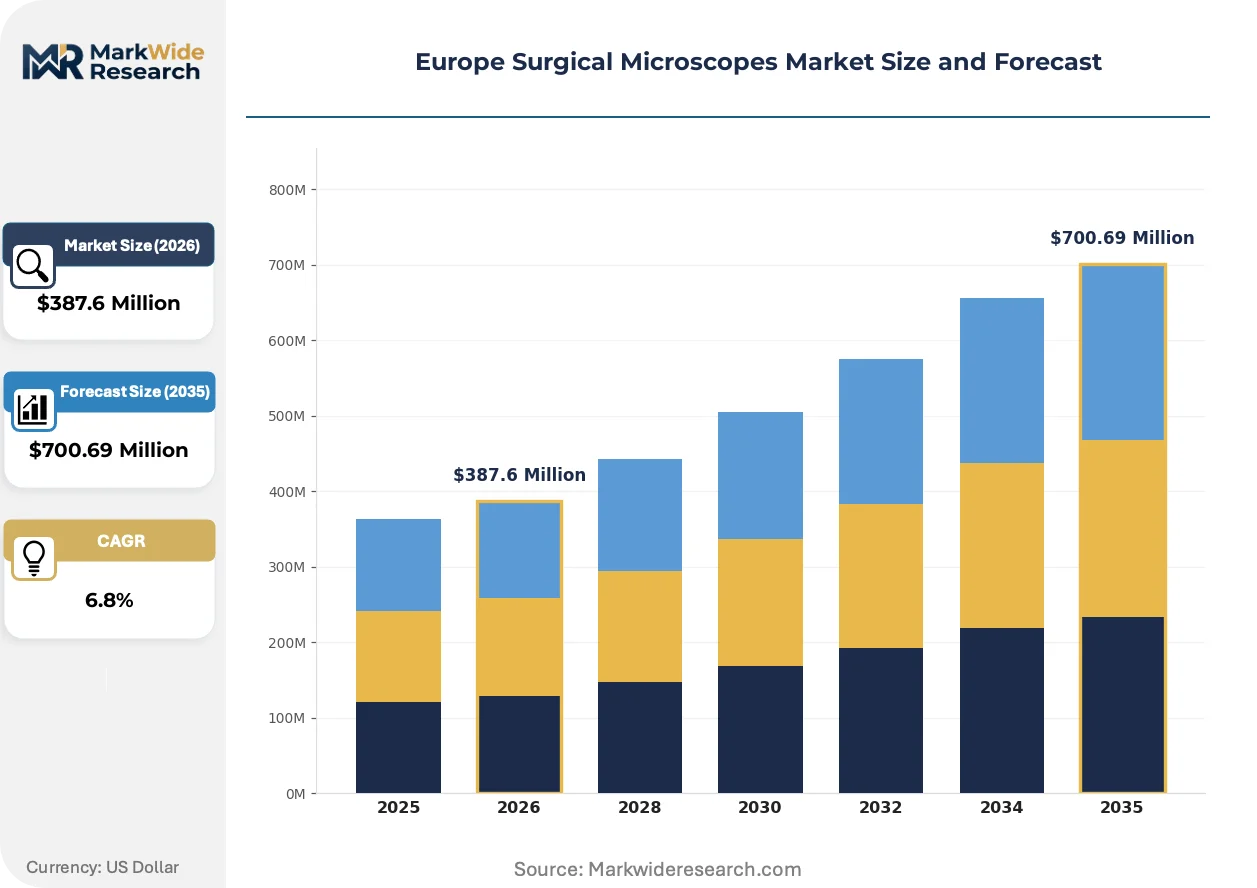
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Microscopes, Digital Microscopes, 3D Microscopes, Robot-Assisted Microscopes End User: Hospitals, Ambulatory Surgical Centers, Research Institutions, Clinics Application: Neurosurgery, Oncology, Plastic Surgery, Ear, Nose & Throat Technology: LED Illumination, Fiber Optic Illumination, Integrated Imaging, Digital Documentation |
| Companies Covered | Carl Zeiss Meditec AG, Leica Microsystems, Olympus Corporation, Haag-Streit Surgical GmbH, Alcon, Inc., Topcon Corporation, Takagi Seiko Co., Ltd., ARI Medical Technology Co., Ltd., Chammed Co., Ltd., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Surgical Microscopes Market Trends and Innovations
Digital fluorescence overlay systems and AI-enhanced image processing are compressing the capability gap between premium and mid-tier microscope platforms, democratizing advanced visualization while pressuring incumbent pricing architectures.
4K-3D exoscope systems are rendering obsolete traditional binocular eyepiece configurations in certain spinal and ENT microsurgical applications. Ambulatory surgical centers in the United Kingdom are adopting these platforms at accelerated pace to support minimally invasive procedure expansion. The shift is compressing addressable market volume for conventional optical microscopes in budget-constrained settings.
REACH restrictions on fluorinated greenhouse gases are forcing illumination subsystem redesigns across European microscope manufacturers. LED thermal management architectures are displacing legacy xenon and metal-halide fiber optic sources to maintain compliance with F-Gas Regulation phase-down schedules. German and Swiss assemblers are most affected, with product refresh cycles accelerating to meet 2027 benchmark obligations.
Service contract unbundling is disrupting traditional distributor economics in France and Spain. Independent third-party maintenance providers are capturing post-warranty optical alignment and illumination calibration work previously monopolized by manufacturer-affiliated networks. University hospitals in Paris and Barcelona are piloting multi-vendor service aggregation to reduce total cost of ownership across heterogeneous microscope fleets.
Europe Surgical Microscopes Market Segmentation
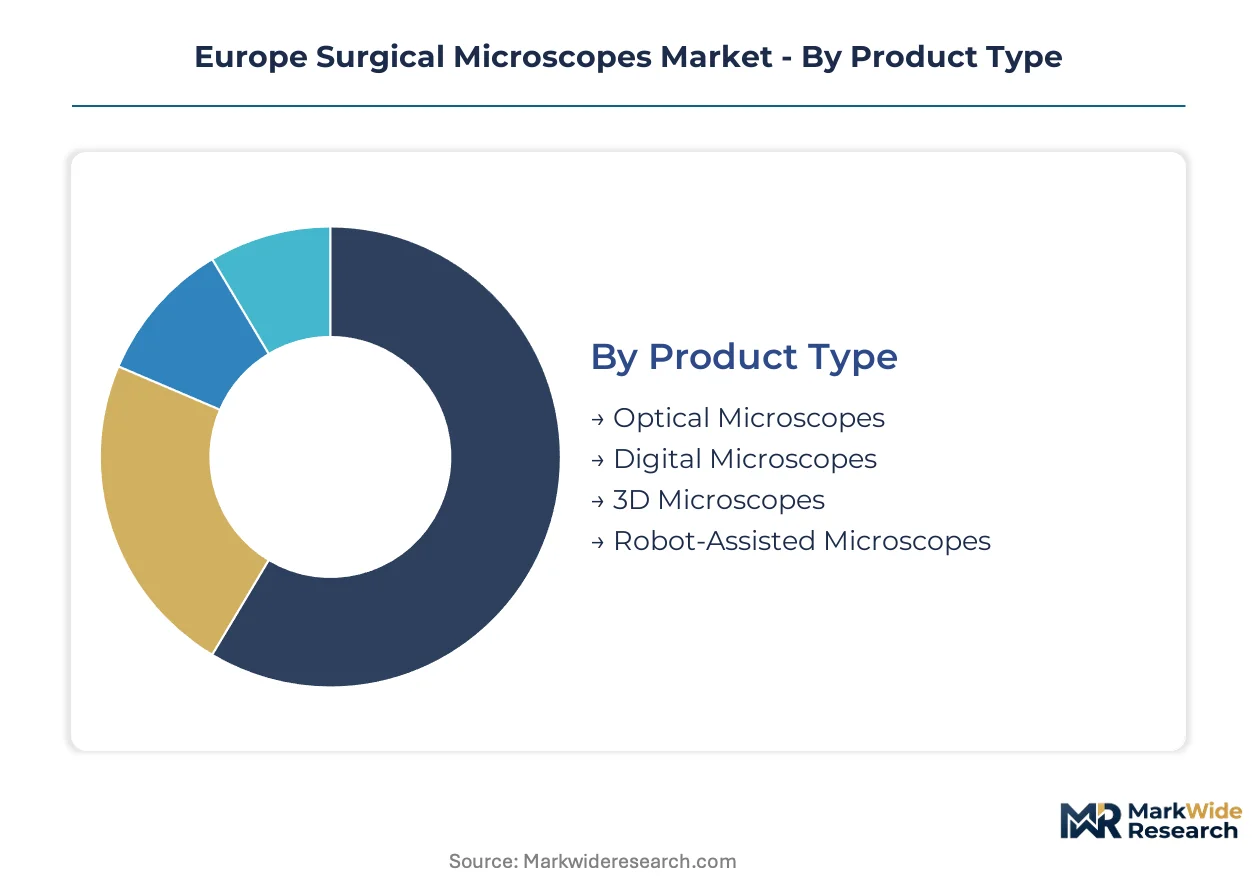
Segmentation in Europe's surgical microscope market reveals how procurement priorities diverge across clinical settings, from capital-intensive German university hospitals to budget-constrained ambulatory centers in Southern Europe. Understanding these fault lines helps manufacturers align product portfolios with distinct performance requirements and funding mechanisms.
Product Type:
The use-case spectrum spans legacy optical platforms through emerging robotic systems, with each tier serving distinct surgical complexity levels and capital availability.
- Optical Microscopes:Apochromatic lens systems with motorized zoom and 200-400mm working distances dominate ambulatory surgical centers across France and Italy where procurement committees prioritize proven reliability over advanced features. Budget constraints in these settings sustain replacement cycles for established binocular configurations despite limited digital integration.
- Robot-Assisted Microscopes:Mechatronic positioning platforms with sub-micrometer stability control are capturing concentrated demand from Baden-Württemberg and Bavarian university hospitals funding dedicated neurosurgical robotics programs. EMA device oversight and EU MDR compliance requirements favor established suppliers with regulatory affairs infrastructure for these Class IIb systems.
- Digital Microscopes:Integrated CMOS sensor arrays enabling real-time 4K capture serve training and liability documentation mandates in United Kingdom hospital systems.
- 3D Microscopes:Stereoscopic visualization platforms with head-mounted display compatibility address ENT and spinal applications in Dutch and Belgian surgical centers.
The dominant share belongs to Optical Microscopes, while Robot-Assisted Microscopes are expanding most quickly in neurosurgical suites.
End User:
Customer type determines pricing tolerance and service contract structure, from centralized European procurement frameworks to fragmented private clinic purchasing.
- Hospitals:Centralized healthcare budgets in Germany, France, and the United Kingdom fund capital-intensive installations with bundled maintenance agreements and multi-year service contracts. These institutions drive specifications for fluorescence imaging modules and PACS connectivity.
- Ambulatory Surgical Centers:Budget-constrained settings across Spain and Portugal prioritize leasing arrangements and managed service contracts to lower capital barriers for mid-tier optical platforms.
- Research Institutions:Academic medical centers in Switzerland and the Netherlands procure specialized configurations for experimental surgical protocols and training accreditation.
- Clinics:Private ophthalmology and plastic surgery practices in metropolitan Paris and Milan represent fragmented demand for compact tabletop systems.
Hospitals command the largest installed base, though Ambulatory Surgical Centers are climbing the fastest as minimally invasive procedure volumes expand.
Application:
Clinical specialization dictates resolution requirements and illumination specifications, with neurovascular procedures demanding the most sophisticated optical performance.
- Neurosurgery:Sub-micrometer resolution and fluorescence overlay capabilities for indocyanine green perfusion assessment concentrate demand in German and Scandinavian university hospitals. Technical limitations around photobleaching artifacts constrain confidence in real-time vascular mapping.
- Oncology:Specialized fluorescence imaging modules for tumor margin delineation anchor Leica Microsystems' competitive position in neuro-oncology procedures across French and Belgian centers.
- Plastic Surgery:Moderate magnification requirements with emphasis on ergonomic positioning support reconstructive microsurgical applications in private clinic settings.
- Ear, Nose & Throat:4K-3D exoscope configurations are displacing traditional binocular eyepieces in United Kingdom ambulatory centers performing minimally invasive sinus and laryngeal procedures.
Neurosurgery retains the premium technology concentration, while ENT applications are gaining share fastest through exoscope adoption.
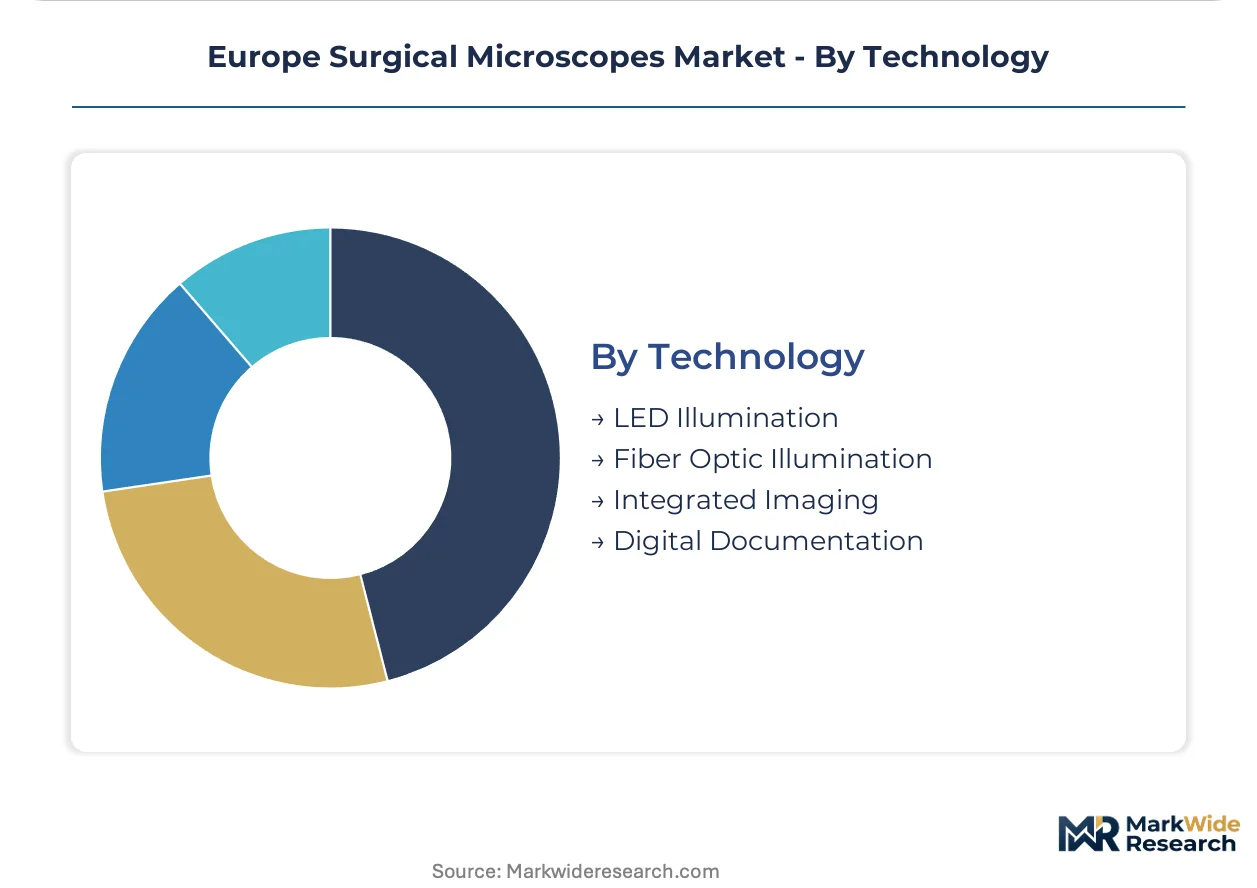
Technology:
Illumination and imaging architectures are restructuring compliance obligations and supply chain exposure across European assemblers.
- Digital Documentation:Integrated video archiving systems represent the steepest expansion trajectory as hospital liability frameworks and surgical training accreditation standards mandate capture capabilities. United Kingdom and German institutions lead replacement cycles for legacy systems lacking embedded recording.
- LED Illumination:Solid-state thermal management architectures are displacing legacy xenon and metal-halide sources to maintain REACH and F-Gas Regulation compliance, accelerating product refresh cycles for German and Swiss manufacturers.
- Fiber Optic Illumination:Halogen and xenon-based systems face phase-down pressure under EU fluorinated greenhouse gas restrictions.
- Integrated Imaging:Sensor-embedded optical paths enabling fluorescence overlay and augmented visualization support advanced neurovascular and oncologic applications.
LED Illumination holds the current installed base majority, though Digital Documentation is closing the gap fastest under regulatory and training mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
University hospitals and centralized procurement frameworks dominate purchasing patterns across European surgical microscope markets, with national healthcare budgets determining capital allocation intensity and technology tier access.
Germany
Baden-Württemberg and Bavarian university hospitals drive concentrated demand for robot-assisted neurosurgical platforms through dedicated robotics program funding. EU MDR Annex IX annual surveillance audits favor established suppliers with dedicated regulatory affairs infrastructure. The Stuttgart-Munich corridor anchors precision optics manufacturing clusters serving domestic and export markets.
France
Centralized hospital procurement through regional health agencies (ARS) concentrates capital equipment decisions in Île-de-France and Auvergne-Rhône-Alpes. ANSM device oversight aligns with EMA frameworks for Class IIb surgical microscope certification. Paris university hospitals pilot multi-vendor service aggregation to reduce total cost of ownership across heterogeneous microscope fleets.
United Kingdom
NHS England digital documentation mandates accelerate replacement cycles for legacy optical systems lacking integrated video capture. NICE technology appraisal frameworks influence adoption timelines for fluorescence imaging modules. London and Greater Manchester surgical centers lead 4K-3D exoscope deployment for minimally invasive ENT procedures.
Italy
Regional health authority budgets in Lombardy and Emilia-Romagna sustain mid-tier optical microscope procurement through leasing arrangements. REACH F-Gas Regulation phase-down schedules pressure illumination subsystem redesigns for Italian distributors. Milan private ophthalmology practices represent fragmented demand for compact tabletop configurations.
Poland
EU cohesion funds are modernizing surgical infrastructure in Masovian and Silesian Voivodeships, creating first-mover advantages for vendors establishing localized service networks. The national pharmaceutical regulator enforces CE marking conformity for imported optical surgical equipment. Warsaw and Kraków academic medical centers drive specifications for integrated imaging capabilities.
Europe Surgical Microscopes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered procurement segments. The vendor base clusters around three strategic archetypes: captive optics manufacturers leveraging backward integration, fluorescence imaging specialists, and endoscopy service network extenders. Dominant competitive moves include managed service contract penetration and regulatory affairs infrastructure consolidation under EU MDR timelines.
Among Germany-based precision optics fabricators, Carl Zeiss Meditec AG and Leica Microsystems occupy positions anchoring premium-tier market access. Olympus Corporation represents the service-network extension archetype, leveraging endoscopy maintenance infrastructure into integrated microscope contracts. These three exemplify how regulatory compliance scale and captive manufacturing capabilities concentrate competitive positioning.
| Leading Market Players |
|---|
| Carl Zeiss Meditec AG |
| Leica Microsystems |
| Olympus Corporation |
| Haag-Streit Surgical GmbH |
| Alcon, Inc. |
| Topcon Corporation |
| Takagi Seiko Co., Ltd. |
| ARI Medical Technology Co., Ltd. |
| Chammed Co., Ltd. |
| Others |
Pricing and Supply Chain Analysis
Single-source dependency on German and Japanese apochromatic lens fabricators determines both pricing tier spreads and supply chain shape across European surgical microscope assembly. REACH F-Gas Regulation compliance costs and EU MDR certification timelines widen the gap between premium robot-assisted platforms and mid-tier optical systems, while input concentration forces assemblers into long-term offtake arrangements with Schott AG and Hoya Corporation.
Pricing Analysis
Cost-plus contracts with optical glass indexation dominate procurement between German assemblers and Baden-Württemberg specialty suppliers. Pricing stratifies across premium, standard, and economy tiers based on CE marking tier under EU MDR Annex IX and bundled service contract depth. Cost compression in mid-tier optical systems is intensifying because ambulatory surgical centers in France and Italy are consolidating purchases through GPO frameworks. Academic medical centers in Bavaria show least price sensitivity, while Portuguese leasing-funded clinics represent the most margin-constrained buyer segment.
Supply Chain Analysis
Contract manufacturing concentrates with Jabil Healthcare and Plexus Corporation holding dedicated medical device capacity in Ireland and Poland. Precision optical glass fabrication centers on Germany and Japan, with LED illumination modules sourcing from South Korean and Taiwanese semiconductor foundries. Raw material dependencies include rare-earth-doped optical glass, high-purity germanium substrates, and ceramic thermal management components. Single-source vulnerability runs through Schott AG's dominance in apochromatic blank production. Distribution runs through manufacturer-affiliated service networks in Germany and France, with third-party maintenance providers gaining share in Spain and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe surgical microscope market is approaching a platform-economics inflection as PACS connectivity and EMR integration requirements force interoperability investments that favor ecosystem orchestrators over standalone hardware vendors.
For Market Incumbents: Insulate premium positioning by deepening backward integration into captive optics manufacturing and accelerating EU MDR regulatory affairs infrastructure consolidation. The threat of 4K-3D exoscope substitution in ENT applications demands defensive R&D allocation toward fluorescence overlay modules. Vertical integration into LED illumination thermal management represents the critical lever for margin defense against REACH compliance cost pass-through. For New Entrants and Emerging Players: Establish a beachhead in Poland and Czech Republic ambulatory surgical centers where EU cohesion fund modernization creates first-mover windows before incumbent service networks solidify. The most penetrable segment is mid-tier optical platforms with managed service contract bundling for hospitals outside the Stuttgart-Munich corridor. A software-companion go-to-market angle targeting AI-assisted image guidance compliance arbitrage under the EU AI Act offers regulatory differentiation. For Investors and Strategic Acquirers: EU MDR Annex IX annual surveillance audit requirements reshape the acquisition landscape toward targets with pre-existing CE portfolios and dedicated European compliance teams. Long-term viability favors vertically integrated precision optics fabricators with hospital system channel control and fluorescence imaging module IP. The signal to watch is notified body capacity expansion timelines, which would unlock frozen commercialization pipelines for mid-tier manufacturers.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Pathway | CE marking under Annex IX with annual surveillance audits secures market access for Class IIb robot-assisted platforms in German university hospitals. |
| Hospital System Partnership | Multi-year managed service contracts with Île-de-France regional health agencies lock in replacement cycle visibility and service revenue streams. |
| Software Companion Development | AI-assisted image guidance modules triggering favorable EU AI Act classification as assistive devices open pricing arbitrage against autonomous surgical robotics. |
| Backward Integration into Optics | Captive apochromatic lens production insulates margin control from Schott AG single-source pricing power and supply volatility. |
| Geographic Service Expansion | Localized technical networks in Masovian and Silesian Voivodeships capture EU cohesion fund-driven hospital modernization in Central Europe. |
Research Methodology
The analysis maps optical, robot-assisted, digital, and 3D microscope sub-sectors, each validated through hospital procurement committees, biomedical engineers, GPO contracts managers, and regulatory affairs leads at established manufacturers. Primary interviews with clinical end-users and distributor service heads combined with secondary validation from EMA device filings, EU MDR notified body audit records, hospital procurement databases, and REACH compliance disclosures. Bottom-up installation base modeling and top-down healthcare capital expenditure triangulation anchored volume estimates.
Assumptions held fixed include EU MDR regulatory timelines, REACH F-Gas Regulation phase-down schedules, and German university hospital robotics program funding commitments. Variables tested across the projection horizon encompass AI Act software classification pathways, notified body capacity expansion, and Poland-Czech Republic cohesion fund disbursement rates. Segmentation dimensions modeled cover product type, end user, application, and technology tier with geographic adoption pattern differentiation. CAGRs derived from replacement cycle analysis and capital budget elasticity to digital documentation mandates, with fluorescence imaging module penetration and LED illumination compliance conversion as key forecast inputs.
Sensitivities concentrate around notified body capacity constraints extending CE marking timelines and apochromatic lens supply disruptions from German-Japanese fabrication concentration. Forecasts embed assumptions about EU MDR enforcement consistency and hospital liability framework evolution. Quarterly review of EMA guidance updates, notified body designation expansions, and cohesion fund allocation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Devices Market
Medical Devices
Nerve Locator Stimulator Market
Medical Devices
Ophthalmoscopes Market
Medical Devices
Electronic Pill Market
Medical Devices
Dialysis Disposable Devices Market
Medical Devices
Spain Diabetes Devices Market
Medical Devices
Global Transcranial Magnetic Stimulators Market
Medical Devices
Abdominal Closure Systems Market
Medical Devices
Dissolving Microneedle Eye Patch Market
Medical Devices
Medical Electronics Market
Medical Devices
Disposable Contact Lenses Market
Medical Devices
Snoring Control Devices Market
Medical Devices
Polyether Ether Ketone (PEEK) Interbody Devices Market
Medical Devices
Connected Drug Delivery Devices Market
Medical Devices
US Patient Positioning Systems Market
Medical Devices
Global Transdermal Skin Patches Market