
 Contact Lens Inspection Equipment Market | 2026-2036
Contact Lens Inspection Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Contact Lens Inspection Equipment Market Outlook
Software-defined analytics modules is recalibrating how inspection equipment vendors monetize hardware deployments. Nidek Co., Ltd. leverages integrated data platforms to sustain recurring revenue from lens manufacturers. Topcon Corporation anchors its position through deep R&D intensity in optical metrology. Qioptiq differentiates via specialized illumination architectures for high-tolerance measurement.
Contact lens inspection equipment comprises automated and manual systems that evaluate optical power, surface integrity, dimensional accuracy, and material uniformity of soft and rigid lenses, typically resolving defects at micron-scale precision through interferometric or image-processing methods. The equipment serves manufacturers and quality control departments seeking to eliminate defective units before packaging. Automated inspection systems lead current deployment volumes among product types, while optical measurement tools capture expanding margins as toric and multifocal designs proliferate. Image processing technology dominates installed bases, though 3D profiling grows fastest where complex geometries require full-surface mapping rather than spot checks.
FDA quality system regulations and ISO 13485 medical device standards shape product validation requirements, compelling manufacturers to document traceable inspection records for every lens batch. The EPA and OSHA frameworks further influence equipment design where chemical handling or laser safety protocols apply. Stakeholders must monitor how evolving MDR obligations in Europe and tightening China's NMPA device classifications reshape compliance verification workflows and capital allocation priorities.
Market Dynamics
Automated optical inspection systems are compressing the operational gap between high-volume soft lens production and precision rigid gas-permeable manufacturing, forcing equipment vendors to reconcile throughput demands with micron-scale defect detection requirements.
Growth Catalysts
- ISO 13485 medical device mandates:Batch traceability requirements in Europe and North America compel manufacturers to deploy inspection systems with integrated data logging capabilities.
- Silicone hydrogel material proliferation:Complex oxygen permeability specifications in toric and multifocal designs necessitate advanced surface integrity verification beyond traditional spot-check protocols.
- South Korean manufacturing clusters:Concentrated contact lens production around Daejeon and Gwangju drives localized equipment procurement and technical service contracts.
Market Restraints
- Precision optics input volatility:German and Japanese suppliers dominate interferometer-grade lens and sensor sourcing, exposing buyers to extended lead times and currency fluctuation risks.
- MDR compliance documentation burden:European manufacturers face expanded technical file requirements for inspection equipment validation, extending sales cycles by 6-12 months.
- Manual inspection labor arbitrage:Low-wage assembly economies in Vietnam and Indonesia sustain hybrid quality workflows that delay full automation adoption.
Strategic Opportunities
- India's PLI scheme for medical devices:Domestic manufacturing incentives create procurement pathways for inspection equipment vendors establishing local assembly or partnership structures.
- 3D profiling-photogrammetry convergence:Combined full-surface mapping technologies enable single-platform inspection of complex scleral and orthokeratology lens geometries.
- Direct-to-manufacturer digital channels:Equipment configurators and remote commissioning protocols reduce distributor dependency in established markets.
Industry Challenges
- Interferometry specialist scarcity:Optical metrology expertise concentration in aging European and Japanese engineering workforces constrains vendor expansion and service scaling.
- FDA 510(k) pathway complexity:Substantial equivalence determinations for next-generation inspection algorithms require extensive predicate device analysis and clinical validation data.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Contact Lens Inspection Equipment Market |
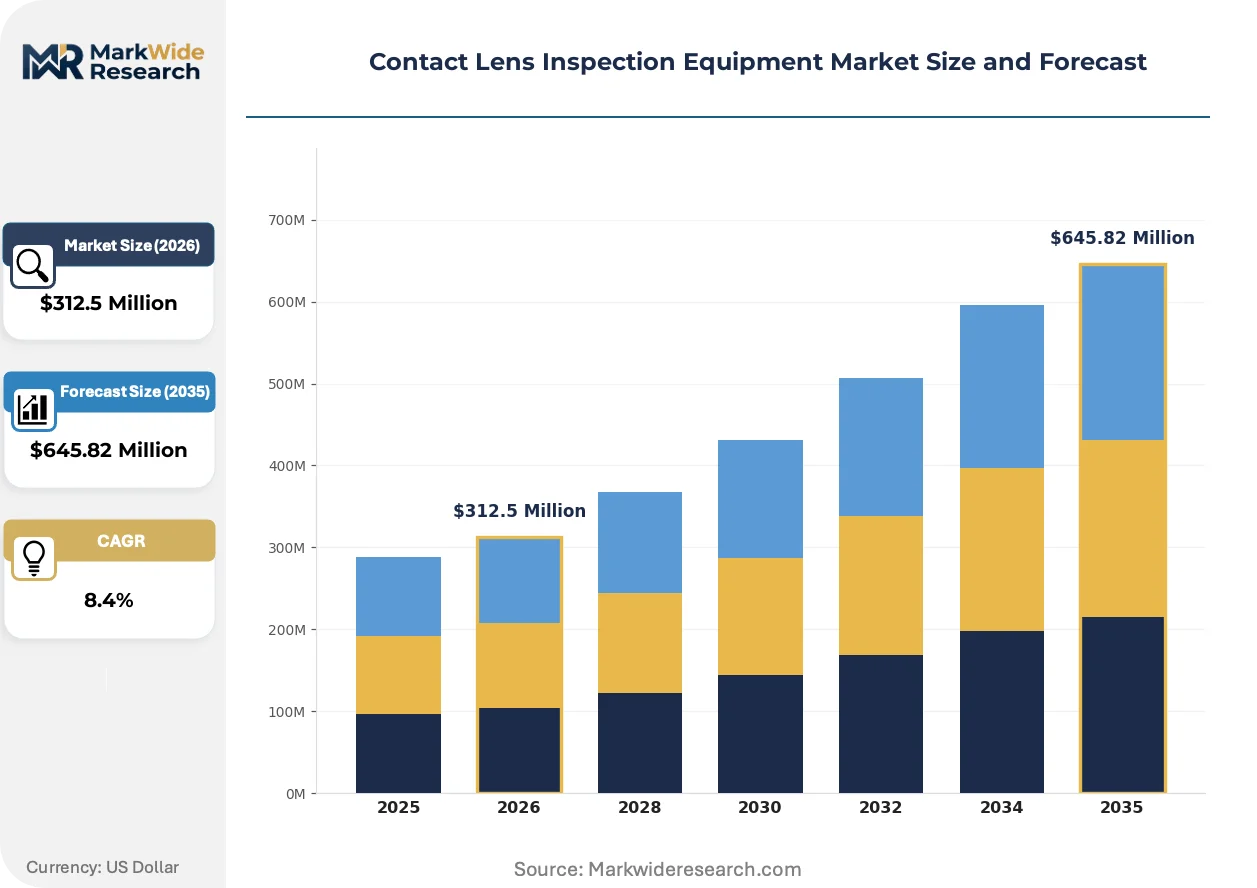
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $645.82 Million |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Automated Inspection Systems, Manual Inspection Devices, Optical Measurement Tools, Surface Roughness Analyzers End Use: Manufacturers, Research Laboratories, Quality Control Departments, Educational Institutions Technology: Image Processing, Optical Inspection, Laser Scanning, 3D Profiling Application: Quality Assurance, Research & Development, Product Testing, Compliance Verification |
| Companies Covered | Optikos Corporation, Optimec Limited, Neitz Instruments, Rotlex, Contact Lens Technologists, Qioptiq, Nidek Co., Ltd., Topcon Corporation, Essilor Instruments USA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Contact Lens Inspection Equipment Market Strategic Shifts
Edge-deployed machine vision architectures are redistributing computational loads away from centralized quality servers, enabling real-time defect classification at production line speeds without network latency dependencies.
Embedded GPU-accelerated inference engines within inspection head units are decentralizing quality decision-making from plant-level MES systems to individual measurement stations. Mid-tier Chinese and Taiwanese lens manufacturers are adopting these architectures fastest, bypassing legacy SCADA integration requirements. This shift is decentralizing vendor competitive advantage from software platform dominance toward hardware-optimized inference performance.
EU MDR Article 10 technical documentation requirements now mandate design verification evidence for automated inspection equipment used in Class IIa and higher lens manufacturing. Equipment suppliers must provide validated measurement uncertainty budgets and software lifecycle documentation. Toric lens producers in Germany and Italy are absorbing the highest compliance costs, driving preference toward vendors with established notified body relationships.
Subscription-based analytics modules are displacing perpetual software licenses in equipment procurement negotiations. Lens manufacturers in Japan and South Korea prioritize vendors offering consumption-priced defect trend analysis and predictive maintenance algorithms. This reconfiguration is most visible among silicone hydrogel specialists managing complex multi-curve production lines where downtime costs exceed capital amortization schedules.
Contact Lens Inspection Equipment Market Segmentation
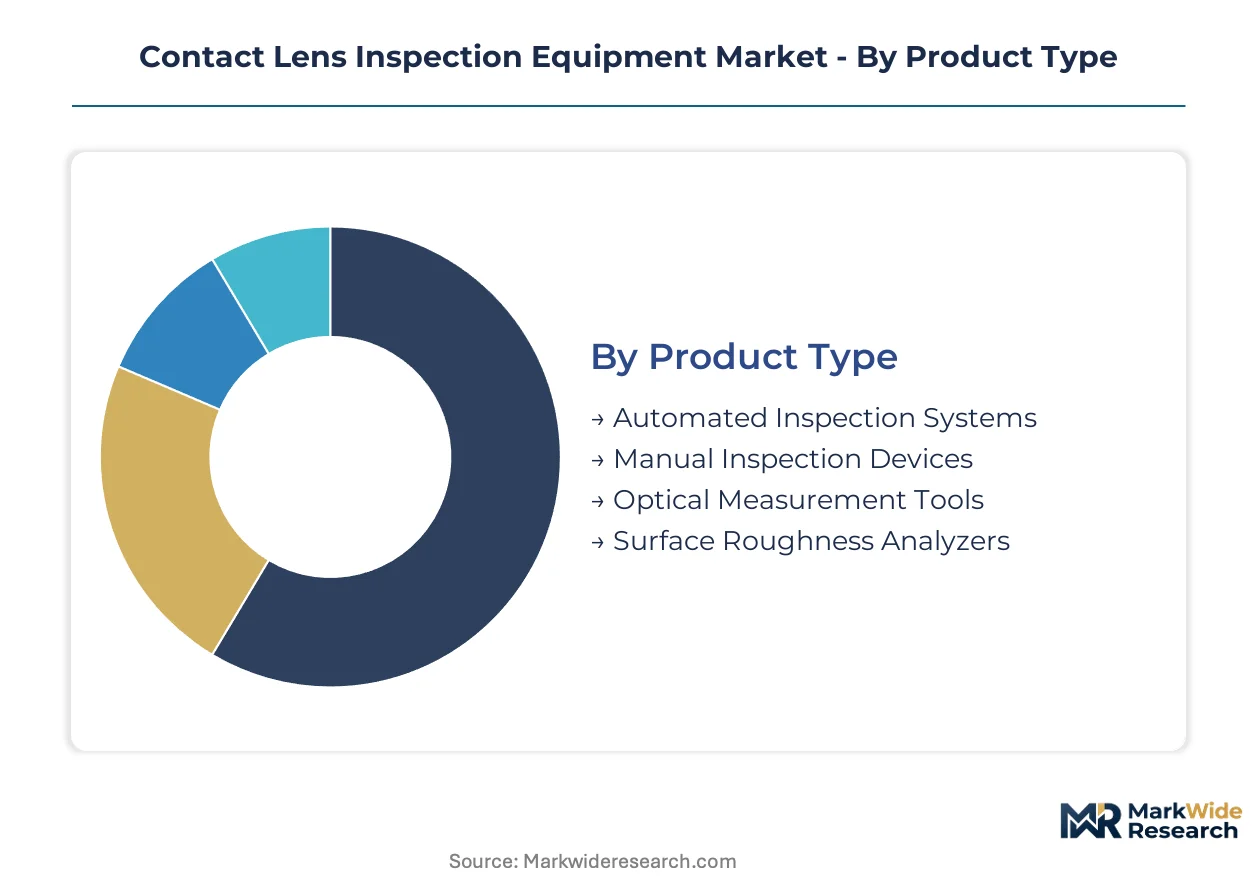
Equipment segmentation in contact lens inspection reflects divergent capital deployment strategies across silicone hydrogel specialists and rigid gas-permeable manufacturers. Upgrade cycles accelerate where toric and multifocal designs demand micron-scale surface mapping capabilities beyond legacy spot-check protocols.
Product Type:
Replacement timelines stretch from 5-7 years for mechanical platforms to 3-4 years for vision-system architectures as inference hardware evolves.
- Automated Inspection Systems:Conveyor-integrated platforms deploy interferometric sensors and GPU-accelerated defect classification for high-volume soft lens lines. South Korean manufacturers around Daejeon drive procurement of these systems as FDA batch traceability mandates tighten documentation requirements.
- Optical Measurement Tools:Benchtop power mapping and wavefront analysis instruments verify toric axis alignment and multifocal add power accuracy. German and Italian toric specialists absorb the highest compliance costs under EU MDR Article 10 technical documentation rules.
- Manual Inspection Devices:Operator-dependent stereomicroscopes and slit-lamp adaptations serve low-volume rigid lens workshops and educational training facilities.
- Surface Roughness Analyzers:Stylus and optical profilometers quantify nanometer-scale texture variations critical for silicone hydrogel oxygen permeability performance.
Automated Inspection Systems sit at the top of the volume ranking, with Optical Measurement Tools climbing the fastest.
End Use:
Customer-type concentration shapes service contract structures and software subscription penetration rates across the installed base.
- Manufacturers:Production-scale deployments integrate inspection stations with MES and ERP systems for real-time yield optimization. Chinese and Taiwanese silicone hydrogel specialists adopt edge-deployed machine vision architectures fastest, bypassing legacy SCADA integration.
- Quality Control Departments:Standalone validation labs require documented measurement uncertainty budgets for ISO 13485 compliance and customer audit defense.
- Research Laboratories:Prototyping facilities prioritize flexibility over throughput, driving demand for reconfigurable optical benches and custom illumination geometries.
- Educational Institutions:Training programs purchase refurbished manual systems and entry-level automated platforms for technician certification curricula.
Manufacturers command the dominant share of capital allocation, with Research Laboratories expanding most quickly as scleral and orthokeratology innovation accelerates.
Technology:
Technology selection determines capital intensity, operator skill requirements, and compatibility with existing plant automation infrastructure.
- Image Processing:CCD and CMOS-based area scan systems dominate installed bases through mature algorithm libraries and interoperable software stacks. Mid-tier Asian lens manufacturers leverage these proven architectures for immediate deployment without specialized optical engineering support.
- 3D Profiling:Structured light and confocal chromatic sensors generate full-surface elevation maps for complex scleral lens geometries. Japanese and South Korean producers managing multi-curve production lines prioritize these platforms where downtime costs exceed capital amortization schedules.
- Optical Inspection:Interferometric and Shack-Hartmann wavefront systems deliver highest-precision power and aberration measurement for premium toric and multifocal validation.
- Laser Scanning:Triangulation and time-of-flight methods provide rapid coarse geometry verification for initial forming and edge profiling operations.
Image Processing maintains the broadest installed footprint, while 3D Profiling gains share fastest as complex lens geometries proliferate.
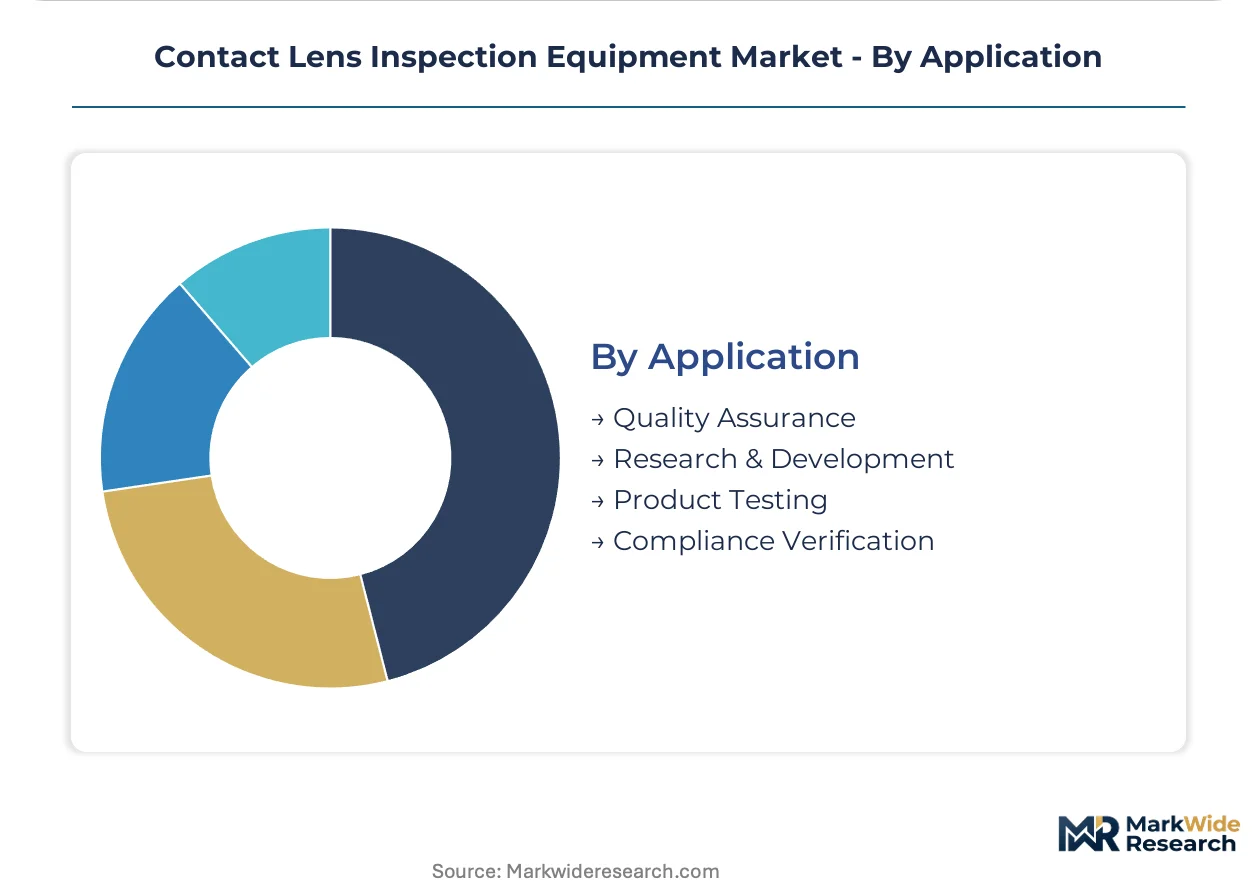
Application:
Application focus dictates equipment specification, validation documentation depth, and recurring software revenue potential.
- Quality Assurance:In-line and at-line inspection stations enforce statistical process control with automated reject routing and batch segregation protocols. FDA quality system regulations and ISO 13485 medical device standards compel comprehensive data logging for every production lot.
- Compliance Verification:Final release testing generates certificates of analysis with traceable metrology chain documentation for regulatory submission. European manufacturers face expanded technical file requirements under MDR, extending sales cycles for validation-intensive installations.
- Research & Development:Formulation and design iteration labs require rapid reconfiguration capabilities and exploratory data analysis tools.
- Product Testing:Accelerated aging and wear simulation studies demand specialized environmental chambers integrated with periodic optical measurement.
Quality Assurance anchors the revenue base, with Compliance Verification expanding most steeply as notified body scrutiny intensifies across Europe and China.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's inspection equipment procurement outpaces Germany's toric lens validation investments by a factor of three, while South Korean manufacturing clusters absorb specialized optical metrology systems at rates unmatched elsewhere.
United States
FDA quality system regulations and batch traceability mandates drive automated inspection deployments across Massachusetts and California lens fabrication facilities. The EPA and OSHA frameworks further constrain equipment design where laser safety protocols apply. Boston-area optical manufacturers integrate edge-deployed machine vision architectures to bypass legacy SCADA requirements.
Germany
EU MDR Article 10 technical documentation obligations impose the highest compliance costs on toric and multifocal lens producers. German notified body relationships confer competitive advantage to established equipment vendors. Stuttgart and Munich industrial corridors concentrate precision optics engineering expertise for interferometer-grade sensor development.
China
NMPA device classification tightening and domestic manufacturing scale propel inspection equipment procurement in Jiangsu and Zhejiang provinces. The country's dual carbon goals influence energy-efficient equipment specifications. Suzhou and Hangzhou lens fabrication clusters adopt GPU-accelerated defect classification faster than European counterparts.
South Korea
MFDS regulatory alignment with FDA standards accelerates validation-intensive equipment sales cycles. Concentrated contact lens production around Daejeon and Gwangju drives localized technical service contracts. Seoul Capital Area headquarters anchor regional procurement decisions for multi-curve silicone hydrogel lines.
Japan
METI industrial standards and PMDA medical device frameworks shape equipment validation requirements for domestic lens manufacturers. Aging optical metrology workforces in Osaka and Nagoya constrain vendor service scaling. Yokohama-based precision instrument specialists maintain captive supply relationships for interferometer components.
Contact Lens Inspection Equipment Market Competitive Environment
Top-tier vendors anchor premium optical metrology segments, while mid-tier Asian specialists capture volume deployments through hardware-optimized inference performance. The vendor base stratifies across three tiers: precision interferometry specialists with notified body relationships, vision-system integrators serving high-throughput soft lens lines, and regional assemblers targeting emerging market price sensitivity. Strategic moves concentrate on backward integration into sensor sourcing and subscription-based analytics module monetization.
Within the precision-tier segment, Nidek Co., Ltd. and Topcon Corporation exemplify established Japanese optical instrumentation houses with deep R&D intensity in wavefront analysis. Qioptiq occupies a position representing European specialists in specialized illumination architectures for high-tolerance measurement applications.
| Leading Market Players |
|---|
| Optikos Corporation |
| Optimec Limited |
| Neitz Instruments |
| Rotlex |
| Contact Lens Technologists |
| Qioptiq |
| Nidek Co., Ltd. |
| Topcon Corporation |
| Essilor Instruments USA |
| Others |
Value Chain & Pricing Dynamics
Interferometer-grade optical components sourced from German and Japanese precision manufacturers flow through three pricing tiers before reaching lens fabrication facilities, with certification-grade sensors commanding premiums over commercial-grade alternatives in FDA-regulated deployments.
Pricing Analysis
Capacity additions in Chinese machine vision component manufacturing are reshaping price floors for mid-tier automated inspection platforms. Three-tier pricing structure across premium, standard, and economy levels separates notified body-validated systems from commercial-grade alternatives, with ISO 13485 certification tier and after-sales service bundling as primary differentiation drivers. Cost compression in economy-tier equipment is intensifying because domestic Chinese suppliers are bypassing legacy distributor markups. Research laboratories and educational institutions exhibit highest price sensitivity, while silicone hydrogel specialists managing multi-curve production lines prioritize performance over capital outlay.
Supply Chain Analysis
Ocean freight volatility from Yokohama and Stuttgart to Shanghai and Busan injects cost uncertainty into capital equipment delivery schedules. Precision interferometer lenses draw from Japan, Germany, and Switzerland, while CMOS sensors and GPU accelerators source from Taiwan and South Korea. Single-source vulnerability concentrates in Shack-Hartmann wavefront sensor arrays produced by a handful of Osaka-area specialists. Distribution runs through authorized technical service partners who bundle installation validation with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The contact lens inspection equipment market functions as a regulatory compounder, with EU MDR Article 10 technical documentation obligations extending equipment validation cycles and locking in vendor relationships through notified body familiarity.
For Market Incumbents: Anticipate margin compression from GPU-accelerated edge architectures developed by Chinese vision-system specialists. Defend position by deepening backward integration into sensor sourcing through captive supply relationships with Yokohama precision optics houses. Prioritize subscription-based analytics module development to displace perpetual license revenue models threatened by hardware-optimized inference competitors. For New Entrants and Emerging Players: Enter via India's PLI scheme for medical devices, where domestic manufacturing incentives create procurement pathways without established distributor relationships. Target research laboratories prototyping scleral and orthokeratology lenses, as this segment expands fastest and prioritizes flexibility over brand heritage. Pursue direct-to-manufacturer digital channels with remote commissioning protocols to bypass entrenched technical service networks in South Korea and Japan. For Investors and Strategic Acquirers: Consolidation pressure builds where aging optical metrology workforces in Osaka and Nagoya constrain vendor service scaling. Long-term viability favors precision-tier specialists with established notified body relationships over volume-oriented vision-system integrators facing hardware commoditization. Monitor MFDS regulatory alignment with FDA standards as inflection signal for accelerated validation-intensive equipment sales cycles in South Korean manufacturing clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Notified Body Partnership Deepening | EU MDR Article 10 compliance costs favor vendors with pre-validated technical documentation packages. |
| Edge-Deployed Machine Vision Launch | GPU-accelerated inference engines decentralize quality decision-making from plant-level MES systems. |
| Subscription Analytics Module Development | Consumption-priced defect trend analysis displaces perpetual software licenses in Japanese and South Korean negotiations. |
| Precision Optics Backward Integration | Captive supply of interferometer-grade components mitigates lead time exposure from German and Japanese suppliers. |
| Remote Commissioning Protocol Expansion | Direct-to-manufacturer digital channels reduce distributor dependency in established North American and European markets. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Interviews with contact lens manufacturing executives, quality control department heads, biomedical engineers, and GPO contracts managers anchored demand-side perspectives. Secondary sources included FDA 510(k) filings, NMPA device classification databases, ISO 13485 certification registries, and customs trade data for precision optical component flows. Bottom-up equipment deployment estimates triangulated against top-down market sizing derived from lens production volume data.
Granularity-level modeling addressed product type, end use, technology, and application dimensions across the projection horizon. CAGRs were derived from segment-level growth trajectory analysis incorporating regulatory milestone timing and capital expenditure cycle patterns. Forecast inputs included silicone hydrogel material adoption curves, toric and multifocal design proliferation rates, and notified body validation backlog estimates.
Inputs from regulatory filing databases and manufacturing facility announcements were available through the study window; gaps in private capital expenditure plans introduce uncertainty bands around equipment procurement timing assumptions. Forecasts reflect documented assumptions regarding MDR implementation pacing and NMPA classification tightening schedules. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Equipment
Thermal Cycler Market
Medical Equipment
Southern Europe and Middle East Medical Robotics Market
Medical Equipment
Next Generation Centrifuge Market
Medical Equipment
Urodynamic Equipment and Consumables Market
Medical Equipment
Medical Equipment Rental Market
Medical Equipment
Stereotactic Biopsy Tables Market
Medical Equipment
Global Medical Device Reprocessing Market
Medical Equipment
Tanning Units Market
Medical Equipment
Global Medical Lighting Technologies Market
Medical Equipment
US Medical Carts Market
Medical Equipment
Blood Banking Equipment Market
Medical Equipment
Medical Computer Carts Market
Medical Equipment
Hospital-at-Home Equipment Rental Market
Medical Equipment
Medical Vending Machines Market
Medical Equipment
PCR Plate Sealer Market
Medical Equipment
US Radiotherapy Market