
 Microscope Market | 2026-2036
Microscope Market Size, Share, and Industry Trends Forecast 2026-2036
Microscope Market Intelligence
Subscription-based software-defined imaging is repositioning how microscope vendors capture recurring revenue from hardware installations. Thermo Fisher Scientific leverages its embedded analytical software suites to sustain high-margin service contracts across electron microscopy fleets. Nikon Corporation anchors its competitive stance in Asia-Pacific life sciences through localized service infrastructure and application-specific training programs. Olympus Corporation differentiates via endoscope-adjacent optical expertise that extends into advanced fluorescence workstations for clinical research.
A microscope is an instrument that uses lenses or electron beams to magnify specimens beyond the resolution limit of the unaided eye, with optical variants achieving up to approximately two thousand times magnification and electron microscopes reaching sub-angstrom resolution through electromagnetic lensing. Its primary commercial purpose spans quality verification in semiconductor fabrication, cellular pathology diagnostics, and materials failure analysis. Electron microscope systems command the largest installed-value base among product categories due to their capital intensity and specialized facility requirements. Digital microscope adoption accelerates fastest in pharmaceutical quality-control environments where networked image archiving satisfies regulatory audit trails. Scanning probe microscopy occupies a narrower but defensible margin pool in nanotechnology research institutions requiring atomic-scale surface mapping.
FDA quality-system regulations for medical-device manufacturing shape optical-inspection requirements, while ISO 17025 laboratory accreditation standards govern calibration protocols that vendors must support. REACH chemical-substance restrictions in Europe constrain the mercury-vapor lamp supply chain, accelerating LED-illumination retrofit demand across fluorescence-installed bases. Stakeholders must monitor how AI-assisted image-analysis modules trigger new medical-device classification debates at FDA and parallel agencies, since software-as-diagnostic-tool pathways could reshape vendor liability and service-attachment models independently of hardware refresh cycles.
Market Dynamics
Semiconductor node shrinkage below three nanometers is forcing inspection labs to replace optical systems with electron microscopy platforms, compressing replacement cycles and redrawing vendor competitive boundaries.
Growth Catalysts
- Sub-3nm Semiconductor Fabrication:Taiwan and South Korean foundries are accelerating electron microscope procurement to resolve atomic-scale defect detection in advanced logic chips.
- FDA Device-Clearance Pathways:Tightened quality-system regulations for medical-device manufacturing are mandating higher-resolution optical inspection systems across US-based production facilities.
- LED-Illumination Retrofit Mandates:REACH chemical-substance restrictions across Europe are eliminating mercury-vapor lamp supply chains, forcing fluorescence-installed base upgrades.
Market Restraints
- Capital Intensity Barriers:Electron microscope installations require specialized vibration-isolated facilities and climate-controlled cleanrooms, restricting deployment to well-capitalized institutions.
- Supply Concentration Risk:Precision-optics manufacturing clusters in Oberkochen and Jena, Germany, create single-source dependencies for high-NA objective lenses.
- Technical Limitation:Optical microscopy remains fundamentally constrained by the Abbe diffraction limit, blocking resolution gains in live-cell imaging without fluorophore engineering.
Strategic Opportunities
- AI-Assisted Image Analysis:Software-as-diagnostic-tool pathways at FDA and parallel agencies are creating new service-attachment revenue models independent of hardware refresh cycles.
- Pharmaceutical Quality-Control Networks:Digital microscope adoption is accelerating where networked image archiving satisfies regulatory audit trails and enables distributed quality verification.
- ISO 17025 Laboratory Accreditation:Calibration protocol mandates are expanding vendor service contract scopes into recurring revenue streams across analytical laboratories.
Industry Challenges
- Electromagnetic Lens Specialist Shortage:Electron microscope maintenance and operation require rare expertise in high-voltage systems and vacuum engineering, constraining fleet utilization rates.
- Legacy System Integration Friction:Pharmaceutical quality-control environments face complex data-format migrations when connecting new digital microscopy platforms to established LIMS infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Microscope Market |
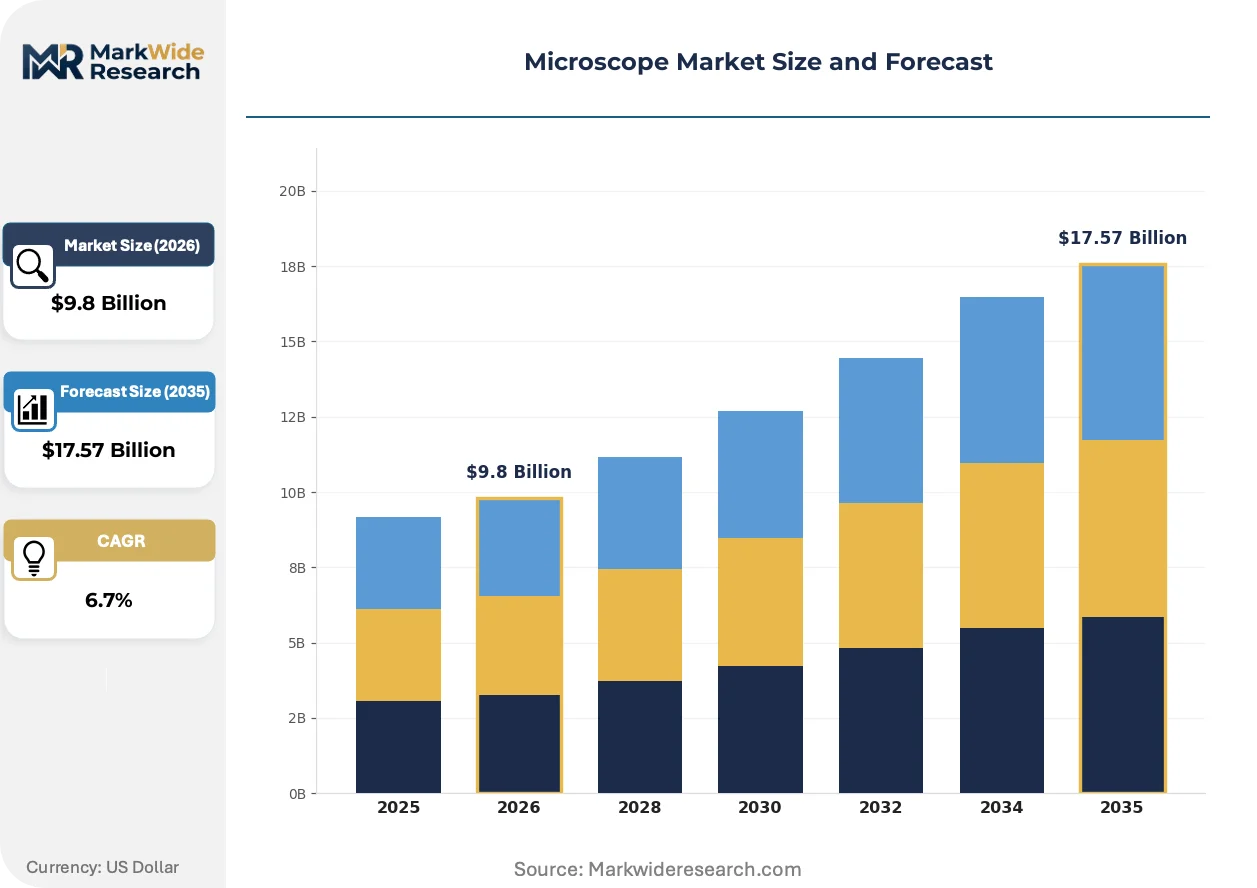
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $17.57 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Microscope, Electron Microscope, Fluorescence Microscope, Digital Microscope, Scanning Probe Microscope Technology: Confocal, Phase Contrast, Transmission Electron, Scanning Electron, Atomic Force, Polarizing Application: Life Sciences Research, Semiconductor Inspection, Material Science, Forensic Analysis, Nanotechnology, Quality Control End User: Academic Institutions, Research Laboratories, Pharmaceutical Companies, Electronics Manufacturers, Forensic Departments, Biotechnology Firms |
| Companies Covered | Nikon Corporation, Thermo Fisher Scientific, Leica Microsystems, Hitachi High-Tech Corporation, JEOL Ltd., Carl Zeiss Microscopy, Bruker Corporation, Motic, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Microscope Market Strategic Shifts & Innovations
Software-defined imaging architectures are decoupling hardware value from analytical capability, enabling subscription revenue models that extend vendor relationships across multi-year fleet deployments.
Correlative light-electron microscopy (CLEM) is expanding into live-cell structural biology workflows. Research institutions in Heidelberg and Boston are adopting integrated platforms that bridge fluorescence dynamics with ultrastructural context. This convergence is compressing the traditional gap between functional and morphological investigation methods.
EU F-Gas Regulation phase-down schedules are accelerating cryo-electron microscope cooling system redesigns. Equipment vendors are engineering closed-loop helium recovery systems to maintain operational viability as refrigerant supply tightens. German and Dutch structural biology facilities are prioritizing retrofit-compatible platforms to hedge against compliance-driven obsolescence.
Service unbundling is fragmenting traditional procurement patterns in Asia-Pacific life sciences. Nikon Corporation and regional distributors are separating hardware sales from application training and maintenance contracts, allowing budget-constrained institutions to stage investments across fiscal years. This pattern is most visible in Singaporean and Australian research hospital networks.
Microscope Market Segmentation
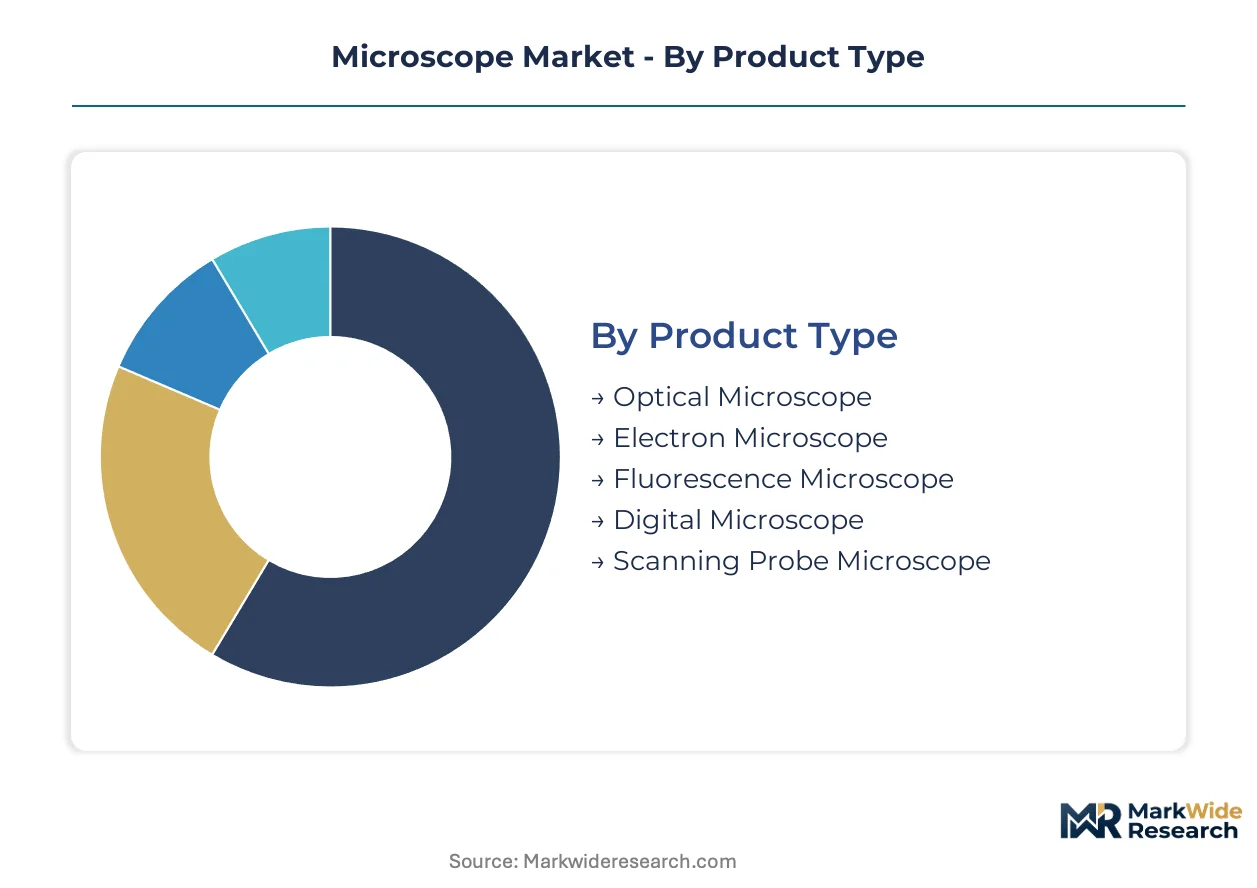
Microscope procurement patterns diverge sharply across buyer categories, with capital intensity and regulatory compliance requirements creating distinct purchasing behaviors. Semiconductor fabs prioritize resolution specifications over cost, while pharmaceutical quality-control departments weight audit-trail capabilities and networked data management more heavily than raw optical performance.
Product Type:
Capital deployment thresholds and facility requirements separate institutional buyers from commercial laboratories in this category.
- Optical Microscope:Conventional light-based systems using glass objective lenses achieve up to two thousand times magnification for routine cellular pathology and educational applications. Demand concentrates in German precision-optics clusters around Oberkochen and Jena, where Zeiss and Leica maintain specialized supply chains for high-NA objective lenses. FDA device-clearance pathways for medical-device manufacturing tighten optical-system requirements, forcing US-based production facilities toward higher-resolution configurations.
- Electron Microscope:Electromagnetic lensing systems reach sub-angstrom resolution through accelerated electron beams in vacuum chambers. Taiwan and South Korean semiconductor foundries are expanding procurement as chip node sizes shrink below three nanometers, compressing replacement cycles and redrawing vendor competitive boundaries. Capital intensity and specialized facility requirements restrict deployment to well-capitalized institutions with vibration-isolated cleanrooms.
- Fluorescence Microscope:Excitation-emission systems for labeled specimen analysis face REACH-driven mercury-vapor lamp phase-outs across Europe. LED-illumination retrofits dominate replacement demand in Heidelberg and Boston research institutions adopting correlative light-electron microscopy workflows.
- Digital Microscope:Camera-integrated systems with networked image archiving accelerate fastest in pharmaceutical quality-control environments satisfying regulatory audit trails. Singaporean and Australian research hospital networks prioritize distributed quality verification capabilities.
- Scanning Probe Microscope:Atomic-scale surface mapping systems occupy defensible margin pools in nanotechnology research institutions requiring precise topographical characterization. Specialized operator expertise constrains fleet utilization rates.
Electron microscope systems command the largest installed-value base today; digital microscope adoption is gaining share fastest in regulated pharmaceutical environments.
Technology:
Resolution methodology and sample preparation complexity distinguish research-grade from industrial-deployment buyers.
- Confocal:Laser-scanning optical sectioning eliminates out-of-focus blur in thick biological specimens. Life sciences research institutions in Boston and Heidelberg integrate these platforms with electron microscopy for correlative workflows bridging fluorescence dynamics with ultrastructural context.
- Phase Contrast:Refractive index visualization for unstained live cells remains standard in academic teaching laboratories. Budget constraints in Singaporean and Australian research hospital networks sustain demand for cost-effective brightfield alternatives.
- Transmission Electron:Electron beam transmission through ultra-thin specimens delivers highest-resolution morphological data. EU F-Gas Regulation phase-down schedules are accelerating cryo-electron microscope cooling system redesigns with closed-loop helium recovery in German and Dutch structural biology facilities.
- Scanning Electron:Surface topography imaging via secondary electron detection dominates materials failure analysis and semiconductor defect inspection. Taiwan foundries prioritize procurement as node shrinkage forces atomic-scale detection capabilities.
- Atomic Force:Mechanical probe scanning achieves true atomic resolution for surface science applications. Nanotechnology research institutions maintain specialized operator pools given the technique's steep learning curve.
- Polarizing:Birefringence detection for crystalline materials and geological specimens serves materials science and forensic analysis applications. Lower capital requirements sustain presence in budget-constrained academic settings.
Scanning electron technology leads commercial volumes today; confocal systems are expanding most quickly through correlative microscopy adoption.
Application:
Regulatory stringency and capital availability shape divergent procurement timelines across use cases.
- Life Sciences Research:Cellular and molecular investigation workflows drive demand for fluorescence and electron microscopy platforms. Correlative light-electron microscopy convergence in Heidelberg and Boston compresses traditional gaps between functional and morphological methods.
- Semiconductor Inspection:Defect detection and metrology for advanced logic chips force optical-to-electron microscope transitions below three nanometer nodes. Taiwan and South Korean foundries anchor procurement volume with compressed replacement cycles.
- Material Science:Microstructural characterization for metals, ceramics, and composites utilizes scanning electron and atomic force platforms. German precision-optics clusters supply high-NA objectives for optical failure analysis.
- Forensic Analysis:Trace evidence and document examination employs polarizing and comparison microscopy. Budget cycles in government laboratories extend replacement timelines versus commercial sectors.
- Nanotechnology:Atomic-scale fabrication verification requires scanning probe and transmission electron systems. Research institutions hedge against EU F-Gas compliance-driven obsolescence through retrofit-compatible platform selection.
- Quality Control:Pharmaceutical manufacturing mandates networked digital microscopy for regulatory audit trails. FDA quality-system regulations tighten optical-inspection requirements across US-based production facilities.
Semiconductor inspection leads application volumes today; quality control is climbing the fastest as pharmaceutical digitization accelerates.
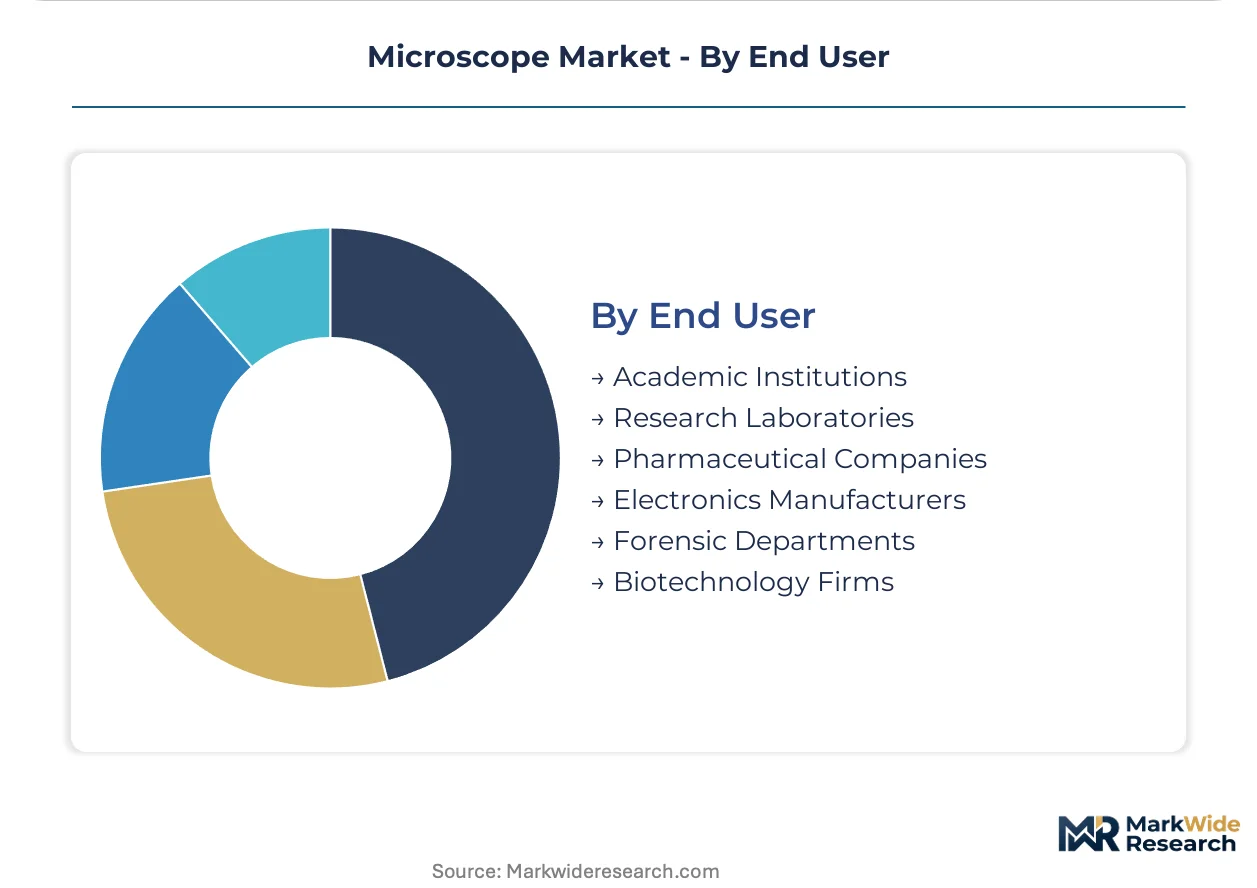
End User:
Funding stability and regulatory exposure create distinct purchasing authority patterns across buyer types.
- Academic Institutions:Teaching and basic research operations balance capability against capital constraints. Service unbundling by Nikon Corporation and regional distributors allows Singaporean and Australian networks to stage investments across fiscal years.
- Research Laboratories:Advanced investigation facilities prioritize resolution and correlative workflow integration. Heidelberg and Boston institutions lead correlative light-electron microscopy adoption for live-cell structural biology.
- Pharmaceutical Companies:Regulatory compliance mandates dominate procurement specifications. FDA device-clearance pathways and ISO 10993 biocompatibility standards tighten optical-system requirements for medical-device manufacturing.
- Electronics Manufacturers:Semiconductor and component producers drive electron microscope demand as process nodes shrink. Taiwan and South Korean foundries compress vendor replacement cycles through accelerated procurement.
- Forensic Departments:Government-funded trace evidence analysis faces extended budget cycles versus commercial buyers. Polarizing microscopy maintains presence for crystalline material identification.
- Biotechnology Firms:Venture-funded development operations prioritize flexible procurement structures. Subscription-based software-defined imaging enables staged capability expansion without full capital commitment.
Electronics manufacturers lead end-user volumes today; biotechnology firms are gaining share fastest through software-defined imaging adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting microscope procurement toward jurisdictions with clearer FDA equivalency pathways and subsidized research infrastructure, compressing lead times for electron microscopy installations in East Asian semiconductor corridors while European facilities absorb REACH compliance costs through LED retrofit cycles.
United States
FDA quality-system regulations for medical-device manufacturing tighten optical-inspection requirements across production facilities in Massachusetts and California. The IRA's clean energy provisions indirectly support advanced manufacturing instrumentation through domestic production credits. Greater Boston anchors correlative light-electron microscopy adoption for live-cell structural biology workflows.
Germany
EU F-Gas Regulation phase-down schedules accelerate cryo-electron microscope cooling system redesigns with closed-loop helium recovery. REACH chemical-substance restrictions eliminate mercury-vapor lamp supply chains, forcing fluorescence-installed base upgrades. Precision-optics clusters around Oberkochen and Jena maintain specialized supply chains for high-NA objective lenses serving global semiconductor and life sciences demand.
Taiwan
Sub-3nm semiconductor fabrication drives accelerated electron microscope procurement for atomic-scale defect detection in advanced logic chips. The National Development Council's strategic technology programs subsidize analytical instrumentation for foundry ecosystems. Hsinchu Science Park concentrates inspection lab expansion as node shrinkage compresses vendor replacement cycles.
South Korea
MFDS medical device regulations and K-Battery strategy investments create dual demand streams for clinical research and materials characterization platforms. Government-backed semiconductor R&D consortia mandate metrology capability expansion. Pangyo and Giheung clusters anchor electron microscopy fleet growth tied to memory and foundry process development.
Japan
METI's semiconductor revitalization policies channel funding toward analytical instrumentation for domestic chip manufacturing resurgence. PMDA's evolving software-as-medical-device frameworks shape AI-assisted image analysis adoption timelines. Kansai and Kyushu industrial corridors maintain specialized operator pools for transmission electron systems serving materials science applications.
Microscope Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with precision-optics fabrication concentrating in German industrial clusters while Asian electronics conglomerates integrate electron microscopy through captive supply arrangements. The structure tiers across three archetypes: diversified analytical instrumentation conglomerates, dedicated microscopy specialists with century-scale optical heritage, and precision-mechanics contract manufacturers serving OEM specification. Dominant competitive moves include strategic partnerships for correlative workflow integration and geographic expansion through localized service infrastructure in Asia-Pacific life sciences markets.
Within the diversified analytical instrumentation tier, Thermo Fisher Scientific and Bruker Corporation represent scale-driven platform consolidation, embedding software suites to sustain service contract attachment across electron microscopy fleets. Among dedicated microscopy specialists, Nikon Corporation exemplifies Asia-Pacific market penetration through distributed training and maintenance infrastructure, while Carl Zeiss Microscopy and Leica Microsystems anchor German precision-optics heritage in semiconductor and clinical research verticals. JEOL Ltd. occupies a position in high-voltage electron systems requiring specialized vacuum engineering expertise.
| Leading Market Players |
|---|
| Nikon Corporation |
| Thermo Fisher Scientific |
| Leica Microsystems |
| Hitachi High-Tech Corporation |
| JEOL Ltd. |
| Carl Zeiss Microscopy |
| Bruker Corporation |
| Motic |
| Olympus Corporation |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between ISO 17025-accredited analytical laboratories and routine educational users manifests in both pricing power and supply chain configurations. Premium-tier electron microscopy platforms command direct OEM relationships with German precision-optics clusters, while budget-constrained academic buyers route through regional distributors with staged service unbundling.
Pricing Analysis
Distributor margins in the 15-25% range separate direct-to-OEM pricing from institutional procurement through regional channels. Three-tier pricing structure across premium, standard, and economy levels tracks resolution specifications and software-attachment depth rather than hardware cost alone. Cost compression in the optical microscope tier intensifies as LED-illumination retrofits commoditize fluorescence capabilities. Pharmaceutical quality-control departments show lowest price sensitivity due to regulatory audit-trail mandates, while Singaporean and Australian research hospital networks exhibit highest sensitivity driving service-unbundling adoption.
Supply Chain Analysis
Freight costs for vibration-isolated electron microscope installations run 8-12% of equipment value given climate-controlled cleanroom delivery requirements. Precision-optics manufacturing concentrates in Germany, Japan, and the Netherlands, with high-NA objective lens fabrication anchored in Oberkochen and Jena clusters. Vacuum engineering components and electromagnetic lens assemblies draw from specialized Japanese and US suppliers. Single-source vulnerability in high-NA objective lens supply creates procurement risk for semiconductor fabs below three nanometer nodes. Distribution runs through direct OEM sales forces for electron microscopy fleets and authorized distributor networks for optical systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic-arbitrage opportunities emerge from regulatory cost differentials: EU F-Gas compliance burdens German structural biology facilities while Taiwan's National Development Council subsidies compress net acquisition costs for semiconductor foundries.
For Market Incumbents: Extend software-defined imaging architectures to capture recurring revenue independent of hardware refresh cycles. Defensive consolidation moves should prioritize captive supply of high-NA objective lens manufacturing through backward integration into German precision-optics clusters, and accelerate closed-loop helium recovery system development to hedge EU F-Gas Regulation obsolescence risk in cryo-electron microscopy installed bases. For New Entrants and Emerging Players: AI-assisted image analysis modules offer a technology-first wedge into pharmaceutical quality-control networks where FDA software-as-medical-device classification debates create vendor disruption opportunities. White-space targets include distributed digital microscopy platforms for Singaporean and Australian research hospital networks, and retrofit-compatible LED-illumination systems for European fluorescence-installed bases facing REACH-driven mercury-vapor lamp phase-outs. Go-to-market positioning should emphasize subscription-based service attachment over capital equipment sales. For Investors and Strategic Acquirers: Consolidation pressure builds where precision-optics fabrication expertise concentrates in century-scale German industrial clusters with limited replication feasibility. Long-term viability over the analysis window favors diversified analytical instrumentation platforms with embedded software suites sustaining service contract attachment. Acquisition target archetype: specialized electromagnetic lens maintenance providers with rare high-voltage vacuum engineering expertise. Signal to watch: FDA guidance finalization on AI-assisted diagnostic software classification triggering liability restructuring across vendor service models.| Strategic Initiative | Industry Significance |
|---|---|
| Correlative Workflow Integration | Bridges fluorescence dynamics with ultrastructural context in Heidelberg and Boston research institutions. |
| Closed-Loop Helium Recovery Systems | Maintains cryo-electron microscope operational viability under EU F-Gas Regulation phase-down schedules. |
| Software-Defined Imaging Subscription | Decouples hardware value from analytical capability to extend vendor relationships across multi-year deployments. |
| Localized Service Infrastructure Expansion | Enables Nikon Corporation's Asia-Pacific penetration through distributed training and maintenance networks. |
| LED-Illumination Retrofit Platforms | Captures REACH-driven replacement demand across European fluorescence microscopy installed bases. |
Research Approach
Multiple input streams — primary interviews with semiconductor metrology directors, pharmaceutical quality-control managers, and academic procurement officers; secondary validation through FDA 510(k) filings, ISO 17025 accreditation databases, and SEC instrument-revenue disclosures; plus customs trade data on precision-optics imports — were reconciled through bottom-up and top-down triangulation. Stakeholder conversations spanned equipment vendors, regional distributors, and end-user facilities across Taiwan, Germany, and the United States.
Historical shipment data cross-referenced against panel input from industry participants established baseline parameters across the projection horizon. Segmentation dimensions modeled include product type, resolution technology, application vertical, and end-user funding structure. CAGRs were derived from fitted growth curves adjusted for regulatory inflection points and capital expenditure cycle timing. Semiconductor node shrinkage trajectories and pharmaceutical digitization mandates served as industry-specific demand drivers.
The model holds under stable regulatory enforcement of FDA quality-system requirements and EU F-Gas phase-down schedules; deviation in AI-assisted diagnostic classification timelines or REACH chemical-substance restriction scope would shift vendor revenue mix assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Intraoral Scanners Market
Medical Devices
United States Ultrasound Devices Market
Medical Devices
Middle East and Africa Sperm Separation Devices Market
Medical Devices
Intradermal Injections Market
Medical Devices
Morcellators Market
Medical Devices
Global Metal Implants and Medical Alloys Market
Medical Devices
Sentinel Node Biopsy Market
Medical Devices
DLIF and XLIF Implants Market
Medical Devices
Atrial Fibrillation Devices Market
Medical Devices
Contact and Intraocular Lenses Market
Medical Devices
Global IVF Devices and Consumables Market
Medical Devices
Global Casting Devices Market
Medical Devices
Americas Wearable Medical Device Market
Medical Devices
Retinal Implant Market
Medical Devices
Canada Spinal Surgery Devices Market
Medical Devices
China Contraceptive Devices Market