
 Single Trip Travel Insurance Market | 2026-2036
Single Trip Travel Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Single Trip Travel Insurance Market Analysis
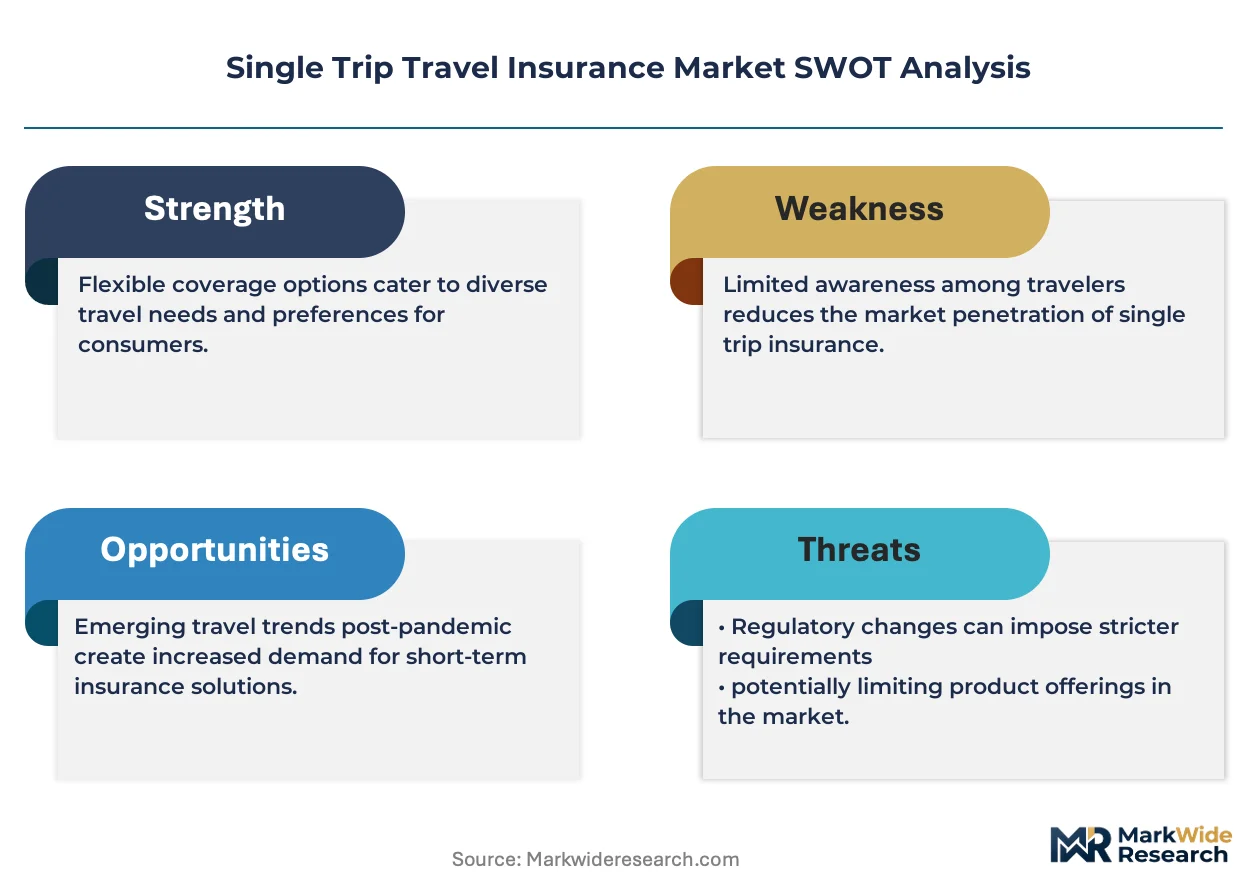
Premium medical coverage tiers is collapsing the gap between basic and comprehensive single trip policies as travelers prioritize health security over cost savings. Allianz leverages its hospital network partnerships across multiple continents to sustain underwriting advantages. AXA competes through embedded distribution with major airline and hotel chains. World Nomads specializes in adventure-focused policies that dominate the niche expedition segment.
Single trip travel insurance constitutes short-duration, non-renewable coverage contracts activated for discrete journeys, typically incorporating medical expense reimbursement, trip cancellation protection, and emergency evacuation provisions with policy terms ranging from one to 180 days. Its commercial purpose centers on transferring travel-related financial risk from consumers to underwriters for isolated departures rather than annual multi-trip portfolios. Medical expenses coverage anchors the largest premium pool within the product structure, while online platforms represent the fastest-growing provider type as direct-to-consumer digital distribution displaces traditional broker channels. Family policies command higher average premiums per transaction than individual equivalents, though group business travel contracts deliver superior margin stability through corporate master agreements.
The EU's IDD and GDPR frameworks impose strict disclosure and data handling obligations on insurers distributing across member states, while the UK's Financial Conduct Authority maintains parallel conduct standards post-Brexit that affect London-based underwriters serving European travelers. The US lacks federal travel insurance regulation, leaving oversight to state insurance commissioners whose requirements vary across jurisdictions and complicate national product standardization. Stakeholders must monitor regulatory divergence between digital-first distribution markets and legacy offline channels as compliance costs increasingly determine competitive viability.
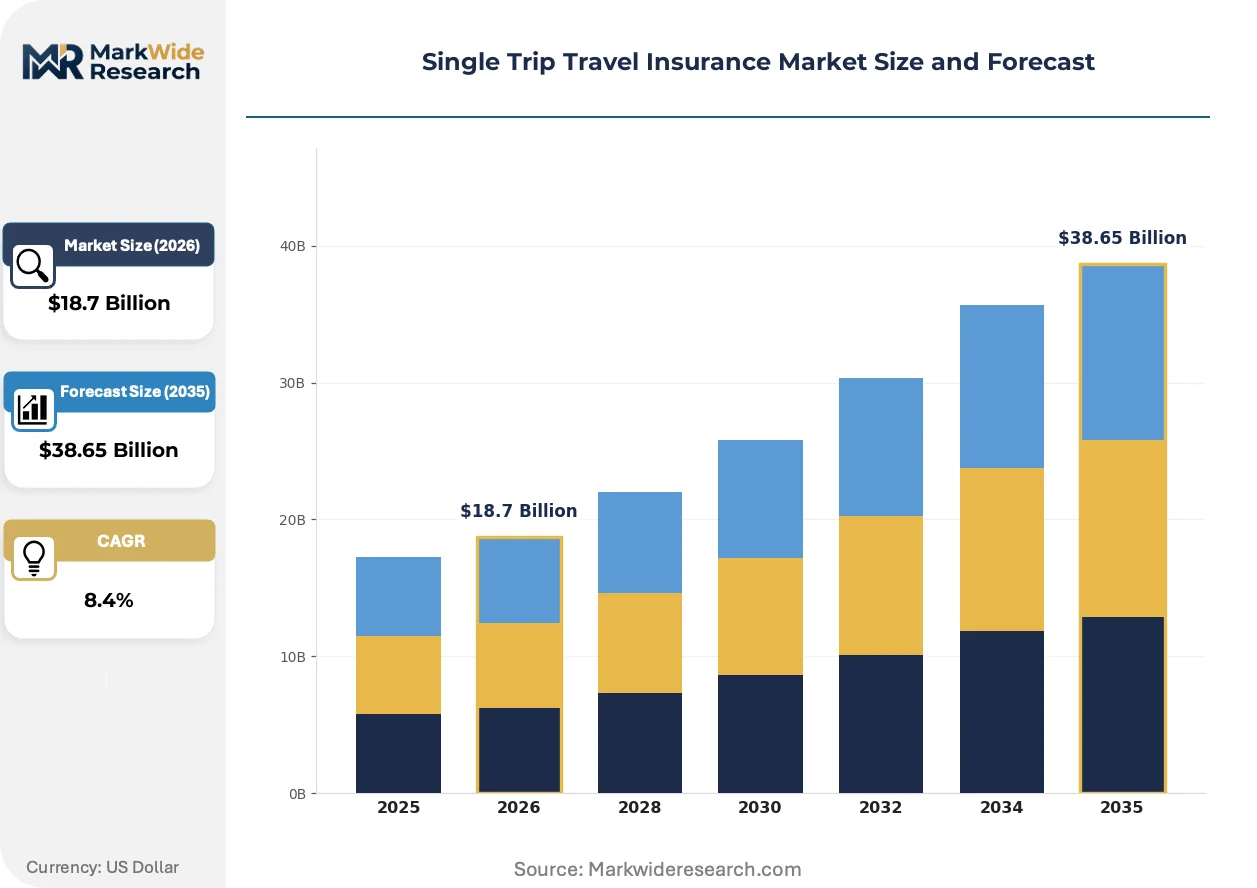
Market Dynamics
The EU's Insurance Distribution Directive is fragmenting traditional broker networks by mandating granular product disclosure standards that favor direct-to-consumer digital platforms over legacy distribution channels.
Growth Catalysts
- Senior Traveler Demographics:Aging populations in Germany, Japan, and the United States are prioritizing medical coverage abroad, creating sustained demand for comprehensive single trip policies with extended age brackets.
- Outbound Tourism Resurgence:Thailand, Vietnam, and Indonesia are experiencing post-pandemic travel volume recovery that concentrates premium growth in Southeast Asian distribution channels.
- Embedded Distribution Partnerships:Airlines and hotel chains are integrating insurance at point-of-booking, reducing friction in policy acquisition for leisure travelers.
Market Restraints
- Regulatory Fragmentation:The US state-based insurance commissioner system creates compliance complexity that prevents standardized national product deployment.
- Medical Cost Volatility:Emergency evacuation and hospitalization pricing in North America and Western Europe introduces unpredictable claims exposure for underwriters.
- Digital Platform Concentration:Online aggregator dominance in price-sensitive segments compresses margin pools and limits carrier differentiation.
Strategic Opportunities
- Adventure Tourism Expansion:Expedition travel in Nepal, Patagonia, and New Zealand remains underpenetrated by specialized coverage tiers that address altitude and remote evacuation risks.
- GDPR-Compliant Data Services:Policy personalization engines leveraging behavioral analytics can unlock cross-sell potential while meeting EU data handling obligations.
- Corporate Master Agreements:Multi-national employers seeking consolidated travel risk management present white space for customized group single trip structures.
Industry Challenges
- Legacy System Integration:Incumbent carriers face technical debt when connecting modern API-based distribution to decades-old policy administration platforms.
- Actuarial Talent Scarcity:Pricing expertise for emerging risk categories including pandemic interruption and climate-related trip disruption remains concentrated among specialized underwriters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Single Trip Travel Insurance Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Family, Individual, Group, Business Coverage Type: Medical Expenses, Trip Cancellation, Lost Luggage, Accidental Death Provider Type: Direct Insurers, Brokers, Aggregators, Online Platforms Distribution Channel: Online, Offline, Travel Agencies, Banks |
| Companies Covered | Allianz, AXA, Travel Guard, Berkshire Hathaway, Chubb, World Nomads, Generali, InsureandGo, Nationwide Mutual Insurance Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Single Trip Travel Insurance Market Emerging Trajectories
Digital distribution infrastructure is compressing policy issuance cycles from days to minutes while AI-powered claims assessment is reducing loss adjustment expenses. These shifts are redrawing competitive boundaries between traditional insurers and technology-enabled entrants.
Parametric triggers for trip cancellation coverage are fragmenting the standard indemnity model by offering predetermined payouts upon verified event occurrence rather than documented loss submission. Adventure tour operators and cruise lines are adopting these instruments to accelerate customer recovery. This mechanism is compressing claims resolution timelines from weeks to hours while reducing administrative overhead for carriers.
The EU's Digital Operational Resilience Act is imposing strict cybersecurity and third-party risk management standards on insurers handling cross-border policy distribution. Firms must now demonstrate continuity planning for cloud-hosted underwriting platforms. London-based underwriters serving European travelers are restructuring vendor governance frameworks to maintain passporting-equivalent access post-Brexit.
Direct-to-consumer platforms are displacing traditional travel agency intermediaries as the primary policy discovery channel for leisure travelers. Price comparison engines and embedded checkout integrations now capture the majority of first-time buyer acquisitions. This channel rotation is most pronounced in the United Kingdom and Australia, where digital-native travelers demonstrate minimal loyalty to historical broker relationships.
Single Trip Travel Insurance Market Segmentation
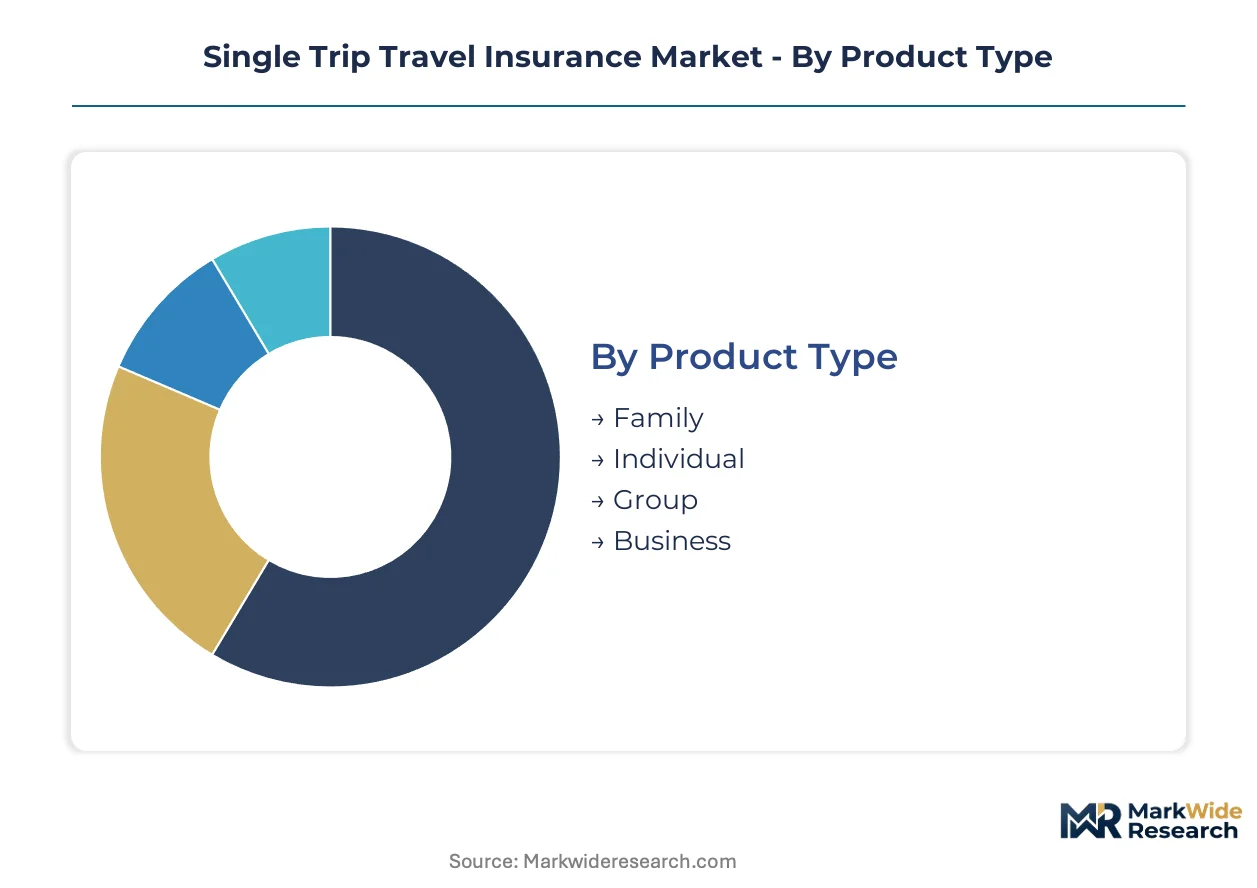
Segmentation in single trip travel insurance reveals how risk transfer products align with distinct traveler profiles, distribution economics, and regulatory exposure. Insurers calibrate pricing models, policy terms, and compliance frameworks differently across each dimension.
Product Type:
Domestic leisure travel drives family and individual policy volumes, while corporate outbound travel concentrates group and business contract values in cross-border distribution channels.
- Family:Multi-traveler policies bundle dependent coverage under single premiums with age-tiered pricing for children and seniors. Demand clusters in Germany and Australia's outbound holiday corridors where extended family travel requires consolidated medical protection.
- Individual:Single-traveler contracts offer maximum flexibility on destination, duration, and coverage limits with personalized medical underwriting. Solo adventure travelers in New Zealand and Nepal drive specialized policy attachment for remote evacuation scenarios.
- Group:Organizations purchasing coverage for 10+ travelers on shared itineraries negotiate master agreements with standardized terms. Educational institutions and religious organizations in the United States favor this structure for mission trips and study abroad programs.
- Business:Corporate travel managers integrate single trip coverage into duty-of-care frameworks with 24/7 assistance hotlines and pre-trip security briefings. Multinational employers in London and Singapore use these contracts to satisfy board-level risk governance requirements.
Individual policies hold the largest share; momentum sits with family products as multi-generational travel rebounds.
Coverage Type:
Cost tier differentiation separates basic from comprehensive offerings, with premium tiers commanding substantially higher attachment rates in medical-volatile destinations.
- Medical Expenses:Hospitalization and outpatient treatment reimbursement forms the core risk transfer mechanism, with sub-limits for dental emergencies and prescription medications. Senior travelers in Japan and the United States prioritize this coverage tier above all others.
- Trip Cancellation:Pre-departure interruption protection reimburses non-refundable deposits when insured events prevent travel. Tour operators in Thailand embed this coverage to reduce customer service friction from weather-related cancellations.
- Lost Luggage:Personal effects and baggage delay coverage addresses airline mishandling risks with per-item caps and depreciation schedules. Business travelers in Frankfurt and Dubai claim most frequently on electronics and professional equipment.
- Accidental Death:Lump-sum survivor benefits activate on transport-related fatalities during the insured journey. Aviation-dependent routes across Indonesia and Vietnam drive higher attachment rates for this coverage tier.
Medical expenses coverage dominates premium pools; trip cancellation is climbing fastest as travelers seek deposit protection.
Provider Type:
Volume concentration varies sharply by customer acquisition channel, with digital-native platforms capturing disproportionate share among first-time buyers.
- Direct Insurers:Underwriters selling proprietary products through owned channels retain full margin and control brand positioning. Allianz and AXA leverage direct platforms in European markets to bypass intermediary commissions.
- Brokers:Independent intermediaries advise travelers on policy selection across multiple carrier panels for complex or high-value trips. Australian and UK travelers still rely on broker counsel for extended-duration or adventure-focused coverage.
- Aggregators:Price comparison engines display standardized quotes from competing underwriters, compressing margins through transparent competition. Comparethemarket and similar platforms dominate UK policy discovery.
- Online Platforms:Digital-first insurers and managing general agents issue policies through API-connected checkout flows with sub-minute issuance. World Nomads built market position in expedition travel through this channel architecture.
Direct insurers command the largest share; online platforms are expanding most quickly as embedded distribution displaces traditional search-and-compare behavior.
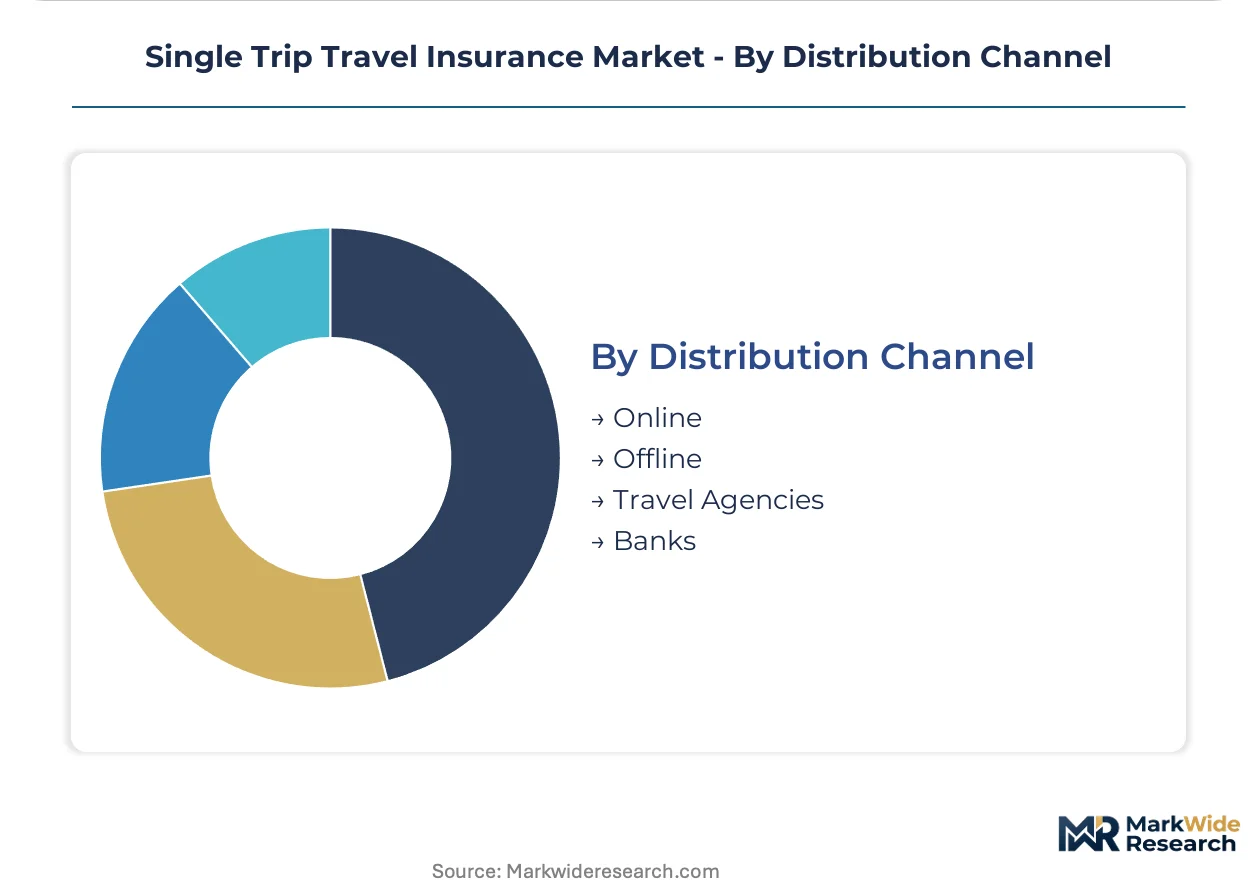
Distribution Channel:
Customer type and purchase context determine channel selection, with leisure travelers diverging sharply from corporate procurement patterns.
- Online:Direct-to-consumer websites and mobile applications capture price-sensitive leisure travelers seeking immediate policy documentation. UK and Australian markets show the highest online penetration rates for single trip products.
- Offline:Telephone and mail-based sales persist among senior demographics and complex medical underwriting cases requiring human review. German travelers over 65 still prefer voice consultation for coverage explanations.
- Travel Agencies:High-street and online travel bookers attach insurance at point-of-sale with simplified medical screening. Southeast Asian outbound specialists in Bangkok and Jakarta bundle coverage with package tour sales.
- Banks:Financial institutions cross-sell travel insurance to cardholders and account holders through relationship pricing and loyalty programs. Singaporean and Hong Kong banks leverage premium customer segments for attachment.
Online channels hold the largest share; travel agencies are gaining share fastest through embedded checkout integration with airline and hotel booking engines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. German and Japanese buyers prioritize comprehensive medical tiers regardless of premium cost. Southeast Asian and Indonesian travelers gravitate toward stripped-down policies where price dominates selection.
United States
Senior travelers over 65 drive policy attachment rates, particularly for medical evacuation coverage. State insurance commissioners maintain fragmented oversight that complicates national product standardization. Florida and Arizona retirement corridors concentrate outbound policy issuance for cruise and winter escape travel.
Germany
Aging demographics prioritize extended medical coverage brackets for European and long-haul destinations. The EU's Insurance Distribution Directive mandates granular product disclosure that favors direct-to-consumer digital platforms. Munich and Frankfurt underwriters leverage hospital network partnerships across multiple continents for underwriting advantages.
United Kingdom
Digital-native travelers demonstrate minimal loyalty to historical broker relationships, accelerating aggregator dominance. The Financial Conduct Authority maintains conduct standards post-Brexit that affect London-based underwriters serving European travelers. Price comparison engines in London capture the majority of first-time buyer acquisitions.
Thailand
Post-pandemic outbound tourism resurgence concentrates premium growth in Southeast Asian distribution channels. Tour operators embed trip cancellation coverage to reduce customer service friction from weather-related disruptions. Bangkok specialists bundle coverage with package tour sales through travel agency channels.
Australia
Extended family travel requires consolidated medical protection, driving family policy volumes. The Australian Securities and Investments Commission oversees travel insurance distribution with conduct obligations. Sydney and Melbourne digital platforms displace traditional travel agency intermediaries as primary policy discovery channels.
Single Trip Travel Insurance Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the single trip travel insurance market. Global multi-line insurers with proprietary hospital networks command premium-tier positioning, while digital-native managing general agents capture price-sensitive segments through API-connected distribution. Three archetypes dominate: integrated underwriters with captive medical networks, embedded distribution specialists partnering with airlines and hotel chains, and adventure-focused niche carriers serving expedition travel. Competitive moves concentrate on embedded checkout integrations and parametric claims automation.
Within the integrated underwriter tier, Allianz and AXA occupy positions sustained by hospital network partnerships across multiple continents. World Nomads exemplifies the adventure-specialist archetype, dominating the niche expedition segment through digital-first distribution. These three entities represent the spectrum from scale-driven comprehensive coverage to targeted risk-specific policies.
| Leading Market Players |
|---|
| Allianz |
| AXA |
| Travel Guard |
| Berkshire Hathaway |
| Chubb |
| World Nomads |
| Generali |
| InsureandGo |
| Nationwide Mutual Insurance Company |
| Others |
Supply Flow & Price Mechanics
Capacity reservation agreements with hospital networks lock in medical expense coverage rates and eliminate spot-market volatility for underwriters operating across Germany, Thailand, and Australia. These multi-year contracts tether pricing visibility to network exclusivity, compressing margin uncertainty for integrated carriers while raising barriers for digital entrants lacking established provider relationships.
Pricing Analysis
The EU's Insurance Distribution Directive dictates the pricing tier structure by mandating granular disclosure standards that compress opacity premiums formerly captured by legacy brokers. Three-tier pricing structure across premium, standard, and economy levels separates comprehensive medical coverage from stripped-down deposit protection from bare-minimum evacuation-only contracts. Cost compression in the economy tier is intensifying because aggregator platforms force transparent comparison, while senior travelers in Japan and Germany demonstrate minimal price sensitivity for extended medical brackets. Corporate procurement teams in London and Singapore negotiate master agreements with superior rate stability, whereas Southeast Asian leisure travelers through Bangkok channels exhibit maximal price elasticity.
Supply Chain Analysis
Just-in-time policy issuance through API-connected distribution platforms has displaced strategic stockpiling of pre-underwritten inventory across the industry. Underwriting capacity concentrates in Germany, the United Kingdom, and Singapore where regulatory clarity supports cross-border passporting. Medical expense reserves draw from reinsurance treaties with London-based syndicates, emergency evacuation networks spanning Southeast Asian hubs, and actuarial talent pools concentrated in Munich and Sydney. Single-source vulnerability sits with cloud-hosted policy administration platforms subject to the EU's Digital Operational Resilience Act continuity requirements. Distribution runs through embedded checkout integrations with airline reservation systems and hotel booking engines rather than traditional broker panels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power has concentrated through aggregator platform dominance in the United Kingdom and Australia, fragmenting carrier pricing power and forcing margin compression across price-sensitive segments.
For Market Incumbents: Compound network exclusivity advantages by deepening hospital partnership density in Thailand and Vietnam before digital entrants secure API access. The EU's Digital Operational Resilience Act imposes compliance costs that favor scaled carriers with dedicated vendor governance teams. Priority levers include backward integration into claims assessment automation and captive medical assistance hotlines in Southeast Asian growth corridors. For New Entrants and Emerging Players: GDPR-compliant data personalization certification fast-track unlocks white space in corporate master agreements where incumbent legacy systems create service gaps. Target adventure tourism operators in Nepal and Patagonia with parametric cancellation products that bypass traditional loss adjustment infrastructure. Go-to-market execution should embed through tour operator checkout flows rather than competing for aggregator visibility. For Investors and Strategic Acquirers: Capital is best deployed toward digital-native managing general agents with established API distribution and specialized risk expertise in expedition or senior travel segments. Long-term viability across the analysis window hinges on regulatory technology capabilities that automate IDD and GDPR compliance workflows. Watch embedded insurance attachment rates at point-of-booking as the inflection indicator for distribution channel permanence.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Claims Automation | Reduces resolution timelines from weeks to hours for tour operators in Thailand. |
| Hospital Network Exclusivity Expansion | Secures underwriting advantages in Germany and Southeast Asian medical corridors. |
| GDPR-Compliant Personalization Engine | Unlocks cross-sell potential for direct insurers serving EU senior travelers. |
| Embedded Checkout Integration | Captures first-time buyers through airline and hotel booking engine partnerships. |
| Corporate Master Agreement Specialization | Addresses duty-of-care requirements for multinational employers in London and Singapore. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with underwriting executives at integrated carriers, distribution leads at digital platforms, regulatory compliance officers navigating IDD implementation, and claims operations managers handling medical evacuation logistics. Secondary validation drew from EU regulatory filings, UK Financial Conduct Authority conduct reports, hospital network partnership disclosures, and customs data on outbound tourism flows from Thailand and Indonesia. Bottom-up policy volume estimates triangulated against top-down premium pool calculations across the analysis window.
Across the projection horizon, the analytical framework modeled traveler demographics, coverage tier attachment rates, distribution channel mix, and provider type concentration. CAGRs were derived from segmented growth trajectories weighted by regional price elasticity differentials. Industry-specific inputs included senior traveler medical claim frequency patterns, parametric trigger adoption rates among tour operators, and embedded insurance attachment benchmarks at airline point-of-sale.
Decision-makers should treat outputs as directional under assumptions of sustained outbound tourism recovery and stable regulatory enforcement intensity; material deviation would warrant model refresh. Forecasts reflect these base conditions without contingency for pandemic resurgence or abrupt tariff imposition on cross-border reinsurance flows. Revision becomes warranted when digital platform concentration crosses thresholds that trigger antitrust intervention or when medical cost inflation in North America exceeds actuarial reserve buffers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Europe Electronic Gadgets Insurance Market
Insurance
Global SME Insurance Market
Insurance
Asia-Pacific Insurance Aggregators Market
Insurance
UK Travel Insurance Market
Insurance
Group Health Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
Commercial Earthquake Insurance Market
Insurance
Medical Claims Processing Services Market
Insurance
Singapore Property and Casualty Insurance Market
Insurance
Global Long Term Care Insurance Market
Insurance
Mobile Phone Insurance Market
Insurance
Financial Protection Market
Insurance
Europe Health Insurance Market
Insurance
Canada Parametric Insurance Market
Insurance
Crime Insurance Market