
 Singapore Property and Casualty Insurance Market | 2026-2036
Singapore Property and Casualty Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Singapore Property and Casualty Insurance Market Analytics
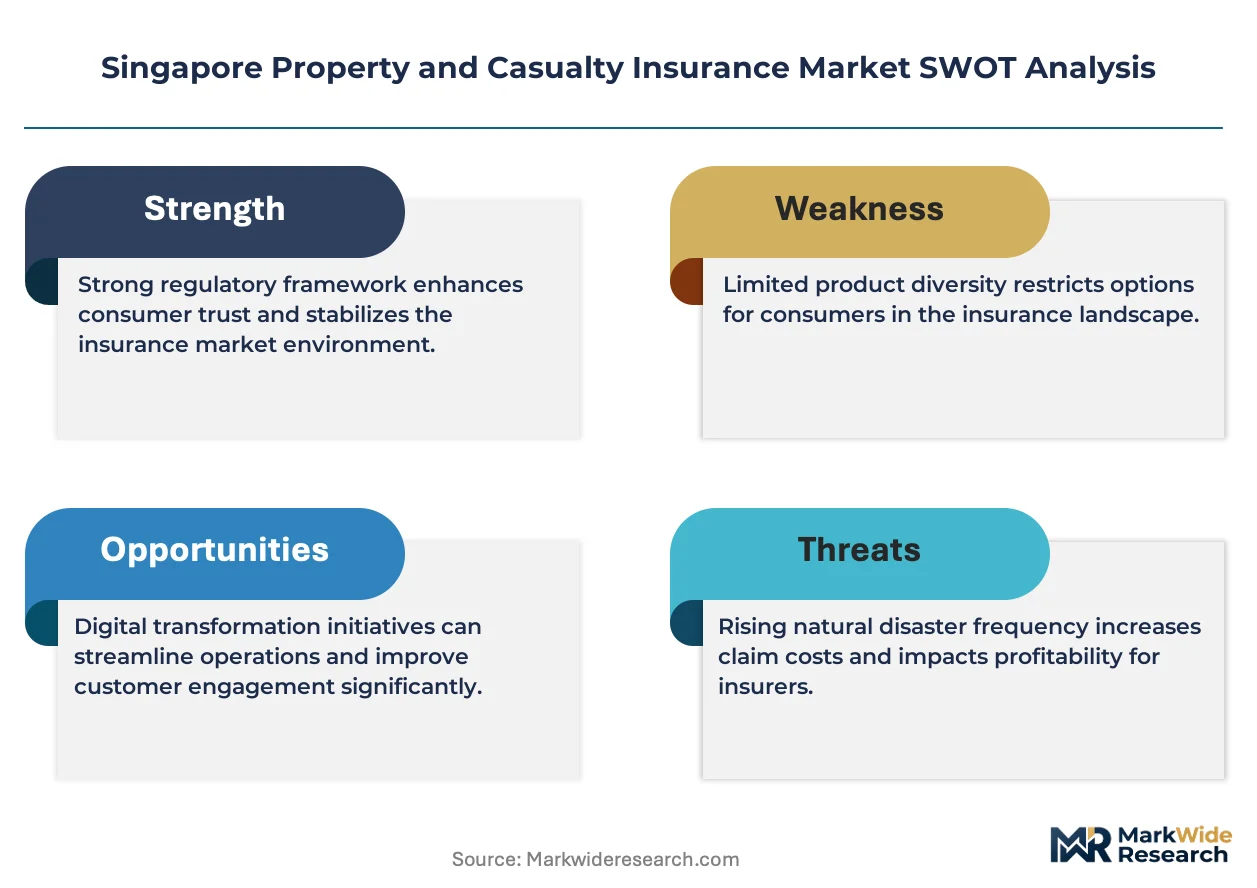
Singapore's Green Plan 2030 sustainability mandate is pivoting property underwriting toward climate-resilient construction standards and flood-risk pricing. AXA Singapore leverages its global engineering expertise to underwrite renewable energy infrastructure projects across Southeast Asia. MSIG Insurance (Singapore) Pte Ltd anchors its competitive position in commercial property through deep relationships with Japanese manufacturing affiliates operating in Jurong and Tuas. Chubb Singapore differentiates via high-net-worth personal lines and specialized liability coverage for professional services firms.
Property and casualty insurance constitutes risk transfer mechanisms covering physical asset damage, legal liability, and financial loss from operational interruptions, with policies typically specifying per-occurrence limits, aggregate caps, and deductible structures calibrated to insured risk profiles. Motor coverage dominates premium volume among individual buyers, reflecting Singapore's vehicle quota system and elevated repair costs tied to certified workshop networks. Commercial property and liability lines capture disproportionate margin pools from corporates, where complex supply chain exposures and directors-and-officers liability require bespoke underwriting and captive reinsurance structures.
The Monetary Authority of Singapore enforces risk-based capital requirements and corporate governance standards that elevate operational thresholds for licensed insurers. BIS standards on operational resilience and MAS technology risk management guidelines shape product design, distribution architecture, and data governance protocols across the sector. Stakeholders must monitor how climate scenario testing and embedded insurance models redistribute competitive advantage between traditional carriers and platform-native distributors.
Market Dynamics
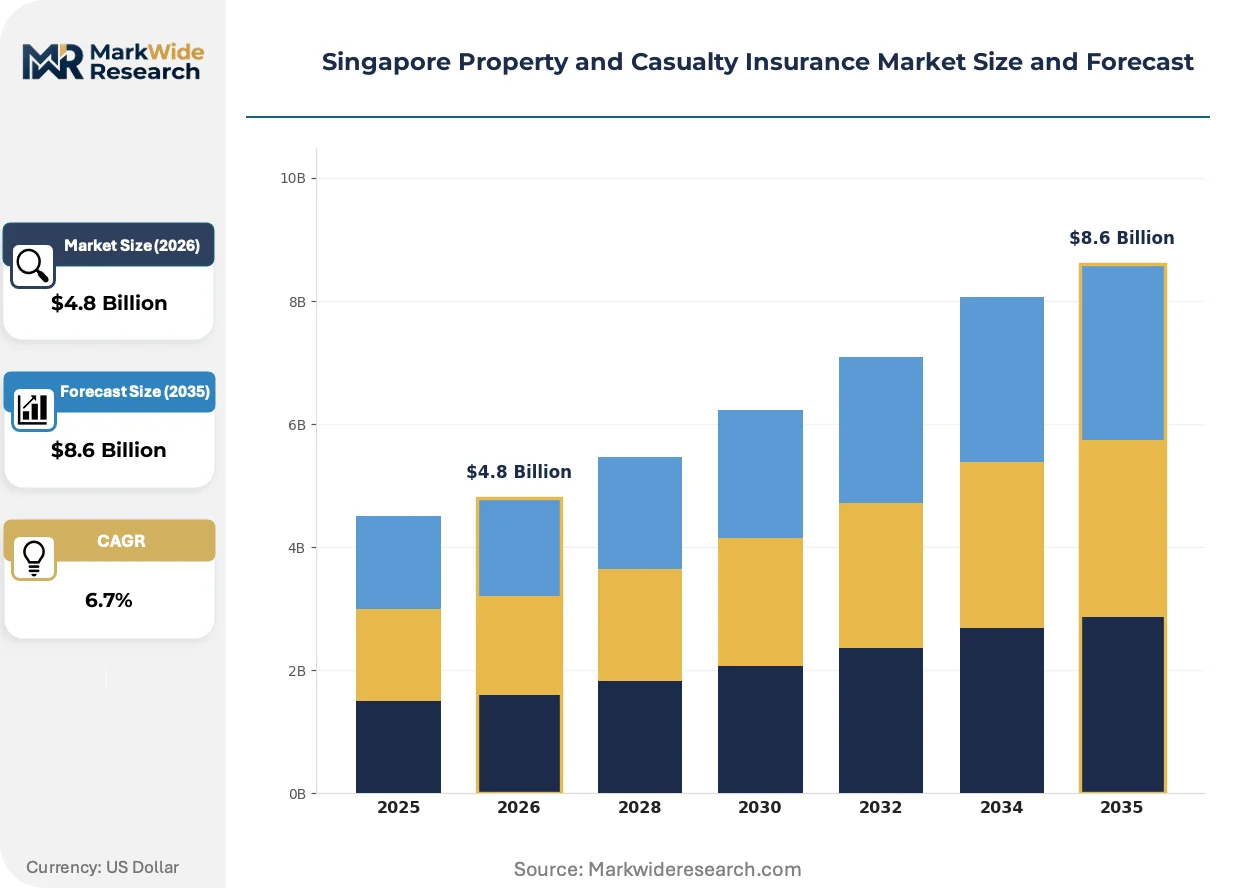
The Monetary Authority of Singapore's risk-based capital framework is compressing underwriting margins and forcing carriers to deploy advanced catastrophe modeling for property portfolios. This regulatory pressure is reshaping capital allocation across commercial lines and accelerating the shift from traditional indemnity products toward parametric and embedded coverage structures.
Growth Catalysts
- Climate-Resilient Construction Mandates:Singapore's Green Plan 2030 mandates flood-adaptive building standards, expanding demand for specialized property coverage tied to certified resilient infrastructure.
- Regional Trade Hub Expansion:Logistics and warehousing operators in Jurong and Tuas are scaling commercial property programs as transshipment volumes through Port of Singapore intensify.
- Cyber Liability Attachments:Financial institutions and multinational headquarters are bundling cyber coverage with traditional D&O policies, creating integrated risk transfer programs.
Market Restraints
- Reinsurance Capacity Squeeze:Global retrocession markets have tightened property catastrophe capacity, pushing Singapore carriers toward higher retention levels and captive structures.
- Certified Workshop Repair Costs:Motor coverage margins compress under Singapore's vehicle quota system, where mandated repair networks elevate claims severity.
- Interest Rate Sensitivity:Investment income volatility constrains pricing flexibility for long-tail liability lines, where reserves must match duration against rising yield curves.
Strategic Opportunities
- Embedded Insurance Distribution:Platform-native distributors are integrating property coverage into e-commerce checkout flows and property leasing workflows, bypassing traditional agency channels.
- Renewable Energy Infrastructure:Southeast Asian solar and offshore wind projects require engineering and construction all-risk coverage that Singapore underwriters can anchor regionally.
- Parametric Flood Products:Satellite-triggered payouts for commercial property damage are gaining traction among industrial operators in low-lying Tuas and Jurong Island zones.
Industry Challenges
- Catastrophe Modeling Talent Scarcity:Underwriting teams lack sufficient actuarial depth in climate scenario analysis, forcing reliance on external vendor models for flood and wind pricing.
- Legacy Core System Integration:Carriers struggle to embed API-first distribution architectures into decades-old policy administration platforms, delaying product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Singapore Property and Casualty Insurance Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Homeowners, Commercial Property, Liability, Motor Customer Type: Individuals, SMEs, Corporates, Government Coverage Type: All Risk, Named Peril, Comprehensive, Third Party Distribution Channel: Direct Sales, Brokers, Agents, Online Platforms |
| Companies Covered | AXA Singapore, Chubb Singapore, NTUC Income, MSIG Insurance (Singapore) Pte Ltd, AIG Asia Pacific Insurance Pte Ltd, Liberty Insurance, Great Eastern, Sompo Insurance Singapore, Tokio Marine Singapore, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Singapore Property and Casualty Insurance Market Evolving Landscape
Digital distribution architectures and climate risk quantification tools are converging to transform how Singapore carriers price, distribute, and service property and casualty contracts. This technological infusion is compressing traditional value chain segments and enabling new entrant competition.
Telematics-enabled motor underwriting is converging with usage-based insurance platforms to generate real-time risk scoring from vehicle telematics data. Fleet operators and ride-hailing platforms are adopting these programs fastest, with pricing now reflecting actual driving behavior rather than demographic proxies. The structural consequence is margin compression for traditional motor underwriters who lack data infrastructure.
Singapore's MAS technology risk management guidelines are mandating operational resilience testing for all licensed insurers, with specific requirements for cyber incident response and third-party vendor oversight. Carriers must now demonstrate failover capabilities and data sovereignty compliance before product approvals. Commercial lines divisions face the heaviest compliance burden, as they rely most heavily on cloud-hosted policy administration systems.
Corporate risk managers are unbundling traditional packaged policies in favor of modular coverage components purchased through digital broker platforms. This procurement evolution displaces the historical dominance of bundled commercial property and liability programs. Financial services and technology sectors in Singapore's central business district show the fastest adoption of à-la-carte risk transfer structures.
Singapore Property and Casualty Insurance Market Segmentation
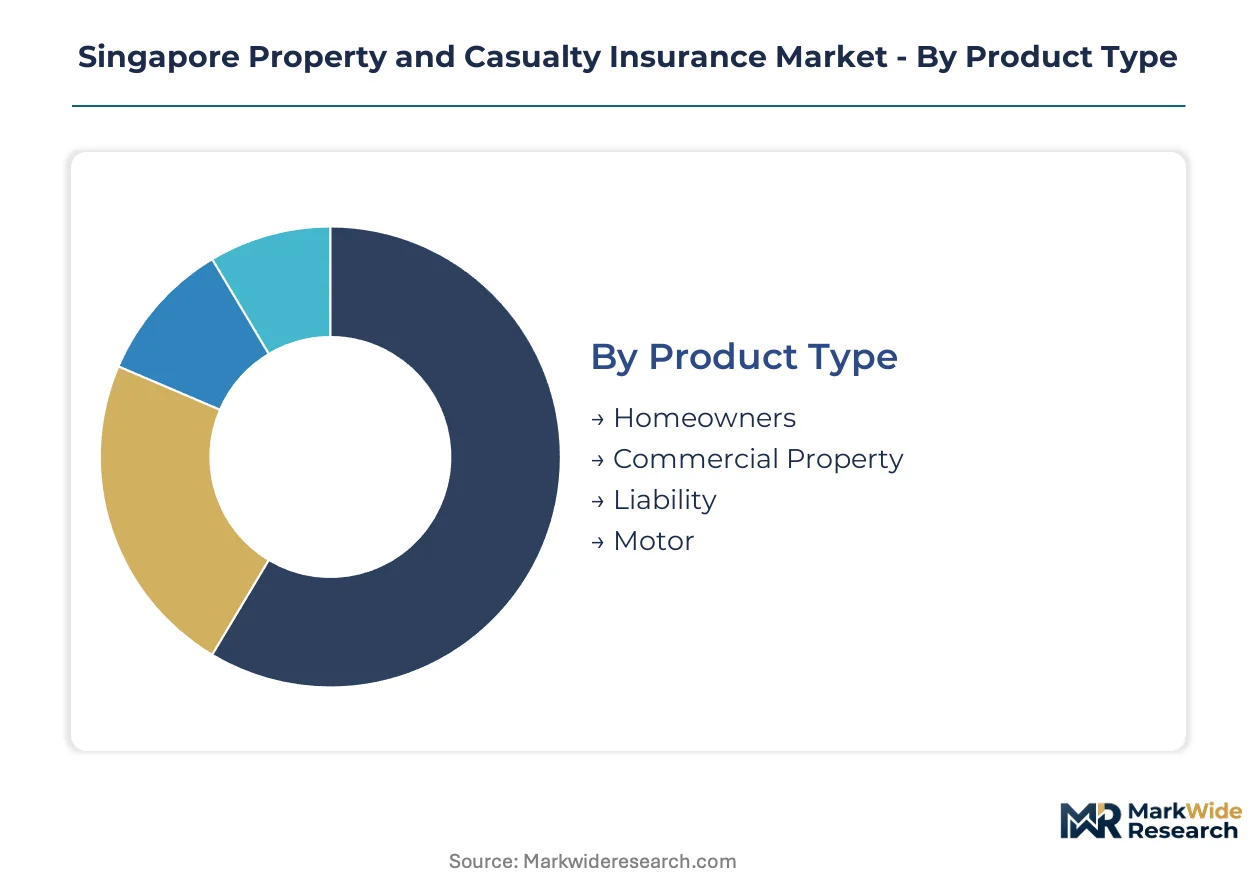
Segmentation in Singapore's property and casualty insurance market reveals how risk appetite, regulatory exposure, and procurement sophistication vary across buyer profiles. Insurers calibrate capital allocation, pricing models, and distribution architecture to these distinct segment economics.
Product Type:
Risk severity and claims frequency diverge sharply across asset classes, driving specialized underwriting capabilities and reinsurance structures.
- Commercial Property:Covers physical damage to industrial facilities, office towers, and logistics infrastructure against fire, flood, and business interruption. Demand concentrates among Jurong Island petrochemical operators and Tuas port logistics firms as Singapore expands transshipment capacity. The Monetary Authority of Singapore's risk-based capital framework elevates retention requirements for catastrophe-exposed portfolios.
- Liability:Encompasses directors-and-officers coverage, professional indemnity, and general liability for legal defense and settlement costs. Financial institutions in Raffles Place and technology firms in one-north drive bespoke program demand with complex cyber attachments and regulatory defense provisions.
- Homeowners:Protects residential structures and contents against fire, theft, and natural perils. HDB flat owners and private condominium residents in Districts 9-11 constitute the core insured base.
- Motor:Covers vehicle damage, third-party bodily injury, and property damage under Singapore's certificate-of-insurance mandate. The vehicle quota system and certified workshop network compress margins despite mandatory coverage.
Volume sits with Motor; growth tilts toward Commercial Property.
Customer Type:
Procurement sophistication and risk retention capacity scale with organizational complexity and balance sheet depth.
- Corporates:Multinational headquarters and financial institutions purchase complex, layered coverage programs with captive reinsurance structures and international program coordination. These buyers command dedicated underwriting teams and customized policy wordings.
- SMEs:Small and medium enterprises in manufacturing, retail, and services purchase standardized packaged policies through broker networks. Cost sensitivity dominates purchasing decisions, with limited appetite for risk engineering services.
- Individuals:Personal lines buyers acquire motor, home, and personal liability coverage through direct channels or tied agents. Demographic scoring and telematics data increasingly shape pricing granularity.
- Government:Public sector entities procure coverage for infrastructure assets, statutory board operations, and public liability through centralized tender processes. Long contract tenures and stringent compliance requirements favor established carriers.
Corporates anchor premium value; SMEs are climbing the fastest as digital distribution reduces procurement friction.
Coverage Type:
Scope breadth and premium loading reflect insured willingness to assume residual risk and claims certainty preferences.
- All Risk:Broad-form coverage protecting against all perils except specifically excluded causes. Commercial property buyers in flood-exposed zones prefer this structure despite elevated premiums.
- Named Peril:Limited coverage triggering only for enumerated risks such as fire, lightning, or explosion. Cost-conscious SMEs select this option to reduce premium outlays.
- Comprehensive:Motor-specific coverage combining own-damage and third-party liability under single policy structures. Fleet operators and ride-hailing platforms favor this for administrative simplicity.
- Third Party:Minimum mandatory coverage for legal liability to others without protection for insured assets. Individual motor owners frequently select this to satisfy regulatory requirements at lowest cost.
Comprehensive dominates motor submissions; All Risk gains share fastest in commercial lines as climate volatility intensifies.
Distribution Channel:
Channel economics and customer acquisition costs determine carrier profitability and market access depth.
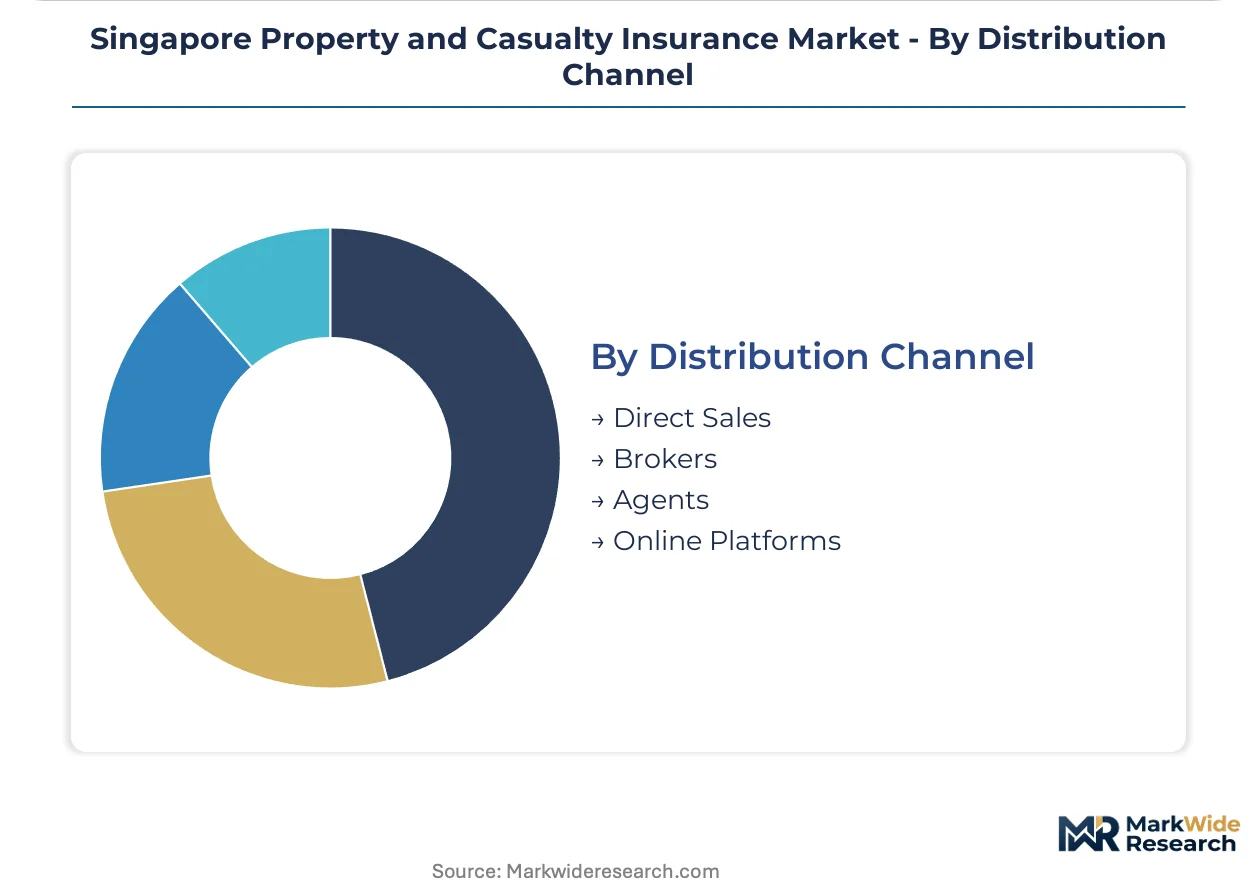
- Brokers:Independent intermediaries serving corporates and high-net-worth individuals with advisory-led placement. Marsh, Aon, and Willis Towers Watson dominate complex risk placement for financial institutions.
- Agents:Tied representatives distributing standardized products to individual and SME segments. Agency force productivity constraints limit growth in digitally native customer segments.
- Direct Sales:Carrier-owned channels bypassing intermediaries for motor and simple homeowner policies. DBS and OCBC bank assurance partnerships leverage existing customer relationships.
- Online Platforms:Digital-native distributors embedding insurance into e-commerce, property leasing, and mobility workflows. Grab Financial and Singlife lead platform integration for usage-based motor products.
Brokers capture corporate value pools; online platforms show steepest expansion trajectory as embedded distribution models mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jurong Island and the Tuas port corridor anchor Singapore's property and casualty insurance concentration, where petrochemical operators and logistics firms generate complex commercial coverage demand. The Monetary Authority of Singapore's risk-based capital framework shapes underwriting standards across all sub-regional markets.
Central Business District
Multinational headquarters and financial institutions in Raffles Place and Marina Bay drive demand for directors-and-officers liability with cyber attachments. MAS technology risk management guidelines mandate operational resilience testing for carriers serving this segment. Tower insurers cluster in the Shenton Way corridor to proximity-underwrite corporate risk programs.
Jurong Island
Petrochemical and refining operations generate Singapore's highest-severity property exposure with business interruption complexity. The country's Green Plan 2030 mandates flood-adaptive construction standards for new industrial facilities. Engineering and construction all-risk coverage concentrates among global carriers with captive reinsurance capabilities.
Tuas and Western Logistics Corridor
Port expansion and warehousing automation are scaling commercial property programs as transshipment volumes intensify. Parametric flood products triggered by satellite data are gaining traction among industrial operators in low-lying zones. Logistics underwriters are embedding coverage into port operator service contracts.
One-North and Technology Precincts
Technology firms and biomedical research operations require specialized professional indemnity with regulatory defense provisions. MAS guidelines on technology risk management shape product design for cloud-hosted policy administration systems. Digital broker platforms are displacing traditional bundled coverage procurement in this segment.
Residential Districts 9-11
Private condominium owners and high-net-worth individuals in Orchard and Tanglin drive demand for tailored homeowners coverage. Telematics-enabled motor underwriting is converging with usage-based platforms for this digitally native segment. Bank assurance partnerships through DBS and OCBC dominate distribution architecture.
Singapore Property and Casualty Insurance Market Competitive Landscape
Premium-margin players sit above commodity-margin players across underwriting sophistication and risk engineering depth. The market structures around three tiers: global carriers with regional balance sheets, Japanese and European affiliates leveraging parent engineering expertise, and domestic cooperatives with captive membership bases. Strategic moves concentrate on parametric product development and embedded distribution partnerships with platform operators.
Within the global carrier tier, AXA Singapore and Chubb Singapore occupy positions defined by engineering depth and high-net-worth specialization respectively. MSIG Insurance (Singapore) Pte Ltd represents the affiliate archetype, anchoring commercial property relationships through parent-company manufacturing networks. These three exemplify how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| AXA Singapore |
| Chubb Singapore |
| NTUC Income |
| MSIG Insurance (Singapore) Pte Ltd |
| AIG Asia Pacific Insurance Pte Ltd |
| Liberty Insurance |
| Great Eastern |
| Sompo Insurance Singapore |
| Tokio Marine Singapore |
| Others |
Value Network & Pricing Analysis
Captive reinsurance structures among Singapore's largest commercial property underwriters anchor both supply security and pricing power in catastrophe-exposed lines. The Monetary Authority of Singapore's risk-based capital framework elevates retention requirements, forcing carriers to internalize risk capacity rather than sourcing freely from global retrocession markets.
Pricing Analysis
Risk-adjusted capital pricing dominates commercial property and liability lines, with premiums calibrated to modeled loss expectancies and regulatory capital charges. Price differentiation separates global carriers with proprietary catastrophe models from domestic players dependent on vendor analytics. Pricing pressure stems from compressed investment yields on long-tail reserves, with liability lines experiencing the steepest margin erosion. SMEs exhibit highest price sensitivity, while multinational headquarters accept premium loading for bespoke coverage wordings and captive coordination.
Supply Chain Analysis
Actuarial talent shortages in Singapore and London constrain underwriting capacity for complex commercial risks. Risk modeling capabilities draw from vendor relationships with RMS and AIR Worldwide, while reinsurance capacity sources from Bermuda, London, and regional Asian markets. Single-source vulnerability concentrates in catastrophe model licensing, where three vendors control proprietary hazard data. Distribution runs through broker networks for corporates and embedded platforms for SME digital acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Monetary Authority of Singapore's risk-based capital framework functions as a cost-of-compliance moat, elevating operational thresholds that filter out undercapitalized entrants and reward established carriers with sophisticated risk infrastructure.
For Market Incumbents: Acquire catastrophe modeling talent pools in climate science and actuarial analytics to defend pricing precision against parametric disruptors. Deepen captive reinsurance capabilities to reduce dependency on tightening global retrocession capacity. Fortify API-first distribution architectures before legacy system constraints cede SME segments to platform-native competitors. For New Entrants and Emerging Players: Mid-market logistics operators in Tuas and Jurong present underserved demand for parametric flood coverage with satellite-triggered payouts. Digital-native SMEs in one-north technology precincts show lowest penetration for modular cyber-embedded D&O products. Partner with property leasing platforms and e-commerce checkout flows to bypass established broker channels. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to regional Asian insurers seeking Singapore licensing and MAS compliance infrastructure. Long-term viability favors carriers with proprietary risk engineering capabilities and renewable energy project underwriting franchises. Watch MAS climate scenario testing mandates as the inflection signal for capital reallocation toward resilient infrastructure specialists.| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Product Development | Enables satellite-triggered payouts that bypass traditional claims adjustment for flood-exposed industrial operators. |
| Catastrophe Modeling Talent Acquisition | Reduces dependency on external vendor models for climate risk pricing under MAS risk-based capital requirements. |
| Embedded Distribution Partnerships | Integrates coverage into Grab Financial and property leasing workflows, displacing agency-dependent acquisition. |
| Captive Reinsurance Structuring | Internalizes capacity for high-severity commercial property risks amid global retrocession market tightening. |
| Renewable Energy Underwriting Expansion | Captures engineering and construction all-risk demand from Southeast Asian solar and offshore wind projects. |
Research Methodology
Multi-period observation of premium volume trajectories, regulatory filing patterns, and risk capital deployment anchored the trend analysis, supplemented by interviews with underwriting directors, actuarial heads, broker placement specialists, and risk managers at multinational headquarters. Secondary validation drew from MAS regulatory circulars, insurer financial statements, reinsurance market reports, and catastrophe model vendor disclosures. Bottom-up policy-level data triangulated against top-down market sizing from regulatory aggregates.
Input-output matrices mapped exposure growth across product type, customer segment, coverage structure, and distribution channel dimensions throughout the forecast period. CAGRs derived from regression analysis of historical premium trends adjusted for regulatory capital requirement changes and climate risk recalibration. Industry-specific forecast inputs incorporated Green Plan 2030 construction mandate timelines and Port of Singapore transshipment volume projections.
Revisions become necessary when MAS capital framework amendments, global retrocession market dislocations, or climate scenario testing mandate expansions materialize beyond modeled assumptions. Forecasts reflect documented expectations regarding regulatory stability and catastrophe model vendor market structure. A small set of named triggers—reinsurance capacity shocks, parametric product regulatory clarity, and embedded distribution platform consolidation—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Electronic Gadgets Insurance Market
Insurance
Saudi Arabia Property and Casualty Insurance Market
Insurance
Germany Property and Casualty Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market
Insurance
Business Insurance Market
Insurance
Peer to Peer Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Insurance Protection Products Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Insurance Brokerage Market
Insurance
Germany Reinsurance Market
Insurance
AI in Insurance Market
Insurance
Bancassurance Market
Insurance
GCC Health Insurance Market
Insurance
Logistics Insurance Market
Insurance
GCC Bancassurance Market