
 Europe Health Insurance Market | 2026-2036
Europe Health Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Health Insurance Market Foresight
Digital-first service platforms are recalibrating distribution economics across the Europe Health Insurance Market. Munich Re leverages its reinsurance scale to anchor risk-bearing capacity for primary carriers across the continent. AXA competes through integrated health and property-casualty bundling in France and Southern Europe. Allianz dominates the German-speaking markets with employer-centric group health contracts and captive agency networks.
Europe health insurance constitutes risk-pooling arrangements covering medical treatment, preventive care, and income replacement during illness, underwritten through statutory solidarity funds, private indemnity contracts, or employer-sponsored schemes. The primary purpose centers on financial protection against health expenditure volatility while ensuring care access across diverse national delivery systems. Public health coverage retains structural dominance in France, Germany, and Italy through statutory fund architectures, yet private supplemental and comprehensive plans capture expanding margin pools among affluent individuals and cross-border mobile professionals. Managed care payment models are gaining traction as governments seek cost containment without explicit rationing.
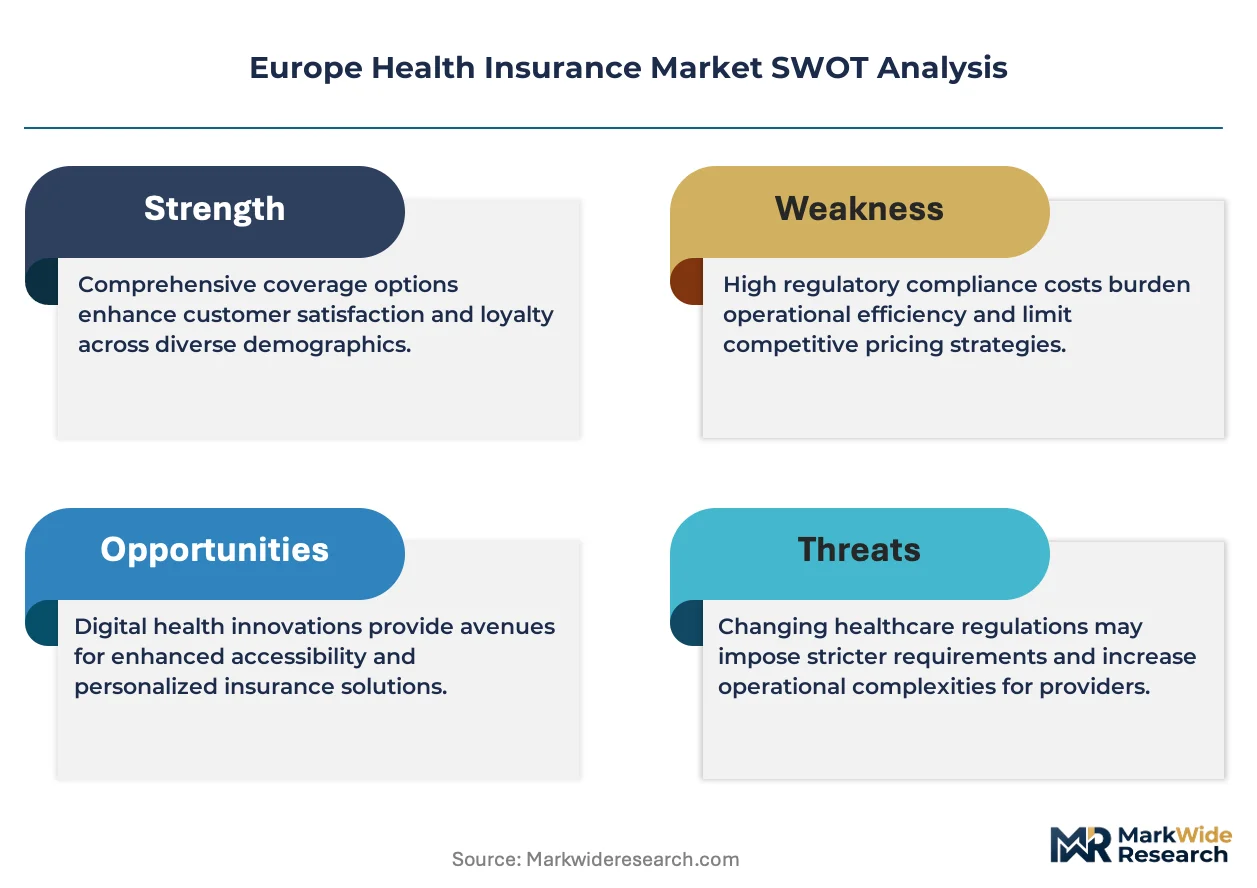
EU-level regulation through EIOPA solvency standards and the GDPR framework shapes capital requirements and data governance across national markets, while country-specific statutory fund oversight by Germany's Federal Financial Supervisory Authority and France's Prudential Supervision and Resolution Authority determines product design and pricing flexibility. The EU AI Act will soon constrain algorithmic underwriting and claims automation, forcing insurers to revalidate scoring models for fairness and explainability. Stakeholders must monitor how national implementation of these layered directives reshapes competitive boundaries between statutory and private coverage domains.
Market Dynamics
EIOPA solvency standards and the EU AI Act are compressing underwriting margins while forcing carriers to rebuild algorithmic models for fairness compliance, fundamentally altering risk selection economics across European health insurance.
Growth Catalysts
- Statutory fund competition:Germany's Federal Financial Supervisory Authority has intensified rivalry among sickness funds, pushing beneficiaries toward private supplementary coverage for dental and optical services.
- GDPR-compliant data monetization:Aggregated anonymized health datasets are enabling predictive wellness programs that reduce claims frequency for employer-sponsored schemes.
- Telemedicine infrastructure:France's Prudential Supervision and Resolution Authority has clarified reimbursement frameworks for remote consultations, accelerating platform adoption by regional mutual insurers.
Market Restraints
- Medical inflation divergence:Pharmaceutical and advanced therapy costs in Switzerland and Germany are rising faster than premium adjustment mechanisms allow.
- Reinsurance capacity concentration:Munich Re and Swiss Re dominate catastrophic health risk coverage, creating pricing power asymmetries for primary carriers.
- EU AI Act compliance timelines:Algorithmic underwriting systems require revalidation by 2026, freezing product innovation cycles for mid-sized insurers.
Strategic Opportunities
- Polish and Romanian employer markets:Corporate health benefits penetration remains below 15%, creating whitespace for group policy expansion.
- Preventive care integration:Wearable data partnerships with fitness platforms enable dynamic pricing models that reward policyholder behavior modification.
- CSRD-aligned health reporting:Mandatory workforce wellness disclosures are driving demand for occupational health insurance bundling with ESG compliance services.
Industry Challenges
- Actuarial-technology hybrid talent:Insurers struggle to recruit professionals who combine traditional risk modeling with machine learning interpretability requirements.
- Legacy core system migration:Decades-old policy administration platforms resist API integration with digital distribution channels, delaying real-time quoting capabilities.
- Cross-border claims adjudication:Varying national electronic health record standards complicate reimbursement processing for mobile professionals under portable coverage schemes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Health Insurance Market |
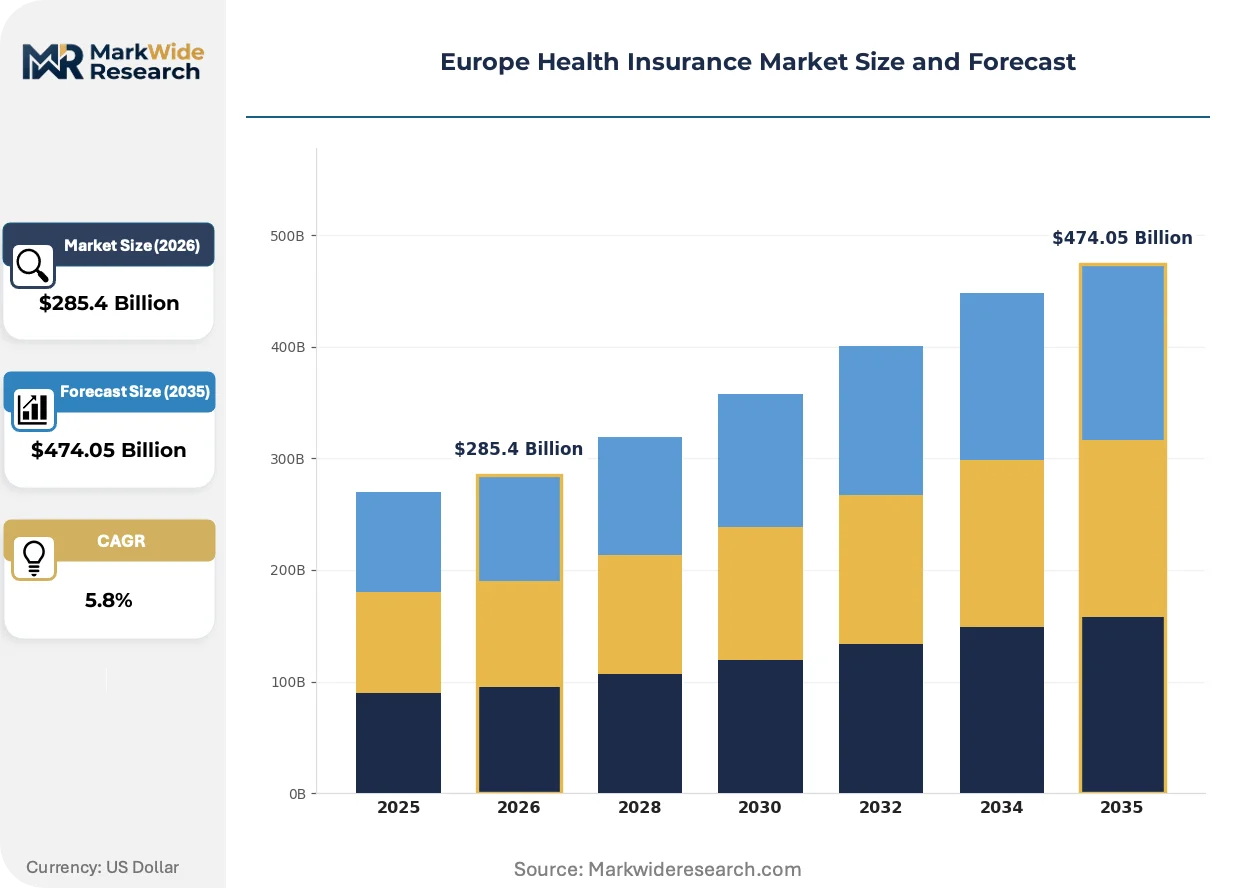
| Market Size in 2026 | $285.4 Billion |
| Market Size in 2035 | $474.05 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Public Health, Private Health, Supplemental Coverage, Comprehensive Plans Policy Duration: Short-term, Long-term, Annual, Multi-year End User: Individuals, Families, SMEs, Corporates Payment Model: Fee-for-service, Capitation, Indemnity, Managed Care |
| Companies Covered | Munich Re, Mapfre, AXA, Crédit Agricole Assurances, CNP Assurances, Allianz, Zurich Insurance Group, BNP Paribas Cardif, Assicurazioni Generali, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Health Insurance Market Shifts & Advancements
European health insurance is pivoting from indemnity reimbursement toward integrated care orchestration, with technology and regulation jointly determining which carriers can capture value from this structural shift.
Machine learning risk stratification is rewriting how insurers segment policyholder pools. German and Dutch carriers now deploy predictive models to identify high-cost chronic conditions before symptom onset. This capability is compressing traditional underwriting cycles and enabling preemptive care intervention.
The EU AI Act's prohibition on opaque automated decision-making is forcing algorithmic transparency. Insurers must document scoring logic and provide human review options for adverse coverage decisions. France's CNIL has already issued guidance on health data processing limits, pushing carriers toward explainable model architectures.
Corporate procurement teams are consolidating wellness spend under single-vendor arrangements. Brokers in the Netherlands and Belgium now bundle health insurance with occupational psychology and nutrition coaching. This unbundling of traditional coverage components favors carriers with captive care networks over pure indemnity underwriters.
Europe Health Insurance Market Segmentation
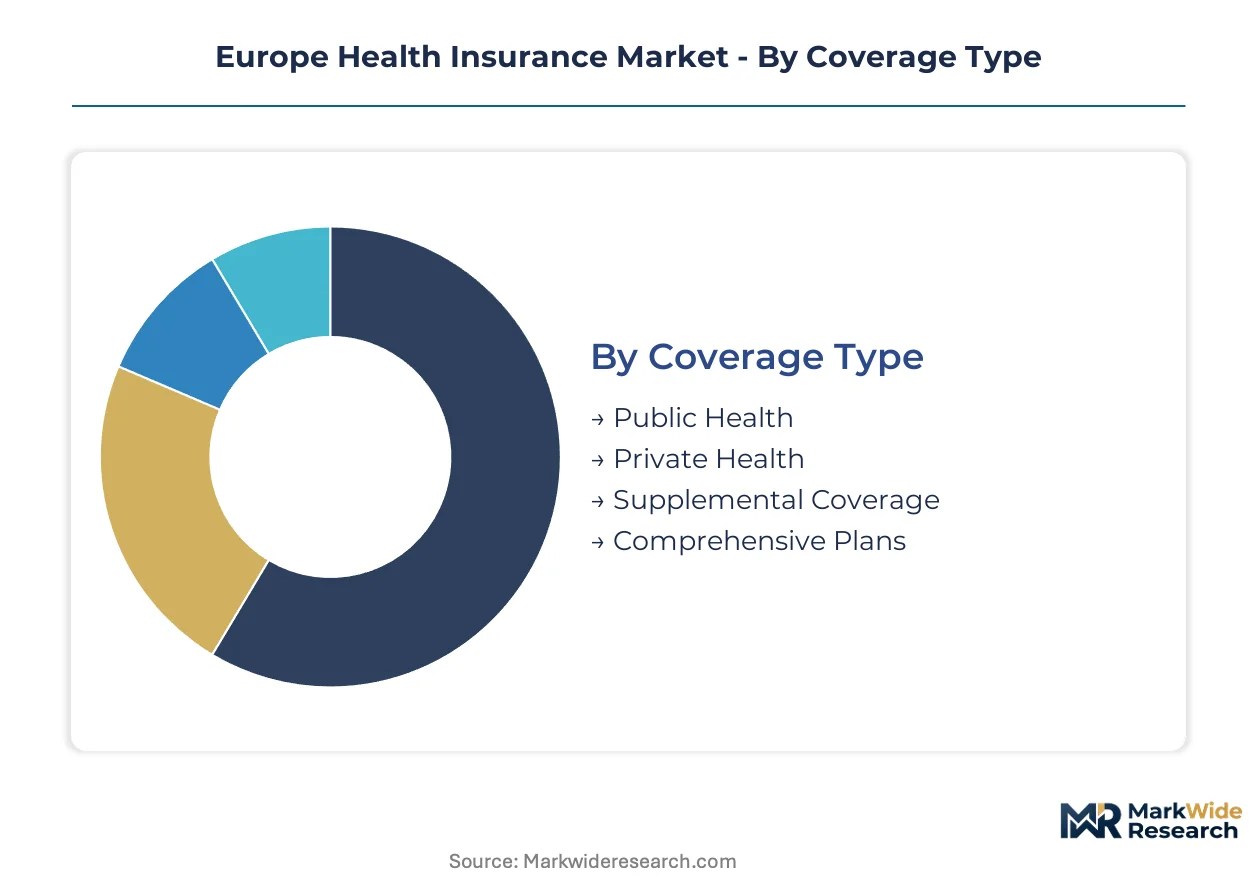
Segmentation in European health insurance reveals how risk-bearing structures fragment across statutory solidarity systems, private indemnity markets, and employer-sponsored pools. Each dimension carries distinct capital requirements, distribution economics, and regulatory exposure that determine carrier profitability.
Coverage Type:
Risk-bearing capacity concentrates disproportionately in statutory funds across Germany, France, and Italy, yet margin pools shift toward supplemental and comprehensive private products.
- Public Health:Statutory solidarity funds dominate enrollment volume through mandatory payroll contributions. Germany's Federal Financial Supervisory Authority oversees competitive bidding among sickness funds, compressing administrative margins while preserving risk-pooling scale.
- Private Health:Indemnity contracts targeting affluent individuals and cross-border mobile professionals capture premium pricing flexibility. French mutual insurers and German private health carriers compete through differentiated hospital access tiers and specialist network breadth.
- Supplemental Coverage:Dental, optical, and alternative therapy riders generate recurring revenue with lower loss ratios than core medical coverage.
- Comprehensive Plans:Integrated inpatient-outpatient-mental health bundles appeal to expatriate executives and high-net-worth households seeking concierge-level service coordination.
Today's leader: Public Health. Tomorrow's challenger: Comprehensive Plans.
Policy Duration:
Pricing precision varies sharply by contract length, with longer tenures enabling predictive wellness investments and shorter cycles favoring transactional distribution.
- Short-term:Travel and cross-border worker policies priced dynamically against claims experience. Dutch brokers dominate this segment through digital platform aggregation.
- Long-term:Guaranteed renewable contracts lock in premium stability for policyholders while exposing carriers to medical inflation risk over multi-decade horizons.
- Annual:Standard renewal cycles align with corporate benefits enrollment periods and individual tax optimization calendars.
- Multi-year:Corporate group contracts spanning three to five years enable capitation-based payment experiments and captive care network development.
Annual contracts anchor current premium volume. Multi-year structures are climbing the fastest as employers seek cost predictability.
End User:
Procurement authority determines distribution channel economics, with intermediated corporate sales yielding scale and direct-to-consumer paths preserving margin.
- Individuals:Price-sensitive shoppers comparing standardized benefit tables through aggregator platforms. GDPR-compliant data sharing enables personalized quoting in Germany and the Netherlands.
- Families:Multi-life policies with pediatric dental and maternity riders command premium multiples over single adult coverage.
- SMEs:Businesses with 10-250 employees represent whitespace in Poland and Romania where broker penetration remains underdeveloped.
- Corporates:Multinational employers consolidate wellness spend under single-vendor arrangements, bundling health insurance with occupational psychology and nutrition coaching.
Corporates dominate current procurement value. SMEs offer the steepest expansion trajectory as benefits penetration deepens in Eastern Europe.
Payment Model:
Reimbursement mechanics shape care utilization patterns and insurer-provider bargaining power across national delivery systems.
- Fee-for-service:Itemized billing for each consultation, procedure, and hospital day. France's Prudential Supervision and Resolution Authority maintains reimbursement schedules that constrain provider price inflation.
- Capitation:Fixed per-member-per-month payments to primary care networks. German sickness funds deploy this model to align physician incentives with preventive care goals.
- Indemnity:Fixed cash payments upon diagnosis or hospitalization, decoupled from actual treatment costs. Appeals to policyholders seeking flexibility in provider choice.
- Managed Care:Prior authorization requirements, gatekeeper primary care, and narrow network restrictions containing expenditure growth. Gaining traction as governments seek cost containment without explicit rationing.
Fee-for-service retains structural dominance. Managed Care is gaining share fastest as public budgets tighten across Southern Europe.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's statutory sickness fund ecosystem anchors premium generation across the European health insurance landscape, while private supplementary coverage penetration creates parallel margin pools in affluent metropolitan zones.
Germany
Competition among statutory sickness funds intensifies under Federal Financial Supervisory Authority oversight, pushing beneficiaries toward private dental and optical riders. Berlin and Munich concentrate employer-sponsored scheme administration for multinational corporations. Munich Re anchors continental reinsurance capacity from its Bavarian headquarters.
France
Mutual insurers dominate supplemental coverage through branch networks embedded in regional banking partnerships. Prudential Supervision and Resolution Authority frameworks clarify telemedicine reimbursement, accelerating platform adoption by Paris-based mutuals. Île-de-France houses the densest concentration of corporate benefits brokers.
United Kingdom
Corporate private medical insurance sustains volume despite National Health Service universal coverage. Financial Conduct Authority solvency requirements shape product design flexibility. London's Square Mile concentrates broker intermediation for financial services sector employers.
Switzerland
Cantonal premium variation creates arbitrage opportunities for basic coverage shopping. Swissmedic oversees supplemental benefit quality standards. Zurich and Geneva anchor international expatriate comprehensive plan underwriting for mobile professionals.
Netherlands
Managed care capitation models align physician incentives with preventive care goals under Dutch Central Bank supervision. Amsterdam's Zuidas district concentrates health-tech platform development for employer wellness bundling. Rotterdam brokers facilitate SME group policy aggregation.
Europe Health Insurance Market Competitive Landscape
Global majors compete with regional champions across distribution channel depth, with reinsurance scale and captive agency networks determining pricing power asymmetries. Market structure tilts toward consolidation at the reinsurance tier while primary carrier fragmentation persists across national statutory fund architectures. Three archetypes dominate: continental reinsurance giants anchoring catastrophic risk capacity, bancassurance-integrated composite insurers leveraging deposit base reach, and specialized mutuals rooted in occupational solidarity traditions. Competitive moves concentrate on algorithmic underwriting capability acquisition and cross-border digital platform licensing.
Within the reinsurance tier, Munich Re and Swiss Re occupy positions as catastrophic health risk capacity anchors for primary carriers continent-wide. Among composite insurers with bancassurance DNA, AXA and Allianz exemplify integrated health-property-casualty bundling strategies. Crédit Agricole Assurances represents the mutual banking group archetype with embedded branch distribution.
| Leading Market Players |
|---|
| Munich Re |
| Mapfre |
| AXA |
| Crédit Agricole Assurances |
| CNP Assurances |
| Allianz |
| Zurich Insurance Group |
| BNP Paribas Cardif |
| Assicurazioni Generali |
| Others |
Supply & Pricing Matrix
Corporate procurement consolidation across Germany and France is forcing insurers to restructure distribution networks toward direct employer channels, compressing intermediary margins and elevating price transparency pressures on regional mutuals.
Pricing Analysis
Medical service cost pass-through from German statutory sickness funds drives premium adjustment cycles for supplemental coverage tiers. Price differentiation hinges on hospital network breadth and telemedicine platform integration. Cost compression in basic indemnity lines intensifies because pharmaceutical inflation outpaces premium indexing mechanisms. SMEs exhibit highest price sensitivity, while multinational employers prioritize service coordination over rate minimization.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the Netherlands anchor policy administration and claims processing infrastructure for cross-border employer schemes. Core underwriting capacity draws from Munich Re and Swiss Re catastrophic risk pools. Single-source vulnerability concentrates in algorithmic scoring model vendors serving mid-sized carriers. Distribution runs through captive agency networks in German-speaking markets and bancassurance partnerships in France and Italy.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Statutory fund competition arbitrage between Germany's Federal Financial Supervisory Authority pricing floors and Poland's underdeveloped employer benefits penetration creates margin expansion opportunities for carriers with cross-border licensing capabilities.
For Market Incumbents: Acquire digital health platform assets to preempt disintermediation by telemedicine-native entrants. Consolidate reinsurance relationships with Munich Re or Swiss Re before capacity tightens further. Invest in GDPR-compliant data infrastructure to defend against algorithmic underwriting challengers. For New Entrants and Emerging Players: The EU AI Act in Brussels opens a window for explainable-model specialists to capture mid-sized insurer modernization contracts. Target Polish and Romanian SME employer markets where broker penetration remains below 15%. Deploy direct-to-employer digital distribution to bypass entrenched agency networks. For Investors and Strategic Acquirers: Asymmetric upside sits with regional mutuals possessing embedded branch networks and untapped data monetization potential. Long-term viability centers on carriers with captive care network integration rather than pure indemnity underwriters. Monitor EIOPA solvency standard implementation timelines as inflection indicators for consolidation pressure.| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Model Revalidation | EU AI Act compliance deadlines force carriers to rebuild scoring architectures for fairness transparency. |
| Telemedicine Platform Licensing | France's Prudential Supervision and Resolution Authority reimbursement clarity accelerates mutual insurer adoption. |
| Cross-Border Digital Distribution | GDPR-compliant data sharing enables personalized quoting for mobile professionals across Benelux markets. |
| Preventive Care Network Integration | German sickness fund capitation models reward carriers with captive primary care relationships. |
| Reinsurance Capacity Lock-In | Munich Re's Bavarian headquarters anchors continental catastrophic health risk coverage for primary carriers. |
Research Methodology
Multiple input streams — carrier underwriting executives, EIOPA regulatory affairs specialists, employer benefits procurement managers, and hospital system contracting officers — were reconciled against statutory fund enrollment databases, national health expenditure accounts, and reinsurance treaty disclosures. Bottom-up policy volume estimates triangulated with top-down premium generation models across coverage type, policy duration, and payment model dimensions.
Historical enrollment trajectories cross-referenced against panel-based expert assessments shaped the analytical framework across the projection horizon. Segmentation modeling incorporated coverage type, end-user procurement authority, and national regulatory cluster variations. CAGRs derived from medical inflation differentials, demographic shift projections, and technology adoption curves for algorithmic underwriting platforms.
Revisions become necessary when EIOPA solvency standard amendments, EU AI Act enforcement interpretations, or statutory fund merger waves materialize beyond baseline assumptions. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Asia-Pacific AI in Insurance Market
Insurance
Musical Instrument Insurance Market
Insurance
Indonesia Private Health Insurance Market
Insurance
Bancassurance in ASEAN Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Singapore Business Income Insurance Market
Insurance
Germany Reinsurance Market
Insurance
Japan Property and Casualty Insurance Market
Insurance
Global Vehicle Insurance Market
Insurance
General Insurance Market
Insurance
Saudi Arabia Travel Insurance Market
Insurance
USA Travelers Insurance Market
Insurance
China Online Insurance Market
Insurance
Single Trip Travel Insurance Market
Insurance
Global SME Insurance Market
Insurance
Norway Cyber (Liability) Insurance Market