
 Asia-Pacific Insurance Aggregators Market | 2026-2036
Asia-Pacific Insurance Aggregators Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Insurance Aggregators Market Analytics
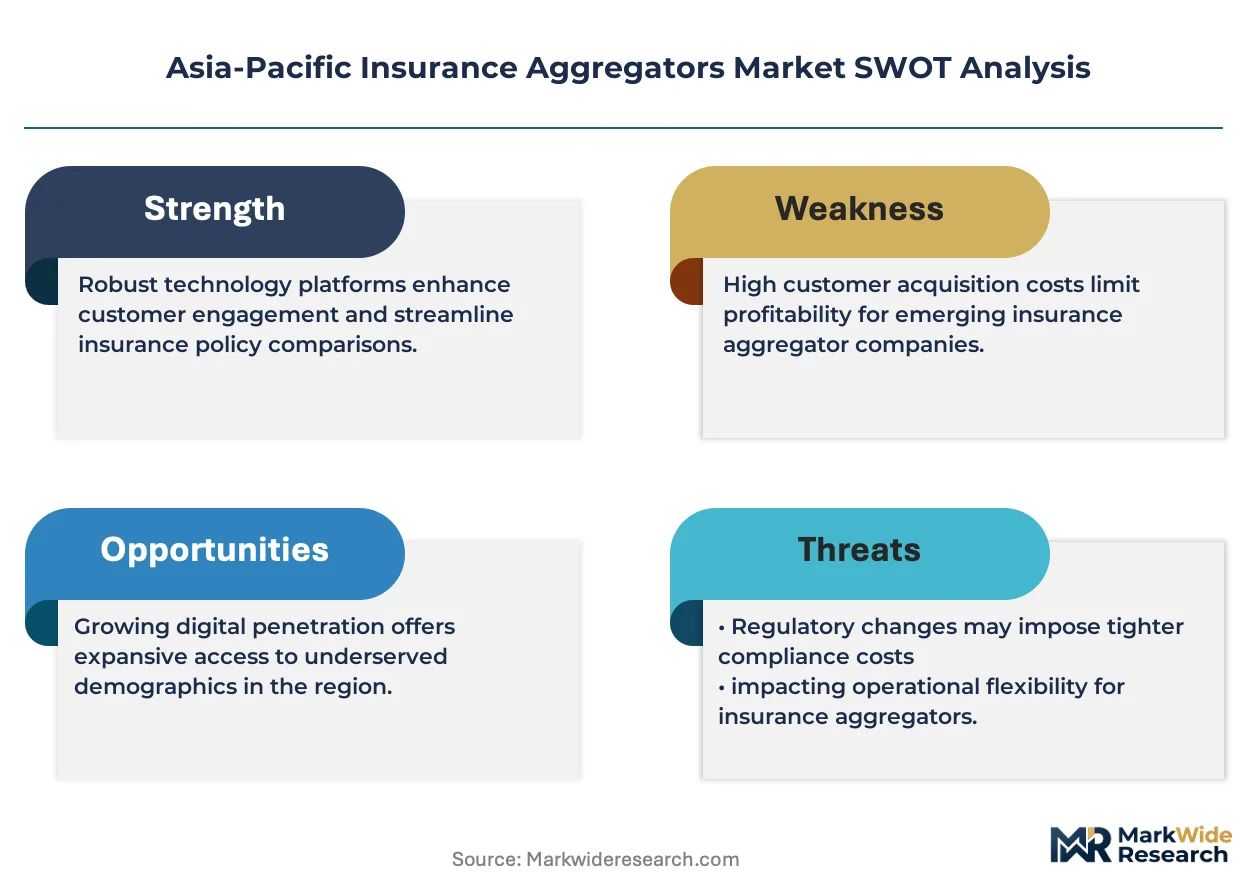
The premium aggregator tier anchored by full-service advisory and embedded claims assistance is rebalancing against commodity quote-comparison-only platforms. PolicyBazaar leverages its vertical integration into policy issuance and renewal management to sustain dominance across Indian metro markets. GoDifferentiates through its API-first architecture that embeds directly into neobank and fintech partner ecosystems.
Asia-Pacific insurance aggregators are digital intermediaries that algorithmically normalize policy features, premium rates, and underwriting terms from multiple insurers into comparable formats, typically processing quote requests through real-time data feeds to carrier rating engines. Comparison Services command the largest transaction volume while AI-Driven Solutions capture the fastest expansion as natural-language underwriting and predictive risk scoring displace static form-based quoting. Mobile Applications occupy a structurally critical position across Indonesia, Philippines, and Vietnam where smartphone penetration exceeds desktop insurance search behavior.
India's IRDAI regulates aggregator licensing and commission disclosure while Australia's ASIC enforces design and distribution obligations under the Corporations Act; both frameworks elevate compliance costs for entrants but protect incumbent platforms with established legal infrastructure. Singapore's MAS digital bank licensing regime indirectly expands aggregator addressable market by legitimizing embedded insurance distribution through non-traditional channels. Stakeholders must monitor whether ASEAN member states harmonize electronic signature and remote KYC standards to unlock cross-border policy comparison.
Market Dynamics
Asia-Pacific insurance aggregators face a structural pivot where mobile-first distribution is converging with embedded finance partnerships, compressing the traditional quote-comparison window and forcing platforms to own policy lifecycle management rather than lead generation alone.
Growth Catalysts
- IRDAI Sandbox Framework:India's regulator permits controlled digital insurance experimentation, lowering barriers for algorithmic underwriting pilots and API-driven distribution models that normalize multi-carrier comparison in real time.
- Neobank Embedded Distribution:Fintech partnerships in Indonesia and the Philippines place insurance comparison interfaces directly within mobile banking workflows, capturing users at transaction moments rather than active search moments.
- AI-Driven Natural Language Quoting:Conversational interfaces and predictive risk scoring displace static form-based applications, reducing quote abandonment rates and expanding addressable markets among digitally native small businesses.
Market Restraints
- Commission Disclosure Mandates:Australia's ASIC design and distribution obligations force granular cost transparency, compressing aggregator margins and elevating compliance infrastructure spend for entrants.
- Carrier API Fragmentation:Inconsistent data standards across Southeast Asian insurers force aggregators to maintain multiple integration layers, raising technical debt and slowing product expansion timelines.
- Desktop-Legacy Brokerage Persistence:Established agent networks in Japan and South Korea retain corporate and high-net-worth segments through relationship-based servicing that digital platforms struggle to replicate.
Strategic Opportunities
- Vietnam Mobile Penetration Gap:Smartphone insurance search behavior exceeds 80 percent in urban centers yet aggregator presence remains thin, creating first-mover advantage for platforms with Vietnamese-language conversational interfaces.
- ASEAN Cross-Border Harmonization:Proposed electronic signature and remote KYC standardization across member states would unlock multi-jurisdiction policy comparison, expanding addressable premium pools for regional platforms.
- Claims Assistance Integration:Premium-tier aggregators embedding end-to-end claims advocacy capture higher retention and commission rates, differentiating against commoditized quote-only competitors.
Industry Challenges
- Actuarial-AI Talent Scarcity:The intersection of traditional underwriting expertise and machine learning implementation remains thin across the region, forcing platforms to import talent or accept slower model deployment.
- Legacy System Integration Friction:Many Southeast Asian insurers operate on decades-old policy administration systems, creating API latency and data inconsistency that degrades real-time quote accuracy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Insurance Aggregators Market |
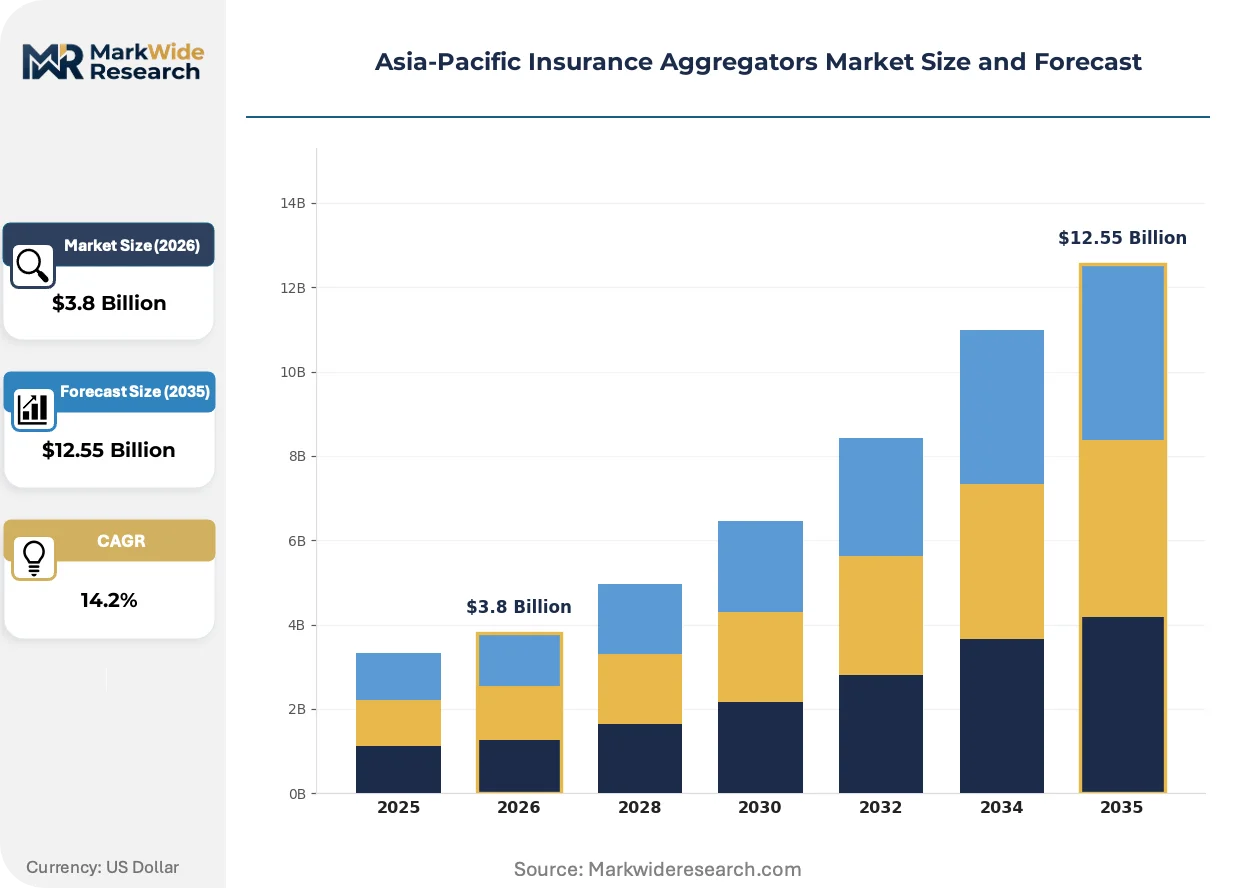
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Comparison Services, Multi-Channel Platforms, Policy Management Tools, Quote Aggregators Customer Type: Individual Consumers, Small Businesses, Corporates, Financial Institutions Technology: AI-Driven Solutions, Mobile Applications, Web Portals, Data Analytics Platforms Distribution Channel: Online Marketplaces, Direct Sales, Affiliate Partners, Brokers |
| Companies Covered | PolicyBazaar, Comparethemarket.com, Insurance.com, GoDigit, Acko, Coverfox, BankBazaar, OneAssure, uCompare, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Insurance Aggregators Market Evolving Landscape
Algorithmic underwriting and embedded distribution channels are actively restructuring how insurance comparison platforms capture value, shifting revenue models from lead fees toward policy lifecycle participation and partnership economics.
Machine learning risk models is converging with real-time telematics data streams to enable dynamic premium adjustment. Motor and health aggregators in Singapore and Thailand are piloting usage-based interfaces that price coverage based on actual driving behavior or wearable-verified activity levels. This convergence is compressing the traditional annual renewal cycle into continuous pricing relationships that reduce churn and expand margin capture.
Singapore's MAS digital bank licensing regime legitimizes embedded insurance distribution through non-traditional channels, granting neobanks and e-wallet operators direct policy placement authority. The industrial consequence is a fragmentation of the aggregator role, with pure-play comparison sites competing against captive distribution arms of financial super-apps. Platforms without embedded finance partnerships face disintermediation in the city-state's concentrated urban market.
Small business procurement of commercial coverage is rotating from broker-mediated annual reviews toward self-service digital comparison with immediate policy issuance. This pattern is most visible in India's tier-two cities, where IRDAI-sandbox-enabled platforms offer packaged liability and property products with simplified risk questions and instant documentation. The shift compresses sales cycles from weeks to minutes but demands aggregators absorb more underwriting authority and claims handling responsibility.
Asia-Pacific Insurance Aggregators Market Segmentation
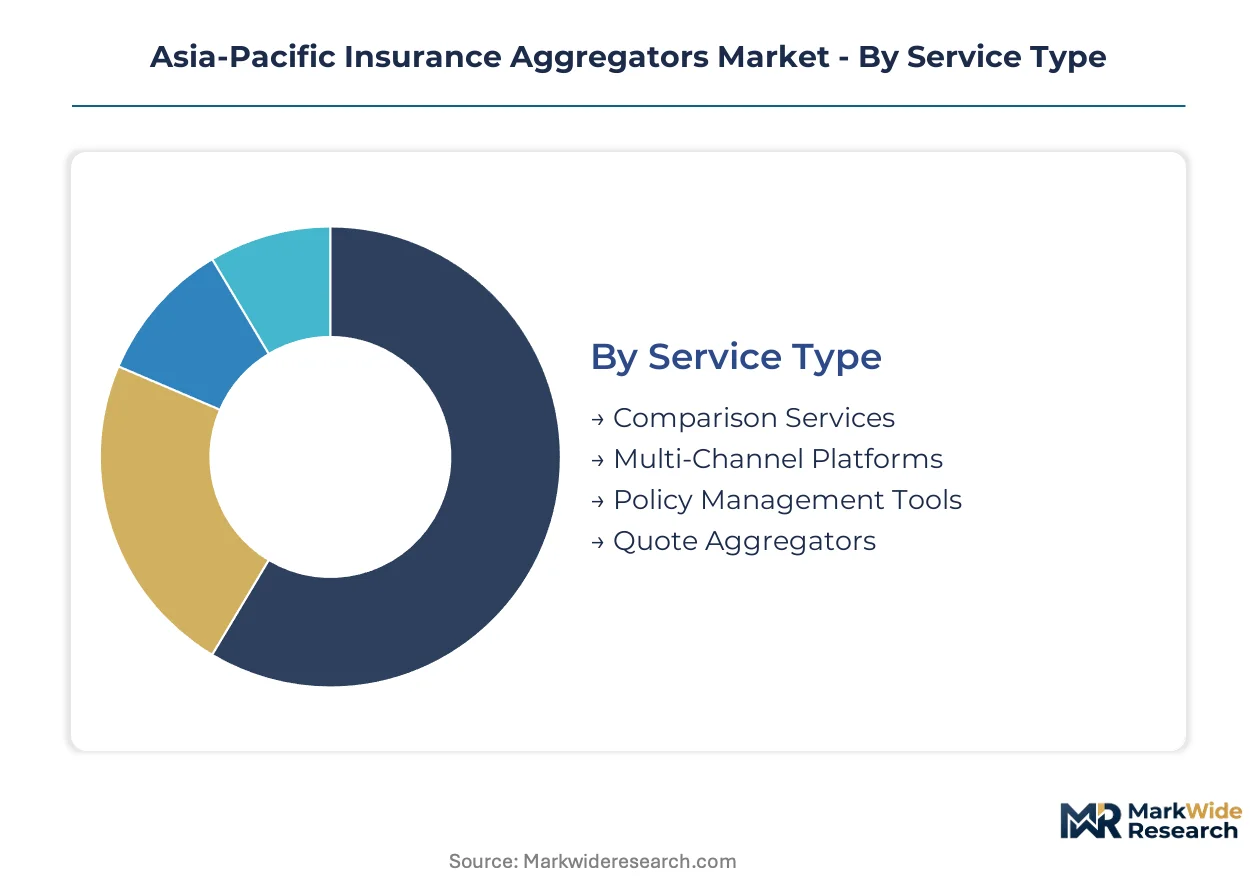
Insurance aggregators in Asia-Pacific segment across service architecture, customer sophistication, and distribution technology, with each axis determining platform economics and regulatory exposure. Understanding these divisions clarifies why certain models dominate specific national markets while others struggle with carrier integration costs.
Service Type:
Supply concentration tilts toward platforms that own the full policy lifecycle rather than lead generation alone.
- Comparison Services:Algorithmic normalization of policy features, premium rates, and underwriting terms from multiple insurers into comparable formats. Demand clusters in Southeast Asian metro markets where mobile-first search behavior exceeds desktop usage, though carrier API fragmentation forces aggregators to maintain multiple integration layers.
- Multi-Channel Platforms:Hybrid architectures combining digital interfaces with human advisory touchpoints for complex commercial coverage. Small business procurement across India's tier-two cities favors this model where IRDAI-sandbox-enabled platforms offer packaged liability products with simplified risk questions.
- Policy Management Tools:Post-issuance servicing platforms handling renewals, endorsements, and documentation.
- Quote Aggregators:Real-time rating engines connecting to carrier systems for instant premium calculation.
Comparison Services absorb the bulk of installed capacity; AI-enhanced Policy Management Tools are expanding most quickly.
Customer Type:
Margin profiles diverge sharply between relationship-heavy corporate segments and self-service digital acquisition.
- Individual Consumers:Digitally native users seeking motor, health, and term life coverage through smartphone interfaces. Urban centers in Indonesia and Vietnam drive volume where smartphone penetration exceeds eighty percent yet aggregator presence remains thin.
- Small Businesses:Commercial procurement rotating from broker-mediated annual reviews toward immediate digital issuance. India's IRDAI sandbox framework enables packaged products with instant documentation, compressing sales cycles from weeks to minutes.
- Corporates:Established agent networks in Japan and South Korea retain these segments through relationship-based servicing that pure digital platforms struggle to replicate.
- Financial Institutions:Banks and neobanks embedding insurance comparison within mobile banking workflows, capturing users at transaction moments rather than active search moments.
Individual Consumers generate the highest transaction volumes; Small Businesses deliver the steepest expansion trajectory as digital procurement normalizes.
Technology:
Development cost tiers separate AI-native platforms from legacy web infrastructure.
- AI-Driven Solutions:Conversational interfaces and predictive risk scoring displace static form-based applications. Singapore and Thailand motor aggregators pilot usage-based pricing using real-time telematics data streams to enable dynamic premium adjustment.
- Mobile Applications:Structurally critical across Indonesia, Philippines, and Vietnam where smartphone insurance search behavior dominates. API-first architectures embed directly into neobank and fintech partner ecosystems.
- Web Portals:Desktop-legacy interfaces retaining relevance in corporate and high-net-worth segments.
- Data Analytics Platforms:Backend systems processing behavioral and telematic inputs for risk model refinement.
Mobile Applications command the largest installed base; AI-Driven Solutions are climbing the fastest as natural-language underwriting reduces quote abandonment.
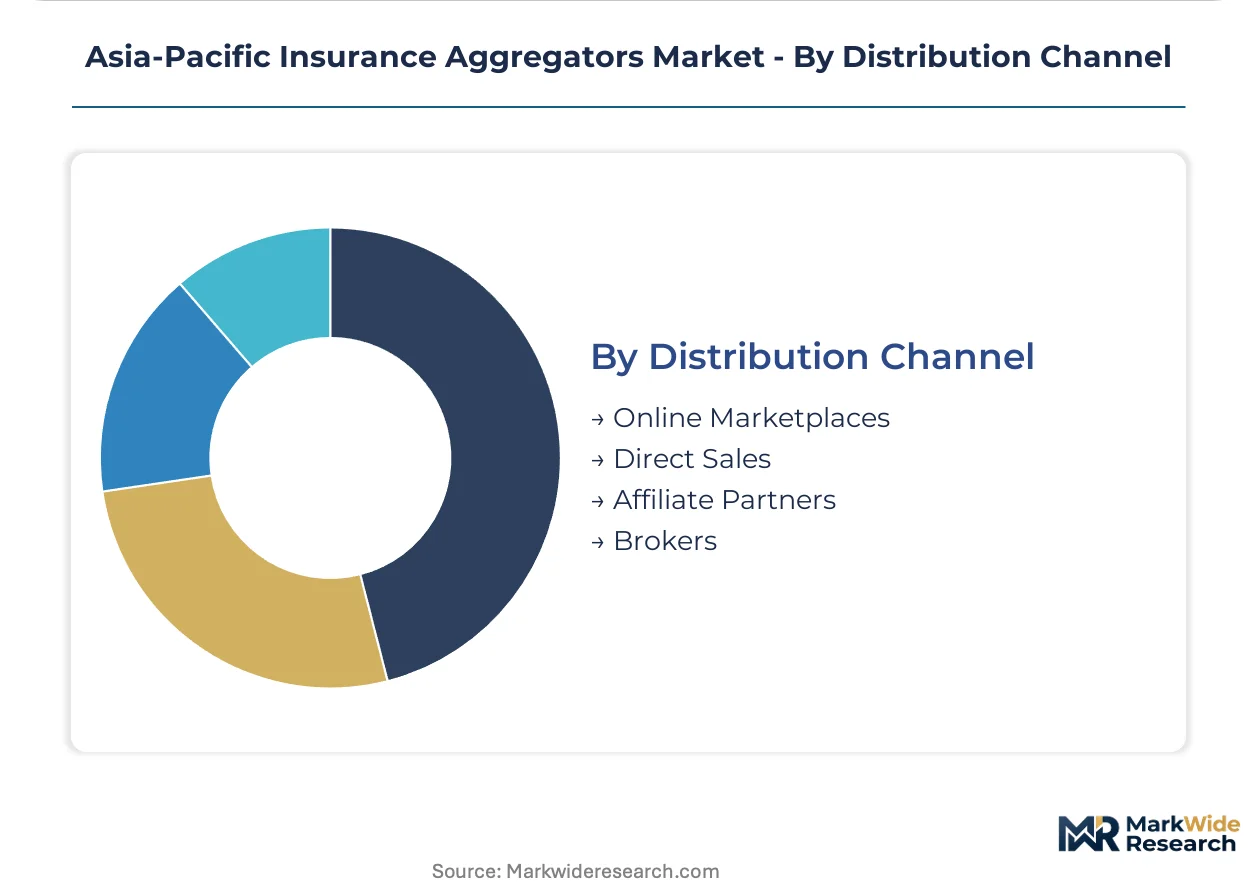
Distribution Channel:
Channel economics determine whether aggregators capture lead fees or full policy lifecycle value.
- Online Marketplaces:Pure-play comparison sites competing for search-driven traffic. Singapore's MAS digital bank licensing regime fragments this role as financial super-apps build captive distribution arms.
- Direct Sales:Proprietary acquisition through performance marketing and brand building.
- Affiliate Partners:Commission-based referral networks including content publishers and price comparison engines.
- Brokers:Traditional intermediaries integrating aggregator tools into existing client relationships.
Online Marketplaces retain the dominant share of transaction flow; embedded Affiliate Partners are gaining share fastest as fintech bundling accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Marina Bay financial district anchors embedded insurance distribution experimentation, where MAS digital bank licensing legitimizes neobank-captive placement channels.
India
IRDAI sandbox permits algorithmic underwriting pilots and API-driven distribution models. The regulator mandates commission disclosure and aggregator licensing. Mumbai and Bangalore clusters host PolicyBazaar and GoDigit, which integrate policy issuance and renewal management into metro market dominance.
Australia
ASIC design and distribution obligations enforce granular cost transparency under the Corporations Act. The regulatory framework elevates compliance infrastructure spend. Sydney and Melbourne financial centers retain established legal infrastructure protecting incumbent platforms against margin-compressed entrants.
Indonesia
Mobile-first insurance search behavior exceeds eighty percent in Jakarta and Surabaya urban corridors. Neobank partnerships embed comparison interfaces within mobile banking workflows. The national financial services authority oversees fintech licensing without harmonized electronic signature standards.
Vietnam
Smartphone penetration in Ho Chi Minh City and Hanoi exceeds aggregator platform presence, creating first-mover gaps. Vietnamese-language conversational interfaces remain thin. The Ministry of Finance regulates insurance intermediation without unified remote KYC protocols.
Thailand
Motor aggregators pilot usage-based pricing through real-time telematics data streams. The Office of Insurance Commission supervises digital distribution licensing. Bangkok's financial district concentrates embedded finance partnerships between insurers and regional e-wallet operators.
Asia-Pacific Insurance Aggregators Market Competitive Landscape
Premium-margin players sit above commodity-margin players across advisory depth and claims integration capabilities. The market structure fragments between full-service lifecycle managers and quote-only lead generators. Three archetypes dominate: vertically integrated issuers, API-first embedders, and hybrid human-digital advisors. Consolidation pressure favors M&A between aggregators lacking embedded finance partnerships and neobanks seeking insurance placement authority.
Within the vertically integrated tier, PolicyBazaar exemplifies metro-market dominance through captive policy administration. GoDigit occupies a position on the API-first vector, embedding comparison engines directly into fintech partner ecosystems. Acko represents the digital-native archetype with simplified risk questions and instant documentation capabilities.
| Leading Market Players |
|---|
| PolicyBazaar |
| Comparethemarket.com |
| Insurance.com |
| GoDigit |
| Acko |
| Coverfox |
| BankBazaar |
| OneAssure |
| uCompare |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up aggregator platforms across Southeast Asia exercise pricing discipline through captive renewal revenue streams and embedded distribution economics, compressing lead-generation-only competitors into commodity margins while elevating compliance infrastructure as a cost barrier.
Pricing Analysis
Outcome-based pricing tied to policy lifecycle participation anchors revenue models across premium-tier aggregators, separating full-service advisory platforms from quote-only competitors. Three-tier pricing structure across premium, standard, and economy levels stratifies by claims integration depth and API sophistication. Cost compression in the comparison-only tier intensifies because carrier commission disclosure mandates force margin transparency. Small businesses exhibit highest price sensitivity, while corporate segments prioritize advisory depth over premium differentials.
Supply Chain Analysis
India's domestic-content mandates for insurance technology infrastructure reshape sourcing toward locally hosted data centers and indigenous API development. Technology development concentrates in India, Singapore, and Australia, drawing from cloud computing resources, carrier rating engine integrations, and mobile SDK frameworks. Single-source vulnerability runs through legacy policy administration systems at Southeast Asian insurers. Distribution runs through neobank and fintech partner ecosystems rather than direct consumer acquisition.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific insurance aggregators operate as a cost-of-compliance story where India's IRDAI licensing framework and Australia's ASIC design obligations create regulatory moats protecting established platforms with pre-built legal infrastructure.
For Market Incumbents: Anchor metro-market dominance through backward integration into policy administration systems, absorbing claims handling authority that quote-only competitors cannot replicate. Deepen API-first partnerships with neobanks before financial super-apps build captive distribution arms. Vertical integration into renewal management and endorsement processing protects against disintermediation by embedded finance channels. For New Entrants and Emerging Players: The premium-economy tier gap in Vietnam's urban centers offers white-space entry where Vietnamese-language conversational interfaces remain thin. Target Indonesia's tier-two cities through neobank-embedded distribution rather than direct marketplace competition. Lead with AI-driven natural language quoting to reduce abandonment rates against static form-based incumbents. For Investors and Strategic Acquirers: Distressed-cycle entries favor API-first embedders with established fintech partnerships in Singapore and Indonesia, where MAS digital bank licensing legitimizes non-traditional distribution. Long-term viability hinges on platforms owning policy lifecycle economics rather than lead fees. Monitor ASEAN electronic signature harmonization as the inflection signal for cross-border premium pool expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Finance Partnership | Neobank integration in Indonesia captures users at transaction moments rather than active search. |
| Claims Assistance Integration | End-to-end advocacy capabilities differentiate premium aggregators from commoditized quote-only platforms. |
| AI-Native Quoting Architecture | Conversational interfaces reduce abandonment rates among digitally native small business segments. |
| Vertical Integration | Captive policy administration and renewal management sustains retention economics against lead generators. |
| Regional API Harmonization | Standardized carrier data feeds would compress technical debt across Southeast Asian expansion. |
Research Methodology
Document review covered IRDAI sandbox filings, ASIC regulatory guidance, and ASEAN fintech licensing frameworks, complemented by interviews with platform CTOs, carrier digital distribution heads, neobank product officers, and regulatory affairs specialists at national financial authorities. Secondary validation drew from SEC filings of listed insurance technology firms, venture capital investment databases, and mobile application analytics. Bottom-up transaction volume estimates triangulated against top-down premium pool calculations.
Segment-level projections across service architecture, customer sophistication, and distribution technology dimensions were generated through the analytical framework, with CAGRs derived from regression against mobile penetration curves and regulatory adoption timelines. Inputs included sandbox approval velocity, carrier API standardization progress, and embedded finance partnership density by metropolitan market.
Inputs from regulatory filing databases and primary stakeholder discussions were available through the study window; gaps in real-time carrier commission rate disclosures introduce uncertainty bands around margin projections. Forecasts reflect assumptions on ASEAN harmonization timelines and neobank licensing velocity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
France Liability Insurance Market
Insurance
US Long-Term Care Private Insurance Market
Insurance
Cloud Computing in Insurance Market
Insurance
Business Travel Accident Insurance Market
Insurance
Specialty Insurance Market
Insurance
Identity Theft Insurance Market
Insurance
Germany Reinsurance Market
Insurance
United Kingdom Parametric Insurance Market
Insurance
India Liability Insurance Market
Insurance
Horse Insurance Market
Insurance
Canada Cyber (Liability) Insurance Market
Insurance
Indonesia Private Health Insurance Market
Insurance
Saudi Arabia Property and Casualty Insurance Market
Insurance
Slovenia Property and Casualty Insurance Market
Insurance
US Property and Casualty (P&C) Insurance Market
Insurance
Business Travel Insurance Market