
 Commercial Earthquake Insurance Market | 2026-2036
Commercial Earthquake Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Commercial Earthquake Insurance Market Analysis
California's expanded underwriting capacity is reshaping how carriers allocate capital against peak seismic exposure. GeoVera Holdings Inc leverages proprietary catastrophe modeling to price layered policies along the San Andreas corridor. Zurich Insurance Group anchors European commercial portfolios through Swiss Re-backed facultative arrangements. FM Global Group differentiates via engineering-led risk selection that ties premium credits to structural retrofit verification.
Commercial earthquake insurance covers structural damage, business interruption, and contingent liabilities arising from seismic events, with policies typically attaching at deductibles between 10% and 20% of insured value and indemnity periods spanning 12 to 24 months for business income loss. The primary purpose centers on stabilizing corporate balance sheets against low-frequency, high-severity events that standard property policies exclude. Replacement cost policies command premium advantages over actual cash value structures as inflation-adjusted reconstruction costs climb across Pacific Rim fault zones. Small businesses represent the fastest-growing customer type as embedded agents automate quoting through parametric trigger platforms.
The California Earthquake Authority and Japan's Earthquake Reinsurance scheme establish pooled backstops that shape primary market capacity and deductible floors across their respective jurisdictions. FM Global's engineering standards and ISO 19901-2 seismic design provisions increasingly influence underwriting acceptability and premium differentiation in commercial placements. Stakeholders must monitor how parametric trigger adoption and satellite-based damage assessment tools redistribute pricing power between carriers and insureds.
Market Dynamics
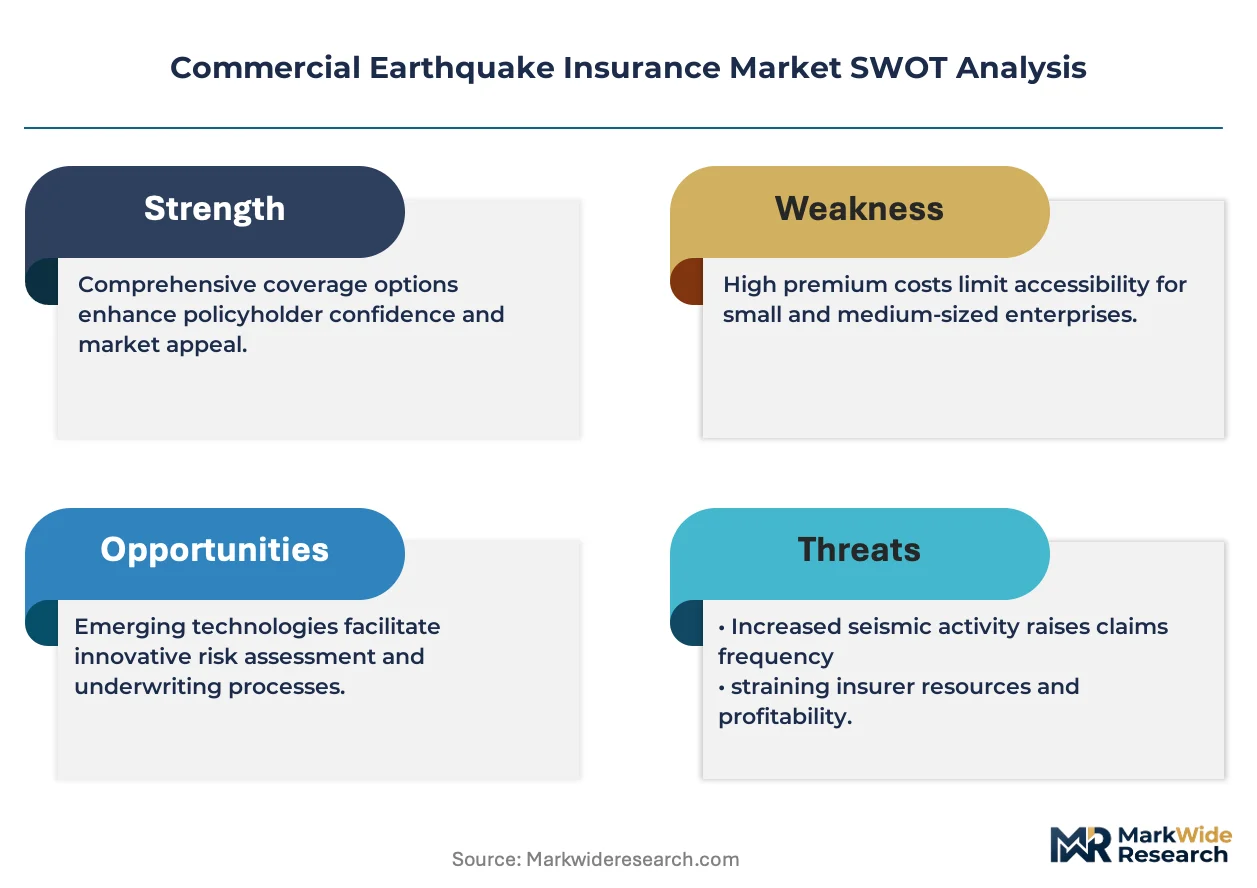
Parametric trigger platforms are compressing policy issuance cycles and redistributing pricing power from underwriters to algorithmic aggregators across seismically active corridors.
Growth Catalysts
- State-level retrofit mandates:California's escalating building code requirements are forcing commercial property owners to secure coverage as a condition of occupancy permits and financing.
- ISO 19901-2 seismic design provisions:Engineering-led risk selection frameworks are expanding insurable building stock by certifying retrofitted structures for standard market placement.
- Small business automation:Embedded agents leveraging API-connected quoting engines are unlocking penetration in previously underserved retail and service sectors.
Market Restraints
- Peak zone capacity concentration:Reinsurer appetite for San Andreas corridor layered risks hardens disproportionately after each seismic event, creating cyclical availability gaps.
- Replacement cost inflation:Construction material volatility and Pacific Rim labor shortages are inflating indemnity exposures beyond historical pricing models.
- Deductible floor rigidity:California Earthquake Authority pooling mechanics prevent meaningful reduction in 10-15% attachment points that exclude marginal buyers.
Strategic Opportunities
- Parametric satellite verification:Synthetic aperture radar damage assessment is enabling instant claims settlement without adjuster deployment, compressing liquidity timelines for insureds.
- Contingent business income riders:Supply chain interruption extensions are penetrating manufacturing and logistics verticals previously reliant on narrow property-only coverage.
- Japan Earthquake Reinsurance scheme alignment:Facultative capacity sharing with Tokyo-based pools could unlock yen-denominated capacity for US West Coast commercial portfolios.
Industry Challenges
- Catastrophe modeler talent scarcity:Actuarial teams with proprietary seismic risk coding capabilities command premium compensation that compresses carrier expense ratios.
- Legacy policy administration integration:Core systems built on 1990s mainframe architectures resist API connectivity with parametric trigger platforms, delaying product launches.
- Retrofit verification standardization:Inconsistent county-level building inspector certification creates underwriting uncertainty that inflates risk-adjusted pricing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Commercial Earthquake Insurance Market |
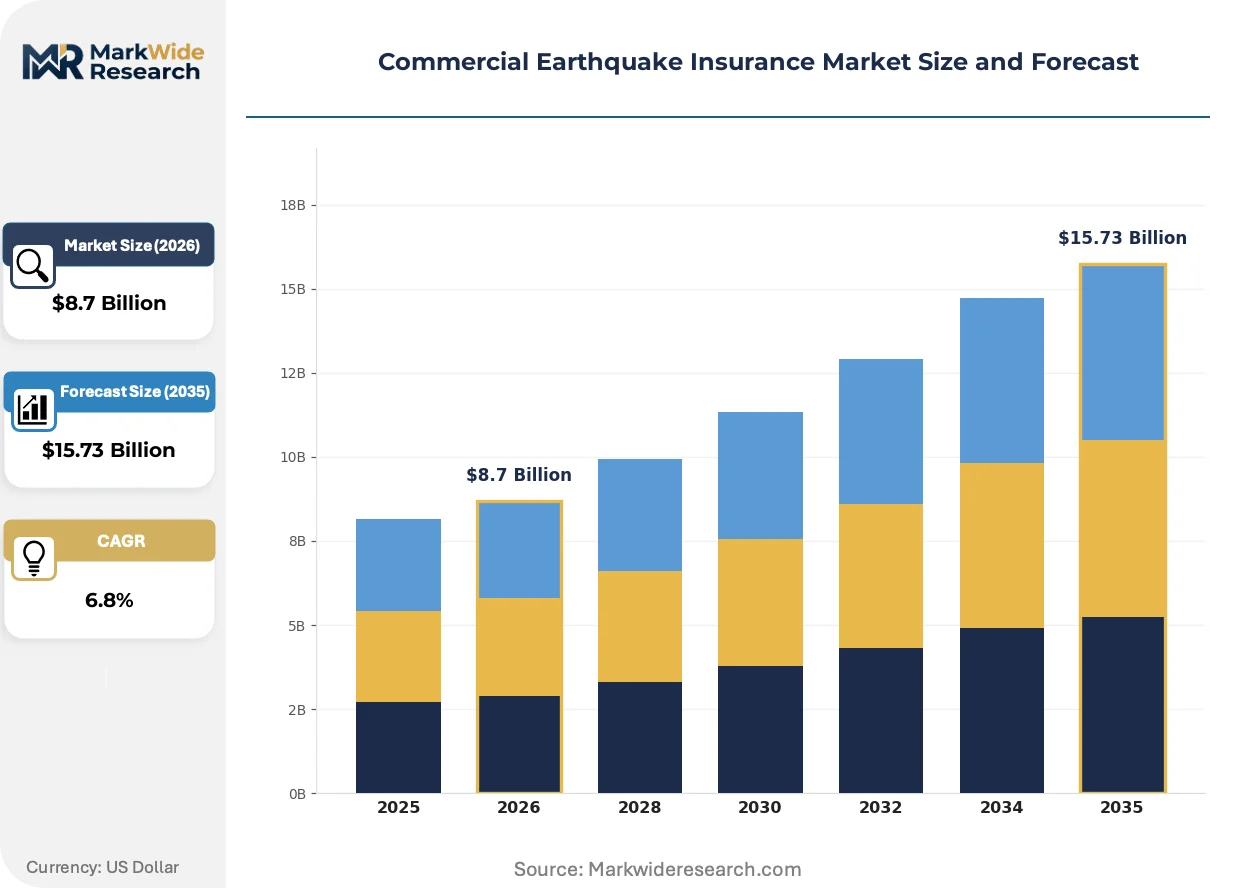
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Policy Type: Standard Coverage, Replacement Cost, Actual Cash Value, Additional Living Expenses Customer Type: Small Businesses, Corporations, Nonprofits, Government Entities Premium Structure: Flat Rate, Variable Rate, Deductible-Based, Pay-As-You-Go Endorsement Option: Business Interruption, Equipment Breakdown, Flood Coverage, Others |
| Companies Covered | GeoVera Holdings Inc, Steadfast Insurance Company, FM Global Group, Everest Indemnity Insurance Company, Princeton Excess & Surplus Lines Insurance Company, Palomar Holdings Group, Arrowhead General Insurance Agency, Chubb Limited, Zurich Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Commercial Earthquake Insurance Market Emerging Trajectories
Algorithmic underwriting engines and satellite-based loss verification are compressing the traditional claims cycle from months to hours, restructuring carrier-insured relationships around liquidity speed rather than dispute resolution.
Blockchain-enabled smart contracts are digitizing parametric earthquake policies by automating payout execution when ground-motion sensors trigger predetermined acceleration thresholds. Small commercial insureds in California and Japan are adopting these instruments fastest, bypassing traditional adjustor review entirely. This architecture is digitizing the back-office function that historically consumed 12-18% of premium dollars in loss adjustment expenses.
California's Division of Financial Services has mandated granular exposure disclosure for insurers holding more than $500 million in seismic risk, forcing carriers to publish fault-line concentration metrics previously treated as proprietary. The regulation is compressing capacity deployment timelines as reinsurers demand real-time portfolio rebalancing. European carriers with US West Coast facultative arrangements are restructuring their retrocession programs to meet these transparency requirements.
Buyers are unbundling engineering services from policy placement, contracting directly with FM Global and similar specialists for retrofit certification before soliciting standalone coverage quotes. This behavior is fragmenting the traditional agent-broker value chain in Los Angeles, San Francisco, and Seattle metropolitan corridors. Manufacturing and data center operators are driving this shift, seeking premium credits that exceed standard market offerings through verified resilience investments.
Commercial Earthquake Insurance Market Segmentation
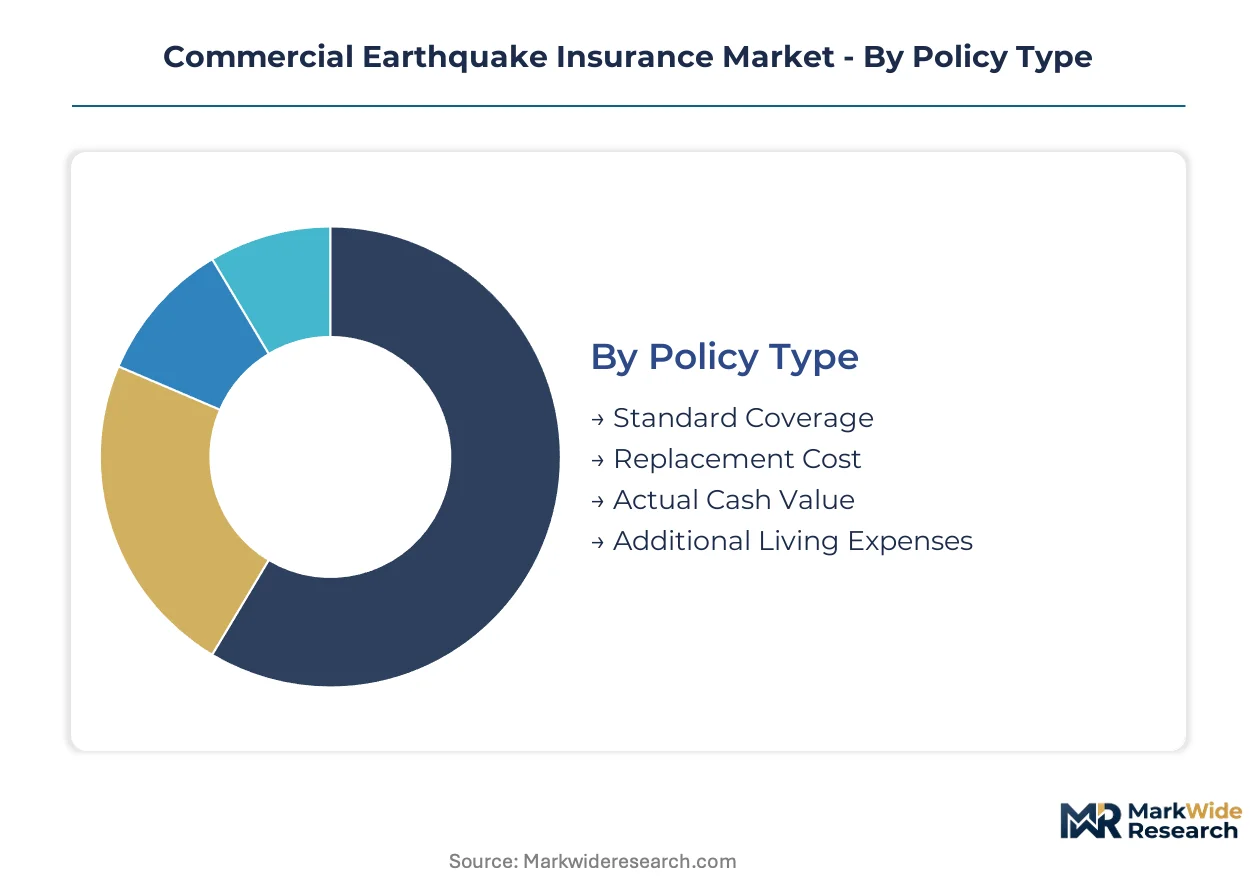
Commercial earthquake insurance segments reflect divergent risk appetites across policy structures and buyer sophistication levels. Carriers calibrate capital allocation by matching deductible mechanics to balance sheet resilience profiles of distinct customer cohorts.
Policy Type:
Property owners select coverage forms based on reconstruction cost exposure and financing covenant requirements.
- Standard Coverage:Named-peril policies covering structural damage from seismic ground shaking with sublimits for masonry veneer and foundation systems. Demand concentrates among small retail operators in California's Central Valley where lender mandates drive purchase decisions.
- Replacement Cost:Policies indemnifying full reconstruction expense without depreciation deduction, commanding premium multiples over actual cash value alternatives. Data center operators in the San Francisco Bay Area favor this form as occupancy permits require full restoration guarantees.
- Actual Cash Value:Depreciation-adjusted settlements reducing carrier exposure on aging commercial stock. Older manufacturing facilities in Los Angeles County select this tier to satisfy minimum coverage requirements at reduced premium outlay.
- Additional Living Expenses:Coverage extensions for temporary relocation costs during repair periods, typically bundled with residential-adjacent commercial policies. Hospitality operators near fault zones add this rider to maintain franchise obligations during reconstruction.
Established volume favors Replacement Cost; emerging adoption favors Additional Living Expenses.
Customer Type:
Purchasing sophistication varies sharply across entity scale and regulatory oversight intensity.
- Small Businesses:Retail and service enterprises with simplified underwriting through embedded agent platforms and parametric quoting engines. California's state retrofit mandates are accelerating penetration among independent contractors in seismically active counties.
- Corporations:Multi-location enterprises with customized layered programs combining primary coverage with captive reinsurance structures. Fortune 500 manufacturers in the Pacific Northwest negotiate engineering-verified premium credits through FM Global certification protocols.
- Nonprofits:Mission-driven organizations with constrained risk management budgets seeking deductible flexibility through community development financial institution partnerships. Religious institutions and charter schools in Utah's Wasatch Front represent concentrated demand.
- Government Entities:Municipal buildings and public infrastructure with coverage placement through state risk pools and federal disaster backstops. California county governments layer CEA participation with standalone commercial policies for facilities exceeding pool limits.
Corporate placements dominate premium volume; small business channels are climbing the fastest.
Premium Structure:
Pricing mechanics determine cash flow timing and risk transfer efficiency for policyholders with varying liquidity positions.
- Flat Rate:Fixed annual premiums without adjustment for claims experience or seismic activity indices. Stable-cost budgeting attracts nonprofit and government buyers with restricted fiscal flexibility.
- Variable Rate:Experience-rated pricing tied to retrofit investment verification and prior loss history. Corporate portfolios with engineering-led risk selection capture rate reductions through ISO 19901-2 compliance documentation.
- Deductible-Based:Premium scaling inversely with attachment points, typically 10-20% of insured value. Small businesses in high-risk zones accept elevated deductibles to meet mandatory coverage thresholds at affordable premium levels.
- Pay-As-You-Go:Usage-adjusted structures aligning premium recognition with revenue fluctuations, emerging among seasonal hospitality operators in California wine country.
Flat Rate structures anchor current placement volume; Variable Rate designs are gaining share fastest.
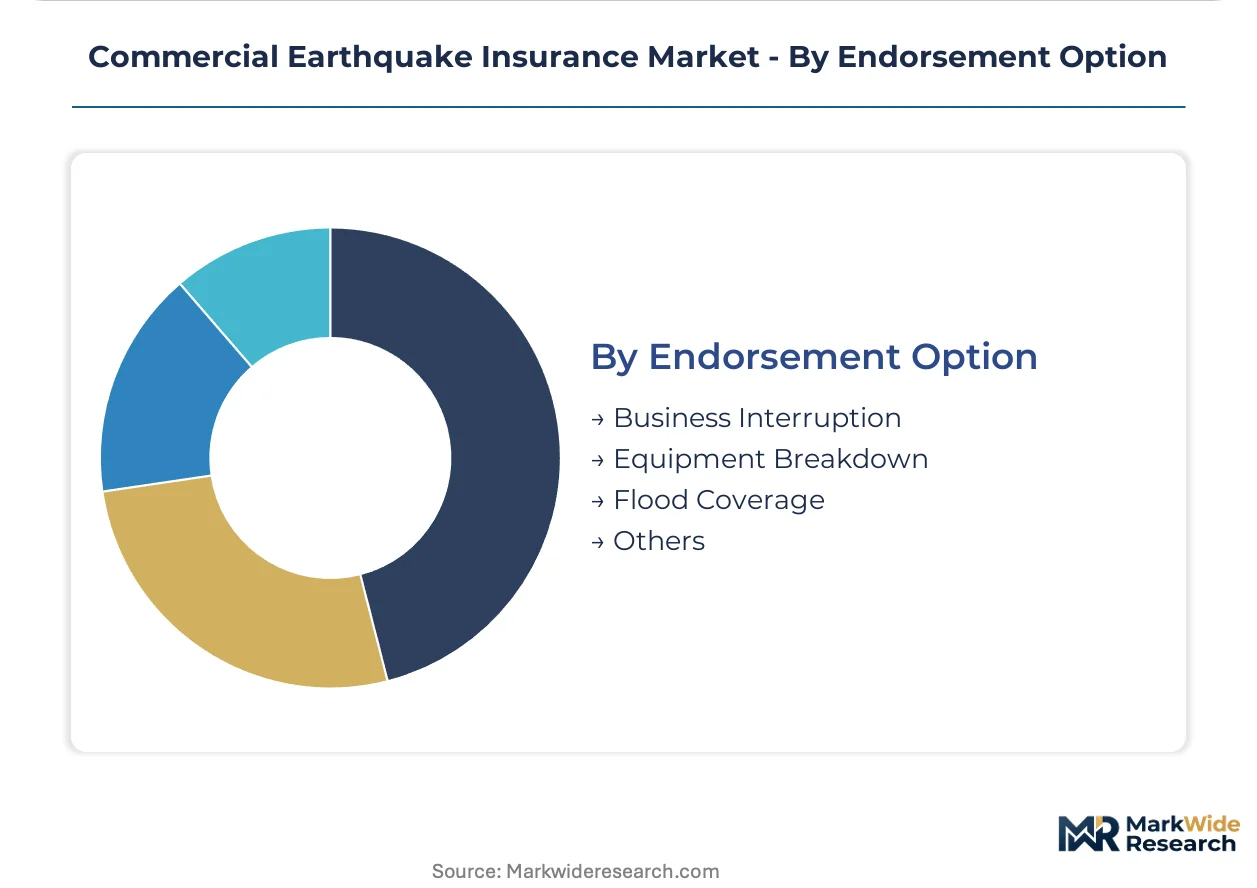
Endorsement Option:
Risk transfer extensions address contingent exposures excluded from base property forms.
- Business Interruption:Indemnity for lost income and continuing expenses during repair periods, with indemnity windows spanning 12-24 months. Manufacturing and logistics verticals in Seattle-Tacoma corridor add this coverage to protect just-in-time contract obligations.
- Equipment Breakdown:Protection for mechanical and electrical system damage from seismic acceleration, critical for data center and healthcare facility operators with sensitive infrastructure dependencies.
- Flood Coverage:Tsunami and seismic-induced flood protection, essential for coastal California and Pacific Northwest port facilities where standard flood policies exclude earthquake-triggered inundation.
- Others:Contingent business income, debris removal, and ordinance or law coverage addressing post-event regulatory compliance costs.
Business Interruption dominates endorsement attachment; Equipment Breakdown shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial earthquake insurance consumption patterns diverge sharply across geographies. California concentrates layered risk-pooling through state-mandated mechanisms, while Japan relies on government-backed reinsurance schemes. New Zealand and Turkey operate national disaster funds with distinct coverage triggers. Switzerland and Italy face Alpine seismic exposure with fragmented private market development.
United States
California's Earthquake Authority dominates placement volume through mandatory participation thresholds for residential-adjacent commercial risks. The state's Division of Financial Services enforces granular exposure disclosure for carriers holding substantial seismic portfolios. Los Angeles and San Francisco metropolitan corridors concentrate demand from data center operators seeking replacement cost guarantees.
Japan
Tokyo and Osaka commercial districts layer private coverage atop Japan's Earthquake Reinsurance scheme, which caps indemnity through government backstops. METI coordinates capacity allocation between domestic carriers and international facultative markets. Manufacturing clusters in Chubu and Kyushu regions drive contingent business income endorsement attachment.
New Zealand
The Earthquake Commission provides foundational coverage with private markets topping up limits for commercial assets in Wellington and Canterbury. The country's national disaster fund structure limits carrier exposure on residential-equivalent commercial properties. Christchurch reconstruction experience has hardened building code enforcement across South Island industrial zones.
Turkey
Istanbul's dense commercial stock relies on the Turkish Catastrophe Insurance Pool for mandatory basic coverage, with excess limits placed through London and European reinsurance markets. The country's central bank supervises pool solvency requirements. Industrial facilities in Izmir and Bursa seek engineering-verified premium credits through ISO-compliant retrofit programs.
Italy
Northern manufacturing centers in Emilia-Romagna and Veneto operate without pooled backstops, creating capacity constraints for seismic-exposed industrial risks. The country's civil protection agency coordinates post-event liquidity but provides no indemnity guarantee. Milan-based corporate buyers negotiate layered programs through Lloyd's syndicates and Swiss reinsurance channels.
Commercial Earthquake Insurance Market Vendor Landscape
Capability concentration sits with engineering-led risk selectors; scale advantage sits with diversified global carriers with facultative reinsurance access. The market structures around three tiers: catastrophe modelers with proprietary seismic pricing engines, mutual-style risk pools with government sponsorship, and generalist carriers with retrocession-dependent capacity. Strategic moves center on parametric trigger platform integration and engineering service unbundling from policy placement.
Within the engineering-verified tier, FM Global Group anchors risk selection protocols that tie premium credits to structural retrofit certification. GeoVera Holdings Inc and Zurich Insurance Group occupy distinct positions along the specialty-generalist spectrum, with the former concentrating proprietary catastrophe modeling capabilities and the latter leveraging Swiss Re-backed facultative arrangements for European commercial portfolio exposure.
| Leading Market Players |
|---|
| GeoVera Holdings Inc |
| Steadfast Insurance Company |
| FM Global Group |
| Everest Indemnity Insurance Company |
| Princeton Excess & Surplus Lines Insurance Company |
| Palomar Holdings Group |
| Arrowhead General Insurance Agency |
| Chubb Limited |
| Zurich Insurance Group |
| Others |
Supply Flow & Price Mechanics
Reinsurer undercapacity in California's San Andreas corridor is compressing primary carrier pricing power and forcing selective risk retention strategies among commercial insureds with concentrated seismic exposure.
Pricing Analysis
Long-term facultative arrangements dominate commercial earthquake placement, with Zurich Insurance Group and European carriers anchoring capacity through Swiss Re-backed treaties that stabilize rate levels across multi-year horizons. Price differentiation rests on ISO 19901-2 certification tier and verified retrofit investment scale, with FM Global engineering credits commanding premium advantages over standard market offerings. Cost compression in small business channels is intensifying because embedded agent platforms automate quoting and compress distribution margins. Nonprofit and government buyers exhibit highest price sensitivity due to restricted fiscal flexibility, while data center operators demonstrate lowest sensitivity given lender-mandated replacement cost requirements.
Supply Chain Analysis
Export-control regimes on seismic sensor technology and satellite-based damage assessment tools are limiting parametric platform deployment across certain jurisdictions, constraining innovation velocity in claims automation. Catastrophe modeling capacity concentrates in the United States, United Kingdom, and Japan, with proprietary risk engines drawing from geological survey data, building inventory databases, and ground-motion sensor networks. Supply chain risk centers on single-source vulnerability for synthetic aperture radar verification services. Distribution runs through embedded agent platforms, wholesale surplus lines channels, and direct captive arrangements for Fortune 500 portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parametric trigger adoption represents a high-growth disruption, with blockchain-enabled smart contracts compressing claims cycles from months to hours and redistributing value from carriers to algorithmic aggregators.
For Market Incumbents: Entrench engineering-led risk selection capabilities through exclusive retrofit certification partnerships that lock out competing premium credit programs. Deepen vertical integration into catastrophe modeling talent pools to defend against actuarial team poaching by insurtech entrants. The priority defensive lever centers on proprietary seismic risk coding capabilities that command premium compensation and compress competitor expense ratios.
For New Entrants and Emerging Players: Build out parametric satellite verification platforms targeting small business channels in California's Central Valley, where state retrofit mandates accelerate coverage penetration but incumbent automation lags. The most penetrable segment combines API-connected quoting engines with embedded agent distribution relationships. The specific go-to-market angle leverages synthetic aperture radar damage assessment for instant claims settlement without adjuster deployment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across parametric trigger platform development, as satellite infrastructure and ground-motion sensor networks require sustained deployment investment. Long-term viability over the next decade favors acquirers of engineering-verified risk selection protocols and proprietary catastrophe modeling capabilities. The acquisition target archetype combines ISO 19901-2 certification authority with established carrier distribution relationships. The specific signal to watch is California Division of Financial Services exposure disclosure compliance timelines, which compress capacity deployment and force real-time portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Parametric Platform Integration | Blockchain-enabled smart contracts automate payout execution when ground-motion sensors trigger predetermined acceleration thresholds. |
| Engineering Service Unbundling | FM Global certification protocols fragment traditional agent-broker value chains in Los Angeles and San Francisco corridors. |
| Retrofit Verification Standardization | County-level building inspector certification harmonization reduces underwriting uncertainty and compresses risk-adjusted pricing. |
| Facultative Capacity Expansion | Swiss Re-backed arrangements anchor European commercial portfolios against peak seismic exposure in US West Coast markets. |
| Contingent Business Income Extension | Supply chain interruption riders penetrate manufacturing verticals previously reliant on narrow property-only coverage forms. |
Methodological Framework
Cross-validation between primary interviews with underwriting executives, catastrophe modeling specialists, and commercial risk managers anchors the qualitative findings against secondary validation from California Earthquake Authority filings, Japan METI capacity reports, and ISO seismic design provision documentation. The analysis draws from reinsurance broker placement data, state insurance department exposure disclosures, and engineering certification body records. Bottom-up segmentation modeling triangulates against top-down market sizing from pooled risk mechanism participation thresholds.
Calibration against historical loss development patterns and retrofitted building performance data informs the projection framework across the analysis window. Segmentation dimensions include policy structure, customer sophistication tier, premium mechanics, and endorsement attachment patterns, with additional modeling of parametric adoption velocity by geography. CAGRs derive from trend extrapolation of state mandate penetration curves and small business automation adoption rates. Industry-specific forecast inputs incorporate ISO 19901-2 compliance trajectory and satellite-based damage assessment deployment timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by insurtech parametric platforms or regulatory acceleration of exposure disclosure requirements would shift outcomes. Material shifts in California retrofit mandate enforcement intensity or Japan Earthquake Reinsurance scheme capacity allocation would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Embedded Insurance Market
Insurance
Compulsory Third Party (CTP) Insurance Market
Insurance
India Electronic Gadget Insurance Market
Insurance
US Travel Insurance Market
Insurance
Data Analytics in Insurance Market
Insurance
US Electronic Gadgets Insurance Market
Insurance
Term Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
India Life and Non-Life Insurance Market
Insurance
Middle East and Africa Travel Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
Asia-Pacific Travel Insurance Market
Insurance
North America Family Floater Health Insurance Market
Insurance
Vietnam Private Health Insurance Market