
 Crime Insurance Market | 2026-2036
Crime Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Crime Insurance Market Analysis
Financial institutions is consolidating as the dominant end-user vertical for crime insurance, displacing traditional retail-heavy purchasing patterns. AIG leverages its multinational underwriting platform to serve complex institutional accounts across multiple jurisdictions. Chubb anchors its competitive stance through specialized crime products targeting high-net-worth commercial clients. Beazley differentiates via technology-forward underwriting tools that streamline policy customization for mid-market enterprises.
Crime insurance is a specialized commercial line indemnifying organizations against direct financial losses from employee dishonesty, computer fraud, forgery, and theft of money or securities, with policies typically specifying per-occurrence limits and aggregate caps calibrated to exposure profiles. The product generates structured protection against asset misappropriation and electronic crime vectors. Cyber Crime coverage within the product type dimension commands accelerating premium flow as ransomware and social engineering losses mount. Employee Theft remains the mature baseline segment with stable renewal rates but compressed margins. Brokers dominate the distribution channel dimension, though online platforms are capturing share among standardized small-commercial placements.
US regulators including the SEC and state insurance commissioners enforce disclosure requirements and capital adequacy standards that shape carrier product design and pricing freedom. The EU's DORA framework and national financial conduct authorities in Germany, France, and Italy impose operational resilience mandates that directly expand mandatory crime coverage scopes for regulated entities. Stakeholders must monitor how converging cyber and traditional crime definitions in policy language affect claims adjudication and coverage gaps.
Market Dynamics
The convergence of cyber and traditional crime definitions is rewriting policy architecture across financial institutions, forcing carriers to recalibrate coverage scopes as DORA mandates tighten operational resilience requirements in Europe and US regulators expand disclosure obligations.
Growth Catalysts
- DORA Compliance Mandates:The EU's Digital Operational Resilience Act compels financial entities across Germany, France, and Italy to expand mandatory crime coverage, directly lifting premium volumes for regulated institutions.
- Social Engineering Loss Severity:Sophisticated phishing and business email compromise schemes targeting mid-market enterprises are accelerating demand for specialized fraud indemnification products.
- Digital Transaction Proliferation:Real-time payment rails and embedded finance platforms in the United States are exposing institutions to novel theft vectors that legacy policies exclude.
Market Restraints
- Reinsurance Capacity Squeeze:Catastrophic cyber crime aggregations have tightened retrocession markets, forcing primary carriers to retain more risk or narrow coverage terms.
- Claims Adjudication Uncertainty:Ambiguous policy language at the intersection of cyber and crime coverages creates coverage gap disputes that delay settlement and inflate legal defense costs.
- Actuarial Data Scarcity:Limited historical loss experience for emerging fraud vectors prevents accurate pricing, compressing margins on innovative product extensions.
Strategic Opportunities
- Small-Commercial Digital Distribution:Online platforms and embedded insurance APIs are capturing standardized crime placements currently underserved by traditional broker channels.
- Technology-Enabled Underwriting:Behavioral analytics and transaction monitoring integrations allow carriers to offer dynamic pricing tied to real-time risk controls.
- Asia-Pacific Regulatory Expansion:Japan's METI and Australia's prudential regulator are developing operational resilience frameworks that will mandate crime coverage for financial institutions.
Industry Challenges
- Specialized Claims Talent Shortage:Underwriters and adjusters with expertise in both financial crime investigation and insurance contract interpretation command premium compensation that erodes unit economics.
- Legacy System Integration Friction:Carriers attempting to deploy automated underwriting tools face data silos and incompatible policy administration platforms that delay product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crime Insurance Market |
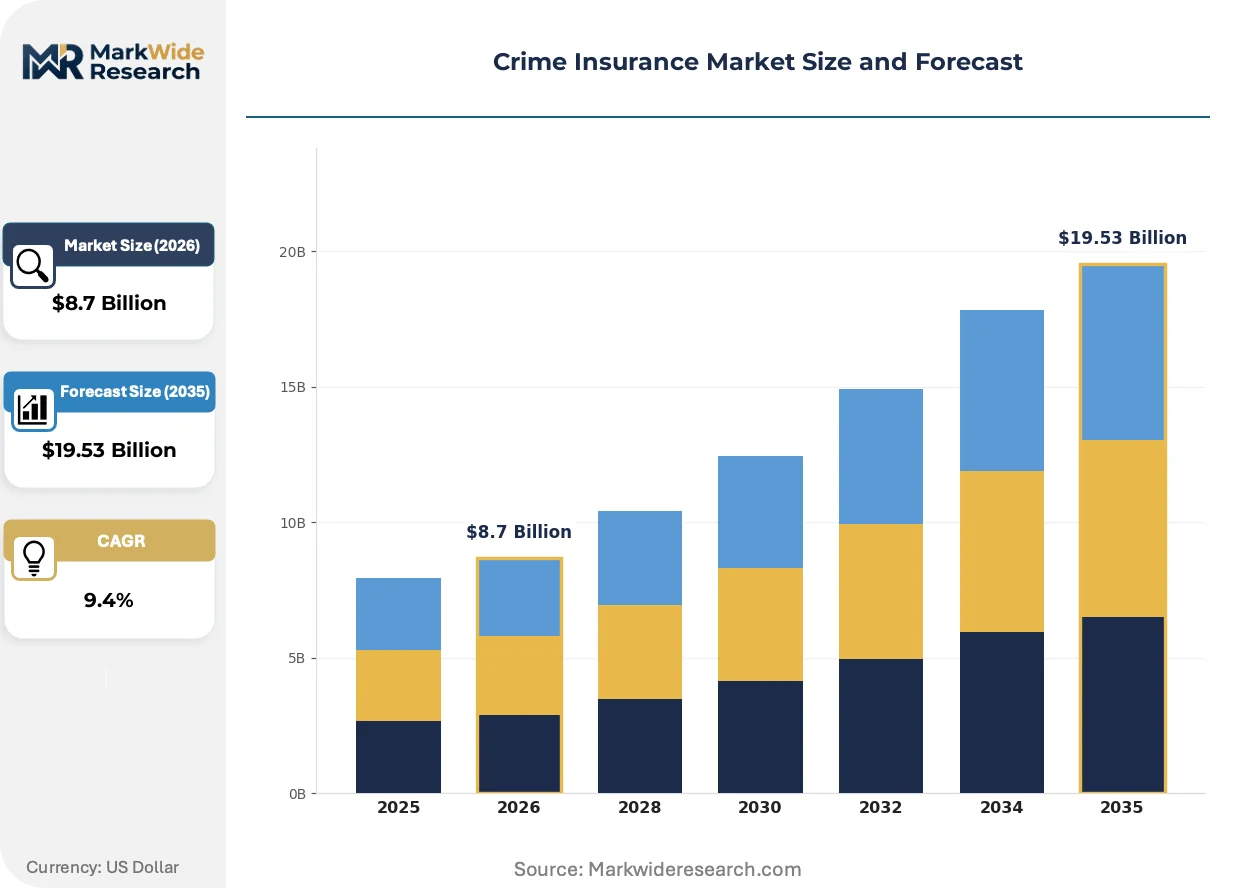
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Employee Theft, Cyber Crime, Forgery, Fraud Coverage Type: On-Premises, Off-Premises, Theft from Safe, Computer Fraud End User: Retailers, Financial Institutions, Non-Profits, Manufacturers Distribution Channel: Brokers, Direct Sales, Online Platforms, Agents |
| Companies Covered | AIG, Beazley, Chubb, Great American Insurance Group, AXIS Capital, Travelers, Tokio Marine, CNA Financial, Zurich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crime Insurance Market Emerging Trajectories
Artificial intelligence and machine learning are penetrating fraud detection and underwriting workflows, compressing decision cycles while regulators race to impose algorithmic accountability standards on automated insurance decisions.
Behavioral biometrics and continuous authentication technologies are rewriting how carriers verify identity and detect anomalous transactions. Mid-market enterprises with distributed workforces are adopting these tools fastest, enabling insurers to offer premium credits tied to demonstrated control effectiveness. The structural consequence is a shift from retrospective indemnification toward preventive risk engineering partnerships.
The EU's Digital Operational Resilience Act and national implementations by BaFin in Germany and ACPR in France are mandating scenario-based resilience testing for financial entities. These requirements force institutions to quantify crime exposure more precisely, expanding demand for tailored coverage that explicitly addresses tested loss scenarios. German banking groups are responding by consolidating crime and cyber policies under unified operational risk frameworks.
Enterprise risk managers are unbundling crime coverage from packaged commercial policies and negotiating standalone placements with specialized terms. This procurement evolution disrupts traditional multi-line broker relationships, favoring carriers with dedicated crime underwriting benches. The shift is most visible among US financial institutions with sophisticated captive insurance structures and direct access to wholesale markets.
Crime Insurance Market Segmentation
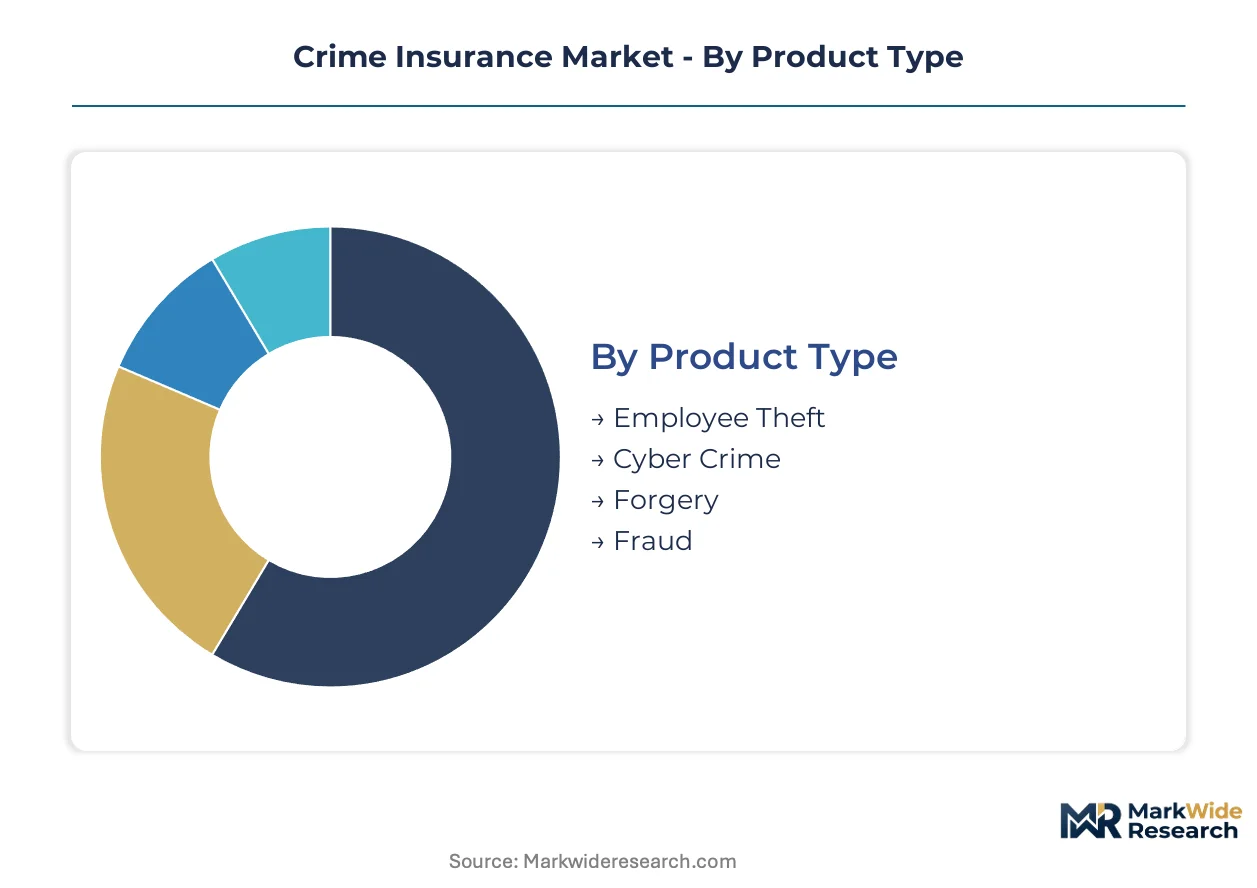
Crime insurance buyers prioritize coverage scope alignment with specific loss vectors rather than price alone. Segmentation reveals how carriers calibrate product architecture to match organizational exposure profiles and procurement sophistication.
Product Type:
Premium allocation decisions hinge on which loss categories dominate an organization's risk register.
- Cyber Crime:Policies indemnify direct financial losses from ransomware, social engineering, and unauthorized electronic funds transfers. Financial institutions in Germany and France are expanding limits here as DORA mandates tighten operational resilience testing requirements.
- Employee Theft:The foundational coverage segment addresses asset misappropriation by insiders through falsified records or physical theft. Retailers with high cash transaction volumes maintain this as their primary coverage layer despite compressed carrier margins on renewals.
- Forgery:Protects against losses from fraudulent alteration of negotiable instruments and authorized signatures. Commercial clients with high check-writing volumes or wire transfer authority concentrate demand in this segment.
- Fraud:Covers deceptive schemes by third parties including vendor kickbacks and false invoicing. Mid-market manufacturers with distributed procurement functions are driving placement growth as supply chain complexity expands.
Cyber Crime leads on scale; Fraud leads on momentum.
Coverage Type:
Geographic dispersion of assets and operations determines which physical and digital loss scenarios require explicit policy language.
- Computer Fraud:Addresses electronic theft through system intrusion, malware deployment, or credential compromise. US financial institutions with real-time payment rail exposure are prioritizing this coverage as legacy crime forms exclude digital vectors.
- On-Premises:Covers theft occurring within owned or leased facilities including cash, securities, and tangible assets. High-net-worth commercial clients with significant physical asset concentrations anchor demand in this mature segment.
- Off-Premises:Protects assets in transit or held by third parties including armored car services and remote employees. Organizations with distributed workforces are expanding sublimits here as remote operations normalize.
- Theft from Safe:Specific coverage for forcible or surreptitious removal from secured storage containers. Jewelry retailers and precious metals dealers maintain this as a standalone coverage component due to concentrated high-value inventory.
Computer Fraud is expanding most quickly; On-Premises retains the largest premium base.
End User:
Industry-specific regulatory pressure and transaction characteristics shape coverage procurement patterns.
- Financial Institutions:Banks, credit unions, and payment processors face the most stringent crime coverage mandates. EU member states implementing DORA are forcing these entities to quantify exposure through scenario testing, expanding demand for tailored policy terms.
- Retailers:Physical and e-commerce operations with high transaction velocity require protection against point-of-sale fraud and cash handling losses. US-based retail chains with captive insurance structures are unbundling crime from packaged policies.
- Non-Profits:Organizations with volunteer-managed finances and limited internal controls present distinct fraud exposure profiles. Donor scrutiny over stewardship practices is driving standalone crime placements among mid-sized charitable entities.
- Manufacturers:Supply chain complexity and vendor payment authority create specialized fraud vulnerabilities. German industrial groups are consolidating crime coverage under unified operational risk frameworks alongside cyber policies.
Financial Institutions command the steepest expansion trajectory; Retailers represent the most price-sensitive volume segment.
Distribution Channel:
Procurement sophistication and policy complexity determine whether buyers engage intermediaries or transact directly.
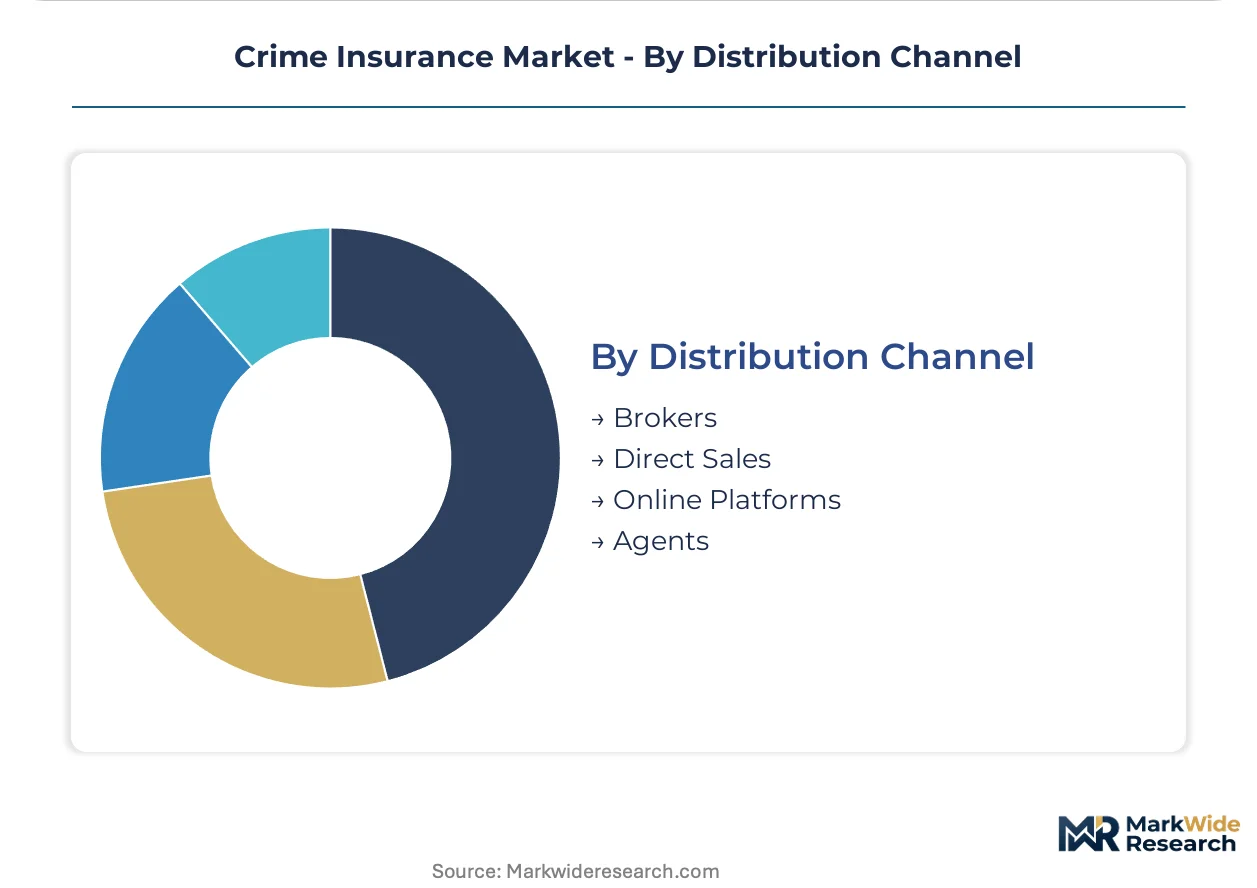
- Brokers:Dominant channel for complex institutional placements requiring coverage customization and claims advocacy. Large US financial institutions with sophisticated risk management functions rely on wholesale broker access to specialty markets.
- Online Platforms:Capturing standardized small-commercial placements through API-enabled quoting and instant policy issuance. Mid-market enterprises with straightforward exposure profiles are migrating here for transactional efficiency.
- Direct Sales:Carrier-employed producers serving high-value commercial accounts with dedicated underwriting relationships. Chubb and AIG leverage direct channels for multinational clients requiring coordinated multi-jurisdictional coverage.
- Agents:Local producers serving smaller commercial accounts within defined territories. Independent agents retain relevance where relationship-based servicing outweighs digital convenience for policy maintenance.
Brokers lead on premium volume; Online Platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Financial institutions in the United States anchor premium concentration as enterprise risk budgets expand and cyber crime severity escalates. Digital transaction volumes are rising across all major economies, tightening compliance requirements and reshaping carrier product design.
United States
Enterprise risk managers at US financial institutions are unbundling crime coverage from packaged commercial policies and negotiating standalone placements with specialized terms. The SEC enforces disclosure requirements that shape carrier product design and pricing freedom for regulated entities. New York-based banking groups with sophisticated captive insurance structures are driving demand for tailored crime and cyber unified frameworks.
Germany
BaFin's implementation of DORA mandates is compelling financial entities to expand mandatory crime coverage scopes and quantify exposure through scenario-based resilience testing. German banking groups are consolidating crime and cyber policies under unified operational risk frameworks. Frankfurt's financial services cluster is witnessing accelerated broker activity as institutions seek coordinated multi-jurisdictional coverage.
France
The ACPR's operational resilience mandates are forcing banks and payment processors to tighten crime coverage alignment with tested loss scenarios. Financial institutions across the Île-de-France region are prioritizing computer fraud coverage as real-time payment rail exposure expands. Paris-based carriers are recalibrating policy architecture to address converging cyber and traditional crime definitions.
United Kingdom
Wholesale broker channels serving London's specialty insurance market are capturing complex institutional placements requiring coverage customization and claims advocacy. The Financial Conduct Authority's operational resilience rules are expanding mandatory coverage scopes for regulated financial entities. Lloyd's syndicates are developing technology-forward underwriting tools to streamline policy customization for mid-market enterprises.
Japan
METI's developing operational resilience framework will mandate crime coverage for financial institutions as regulatory expansion accelerates across Asia-Pacific. Japanese banks with distributed workforces are expanding off-premises coverage sublimits as remote operations normalize. Tokyo's insurance market is witnessing carrier investment in behavioral analytics and transaction monitoring integrations for dynamic pricing models.
Crime Insurance Market Vendor Landscape
Portfolio diversification dominates the current landscape as carriers recalibrate coverage scopes to address converging cyber and traditional crime definitions. The market exhibits a tiered structure with multinational underwriters, specialty crime carriers, and technology-enabled challengers competing across distinct client segments. Three strategic archetypes have emerged: complex institutional servicers, high-net-worth commercial specialists, and mid-market digital distributors. M&A activity and technology licensing partnerships represent the dominant competitive moves as carriers seek automated underwriting capabilities and geographic footprint expansion.
Within the complex institutional servicer tier, AIG leverages its multinational underwriting platform to anchor positioning across multiple jurisdictions. Chubb occupies a position among high-net-worth commercial specialists through dedicated crime underwriting benches and direct sales relationships. Beazley exemplifies the technology-enabled challenger archetype with streamlined policy customization tools targeting mid-market enterprises.
| Leading Market Players |
|---|
| AIG |
| Beazley |
| Chubb |
| Great American Insurance Group |
| AXIS Capital |
| Travelers |
| Tokio Marine |
| CNA Financial |
| Zurich |
| Others |
Supply Flow & Price Mechanics
Reinsurance capacity costs cascade from London and Bermuda retrocession markets through primary carrier pricing tiers, compressing margins on cyber crime extensions while broker commissions absorb residual pressure in complex institutional placements.
Pricing Analysis
Broker commission layers dominate pricing architecture, with wholesale intermediaries capturing differential spreads on multinational financial institution accounts versus direct digital platforms serving standardized small-commercial placements. Premium differentiation hinges on policy customization depth and claims advocacy intensity, with DORA-mandated scenario testing requirements in Germany and France lifting pricing floors for regulated entities. Cost compression in mid-market cyber crime extensions intensifies because actuarial data scarcity prevents accurate risk calibration. Retailers with high cash transaction volumes exhibit greatest price sensitivity, while US financial institutions with captive structures demonstrate lowest sensitivity due to risk retention flexibility.
Supply Chain Analysis
Logistics and distribution costs for policy documentation and claims settlement services concentrate friction in cross-border placements spanning the United States, United Kingdom, and Germany. Underwriting capacity draws from London wholesale markets, Bermuda reinsurance pools, and domestic primary carriers in each major jurisdiction. Raw material dependencies include specialized claims investigation talent, behavioral analytics software licenses, and regulatory compliance infrastructure. Single-source vulnerability sits with concentrated reinsurance capacity for catastrophic cyber crime aggregations. Distribution runs through broker networks for complex accounts, direct sales for multinational clients, and API-enabled platforms for standardized placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market compounds as a regulatory growth engine, with the EU's Digital Operational Resilience Act mandating scenario-tested crime coverage expansion across financial institutions in Germany, France, and Italy.
For Market Incumbents: Deploy technology-enabled underwriting infrastructure to compress decision cycles and capture mid-market share migrating from traditional broker channels. Integrate behavioral analytics and continuous authentication tools into policy pricing mechanisms. Defensive consolidation moves should prioritize acquiring automated underwriting capabilities and expanding multi-jurisdictional licensing footprints to serve DORA-compliant institutions. For New Entrants and Emerging Players: Begin with digital distribution platforms targeting standardized small-commercial crime placements currently underserved by legacy broker relationships. The most penetrable white-space sits in US mid-market enterprises with distributed workforces seeking off-premises coverage sublimits. A focused go-to-market angle leverages API-enabled quoting against traditional channel inefficiency. For Investors and Strategic Acquirers: Consolidation pressure builds where specialized claims talent scarcity meets technology-enabled underwriting capability gaps. Long-term viability favors carriers with demonstrated DORA compliance expertise and integrated cyber-crime policy architecture. The acquisition target archetype is mid-tier specialty carriers with established European financial institution relationships. The signal to watch is regulatory harmonization momentum across Asia-Pacific jurisdictions.| Strategic Initiative | Industry Significance |
|---|---|
| Technology-Enabled Underwriting Deployment | Behavioral analytics integration allows AIG and Beazley to offer dynamic pricing tied to real-time risk controls. |
| Multi-Jurisdictional Licensing Expansion | Chubb leverages direct sales relationships to coordinate coverage across DORA-implementing EU member states. |
| Specialized Claims Talent Acquisition | Underwriting benches with financial crime investigation expertise command premium compensation that erodes unit economics. |
| Digital Platform Integration | API-enabled quoting captures standardized small-commercial placements migrating from traditional broker channels. |
| Regulatory Compliance Infrastructure Investment | BaFin and ACPR scenario testing mandates force institutions to quantify exposure through tailored policy terms. |
Methodological Framework
Multiple input streams — primary interviews with underwriting executives, broker placement specialists, and enterprise risk managers; secondary validation through regulatory filings and trade association data — were reconciled through bottom-up and top-down triangulation. Primary fieldwork engaged carrier product development leads, wholesale broker managing directors, financial institution risk officers, and claims investigation specialists. Secondary sources encompassed SEC disclosure filings, EU regulatory implementation notices from BaFin and ACPR, and Lloyd's market performance data.
Historical premium trajectory cross-references against panel input from underwriting practitioners calibrated the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, coverage type, end-user vertical, and distribution channel complexity. CAGRs were derived from premium volume build-ups by segment, with industry-specific inputs capturing DORA implementation timelines and cyber crime severity trends.
Several conditions sit outside the modeled scope, including catastrophic aggregation events exceeding reinsurance capacity, fundamental cyber-crime definition shifts in policy language, and abrupt regulatory harmonization across Asia-Pacific jurisdictions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Jewelry Insurance Market
Insurance
Business Travel Accident Insurance Market
Insurance
Djibouti Insurance Market
Insurance
Global Livestock Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
United States Bancassurance Market
Insurance
UK Dental Insurance Market
Insurance
Medical Professional Liability Insurance Market
Insurance
Asia-Pacific AI in Insurance Market
Insurance
GCC Bancassurance Market
Insurance
UK Cyber (Liability) Insurance Market
Insurance
Extended Warranty Agreement Market
Insurance
Boiler Insurance Market
Insurance
United Kingdom Car Insurance Market
Insurance
France Property and Casualty Insurance Market
Insurance
Digital Monetary Insurance Market