
 Financial Protection Market | 2026-2036
Financial Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Protection Market Foresight
Cloud-native core systems are repositioning actuarial modeling and claims processing economics across the sector. Ping An Insurance leverages its in-house technology stack to control distribution costs across mainland China. Allianz SE anchors European commercial lines through specialized multinational employer coverage. Prudential Financial dominates group disability and voluntary benefits in the United States through captive broker networks.
Financial protection encompasses risk-transfer instruments that indemnify beneficiaries against mortality, morbidity, or income interruption events, typically structured with medically underwritten pricing, reserve-backed liabilities, and regulatory capital requirements. Life insurance commands the largest premium pool within product type segmentation, while critical illness coverage captures the fastest acceleration as medical cost inflation outpaces wage growth in major economies. Online platforms within channel segmentation are compressing acquisition expenses, though financial advisors retain margin concentration in high-net-worth customizable coverage.
China Banking and Insurance Regulatory Commission capital rules, Solvency II frameworks in Europe, and state-level insurance commissioner rate oversight in the United States collectively shape product design, reserving discipline, and market entry pathways. Stakeholders must monitor regulatory divergence between risk-based capital regimes and prescriptive product approval processes as they allocate technology investment across jurisdictions.
Market Dynamics
Cloud-native core systems are compressing actuarial modeling cycles and claims settlement timelines across the sector, forcing legacy insurers to re-platform or cede efficiency advantages to technology-forward competitors.
Growth Catalysts
- Embedded distribution mandates:China's Banking and Insurance Regulatory Commission requires life coverage bundling with retail banking products, expanding household penetration in tier-one cities.
- AI-driven underwriting automation:Machine learning risk scoring compresses policy issuance from weeks to hours, reducing acquisition costs for digitally native carriers.
- Employer-sponsored coverage expansion:Multinational corporations in Germany and the United States are widening group disability and voluntary benefits as workforce retention tools.
Market Restraints
- Reserve capital intensity:Solvency II frameworks in Europe and state-level reserving requirements in the United States lock substantial capital in low-yield instruments, compressing investment returns.
- Medical cost inflation divergence:Critical illness claims exposure rises faster than pricing adjustments in markets where healthcare provider consolidation outpaces regulatory rate review.
- Legacy system entrenchment:Mainframe-dependent incumbents face decade-long migration timelines to cloud infrastructure, delaying real-time data integration.
Strategic Opportunities
- Microinsurance penetration in India:Regulatory sandbox approvals from the Insurance Regulatory and Development Authority enable sachet-sized products for informal sector workers.
- Parametric coverage expansion:Satellite-triggered climate risk products bypass traditional loss adjustment for agricultural and property segments in catastrophe-prone regions.
- API-first distribution partnerships:Insurtech platforms embed coverage at point-of-sale across e-commerce and ride-hailing applications in Southeast Asian markets.
Industry Challenges
- Actuarial talent scarcity:Demand for data scientists with insurance domain expertise exceeds supply in London, Singapore, and New York hiring markets.
- Interoperability friction:Core system migrations stall where policy administration platforms lack standardized data exchange protocols with third-party claims networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Protection Market |
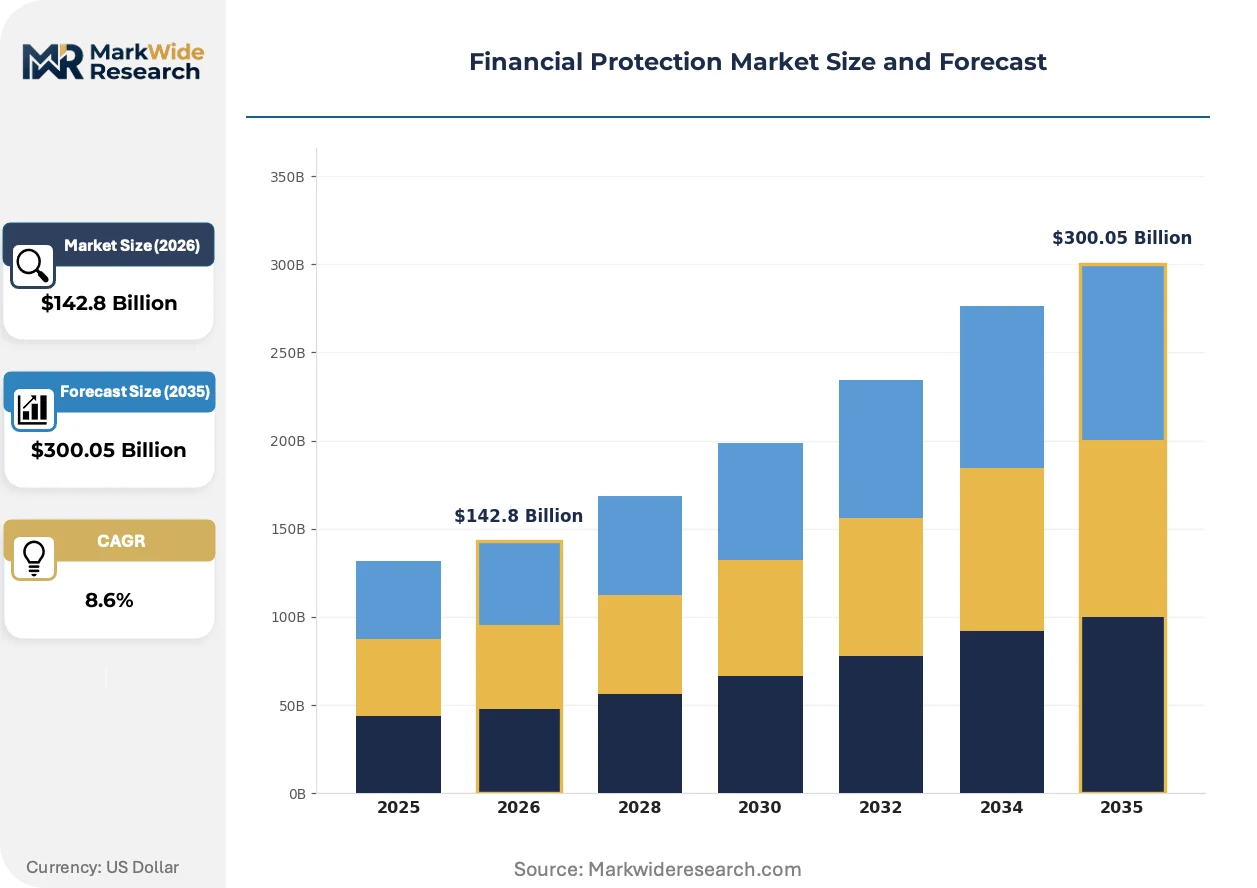
| Market Size in 2026 | $142.8 Billion |
| Market Size in 2035 | $300.05 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Life Insurance, Critical Illness Insurance, Disability Insurance, Accident Insurance Customer Type: Individuals, Families, Corporates, Institutions Channel: Direct Sales, Brokers, Online Platforms, Financial Advisors Coverage Type: Comprehensive, Basic, Customizable, Add-On |
| Companies Covered | Ping An Insurance (Group) Company of China Ltd., Cigna Corporation, Allianz SE, MetLife Inc., Dai-ichi Life Holdings Inc., China Pacific Insurance (Group) Co. Ltd., Nationwide Mutual Insurance Company, Prudential Financial Inc., American International Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Protection Market Shifts & Advancements
Real-time data streams from wearable devices and connected health platforms are redefining risk assessment granularity, shifting pricing from static demographic pools to dynamic behavioral monitoring.
Telematics-integrated life and health products are absorbing continuous biometric feeds from policyholder devices. Insurers in South Korea and the United Kingdom price coverage based on actual activity levels rather than age-banded tables. This data absorption is compressing adverse selection pools while raising privacy governance costs.
Solvency II's ORSA requirements and the EU's Digital Operational Resilience Act impose granular stress-testing and third-party risk management standards on European carriers. Asset-liability matching rules now incorporate climate transition scenarios. Commercial lines and annuity providers face the steepest compliance recalibration.
Direct-to-consumer platforms are disintermediating traditional agent networks for standardized term life and critical illness products. Younger demographics in Australia and Canada complete purchase journeys entirely through mobile-optimized interfaces. Financial advisors retain dominance only in high-complexity estate planning and business succession coverage.
Financial Protection Market Segmentation
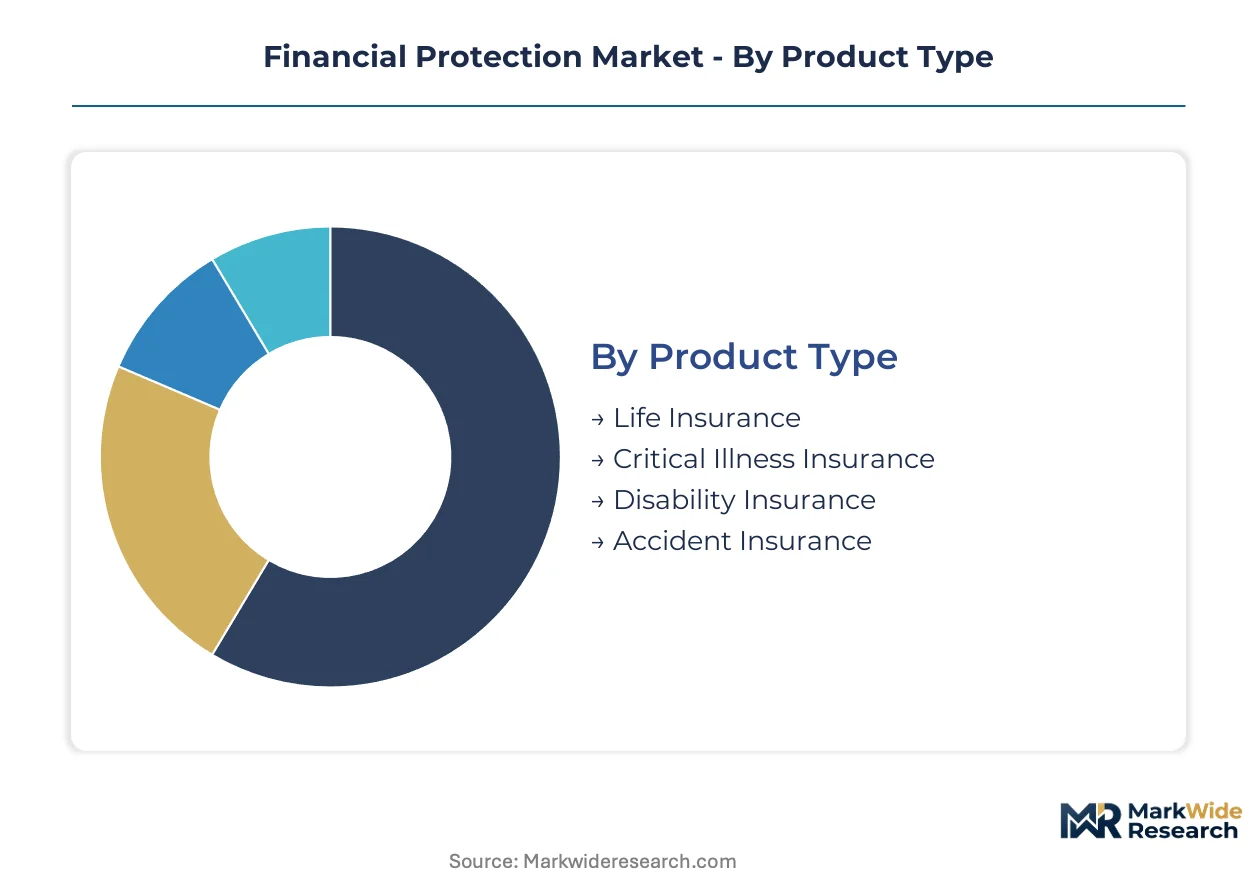
Product architecture in financial protection determines capital intensity, underwriting complexity, and distribution economics. Segment boundaries increasingly blur as embedded offerings and modular riders reshape traditional category definitions.
Product Type:
Standalone mortality products dominate premium pools while embedded health riders integrate into banking and employment relationships. Integration depth separates capital-intensive reserves from lightweight supplementary cover.
- Life Insurance:Long-duration contracts with reserve-backed liabilities and medically underwritten pricing. Demand concentrates among mass-affluent households in China's tier-one cities where state-backed carriers compete for middle-class penetration against mortality protection gaps.
- Critical Illness Insurance:Lump-sum triggers upon diagnosis of specified conditions with accelerated underwriting via AI risk scoring. Claims exposure in Germany and the United States rises faster than pricing adjustments as healthcare provider consolidation outpaces regulatory rate review.
- Disability Insurance:Income replacement products with occupation-class rating and elimination period structures.
- Accident Insurance:Simplified issue coverage with guaranteed acceptance and limited medical screening.
Life Insurance leads volumes today; Critical Illness Insurance is gaining share fastest.
Customer Type:
Purchasing authority and scale economics separate retail decision-makers from pooled risk arrangements. Cost tier differentiation shapes product design from standardized term sheets to negotiated master policies.
- Individuals:Single-life coverage with personalized underwriting and direct premium responsibility. Digital platforms in Australia and Canada compress acquisition costs through mobile-optimized purchase journeys for standardized term products.
- Families:Multi-life policies with spouse and dependent riders requiring household income verification.
- Corporates:Group master contracts with guaranteed issue provisions and experience-rated renewals. Multinational employers in Germany and the United States widen disability and voluntary benefits as workforce retention tools.
- Institutions:Pension funds and endowments securing annuity and longevity risk transfer through captive structures.
Corporates anchor premium volume; Individuals show steepest expansion trajectory as direct channels mature.
Channel:
Margin capture and advisory intensity vary sharply across human-mediated and algorithmic distribution. Application complexity determines where financial advisors retain dominance versus where automation displaces intermediation.
- Direct Sales:Carrier-employed agents with captive product authority and quota-driven compensation. Online platforms in Southeast Asian markets embed coverage at point-of-sale across e-commerce and ride-hailing applications.
- Brokers:Independent intermediaries with multi-carrier access and fiduciary duty variations by jurisdiction.
- Online Platforms:Algorithmic quoting with instant issue for standardized risk profiles and minimal medical evidence. Younger demographics complete entirely digital purchase journeys while acquisition expenses compress for digitally native carriers.
- Financial Advisors:Holistic planners with estate and business succession expertise commanding high-complexity customization.
Financial Advisors retain the highest margins per policy; Online Platforms are expanding most quickly.
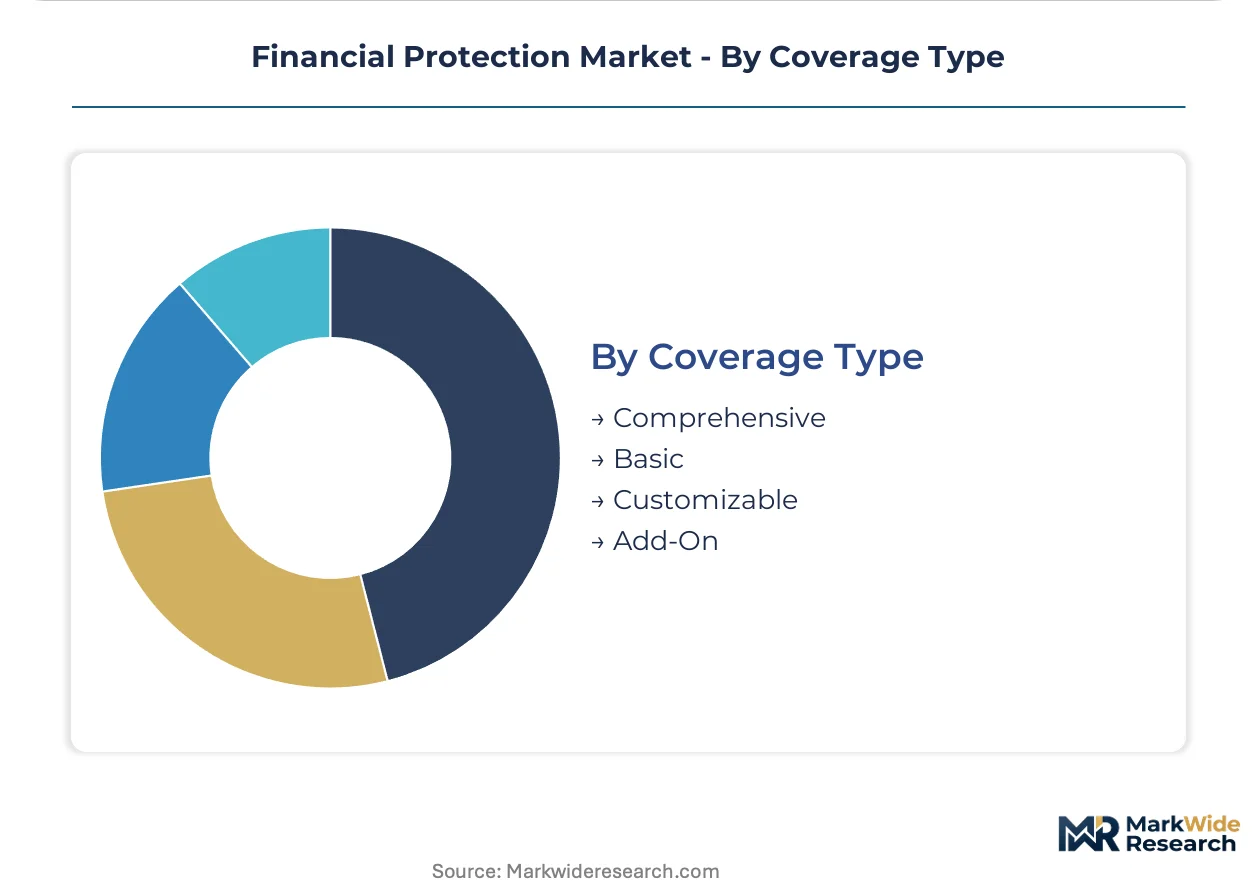
Coverage Type:
Benefit granularity and pricing flexibility separate off-the-shelf products from tailored risk transfer. Maturity of data infrastructure determines where customization remains cost-prohibitive.
- Comprehensive:Bundled mortality, morbidity, and disability protection with integrated claims administration.
- Basic:Stripped-down coverage with limited benefit periods and exclusion-heavy terms.
- Customizable:Modular riders allowing policyholder selection of benefit triggers, elimination periods, and inflation protection. Satellite-triggered parametric products bypass traditional loss adjustment for agricultural segments in catastrophe-prone regions.
- Add-On:Supplementary coverage attached to base policies through API-first distribution partnerships.
Comprehensive policies dominate persistency metrics; Customizable structures are climbing the fastest as telematics integration matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shanghai's financial district anchors premium growth in financial protection, where state-backed carriers and private insurers compete for household penetration. Tier-one cities across China concentrate distribution infrastructure and regulatory innovation. Secondary markets in India and Southeast Asia accelerate through digital underwriting platforms and embedded distribution partnerships.
United States
Employer-sponsored group disability and voluntary benefits drive premium volume as workforce retention strategies tighten. State-level insurance commissioner rate oversight shapes product approval timelines and reserve requirements. The Greater Boston corridor hosts actuarial talent clusters where data science capabilities concentrate for predictive risk modeling.
Germany
Multinational corporations expand group coverage mandates as labor market competition intensifies for skilled workers. Solvency II frameworks impose granular stress-testing and asset-liability matching rules on domestic carriers. The Munich-Frankfurt insurance corridor anchors commercial lines specialization through captive broker networks and reinsurance infrastructure.
China
Household penetration accelerates in Beijing, Shanghai, Shenzhen and Guangzhou where middle-class mortality protection gaps persist. The Banking and Insurance Regulatory Commission mandates life coverage bundling with retail banking products. Ping An Insurance leverages its in-house technology stack to compress distribution costs across mainland tier-one cities.
India
Microinsurance penetration expands through regulatory sandbox approvals for sachet-sized products targeting informal sector workers. The Insurance Regulatory and Development Authority enables digital distribution partnerships with fintech platforms. Mumbai and Bangalore concentrate insurtech development where API-first embedded coverage integrates with ride-hailing and e-commerce applications.
United Kingdom
Telematics-integrated life and health products absorb continuous biometric feeds from policyholder wearable devices. The Financial Conduct Authority and Prudential Regulation Authority oversee conduct standards and solvency requirements. London's Lloyd's market and Edinburgh's pension fund clusters drive innovation in parametric coverage and longevity risk transfer structures.
Financial Protection Market Competitive Landscape
Global majors compete with regional champions across distribution technology and regulatory navigation capabilities. Market structure tilts toward consolidated tier-one players with captive technology stacks, while mid-tier carriers depend on third-party platform partnerships. Three archetypes dominate: integrated technology-insurers with in-house underwriting automation, legacy carriers executing decade-long cloud migrations, and digital-native insurtechs with API-first distribution models. M&A activity concentrates on data science talent acquisition and regional license purchases.
Within the integrated technology tier, Ping An Insurance exemplifies vertical control over distribution infrastructure. Among European commercial lines specialists, Allianz SE occupies a position anchoring multinational employer coverage. Prudential Financial represents the group benefits archetype in North American voluntary and disability markets. These three companies illustrate divergent strategic paths: captive technology investment, regional commercial specialization, and broker network dominance.
| Leading Market Players |
|---|
| Ping An Insurance (Group) Company of China Ltd. |
| Cigna Corporation |
| Allianz SE |
| MetLife Inc. |
| Dai-ichi Life Holdings Inc. |
| China Pacific Insurance (Group) Co. Ltd. |
| Nationwide Mutual Insurance Company |
| Prudential Financial Inc. |
| American International Group |
| Others |
Supply & Pricing Matrix
Cloud-native core system migrations across North America, Europe, and Asia simultaneously compress actuarial modeling costs and concentrate technology procurement power among carriers with captive development capabilities. This infrastructure transition reshapes unit economics as legacy mainframe-dependent insurers face decade-long re-platforming timelines while digitally native competitors capture pricing flexibility through real-time data integration.
Pricing Analysis
Input-cost pass-through from technology infrastructure investments dominates pricing structures across the sector. Three-tier pricing separates comprehensive bundled coverage from modular riders and stripped-down basic products, with premium tiers commanding margins through customization depth. Cost compression in standardized term life products intensifies as online platforms disintermediate agent networks. Individual purchasers through direct channels exhibit highest price sensitivity, while corporate group sponsors prioritize coverage breadth over per-unit cost.
Supply Chain Analysis
Actuarial talent supply rests on specialized labor pools concentrated in the United States, the United Kingdom, and Singapore where data science expertise intersects with insurance domain knowledge. Cloud infrastructure provisioning draws from hyperscaler networks, proprietary technology stacks, and third-party platform partnerships. Single-source vulnerability in legacy system migration expertise creates execution risk for mainframe-dependent incumbents. Distribution runs through captive agent networks, independent broker channels, and algorithmic direct-to-consumer platforms with diverging margin economics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through AI-driven underwriting automation that compresses acquisition costs while enabling premium-tier pricing for behaviorally-monitored coverage. Infrastructure control separates winners from margin-compressed followers.
For Market Incumbents: Acquire cloud-native technology assets and specialized data science teams to defend against digital-native entrants with embedded distribution advantages. Mainframe migration delays represent existential vulnerability as real-time pricing capabilities concentrate among technology-forward competitors. Investment in proprietary underwriting algorithms preserves margin differentiation against platform-dependent mid-tier carriers. For New Entrants and Emerging Players: China's Banking and Insurance Regulatory Commission embedded distribution mandates open a window for API-first insurtechs to penetrate household coverage through banking partnerships. India's regulatory sandbox approvals for microinsurance products present accessible entry points for informal sector-focused offerings. Target parametric coverage segments in catastrophe-prone agricultural regions where satellite-triggered products bypass traditional loss adjustment infrastructure. For Investors and Strategic Acquirers: Roll-up economics work for regional broker networks with captive corporate relationships because employer-sponsored coverage expansion creates stable renewal revenue pools. Mid-tier carriers lacking proprietary technology stacks face margin compression requiring consolidation to achieve infrastructure scale. Watch telematics adoption rates as inflection indicator for dynamic pricing penetration and adverse selection pool compression.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core System Migration | Ping An Insurance's in-house technology stack demonstrates captive infrastructure control over distribution economics. |
| AI-Driven Underwriting Automation | Machine learning risk scoring compresses policy issuance timelines from weeks to hours for digitally native carriers. |
| Embedded Distribution Partnership | API-first platforms integrate coverage at point-of-sale across Southeast Asian e-commerce and ride-hailing applications. |
| Telematics-Integrated Product Development | South Korean and UK insurers price coverage based on continuous biometric feeds from policyholder wearable devices. |
| Microinsurance Regulatory Sandbox Entry | India's Insurance Regulatory and Development Authority enables sachet-sized products for informal sector worker penetration. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's insurance regulatory clusters and technology development corridors. Primary interviews with chief underwriting officers, actuarial directors, insurtech platform executives, and corporate benefits administrators combined with secondary validation from Solvency II disclosure filings, state insurance commissioner rate filings, and CBIRC capital adequacy reports. Bottom-up policy volume modeling and top-down premium pool estimation provided cross-referenced triangulation.
Granularity-level modeling operated at product-type, customer-segment, and channel-dimension resolution across the projection horizon. Life insurance, critical illness, disability, and accident products were modeled separately with distinct reserve-backed liability assumptions and underwriting intensity parameters. CAGRs derived from premium growth trajectories, household penetration curves, and employer-sponsored coverage expansion rates. Technology adoption curves for AI underwriting and telematics integration informed dynamic pricing penetration assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between risk-based capital regimes and prescriptive product approval processes. Forecasts reflect documented assumptions regarding medical cost inflation trajectories, interest rate environments affecting reserve investment returns, and cloud infrastructure cost curves. Interest rate volatility, healthcare provider consolidation pace, and data privacy regulatory expansion warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
IoT Insurance Market
Insurance
MENA Health and Medical Insurance Market
Insurance
Germany Electronic Gadgets Insurance Market
Insurance
Marine Freight Insurance Market
Insurance
Germany Car Insurance Market
Insurance
Global Long Term Care Insurance Market
Insurance
Embedded Insurance Market
Insurance
UK Commercial Insurance Market
Insurance
Business Income Insurance Market
Insurance
General Insurance Market
Insurance
Business Insurance Market
Insurance
Asia-Pacific Extended Warranty Market
Insurance
B2B2C Insurance Market
Insurance
Identity Theft Insurance Market
Insurance
USA Travelers Insurance Market
Insurance
Europe Travel Insurance Market