
 Global SME Insurance Market | 2026-2036
Global SME Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global SME Insurance Market Outlook
Market Context
Multi-source distribution is hardening as the dominant procurement pattern among small and midsize enterprises seeking coverage flexibility. Chubb Ltd. leverages its commercial underwriting depth to serve high-growth technology segments. Allianz SE anchors its SME portfolio through embedded partnerships with banking networks across Germany and Southeast Asia. Hiscox Ltd. specializes in professional liability for professional services firms, differentiating through direct digital origination.
Technical Definition and Segment Structure
SME insurance encompasses risk-transfer instruments calibrated to enterprises with limited employee counts and moderate revenue scales, typically featuring simplified underwriting, standardized policy terms, and premium thresholds below large-commercial tiers. The primary purpose centers on shielding owner-operators from operational liabilities, asset losses, and income disruption without requiring dedicated risk-management departments. Cyber Risk coverage within the Coverage Type dimension is expanding fastest as ransomware exposure penetrates smaller technology and services firms, while Property coverage remains the mature revenue anchor. The Industry Vertical split shows Technology outpacing Manufacturing in policy growth velocity, though Manufacturing still occupies the largest absolute premium pool due to higher per-firm property values.
Regulatory Frame and Outlook
Solvency II in Europe, state-level rate regulation by the NAIC across the United States, and the EU AI Act's risk-classification requirements collectively shape product filing timelines, capital reserves, and algorithmic underwriting transparency. India's IRDAI pushes bancassurance expansion and micro-insurance standardization, tightening distributor qualification while broadening access. Stakeholders must monitor how fragmented national capital requirements and emerging digital-asset coverage definitions alter competitive entry costs across jurisdictions.
Market Dynamics
Digital distribution platforms are compressing acquisition costs and fragmenting traditional broker networks as embedded insurance partnerships penetrate banking and software ecosystems across multiple jurisdictions.
Growth Catalysts
- EU AI Act risk-classification mandates:Algorithmic underwriting transparency requirements are accelerating insurer investment in explainable AI tools for SME policy pricing.
- India's micro-enterprise formalization:IRDAI bancassurance expansion and micro-insurance standardization protocols are driving policy uptake among previously informal businesses.
- Cyber Risk coverage expansion:Ransomware exposure penetrating smaller technology and services firms is electrifying demand for specialized liability products.
Market Restraints
- State-level rate regulation:NAIC filing timelines across the United States create product-launch friction and compress margin flexibility for standardized SME offerings.
- Capital reserve fragmentation:Divergent Solvency II implementation across EU member states elevates compliance costs for cross-border SME portfolios.
- Legacy core system dependency:Mainframe-based policy administration at established carriers constrains real-time data integration for usage-based SME products.
Strategic Opportunities
- Southeast Asia digital platform integration:Technology startups across Singapore, Indonesia, and Vietnam present embedded insurance white space through accounting and payment software partnerships.
- Digital-asset coverage definitions:Emerging regulatory frameworks for cryptocurrency custody and smart-contract liability open specialized product categories for fintech SMEs.
- API-first distribution:Open banking interfaces in Germany and the United Kingdom enable direct policy origination within enterprise resource planning workflows.
Industry Challenges
- Actuarial talent scarcity:Shortage of professionals skilled in machine-learning risk modeling constrains algorithmic product development timelines.
- Multi-jurisdiction compliance integration:Reconciling GDPR data-handling requirements with India's data-localization mandates complicates cloud-based policy administration platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global SME Insurance Market |
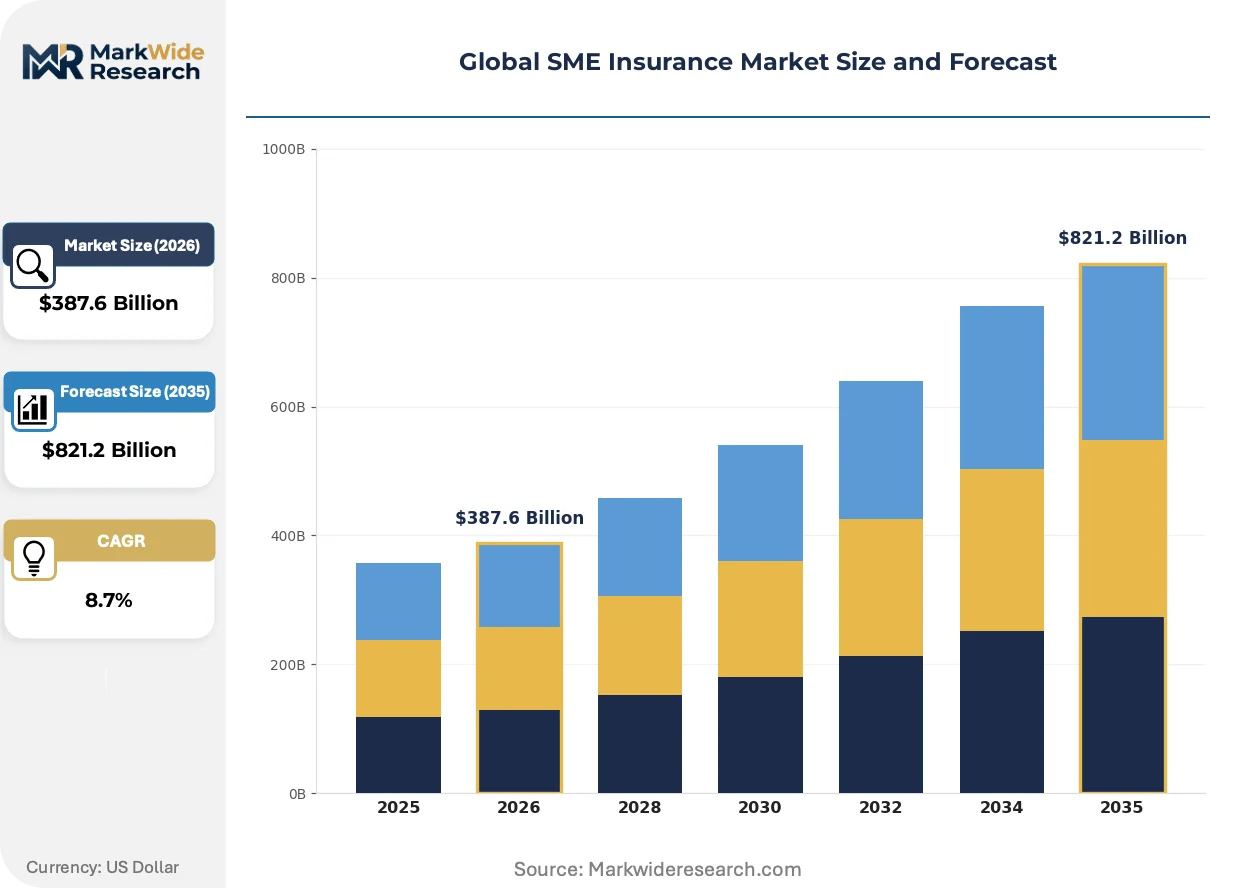
| Market Size in 2026 | $387.6 Billion |
| Market Size in 2035 | $821.2 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Liability, Property, Business Interruption, Cyber Risk Industry Vertical: Manufacturing, Retail, Services, Technology Policy Length: Short-term, Annual, Multi-year, Ongoing Premium Size: Low, Medium, High, Customized |
| Companies Covered | Chubb Ltd., Liberty Mutual, AXA, Travelers Companies, Hiscox Ltd., Allianz SE, The Hartford, QBE Insurance Group, Zurich Insurance Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global SME Insurance Market Strategic Shifts
Parametric triggers and real-time data feeds are displacing traditional indemnity structures as climate volatility and cyber incident frequency outpace conventional loss-adjustment capabilities.
Embedded insurance APIs are electrifying distribution economics by surfacing coverage offers at point-of-sale within accounting software, payment processors, and e-commerce platforms. Technology startups in Southeast Asia and fintech lenders in Germany are adopting these integrations fastest. The structural consequence is disintermediation of traditional broker networks as policy origination shifts to software touchpoints.
REACH chemical safety data requirements and the EU AI Act's algorithmic transparency mandates are reshaping product filing protocols for insurers offering packaged liability coverage to manufacturing and technology SMEs. Industrial consequence includes extended actuarial review cycles and elevated documentation burdens. German and French carriers are responding by consolidating regulatory affairs functions and pre-clearing model documentation with national supervisors.
Purchasing behavior among SMEs is fragmenting across direct digital, embedded, and advisory channels simultaneously. Small technology firms in Singapore and Bangalore are unbundling coverage procurement from traditional annual renewal cycles, instead activating modular policies triggered by project milestones or funding events. This pattern is most visible among venture-backed startups where insurance procurement aligns with investor due-diligence requirements.
Global SME Insurance Market Segmentation
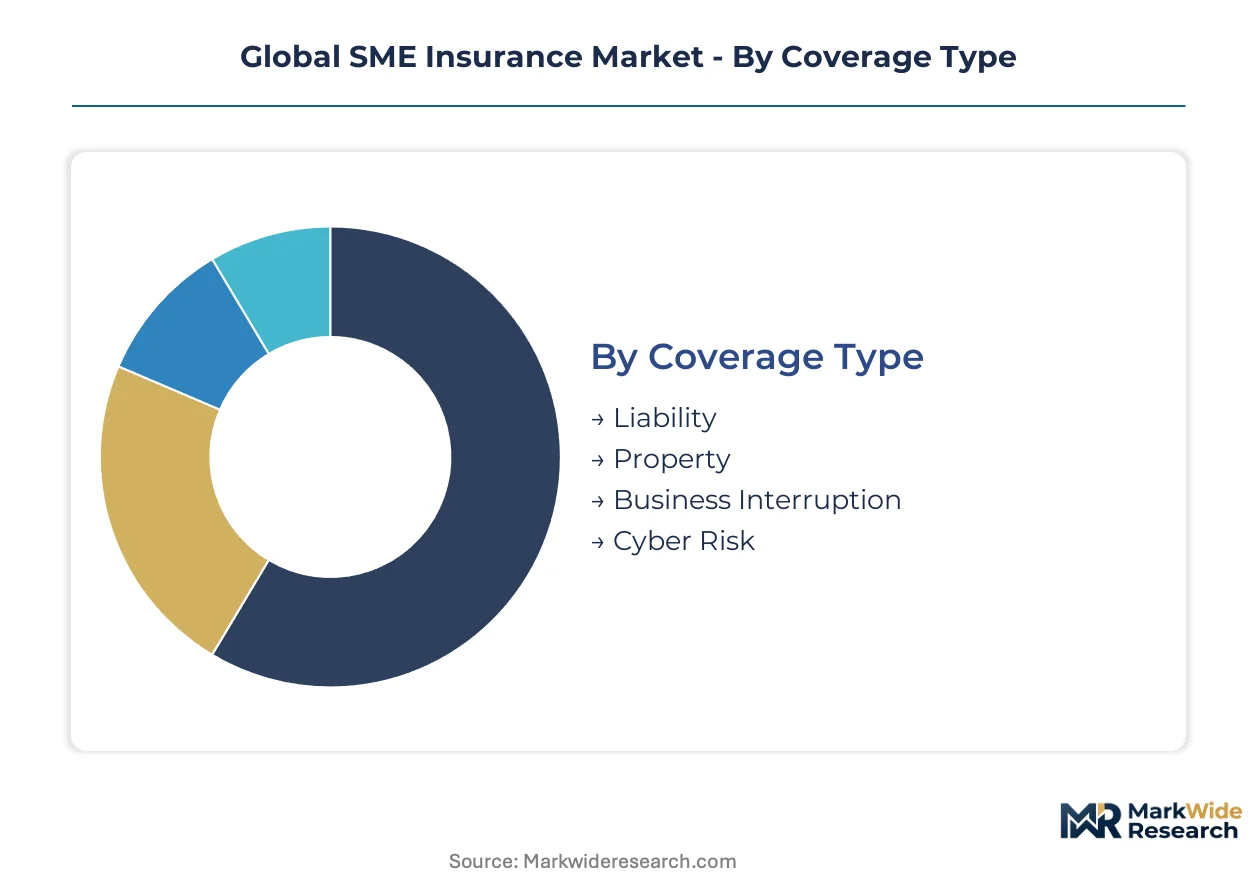
SME insurance segmentation reveals how risk profiles, procurement cycles, and capital constraints fragment demand across coverage types and industry verticals. Insurers calibrate product architecture, distribution channels, and pricing models to match these dimensional splits.
Coverage Type:
Premium thresholds and loss severity drive coverage selection among owner-operators with limited risk-management staff.
- Property:Physical asset protection covering buildings, equipment, and inventory against fire, theft, and natural perils. Manufacturing clusters in Germany and India concentrate demand here as asset-heavy operations require collateral protection for secured financing.
- Cyber Risk:Liability and recovery coverage for data breaches, ransomware, and business interruption from network incidents. Technology startups in Singapore and professional services firms in the United Kingdom are electrifying demand as attack frequency penetrates smaller enterprises.
- Liability:Third-party bodily injury and property damage protection.
- Business Interruption:Income replacement during operational shutdowns from covered perils.
Property leads on scale; Cyber Risk leads on momentum.
Industry Vertical:
Per-firm revenue volatility and regulatory exposure intensity shape vertical-specific product bundling.
- Technology:Coverage for software developers, SaaS providers, and digital platforms combining cyber liability with professional indemnity. Venture-backed startups in Bangalore and Berlin are unbundling annual renewals into modular policies triggered by funding rounds.
- Manufacturing:Asset-heavy protection integrating property, equipment breakdown, and product liability. German Mittelstand firms and Indian micro-enterprises formalizing under IRDAI protocols anchor premium volume despite slower growth velocity.
- Retail:Inventory and premises liability for brick-and-mortar and e-commerce operators.
- Services:Professional liability and general liability for consultancies and trades.
Manufacturing dominates absolute premium; Technology climbs the fastest.
Policy Length:
Cash flow predictability and contractual requirements determine duration preferences across SME subsegments.
- Annual:Standard 12-month renewable terms with rate guarantees. Established retailers in France and professional services firms in the United States default here for budget stability and regulatory compliance simplicity.
- Short-term:Project-based or event-triggered coverage spanning weeks to months. Construction subcontractors in Australia and event vendors in the UAE activate these for contract-specific liability requirements.
- Multi-year:Extended terms with locked pricing for stable operations.
- Ongoing:Continuous coverage with automatic renewal for embedded insurance partnerships.
Annual policies dominate transaction volume; Short-term formats gain share fastest.
Premium Size:
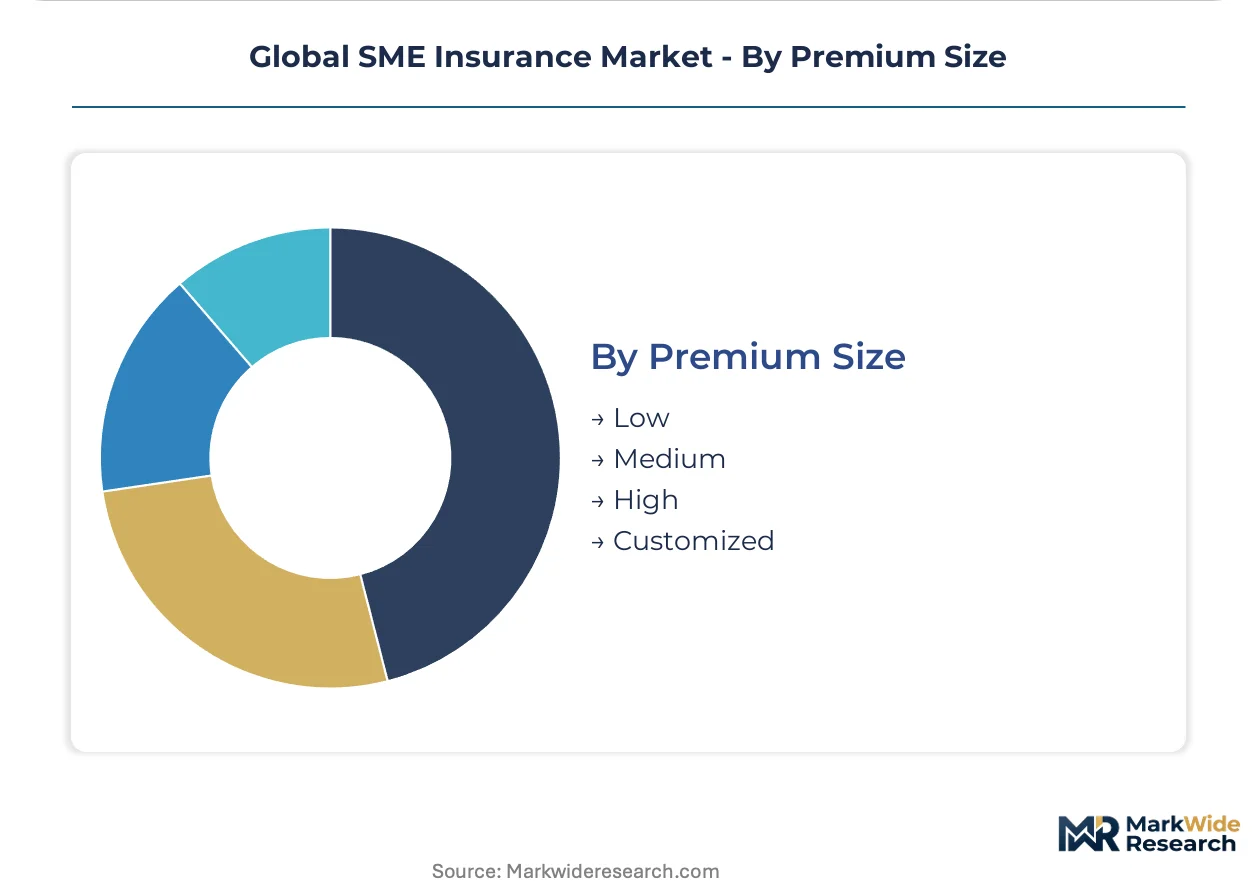
Revenue scale and risk complexity stratify SME buyers into distinct pricing tiers with varying service expectations.
- Medium:Mid-market enterprises with 50-250 employees seeking packaged coverage with limited customization. German automotive suppliers and Indian export manufacturers cluster here, driving standardization in policy wordings.
- Customized:Bespoke programs for complex risks requiring manuscript endorsements and dedicated underwriting. Fintech lenders in the United Kingdom and biotech startups in Switzerland command these structures for unique regulatory and contractual exposures.
- Low:Simplified products for micro-enterprises with minimal assets.
- High:Upper-mid-market accounts approaching large-commercial thresholds.
Medium premium tiers anchor carrier profitability; Customized segments expand most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping where SME insurers concentrate capital as Solvency II implementation variance across EU member states creates compliance-cost gaps that favor certain domiciles over others.
United States
NAIC state-level rate regulation generates filing friction that compresses margin flexibility for standardized SME offerings. Technology startups in Austin and Boston are unbundling annual renewals into modular policies triggered by venture funding rounds. The Hartford and Travelers Companies anchor market presence through commercial underwriting depth.
Germany
Mittelstand manufacturing clusters drive demand for asset-heavy property and equipment breakdown coverage. BaFin supervision of Solvency II implementation elevates capital reserve requirements for cross-border portfolios. Allianz SE leverages embedded partnerships with Sparkasse banking networks across Bavaria and North Rhine-Westphalia.
India
IRDAI bancassurance expansion and micro-insurance standardization protocols are electrifying policy uptake among formalizing micro-enterprises. RBI oversight of distributor qualification tightens while broadening access. Mumbai and Bangalore technology corridors anchor premium growth velocity.
United Kingdom
FCA conduct rules and Lloyd's market infrastructure shape professional liability product design for fintech and services firms. Hiscox Ltd. specializes in direct digital origination for professional services segments. London's insurance cluster concentrates cyber risk underwriting expertise.
Singapore
MAS regulatory sandbox frameworks enable embedded insurance experimentation within accounting and payment software platforms. Technology startups across the island-state are adopting API-first distribution fastest. MAS supervision of digital-asset custody definitions opens specialized coverage categories for fintech SMEs.
Global SME Insurance Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue embedded distribution partnerships and algorithmic underwriting capabilities. The vendor base concentrates around diversified multinational carriers with commercial underwriting depth, specialty underwriters with direct digital origination, and regional champions with bancassurance scale. Three archetypes dominate: integrated conglomerates with balance-sheet capacity, niche specialists with sector-specific expertise, and insurtech platforms with API-native infrastructure. Competitive moves center on strategic partnerships with banking and software ecosystems, plus portfolio diversification into cyber and digital-asset coverage.
Among integrated conglomerates, Chubb Ltd. and Allianz SE exemplify archetypes with commercial underwriting depth and embedded partnership scale respectively. Hiscox Ltd. occupies a position within the specialty tier, representing direct digital origination capabilities for professional liability segments. These three entities anchor competitive positioning across technology, manufacturing, and services verticals without dominating any single geography.
| Leading Market Players |
|---|
| Chubb Ltd. |
| Liberty Mutual |
| AXA |
| Travelers Companies |
| Hiscox Ltd. |
| Allianz SE |
| The Hartford |
| QBE Insurance Group |
| Zurich Insurance Group |
| Others |
Value Chain & Pricing Dynamics
Reinsurance pricing benchmarks cascading from Lloyd's and Bermuda markets compress carrier margin flexibility before products reach SME buyers, with cost pass-through intensity stratifying across premium tiers as embedded distribution partnerships absorb acquisition expense reductions.
Pricing Analysis
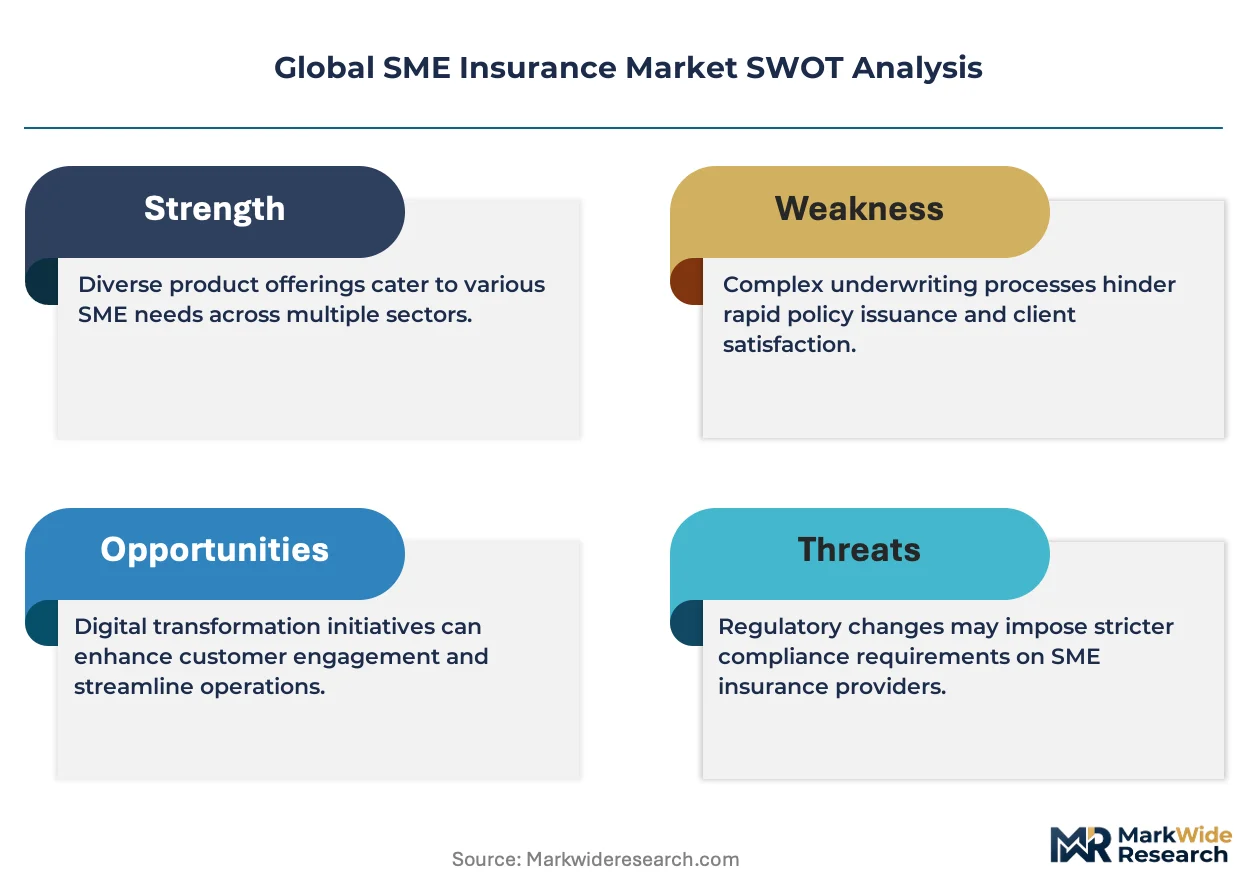
Input-cost pass-through from reinsurance treaty renewals and regulatory capital charges feeds directly into SME premium tiers. Three-tier pricing structure across premium, standard, and economy levels differentiates by policy customization depth and claims service levels. Cost compression in the standard tier is intensifying because embedded insurance APIs disintermediate broker commissions. Micro-enterprises in India's formalizing economy exhibit highest price sensitivity; venture-backed technology firms in Singapore and Germany demonstrate lowest sensitivity due to investor-mandated coverage requirements.
Supply Chain Analysis
Logistics and technology infrastructure costs for cloud-based policy administration platforms concentrate supply chain investment in Ireland, Singapore, and Germany as regulatory-compliant data center hubs. Carrier technology stacks draw from reinsurance capacity providers in Bermuda and London, actuarial software vendors in the United States and United Kingdom, and cloud infrastructure from hyperscalers with EU data residency certifications. Single-source vulnerability sits with legacy core system vendors whose mainframe architectures constrain real-time data integration. Distribution runs through embedded API partnerships with banking networks and accounting software platforms, displacing traditional broker networks fastest in Southeast Asia and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in SME insurance hinges on algorithmic underwriting efficiency gains and premium-tier migration toward cyber liability and digital-asset coverage categories where pricing power remains intact.
For Market Incumbents: Lock in embedded partnership exclusivity with Sparkasse banking networks in Germany and MAS-sandbox-approved software platforms in Singapore before insurtech challengers consolidate API access. Invest in explainable AI tooling to preempt EU AI Act compliance costs that will disadvantage carriers with opaque pricing models. Capacity addition in India through IRDAI-licensed bancassurance joint ventures captures formalizing micro-enterprise volume before regional champions dominate distribution.
For New Entrants and Emerging Players: Banking-as-a-service platforms and vertical SaaS providers for construction and professional services present the most penetrable channel partnerships for policy origination. White-space concentration sits with parametric cyber coverage for technology startups in Bangalore and Berlin, where traditional indemnity structures fail to match incident frequency. Go-to-market execution should prioritize API-first integration with venture-capital portfolio management tools to align coverage activation with funding milestones.
For Investors and Strategic Acquirers: Asymmetric upside sits with insurtech platforms possessing algorithmic underwriting engines and existing embedded distribution contracts. Long-term viability over a multi-year horizon favors carriers with demonstrated Solvency II compliance infrastructure and cross-border license portability. Acquisition targets should show concentration in cyber risk data assets and API-native policy administration. The signal to watch is regulatory pre-clearance of AI-driven pricing models by BaFin or MAS, indicating sustainable competitive moats against legacy carriers.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Insurance API Integration | Surfaces coverage at point-of-sale within accounting software, compressing acquisition costs for German and Southeast Asian carriers. |
| Explainable AI Investment | Preempts EU AI Act compliance costs while accelerating underwriting decisions for technology SME segments. |
| Bancassurance Capacity Expansion | Captures IRDAI-mandated micro-insurance growth among formalizing Indian micro-enterprises. |
| Cyber Risk Data Asset Acquisition | Builds proprietary incident frequency datasets that outperform traditional actuarial models for ransomware exposure. |
| Parametric Product Development | Displaces indemnity structures for climate and cyber volatility where loss adjustment lags incident occurrence. |
Study Parameters
Direct dialogue with chief underwriting officers, embedded partnership directors, regulatory affairs leads at EU and Asian carriers, and API platform engineers grounded qualitative insights. Secondary validation drew from Solvency II disclosure filings, IRDAI bancassurance licensing records, MAS regulatory sandbox approvals, and NAIC rate filing databases. Bottom-up policy volume estimates triangulated against top-down premium pool calculations across coverage type and industry vertical splits.
Bottom-up segmentation modeling across coverage type, industry vertical, policy length, and premium size dimensions generated volume and value outputs over the projection horizon. CAGRs were derived from trend extrapolation of formalization rates, digital platform penetration curves, and regulatory implementation timelines. Forecast inputs included ransomware incident frequency trajectories, IRDAI micro-insurance standardization adoption curves, and EU AI Act compliance cost estimates for algorithmic underwriting systems.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Solvency II implementation variance across EU member states, IRDAI distributor qualification enforcement intensity, and MAS digital-asset custody definition finalization. Forecasts reflect assumptions about regulatory timeline adherence and technology adoption curves without guaranteeing specific outcomes. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
US Homeowner's Insurance Market
Insurance
Auto Compulsory Insurance Market
Insurance
Online Insurance Market
Insurance
Intellectual Property Insurance Market
Insurance
Art Insurance Market
Insurance
Social Media Analytics-Based Insurance Market
Insurance
Event Insurance Market
Insurance
Cannabis Crop Insurance Market
Insurance
Takaful Market
Insurance
Spain Parametric Insurance Market
Insurance
China Property and Casualty Insurance Market
Insurance
South Africa Property and Casualty Insurance Market
Insurance
Global Cargo Transportation Insurance Market
Insurance
Fire Insurance Market
Insurance
Japan Liability Insurance Market
Insurance
Aerial Imaging in Insurance Service Market