
 Global Long Term Care Insurance Market | 2026-2036
Global Long Term Care Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Global Long Term Care Insurance Market Outlook
Multi-source distribution from captive agents toward independent advisors and direct digital channels is shifting how carriers reach policyholders. New York Life leverages its mutual structure to sustain above-average policyholder retention rates. Genworth anchors the traditional stand-alone segment with specialized underwriting expertise in impaired-risk pools. John Hancock differentiates through integrated wellness-linked premium discounts tied to wearable data streams.
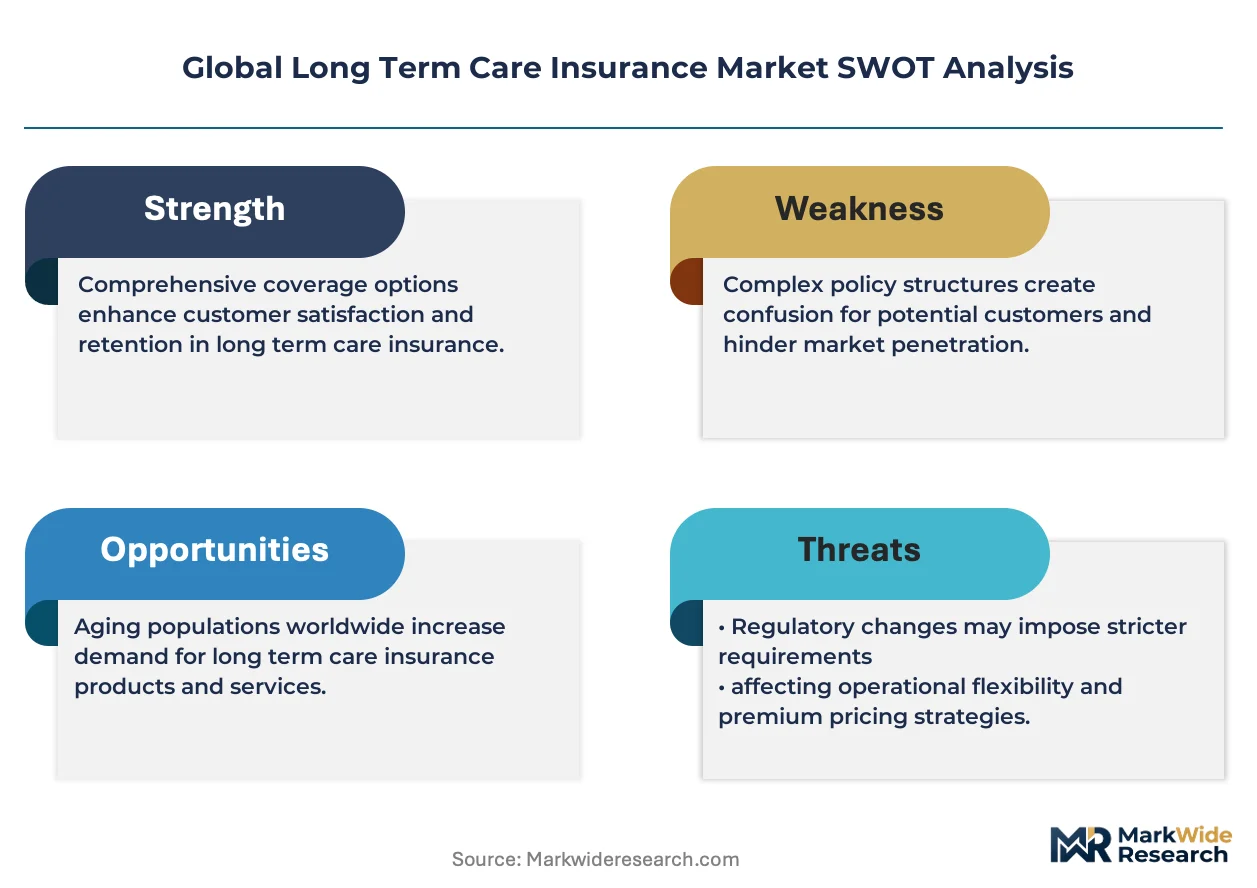
Long term care insurance constitutes a risk-transfer contract covering extended custodial, nursing home, assisted living, or home health services triggered by defined activities-of-daily-living impairments or cognitive decline; policies specify elimination periods, daily benefit maximums, and inflation riders that determine real claim value. The primary commercial purpose centers on protecting retirement asset depletion against extended care episodes that Medicare excludes. Hybrid plans that combine permanent life insurance with accelerated death-benefit long term care riders now capture the fastest-growing structural position as consumers reject use-it-or-lose-it stand-alone designs. Traditional plans remain the largest premium pool but face contraction pressure from carrier exits and repeated rate increase cycles. Corporations as a customer segment represent an underdeveloped margin pool where group voluntary enrollment models reduce adverse selection.
The U.S. Department of Health and Human Services shapes demand through tax-qualified policy standards under IRC Section 7702B, while state insurance commissioners enforce rate stability regulations that constrain pricing flexibility. Japan's Ministry of Health, Labour and Welfare operates the mandatory long-term care social insurance system that competes with and partly substitutes for private coverage. The European Insurance and Occupational Pensions Authority develops solvency capital requirements that affect product profitability across EU carriers. Stakeholders must monitor whether U.S. state Long-Term Care Partnership Program expansions or federal automatic enrollment proposals alter the private-public coverage boundary.
Market Dynamics
Hybrid life-LTC policy designs are electrifying product architecture as carriers abandon stand-alone mortality tables for bundled mortality-morbidity pricing, forcing reinsurance treaty renegotiations and compressing distribution commission structures industry-wide.
Growth Catalysts
- IRC Section 7702B tax incentives:Federal premium deductibility thresholds indexed to age brackets pull high-net-worth households into qualified contracts, amplifying private coverage substitution against Medicaid spend-down strategies.
- Employer-sponsored group voluntary models:Workforce aging at technology and professional services firms creates pooled risk pools with reduced adverse selection, expanding addressable lives without medical underwriting friction.
- Wearable biometric integration:Continuous glucose monitors and activity trackers enable dynamic premium discounts, aligning policyholder incentives with claims prevention and extending policy duration.
Market Restraints
- Long-duration liability duration mismatch:Guaranteed renewable pricing locked in during low-rate environments creates reserve strain as carriers reinvest at compressed yields, forcing repeated rate increase filings.
- Japan's mandatory social LTCI:The Ministry of Health, Labour and Welfare's compulsory 40+ enrollment crowds out private policy demand in the world's most penetrated aging market, capping premium growth.
- Morbidity assumption volatility:Cognitive decline incidence projections diverge materially across actuarial tables, inflating capital requirements under stochastic reserving frameworks and constraining new market entrants.
Strategic Opportunities
- India's uninsured middle class:Family-based elder care norms are eroding as nuclear household formation accelerates, creating first-mover advantage for rupee-denominated indemnity products with home health riders.
- Accelerated underwriting automation:Electronic health record APIs and prescription history algorithms compress issuance timelines from weeks to hours, unlocking direct-to-consumer channels previously uneconomical for complex morbidity products.
- EU Solvency II longevity risk hedging:Capital relief for insurers issuing longevity swaps alongside LTC coverage creates structural profitability improvement unavailable in non-EU jurisdictions.
Industry Challenges
- Actuarial talent scarcity:Predictive modeling for multi-decade morbidity projections requires specialized expertise in geriatric epidemiology that traditional life pricing teams lack, extending product development cycles.
- Legacy policy administration system migration:COBOL-based platforms from the 1990s cannot support real-time wearable data ingestion, forcing costly parallel system builds during active rate increase litigation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Long Term Care Insurance Market |
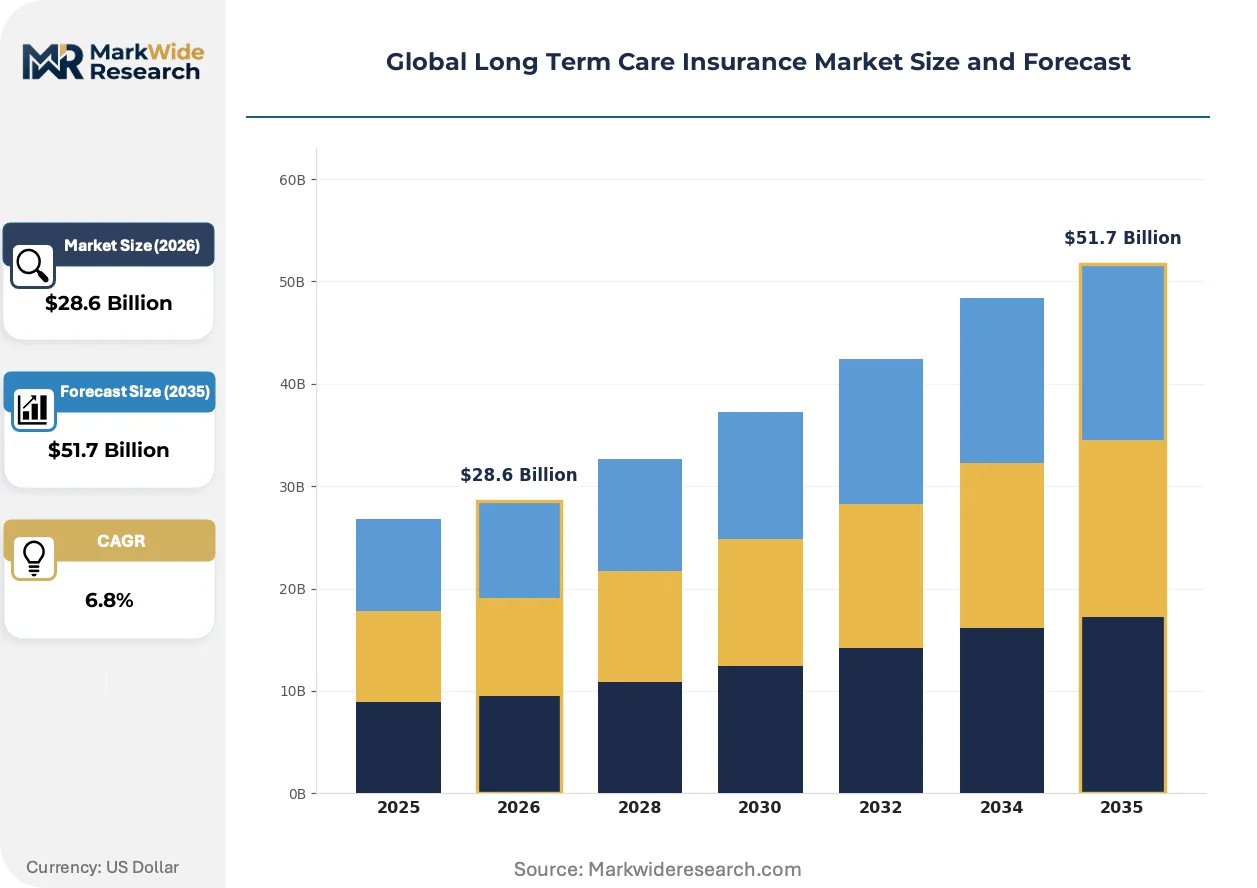
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traditional Plans, Hybrid Plans, Annuity Plans, Short-Term Plans Customer Segment: Individuals, Families, Corporations, Government Payment Structure: Premium Payable, Lump Sum, Waiting Period, Benefit Period Policy Features: Cash Benefit, Care Coordination, Inflation Protection, Waiver of Premium |
| Companies Covered | New York Life, Genworth, John Hancock, Mutual of Omaha, Pacific Life, Lincoln Financial Group, Nationwide, Prudential, National Guardian Life, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Long Term Care Insurance Market Strategic Shifts
Digital distribution infrastructure and predictive health analytics are compressing the traditional agent-mediated sales cycle while enabling dynamic policy structures that respond to real-time biometric inputs rather than static annual renewals.
Telehealth-integrated care coordination platforms are electrifying claims management workflows. Carriers now embed virtual physician networks directly into policy benefits, enabling early intervention that delays nursing home placement. Large group employers in the United States are piloting these bundled offerings, recognizing that remote monitoring reduces absenteeism among caregiver employees while compressing severity-weighted claim reserves.
The EU's CSRD sustainability disclosure requirements are mandating granular reporting on insurance product accessibility for aging populations. Carriers operating across Germany, France, and Italy must now publish demographic penetration rates and premium affordability metrics, creating competitive pressure to simplify contract language and reduce elimination period durations. This regulatory friction most affects traditional stand-alone products with complex benefit triggers.
Behavioral economics-driven enrollment design is displacing conventional opt-in group voluntary structures. Automatic enrollment with opt-out provisions—pioneered in 401(k) retirement plans—are migrating to employer LTC benefits, capturing participation rates three to four times higher than active election models. Large technology employers in California and Washington have deployed this architecture, leveraging payroll integration to reduce decision friction among pre-retirement workers who otherwise defer coverage decisions indefinitely.
Global Long Term Care Insurance Market Segmentation
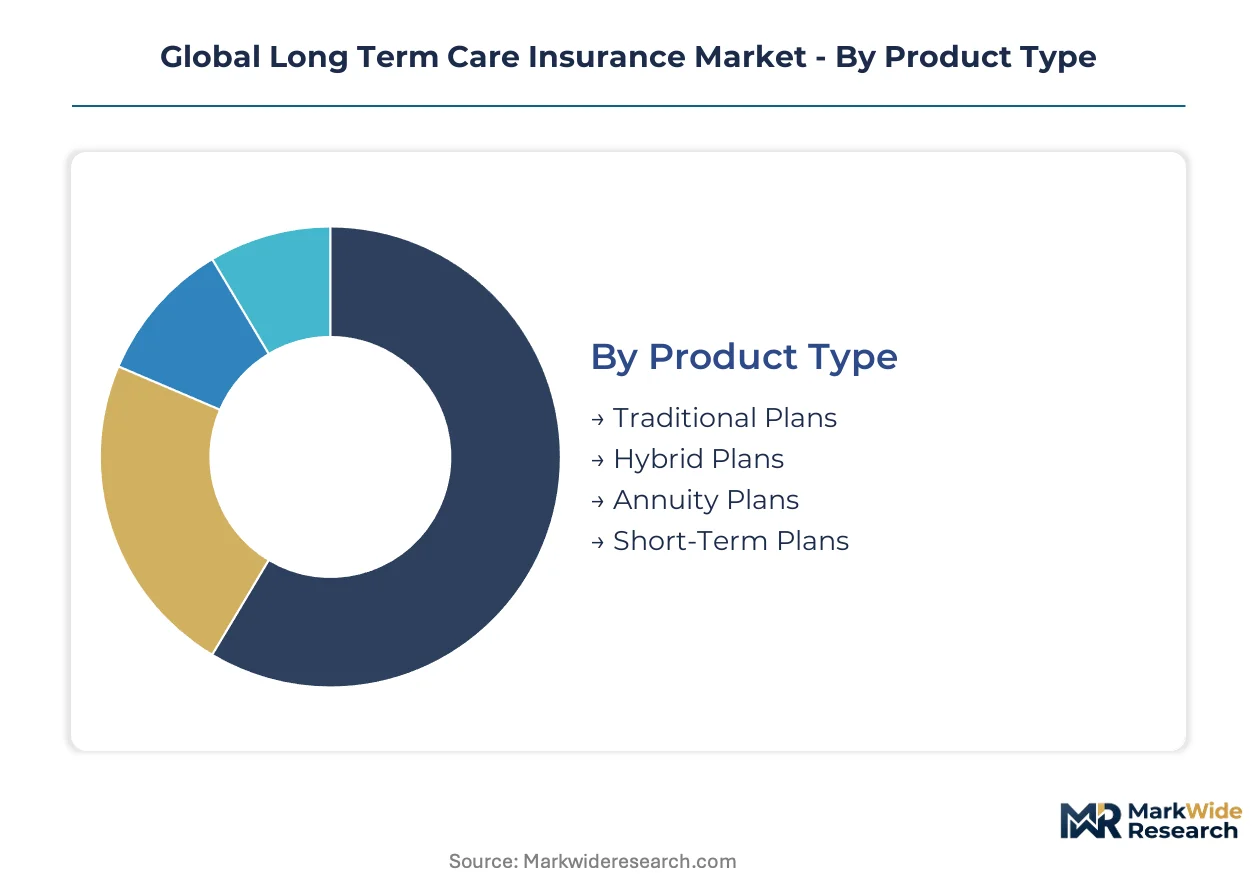
Long term care insurance products diverge sharply in how they integrate with broader financial planning. Standalone policies compete against embedded riders within life insurance and annuity chassis, each carrying distinct capital requirements, distribution economics, and consumer risk profiles that reshape carrier portfolio strategy.
Product Type:
Integration depth separates standalone morbidity contracts from bundled mortality-morbidity hybrids that share policy chassis with permanent life insurance.
- Traditional Plans:Pure long term care contracts with guaranteed renewable pricing and standalone morbidity tables. Japan's Ministry of Health, Labour and Welfare mandates compete directly with these products, compressing private penetration in the world's most aged society.
- Hybrid Plans:Bundled products combining permanent life insurance with accelerated death-benefit long term care riders. U.S. high-net-worth households gravitate toward these structures under IRC Section 7702B tax incentives, rejecting use-it-or-lose-it designs.
- Annuity Plans:Deferred annuity chassis with attached long term care benefit multipliers. Retirees with substantial qualified assets utilize these for tax-deferred accumulation alongside contingent care coverage.
- Short-Term Plans:Limited-duration contracts bridging gaps before Medicare eligibility or employer coverage activation. Younger policyholders purchase these during career transitions or early retirement phases.
Traditional plans lead volumes today; hybrid plans are gaining share fastest.
Customer Segment:
Cost tier stratification separates retail purchasers absorbing full underwriting from group pools where employers subsidize acquisition and reduce adverse selection.
- Individuals:Retail purchasers navigating medical underwriting and individual risk classification. California and Washington technology workers increasingly select individual policies after exhausting employer portability limits.
- Families:Multi-generational purchasing units coordinating coverage across household members. Adult children in India's nuclear households drive first-time demand as informal elder care norms erode.
- Corporations:Employer-sponsored group voluntary enrollment models with simplified underwriting. Professional services firms deploy automatic enrollment architectures that capture participation rates multiples higher than opt-in structures.
- Government:Public sector employee benefit pools and state Long-Term Care Partnership Program administrators. U.S. state Medicaid agencies utilize these partnerships to shift liability toward private coverage.
Individuals dominate premium collection currently; corporations show the steepest expansion trajectory.
Payment Structure:
Application context determines whether policyholders prefund liabilities through single premiums or distribute risk across working-life payment streams.
- Premium Payable:Level or graded periodic payments spanning policy duration. Germany's Solvency II capital requirements penalize long-duration guaranteed liabilities, compressing carrier appetite for these structures.
- Lump Sum:Single premium funding eliminating future payment uncertainty and lapse risk. Affluent retirees favor these for estate planning integration and immediate paid-up status.
- Waiting Period:Elimination interval design choices ranging from zero to one hundred eighty days before benefit activation. Shorter periods concentrate demand among policyholders with limited liquid reserves.
- Benefit Period:Duration limits defining maximum claim payment windows from two years to lifetime coverage. Lifetime benefit designs face severe pricing pressure from reserve strain under low-yield reinvestment environments.
Premium payable structures anchor the market; lump sum designs are climbing the fastest.
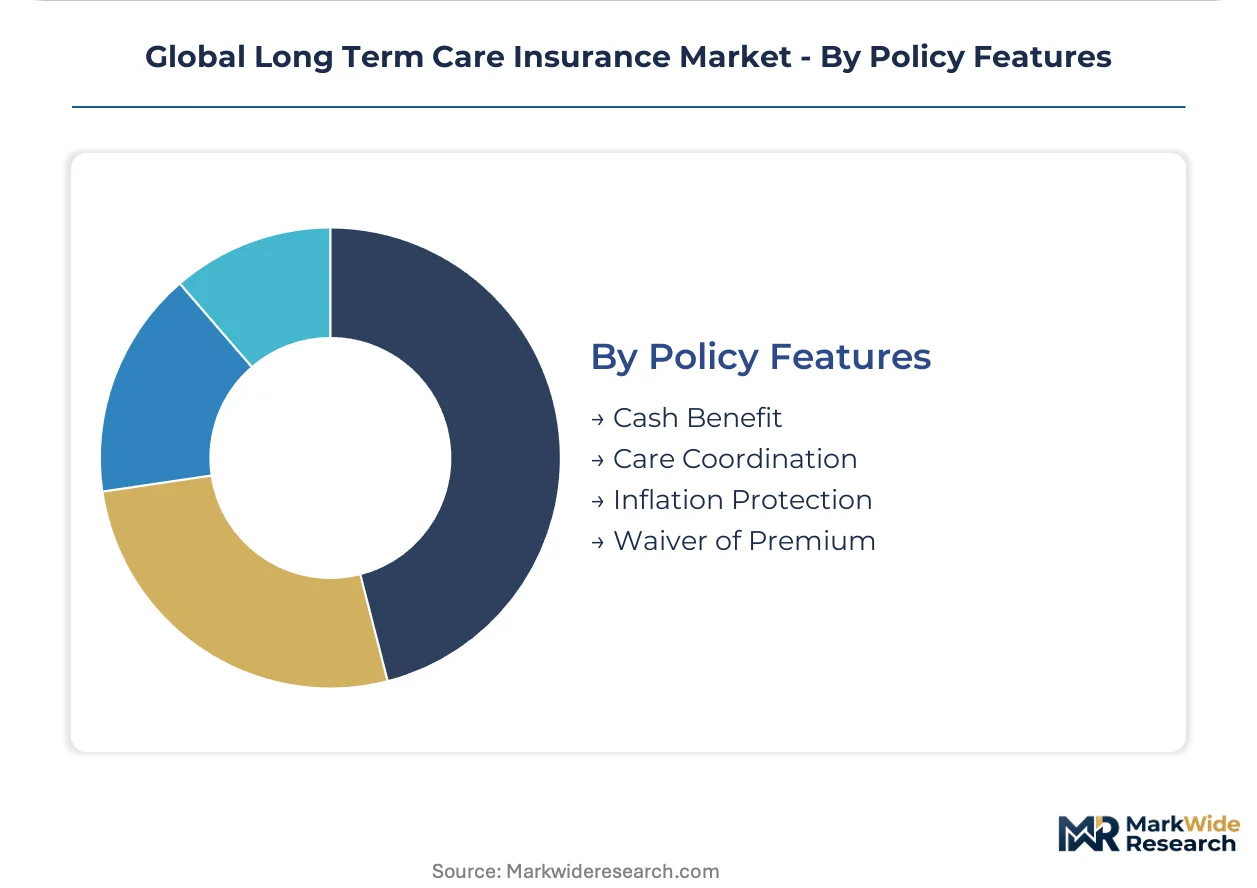
Policy Features:
Maturity differentiation separates basic indemnity contracts from sophisticated products embedding care management and inflation hedging.
- Cash Benefit:Indemnity-style payments without expense reimbursement requirements or care provider restrictions. Policyholders in informal care arrangements prefer these for flexibility in allocating family-provided assistance.
- Care Coordination:Embedded nurse navigation and telehealth-integrated case management services. Large U.S. group employers pilot these bundled offerings to reduce absenteeism among employee caregivers.
- Inflation Protection:Compound or simple benefit increase riders preserving real claim value against medical cost escalation. IRC Section 7702B qualified contracts require these features for tax-advantaged status.
- Waiver of Premium:Premium obligation suspension during active claim periods. This feature concentrates in traditional stand-alone products rather than hybrid chassis where mortality charges persist.
Inflation protection riders lead attachment rates; care coordination features are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Tokyo-Osaka corridor concentrates the world's most penetrated aging demographics, where super-aged population structures have institutionalized long-term care financing across public and private channels.
United States
High-net-worth households in California and New York Metro drive hybrid policy adoption under IRC Section 7702B tax incentives, rejecting traditional use-it-or-lose-it designs. The Department of Health and Human Services expanded federal premium deductibility thresholds indexed to age brackets. Large technology employers in Seattle and Silicon Valley pilot automatic enrollment architectures with opt-out provisions.
Japan
Super-aged demographics in Kanto and Kansai regions sustain policy penetration rates far above Western benchmarks despite structural headwinds. The Ministry of Health, Labour and Welfare operates mandatory long-term care social insurance competing with private coverage. Private carriers concentrate product development in Tokyo's financial district for affluent segments seeking supplemental benefits beyond public provision.
Germany
Solvency II capital requirements penalize long-duration guaranteed liabilities, compressing carrier appetite for premium-payable structures across Bavaria and North Rhine-Westphalia. The European Insurance and Occupational Pensions Authority enforces reserving frameworks affecting product profitability. Frankfurt-based reinsurers dominate longevity risk hedging for EU carriers seeking capital relief.
United Kingdom
London's insurance market anchors European distribution innovation for hybrid life-LTC products targeting retirement asset protection. The Prudential Regulation Authority supervises capital adequacy for carriers issuing multi-decade morbidity contracts. Edinburgh and Glasgow clusters house actuarial expertise for stochastic reserving frameworks.
India
Nuclear household formation in Maharashtra and Karnataka erodes traditional family-based elder care norms, creating first-mover opportunity for indemnity products with home health riders. The Insurance Regulatory and Development Authority of India oversees market entry for foreign carriers. Mumbai and Bangalore financial centers concentrate product development for rupee-denominated coverage targeting the uninsured middle class.
Global Long Term Care Insurance Market Competitive Environment
Global majors compete with regional champions across distribution architecture and product chassis design, producing a tiered structure where mutual insurers, stock life carriers, and specialized underwriters occupy distinct competitive positions. The market fragments across strategic archetypes: mutual structures emphasizing policyholder retention, stock carriers prioritizing hybrid product innovation, and niche specialists maintaining impaired-risk underwriting expertise. Consolidation pressure manifests through reinsurance treaty renegotiations and distribution commission compression rather than horizontal merger activity.
Within the mutual insurer archetype, New York Life exemplifies policyholder-centric governance structures that sustain above-average retention rates. Genworth and John Hancock anchor contrasting strategic positions—Genworth occupies specialized underwriting expertise in traditional stand-alone segments, while John Hancock represents wellness-integrated product design through biometric-linked premium structures. These three carriers collectively illustrate the competitive divergence between legacy morbidity specialists and digitally-enabled hybrid innovators.
| Leading Market Players |
|---|
| New York Life |
| Genworth |
| John Hancock |
| Mutual of Omaha |
| Pacific Life |
| Lincoln Financial Group |
| Nationwide |
| Prudential |
| National Guardian Life |
| Others |
Value Chain & Pricing Dynamics
Captive reinsurance arrangements in Bermuda and Cayman anchor capital efficiency for carriers issuing guaranteed renewable contracts, concentrating pricing power among firms with direct access to alternative capital pools rather than those dependent on traditional treaty markets.
Pricing Analysis
Long-duration liability reinvestment spreads feed directly into premium rate filings, compressing carrier margins when portfolio yields trail guaranteed benefit escalations. Three-tier pricing structure across premium, standard, and economy levels separates affluent buyers seeking inflation-protected lifetime benefits from middle-market purchasers accepting limited duration coverage. Pricing pressure stems from legacy policy reserve strain as carriers reinvest at compressed yields. Corporations as group sponsors exhibit lowest price sensitivity due to payroll integration and tax deductibility, while individual retail purchasers face repeated rate increase cycles that accelerate lapse risk.
Supply Chain Analysis
Freight cost pass-through from care provider networks affects claim cost reserves, particularly for carriers reimbursing institutional nursing home stays across dispersed geographic markets. Underwriting expertise concentrates in the United States, Japan, and Germany where actuarial talent pools and geriatric epidemiology research centers cluster. Morbidity data feeds from electronic health record systems and prescription history algorithms rest on interoperability standards that vary by national healthcare infrastructure. Single-source vulnerability manifests in reliance on limited reinsurance panels for impaired-risk pools. Distribution runs through independent advisors and direct digital channels that displace traditional captive agent structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion opportunities concentrate in hybrid product architectures where mortality-morbidity bundling captures premium dollars from affluent households seeking estate-integrated solutions rather than pure risk-transfer coverage.
For Market Incumbents: Extend wellness-integrated product designs through wearable data partnerships that lock in policyholder engagement and reduce claims frequency. Consolidate distribution relationships with independent advisors before digital direct channels erode commission-based acquisition economics. Defensive positioning against hybrid life-LTC innovators requires accelerated underwriting automation that matches issuance timelines of competing bundled products. For New Entrants and Emerging Players: Employer benefit consultants represent the most accessible channel partner for penetrating the corporate voluntary enrollment segment with simplified underwriting architectures. White-space targets include India's uninsured middle class where nuclear household formation erodes informal care norms, and EU markets where Solvency II longevity hedging creates structural profitability advantages. Automatic enrollment design expertise borrowed from retirement plan administration offers the strongest go-to-market differentiation against legacy opt-in models. For Investors and Strategic Acquirers: Roll-up economics work for regional mutual insurers with sticky policyholder bases because guaranteed renewable pricing creates embedded renewal revenue streams resistant to competitive displacement. Five-to-ten year viability hinges on successful legacy system migration to platforms supporting real-time data ingestion. Acquisition targets should display above-average retention rates and limited exposure to pre-2000 policy blocks with underpriced long-duration liabilities. Watch for state Long-Term Care Partnership Program expansions as inflection indicators that would accelerate private coverage substitution against Medicaid.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Product Architecture Development | Bundled mortality-morbidity pricing captures affluent households under IRC Section 7702B incentives. |
| Wearable Data Partnership Integration | Biometric-linked premium discounts align policyholder incentives with claims prevention objectives. |
| Automatic Enrollment Architecture Deployment | Payroll-integrated opt-out structures triple participation rates versus traditional opt-in models. |
| Accelerated Underwriting Automation | Electronic health record APIs compress issuance timelines from weeks to hours for direct channels. |
| Legacy System Platform Migration | Real-time data ingestion capabilities enable dynamic policy structures and care coordination services. |
Study Parameters
Bottom-up employer-sponsored enrollment modeling reconciled against top-down carrier premium tracking forms the analytical core of this study. Primary interviews with actuarial executives, group benefit administrators, reinsurance treaty underwriters, and state insurance commissioners combined with secondary validation from NAIC rate filing databases, SEC 10-K insurance segment disclosures, and Japan's Ministry of Health, Labour and Welfare statistical reports. Triangulation across these sources ensures coverage of both distribution channel economics and regulatory constraint patterns.
Input-output matrices map policyholder acquisition costs, persistency rates, and severity-weighted claim reserves across product type and customer segment dimensions. Segmentation modeling incorporates payment structure, policy feature attachment rates, and regional regulatory framework variations. CAGRs derive from stochastic reserving simulations and scenario-weighted premium growth assumptions. Forecast inputs include morbidity assumption revisions, interest rate environment projections, and wearable technology penetration curves affecting dynamic pricing adoption.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to cognitive decline incidence divergence across actuarial tables and federal automatic enrollment legislative proposals. Forecasts reflect documented assumptions regarding reinsurance market capacity and state rate stability regulation enforcement. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Insurance Third Party Administrators Market
Insurance
Asia-Pacific Family Floater Health Insurance Market
Insurance
Identity Theft Insurance Market
Insurance
Global Home Insurance Market
Insurance
Online Insurance Market
Insurance
Digital Insurance Market
Insurance
Indonesia Private Health Insurance Market
Insurance
Marine Cargo Insurance Market
Insurance
Embedded Insurance Market
Insurance
Crop Insurance Market
Insurance
Directors and Officers (Dando) Insurance Market
Insurance
Denmark Property and Casualty Insurance Market
Insurance
Africa Insurance Market
Insurance
India Health and Medical Insurance Market
Insurance
Medical Claims Processing Services Market
Insurance
Europe Road Assistance Insurance Market