
 Canada Parametric Insurance Market | 2026-2036
Canada Parametric Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Parametric Insurance Market Insights
Market Context
OSFI's Guideline B-13 on climate risk management is recalibrating the cost-of-entry calculus for parametric underwriters entering the Canadian market. Intact Financial leverages its dominant domestic distribution network to pre-position parametric riders alongside traditional crop policies. Swiss Re anchors its Canadian parametric book through proprietary weather-index modeling calibrated to Prairie growing-degree-day accumulations. Fairfax Financial competes by extending its specialty reinsurance capabilities into parametric structures for commercial property portfolios.
Technical Definition and Segment Structure
Parametric insurance in Canada constitutes a risk-transfer instrument where claim settlement triggers on objectively measurable indices—rainfall millimeters, wind speed thresholds, or temperature deviations—rather than assessed physical damage, enabling payout automation within days of index breach. Natural disaster coverage dominates product type revenue due to recurring flood and wildfire exposure across British Columbia and Alberta river basins, while flight delay parametric products exhibit the fastest growth trajectory as Canadian airlines seek operational risk offloading. Within delivery models, broker services currently occupy the largest margin pool given the complexity of index calibration, though online platforms are displacing traditional placement for standardized agricultural parametric contracts in Saskatchewan grain belts.
Regulatory Frame and Outlook
Health Canada and PMRA oversee agrochemical-linked crop protocols that indirectly shape parametric basis risk calculations, while OSFI capital adequacy rules determine reinsurer capacity deployment into Canadian parametric structures. The Canadian Sustainability Standards Board disclosure mandates are forcing agricultural lenders to demand parametric proof-of-coverage from borrowing farmers. Stakeholders must monitor whether federal disaster assistance program reforms will crowd out or complement private parametric uptake in flood-prone Quebec and Ontario watersheds.
Market Dynamics
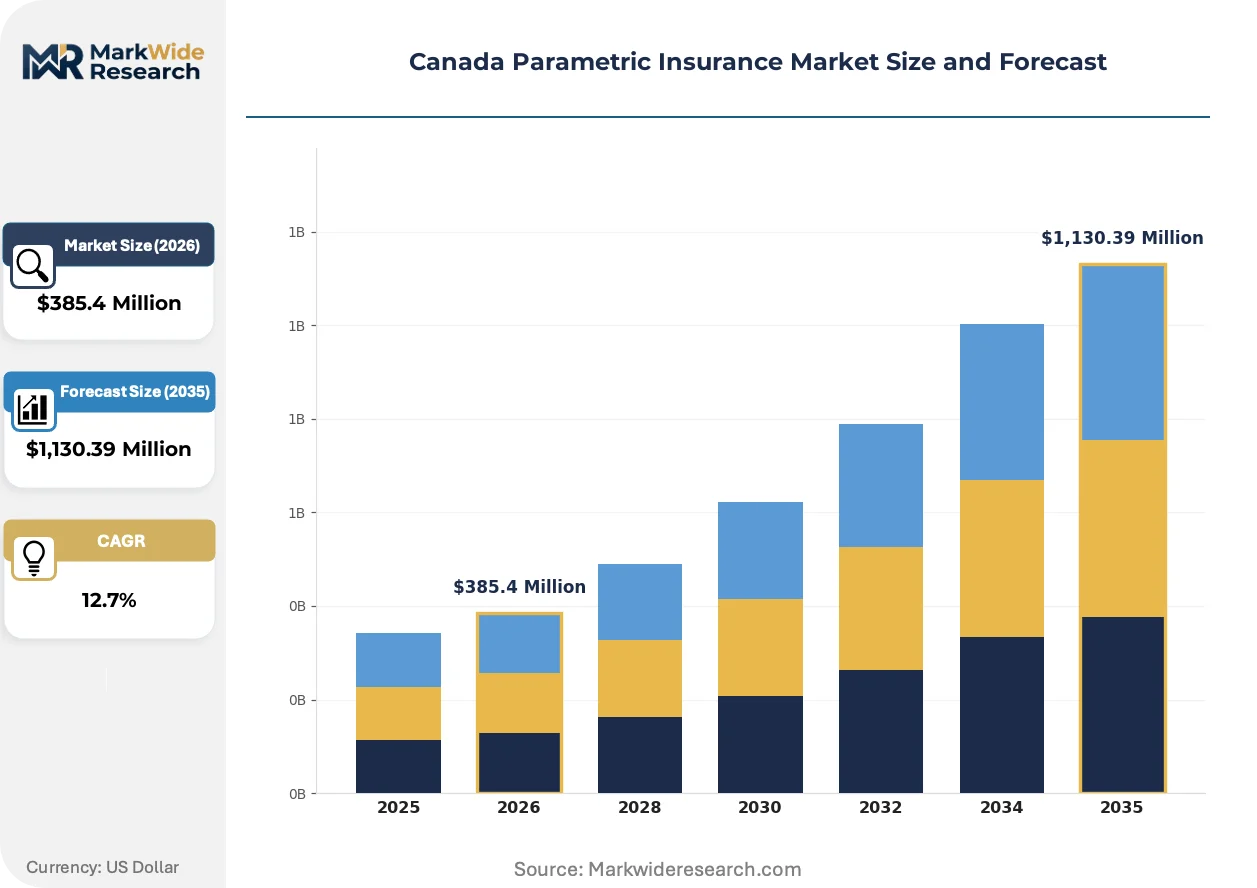
OSFI's Guideline B-13 on climate risk management is forcing Canadian insurers to embed parametric triggers into traditional underwriting workflows, compressing settlement timelines from months to days and rewiring capital allocation across Prairie agricultural portfolios.
Growth Catalysts
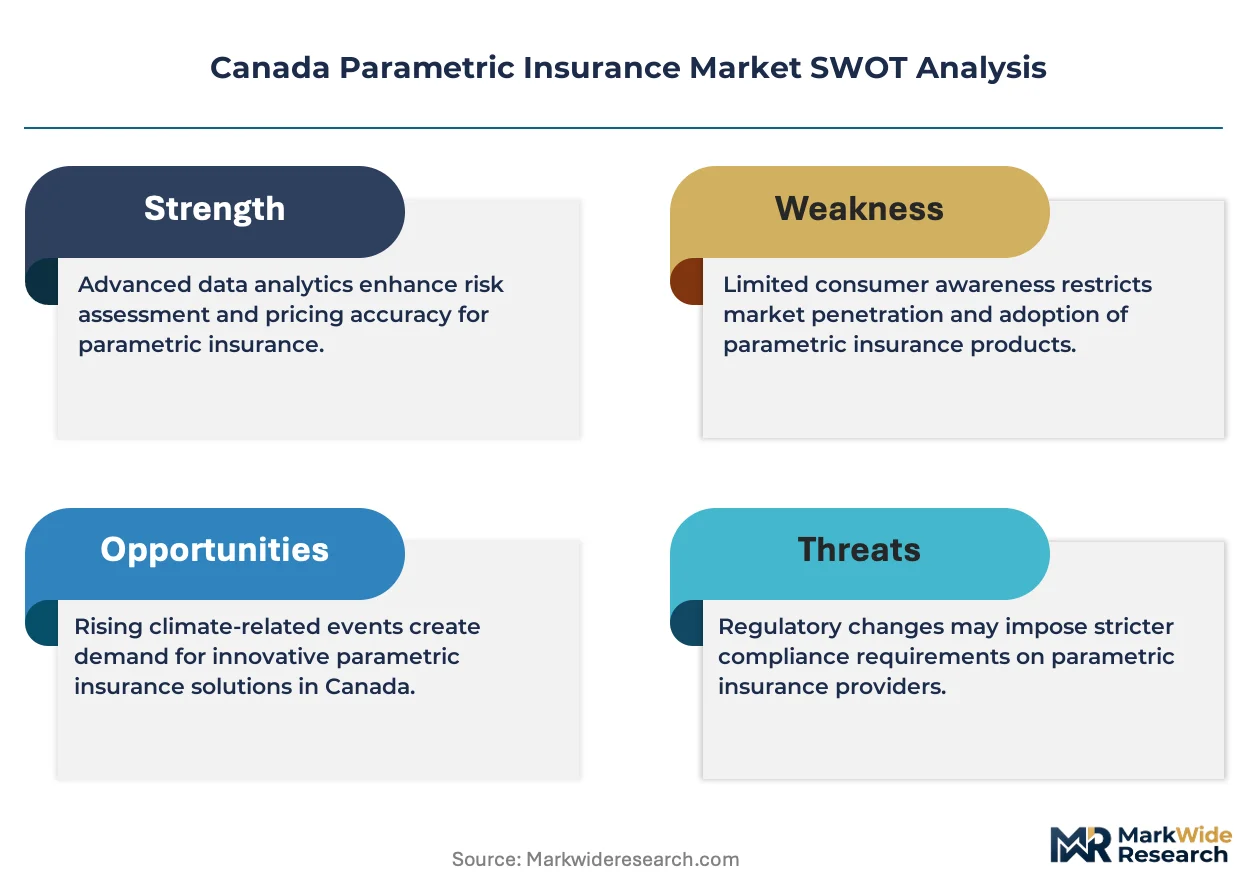
- Prairie Weather Volatility:Alberta, Saskatchewan, and Manitoba grain belts face intensifying drought-flood cycles that conventional crop insurance cannot price adequately, pushing cooperative elevators toward index-based structures.
- Canadian Sustainability Standards Board Mandates:Federal disclosure requirements for agricultural lenders now require climate risk proof-of-coverage, converting parametric policies from optional to obligatory for borrowing farmers.
- Automated Payout Infrastructure:Satellite-derived rainfall and temperature indices eliminate loss-adjustment expenses, enabling same-week settlements that preserve farm liquidity through critical growing windows.
Market Restraints
- Basis Risk Concentration:Mismatches between index triggers and actual field-level losses persist in heterogeneous Prairie soil zones, eroding farmer trust and renewal rates in Saskatchewan's Red River Valley.
- Reinsurer Capacity Limits:OSFI capital adequacy rules constrain domestic reinsurer deployment into uncorrelated parametric structures, forcing primary carriers to seek offshore backing at higher attachment points.
- Public Disaster Program Crowd-Out:Federal and provincial crop disaster assistance in Quebec and Ontario watersheds reduces willingness-to-pay for private parametric layers among risk-averse smallholders.
Strategic Opportunities
- British Columbia Wildfire Index Products:Commercial forestry operators and municipal utilities in the Interior and Coastal regions lack parametric coverage for smoke-taint and evacuation-triggered revenue losses, creating a white-space segment.
- Aviation Operational Risk:Canadian airlines face mounting pressure to offload weather-driven delay costs through parametric structures tied to tarmac time thresholds at Toronto Pearson and Vancouver International.
- Online Platform Distribution:Saskatchewan grain belt farmers are migrating to direct-to-farmer digital placement for standardized drought and excess moisture contracts, bypassing broker commissions and compressing acquisition costs.
Industry Challenges
- Index Calibration Expertise Gap:Underwriting teams lack actuarial depth in growing-degree-day modeling and satellite data validation, forcing reliance on third-party vendors and diluting margin capture.
- Legacy System Integration:Core policy administration platforms at established Canadian carriers require manual workarounds to ingest automated parametric payouts, creating operational friction and settlement delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Parametric Insurance Market |
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $1,130.39 Million |
| CAGR (2026 – 2036) | 12.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Agricultural, Flight Delay, Natural Disaster, Event Cancellation Use Case: Crop Protection, Travel Insurance, Business Interruption, Sporting Events Service Type: Customized Solutions, Off-the-Shelf Products, Advisory Services, Claims Administration Delivery Model: Direct Sales, Online Platforms, Broker Services, Hybrid |
| Companies Covered | Canada Life, Fairfax Financial, Intact Financial, Swiss Re, iA Financial, Desjardins, Sun Life, PartnerRe, Manulife, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Parametric Insurance Market Trends and Innovations
Parametric insurance in Canada is pivoting from agricultural dominance toward multi-peril commercial applications, driven by regulatory pressure for climate disclosure and advances in remote sensing granularity that compress basis risk to tolerable thresholds.
Satellite-based vegetation health indices are overtaking ground-station rainfall measurements as the preferred trigger mechanism for Prairie crop policies. Large-scale grain cooperatives in Alberta and Saskatchewan are mandating normalized difference vegetation index triggers in new placements, abandoning sparse rain-gauge networks that failed to capture field-level moisture stress during the 2021 drought cycle. This sensor transition is overtaking traditional indemnity structures in acreage terms across the Canadian grain belt.
Health Canada and PMRA oversight of agrochemical protocols is indirectly reshaping parametric basis risk calculations by altering yield-response functions to weather stress. The regulator's tightening restrictions on neonicotinoid seed treatments have increased crop vulnerability to early-season moisture deficits, forcing underwriters to recalibrate index triggers for canola and wheat policies. Prairie provincial crop insurance corporations are responding by commissioning proprietary soil-moisture models that integrate agronomic protocol changes.
Direct digital placement is displacing broker-mediated distribution for standardized agricultural parametric contracts in Saskatchewan. Farmers with contiguous acreage above five hundred hectares are bypassing traditional intermediaries to access index products through carrier-built online platforms, compressing placement cycles from weeks to forty-eight hours. This channel migration concentrates in the grain elevator corridor between Regina and Saskatoon where operational scale justifies self-service risk management.
Canada Parametric Insurance Market Segmentation
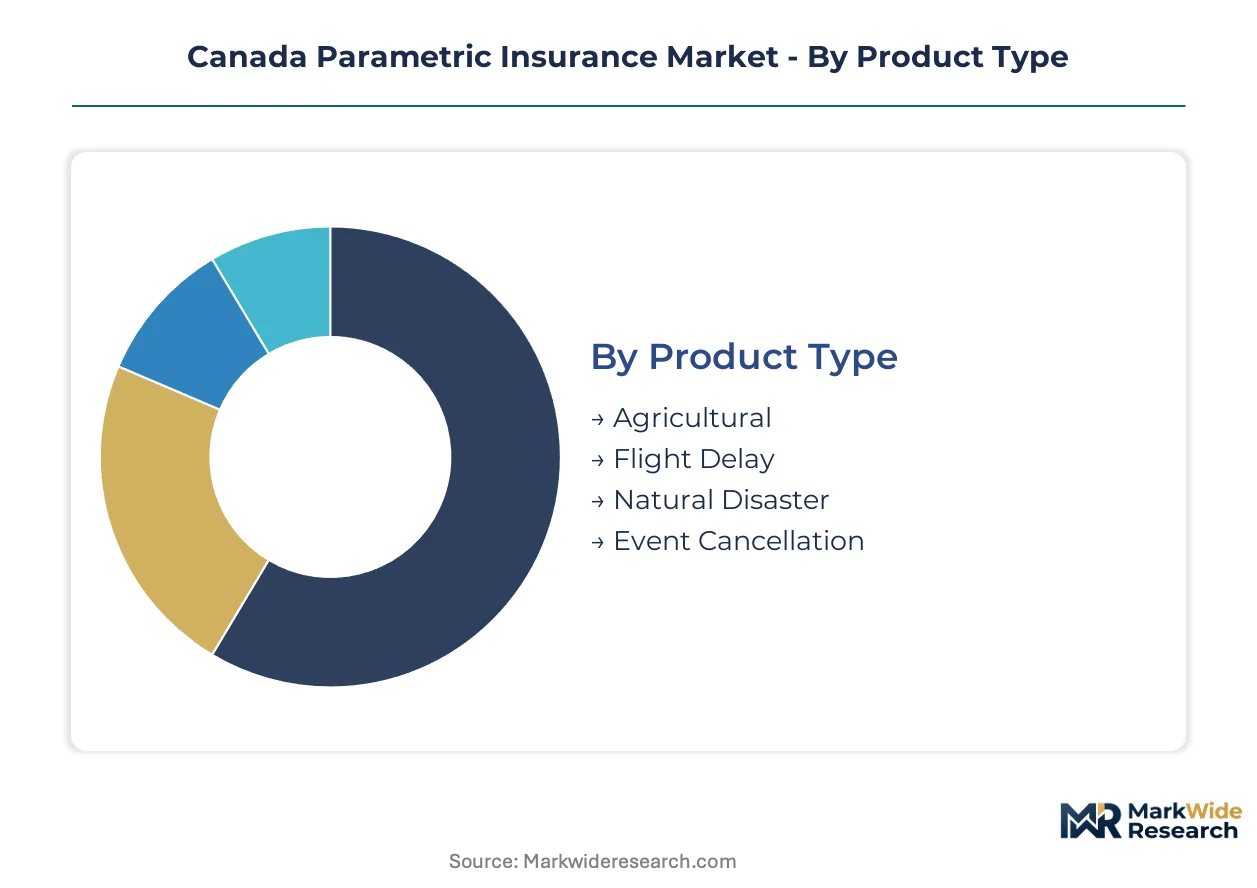
Parametric insurance in Canada fragments across product architecture, deployment context, service intensity, and channel economics. Each segmentation axis reveals distinct margin pools and capability requirements for underwriters targeting Prairie agricultural volatility or commercial property exposure.
Product Type:
Standardization dominates agricultural and natural disaster products where index triggers are widely accepted, while flight delay and event cancellation demand bespoke calibration for specific operational exposures.
- Natural Disaster:Flood and wildfire indices anchor the largest premium volume in British Columbia and Alberta river basins. Municipal utilities and commercial forestry operators in the Interior region drive placement of smoke-taint and evacuation-triggered structures.
- Agricultural:Satellite-derived growing-degree-day and vegetation health indices enable automated payouts for drought and excess moisture across Saskatchewan grain belts. Prairie cooperative elevators are mandating normalized difference vegetation index triggers following the 2021 drought cycle's rain-gauge failures.
- Flight Delay:Canadian airlines at Toronto Pearson and Vancouver International seek parametric offloading of tarmac time thresholds. Operational risk transfer for weather-driven delays requires airline-specific delay cost modeling.
- Event Cancellation:Sporting and entertainment promoters in Montreal and Calgary purchase bespoke structures for revenue protection against weather-triggered postponement.
Most installed capacity flows through Natural Disaster. Expansion is steepest in Flight Delay.
Use Case:
Volume concentrates in crop protection where federal disclosure mandates have converted parametric coverage from optional to obligatory for borrowing farmers.
- Crop Protection:Prairie grain producers face acute basis risk in heterogeneous soil zones. Saskatchewan's Red River Valley exhibits persistent mismatches between index triggers and field-level losses that erode renewal rates.
- Business Interruption:Commercial property portfolios in flood-prone Quebec and Ontario watersheds utilize parametric layers where conventional business interruption excludes climate-driven supply chain disruption.
- Travel Insurance:Flight delay parametric products attach to corporate travel policies for resource sector employees operating remote northern sites.
- Sporting Events:Outdoor tournament organizers in Alberta and British Columbia purchase precipitation and temperature threshold coverage for gate revenue protection.
Most premium volume attaches to Crop Protection. Business Interruption is gaining share fastest as OSFI climate disclosure rules force commercial portfolio reassessment.
Service Type:
Margin distribution follows complexity gradient from standardized off-the-shelf agricultural contracts to actuarially intensive customized solutions.
- Customized Solutions:Commercial forestry operators and municipal utilities require proprietary index design for wildfire smoke-taint and evacuation cost structures. Underwriting teams rely on third-party vendors for growing-degree-day modeling and satellite data validation.
- Off-the-Shelf Products:Standardized drought and excess moisture contracts for Saskatchewan grain belts migrate to direct digital placement. Farmers above five hundred contiguous hectares bypass broker intermediaries through carrier-built online platforms.
- Advisory Services:Agricultural lenders under Canadian Sustainability Standards Board mandates demand parametric proof-of-coverage consultation for borrowing farmers.
- Claims Administration:Automated payout infrastructure eliminates loss-adjustment expenses, though legacy policy administration platforms at established carriers require manual workarounds that create settlement friction.
Most revenue contribution derives from Customized Solutions. Off-the-Shelf Products are climbing the fastest as digital distribution compresses acquisition costs.
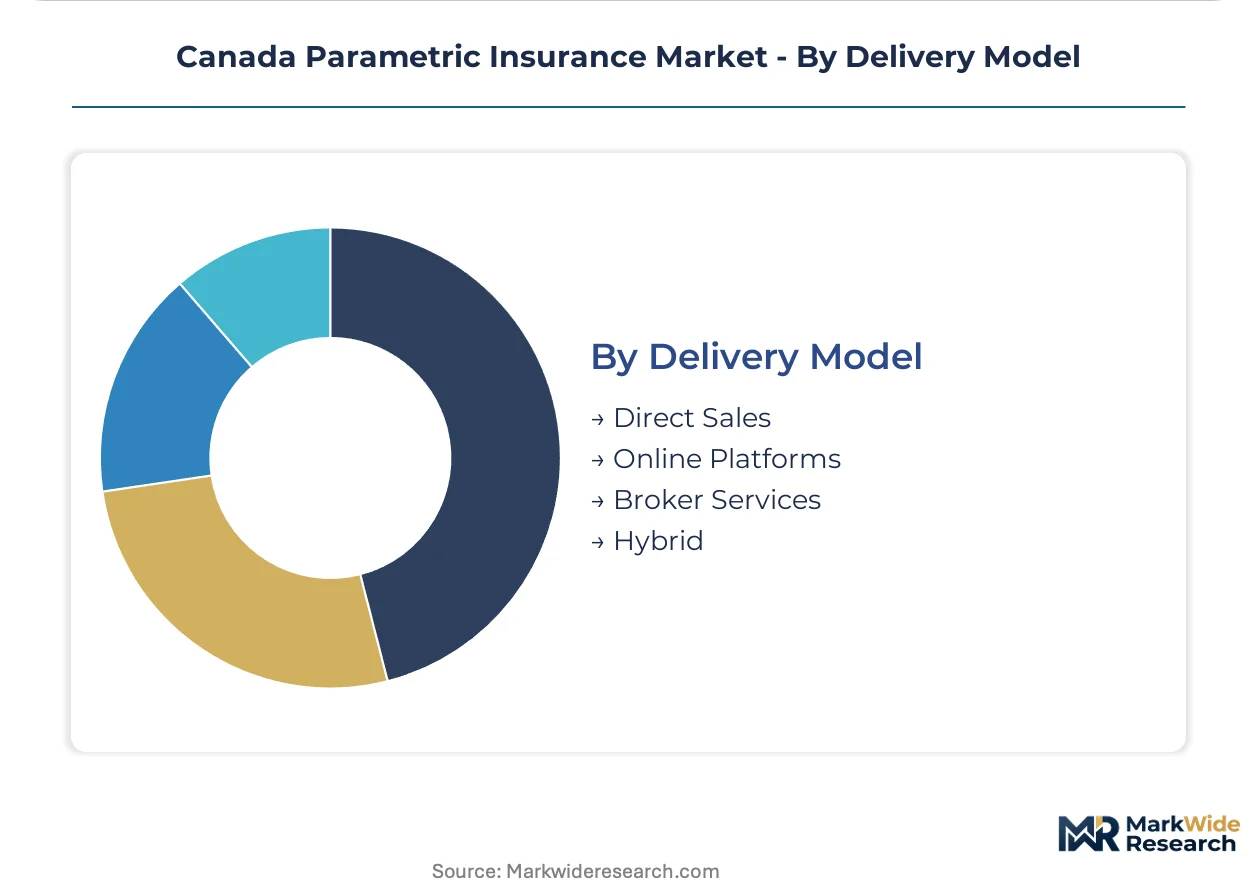
Delivery Model:
Channel economics split between high-touch broker services for complex index calibration and low-friction online platforms for standardized Prairie agricultural contracts.
- Broker Services:Complex commercial property and wildfire index products require intermediary expertise for trigger design and basis risk explanation. Broker networks capture the largest margin pool in current market structure.
- Online Platforms:Saskatchewan grain belt farmers between Regina and Saskatoon self-serve through carrier-built digital placement. Contiguous acreage scale justifies bypassing traditional intermediaries for forty-eight-hour placement cycles.
- Direct Sales:Intact Financial leverages its domestic distribution network to pre-position parametric riders alongside traditional crop policies.
- Hybrid:Large grain cooperatives in Alberta combine digital quoting with broker-assisted contract finalization for multi-location coverage.
Most policy count runs through Broker Services. Online Platforms are expanding most quickly as standardized agricultural contracts commoditize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Parametric insurance in Canada emerged from Prairie agricultural cooperatives seeking alternatives to conventional crop indemnity structures that failed during catastrophic drought cycles. The industry's geographic footprint now spans five distinct provincial markets shaped by divergent climate exposures and regulatory environments.
Prairie Provinces
Alberta, Saskatchewan, and Manitoba generate the dominant share of agricultural parametric premium as grain cooperatives mandate satellite-derived vegetation index triggers. Health Canada and PMRA oversight of neonicotinoid restrictions has recalibrated yield-response models for canola and wheat policies. The Regina-Saskatoon corridor anchors direct digital placement platforms where farmers above five hundred contiguous hectares self-serve standardized drought contracts.
Ontario
Commercial property portfolios in flood-prone watersheds drive business interruption parametric adoption as OSFI climate disclosure rules force portfolio reassessment. The Canadian Sustainability Standards Board mandates now require agricultural lenders to demand proof-of-coverage from borrowing farmers in the province's corn and soybean belts. Toronto's financial services cluster hosts the underwriting infrastructure for multi-peril commercial structures.
Quebec
Federal and provincial crop disaster assistance programs create persistent crowd-out effects that suppress private parametric willingness-to-pay among smallholders. The St. Lawrence River basin's recurring spring flood exposure nonetheless attracts municipal utility interest in index-based evacuation cost coverage. Montreal's commercial insurance broker networks specialize in bespoke trigger design for heterogeneous soil zones.
British Columbia
Commercial forestry operators and municipal utilities in the Interior and Coastal regions purchase wildfire smoke-taint and evacuation-triggered parametric products that conventional policies exclude. The province's 2021 heat dome and subsequent atmospheric river events accelerated index calibration for temperature deviation triggers. Vancouver's proximity to reinsurance markets facilitates offshore capacity placement at competitive attachment points.
Canada Parametric Insurance Market Competitive Landscape
The competitive structure tilts toward domestic incumbent carriers with established Prairie distribution networks and global reinsurers supplying offshore capacity. Tier-one domestic underwriters leverage crop policy relationships to pre-position parametric riders, while specialty reinsurers anchor capacity through proprietary weather-index modeling. Strategic moves concentrate on digital platform buildout for standardized agricultural contracts and partnerships with satellite data vendors to compress basis risk calculations.
Among domestic carriers, Intact Financial occupies a position exemplifying the integrated incumbent archetype through its dominant Prairie distribution infrastructure. Fairfax Financial represents the specialty reinsurance extension model, deploying capital into parametric structures for commercial property portfolios. Swiss Re anchors the global reinsurer tier, calibrating proprietary growing-degree-day accumulations for Prairie agricultural exposure. These three players collectively illustrate the market's tripartite structure: domestic network leverage, specialty capacity deployment, and global modeling expertise.
| Leading Market Players |
|---|
| Canada Life |
| Fairfax Financial |
| Intact Financial |
| Swiss Re |
| iA Financial |
| Desjardins |
| Sun Life |
| PartnerRe |
| Manulife |
| Others |
Pricing and Supply Chain Analysis
Canadian Sustainability Standards Board disclosure mandates gate both qualified parametric underwriter status and premium-tier pricing access for agricultural lenders demanding climate risk proof-of-coverage from borrowing farmers. Prairie grain cooperatives now treat certified index calibration as a procurement prerequisite, compressing margins for uncertified vendors while elevating pricing power for carriers with proprietary satellite validation capabilities.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels organizes the Canadian parametric market. Premium tiers attach to customized wildfire smoke-taint and evacuation cost structures for British Columbia forestry operators, while standard tiers cover Saskatchewan grain belt drought contracts with NDVI triggers. Price differentiation rests on satellite data granularity and actuarial modeling depth. Pricing pressure stems from direct digital placement platforms eliminating broker commissions. Smallholders in Quebec and Ontario exhibit highest price sensitivity due to federal disaster program crowd-out effects.
Supply Chain Analysis
Dual-sourcing requirements from Prairie agricultural lenders mandate multi-supplier qualification for satellite data vendors and third-party index calibration specialists. Supply concentrates in Canada, the United States, and Switzerland for proprietary weather-index modeling and growing-degree-day accumulation algorithms. Raw material dependencies include satellite imagery licenses, soil-moisture sensor networks, and actuarial software platforms. Single-source vulnerability runs through sparse ground-station rainfall networks in Saskatchewan's Red River Valley. Distribution runs through broker networks for complex commercial structures and carrier-built online platforms for standardized agricultural contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in Canadian parametric insurance rests on automated payout infrastructure eliminating loss-adjustment expenses and satellite-derived indices compressing basis risk calculations to tolerable thresholds.
For Market Incumbents: Deepen proprietary weather-index modeling capabilities to defend against global reinsurer displacement. Invest in direct digital platform buildout for Saskatchewan grain belt standard contracts to capture commission compression benefits. Intact Financial's dominant Prairie distribution network exemplifies channel control leverage against emerging online competitors. For New Entrants and Emerging Players: Launch via white-label partnerships with agricultural cooperatives to bypass established broker networks. Target British Columbia commercial forestry operators and municipal utilities with bespoke wildfire smoke-taint products where incumbent coverage gaps persist. Aviation operational risk at Toronto Pearson and Vancouver International represents the most penetrable segment for parametric delay cost offloading. For Investors and Strategic Acquirers: Valuations sit cheapest among satellite data validation specialists with Health Canada and PMRA protocol integration capabilities. Long-term viability centers on carriers bridging automated payout infrastructure with legacy policy administration platform compatibility. Watch OSFI capital adequacy rule reforms as the inflection signal for domestic reinsurer capacity deployment into uncorrelated parametric structures.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Index Calibration Investment | Swiss Re's growing-degree-day modeling anchors Prairie agricultural premium capture against commoditized competitors. |
| Direct Digital Platform Launch | Saskatchewan grain belt farmers self-serve through carrier-built interfaces, compressing forty-eight-hour placement cycles. |
| Wildfire Smoke-Taint Product Development | British Columbia commercial forestry operators lack parametric coverage for evacuation-triggered revenue losses. |
| Aviation Delay Cost Parametric Structure | Canadian airlines at Toronto Pearson seek operational risk offloading through tarmac time threshold triggers. |
| Legacy System Integration Partnership | Established carriers require manual workarounds for automated payouts, creating operational friction and settlement delays. |
Research Methodology
Coverage spans Prairie provinces, British Columbia, Ontario, and Quebec, with primary inputs from each regional market. The analysis combines primary interviews with agricultural cooperative risk managers, grain elevator operators, commercial forestry procurement leads, municipal utility planning officers, and airline operational risk directors with secondary validation. Secondary sources include OSFI regulatory filings, Canadian Sustainability Standards Board disclosure protocols, Health Canada and PMRA agrochemical oversight documents, and Prairie provincial crop insurance corporation annual reports. Bottom-up policy count triangulation with top-down premium volume estimates ensures cross-verified outputs.
Granularity-level modeling disaggregates projections across product type, use case, service intensity, and delivery channel dimensions. The analytical framework incorporates agricultural acreage exposure, commercial property portfolio concentration, and aviation passenger volume as industry-specific demand drivers. CAGRs derive from segment-level growth rate blending across the projection horizon. Satellite data vendor capacity, reinsurer attachment point availability, and regulatory mandate implementation timelines feed directly into forecast sensitivity.
Forecast precision tightens around the base case; tail outcomes carry wider variance under federal disaster assistance program reform scenarios or OSFI capital adequacy rule tightening. Forecasts reflect documented assumptions regarding Prairie weather volatility persistence and satellite index validation accuracy. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
United Kingdom Parametric Insurance Market
Insurance
Global Long Term Care Insurance Market
Insurance
France Liability Insurance Market
Insurance
Horse Insurance Market
Insurance
Internet of Things Insurance Market
Insurance
New Zealand Property and Casualty Insurance Market
Insurance
Marine Crew Insurance Market
Insurance
Asia-Pacific Critical Illness Insurance Market
Insurance
India Property & Casualty Insurance Market
Insurance
US Extended Warranty Market
Insurance
Agriculture Reinsurance Market
Insurance
Green Insurance Market
Insurance
China Liability Insurance Market
Insurance
United Kingdom Health and Medical Insurance Market
Insurance
South Korea Liability Insurance Market
Insurance
Income Protection Insurance Market