
 Russia Life and Non-Life Insurance Market | 2026-2036
Russia Life and Non-Life Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Life and Non-Life Insurance Market Analytics
Multi-channel distribution is restructuring how Russian insurers reach policyholders across vast territory. Sberbank Life Insurance leverages its banking network to embed products in retail and corporate accounts. Ingosstrakh anchors the non-life segment with industrial and property coverage for energy and infrastructure clients. VTB Insurance competes through bancassurance integration with state-backed lending platforms.
Russia Life and Non-Life Insurance encompasses risk transfer contracts where insurers collect premiums to cover mortality, morbidity, property damage, and liability exposures under defined policy terms and sum-assured limits. The primary purpose centers on financial protection for households and enterprises against contingent losses that would otherwise disrupt solvency or operations. Life Insurance and Health Insurance draw structural attention as aging demographics elevate mortality-linked savings products and state healthcare gaps drive supplemental medical coverage. Property Insurance and Auto Insurance retain mature premium bases tied to mandatory motor third-party liability and commercial real estate lending requirements.
The Central Bank of Russia sets prudential norms for insurer solvency and reserve adequacy, while mandatory motor insurance regulations enforce minimum coverage thresholds nationwide. These frameworks shape product design, pricing freedom, and market entry conditions for domestic and foreign-capital participants. Stakeholders must monitor regulatory capital reforms and digital distribution licensing as determinants of competitive viability and portfolio growth trajectory.
Market Dynamics
Central Bank of Russia solvency reforms are compressing insurer capital structures while simultaneously opening distribution pathways through embedded banking partnerships and telematics-enabled auto products.
Growth Catalysts
- Mandatory Motor Third-Party Liability:Federal law compels vehicle registration contingent upon valid coverage, sustaining baseline premium flow across all 85 federal subjects regardless of economic cycle.
- Bancassurance Channel Expansion:State banking networks embed life and property products within mortgage and corporate lending workflows, capturing policyholders at point of financial decision.
- Telematics Integration:Usage-based auto insurance platforms calculate premiums from real-time driving behavior data, attracting younger policyholders with personalized pricing.
Market Restraints
- Capital Adequacy Ratios:Central Bank of Russia prudential norms require higher risk-adjusted reserves, constraining smaller insurers' capacity to underwrite large commercial risks.
- Reinsurance Capacity Concentration:International sanctions limit access to London and European reinsurance markets, forcing domestic carriers to retain catastrophic exposure or seek alternative retrocession.
- Low Interest Rate Environment:Central bank policy rates compress investment yields on insurer bond portfolios, squeezing profitability on long-duration life liabilities.
Strategic Opportunities
- Cyber Liability Underwriting:Corporate demand for data breach and business interruption coverage outpaces supply, creating premium growth in mid-market segments.
- Siberian and Far Eastern Expansion:Underpenetrated regions beyond the Urals present whitespace for digital-first distribution models bypassing physical branch infrastructure.
- Supplemental Health Microinsurance:Gaps in state compulsory medical insurance coverage enable short-term hospitalization and critical illness riders sold through mobile platforms.
Industry Challenges
- Actuarial Talent Scarcity:Shortage of professionals proficient in both Russian regulatory reporting and international reserving standards complicates product development timelines.
- Legacy System Integration:Core policy administration platforms from the 1990s resist API connectivity with modern distribution partners, delaying real-time quoting capabilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Life and Non-Life Insurance Market |
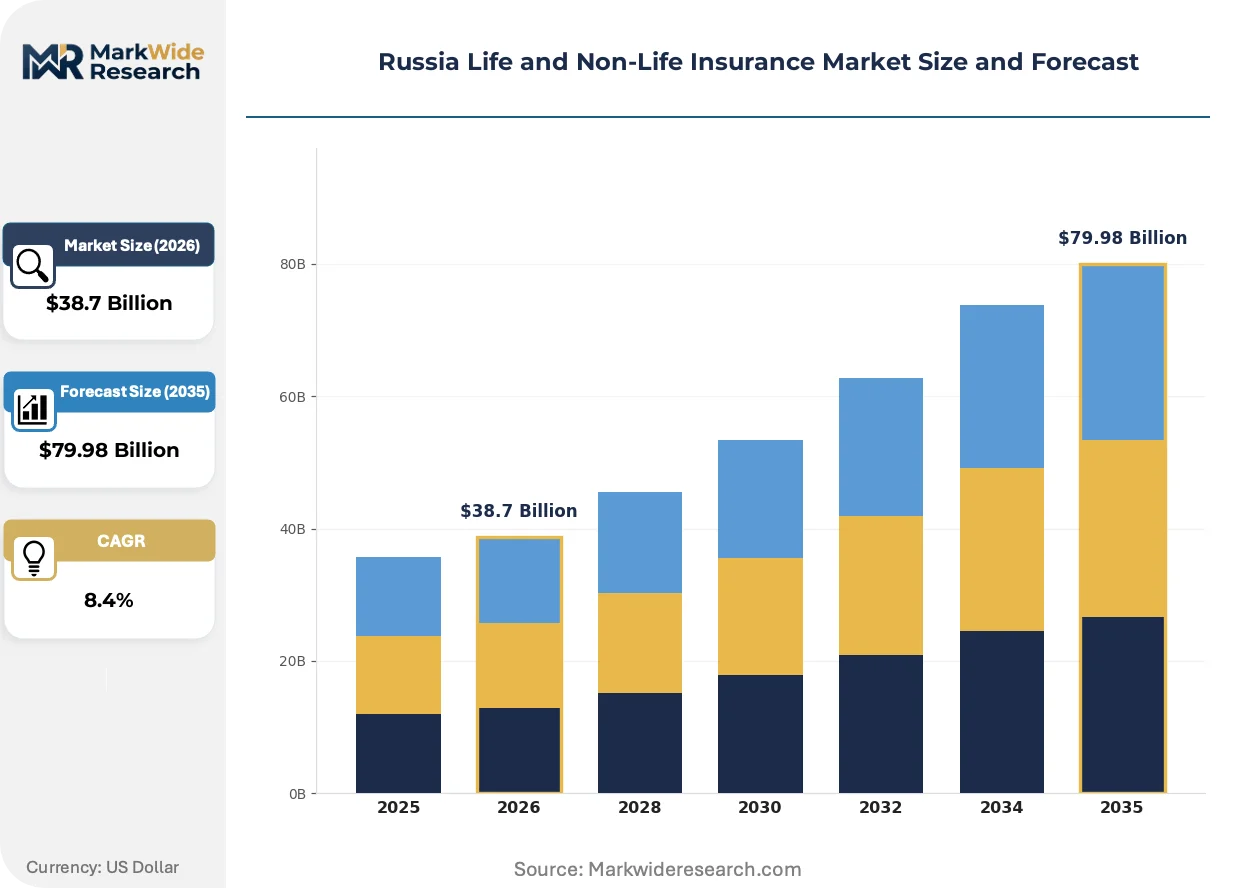
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Insurance Type: Life Insurance, Health Insurance, Property Insurance, Auto Insurance Product Category: Term Life, Whole Life, Critical Illness, Travel Insurance Distribution Channel: Online, Brokers, Agents, Direct Sales Client Type: Individual, Small Business, Corporate, Government |
| Companies Covered | Ingosstrakh, Rosgosstrakh, Sogaz, Renaissance Insurance, VSK, Sberbank Life Insurance, RESO-Garantia, VTB Insurance, AlfaStrakhovanie, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Life and Non-Life Insurance Market Evolving Landscape
Digital distribution infrastructure and regulatory data mandates are restructuring how Russian insurers acquire customers, price risk, and manage claims workflows across geographically dispersed markets.
Artificial intelligence is automating claims assessment for auto physical damage and property lines. Major carriers deploy computer vision algorithms to evaluate photographic evidence from policyholder smartphones, reducing loss adjuster dispatch requirements. This compression of claims cycle time is automating cost structures while improving customer retention metrics.
Central Bank of Russia mandatory financial reporting standards now require granular disclosure of investment portfolio concentration and reinsurance counterparty exposure. Insurers must restructure asset allocations and retrocession arrangements to maintain compliance. The property and casualty segment bears the heaviest adaptation burden as catastrophe reserves face stricter stress-testing protocols.
Corporate risk managers now unbundle insurance procurement from bundled broker relationships, conducting direct competitive tenders for specific coverage lines. Large industrial policyholders in the energy sector solicit separate proposals for property damage, business interruption, and environmental liability rather than accepting packaged programs. This disintermediation pressure concentrates in Moscow where headquarters procurement functions maintain specialized risk financing expertise.
Russia Life and Non-Life Insurance Market Segmentation
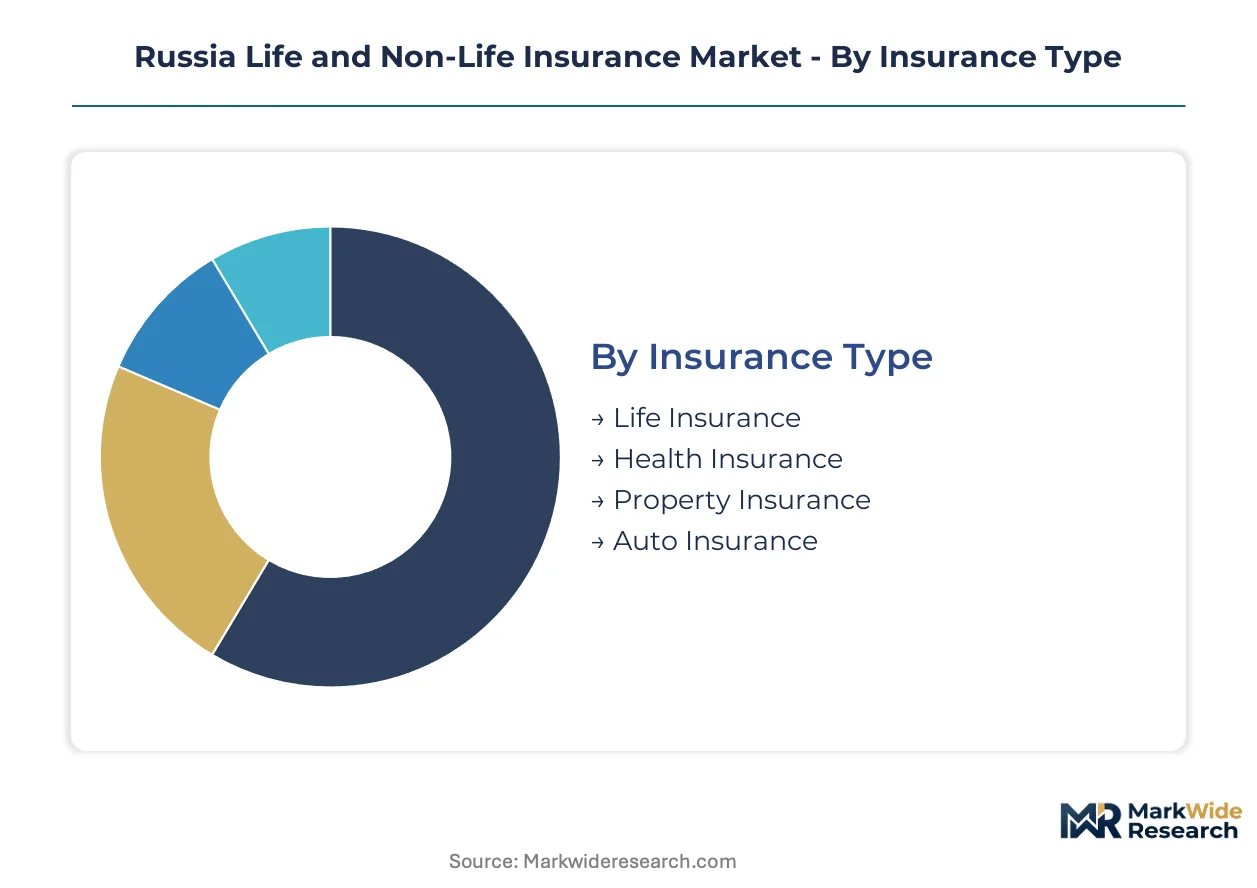
Segmentation in Russian insurance reveals divergent growth trajectories across product lines and channel economics. Life and health products command premium pricing and longer policy durations, while property and auto lines operate on volume-driven renewal cycles shaped by regulatory mandates.
Insurance Type:
Life Insurance and Property Insurance split premium volume roughly evenly, though capital intensity and reserve requirements differ substantially.
- Life Insurance:Long-duration mortality and savings contracts with substantial reserve backing requirements. Moscow and Saint Petersburg households concentrate demand for endowment-linked products as wealth preservation instruments amid currency volatility.
- Health Insurance:Supplemental medical coverage filling gaps in state compulsory medical insurance. Corporate clients in extractive industries drive voluntary medical insurance uptake to attract talent in remote locations.
- Property Insurance:Commercial real estate and industrial asset coverage tied to lending covenants. Energy infrastructure in the Volga and Ural regions generates catastrophic exposure requiring domestic reinsurance retention.
- Auto Insurance:Mandatory motor third-party liability dominates volume, with comprehensive coverage concentrated in new vehicle financing. Telematics adoption is climbing fastest in this segment.
Mature deployment sits with Auto Insurance. Newer deployment is concentrated in Health Insurance.
Product Category:
Cost tier stratification separates mass-market term products from investment-linked whole life and specialized critical illness riders.
- Term Life:Pure mortality protection with no cash value accumulation. Younger policyholders in urban centers select these for mortgage protection during peak earning years.
- Whole Life:Permanent coverage with guaranteed cash value growth and participating dividends. High-net-worth individuals utilize these for estate liquidity and generational wealth transfer.
- Critical Illness:Lump-sum payout upon diagnosis of specified conditions. Employer-sponsored group policies in manufacturing and logistics sectors are expanding fastest.
- Travel Insurance:Short-duration medical and trip cancellation coverage. Cross-border restrictions have compressed this segment, though domestic tourism substitution is emerging.
Whole Life commands the highest margins per policy. Critical Illness is expanding most quickly among employer-paid benefits.
Distribution Channel:
Customer type determines channel selection, with corporate procurement favoring broker relationships and retail gravitating toward embedded banking and digital platforms.
- Online:Direct-to-consumer platforms with instant quoting and policy issuance. Smartphone penetration in cities beyond one million residents is driving self-service adoption.
- Brokers:Independent intermediaries handling complex commercial risks and coverage unbundling. Large industrial accounts in the energy sector rely on specialized broker expertise for international placement.
- Agents:Tied representatives with exclusive or preferred carrier relationships. Rural and small-town markets depend on agent networks for trust-based policy sales.
- Direct Sales:Carrier-employed sales forces and call center operations. Sberbank and VTB leverage branch staff for bancassurance product attachment.
Brokers retain the highest value per transaction. Online channels are gaining share fastest among policyholders under 35.
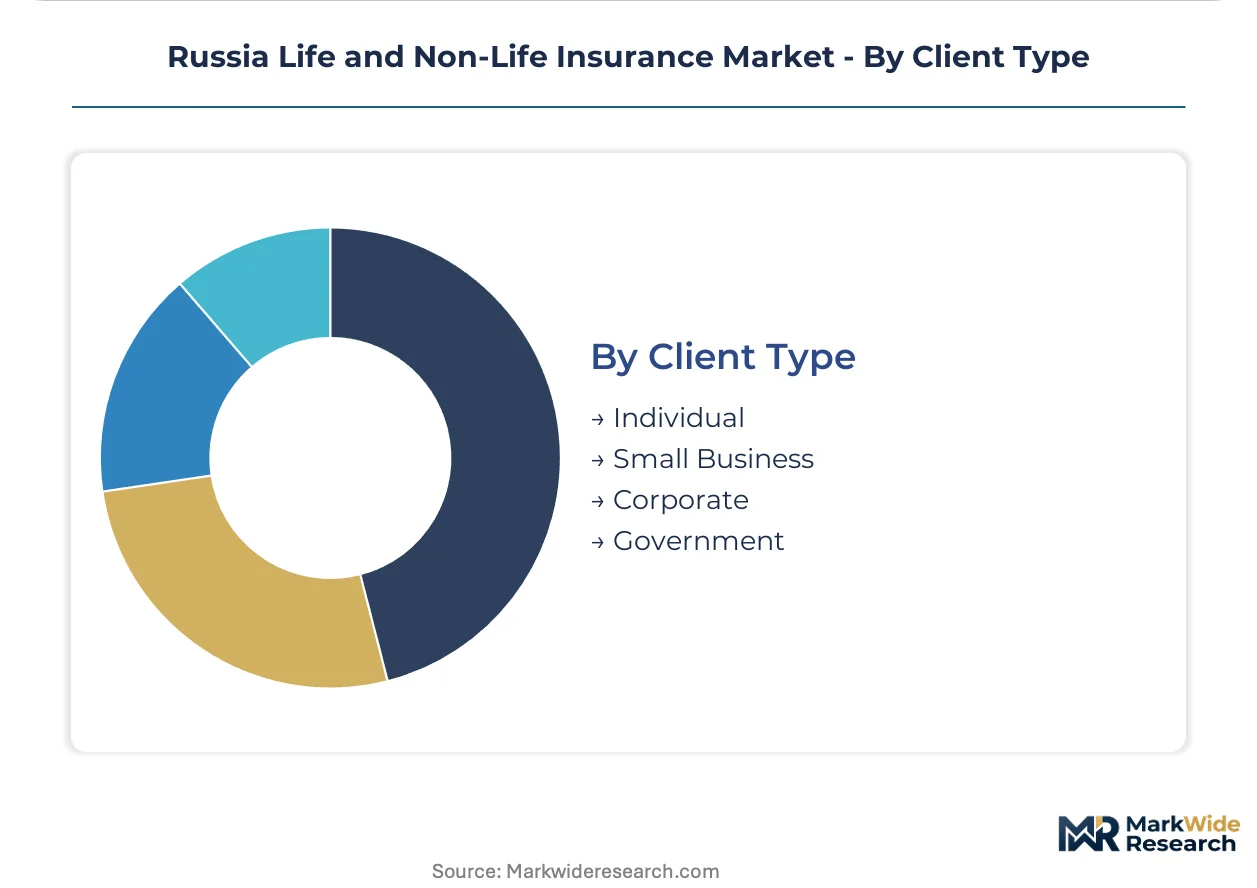
Client Type:
Geography and policy complexity separate individual retail from institutional procurement with divergent servicing economics.
- Individual:Household purchasers of life, health, and personal lines coverage. Premium collection concentrates in Moscow, Saint Petersburg, and Yekaterinburg metropolitan areas.
- Small Business:Microenterprises and sole proprietors with bundled property and liability needs. Regulatory simplification for small firm registration is expanding the addressable base.
- Corporate:Large enterprises with dedicated risk managers and captive insurance considerations. Centralized procurement functions in Moscow headquarters manage multi-line programs.
- Government:State-owned enterprises and municipal entities with specialized coverage requirements. Public procurement rules mandate competitive tendering for insurance services.
Corporate clients generate the highest premium per relationship. Small Business represents the steepest expansion trajectory as formalization increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crude oil and natural gas extraction in Western Siberia anchors the economic geography underwriting Russia's insurance demand. Corporate risk concentration follows hydrocarbon infrastructure placement across federal districts. Premium generation clusters where state-owned energy majors maintain operational headquarters.
Central Federal District
Moscow hosts the headquarters of Sberbank Life Insurance and VTB Insurance, concentrating bancassurance distribution capacity. The Central Bank of Russia maintains its regulatory headquarters here, shaping solvency compliance timelines for nationwide carriers. Moscow's corporate procurement functions manage multi-line programs for energy and metals clients.
Northwestern Federal District
Saint Petersburg anchors maritime cargo and hull underwriting for Baltic Sea port operations. The city's industrial risk managers source property coverage for shipbuilding and machinery manufacturing clusters. Northwestern premiums reflect cross-border trade exposure to European markets.
Volga Federal District
Automotive manufacturing in Tolyatti and Nizhny Novgorod drives group health and property insurance placement. The region's chemical and petrochemical complexes generate liability coverage demand. Local insurers compete for industrial accounts through specialized risk engineering services.
Ural Federal District
Yekaterinburg concentrates mining and metals industry risk management functions. The district's heavy machinery manufacturers require equipment breakdown and business interruption coverage. Regional carriers retain catastrophic exposure given limited reinsurance alternatives.
Siberian Federal District
Novosibirsk serves as the distribution hub for digital-first insurance platforms targeting underpenetrated populations. The region's sparse branch infrastructure favors mobile-based policy issuance. Telemedicine-linked health products gain traction among remote corporate workforces.
Russia Life and Non-Life Insurance Market Competitive Landscape
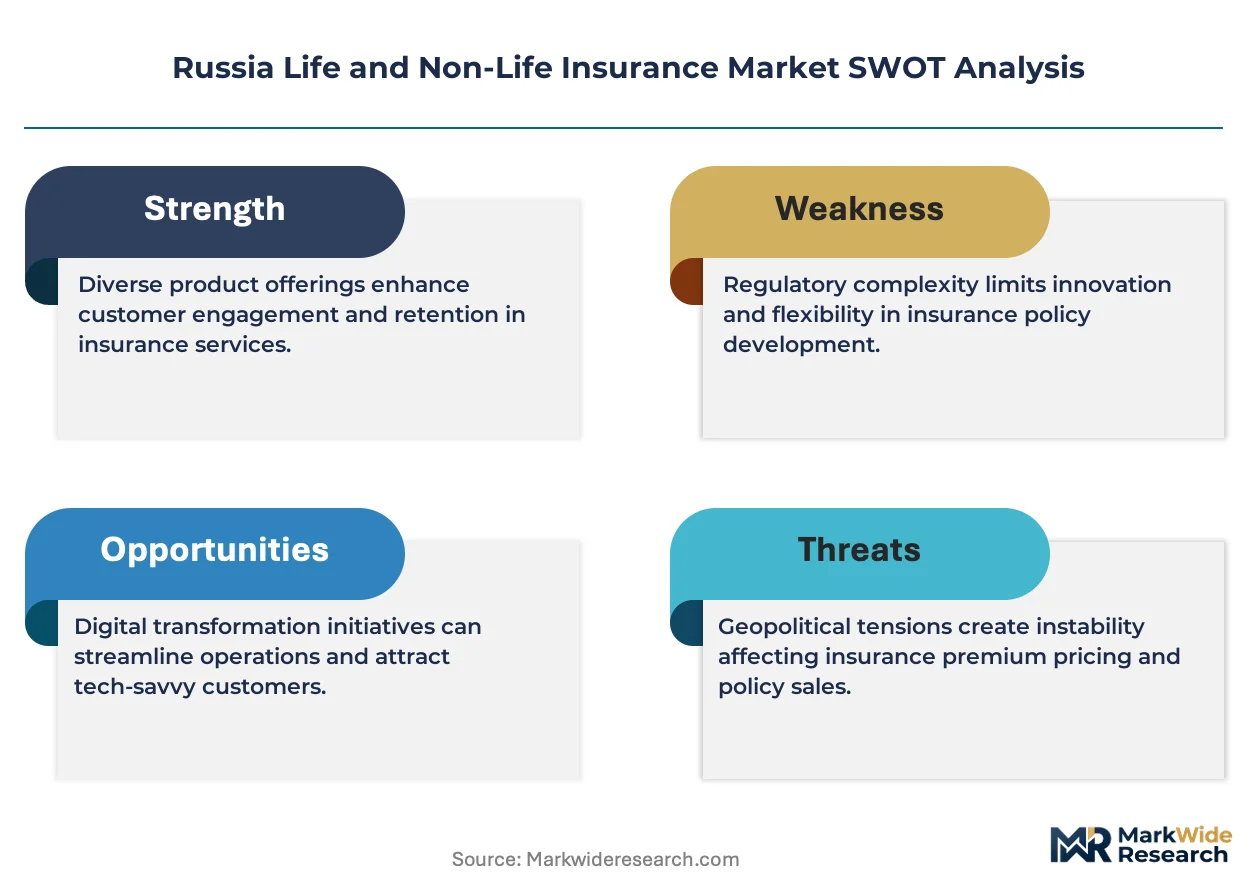
Strategic partnerships with state banking networks dominate the current landscape as carriers embed products within lending workflows. The market structure concentrates around ten major groups controlling premium volume, with tiered differentiation between bancassurance-integrated players and independent commercial lines specialists. Three archetypes prevail: state-backed banking subsidiaries, legacy mutual insurers with industrial expertise, and digitally native direct writers. Competitive intensity manifests through exclusive distribution agreements and telematics-enabled pricing models.
Among state banking-integrated carriers, Sberbank Life Insurance and VTB Insurance exemplify the bancassurance archetype through branch-embedded product distribution. Ingosstrakh occupies a position representing legacy industrial underwriting specialization. These three anchors illustrate how competitive positioning splits between financial conglomerate leverage and technical risk expertise.
| Leading Market Players |
|---|
| Ingosstrakh |
| Rosgosstrakh |
| Sogaz |
| Renaissance Insurance |
| VSK |
| Sberbank Life Insurance |
| RESO-Garantia |
| VTB Insurance |
| AlfaStrakhovanie |
| Others |
Value Network & Pricing Analysis
Corporate risk managers in Moscow and Saint Petersburg concentrate procurement authority, enabling direct competitive tenders that compress brokerage margins and unbundle historically packaged coverage lines. This buyer concentration shifts pricing power toward large industrial policyholders while fragmenting premium pools for mid-market carriers.
Pricing Analysis
Warranty-style service bundling separates premium offerings from stripped-down coverage, with Sberbank and VTB embedding insurance within lending covenants as value-added attachments. Three-tier pricing structure across premium, standard, and economy levels reflects capital adequacy tiering under Central Bank of Russia solvency norms, with smaller insurers priced out of catastrophic commercial risks. Pricing pressure stems from low central bank policy rates compressing investment yields on long-duration life reserves. Small business segments exhibit highest price sensitivity, while energy majors with captive risk management functions negotiate least.
Supply Chain Analysis
Actuarial workforce scarcity in Moscow and Yekaterinburg constrains product development velocity for domestic carriers adapting to international reserving standards. Supply concentrates in Russia's domestic reinsurance pool and residual international retrocession channels in China and India, with limited London market access due to sanctions exposure. Catastrophe modeling software and telematics hardware feed from Western technology vendors facing export restrictions. Single-source vulnerability sits with proprietary risk engines licensed from offshore providers. Distribution runs through state banking networks and independent broker relationships serving corporate procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Domestic reinsurance retention capacity acts as the binding constraint propping premium pricing for catastrophic commercial lines, with international sanctions limiting alternative retrocession pathways.
For Market Incumbents: Anchor solvency compliance through accelerated reserve adequacy builds ahead of Central Bank of Russia stress-testing deadlines. Deepen bancassurance exclusivity with VTB and Sberbank lending platforms to lock out competing distribution access. Defend against disintermediation by corporate risk managers through specialized risk engineering services for energy sector accounts. For New Entrants and Emerging Players: Launch via mobile-first distribution targeting Siberian and Far Eastern federal districts where physical branch infrastructure remains sparse. White-space opportunity concentrates in supplemental health microinsurance for remote corporate workforces and telematics-enabled auto products for younger policyholders in cities beyond one million residents. Partner with regional telecom operators for customer acquisition cost efficiency. For Investors and Strategic Acquirers: The window for entry favors digitally native direct writers with API-native core systems bypassing legacy platform migration costs. Long-term viability hinges on regulatory capital reform implementation pace and reinsurance market reopening trajectory. Acquisition target archetype: mid-tier carriers with established broker relationships but aging policy administration infrastructure. Monitor Central Bank of Russia digital distribution licensing thresholds as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Telematics Platform Integration | VTB Insurance and Sberbank Life Insurance deploy usage-based auto pricing to capture younger policyholder segments. |
| Reinsurance Pool Expansion | Domestic carriers strengthen catastrophic retention capacity through National Reinsurance Company participation. |
| Cyber Liability Product Launch | Mid-market corporate demand for data breach coverage outpaces supply from established commercial lines specialists. |
| Siberian Digital Distribution Buildout | Novosibirsk-based platforms bypass physical infrastructure constraints in underpenetrated Far Eastern markets. |
| Actuarial Talent Acquisition Program | Carriers recruit professionals proficient in both Russian regulatory reporting and international Solvency II standards. |
Research Methodology
Central Bank of Russia regulatory filings, insurer solvency disclosures, and federal statistical agency premium data formed the secondary backbone of this analysis. Primary interviews with chief risk officers at national carriers, corporate insurance procurement managers at energy majors, independent broker principals, and actuarial consultants validated quantitative assumptions. Triangulation across bottom-up policy count estimates and top-down premium aggregation reconciled segmentation outputs.
Historical trendline analysis of premium volume by federal district and product line established baseline growth patterns across the analysis window. Segmentation modeling incorporated insurance type, distribution channel, client archetype, and regional regulatory cluster dimensions. CAGRs derived from regression analysis of macroeconomic drivers including hydrocarbon export revenues, central bank policy rates, and vehicle registration volumes.
Sanctions regime evolution, reinsurance market access restoration, and capital adequacy ratio recalibration are the dominant revision risks to forecast outputs. Material deviation in named triggers warrants pause and re-evaluation of premium growth and competitive positioning assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Life and Non Life Insurance
Ireland Life and Non-Life Insurance Market
Life and Non Life Insurance
Germany Life and Non-Life Insurance Market
Life and Non Life Insurance
Czech Republic Life & Non-Life Insurance Market
Life and Non Life Insurance
Austria Life and Non-Life Insurance Market
Life and Non Life Insurance
Singapore Life and Non-Life Insurance Market
Life and Non Life Insurance
Indonesia Life and Non-Life Insurance Market
Life and Non Life Insurance
Life Insurance Policy Administration System Market
Life and Non Life Insurance
North America Business Income Insurance Market
Life and Non Life Insurance
Spain Life & Non-Life Insurance Market
Life and Non Life Insurance
Colombia Life and Non-Life Insurance Market
Life and Non Life Insurance
Global Life and Non-Life Insurance Market
Life and Non Life Insurance
China Life and Non-Life Insurance Market
Life and Non Life Insurance
Australia Life and Non-Life Insurance Market
Life and Non Life Insurance
France Life and Non-Life Insurance Market
Life and Non Life Insurance
Group Life Insurance Market
Life and Non Life Insurance
Peru Life and Non-Life Insurance Market