
 UK Travel Insurance Market | 2026-2036
UK Travel Insurance Market Size, Share, and Industry Trends Forecast 2026-2036
UK Travel Insurance Market Outlook
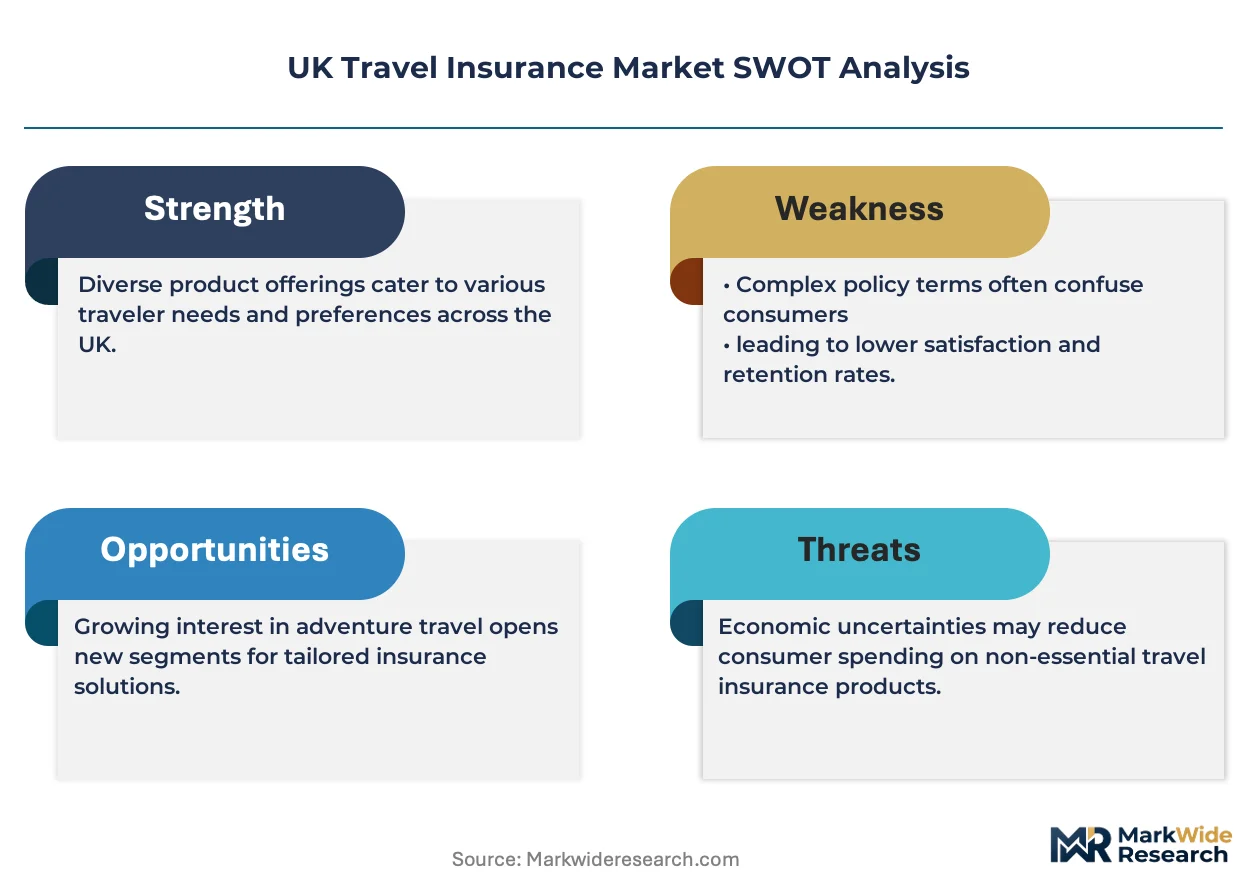
Multi-source distribution is realigning how UK travel insurance reaches end buyers. Aviva Plc leverages its direct-to-consumer digital platform to capture price-sensitive holiday bookers. Admiral Group anchors its position through bundled motor-travel cross-sell propositions. Saga PLC specializes in age-banded medical underwriting for the over-fifties segment, a demographic with rising trip frequency and higher per-policy premiums.
Travel insurance constitutes a short-term risk-transfer contract indemnifying policyholders against trip-related financial losses including medical evacuation, cancellation penalties, and personal liability abroad. Policies typically specify territorial scope through geographical zones, maximum trip durations, and pre-existing condition disclosure windows to determine claims validity. Medical expenses coverage dominates premium pools due to NHS non-reciprocal treatment costs in non-EEA destinations. Annual multi-trip policies represent the fastest-growing policy duration segment as frequent flyers seek convenience and per-trip cost reduction. Online aggregators now control price discovery, compressing front-book commissions while shifting margin to ancillary upsells and post-sale adjustment fees.
The Financial Conduct Authority's consumer duty framework requires insurers to demonstrate fair value across product lines, with particular scrutiny of add-on pricing transparency. The Prudential Regulation Authority supervises solvency adequacy for underwriters backing travel liabilities, especially where pandemic-era claims reserves proved deficient. Stakeholders must monitor how the FCA's ongoing travel insurance market study reshapes renewal practices and exclusion clarity standards.
Market Dynamics
The Financial Conduct Authority's consumer duty framework is compressing margin structures across UK travel insurance distribution channels. Underwriters now face mandatory fair value demonstrations that reshape product design, pricing transparency, and renewal practices throughout the value chain.
Growth Catalysts
- FCA Consumer Duty:The Financial Conduct Authority's fair value requirements are accelerating product simplification and disclosure standardization across annual multi-trip and single-trip policy lines.
- Post-pandemic leisure normalization:British holidaymakers are renewing coverage at elevated medical limits for extended European trips, particularly among the over-fifties demographic with higher per-policy premiums.
- Digital distribution infrastructure:Online aggregators and direct-to-consumer platforms are capturing price-sensitive bookers through real-time quote comparison and instant policy issuance.
Market Restraints
- Medical cost inflation in non-EEA destinations:NHS non-reciprocal treatment costs in the United States, Switzerland, and Caribbean jurisdictions are inflating claims severity and reserve requirements.
- Pandemic-era reserve deficiencies:Underwriters that underestimated trip cancellation frequency and repatriation volume during 2020-2021 face elevated capital charges from the Prudential Regulation Authority.
- Commission compression on front-book business:Price comparison websites are squeezing distributor margins to single-digit percentages, forcing reliance on ancillary upsells and adjustment fees.
Strategic Opportunities
- Embedded insurance partnerships:Airlines, cruise operators, and accommodation platforms in the UK are integrating travel coverage at point-of-booking, capturing customers before aggregator search behavior initiates.
- Age-banded medical underwriting:Specialized propositions for the over-seventies segment address unmet demand for extended trip durations and pre-existing condition coverage in Spain, Portugal, and Greek island destinations.
- Annual multi-trip policy expansion:Frequent flyers seeking convenience and per-trip cost reduction represent an underpenetrated conversion opportunity from single-trip purchasers.
Industry Challenges
- Pre-existing condition disclosure verification:Underwriters struggle to validate medical history windows at point-of-sale, creating claims disputes and regulatory scrutiny from the Financial Ombudsman Service.
- Legacy policy administration system integration:Incumbent insurers face technical debt when connecting traditional underwriting engines to real-time digital distribution APIs and aggregator quote feeds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Travel Insurance Market |
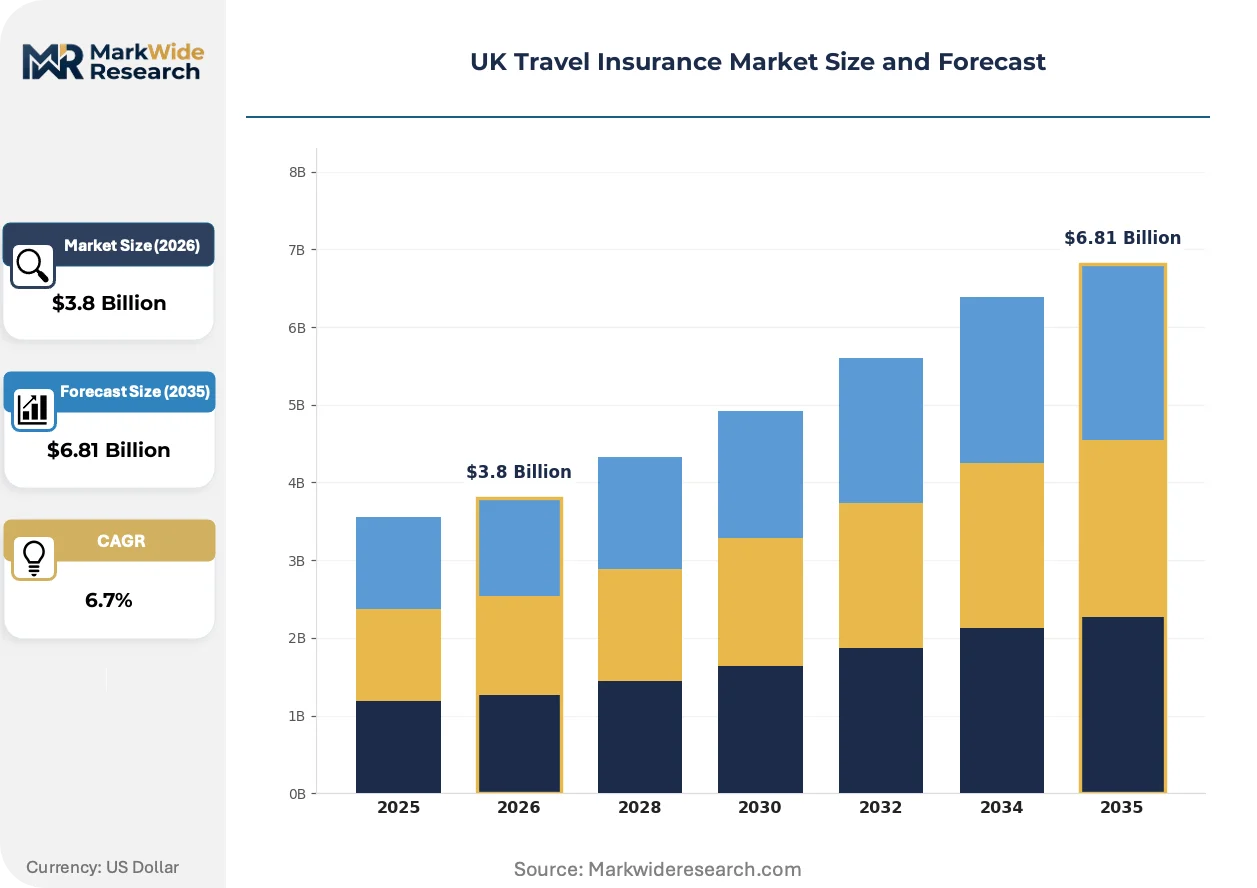
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Coverage Type: Medical Expenses, Trip Cancellation, Baggage Loss, Travel Delay Distribution Channel: Direct Sales, Online Aggregators, Insurance Brokers, Travel Agents Customer Type: Families, Business Travelers, Solo Travelers, Senior Citizens Policy Duration: Single Trip, Annual Multi-Trip, Long-Term, Short-Term |
| Companies Covered | Munich Re, Direct Line Group, Aviva Plc, Saga PLC, Admiral Group, Allianz Partners, Chubb, Europ Assistance, AXA UK & Ireland, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Travel Insurance Market Strategic Shifts
Digital distribution infrastructure is actively reshaping how UK travel insurance reaches end buyers. Technology deployment, regulatory adaptation, and behavioral shifts are converging to compress traditional intermediation layers and elevate transparency requirements.
Parametric trip cancellation coverage is expanding into mainstream product portfolios. This structured payout mechanism triggers automatic compensation upon verified flight delays or destination lockdowns without claims adjustment overhead. Price-sensitive holiday bookers are adopting these policies at accelerated rates through airline and travel agent embedded partnerships. The technology is expanding into standard annual multi-trip products, compressing traditional indemnity-based cancellation coverage into secondary position.
The Financial Conduct Authority's ongoing travel insurance market study is tightening add-on pricing transparency and renewal practice standards. This regulatory intervention requires underwriters to demonstrate that ancillary products represent fair value relative to standalone alternatives. Distribution partners and direct writers are responding by unbundling previously packaged coverage elements and introducing standalone medical top-up options.
Price comparison websites have captured majority share of UK travel insurance discovery and purchase journeys. These digital intermediaries displace traditional broker relationships through instant quote aggregation and policy issuance. The channel shift is most visible among younger demographics booking European city breaks and short-haul beach holidays, where convenience and premium minimization dominate selection criteria.
UK Travel Insurance Market Segmentation
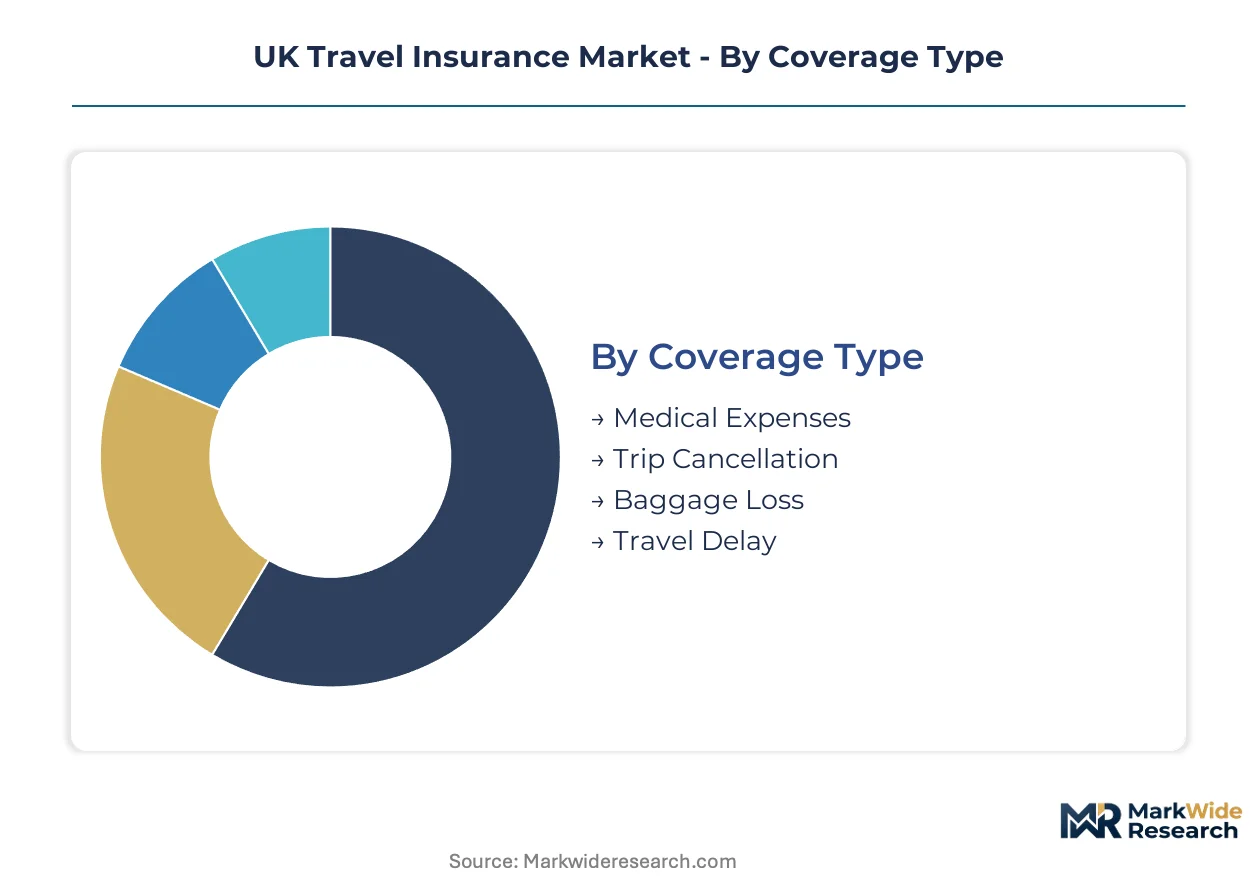
Segmentation in UK travel insurance reveals how coverage design, purchase pathways, and policyholder profiles intersect to shape premium pools and claims experience. Understanding these divisions exposes where underwriting complexity concentrates and where distribution economics favor scale over specialization.
Coverage Type:
Medical underwriting sophistication distinguishes product tiers across the coverage spectrum, with actuarial modeling varying sharply by benefit trigger.
- Medical Expenses:Core indemnity protection against overseas treatment costs where NHS reciprocity does not apply, particularly in United States, Switzerland, and Caribbean jurisdictions. Demand concentrates among senior citizens booking extended European trips, driven by non-reciprocal treatment cost exposure and higher per-policy premium tolerance.
- Trip Cancellation:Reimbursement of prepaid, non-refundable travel costs upon specified peril occurrence including illness, bereavement, or destination lockdown. Families with substantial sunk costs in package holidays represent the primary demand concentration, pressured by deposit protection gaps in standard consumer credit coverage.
- Baggage Loss:Indemnity for personal effects theft, damage, or misrouting during transit. Business travelers with high-value equipment and professional wardrobe requirements generate disproportionate claim frequency.
- Travel Delay:Fixed benefit or expense reimbursement upon verified carrier delay exceeding policy-specified thresholds. Solo travelers on tight itineraries and connecting flights demonstrate highest attachment rates.
Mature deployment sits with Medical Expenses. Newer deployment is concentrated in Travel Delay parametric structures.
Distribution Channel:
Cost-to-serve economics and customer acquisition efficiency separate channel strategies, with digital intermediation compressing traditional commission structures.
- Direct Sales:Insurer-controlled digital platforms and telephone operations capturing full margin without intermediary commission. Aviva Plc deploys proprietary technology stacks to serve price-sensitive holiday bookers seeking instant policy issuance.
- Online Aggregators:Price comparison websites aggregating quotes across multiple underwriters for simultaneous consumer evaluation. These platforms now dominate discovery and purchase journeys among younger demographics booking European city breaks, though front-book commissions have compressed to single-digit percentages.
- Insurance Brokers:Intermediaries providing advisory services and claims advocacy, typically serving complex medical underwriting requirements. The channel retains relevance for pre-existing condition disclosure and extended trip duration negotiations.
- Travel Agents:Point-of-sale bundling with holiday packages, capturing customers before independent aggregator search behavior initiates. Embedded partnerships with airlines and cruise operators are expanding this channel's relevance.
Volume leadership belongs to Online Aggregators. Margin protection efforts concentrate in Direct Sales and Travel Agent embedded partnerships.
Customer Type:
Risk profile heterogeneity and trip frequency patterns create distinct underwriting approaches across demographic groupings.
- Families:Multi-person policies covering dependent children with standardized benefit limits and simplified medical screening. Trip cancellation exposure peaks during school holiday periods with non-refundable package tour deposits.
- Business Travelers:Frequent, short-duration trips with employer-funded premiums and emphasis on inconvenience minimization over cost optimization. Annual multi-trip policies dominate this segment with automatic coverage activation.
- Solo Travelers:Individual coverage with flexible destination switching and backpacker-oriented medical limits. Price sensitivity drives aggregator channel preference and basic tier selection.
- Senior Citizens:Over-fifties and over-seventies segments requiring age-banded medical underwriting for extended European trips. Saga PLC specializes in this demographic with higher per-policy premiums and pre-existing condition accommodation.
Commercial value concentrates in Senior Citizens. Volume expansion is concentrated in Solo Travelers through digital acquisition.
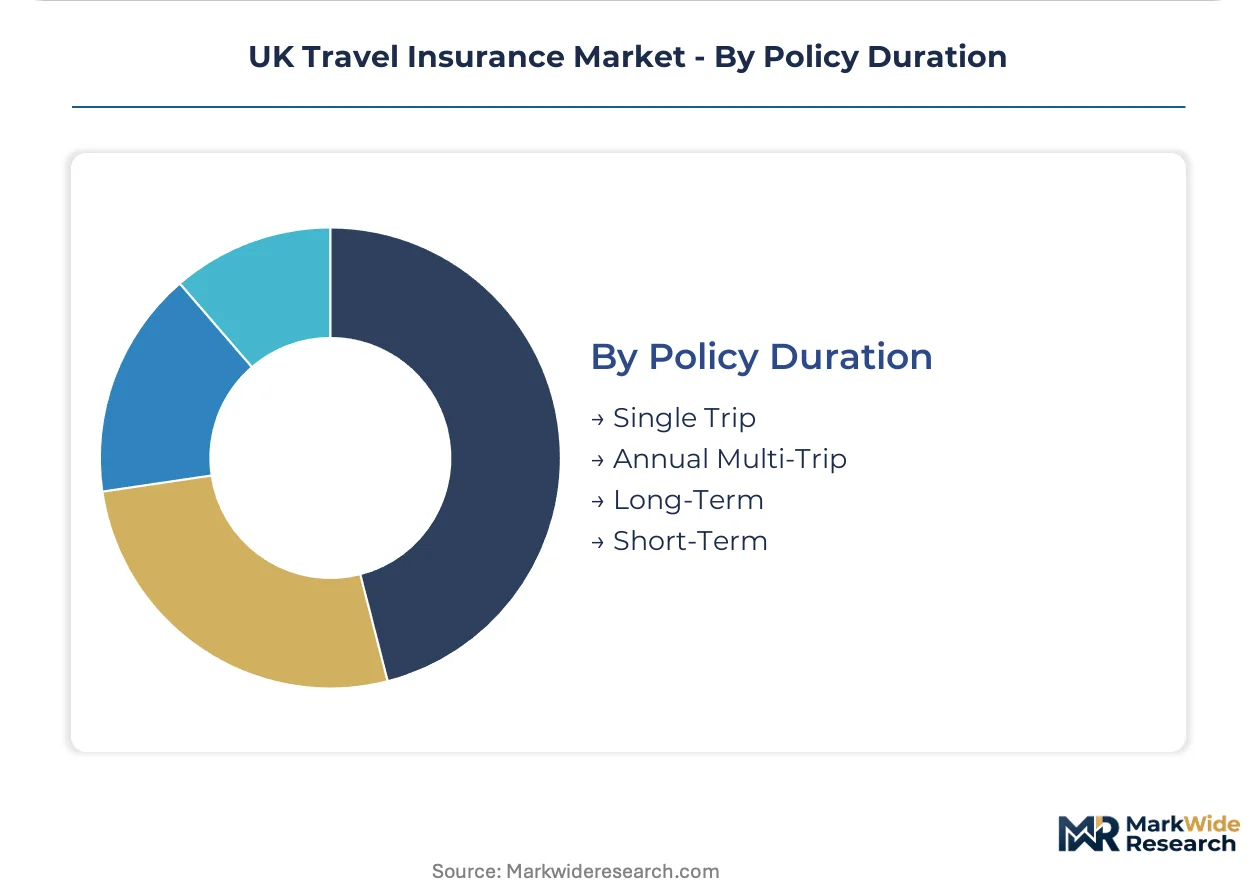
Policy Duration:
Trip frequency and convenience valuation determine duration selection, with structural shifts visible in post-pandemic renewal behavior.
- Single Trip:Discrete coverage for one specified journey with defined departure and return dates. Infrequent holidaymakers and first-time purchasers default to this structure despite higher per-trip cost.
- Annual Multi-Trip:Rolling coverage for unlimited journeys within a twelve-month period, subject to maximum trip duration limits per excursion. Frequent flyers seeking convenience and per-trip cost reduction are converting from single-trip purchases at accelerating rates.
- Long-Term:Extended coverage exceeding standard annual periods, typically for expatriate assignments, sabbaticals, or gap year travel. Medical underwriting rigor intensifies with duration extension.
- Short-Term:Brief coverage windows for weekend breaks and single-city visits, often distributed through airline and accommodation embedded partnerships at point-of-booking.
Legacy concentration remains in Single Trip. Annual Multi-Trip is expanding most quickly as post-pandemic leisure normalization drives renewal behavior change.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's underwriting capital anchors UK travel insurance distribution, with actuarial expertise and regulatory proximity concentrating in the Square Mile. Regional demand patterns diverge sharply across England's sub-regions, shaped by demographic composition, outbound travel frequency, and local broker networks.
London and Southeast England
Affluent professionals booking long-haul leisure trips drive demand for comprehensive medical coverage with high limits. The Financial Conduct Authority's consumer duty rules apply most stringently here given the concentration of direct-to-consumer digital platforms. Canary Wharf and the City host underwriter headquarters where pricing models and risk selection algorithms are developed.
Midlands
Manufacturing and logistics employment bases generate substantial business travel insurance volumes through employer-sponsored annual multi-trip policies. Birmingham's emerging fintech cluster is incubating digital distribution startups challenging incumbent aggregator relationships. Regional broker networks retain relevance for complex medical underwriting cases.
North England
Price-sensitive holidaymakers dominate, with aggregator channel penetration highest in Manchester and Liverpool metropolitan areas. Post-pandemic renewal behavior shows elevated attachment of cancellation coverage among families with non-refundable package tour deposits. Local insurance broker partnerships with independent travel agents persist in smaller urban centers.
Scotland
Extended European trip durations among retirees concentrate demand for age-banded medical underwriting. Edinburgh's financial services sector hosts specialist reinsurance operations supporting Scottish underwriter capacity. Rural Highland and Island communities exhibit lower digital adoption, sustaining telephone and branch-based distribution.
Wales
Coastal tourism economies in Gwynedd and Pembrokeshire generate seasonal single-trip policy spikes. Cardiff's growing insurance sector is attracting back-office operations from London-based underwriters seeking cost arbitrage. Welsh-language policy documentation requirements add compliance complexity for national distributors.
UK Travel Insurance Market Competitive Environment
Portfolio diversification dominates the current landscape as underwriters rebalance toward annual multi-trip and embedded distribution channels. The market exhibits tiered concentration: global reinsurance-backed carriers with balance sheet scale, mid-sized domestic specialists with demographic or channel focus, and digital-native entrants exploiting aggregator price transparency. Three archetypes define positioning: reinsurance-backed scale players, age-specialist underwriters, and direct-to-consumer platform operators. Competitive intensity centers on embedded airline partnerships and annual policy conversion from single-trip purchasers.
Among the reinsurance-backed tier, Munich Re and Chubb exemplify capital depth enabling medical cost inflation absorption in United States and Caribbean jurisdictions. Aviva Plc and Saga PLC occupy distinct specialist positions—Aviva leveraging proprietary digital infrastructure for price-sensitive acquisition, Saga anchoring the over-fifties segment where per-policy premiums and medical underwriting complexity converge. Admiral Group represents the cross-sell archetype, integrating travel coverage with motor insurance relationships.
| Leading Market Players |
|---|
| Munich Re |
| Direct Line Group |
| Aviva Plc |
| Saga PLC |
| Admiral Group |
| Allianz Partners |
| Chubb |
| Europ Assistance |
| AXA UK & Ireland |
| Others |
Value Chain & Pricing Dynamics
The Financial Conduct Authority's consumer duty framework gates both qualified supply and premium-tier pricing access, as underwriters must demonstrate fair value across product lines to maintain distribution partnerships. Price-sensitive holiday bookers gravitate toward digital platforms where unbundled medical top-up options compete against packaged coverage, while specialized age-banded propositions command structural premiums through complex underwriting access.
Pricing Analysis
Warranty-style service bundling differentiates pricing tiers, with annual multi-trip policies embedding automatic renewal guarantees and claims advocacy versus stripped-down single-trip equivalents. Three-tier pricing structure across premium, standard, and economy levels segments by medical limit ceilings and pre-existing condition accommodation. Cost compression in economy tiers intensifies because aggregator commission compression forces reliance on ancillary adjustment fees. Solo travelers booking European city breaks exhibit highest price sensitivity, while over-fifties segments demonstrate premium tolerance for comprehensive medical evacuation coverage.
Supply Chain Analysis
Single-source vulnerability sits with London-based reinsurance capacity backing medical cost inflation exposure in United States and Caribbean jurisdictions. Underwriting expertise concentrates in the United Kingdom, Germany, and Switzerland, while claims adjustment services draw from Portugal, Spain, and Greek island medical networks. Tariff exposure runs through post-Brexit regulatory divergence affecting European Health Insurance Card reciprocity negotiations. Distribution runs through online aggregators controlling price discovery, with embedded airline partnerships capturing customers before independent search behavior initiates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Parametric trip cancellation technology is displacing traditional indemnity-based claims adjustment, compressing processing overhead and reshaping competitive positioning around real-time payout verification. Incumbents must adapt legacy policy administration infrastructure to API-native distribution or surrender aggregator channel access to digital-native entrants.
For Market Incumbents: Cement proprietary data integration with airline and cruise operator booking systems to preempt aggregator search behavior. Invest in age-banded medical underwriting automation for over-seventies segmentation, where substitute technology from insurtech challengers threatens pricing power. Channel control through embedded partnerships represents the critical defensive lever against commission compression.
For New Entrants and Emerging Players: The price-point gap between Saga PLC's premium age-specialist positioning and aggregator economy tiers opens white-space for mid-market annual multi-trip propositions. Target underpenetrated conversion from single-trip purchasers among frequent flyers in Midlands business travel corridors. Go-to-market execution should emphasize employer-sponsored group policy distribution bypassing individual price comparison friction.
For Investors and Strategic Acquirers: Prudential Regulation Authority capital charge adjustments for pandemic-era reserve deficiencies are the leading indicator that reinsurance-backed scale players will consolidate specialist underwriters lacking balance sheet depth. Long-term viability favors carriers with diversified medical cost inflation exposure across United States, Switzerland, and Caribbean jurisdictions. Acquisition focus should target digital distribution infrastructure rather than legacy policy administration estates.
| Strategic Initiative | Industry Significance |
|---|---|
| Embedded Insurance Partnership | Airline point-of-booking integration captures customers before aggregator search initiates. |
| Parametric Claims Automation | Flight delay verification technology eliminates adjustment overhead and accelerates payout velocity. |
| Age-Banded Underwriting Expansion | Over-seventies medical specialization addresses unmet demand in Spanish and Portuguese destinations. |
| Annual Multi-Trip Conversion Program | Frequent flyer migration from single-trip policies improves lifetime value and retention economics. |
| FCA Consumer Duty Compliance Investment | Fair value demonstration capability preserves distribution access under tightening regulatory scrutiny. |
Study Parameters
Independent corroboration across underwriter pricing directors, aggregator platform managers, and reinsurance treaty negotiators underwrites the qualitative findings in this study. Primary interviews with Financial Conduct Authority policy specialists, travel agent consortium leaders, and claims adjustment operations heads combined with secondary validation from Prudential Regulation Authority solvency disclosures, Financial Ombudsman Service complaint trend data, and airline partnership announcement filings. Bottom-up policy volume estimates triangulated against top-down premium pool calculations derived from distribution channel commission structures.
Rate-of-change decomposition across the analysis window separates volume expansion from pricing mix effects and segment migration patterns. The analytical framework models coverage type, distribution channel, customer demographic, and policy duration dimensions alongside regional booking corridor intensity. CAGRs were derived from policy issuance velocity trends and per-policy premium evolution, with medical cost inflation assumptions and post-pandemic renewal behavior shifts as key forecast inputs.
Underlying measurement precision varies by segment; online aggregator channel estimates carry tighter precision than embedded airline partnership volumes where disclosure opacity persists. Forecasts reflect assumptions around regulatory stability and reinsurance capacity availability, with Financial Conduct Authority market study outcomes and European Health Insurance Card reciprocity negotiations as specific risk factors that could revise trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Insurance
Family Floater Health Insurance Market
Insurance
Disability Insurance Market
Insurance
Dental Insurance Market
Insurance
Vietnam Private Health Insurance Market
Insurance
Insurance Protection Products Market
Insurance
France Property and Casualty Insurance Market
Insurance
Insurance BPO Services Market
Insurance
Travel Insurance Market
Insurance
Saudi Arabia Health & Medical Insurance Market
Insurance
Austria Property and Casualty Insurance Market
Insurance
US Travel Insurance Market
Insurance
Factory and Warehouse Insurance Market
Insurance
Specialty Insurance Market
Insurance
France Car Insurance Market
Insurance
Digital Innovation in Insurance Market
Insurance
Europe Parametric Insurance Market