
 Solar Rooftop Sales Market | 2026-2036
Solar Rooftop Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Rooftop Sales Market Insights
Chinese wafer and cell manufacturers is realigning capacity toward higher-efficiency formats, tightening supply availability for legacy module producers. Jinko Solar leverages vertical integration from polysilicon to module assembly to sustain margin capture across volatile input cycles. Tesla anchors its rooftop sales through direct-to-consumer channel control and integrated storage bundling. Canadian Solar competes on utility-scale manufacturing scale while extending selective distribution partnerships into residential installer networks.
Solar rooftop sales encompass photovoltaic system transactions designed for building-mounted energy generation, typically involving modules rated between 300W and 700W with conversion efficiencies from 20% to 23% depending on cell architecture. These systems serve on-site electricity supply, grid export revenue, and corporate sustainability compliance objectives. Monocrystalline modules dominate value capture due to superior efficiency density on space-constrained rooftops, while bifacial formats are gaining traction on commercial flat roofs where albedo reflection boosts yield. Residential applications remain the largest volume pool, though agricultural end users represent an emerging margin segment where irrigation load offset creates compelling payback profiles.
FERC net metering rules and state-level renewable portfolio standards in the US shape interconnection access and compensation structures for distributed solar assets, while India's CEA technical standards and state electricity regulatory commission orders govern system sizing and grid injection limits. The EU Green Deal and national building renovation mandates are embedding solar readiness requirements into construction codes across member states. Stakeholders must monitor evolving tariff structures and storage pairing economics as grid operators recalibrate compensation frameworks for high distributed generation penetration.
Market Dynamics
Chinese polysilicon and wafer concentration is forcing module assemblers outside China to reconfigure procurement strategies around tariff-exposed supply chains and alternative sourcing corridors.
Growth Catalysts
- India's PLI scheme for domestic solar module manufacturing:Production-linked incentives are redirecting supply chains toward local cell and module assembly, reducing import dependency for project developers in Maharashtra and Gujarat.
- Commercial building electrification mandates:Corporate sustainability compliance targets are accelerating procurement of rooftop photovoltaic systems across India's warehousing and logistics real estate stock.
- Monocrystalline PERC and TOPCon efficiency gains:Conversion improvements above 22% are compressing payback periods for space-constrained urban installations.
Market Restraints
- Polysilicon price volatility:Input cost swings from Xinjiang-based metallurgical-grade silicon refining compress margin visibility for module distributors.
- Legacy module inventory obsolescence:Wafer format transitions from M10 to G12 standards are stranding capacity at second-tier assembly operations.
- Net metering compensation compression:State electricity regulatory commission orders in Karnataka and Andhra Pradesh are reducing export tariffs below avoided cost benchmarks.
Strategic Opportunities
- Agricultural irrigation load offset:Solar-powered pumping systems for groundwater extraction represent an emerging margin segment where diesel displacement economics favor rooftop deployment.
- Bifacial module adoption on commercial flat roofs:Albedo reflection yield boosts are opening technical differentiation for EPC contractors serving industrial park developments.
- CEA technical standards for storage integration:Grid code amendments enabling AC-coupled battery pairing create bundled revenue streams for commercial asset owners.
Industry Challenges
- Skilled installer capacity constraints:Rooftop system design and DC-AC electrical integration expertise remains concentrated among a limited pool of certified contractors in Tier-2 cities.
- Distribution network credit exposure:Working capital intensity for inventory financing and extended payment terms to EPC partners strains balance sheets of regional distributors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Rooftop Sales Market |
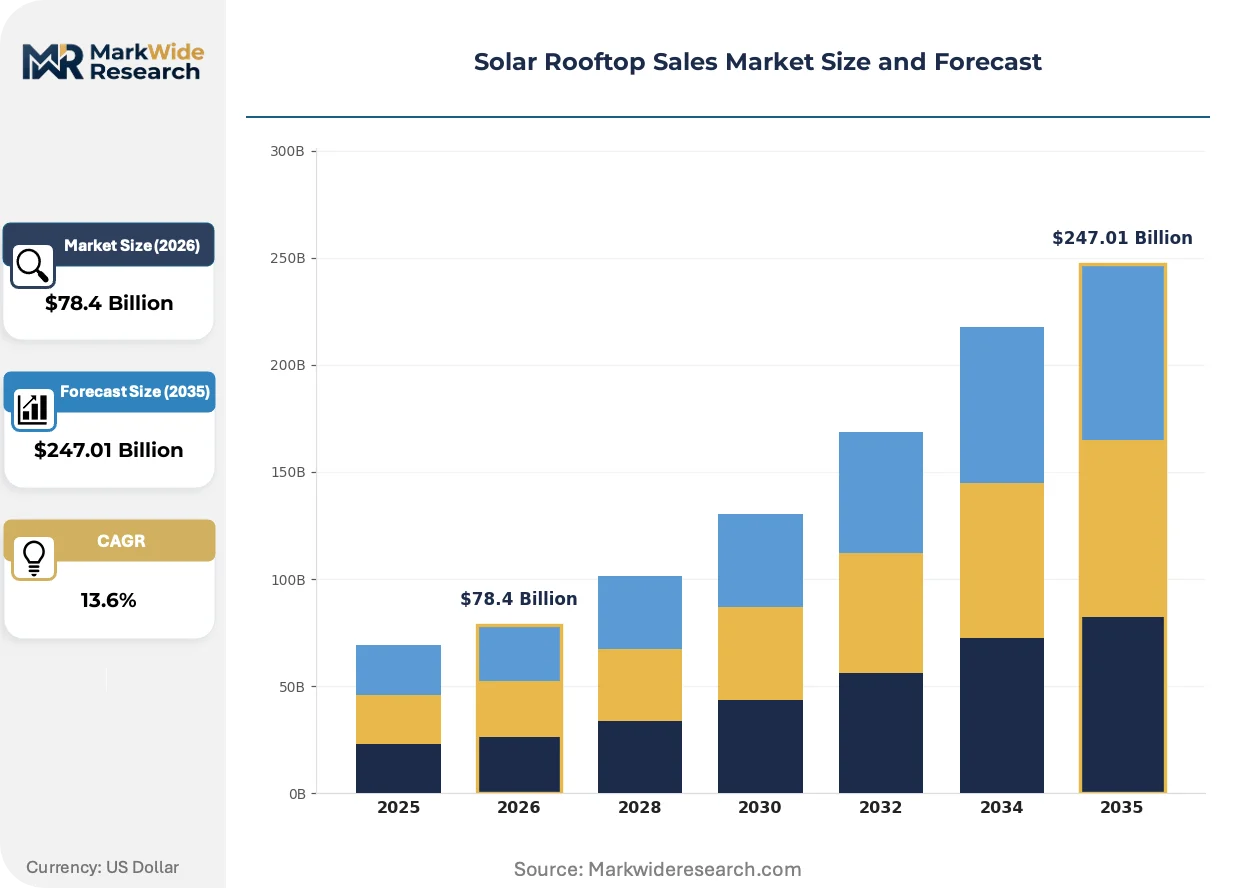
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monocrystalline, Polycrystalline, Thin-Film, Bifacial Application: Residential, Commercial, Industrial, Agricultural Installation Type: Rooftop, Ground-mounted, Building-integrated, Off-grid End User: Homeowners, Corporations, Farms, Government |
| Companies Covered | SunPower Corporation, First Solar, Tesla, Canadian Solar, Jinko Solar, Trina Solar, JA Solar, Sunrun, SolarEdge Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Rooftop Sales Market Trends and Innovations
Module efficiency competition and interconnection rule evolution are compressing technology cycles and reshaping how project developers structure asset ownership and financing.
TOPCon cell architecture is consolidating manufacturing investment away from legacy PERC lines. Commercial and industrial buyers in Gujarat are specifying n-type modules for new procurement. This transition is consolidating supplier market share toward cell-integrated module producers with captive wafer supply.
India's CEA technical standards for grid-connected rooftop systems are tightening inverter anti-islanding and voltage ride-through requirements. Compliance testing timelines have extended by four to six weeks for imported equipment. Domestic inverter manufacturers with BIS certification are capturing share from European and Chinese suppliers in Maharashtra state tenders.
Direct-to-consumer sales models are displacing traditional installer-led channel structures in metropolitan markets. Tesla's integrated storage bundling and digital configuration tools are setting reference pricing expectations. This channel compression is most visible in Bangalore and Hyderabad, where tech-sector employment density correlates with online purchase intent for residential systems.
Solar Rooftop Sales Market Segmentation
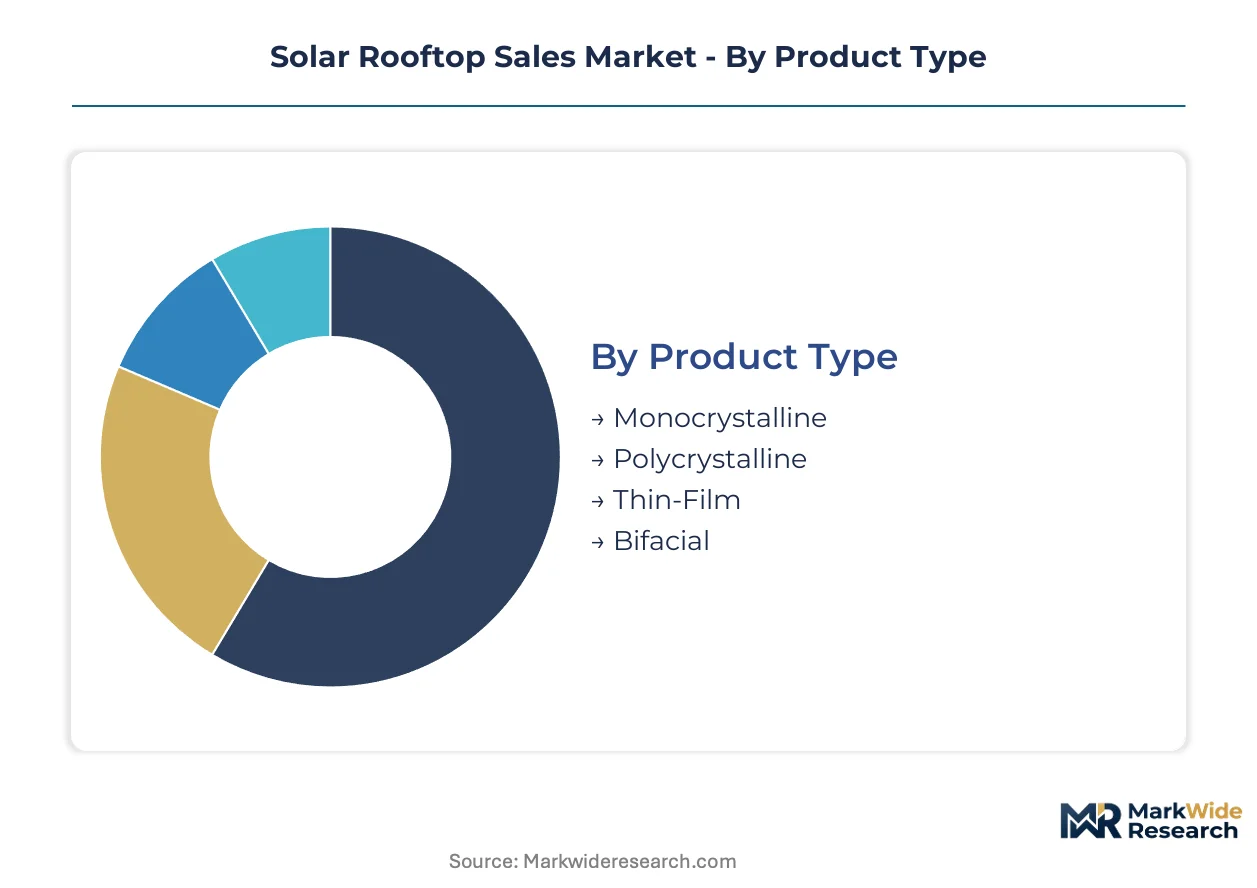
Solar rooftop sales fragment across technical specifications, building types, and ownership structures that determine system sizing, financing models, and regulatory compliance pathways. Understanding these divisions reveals where module efficiency premiums command pricing power and where standardized procurement dominates.
Product Type:
Standardization prevails at the commodity end while premium tiers reward efficiency density and bifacial yield capture.
- Monocrystalline:Silicon ingots from single-crystal growth deliver conversion efficiencies above 22% in PERC and TOPCon architectures. Demand concentrates in Maharashtra and Gujarat urban rooftops where space constraints maximize value per square meter. CEA technical standards favor these modules for grid-connected commercial installations.
- Bifacial:Dual-sided cell architecture harvests albedo reflection from concrete or white membrane commercial roofs, boosting effective yield 8-15% over monofacial equivalents. Industrial park developments in Gujarat specify these for flat-roof warehouses where ground coverage ratios permit elevated mounting.
- Polycrystalline:Multi-crystal silicon production offers lower unit costs for price-sensitive rural deployments with ample rooftop area.
- Thin-Film:Cadmium-telluride and CIGS technologies occupy niche applications where weight constraints or partial shading tolerance outweigh efficiency penalties.
Leading the category by volume: Monocrystalline. Growing fastest: Bifacial.
Application:
Scale economics and regulatory treatment diverge sharply across building use classes.
- Residential:Individual homeowner purchases drive the largest unit volume pool, typically 3-10 kW systems with net metering to state electricity regulatory commissions. Tesla's direct-to-consumer model in Bangalore and Hyderabad compresses customer acquisition costs through digital configuration tools.
- Commercial:Corporate sustainability mandates accelerate procurement across India's warehousing and logistics real estate stock, with 100 kW-2 MW systems dominating. PLI scheme domestic content requirements shape supplier selection for Maharashtra retail and office developments.
- Industrial:Factory rooftops and captive power arrangements serve continuous process loads with high self-consumption ratios.
- Agricultural:Solar-powered groundwater pumping for irrigation creates compelling diesel displacement economics in Gujarat and Andhra Pradesh, emerging as a margin-accretive segment.
Residential claims the volume lead. Agricultural irrigation load offset expands most quickly.
Installation Type:
Mounting configuration determines structural engineering requirements, permitting complexity, and grid interconnection pathways.
- Rooftop:Building-mounted arrays constitute the core market addressed in this analysis, spanning pitched residential tiles and flat commercial membranes. State-level net metering policies in Karnataka and Andhra Pradesh govern compensation structures, though export tariff compression is reducing project returns.
- Building-integrated:Photovoltaic elements replace conventional roofing or facade materials, commanding architectural premiums in commercial developments where aesthetics constrain conventional panel deployment.
- Ground-mounted:Land-based installations compete with agricultural use and face distinct land acquisition and environmental clearance requirements.
- Off-grid:Standalone systems with battery storage serve unelectrified or unreliable grid areas, typically below 10 kW scale with DC-coupled load management.
Rooftop dominates absolute installations. Building-integrated gains share fastest among premium commercial segments.
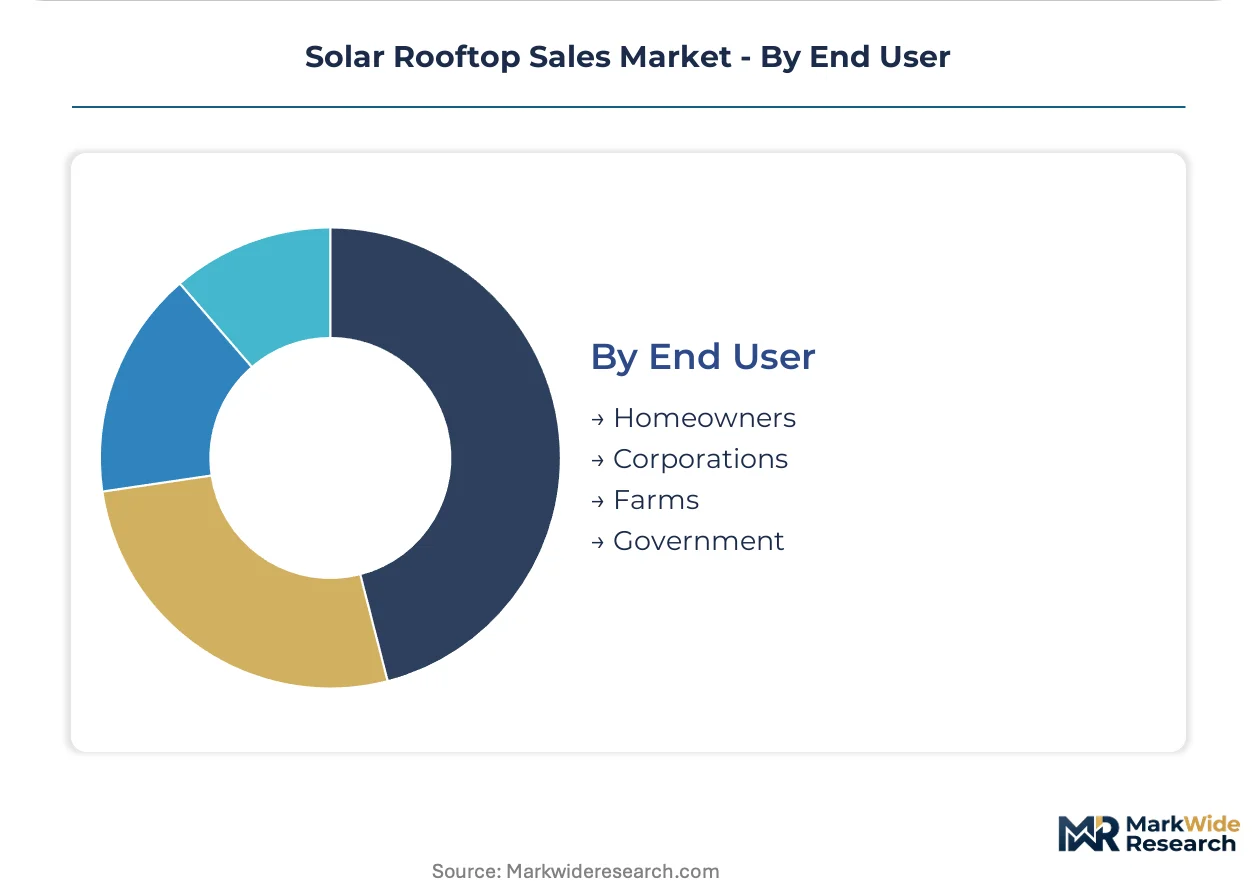
End User:
Decision-making authority and capital access separate consumer-driven from institutionally procured systems.
- Corporations:Balance-sheet financing and sustainability reporting requirements drive standardized procurement at scale, with ESG disclosure mandates under EU Green Deal influencing multinational operations in India. Power purchase agreements and operating leases predominate over direct ownership.
- Homeowners:Individual purchase decisions rely on payback period calculations and available subsidies, with digital sales channels displacing traditional installer networks in metropolitan markets.
- Farms:Agricultural producers evaluate systems against diesel pump operating costs, with PM-KUSUM scheme subsidies influencing adoption timing.
- Government:Public building mandates and rural electrification programs deploy centralized procurement with domestic content requirements.
Corporations lead by contract value. Farms show steepest expansion trajectory amid irrigation electrification priorities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polysilicon refining clusters in Xinjiang and Inner Mongolia anchor supply-side capacity for module assembly across Asia-Pacific markets. This concentration shapes procurement corridors for rooftop system developers in India, Southeast Asia, and Australia.
India
Maharashtra and Gujarat dominate procurement volumes through state-level net metering policies and high solar irradiance. The CEA technical standards govern grid interconnection requirements, while the PLI scheme redirects supply chains toward domestic cell and module assembly. Industrial park developments in Ahmedabad and Surat specify bifacial modules for flat-roof warehouses.
China
Wafer and cell manufacturers in Jiangsu and Anhui provinces realign capacity toward higher-efficiency TOPCon formats. MIIT industrial policy supports dual carbon goals through manufacturing scale consolidation. Ningbo and Huzhou industrial clusters supply module assembly operations serving Southeast Asian export markets.
United States
California and Texas lead residential and commercial deployment through FERC net metering rules and state renewable portfolio standards. The IRA production tax credits reshape domestic content requirements for project finance. Installer networks in Phoenix and Dallas-Fort Worth metro areas concentrate certified contractor capacity.
Germany
Bavaria and North Rhine-Westphalia drive building-integrated photovoltaic adoption through EU Green Deal renovation mandates. The F-Gas Regulation and REACH compliance frameworks shape equipment specification for commercial developments. Munich and Cologne industrial zones anchor EPC contractor expertise for corporate sustainability procurement.
Australia
New South Wales and Queensland accelerate residential rooftop penetration through state-level feed-in tariff structures and solar irradiance advantages. The Clean Energy Council accreditation program governs installer certification requirements. Sydney and Brisbane metropolitan markets concentrate direct-to-consumer sales channel development.
Solar Rooftop Sales Market Competitive Landscape
Global majors compete with regional champions across module efficiency tiers and channel access structures. The vendor base separates into integrated cell-to-module producers, pure-play distributors, and direct-to-consumer platform operators. Three archetypes dominate: vertically integrated manufacturers with captive wafer supply, installer-network-dependent distributors, and digital-native bundlers of hardware-plus-storage systems. Capacity expansion and strategic partnerships constitute the dominant competitive moves as players secure input supply and distribution reach.
Within the integrated manufacturing tier, Jinko Solar and Canadian Solar exemplify scale-driven positioning through upstream control over polysilicon refining and wafer production. Tesla occupies a distinct archetype as a direct-to-consumer platform operator leveraging digital configuration tools and integrated storage bundling. These three companies represent contrasting strategic vectors—manufacturing scale, vertical integration depth, and channel disintermediation—through which competitive positioning is negotiated.
| Leading Market Players |
|---|
| SunPower Corporation |
| First Solar |
| Tesla |
| Canadian Solar |
| Jinko Solar |
| Trina Solar |
| JA Solar |
| Sunrun |
| SolarEdge Technologies |
| Others |
Pricing and Supply Chain Analysis
Commercial buyers in Gujarat and Maharashtra specifying n-type TOPCon modules are compressing procurement timelines and squeezing margin buffers for distributors holding legacy PERC inventory. This demand-side specification shift forces supply chains to accelerate format transitions while pricing power concentrates with cell-integrated producers holding captive wafer supply.
Pricing Analysis
Warranty and performance guarantees bundled into module sales separate premium tiers from unbundled commodity transactions. Three-tier pricing structure across premium, standard, and economy levels tracks efficiency density and certification tier—BIS-marked modules with 25-year linear warranties command substantial premiums over non-certified alternatives. Pricing pressure stems from polysilicon cost volatility emanating from Xinjiang refining clusters, compressing distributor margins on inventory held during input price swings. Agricultural irrigation buyers in Andhra Pradesh exhibit highest price sensitivity, while corporate sustainability procurement teams in Maharashtra prioritize performance guarantees over unit cost.
Supply Chain Analysis
Regional distribution centers in Ahmedabad, Surat, and Pune operate hub-and-spoke patterns feeding installer networks across western India. Manufacturing gravity centers on China, India, and Vietnam—Chinese wafer and cell producers in Jiangsu and Anhui feed module assembly operations, while India's PLI scheme builds domestic cell and module capacity in Gujarat and Tamil Nadu. Polysilicon refining in Xinjiang and Inner Mongolia anchors upstream material flows, exposing procurement corridors to tariff and regulatory risk. Distribution runs through state-level distributor networks with BIS certification requirements, though direct-to-consumer platforms are compressing traditional channel structures in Bangalore and Hyderabad.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar rooftop sales market has become a vertical-integration race where control over cell manufacturing and wafer supply determines margin capture. Players securing captive polysilicon refining or TOPCon cell capacity gain pricing power as format transitions accelerate.
For Market Incumbents: Hedge against legacy module inventory obsolescence by accelerating M10-to-G12 wafer format transitions and securing long-term polysilicon offtake agreements with Xinjiang and Inner Mongolia refiners. Build backward integration into cell manufacturing under India's PLI scheme to defend margin position against pure-play distributors. Channel control through certified installer networks in Tier-2 cities remains a defensible moat as direct-to-consumer platforms expand. For New Entrants and Emerging Players: Capture agricultural irrigation load offset segments in Gujarat and Andhra Pradesh where diesel displacement economics favor rooftop deployment and incumbent coverage remains thin. Target commercial flat-roof bifacial installations in industrial park developments where albedo yield boosts create technical differentiation opportunities. Pursue EPC contractor partnerships rather than distributor relationships to bypass working capital intensity of inventory financing. For Investors and Strategic Acquirers: The window for entry favors cell-integrated module producers with captive wafer supply and BIS certification pathways already cleared. Long-term viability hinges on manufacturing scale and regulatory compliance depth rather than channel reach alone. Watch CEA technical standard amendments for storage integration as the inflection signal—grid code shifts enabling AC-coupled battery pairing will revalue commercial asset portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Manufacturing | Captive TOPCon capacity under India's PLI scheme secures margin capture through volatile input cycles. |
| Direct-to-Consumer Platform Launch | Tesla's digital configuration tools in Bangalore and Hyderabad compress customer acquisition costs and installer dependency. |
| Bifacial Module Portfolio Expansion | Albedo reflection yield boosts on Gujarat industrial flat roofs open premium pricing for EPC contractors. |
| Storage Integration Certification | CEA grid code amendments enabling AC-coupled battery pairing create bundled revenue streams for commercial owners. |
| Agricultural Irrigation Channel Development | PM-KUSUM scheme subsidies in Andhra Pradesh accelerate solar-powered pumping adoption with compelling diesel displacement economics. |
Research Methodology
Multi-period observation of module efficiency transitions, state-level net metering policy amendments, and PLI scheme capacity buildouts anchored the trend analysis, supplemented by interviews with EPC contractors, regional distributors, CEA regulatory officials, and corporate sustainability procurement leads. Secondary validation drew from CEA technical standards filings, state electricity regulatory commission orders, SECI tender documents, and MNRE deployment statistics. Bottom-up project pipeline tracking across Maharashtra, Gujarat, Karnataka, and Andhra Pradesh triangulated against top-down manufacturing capacity assessments from MIIT and industry associations.
Segment-weighting approaches modeled rooftop, building-integrated, ground-mounted, and off-grid installation types alongside monocrystalline, bifacial, polycrystalline, and thin-film product categories. CAGRs were derived through regression analysis of historical deployment trajectories and policy incentive schedules across the projection horizon. Forecast inputs incorporated solar irradiance mapping, state-level net metering compensation trajectories, and polysilicon price elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to PLI scheme extension decisions, CEA storage integration mandates, and polysilicon supply chain reconfigurations. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Amorphous Silicon PV Market
Solar Power Systems
Solar Photovoltaic Ribbon Market
Solar Power Systems
Box Solar Cookers Market
Solar Power Systems
Hairy Solar Panels Market
Solar Power Systems
On-Grid Solar Inverter Market
Solar Power Systems
Solar Power Bank Market
Solar Power Systems
Qatar Solar Energy Market
Solar Power Systems
Solar Panels for Home Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
United Arab Emirates Solar Photovoltaic (PV) Market
Solar Power Systems
Europe Bifacial Solar Market
Solar Power Systems
South America Solar Photovoltaic Market
Solar Power Systems
Italy Solar Energy Market
Solar Power Systems
Residential Solar Inverter Market
Solar Power Systems
Global Solar Power Windows Market
Solar Power Systems
Organic Solar Cells Market