
 North America Concentrated Solar Power (CSP) Market | 2026-2036
North America Concentrated Solar Power (CSP) Market Size, Share, and Industry Trends Forecast 2026-2036
North America Concentrated Solar Power (CSP) Market Analytics
Modular thermal energy storage bundling is consolidating buyer choice across the North America CSP landscape. ENGIE leverages its European project heritage to anchor utility-scale development in the southwestern United States. BrightSource Energy, Inc. specializes in solar tower configurations with molten salt storage. Siemens Energy dominates power block and turbine supply, extending its fossil-era relationships into renewable thermal generation.
Concentrated Solar Power harnesses mirrors or lenses to focus direct normal irradiance onto a receiver, heating transfer media such as molten salt or synthetic oil to temperatures exceeding 500°C for thermoelectric conversion or industrial process heat. Parabolic trough technology occupies the largest installed base due to decades of operational validation and lower capital intensity per megawatt. Solar tower configurations represent the fastest-growing technology segment as higher operating temperatures unlock superior thermal storage duration and round-trip efficiency. Thermal Energy Storage components command disproportionate margin attention because storage duration differentiates CSP from photovoltaic alternatives in wholesale capacity markets.
The Federal Energy Regulatory Commission shapes market access through interconnection queue reforms and capacity market participation rules that reward dispatchable renewable assets. The EPA's greenhouse gas standards for power plants and state-level renewable portfolio standards in California, Arizona, and New Mexico create layered compliance demand for firm clean generation. The IRA's domestic content bonus and standalone storage credit structures from the US Treasury are recalibrating project finance assumptions. Stakeholders must monitor how evolving FERC Order 2222 implementation affects aggregated thermal storage participation in regional transmission organization markets.
Market Dynamics
The Inflation Reduction Act's standalone storage credit and domestic content bonus are compressing project finance timelines for developers across the southwestern United States. These federal incentives intersect with state-level clean energy mandates to create procurement urgency among utilities seeking firm renewable capacity.
Growth Catalysts
- Investment Tax Credit Expansion:The IRA's enhanced credit structures reduce levelized cost of energy for molten salt tower configurations. Developers in California and Arizona are restructuring power purchase agreements to capture these benefits.
- Grid Operator Capacity Procurement:California Independent System Operator and Electric Reliability Council of Texas are revising resource adequacy frameworks to value dispatchable renewable assets. Thermal storage duration differentiates CSP bids in these solicitations.
- Industrial Process Heat Demand:Chemical manufacturers and mining operators in Nevada and New Mexico are piloting CSP-generated steam for decarbonization. These off-takers seek long-term thermal contracts independent of electricity market volatility.
Market Restraints
- Capital Intensity Barrier:Front-loaded engineering and construction costs for solar tower projects exceed parabolic trough alternatives by substantial margins. Project sponsors face equity commitment thresholds that limit participation to utility-scale developers.
- Heliostat Supply Concentration:Precision mirror manufacturing concentrates among specialized glass and coating suppliers in concentrated industrial zones. Transportation logistics for these large-format components add cost uncertainty to remote southwestern sites.
- Photovoltaic Cost Compression:Utility-scale PV with lithium-ion battery storage has achieved lower overnight capital costs in recent solicitations. This substitute technology captures capacity market share absent storage duration requirements.
Strategic Opportunities
- Green Hydrogen Production Integration:Electrolyzer developers in Texas and Arizona are co-locating with CSP facilities to access high-capacity-factor renewable thermal input. This convergence creates new off-take structures beyond wholesale electricity markets.
- Desalination and Water Treatment:Municipal utilities in California's Central Valley are evaluating CSP-driven thermal desalination for agricultural water supply. These applications value continuous thermal output over electricity generation.
- FERC Order 2222 Aggregation:Distributed thermal storage assets can participate in regional transmission organization markets through aggregated resource frameworks. This regulatory pathway opens revenue stacking for smaller CSP installations.
Industry Challenges
- Specialized EPC Talent Scarcity:Solar tower construction requires welding and precision alignment skills distinct from conventional power plant or PV installation workforces. Training pipelines for heliostat field assembly remain underdeveloped across the southwestern labor market.
- Interconnection Queue Backlogs:Federal Energy Regulatory Commission reform efforts have not eliminated study timeline delays for thermal storage projects in congested transmission zones. Queue position uncertainty complicates project financing commitments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Concentrated Solar Power (CSP) Market |
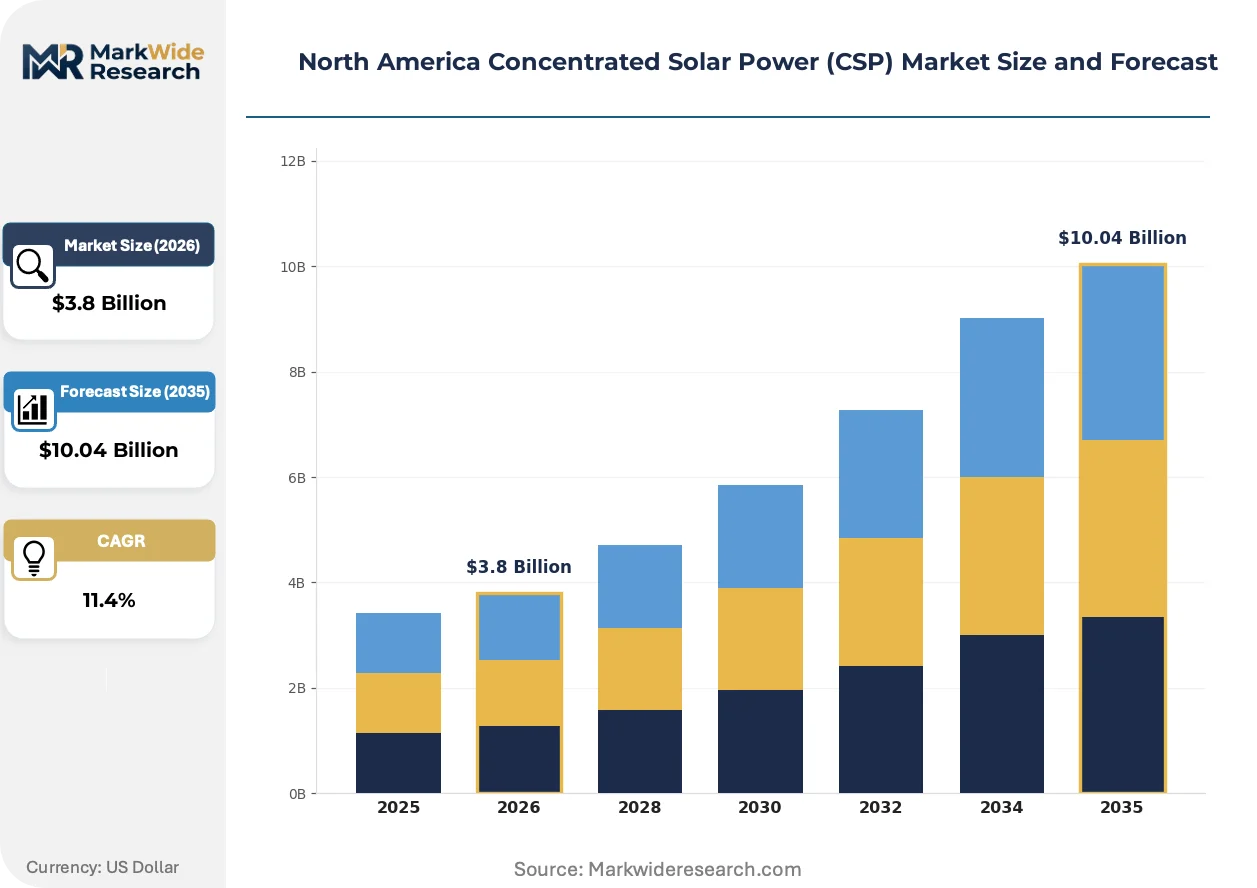
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Parabolic Trough, Solar Tower, Fresnel Reflector, Dish Stirling Component: Solar Receiver, Heat Transfer Fluid, Power Block, Thermal Energy Storage Deployment Mode: Utility-Scale, Commercial, Industrial, Off-Grid Application: Electricity Generation, Water Desalination, Process Heat, Hybrid Systems |
| Companies Covered | EnergyNest AS, ENGIE, BrightSource Energy, Inc., Siemens Energy, NextEra Energy, Inc., ACCIONA, CSP Ultra Lite Solar, Heliogen, Inc., Abengoa, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Concentrated Solar Power (CSP) Market Evolving Landscape
Advanced receiver designs and sCO2 power cycles are compressing the cost gap between CSP and conventional thermal generation. These innovations target higher thermodynamic efficiency and reduced water consumption in arid southwestern deployment environments.
Molten salt receiver technology is absorbing higher flux densities through advanced nickel alloy tubing and improved cavity geometries. Sandia National Laboratories validates these designs at the National Solar Thermal Test Facility in New Mexico. Developers are incorporating these innovations into next-generation tower projects to extend storage duration beyond fifteen hours.
The EPA's greenhouse gas standards for existing power plants are creating compliance pathways for fossil plant operators. Coal and natural gas facilities in Arizona and Nevada are evaluating CSP retrofits for steam cycle integration. These hybrid configurations preserve turbine assets while meeting emissions reduction timelines.
Utility procurement departments are consolidating renewable portfolio standard compliance through single-source firm capacity contracts. California investor-owned utilities prefer CSP with thermal storage over PV-plus-battery for evening ramp requirements. This preference shift concentrates developer attention on storage duration specifications in request-for-proposal documents.
North America Concentrated Solar Power (CSP) Market Segmentation
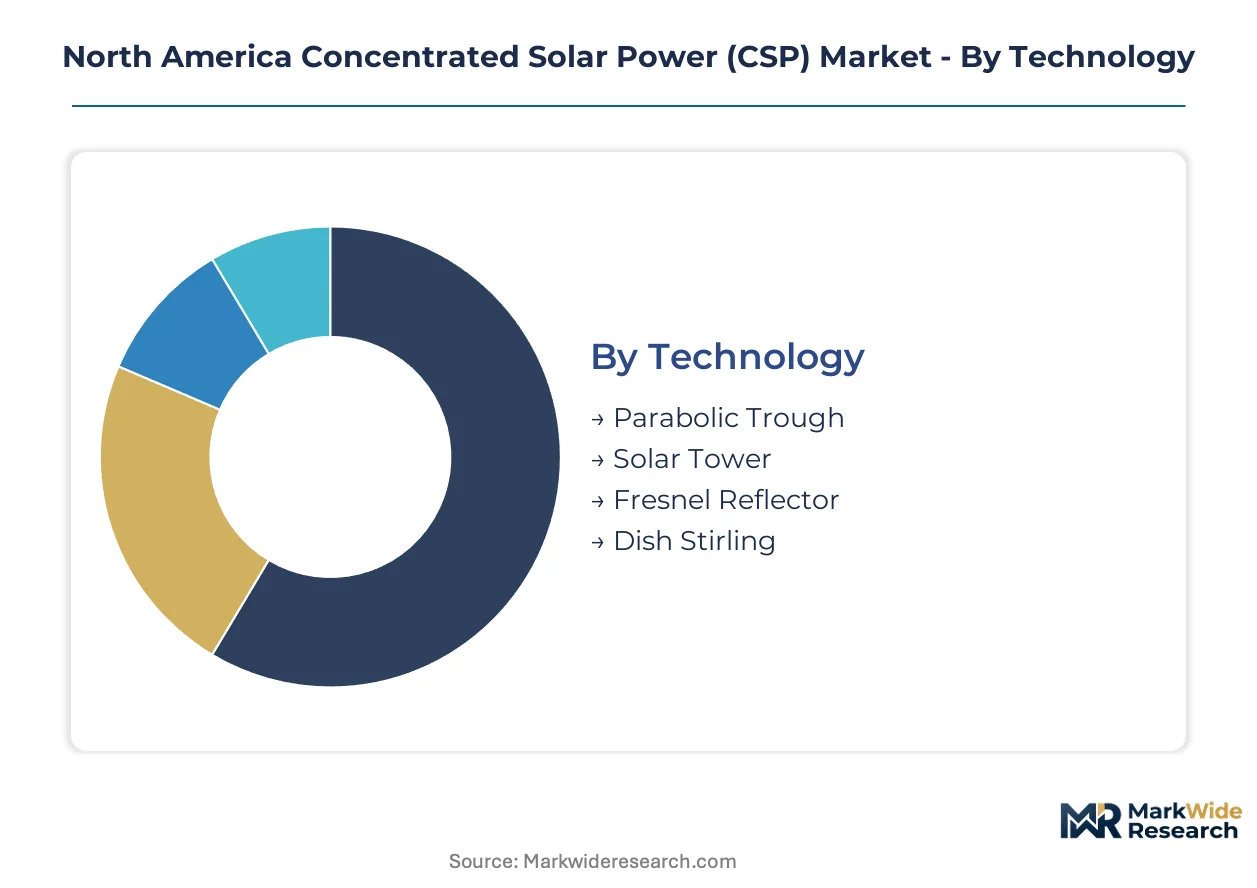
CSP technology selection determines project economics, storage duration capability, and offtake contract structures across southwestern US utility procurement. Component bundling and deployment scale further differentiate buyer risk profiles and financing requirements.
Technology:
Buyers differentiate primarily by capital intensity tolerance and storage duration requirements in resource adequacy solicitations.
- Parabolic Trough:Curved mirrors track the sun to heat synthetic oil circulating through receiver tubes, delivering proven operational performance across decades of commercial deployment. California utilities favor this configuration for baseload contracts where moderate storage duration satisfies evening ramp requirements. Volume sits with Parabolic Trough; growth tilts toward Solar Tower.
- Solar Tower:Heliostat fields concentrate irradiance onto a central receiver, achieving temperatures exceeding 565°C for superior thermodynamic efficiency. Arizona and Nevada developers specify molten salt towers to capture IRA investment tax credits while bidding into CAISO resource adequacy frameworks requiring dispatchable capacity.
- Fresnel Reflector:Flat mirror strips with simplified tracking mechanics reduce precision manufacturing costs for lower-capital installations.
- Dish Stirling:Parabolic dishes drive Stirling engines for modular distributed generation without thermal storage integration.
Cost tiering separates proven trough configurations from tower investments; technology maturity dictates financing terms.
Component:
Margin capture concentrates where thermal storage duration creates competitive differentiation against PV-plus-battery alternatives.
- Solar Receiver:Cavity and external receiver designs absorb concentrated flux to heat transfer media, with nickel alloy tubing specifications validated at Sandia National Laboratories. California tower projects specify advanced receiver geometries to extend operational temperature ranges and storage capacity.
- Thermal Energy Storage:Molten salt tanks decouple generation from irradiance availability, enabling dispatch across evening peak demand periods. Arizona utilities require minimum twelve-hour storage duration in CSP procurement documents to qualify for firm capacity payments.
- Heat Transfer Fluid:Synthetic oils and molten salt mixtures circulate thermal energy between receiver and power block.
- Power Block:Steam turbines and emerging sCO2 cycles convert thermal energy to electricity.
Procurement is shifting toward integrated storage-receiver packages; standalone component sourcing is declining.
Deployment Mode:
Scale determines interconnection voltage level, offtake counterparty type, and FERC jurisdiction applicability.
- Utility-Scale:Projects exceeding 100 MW connect to transmission voltage for wholesale market participation and utility power purchase agreements. Nevada and Arizona host the preponderance of development activity targeting CAISO and ERCOT resource adequacy solicitations.
- Industrial:On-site thermal generation serves mining and chemical process heat demand in Nevada and New Mexico, bypassing electricity market volatility through direct thermal contracts.
- Commercial:Smaller installations serve institutional loads with behind-the-meter configurations.
- Off-Grid:Remote applications supply isolated loads without transmission infrastructure.
Volume concentrates in Utility-Scale; Industrial deployment is expanding most quickly as process heat decarbonization accelerates.
Application:
End-use selection shapes thermal output specifications, storage sizing, and revenue stream diversification.
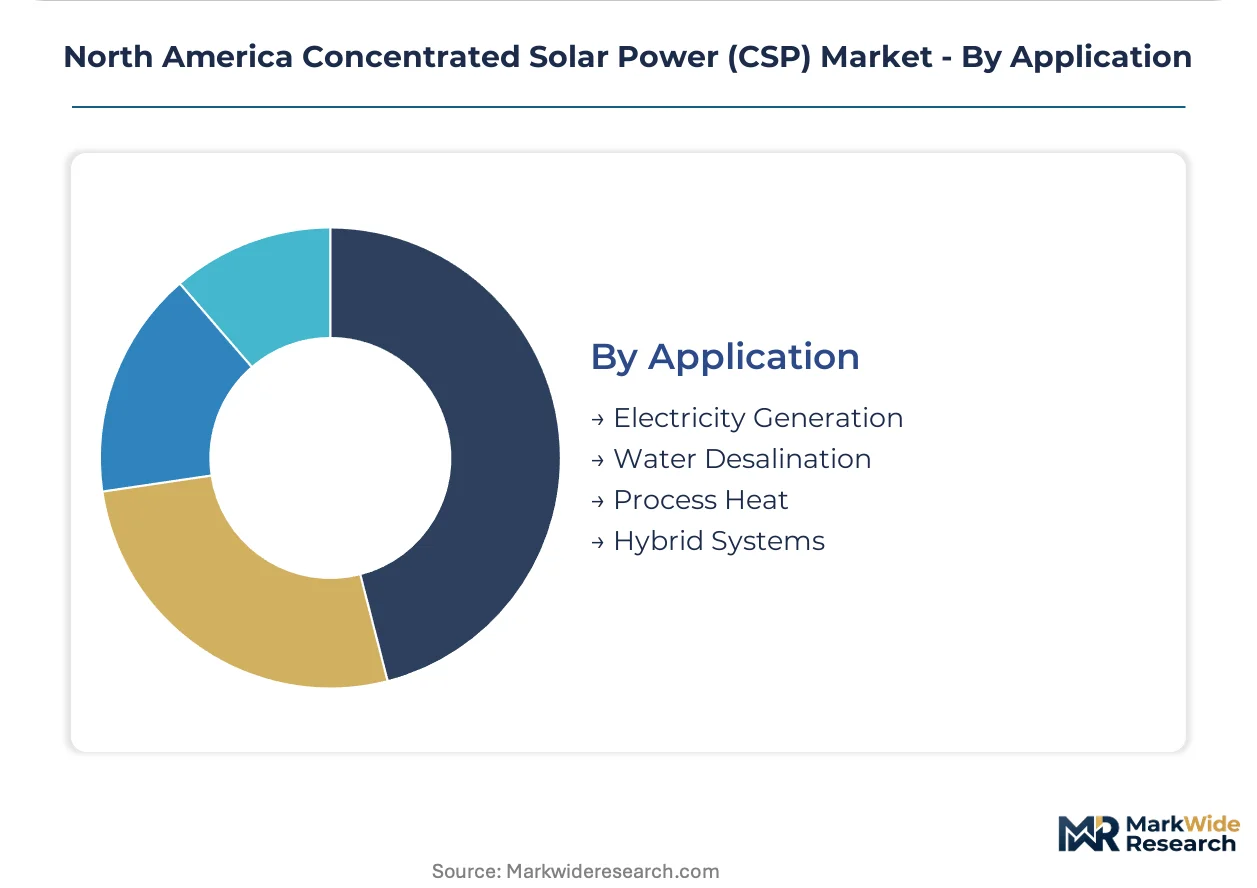
- Electricity Generation:Thermoelectric conversion dominates installed capacity, with molten salt storage enabling dispatchable renewable capacity credit eligibility. California investor-owned utilities specify CSP for evening ramp requirements where PV-plus-battery economics prove insufficient.
- Process Heat:Direct thermal delivery to industrial facilities avoids conversion losses and electricity market exposure. Chemical manufacturers in Texas and Arizona pilot CSP steam supply for decarbonization commitments independent of grid interconnection queues.
- Water Desalination:Thermal desalination applications leverage continuous heat output for agricultural water supply in California's Central Valley.
- Hybrid Systems:CSP retrofits integrate with existing fossil steam cycles for emissions compliance.
Electricity Generation retains volume leadership; Process Heat is gaining share fastest as industrial thermal offtake contracts proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States dominates North American CSP deployment through southwestern utility procurement, while Mexico and Canada occupy nascent development stages with distinct resource and regulatory profiles.
United States
California utilities drive procurement volume through resource adequacy mandates requiring firm evening capacity. The Inflation Reduction Act's standalone storage credit and domestic content bonus reshape project economics across Arizona and Nevada. Developers concentrate activity in California's Mojave Desert, Arizona's Sonoran Desert, and Nevada's Clark County where solar resource quality intersects with transmission access.
Southwestern States
California, Arizona, and Nevada host the preponderance of operational and pipeline capacity targeting CAISO and ERCOT markets. State renewable portfolio standards in California and Arizona create layered compliance demand beyond federal incentives. Imperial Valley, California and Gila Bend, Arizona anchor development clusters where land availability and irradiance levels support utility-scale configurations.
Mexico
High direct normal irradiance in Sonora and Baja California attracts developer interest for industrial process heat applications. The country's national energy regulator shapes market access through wholesale electricity market participation rules. Hermosillo and Mexicali industrial zones pilot CSP thermal supply for mining and chemical operations seeking decarbonization pathways.
Canada
Seasonal solar resource limitations constrain electricity generation economics, though thermal storage applications for remote industrial sites attract niche development. Provincial clean energy mandates in Alberta and Saskatchewan create exploratory procurement frameworks. Calgary and Edmonton engineering clusters support technology evaluation for hybrid renewable thermal systems.
North America Concentrated Solar Power (CSP) Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology supply and project development segments. The market structure concentrates around integrated developers controlling site origination and power purchase agreement execution, with component suppliers occupying tiered positions based on storage duration capabilities. Three archetypes dominate: European-headquartered energy majors leveraging cross-border project experience, specialized solar tower technology developers, and industrial conglomerates extending power generation equipment relationships into renewable thermal. Competitive moves center on strategic partnerships for heliostat field deployment and portfolio diversification into green hydrogen co-location.
Among European-headquartered developers, ENGIE and ACCIONA represent the integrated energy major archetype, while BrightSource Energy, Inc. and Heliogen, Inc. occupy positions within the specialized solar tower technology tier. Siemens Energy anchors the power block and turbine supply segment, extending fossil-era industrial relationships into renewable thermal generation equipment.
| Leading Market Players |
|---|
| EnergyNest AS |
| ENGIE |
| BrightSource Energy, Inc. |
| Siemens Energy |
| NextEra Energy, Inc. |
| ACCIONA |
| CSP Ultra Lite Solar |
| Heliogen, Inc. |
| Abengoa |
| Others |
Value Network & Pricing Analysis
Heliostat precision mirror manufacturing costs cascade through three-tier pricing structures separating molten salt tower configurations from parabolic trough alternatives, with nickel alloy receiver tubing and specialized glass coatings anchoring upstream cost tiers before downstream utility procurement negotiations.
Pricing Analysis
Cost-down pressure on utility-scale tower projects accelerates because photovoltaic-plus-battery alternatives achieve lower overnight capital costs in recent southwestern solicitations. Project-based long-term offtake contracts dominate, with price differentiation resting on storage duration specifications and domestic content bonus qualification under IRA structures. Arizona utilities exhibit highest price sensitivity in resource adequacy bids, while California investor-owned utilities prioritize firm capacity attributes over unit cost minimization.
Supply Chain Analysis
Single-source vulnerability sits with precision heliostat mirror manufacturing concentrated in specialized industrial zones of China, Germany, and the United States. Raw material dependencies center on high-purity nickel alloys for receiver tubing, molten salt mixtures for thermal storage, and low-iron float glass for mirror substrates. Tariff exposure on Chinese-sourced precision glass components elevates supply chain risk for southwestern developers. Distribution runs through EPC contractors with established relationships to utility procurement departments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over thermal storage component manufacturing and heliostat field assembly capabilities determines project margin capture and queue position security.
For Market Incumbents: Hedge against photovoltaic cost compression by securing captive molten salt storage manufacturing capacity and deepening relationships with FERC interconnection queue managers. Prioritize backward integration into precision mirror coating operations to reduce exposure to concentrated supplier geographies. Defend resource adequacy contract positions through extended storage duration offerings that lithium-ion alternatives cannot economically match. For New Entrants and Emerging Players: Capture industrial process heat segments in Nevada and New Mexico where direct thermal contracts bypass electricity market volatility and interconnection queue delays. Target mining and chemical manufacturing facilities with behind-the-meter configurations. Pursue green hydrogen co-location partnerships as an alternative revenue stream to wholesale power markets. For Investors and Strategic Acquirers: FERC Order 2222 implementation progress is the leading indicator that aggregated thermal storage participation will unlock revenue stacking opportunities for distributed CSP assets. Long-term viability hinges on developer capabilities spanning site origination, PPA execution, and integrated storage technology. Monitor CAISO resource adequacy framework revisions as the primary signal for capacity payment structure shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Heliostat Manufacturing Integration | Captive mirror production reduces tariff exposure and logistics uncertainty for southwestern tower projects. |
| Molten Salt Storage Capacity Buildout | Dedicated tank fabrication facilities compress delivery timelines for twelve-hour duration utility specifications. |
| Green Hydrogen Co-location Partnerships | Electrolyzer developers in Texas and Arizona create thermal offtake structures beyond wholesale electricity markets. |
| FERC Order 2222 Aggregation Platforms | Distributed thermal storage assets access regional transmission organization markets through aggregated resource frameworks. |
| Industrial Process Heat Direct Contracts | Mining and chemical facilities in Nevada seek decarbonization pathways independent of grid interconnection queues. |
Research Methodology
EIA generation databases, IEA renewable energy reports, and FERC interconnection queue filings formed the secondary backbone for market sizing and capacity pipeline tracking. Primary interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators supplied forward-looking procurement timelines and technology preference shifts. Bottom-up project-level aggregation and top-down regulatory scenario analysis enabled triangulation across data sources.
Bottom-up modeling traced individual CSP developments through permitting, financing, and construction phases across the projection horizon. Segmentation dimensions included technology configuration, storage duration tier, deployment scale, and regional grid operator jurisdiction. CAGRs derived from installed capacity build-out curves and levelized cost evolution trajectories. Forecast inputs incorporated IRA incentive phase-out assumptions and state renewable portfolio standard trajectory variations.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to interconnection queue reform effectiveness and lithium-ion battery cost decline rates. Forecasts reflect assumptions regarding FERC implementation timelines and state-level clean energy mandate durability. Deviation in photovoltaic-plus-battery storage duration economics would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Grid-Tied Systems Market
Solar Power Systems
Home Solar System Market
Solar Power Systems
Australia Solar Power Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Flexible Solar Panel Market
Solar Power Systems
Photovoltaic Coating Market
Solar Power Systems
Outdoor Solar LED Market
Solar Power Systems
Polycrystalline Solar Panel Market
Solar Power Systems
Southeast Asia Solar Energy Market
Solar Power Systems
Floating Solar System Market
Solar Power Systems
Netherlands Solar Energy Market
Solar Power Systems
Middle East and Africa Solar Photovoltaic (PV) Market
Solar Power Systems
Europe Solar Blanket Market
Solar Power Systems
Thailand Solar Energy Market
Solar Power Systems
South America Solar Tracker Market