
 India Data Center Processor Market | 2026-2036
India Data Center Processor Market Size, Share, and Industry Trends Forecast 2026-2036
India Data Center Processor Market Insights
Domestic semiconductor fabrication capacity is realigning as India builds out its chip ecosystem under government incentive programs. Intel Corporation leverages its established x86 architecture dominance to sustain enterprise server relationships across Indian metros. Advanced Micro Devices Inc. competes aggressively on performance-per-watt metrics in cloud deployments, while NVIDIA Corporation anchors artificial intelligence training clusters with GPU-intensive configurations.
Data center processors are integrated circuits designed to execute computational workloads in centralized server environments, typically fabricated on advanced process nodes below 7 nanometers and optimized for thermal design power envelopes exceeding 150 watts to sustain continuous operation. Their primary purpose is to power cloud infrastructure, enterprise applications, and artificial intelligence inference at scale. CPU deployments still occupy the largest volume share among processor types, though GPU segments command premium pricing for parallel compute workloads. ARM architecture is gaining traction among hyperscalers seeking power efficiency, while x86 retains entrenched positions in legacy enterprise data centers.
India's PLI scheme for semiconductor manufacturing, administered by MeitY, shapes capital allocation toward domestic chip design and eventual fabrication. BIS standards govern electromagnetic compatibility and safety certifications for imported server hardware, affecting market access timelines for foreign suppliers. CDSCO oversight extends to processors embedded in medical imaging and diagnostic equipment, creating specialized compliance pathways. Stakeholders must monitor foundry partnership announcements and state-level data center policies to anticipate procurement shifts.
Market Dynamics
Hyperscale cloud operators are compressing procurement cycles and forcing rapid architectural pivots toward power-efficient compute, while India's PLI scheme for semiconductor manufacturing redirects capital toward domestic chip design capabilities.
Growth Catalysts
- MeitY's PLI scheme:Production-linked incentives for semiconductor manufacturing are accelerating domestic chip ecosystem development and attracting foundry investments to Gujarat and Tamil Nadu.
- AI inference demand:Generative AI deployment across fintech and e-commerce platforms is driving GPU-intensive configurations into Mumbai and Bangalore cloud regions.
- ARM architecture migration:Hyperscalers seeking thermal efficiency are adopting ARM-based processors for scale-out workloads, displacing legacy x86 dominance in new-build facilities.
Market Restraints
- Advanced node dependency:Domestic players lack access to sub-5 nanometer fabrication, forcing reliance on Taiwan and South Korea foundries for high-performance processors.
- Power infrastructure constraints:Maharashtra and Karnataka grid stability issues limit data center density, capping processor deployment per facility.
- BIS certification timelines:Electromagnetic compatibility testing for imported server hardware extends market access by 4-6 months, delaying hyperscale refresh cycles.
Strategic Opportunities
- Edge compute expansion:Tier-2 cities including Hyderabad, Chennai, and Pune present underpenetrated demand for low-latency processor deployments.
- CDSCO medical imaging pathway:Processors embedded in diagnostic equipment face specialized compliance requirements, creating premium positioning for validated silicon.
- Chiplets and advanced packaging:Domestic assembly and test capabilities are converging with 2.5D packaging technology, enabling value capture without full fabrication.
Industry Challenges
- VLSI design talent scarcity:India's semiconductor workforce lacks depth in physical design and verification, constraining domestic chip development velocity.
- Legacy x86 integration friction:Enterprise data centers in Delhi-NCR face complex workload migration costs when adopting ARM or alternative architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Data Center Processor Market |
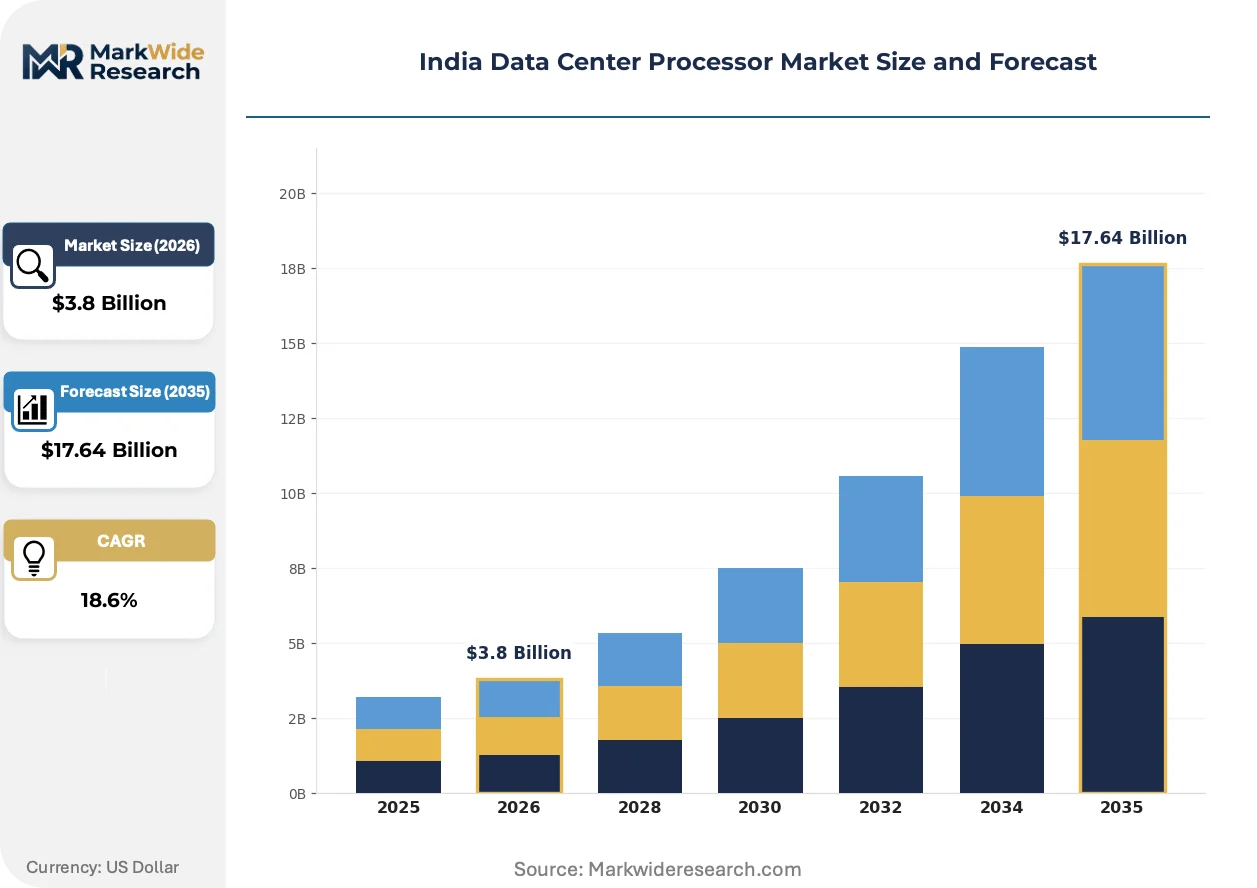
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $17.64 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Processor Type: ASIC, FPGA, CPU, GPU End User: Cloud Service Providers, Enterprises, Telecommunications, Colocation Providers Product Offering: Entry-Level, Mid-Range, High-Performance, Customized Solutions Technology: X86 Architecture, ARM Architecture, RISC-V, Power Architecture |
| Companies Covered | Intel Corporation, Advanced Micro Devices Inc., NVIDIA Corporation, Ampere Computing LLC, Arm Limited, Qualcomm Technologies, Broadcom Inc., Marvell Technology, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Data Center Processor Market Trends and Innovations
Compute architectures are fragmenting across workload-specific optimizations, with power efficiency and thermal density now dominating procurement criteria over raw performance benchmarks.
Chiplet-based processor designs are rewriting how silicon scalability is achieved in Indian data centers. AMD and Intel have both transitioned to disaggregated die architectures that mix process nodes within a single package. Hyperscalers in Bangalore are adopting these configurations for mixed workloads. This modular approach is rewriting total cost of ownership calculations by extending socket compatibility across generations.
India's PLI scheme for semiconductor manufacturing is reshaping capital allocation timelines for domestic processor ventures. MeitY incentive structures require minimum investment thresholds and local value-add commitments. Domestic design houses in Noida and Hyderabad are responding by prioritizing chiplet assembly and test capabilities over full mask-set development.
Power purchase agreement structures are altering how processor procurement decisions flow through data center operators. Large cloud providers are now signing 10-15 year renewable energy contracts before committing to facility expansions. This behavioral shift is most visible in Maharashtra, where Maharashtra State Electricity Regulatory Commission tariffs have pushed operators toward captive solar installations that constrain processor power envelope selections.
India Data Center Processor Market Segmentation
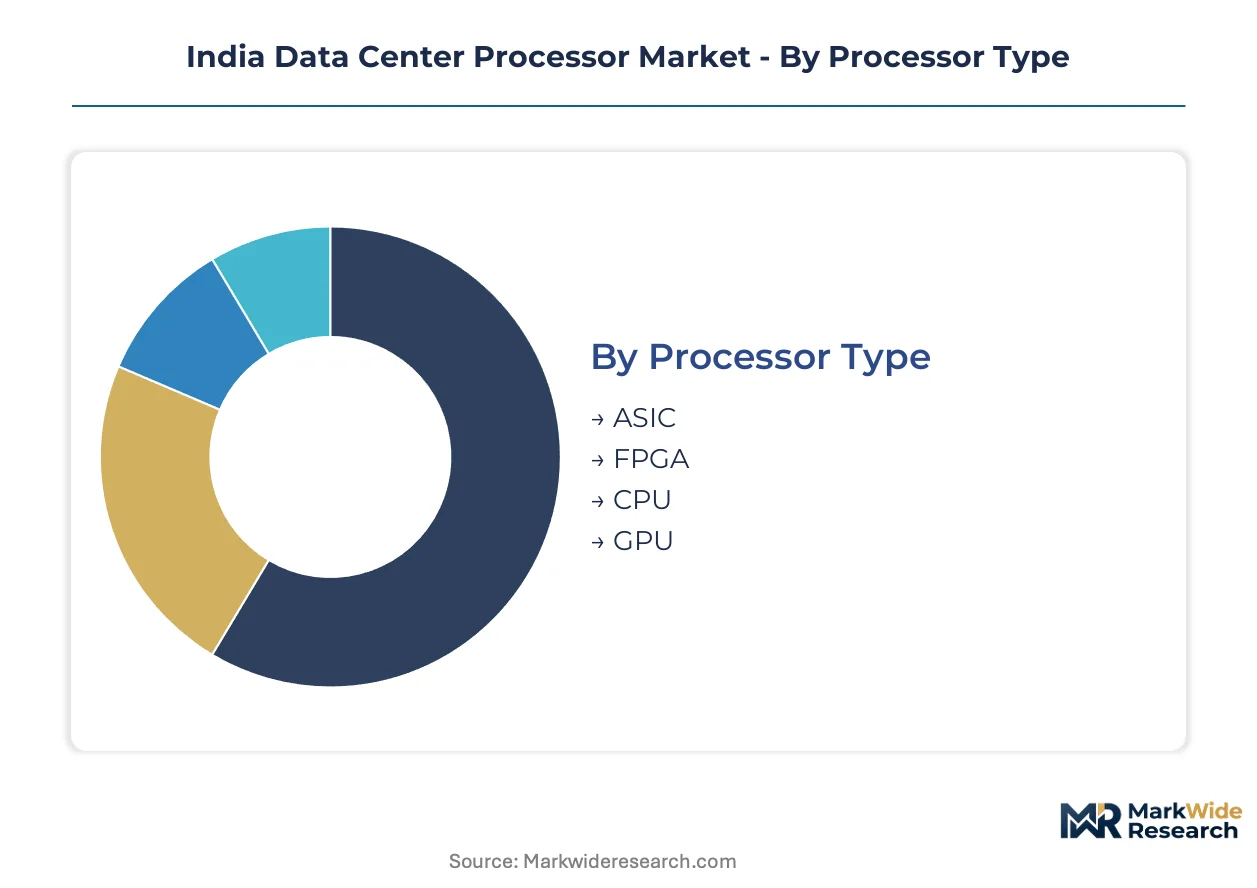
Processor segmentation in India's data center market reveals how workload specialization, power constraints, and cloud procurement patterns are fragmenting demand across architectural lines. Understanding these divisions exposes where capital is concentrating and which technology bets hyperscalers are placing.
Processor Type:
Architectural specialization determines thermal envelope, software compatibility, and total cost of ownership across Mumbai and Bangalore facilities.
- CPU:General-purpose x86 and ARM cores handle the bulk of transactional and containerized workloads. Maharashtra and Karnataka cloud regions deploy CPU-dense configurations for enterprise SaaS and database operations, constrained by grid stability limits on per-rack power density.
- GPU:Parallel compute engines from NVIDIA and AMD dominate AI training clusters in Bangalore's hyperscale campuses. Generative AI inference demand from fintech and e-commerce platforms is forcing rapid procurement cycles for H100 and MI300 configurations despite import certification delays.
- ASIC:Workload-specific silicon accelerates inference at lower wattage for video transcoding and recommendation engines.
- FPGA:Reconfigurable logic serves niche financial services applications requiring deterministic latency in Mumbai's trading infrastructure.
CPU leads on scale; GPU leads on momentum.
End User:
Procurement authority and volume commitments vary sharply across buyer categories, reshaping vendor engagement models.
- Cloud Service Providers:AWS, Azure, and Google Cloud drive 60-70% of processor volume through direct foundry relationships and custom silicon programs. Their Maharashtra and Karnataka region expansions are compressing refresh cycles to 18-24 months.
- Enterprises:Delhi-NCR financial services and manufacturing firms maintain legacy x86 estates with 4-5 year replacement horizons, creating integration friction for ARM migration.
- Telecommunications:Jio and Airtel edge deployments prioritize power-efficient processors for 5G core and RAN virtualization in Tier-2 cities.
- Colocation Providers:NTT, STT GDC, and CtrlS aggregate fragmented enterprise demand, standardizing on mid-range configurations to preserve multi-tenant flexibility.
Cloud Service Providers dominate procurement volume; Telecommunications is expanding most quickly at the edge.
Product Offering:
Price-performance positioning stratifies across certification tiers, support levels, and thermal design power envelopes.
- High-Performance:250W+ TDP processors with liquid cooling requirements anchor AI training clusters. Bangalore hyperscalers absorb premium pricing for HBM-equipped configurations to minimize training job completion times.
- Mid-Range:150-200W SKUs balance core density and power draw for general-purpose cloud compute. This tier captures the largest unit volume as colocation providers standardize configurations.
- Entry-Level:Low-core-count processors serve branch office virtualization and development environments with minimal cooling overhead.
- Customized Solutions:Bespoke SKUs for MeitY PLI-compliant domestic assembly programs, featuring India-specific packaging and test flows.
Mid-Range commands the deepest volume penetration; High-Performance claims the steepest expansion trajectory.
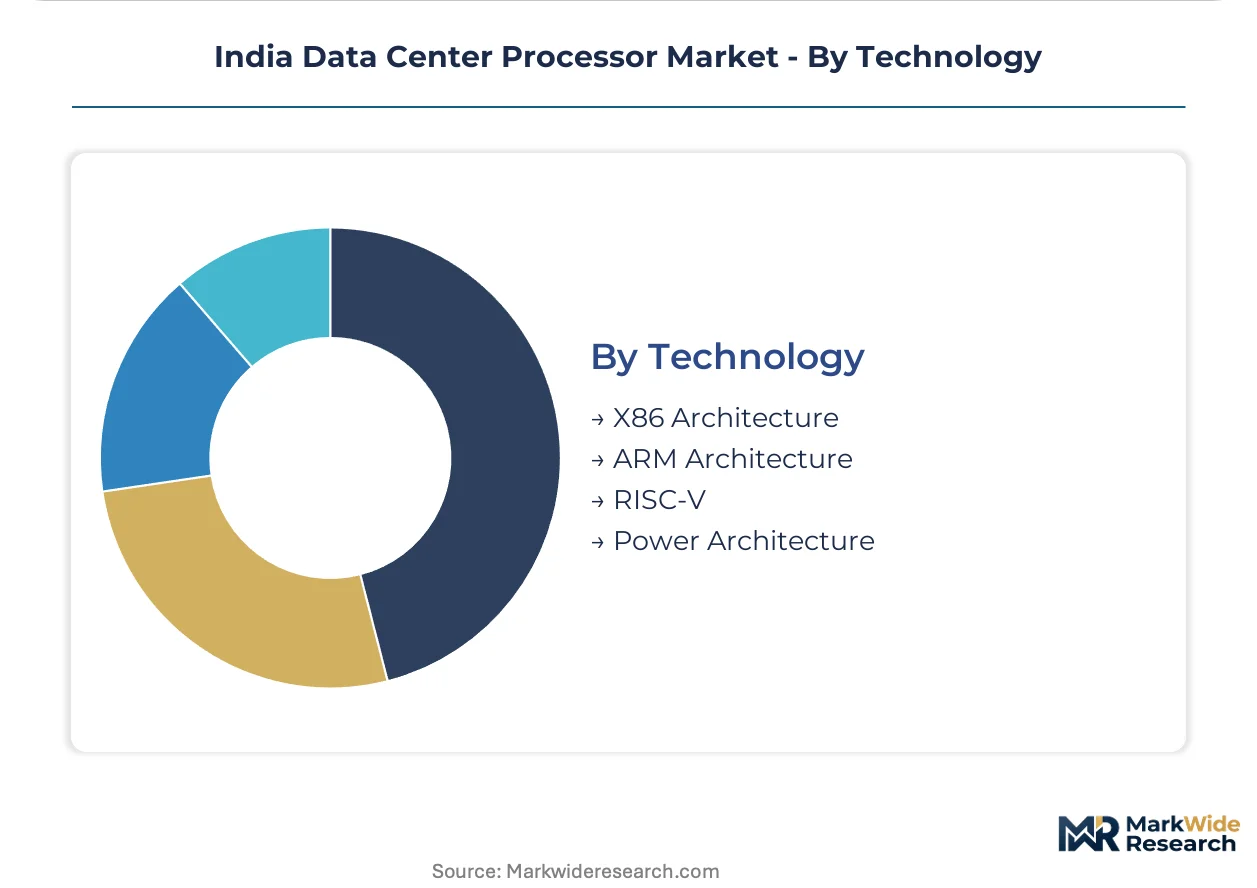
Technology:
Instruction set architecture choices are locking in ecosystem dependencies that persist across multiple refresh cycles.
- X86 Architecture:Intel and AMD's entrenched software compatibility preserves dominance in legacy enterprise data centers. Delhi-NCR financial services firms face complex migration costs when evaluating alternatives.
- ARM Architecture:AWS Graviton and Ampere Altra deployments are gaining share in Bangalore hyperscale facilities seeking wattage reductions for scale-out workloads. MeitY PLI incentives favor domestic ARM design ventures.
- RISC-V:Open instruction set architectures are attracting domestic design houses in Hyderabad for embedded control and security applications.
- Power Architecture:IBM's proprietary ecosystem retains niche presence in high-reliability banking infrastructure with decades-long platform commitments.
X86 Architecture maintains installed base dominance; ARM Architecture is gaining share fastest among new-build capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage between Maharashtra's established data center policy and Karnataka's newer incentive structures is redistributing processor procurement volumes across western and southern India. Cost-of-compliance gaps in power infrastructure approvals are accelerating facility development in Tamil Nadu and Gujarat.
Maharashtra
Hyperscale cloud operators are expanding Mumbai cloud regions to capture financial services latency requirements. The Maharashtra State Electricity Regulatory Commission's renewable energy tariffs are pushing operators toward captive solar installations that constrain processor power envelope selections. Navi Mumbai and Thane industrial corridors are absorbing the bulk of H100 and MI300 GPU deployments for AI training clusters.
Karnataka
Bangalore's hyperscale campuses are driving ARM architecture adoption for scale-out workloads seeking thermal efficiency. The state's Electronics, IT and BT Department incentive structures are accelerating foundry partnership announcements for domestic chip assembly. Whitefield and Devanahalli data center clusters are standardizing on chiplet-based processor configurations for mixed workload environments.
Tamil Nadu
Semiconductor packaging and test facilities are concentrating in Sriperumbudur and Oragadam industrial zones under MeitY PLI scheme allocations. The state's Electronics Manufacturing Policy is attracting domestic design houses prioritizing 2.5D packaging capabilities over full mask-set development. Chennai's emerging cloud region is capturing spillover demand from Bangalore capacity constraints.
Gujarat
Dholera and Sanand industrial corridors are positioning for foundry investments under central government semiconductor incentives. The Gujarat Industrial Development Corporation's land allotment policies are compressing facility development timelines relative to Maharashtra. Ahmedabad's data center pipeline remains nascent but is attracting processor procurement pre-commitments from telecommunications operators.
Telangana
Hyderabad's Tier-2 city status is creating underpenetrated demand for edge compute processor deployments in 5G core virtualization. The state's T-Hub electronics ecosystem is incubating domestic ARM design ventures seeking PLI compliance. The Financial District and Gachibowli corridors are absorbing mid-range CPU configurations for enterprise SaaS workloads.
India Data Center Processor Market Competitive Landscape
United States-based semiconductor giants anchor the premium processor tier; domestic Indian design ventures and assembly specialists hold emerging positions in the value chain. The market structure is consolidating around three global x86 and GPU architects while fragmenting across ARM ecosystem licensees and domestic chiplet assemblers. Strategic archetypes include architecture licensors, foundry-dependent fabless designers, and PLI-compliant domestic packaging houses. Competitive moves center on custom silicon programs for hyperscalers and backward integration into advanced packaging capabilities.
Within the established architecture tier, Intel Corporation and NVIDIA Corporation exemplify divergent positioning strategies, with the former preserving enterprise software compatibility and the latter anchoring AI training infrastructure. Advanced Micro Devices Inc. occupies a hybrid position across both general-purpose and accelerated compute domains. These three entities represent the dominant competitive anchors shaping procurement patterns across Maharashtra and Karnataka cloud regions.
| Leading Market Players |
|---|
| Intel Corporation |
| Advanced Micro Devices Inc. |
| NVIDIA Corporation |
| Ampere Computing LLC |
| Arm Limited |
| Qualcomm Technologies |
| Broadcom Inc. |
| Marvell Technology |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Hyperscale procurement compression toward 18-24 month refresh cycles is forcing foundry partners to accelerate wafer starts and absorb upfront mask costs, compressing margin buffers across Taiwan and South Korea suppliers while pushing domestic assembly houses toward volume-tier pricing concessions.
Pricing Analysis
Distributor margins on imported server processors typically capture 8-12 percent before customs clearance and BIS certification overhead. Three-tier pricing structure across premium AI accelerators, standard cloud CPUs, and economy edge configurations stratifies by thermal design power envelope and HBM memory integration. Pricing pressure stems from hyperscaler direct-foundry negotiations that bypass traditional channel markups. Cloud service providers exhibit lowest price sensitivity due to workload-optimized total cost of ownership calculations; colocation providers remain most sensitive, standardizing on mid-range SKUs to preserve multi-tenant flexibility.
Supply Chain Analysis
Regional distribution centers in Singapore and Dubai anchor hub-and-spoke patterns for processor shipments into Mumbai and Chennai ports. Wafer fabrication concentrates in Taiwan and South Korea; advanced packaging and test operations are expanding in Tamil Nadu under MeitY PLI incentives. Silicon wafers, EUV photoresists, and HBM memory stacks constitute critical input dependencies. Single-source vulnerability around TSMC's leading-edge node allocation creates exposure for Indian hyperscaler procurement timelines. Distribution runs through authorized distributors with BIS pre-certification capabilities, extending landed cost structures by 4-6 months relative to direct import.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in this market rests on domestic value-add capture through chiplet assembly and test capabilities, coupled with premium-tier GPU configurations commanding pricing power in Bangalore AI clusters.
For Market Incumbents: Deepen backward integration into advanced packaging capabilities at Tamil Nadu facilities to offset foundry margin compression. Secure captive supply of HBM memory through long-term procurement commitments with Korean suppliers. ARM architecture migration among hyperscalers threatens x86 socket dominance; defend enterprise Delhi-NCR relationships through workload migration consulting and extended support contracts. For New Entrants and Emerging Players: Begin with domestic chiplet assembly and test services for PLI-compliant value capture without full mask-set development investment. Target Telangana edge compute deployments for 5G core virtualization processors, where incumbent presence remains thin. Pursue CDSCO medical imaging certification pathway as differentiated positioning against commodity server silicon competitors. For Investors and Strategic Acquirers: Asymmetric upside sits with domestic packaging houses possessing 2.5D interposer capabilities and MeitY incentive qualification. Five-to-ten year viability favors assets with foundry partnership visibility rather than pure-play design ventures lacking fabrication access. Monitor Maharashtra State Electricity Regulatory Commission tariff announcements as signal for captive renewable energy investment intensity and associated processor power envelope constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Chiplet Assembly Scale-Up | Captures PLI value-add thresholds without EUV fabrication dependency in Tamil Nadu corridors. |
| Hyperscaler Custom Silicon Partnership | Locks volume commitments through AWS Graviton-class ARM design collaborations for Bangalore facilities. |
| HBM Supply Security Agreement | Secures memory stack allocation priority for MI300 and H100 configurations amid GPU demand surge. |
| CDSCO Medical Imaging Certification | Opens premium positioning in diagnostic equipment processors with specialized compliance moats. |
| Captive Renewable Energy Procurement | Aligns Maharashtra facility expansions with MSEEC tariff structures constraining processor power envelopes. |
Research Methodology
Multiple input streams — hyperscaler procurement officer interviews, foundry partnership announcements, and BIS certification database tracking — were reconciled against secondary validation from MeitY PLI scheme disclosures, CDSCO medical device filings, and Maharashtra State Electricity Regulatory Commission tariff orders. Primary engagement spanned cloud infrastructure architects, semiconductor packaging engineers, and data center facility planners across Mumbai, Bangalore, and Chennai clusters. Secondary sources included SEC 10-K filings from listed processor vendors, customs import records for server hardware, and state-level electronics manufacturing policy documents. Bottom-up unit deployment estimates triangulated against top-down foundry wafer allocation disclosures.
Historical hyperscaler capex patterns cross-referenced against panel input from procurement directors established baseline growth trajectories across the projection horizon. Segmentation modeling spanned processor type, end user category, product offering tier, and instruction set architecture dimensions. CAGRs derived from unit shipment elasticity to cloud region expansion announcements and AI training cluster deployment schedules. Forecast inputs incorporated foundry capacity buildout timelines, state-level data center policy incentive structures, and grid stability constraints on facility power density.
Several conditions sit outside the modeled scope, including geopolitical disruption to Taiwan Strait shipping lanes, unannounced revisions to MeitY PLI minimum investment thresholds, and breakthroughs in domestic sub-5 nanometer fabrication capability. Forecasts reflect assumptions about continued hyperscaler cloud region expansion in Maharashtra and Karnataka, ARM architecture share gains in new-build facilities, and stable BIS certification processing timelines. Stakeholders should weight assumptions against their own operating context and monitor foundry partnership announcements for procurement timing inflections.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
China Automotive Microcontroller Market
Chipset and Processors
Microprocessor Market
Chipset and Processors
AI Chipsets Market
Chipset and Processors
Global Microcontroller (MCU) Market
Chipset and Processors
Automotive Infotainment SOC Market
Chipset and Processors
Digital Signal Controller and Processor Market
Chipset and Processors
Chiplet Technology Market
Chipset and Processors
United States Data Center Processor Market
Chipset and Processors
Europe 8- Bit Microcontroller Market
Chipset and Processors
PLL Clock Generator Market
Chipset and Processors
Combo Chip Market
Chipset and Processors
Global Automotive Self-Driving Chip Market
Chipset and Processors
Automotive Battery Management System (BMS) Chip Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Germany Data Center Processor Market