
 Power Over Ethernet (Poe) Chipsets Market | 2026-2036
Power Over Ethernet (Poe) Chipsets Market Size, Share, and Industry Trends Forecast 2026-2036
Power Over Ethernet (Poe) Chipsets Market Intelligence
Asian semiconductor foundries are pivoting toward higher-margin PoE chipset production as Ethernet-powered device volumes climb. Texas Instruments leverages its analog power management heritage to sustain design wins across industrial automation controllers. Broadcom anchors enterprise switch silicon with integrated PoE controllers, while Microchip Technology competes through specialized Powered Device ICs for security camera OEMs.
Power over Ethernet chipsets are mixed-signal integrated circuits that combine data-path Ethernet PHYs with DC-DC power controllers to deliver up to 90 watts over standard CAT5e/CAT6 cabling, governed by IEEE 802.3af/at/bt standards. These devices eliminate separate electrical infrastructure for networked endpoints, serving commercial building automation, telecommunications infrastructure, and physical security systems. Multi-port chipsets dominate volume shipments as enterprise switches consolidate power delivery across dozens of edge connections, while 802.3bt technology leads value growth by supporting high-draw applications like pan-tilt-zoom cameras and digital signage. Powered Device ICs concentrate margin pools where thermal efficiency and protocol compliance determine OEM qualification timelines.
FCC equipment authorization requirements shape US market access for PoE chipsets emitting electromagnetic interference, while CE marking under the EU Radio Equipment Directive governs European commercial deployments. IEEE 802.3bt compliance testing, administered through accredited laboratories, functions as a de facto gatekeeper for interoperability certification among switch vendors and endpoint manufacturers. Stakeholders must monitor whether emerging national building codes mandate PoE as primary power for low-voltage lighting and environmental sensors, as this regulatory trajectory would structurally expand addressable unit demand beyond traditional networking applications.
Market Dynamics
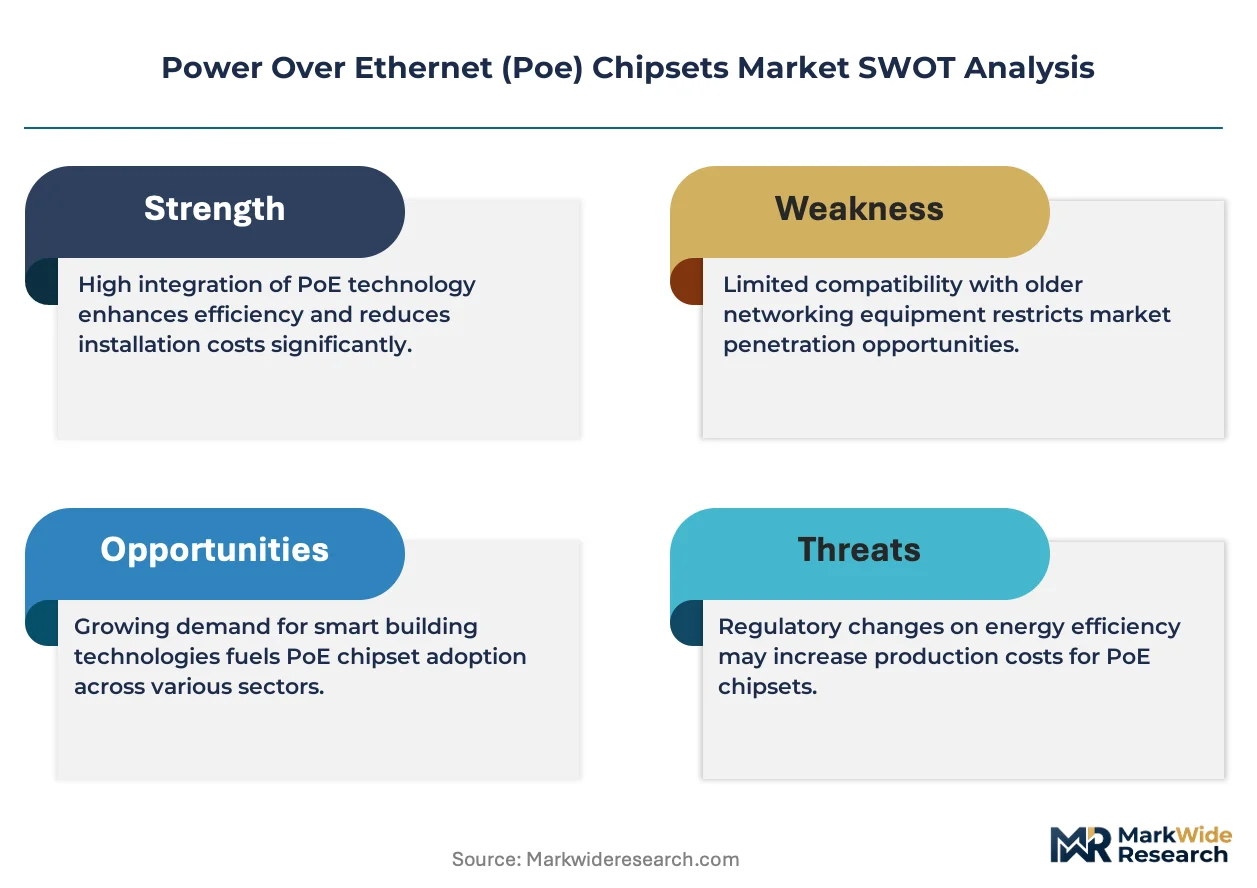
The IEEE 802.3bt standard's 90-watt power ceiling is redrawing competitive boundaries by enabling PoE chipsets to displace traditional AC infrastructure in high-draw industrial and medical equipment categories previously unreachable for Ethernet-powered solutions.
Growth Catalysts
- Smart Building Mandates:Municipal energy codes in Germany and California now incentivize PoE lighting retrofits, accelerating Powered Device IC procurement for LED fixture OEMs.
- Data Center Buildouts:Hyperscale facilities in the United States and China are standardizing on multi-port PoE switches to consolidate power management for server rack environmental sensors.
- Healthcare Infrastructure Modernization:Hospital IT departments are deploying 802.3bt-powered patient monitoring carts to eliminate AC outlet dependency in clinical workflows.
Market Restraints
- Silicon Supply Concentration:Advanced BCD-on-SOI wafer capacity remains captive to a handful of Taiwanese and Korean foundries, constraining multi-port PSE controller output.
- Thermal Management Costs:High-current 802.3bt implementations require magnetics and PCB substrates with enhanced heat dissipation, inflating bill-of-materials for mid-tier switch vendors.
- Copper Price Volatility:CAT6A cabling represents a material cost exposure for large-scale PoE deployments, with commodity fluctuations directly impacting project ROI calculations.
Strategic Opportunities
- Industrial IoT White Space:Factory automation integrators in Japan and South Korea are piloting PoE-powered motor controllers and pneumatic valve arrays for predictive maintenance networks.
- Edge AI Convergence:The pairing of 802.3bt power delivery with onboard GPU acceleration is creating a new endpoint category for computer vision security applications.
- EU Green Deal Alignment:Building renovation wave funding streams in France and Italy are structurally favoring PoE lighting over conventional electrical retrofits through embodied carbon accounting rules.
Industry Challenges
- Interoperability Certification Bottlenecks:IEEE 802.3bt compliance testing queue times at accredited laboratories are extending OEM product launch timelines by four to six months.
- Mixed-Signal Talent Scarcity:The specialized skill set spanning Ethernet PHY design and high-efficiency DC-DC conversion is concentrating among senior engineers at a shrinking pool of analog semiconductor specialists.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Power Over Ethernet (Poe) Chipsets Market |
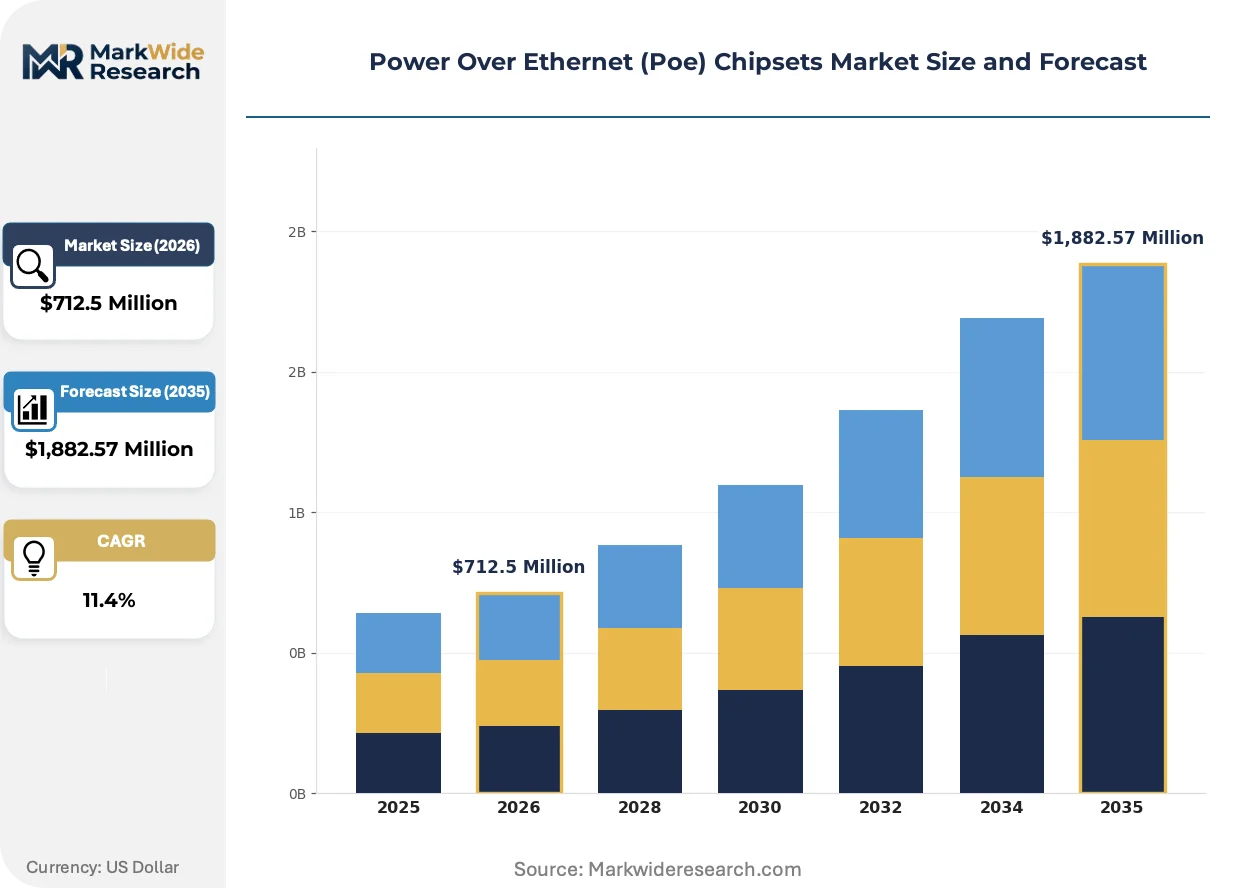
| Market Size in 2026 | $712.5 Million |
| Market Size in 2035 | $1,882.57 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Port Chipsets, Multi-Port Chipsets, Integrated Controllers, Power Sourcing Equipment ICs, Powered Device ICs Technology: 802.3af, 802.3at, 802.3bt, Passive PoE, Proprietary PoE Application: IP Cameras, VoIP Phones, Wireless Access Points, LED Lighting, Network Switches End User: Telecommunication Providers, Data Center Operators, Smart Building Integrators, Security Service Firms |
| Companies Covered | Texas Instruments Incorporated, Broadcom Inc., Microchip Technology Inc., Analog Devices Inc., STMicroelectronics N.V., NXP Semiconductors N.V., ON Semiconductor Corporation, Marvell Technology Inc., Realtek Semiconductor Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Power Over Ethernet (Poe) Chipsets Market Strategic Shifts & Innovations
Power delivery architectures are fragmenting into application-optimized configurations, with chipset vendors racing to embed intelligence that simplifies thermal design and protocol negotiation for non-traditional PoE endpoints.
Silicon vendors are modularizing their PoE controller portfolios into discrete PSE and PD building blocks that system designers can recombine across industrial, healthcare, and smart building applications. This architectural shift lets switch OEMs source power management and data-path functions from separate suppliers, compressing development cycles for specialized multi-port configurations. The disaggregation is accelerating adoption in mid-market segments previously locked out by integrated chipset minimum order constraints.
CE marking under the EU Radio Equipment Directive is tightening electromagnetic compatibility thresholds for PoE chipsets deployed in medical environments, forcing redesigns of magnetics and isolation architectures. The industrial consequence is a bifurcation between standard commercial-grade controllers and higher-margin medical-certified variants with extended documentation packages. German and French healthcare IT procurement teams are now requiring pre-submitted CE technical files as a gatekeeping criterion in switch vendor qualification.
Facility managers are consolidating vendor relationships by specifying switch platforms that bundle power delivery with network management software, displacing the historical practice of sourcing PoE injectors and Ethernet infrastructure separately. This preference compression is reshaping channel economics, with value-added distributors in the United States and China capturing larger project margins through integrated solution bundling. The shift is most visible in K-12 education and municipal building retrofits where capital budgets favor single-source accountability over component-level optimization.
Power Over Ethernet (Poe) Chipsets Market Segmentation
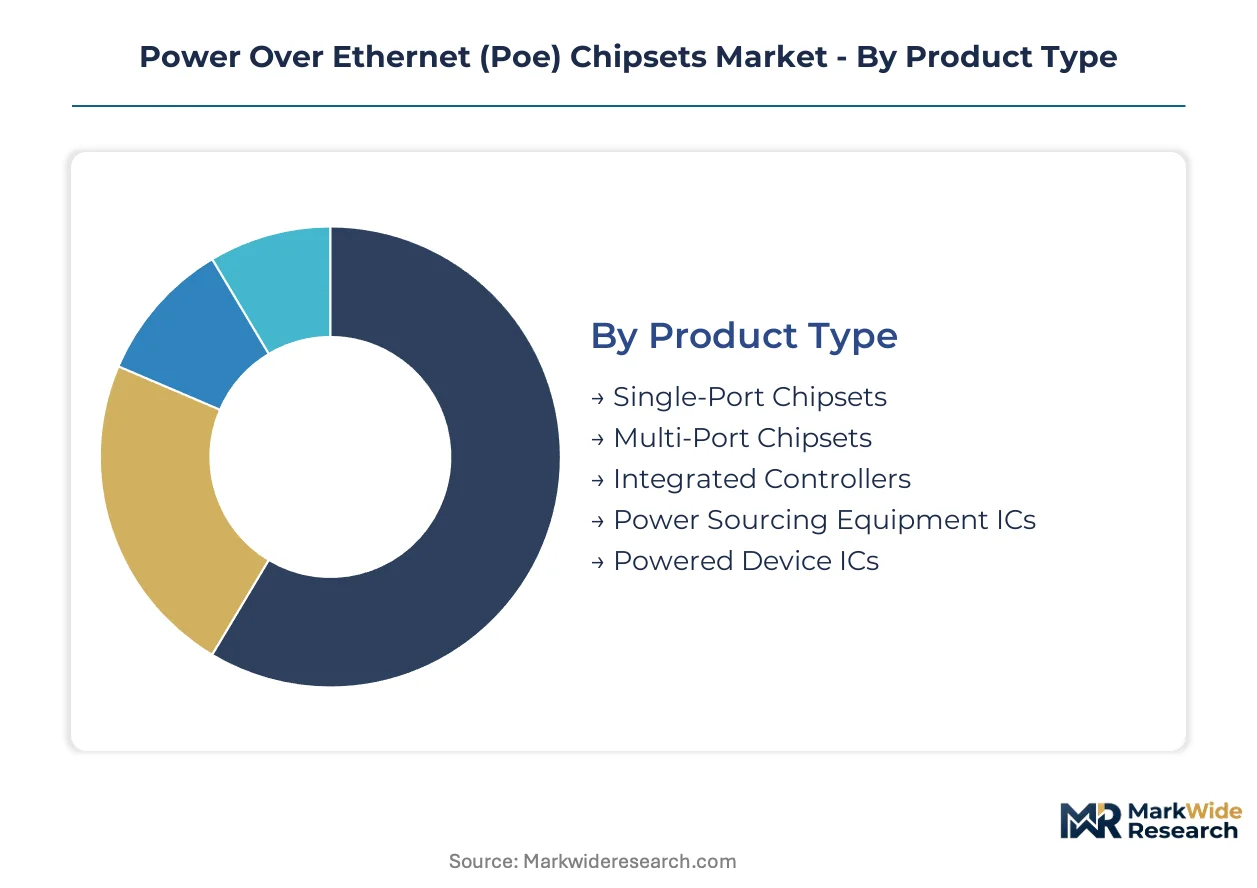
PoE chipset segmentation reveals how power delivery architectures fragment across port density, protocol generation, and endpoint power requirements. Vendors configure their product portfolios around these axes to capture margin pools in enterprise switching, industrial automation, and smart building infrastructure.
Product Type:
Wafer capacity allocation at Taiwanese foundries concentrates most heavily on multi-port configurations serving enterprise switch OEMs.
- Multi-Port Chipsets:These devices integrate PSE controllers for 8 to 48 ports per chip, combining Ethernet PHYs with per-port power management. Data center operators in the United States and China specify these for rack-level environmental sensor networks where consolidated power delivery reduces cabling complexity.
- Powered Device ICs:PD controllers handle signature detection, classification, and DC-DC conversion for endpoint devices. LED lighting OEMs in Germany source these for fixture-integrated drivers where thermal efficiency and IEEE 802.3bt compliance determine qualification timelines.
- Single-Port Chipsets:Discrete PSE or PD controllers for specialized industrial endpoints where port density is not a constraint.
- Integrated Controllers:Combined PSE and PD functionality on single die for compact embedded systems.
- Power Sourcing Equipment ICs:Dedicated PSE controllers without integrated PHYs, allowing switch designers to source data-path and power functions from separate suppliers.
Multi-port configurations absorb the bulk of installed capacity; Powered Device ICs are expanding most quickly as smart building mandates accelerate fixture-level procurement.
Technology:
Protocol generation determines the addressable power envelope and corresponding magnetics requirements for each design win.
- 802.3bt:The 90-watt standard enables pan-tilt-zoom cameras, digital signage, and patient monitoring carts. Hospital IT departments in France deploy these for mobile clinical workstations where AC outlet elimination streamlines workflow redesign.
- 802.3at:The 30-watt mid-power standard dominates wireless access point and VoIP phone installations. Enterprise campus networks in Germany standardize on this protocol for Wi-Fi 6 access point backhaul where power reserves accommodate peak transmit loads.
- 802.3af:The original 15.4-watt standard persists in legacy security camera and basic sensor deployments.
- Passive PoE:Non-standard implementations using fixed voltage injection for proprietary industrial equipment.
- Proprietary PoE:Vendor-specific extensions beyond IEEE specifications for specialized telecommunications infrastructure.
802.3at maintains the largest installed base; 802.3bt is gaining share fastest as high-draw applications displace traditional AC infrastructure.
Application:
Endpoint power requirements vary dramatically across use cases, forcing chipset vendors to optimize thermal profiles and protocol stacks for specific load characteristics.
- IP Cameras:Surveillance endpoints span 802.3af through 802.3bt depending on motorization and heater requirements. Security service firms in the United States specify 802.3bt for perimeter PTZ installations where cold-weather operation demands sustained power reserves.
- LED Lighting:PoE-powered fixtures integrate PD controllers with constant-current drivers. Smart building integrators in California leverage municipal energy code incentives to specify these for commercial retrofits where centralized power management enables granular dimming control.
- Wireless Access Points:Enterprise Wi-Fi infrastructure represents stable volume demand across 802.3at implementations.
- VoIP Phones:Mature 802.3af endpoint category with replacement-driven demand cycles.
- Network Switches:Infrastructure equipment incorporating PSE functionality for downstream power distribution.
IP cameras command the largest dedicated silicon allocation; LED lighting is climbing the fastest as building codes structurally favor PoE retrofits.
End User:
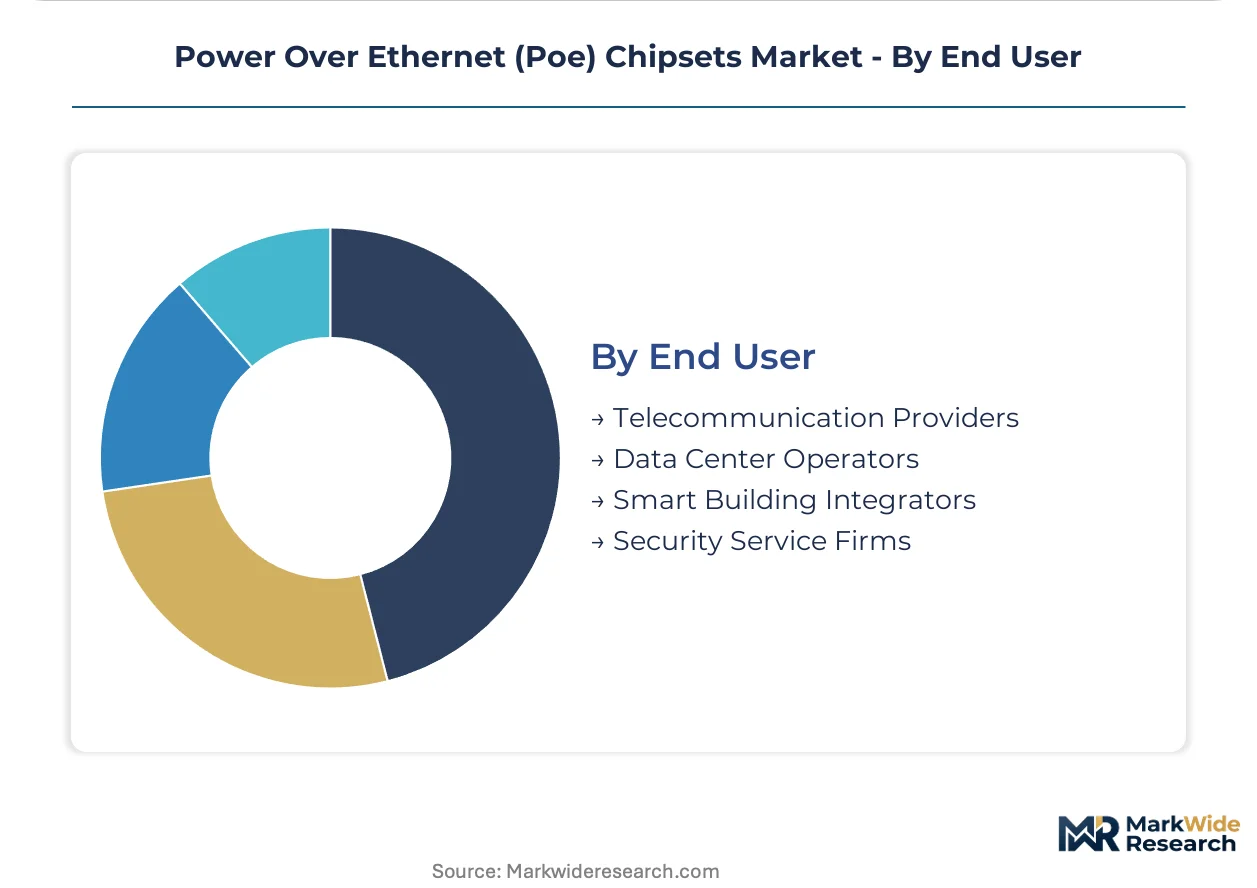
Procurement patterns diverge sharply between volume-driven data center operators and project-based smart building integrators.
- Data Center Operators:Hyperscale facilities prioritize multi-port PSE density for server rack environmental monitoring. Operators in China specify 48-port controllers with integrated thermal management to minimize switch hardware footprint.
- Smart Building Integrators:These firms bundle PoE lighting, access control, and sensor networks into unified infrastructure packages. German integrators capture EU Green Deal renovation funding by specifying 802.3bt-powered LED systems with embodied carbon accounting advantages.
- Telecommunication Providers:Carrier infrastructure for small cell backhaul and customer premises equipment.
- Security Service Firms:Physical security specialists specifying camera and access control networks with centralized power redundancy.
Data center operators absorb the bulk of high-volume procurement; smart building integrators are expanding most quickly as municipal mandates accelerate retrofit activity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Taiwanese BCD-on-SOI wafer foundries anchor the geographic concentration of PoE chipset manufacturing capacity. German smart building mandates and United States data center buildouts drive demand clustering across three continents. Regulatory divergence between FCC equipment authorization and CE marking under the EU Radio Equipment Directive shapes competitive access patterns.
United States
Hyperscale data center operators in Virginia and Oregon specify multi-port PSE controllers for server rack environmental sensor networks. FCC equipment authorization requirements govern electromagnetic interference compliance for switch silicon entering commercial deployment. Dallas-based systems integrators bundle PoE lighting with network management software for K-12 education retrofits.
China
MIIT standards harmonization with IEEE 802.3bt protocols accelerates domestic switch OEM qualification timelines. Yangtze River Delta foundries in Shanghai and Suzhou concentrate advanced BCD-on-SOI wafer capacity for multi-port controller production. Shenzhen security camera manufacturers source Powered Device ICs for perimeter surveillance installations.
Germany
Municipal energy codes in Bavaria and North Rhine-Westphalia incentivize PoE LED lighting retrofits through embodied carbon accounting rules. CE marking under the EU Radio Equipment Directive tightens electromagnetic compatibility thresholds for medical-grade deployments. Stuttgart industrial automation clusters pilot 802.3bt-powered motor controllers for predictive maintenance networks.
Japan
METI technology roadmaps prioritize PoE integration for factory automation and healthcare infrastructure modernization. Kanto region electronics manufacturers develop thermal-optimized magnetics for high-current 802.3bt implementations. Osaka-based building integrators specify centralized power redundancy for commercial access control networks.
France
EU Green Deal renovation wave funding streams structurally favor PoE lighting over conventional electrical retrofits in Île-de-France commercial buildings. ANSM medical device regulations influence procurement criteria for hospital IT departments deploying patient monitoring carts. Lyon smart city projects consolidate environmental sensor networks on unified PoE infrastructure.
Power Over Ethernet (Poe) Chipsets Market Key Industry Players
Global majors compete with regional champions across analog power management heritage and integrated switch silicon portfolios. The vendor base concentrates among analog semiconductor specialists with mixed-signal design capabilities spanning Ethernet PHY and DC-DC conversion functions. Three archetypes dominate: diversified analog conglomerates with broad power management portfolios, communications-focused silicon vendors anchoring enterprise switching platforms, and specialized mixed-signal houses optimizing Powered Device ICs for endpoint thermal efficiency. Competitive moves center on IEEE 802.3bt compliance certification acceleration and disaggregated PSE/PD controller architectures that compress OEM development cycles.
Within the diversified analog tier, Texas Instruments Incorporated and Analog Devices Inc. occupy positions reflecting decades of power management heritage. Broadcom Inc. exemplifies the communications-integrated archetype through enterprise switch silicon anchoring. Microchip Technology Inc. sits within the specialized endpoint controller segment where Powered Device IC qualification timelines determine design win velocity. These three company structures represent distinct strategic postures without implying specific market share positions or recent tactical moves.
| Leading Market Players |
|---|
| Texas Instruments Incorporated |
| Broadcom Inc. |
| Microchip Technology Inc. |
| Analog Devices Inc. |
| STMicroelectronics N.V. |
| NXP Semiconductors N.V. |
| ON Semiconductor Corporation |
| Marvell Technology Inc. |
| Realtek Semiconductor Corp. |
| Others |
Cost & Logistics Intelligence
Enterprise switch OEMs in the United States and China concentrate procurement volume for multi-port PSE controllers, anchoring a contract-based long-term offtake model where IEEE 802.3bt certification tier and thermal performance grade drive price differentiation across premium medical-certified, standard commercial, and economy industrial variants.
Pricing Analysis
Warranty and technical documentation bundling separates medical-certified controllers from unbundled commercial variants, with CE technical file pre-submission and extended magnetics validation forming premium tier inclusions. Pricing stratifies across 802.3bt compliance tier, volume commitment scale, and geographic delivery cost, with thermal-optimized configurations commanding sustained premiums. Cost compression in mid-tier switch silicon is intensifying because Taiwanese foundry capacity allocation favors high-margin medical and automotive BCD-on-SOI wafers. Smart building integrators in Germany exhibit highest price sensitivity due to EU Green Deal renovation funding constraints, while data center operators in Virginia absorb premium pricing for 48-port density with integrated thermal management.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese BCD-on-SOI wafer foundries, where TSMC and UMC anchor advanced mixed-signal capacity for multi-port PSE controllers. Manufacturing concentrates in Taiwan, South Korea, and China, with Yangtze River Delta packaging houses handling PD controller assembly. Raw material dependencies include high-purity silicon substrates, copper magnetics for 90-watt implementations, and specialized epoxy molding compounds. Tariff exposure on Chinese-assembled switch hardware feeds into downstream pricing volatility. Distribution runs through Arrow Electronics and Avnet in North America, with WPG Holdings and Yosun Industrial capturing Asia-Pacific project bundling margins.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Power Over Ethernet chipsets market sits in a technology-transition phase where IEEE 802.3bt's 90-watt ceiling is systematically displacing legacy 802.3at infrastructure across industrial automation and healthcare endpoints.
For Market Incumbents: Anchor design win velocity through accelerated IEEE 802.3bt compliance certification investment at accredited laboratories, compressing OEM qualification timelines that currently extend four to six months. Deepen backward integration into BCD-on-SOI wafer capacity through foundry partnership structures or captive supply agreements with Taiwanese and Korean facilities, defending against silicon supply concentration risk. Prioritize thermal-optimized magnetics co-development with Japanese component suppliers to sustain margin pools in medical-certified variants where CE marking thresholds are tightening. For New Entrants and Emerging Players: Enter via specialized Powered Device IC development for 802.3bt-powered LED lighting fixtures, where German smart building mandates and California municipal energy codes are structurally expanding procurement volume. Target industrial IoT motor controller and pneumatic valve array applications in Japan and South Korea, where factory automation integrators are piloting predictive maintenance networks with PoE-powered endpoints. Pursue channel partnerships with value-added distributors bundling network management software, capturing project-level margins in K-12 education and municipal building retrofits. For Investors and Strategic Acquirers: The window for entry favors analog semiconductor specialists with mixed-signal capabilities spanning Ethernet PHY and DC-DC conversion functions, particularly those holding active IEEE 802.3bt compliance certifications. Long-term viability hinges on architectural disaggregation trends that let switch OEMs source PSE and PD functions from separate suppliers, compressing development cycles. Target acquisition candidates with medical-certified controller portfolios and pre-submitted CE technical files. Watch for inflection when national building codes in France, Italy, or Germany mandate PoE as primary power for low-voltage lighting, structurally expanding addressable demand beyond traditional networking applications.| Strategic Initiative | Industry Significance |
|---|---|
| IEEE 802.3bt Compliance Certification Acceleration | Reduces OEM product launch timelines at accredited laboratories by four to six months. |
| Backward Integration into BCD-on-SOI Wafer Capacity | Secures captive supply from Taiwanese and Korean foundries against silicon concentration risk. |
| Medical-Certified Controller Portfolio Development | Captures CE marking premiums as EU Radio Equipment Directive tightens electromagnetic compatibility thresholds. |
| Channel Partnership with Value-Added Distributors | Enables integrated solution bundling for K-12 education and municipal building retrofit projects. |
| Industrial IoT Endpoint Controller Specialization | Addresses factory automation pilot demand for 802.3bt-powered motor controllers in Japan and South Korea. |
Research Approach
SEC 10-K filings, IEEE standards documentation, and semiconductor foundry capacity disclosures formed the secondary backbone, cross-referenced with customs and trade data for PoE controller import flows. Primary interviews with analog power management executives, enterprise switch OEM procurement directors, smart building integrators, and hospital IT department heads validated demand assumptions and qualification timeline estimates. Bottom-up and top-down triangulation reconciled wafer capacity allocation data with endpoint device shipment projections across the analysis window.
Bottom-up modeling built from individual product type segments—multi-port chipsets, Powered Device ICs, single-port configurations—aggregated through technology generation and application endpoint power requirements. Top-down validation anchored on data center buildout capex disclosures from hyperscale operators in the United States and China, plus EU Green Deal renovation funding allocation patterns in Germany, France, and Italy. CAGRs derived from weighted average growth across 802.3af, 802.3at, and 802.3bt protocol generations, with thermal management cost curves and copper price volatility scenarios informing sensitivity bands.
Forecast precision tightens around the base case; tail outcomes carry wider variance under extended IEEE 802.3bt compliance testing queue times or sudden BCD-on-SOI wafer capacity constraints at Taiwanese foundries. Forecasts reflect documented assumptions regarding municipal energy code adoption trajectories, hospital infrastructure modernization budgets, and industrial automation pilot conversion rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Mexico Data Center Processor Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
High Performance Computing (HPC) Chipset Market
Chipset and Processors
Processor Chip Market
Chipset and Processors
Tablet Application Processor Market
Chipset and Processors
United States Wi-Fi Chipset Market
Chipset and Processors
Application Processor Market
Chipset and Processors
Microcontroller Unit (MCU) Market
Chipset and Processors
Global AI Processor Market
Chipset and Processors
Accelerated Processing Unit (APU) Market
Chipset and Processors
Cockpit Soc Chip Market
Chipset and Processors
Electric Vehicle Silicon Chip Market
Chipset and Processors
NFC Chips Market
Chipset and Processors
Global Battery Management IC Market
Chipset and Processors
Data Center Chip Market
Chipset and Processors
India Data Center Processor Market