
 Auto Chip Market | 2026-2036
Auto Chip Market Size, Share, and Industry Trends Forecast 2026-2036
Auto Chip Market Insights
Automotive semiconductor distribution is fragmenting as OEMs bypass traditional tier-1 aggregators to contract directly with chip vendors for advanced driver-assistance systems and battery management. Infineon Technologies leverages its power semiconductor dominance to anchor European EV supply chains, while NXP Semiconductors competes through its vehicle networking and radar sensor portfolio. Texas Instruments sustains analog and embedded processing leadership by controlling pricing and inventory allocation to tier-1 suppliers during capacity constraints.
An auto chip is a purpose-built semiconductor device engineered to operate across temperature extremes from minus 40 to 150 degrees Celsius, with AEC-Q100 stress qualification governing reliability for underhood and cabin deployments. These components execute real-time control, sensing, and compute functions that enable powertrain efficiency, occupant protection, and connected cabin experiences. Microcontrollers and SoC solutions capture the dominant share of value as software-defined vehicle architectures displace distributed ECU designs. Analog ICs for battery current sensing and voltage monitoring represent the fastest-expanding margin pool, while sensor integration for cabin air quality and occupant detection is maturing into a commoditized supply category.
ISO 26262 functional safety standards, UNECE WP.29 cybersecurity regulations, and China GB/T automotive semiconductor guidelines collectively determine product qualification timelines and market access eligibility for chip suppliers. NHTSA crashworthiness requirements and EPA emissions compliance in the United States further constrain processor selection for powertrain and chassis control modules. Stakeholders must monitor foundry capacity allocation policies and geopolitical export controls to secure supply continuity for safety-critical automotive programs.
Market Dynamics
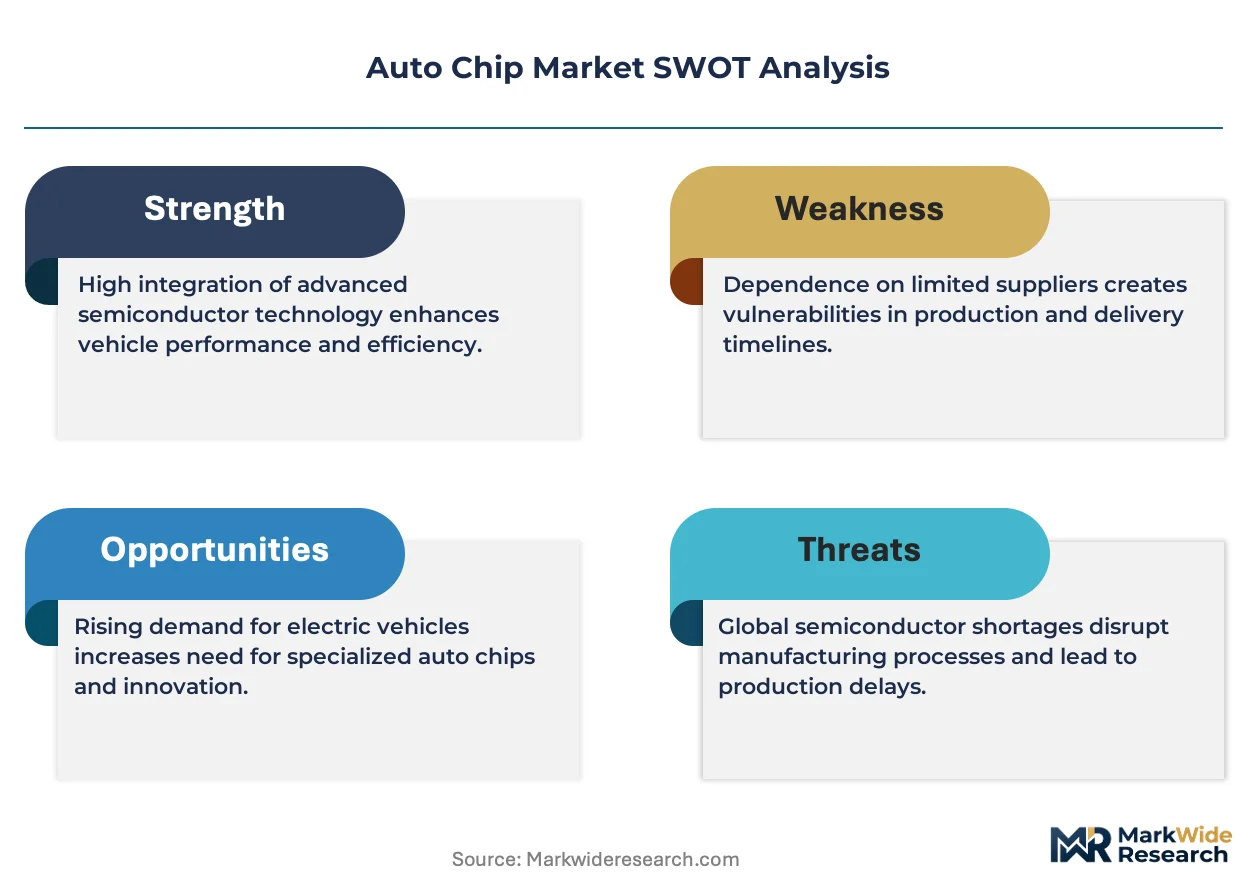
Software-defined vehicle architectures are collapsing distributed ECU designs into centralized compute domains, forcing chip suppliers to requalify entire product portfolios for higher thermal envelopes and functional safety grades under ISO 26262.
Growth Catalysts
- UNECE WP.29 cybersecurity mandates:European and Chinese regulators now require certified secure boot and over-the-air update capabilities, pulling hardware-based trust anchors into every new vehicle platform.
- Silicon carbide power modules:Traction inverter applications above 800V architectures are expanding addressable die area per vehicle as OEMs chase charging speed parity.
- BYD's captive sourcing model:China's largest EV producer internalizes IGBT and SiC production, accelerating domestic foundry capacity buildout for automotive-grade processes.
Market Restraints
- 300mm automotive-qualified wafer shortage:Foundry allocation to consumer electronics during peak demand cycles starves safety-critical automotive programs of leading-edge capacity.
- AEC-Q100 qualification timelines:Eighteen to twenty-four month stress-testing requirements delay revenue recognition for new entrants against entrenched suppliers.
- Legacy 8-bit microcontroller substitution:32-bit ARM cores at price parity are eroding socket retention for incumbent automotive MCU architectures.
Strategic Opportunities
- Chassis domain centralization:Brake-by-wire and steer-by-wire convergence creates demand for ASIL-D rated SoCs that consolidate multiple safety functions onto single die.
- India's automotive semiconductor PLI scheme:Duty incentives for local packaging and testing attract OSAT investment to serve emerging domestic EV production.
- Battery digital twin integration:Physics-based cell modeling embedded at the BMS chip level enables predictive thermal runaway detection before pack deployment.
Industry Challenges
- Functional safety architect scarcity:ISO 26262 certified hardware and software engineers command premium compensation, constraining program staffing for tier-2 suppliers.
- Multi-die packaging thermal management:Chiplets for autonomous compute clusters require novel TIM materials and liquid cooling integration that exceed traditional underhood design envelopes.
- Legacy LIN bus coexistence:Mixed 12V/48V electrical architectures force semiconductor vendors to maintain dual-process qualification for transitional vehicle generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Auto Chip Market |
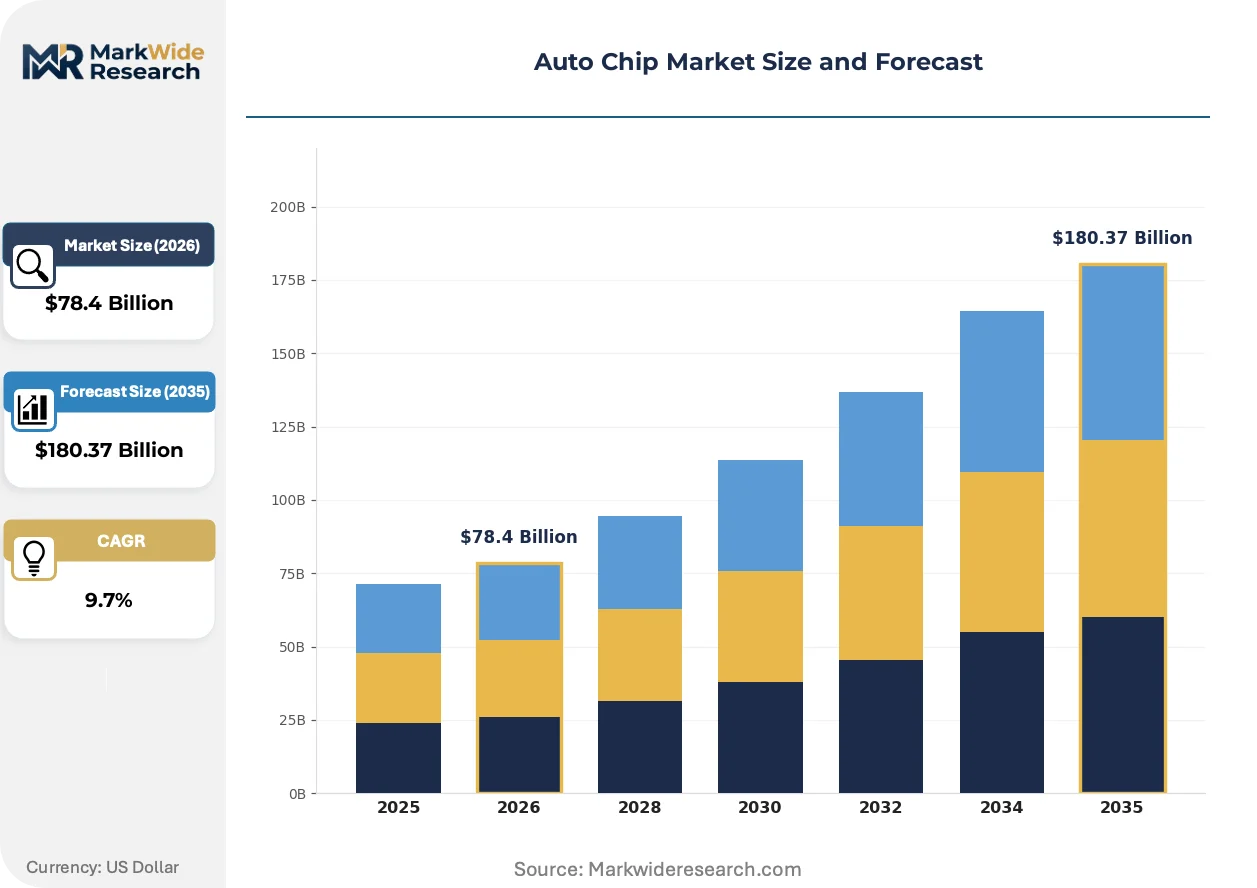
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $180.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microcontrollers, Sensors, Processors, Analog ICs Application: Infotainment Systems, Safety Systems, Powertrain Systems, Driver Assistance End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Dealerships Technology: FPGA, ASIC, SoC, DSP |
| Companies Covered | Infineon Technologies, NXP Semiconductors, STMicroelectronics, Texas Instruments, Renesas Electronics, Robert Bosch GmbH, ON Semiconductor, Analog Devices, Micron Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Auto Chip Market Trends and Innovations
Real-time virtualization of safety-critical workloads onto heterogeneous compute fabrics is redefining how automotive semiconductors are specified, validated, and monetized across the supply chain.
Domain controller SoCs with hardware-enforced hypervisors are virtualizing previously discrete ECU functions onto shared silicon. Tier-1 system integrators in Germany and Japan are adopting these consolidated compute platforms for 2026 model-year architectures. This consolidation is virtualizing the traditional one-function-one-chip procurement model, compressing supplier counts per vehicle platform from dozens to single-digit domain vendors.
China's GB/T automotive semiconductor guidelines now mandate domestic certification laboratories for cybersecurity and functional safety validation. This regulatory localization extends product launch timelines for foreign chip vendors by six to nine months. European suppliers with existing Shanghai technical centers are responding by transferring validation engineering headcount to joint-venture entities.
Direct contracting between OEM powertrain divisions and foundries is bypassing traditional tier-1 distribution for battery management and traction inverter silicon. This disintermediation concentrates procurement leverage with vehicle manufacturers possessing sufficient volume to secure wafer starts. The pattern is most visible in China, where NIO, XPeng, and Li Auto negotiate directly with TSMC and SMIC for automotive process nodes.
Auto Chip Market Segmentation
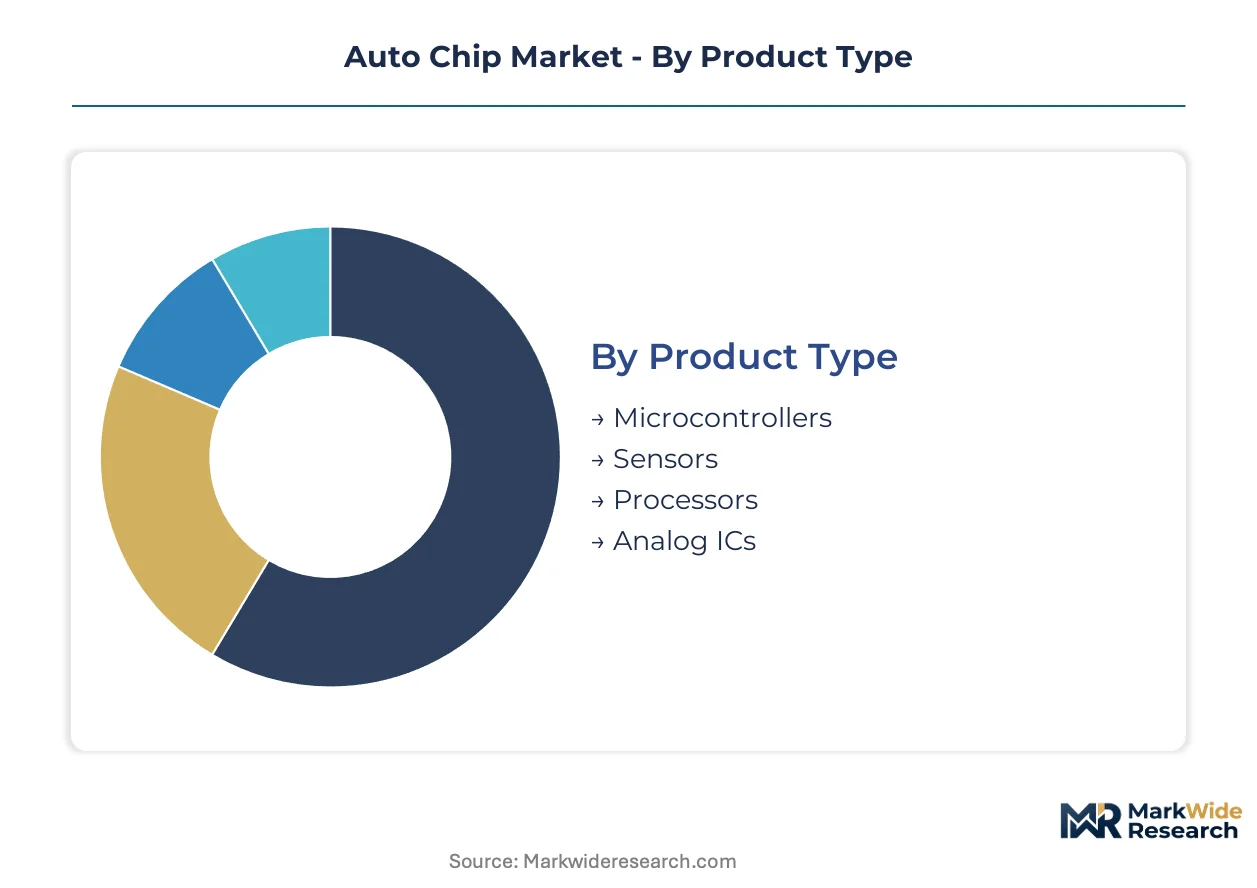
Automotive semiconductor procurement cycles vary dramatically across chip categories, with powertrain silicon requiring multi-year qualification timelines while cabin sensors refresh annually. Understanding these velocity differences enables suppliers to align inventory strategies with OEM platform roadmaps and foundry allocation windows.
Product Type:
Microcontrollers turn over fastest as software-defined architectures displace legacy 8-bit sockets, while analog ICs for battery sensing exhibit the longest design-in cycles due to AEC-Q100 thermal stress requirements.
- Microcontrollers:ARM Cortex-based 32-bit cores now dominate new platform designs, executing real-time control for chassis and body electronics. BYD and NIO in China are driving demand for ASIL-D rated MCUs as they consolidate distributed ECU functions.
- Analog ICs:Precision voltage references and current sense amplifiers monitor battery cell health across 800V architectures. These components command premium margins in European EV programs where ISO 26262 functional safety mandates the tightest accuracy specifications.
- Sensors:Cabin air quality and occupant detection modules are commoditizing as Chinese vendors flood the market with pin-compatible alternatives.
- Processors:Heterogeneous SoCs for autonomous compute clusters require liquid cooling integration that exceeds traditional underhood thermal envelopes.
Microcontrollers anchor the volume base while analog ICs gain share at the steepest rate.
Application:
Margin structures diverge sharply across vehicle domains, with safety-critical systems justifying qualification premiums and infotainment silicon competing on cost-per-transistor metrics.
- Powertrain Systems:Traction inverter controllers and battery management ICs operate across minus 40 to 150 degree Celsius ranges. Silicon carbide power modules for 800V architectures are expanding die area per vehicle as OEMs in Germany and China chase charging speed parity.
- Safety Systems:Brake-by-wire and steer-by-wire convergence demands ASIL-D rated SoCs that consolidate multiple safety functions onto single die. NHTSA crashworthiness requirements in the United States constrain processor selection for chassis control modules.
- Driver Assistance:Radar sensor fusion processors require hardware-enforced hypervisors to virtualize previously discrete ECU functions.
- Infotainment Systems:Consumer-grade silicon repurposing accelerates replacement cycles but compresses margin pools for traditional automotive suppliers.
Powertrain systems dominate procurement spend while safety systems expand most quickly as regulatory mandates tighten.
End User:
Direct OEM contracting is bypassing traditional tier-1 aggregators for advanced silicon, fragmenting historical distribution relationships.
- OEMs:Vehicle manufacturers with sufficient volume now negotiate wafer starts directly with TSMC and SMIC for automotive process nodes. This disintermediation concentrates procurement leverage with powertrain divisions in China.
- Tier-1 Suppliers:Continental and Bosch retain analog and embedded processing relationships where inventory allocation control during capacity constraints provides strategic value.
- Aftermarket Providers:Replacement chip sourcing for legacy vehicle fleets depends on secondary market availability of AEC-Q100 qualified inventory.
- Dealerships:Service bay diagnostics and module replacement drive demand for pre-programmed microcontroller variants.
Tier-1 suppliers retain the installed base while OEMs capture the steepest share gains in new platform silicon.
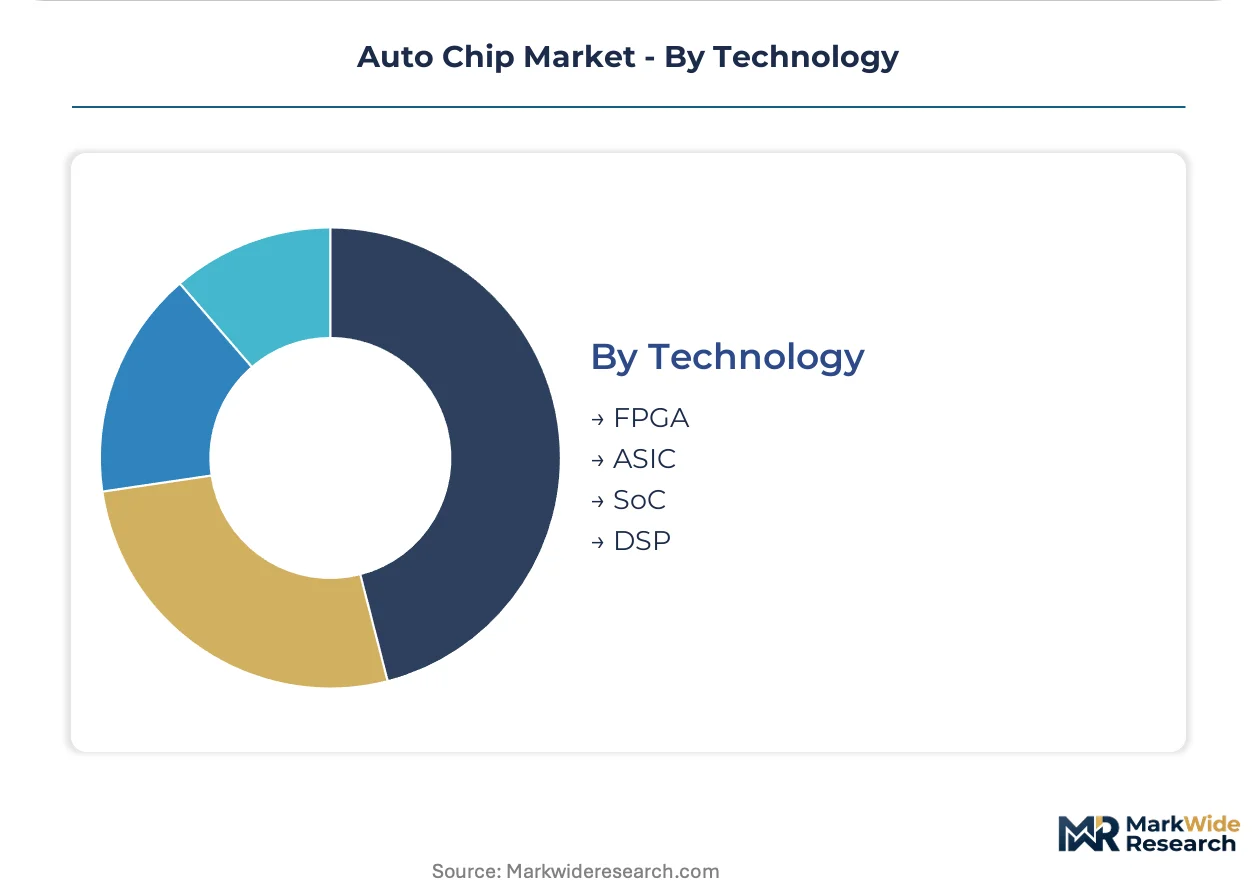
Technology:
Silicon efficiency tradeoffs determine technology selection, with programmable logic serving prototyping phases and hardwired ASICs optimizing production scale.
- SoC:Domain controller solutions with hardware-enforced hypervisors consolidate compute for 2026 model-year architectures. Infineon leverages its power semiconductor dominance to anchor European supply chains for these integrated platforms.
- ASIC:Custom silicon for battery digital twin integration enables predictive thermal runaway detection before pack deployment, commanding development premiums from premium EV manufacturers.
- FPGA:Reconfigurable logic accelerates algorithm validation for autonomous perception stacks before ASIC tape-out.
- DSP:Dedicated signal processing cores execute radar and lidar sensor fusion with deterministic latency guarantees.
SoC solutions anchor the volume base while ASICs gain share at the steepest rate as OEMs internalize chip design.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese OEMs command pricing leverage over European suppliers for 800V silicon carbide modules, while German automakers absorb qualification premiums for ASIL-D rated chassis controllers.
China
Domestic EV production drives captive foundry capacity expansion for automotive-grade processes. GB/T standards mandate domestic certification laboratories for cybersecurity validation. BYD's vertical supply chain in Shenzhen accelerates local IGBT and SiC production for powertrain controllers.
Germany
Infineon anchors European EV supply chains through power semiconductor dominance in Munich and Dresden fabs. KBA enforces UNECE WP.29 cybersecurity mandates for secure boot architectures. Stuttgart's OEM powertrain divisions negotiate directly with foundries for traction inverter silicon.
United States
NHTSA crashworthiness requirements constrain processor selection for brake-by-wire and steer-by-wire modules. EPA emissions compliance drives battery management IC qualification timelines. Texas Instruments controls analog and embedded processing allocation from Dallas to tier-1 suppliers during capacity constraints.
Japan
Renesas Electronics sustains MCU market presence through legacy automotive relationships with Toyota and Honda. METI coordinates domestic semiconductor resilience initiatives post-supply chain disruptions. Nagoya's Chubu region clusters tier-1 system integrators adopting domain controller SoCs for 2026 architectures.
South Korea
Hyundai and Samsung SDI partnerships drive local packaging investment for battery management systems. MFDS alignment with ISO 26262 functional safety standards accelerates chip qualification for autonomous programs. Seoul's Pangyo cluster concentrates fabless automotive semiconductor design houses serving domestic OEMs.
Auto Chip Market Competitive Landscape
Integrated device manufacturers and fabless specialists split the market along power semiconductor and compute silicon fault lines. The structure concentrates around five European and Asian conglomerates with captive fab capacity, while tier-2 specialists occupy niche sensor and analog sockets. IDMs with automotive-qualified 300mm capacity and fabless designers with domain controller expertise represent the dominant archetypes. Capacity expansion and direct OEM contracting constitute the primary competitive moves as procurement relationships fragment.
Within the integrated device manufacturer tier, Infineon Technologies and NXP Semiconductors exemplify European power and networking semiconductor dominance. Texas Instruments occupies a position anchoring analog and embedded processing relationships with tier-1 suppliers. These three entities represent the scale-driven end of automotive semiconductor supply, with geographic concentration in Germany, the Netherlands, and the United States respectively.
| Leading Market Players |
|---|
| Infineon Technologies |
| NXP Semiconductors |
| STMicroelectronics |
| Texas Instruments |
| Renesas Electronics |
| Robert Bosch GmbH |
| ON Semiconductor |
| Analog Devices |
| Micron Technology |
| Others |
Pricing and Supply Chain Analysis
The Shanghai-Rotterdam maritime corridor's container rate volatility feeds directly into landed cost spreads for AEC-Q100 qualified silicon, compressing margins for European distributors while amplifying pricing power for Chinese OEMs with captive Shenzhen packaging capacity. This freight-cost wedge separates procurement economics between centralized foundry-direct buyers and tier-1 aggregator-dependent suppliers.
Pricing Analysis
Configured-to-order pricing for ASIL-D rated SoCs commands 40-60% premiums over standard-grade microcontroller catalog pricing, with certification tier and volume scale as the primary differentiation drivers. Contract-based long-term offtake agreements dominate powertrain silicon procurement, though spot-market pressure from Chinese IGBT oversupply is eroding analog IC margins. Tier-1 suppliers exhibit highest price sensitivity in legacy body electronics sockets, while OEM powertrain divisions absorb premiums for functional safety-qualified traction inverter controllers.
Supply Chain Analysis
Export-control restrictions on extreme ultraviolet lithography equipment limit leading-edge automotive process node expansion in China, concentrating advanced silicon carbide die production in Taiwan, South Korea, and the United States. Raw material dependencies on neon gas from Ukraine, high-purity silicon metal from Norway, and specialty epoxy molding compounds from Japan create single-source vulnerability for automotive-qualified packaging. Distribution runs through dual-channel structures: direct foundry contracting for high-volume OEMs, and tier-1 system integrator aggregation for mid-tier suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Software-defined vehicle architectures fragment procurement relationships, creating white-space opportunities for specialized chip designers across chassis domain centralization and battery digital twin integration.
For Market Incumbents: Entrench power semiconductor dominance by securing 300mm automotive-qualified wafer allocation through binding capacity reservations with TSMC and GlobalFoundries. Invest in ISO 26262 certified hardware engineering headcount to defend against fabless specialists targeting ASIL-D rated SoC sockets. Counter BYD's captive sourcing model by anchoring European EV supply chains through Dresden fab expansion. For New Entrants and Emerging Players: India's underpenetrated automotive semiconductor packaging landscape offers tariff-advantaged entry points through the PLI scheme's duty incentives for local OSAT investment. Target battery management IC design for domestic EV producers in Pune and Chennai, leveraging fabless partnerships with SMIC for automotive process nodes. Pursue joint-venture structures with established tier-1 suppliers to bypass eighteen-month AEC-Q100 qualification barriers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with captive automotive semiconductor divisions lacking scale to justify standalone foundry access. Focus on analog and sensor specialists with existing AEC-Q100 portfolios and tier-1 supplier relationships, positioned for consolidation into domain controller platforms. Watch for inflection when NHTSA mandates steer-by-wire architectures, accelerating ASIL-D rated SoC demand beyond incumbent capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Carbide Capacity Expansion | Secures 800V traction inverter supply for German and Chinese OEM charging parity programs. |
| Domain Controller SoC Platform Launch | Consolidates brake-by-wire and steer-by-wire functions onto single die for 2026 architectures. |
| Automotive-Grade Foundry Joint Venture | Locks in 300mm wafer allocation bypassing consumer electronics capacity competition. |
| GB/T Certification Laboratory Partnership | Accelerates cybersecurity validation timelines for foreign chip vendors in China. |
| Battery Digital Twin ASIC Development | Enables predictive thermal runaway detection commanding premium EV manufacturer development fees. |
Research Methodology
A spread of perspectives from OEM platform engineers, tier-1 supplier procurement directors, foundry account managers, and aftermarket distributors converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings, IHS Markit vehicle production databases, customs records for semiconductor trade flows, and UNECE WP.29 regulatory documentation. Bottom-up content-per-vehicle estimates triangulated against top-down foundry capacity allocation data across the analysis window.
Demand-supply balance modeling segmented the market by propulsion architecture, vehicle class, content per vehicle, OEM tier, and regional production cluster. CAGRs derived from regression analysis of historical semiconductor content growth against EV penetration trajectories, incorporating silicon carbide adoption curves and functional safety mandate implementation timelines. Forecast inputs included foundry capex disclosure patterns and GB/T regulatory localization schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese captive-sourcing OEMs or unexpected relaxation of EUV export controls would shift outcomes. Material shifts in UNECE WP.29 cybersecurity enforcement timelines or 300mm automotive wafer allocation policy would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chipset and Processors
Global Graphic Processors Market
Chipset and Processors
High-Performance Dual-Core Processor Market
Chipset and Processors
IP Core Chip Market
Chipset and Processors
Global Microprocessor and GPU Market
Chipset and Processors
IPC Soc Front-End Chip Market
Chipset and Processors
Deep Learning Chip Market
Chipset and Processors
Canada Data Center Processor Market
Chipset and Processors
Mobile Chipset Market
Chipset and Processors
System on Chip (Soc) Market
Chipset and Processors
Airbag Chip Market
Chipset and Processors
Cockpit Soc Chip Market
Chipset and Processors
Global Smartcard MCU Market
Chipset and Processors
Hybrid Memory Cube (HMC) and High-Bandwidth Memory (HBM) Market
Chipset and Processors
Brazil Data Center Processor Market
Chipset and Processors
Graphics Processing Unit (GPU) Market
Chipset and Processors
Japan Microprocessor (MPU) Market