
 Silyl Acrylate Polymer (SAP) Market | 2026-2036
Silyl Acrylate Polymer (SAP) Market Size, Share, and Industry Trends Forecast 2026-2036
Silyl Acrylate Polymer (SAP) Market Analysis
Market Context
A wide capital-intensity gap between integrated resin producers and regional blenders is bifurcating competitive dynamics in the silyl acrylate polymer value chain. AkzoNobel N.V. leverages captive silane precursor supply to control raw material cost volatility across marine coating formulations. Hempel A/S anchors its position through specialized antifouling R&D pipelines serving deep-sea vessel operators. Jotun A/S differentiates via direct technical service ties with Scandinavian and Southeast Asian shipyard networks.
Technical Definition and Segments
Silyl acrylate polymer denotes a hybrid organosilicon-acrylate resin incorporating pendant trialkoxysilyl groups that hydrolyze to form siloxane crosslinks, delivering self-polishing antifouling performance with tunable erosion rates in marine coatings. The material functions primarily as a binder system where controlled surface renewal releases biocides while maintaining hull smoothness across static and dynamic immersion conditions. Waterborne formulations now lead volume shipments as drydock operators face tightening solvent emission rules, while UV-curable grades represent the fastest-expanding niche driven by in-yard curing speed demands. Emulsion polymerization technology dominates commercial production due to lower capital barriers, though solution polymerization retains margin concentration in high-performance naval specifications.
Regulatory Frame
EPA antifouling pesticide registrations under FIFRA and ECHA biocidal product regulations constrain active ingredient choices and binder compatibility in silyl acrylate systems. The EU Green Deal's marine strategy framework pressures coating lifecycle assessments, while China's MEE emission standards accelerate waterborne conversion at domestic shipyards. Stakeholders must monitor regulatory divergence between biocide approval timelines in Europe and Asia-Pacific to anticipate reformulation cycles and regional product registration requirements.
Market Dynamics
Marine coating formulators face mounting pressure to reconcile biocide efficacy with tightening environmental discharge limits, forcing simultaneous reformulation of binder chemistry and active ingredient selection across drydock supply chains.
Growth Catalysts
- EU Green Deal marine strategy:Lifecycle assessment mandates for vessel coatings accelerate silyl acrylate adoption in European shipyards seeking compliant self-polishing systems.
- East Asian shipbuilding clusters:South Korean and Chinese drydock operators expand fleet renewal programs, concentrating demand for high-performance antifouling binders.
- Waterborne emulsion polymerization:MEE emission standards in China push domestic producers toward lower-VOC formulation platforms compatible with silyl acrylate chemistry.
Market Restraints
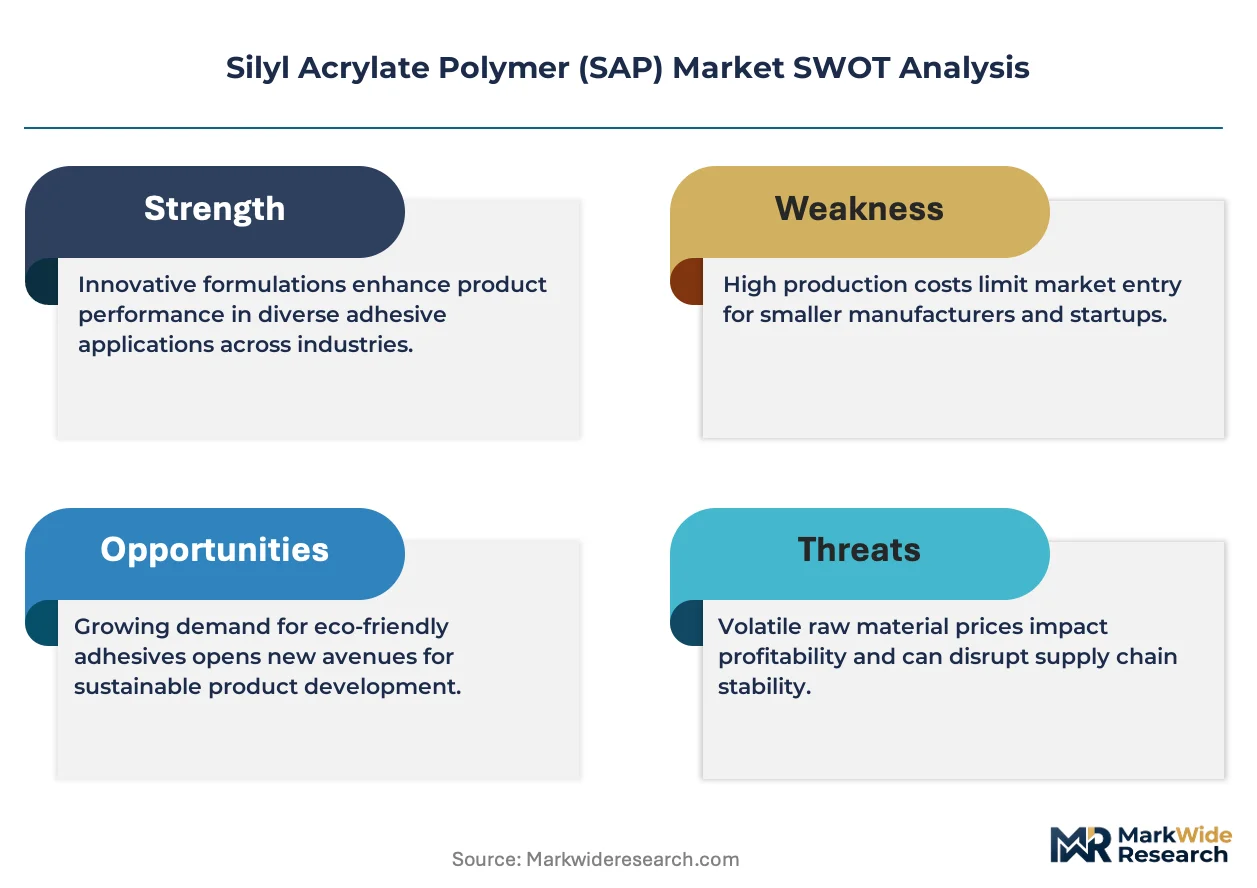
- Silane precursor cost volatility:Captive supply constraints among non-integrated blenders expose margin compression when organosilicon feedstock prices fluctuate.
- FIFRA registration timelines:EPA pesticide approval delays for new biocide-binder combinations extend product development cycles beyond typical coating reformulation windows.
- Copper-based antifouling substitution:Legacy tin-free systems retain cost advantages in price-sensitive regional fleets, limiting silyl acrylate penetration in emerging maritime economies.
Strategic Opportunities
- UV-curable silyl acrylate grades:In-yard curing speed requirements at Southeast Asian shipyards create white space for radiation-cured binder technologies.
- Naval specification channels:Solution polymerization capabilities align with defense procurement standards in NATO-aligned maritime forces seeking controlled erosion rates.
- REACH-registered biocide convergence:ECHA-approved active ingredient pipelines enable European formulators to bundle compliant binder-biocide systems for export markets.
Industry Challenges
- Organosilicon synthesis expertise:Shortage of polymer chemists skilled in trialkoxysilyl group incorporation constrains R&D throughput at mid-scale resin producers.
- Dual-registration compliance:Coordinated FIFRA and BPR filing requirements demand dedicated regulatory affairs capacity that fragments smaller formulator resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silyl Acrylate Polymer (SAP) Market |
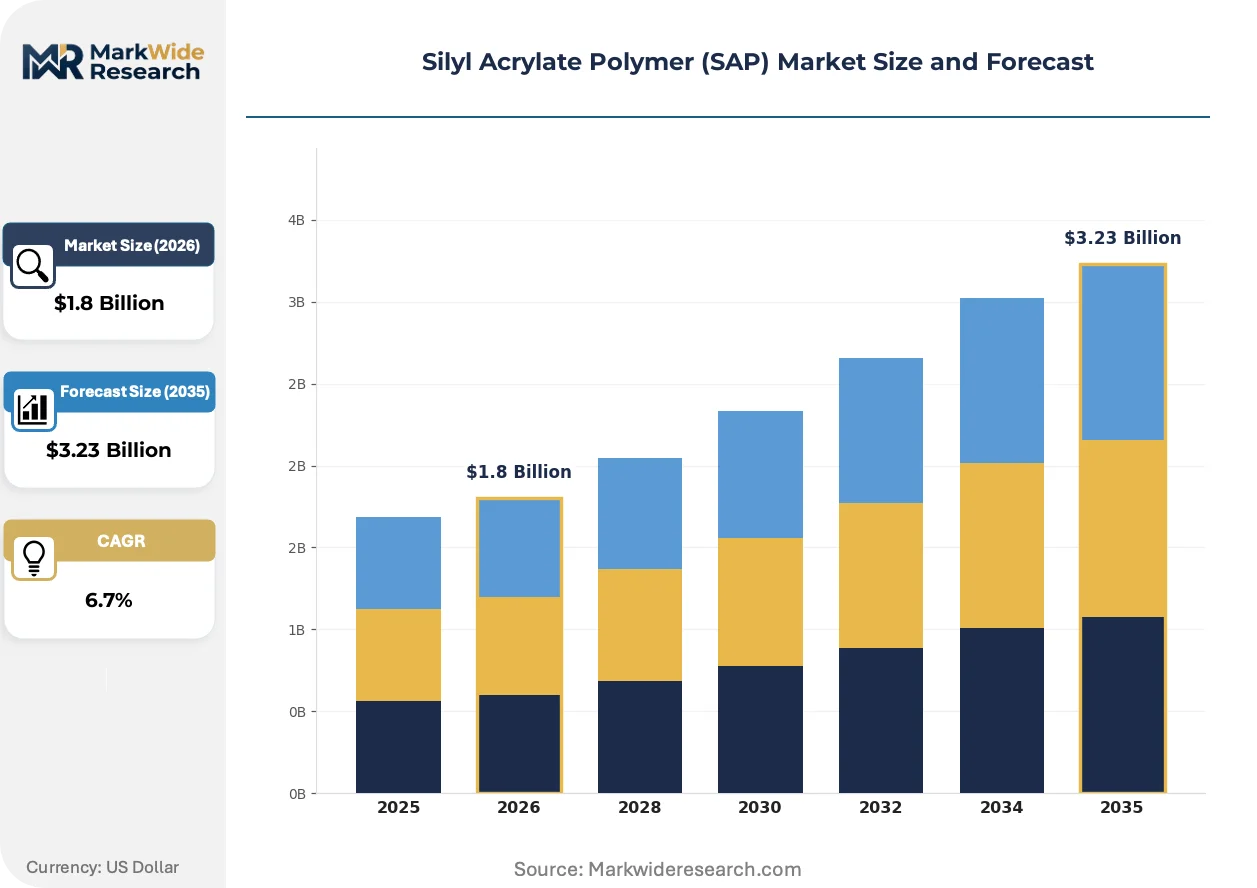
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Waterborne, Solventborne, UV-Curable, Hot Melt End Use Industry: Construction, Automotive, Electronics, Pharmaceuticals Formulation Type: Single-Component, Two-Component, Reactive, Non-Reactive Technology: Emulsion Polymerization, Solution Polymerization, Suspension Polymerization, Block Copolymerization |
| Companies Covered | AkzoNobel N.V., Chugoku Marine Paints, Ltd., Hempel A/S, Jotun A/S, PPG Industries Inc., Nippon Paint Holdings Co., Ltd., KCC Corporation, Arkema SA, BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silyl Acrylate Polymer (SAP) Market Emerging Trajectories
Coating chemistry is pivoting toward hydrolysis-controlled surface renewal mechanisms that eliminate heavy metal biocide dependency while maintaining hull performance across static and dynamic immersion regimes.
Self-polishing silyl acrylate binders with tunable siloxane crosslink density are decomposing the traditional dichotomy between short-term static protection and long-haul dynamic performance. Deep-sea container operators now specify erosion-rate-matched systems that align biocide release with voyage profiles. This decomposition enables single-coat solutions that previously required layered application protocols.
REACH authorization procedures for existing biocidal active ingredients are compressing the approved substance list available to European formulators. Coating manufacturers must revalidate binder compatibility with substitute actives under tightened hazard classification rules. Naval and commercial drydock operators in Germany, the Netherlands, and Denmark face accelerated reformulation cycles as ECHA sunset dates approach.
Shipyard procurement teams are consolidating supplier relationships around technical service-integrated coating packages rather than commodity resin transactions. Scandinavian and Southeast Asian yard networks now demand direct formulation support, displacing traditional distributor intermediaries. This concentration is most visible in South Korean mega-yard operations where single-source technical partnerships reduce application liability exposure.
Silyl Acrylate Polymer (SAP) Market Segmentation
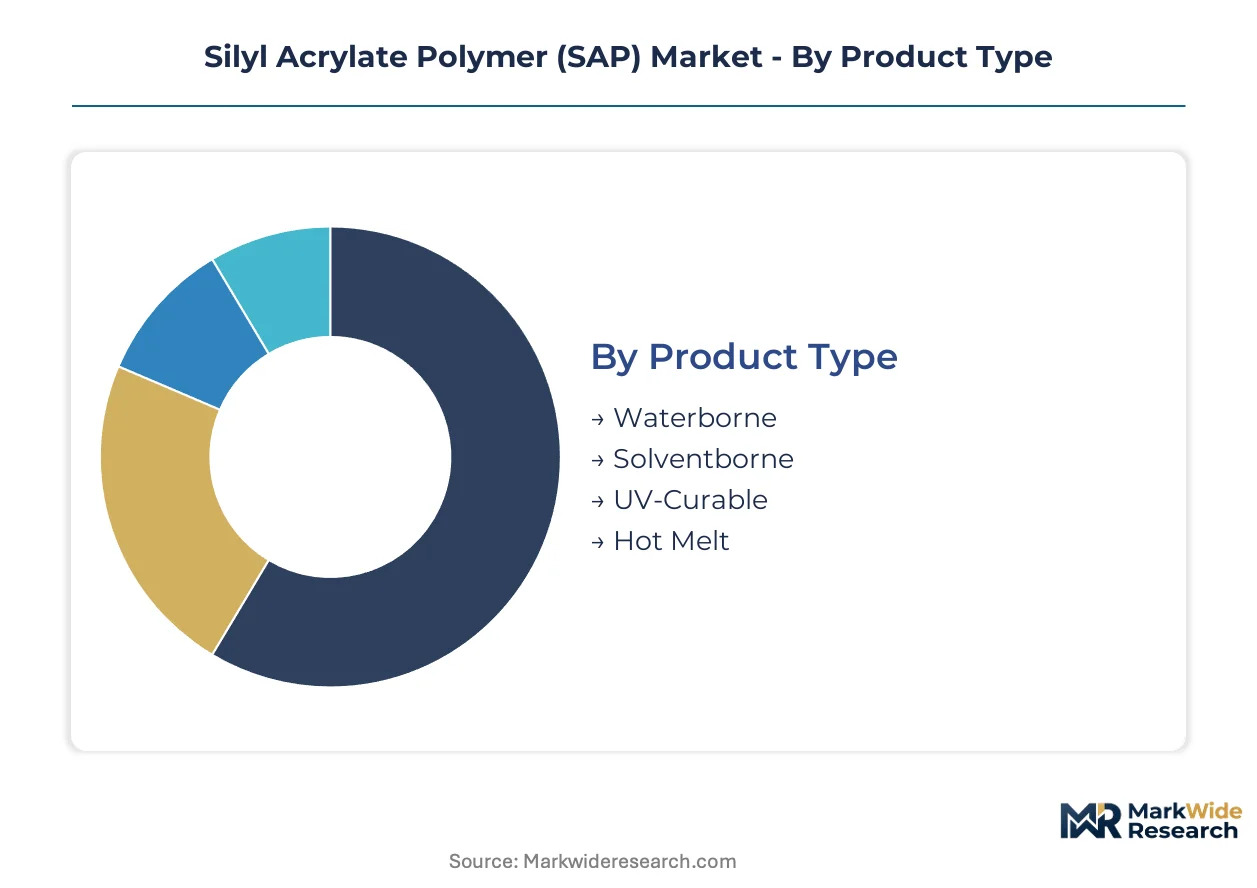
Silyl acrylate polymer formulations fragment across incompatible regulatory compliance requirements, forcing formulators to maintain parallel product architectures for marine, industrial, and specialty applications. Segmentation strategy determines whether producers capture volume in standardized waterborne marine coatings or margin in specification-grade naval systems.
Product Type:
REACH VOC limits and China's MEE emission standards bifurcate formulation portfolios between compliant waterborne systems and legacy solventborne platforms.
- Waterborne:Emulsion-based silyl acrylate dispersions incorporate trialkoxysilyl functionality through post-polymerization grafting, achieving sub-50 g/L VOC content. South Korean drydock operators now mandate these systems for in-yard application, driven by port authority emission enforcement at Busan and Ulsan facilities.
- Solventborne:Solution-grade resins retain performance advantages in high-build marine specifications where humidity tolerance and wet-edge time prove critical. German and Dutch formulators maintain solventborne lines for deep-sea vessel operators requiring extended static immersion protection.
- UV-Curable:Acrylated silyl macromers enable rapid through-cure at Southeast Asian shipyards facing compressed drydock windows.
- Hot Melt:Reactive silyl acrylate hot melts serve industrial adhesive applications outside marine coating channels.
Established volume favors Waterborne; emerging adoption favors UV-Curable.
End Use Industry:
Marine coating demand concentrates hull protection applications, while non-marine segments require reformulated binder architectures with divergent curing protocols.
- Construction:Silyl-terminated acrylate sealants leverage siloxane crosslinking for joint movement accommodation in high-rise glazing and infrastructure waterproofing. Chinese construction chemical producers now specify these systems for megaproject concrete protection, substituting conventional polyurethane moisture-cure chemistry.
- Automotive:Clearcoat applications exploit silyl acrylate weathering resistance for premium vehicle segments, though automotive qualification timelines extend commercialization cycles.
- Electronics:Low-outgassing silyl acrylate encapsulants protect semiconductor packaging against moisture ingress.
- Pharmaceuticals:Medical-grade silyl acrylate adhesives serve transdermal patch and device assembly with biocompatibility certifications.
Construction commands current volume leadership; electronics applications climb the fastest on semiconductor packaging demand.
Formulation Type:
Application economics and in-yard logistics determine whether shipyards adopt single-component convenience or accept two-component mixing complexity for performance gains.
- Single-Component:Moisture-cure silyl acrylate systems package reactive silane functionality in stable one-part containers, eliminating pot-life management at drydock application sites. Chinese and South Korean mega-yards prefer these formulations for labor efficiency in high-throughput coating operations.
- Two-Component:Catalyzed crosslinking enables accelerated cure schedules and tailored mechanical properties for naval specification work.
- Reactive:Silane-functional oligomers participate in condensation curing with ambient moisture or substrate hydroxyl groups.
- Non-Reactive:Physical drying silyl acrylate blends serve temporary protective coating applications without chemical crosslinking.
Single-Component formulations dominate shipyard procurement; Two-Component systems gain share in defense channel specifications.
Technology:
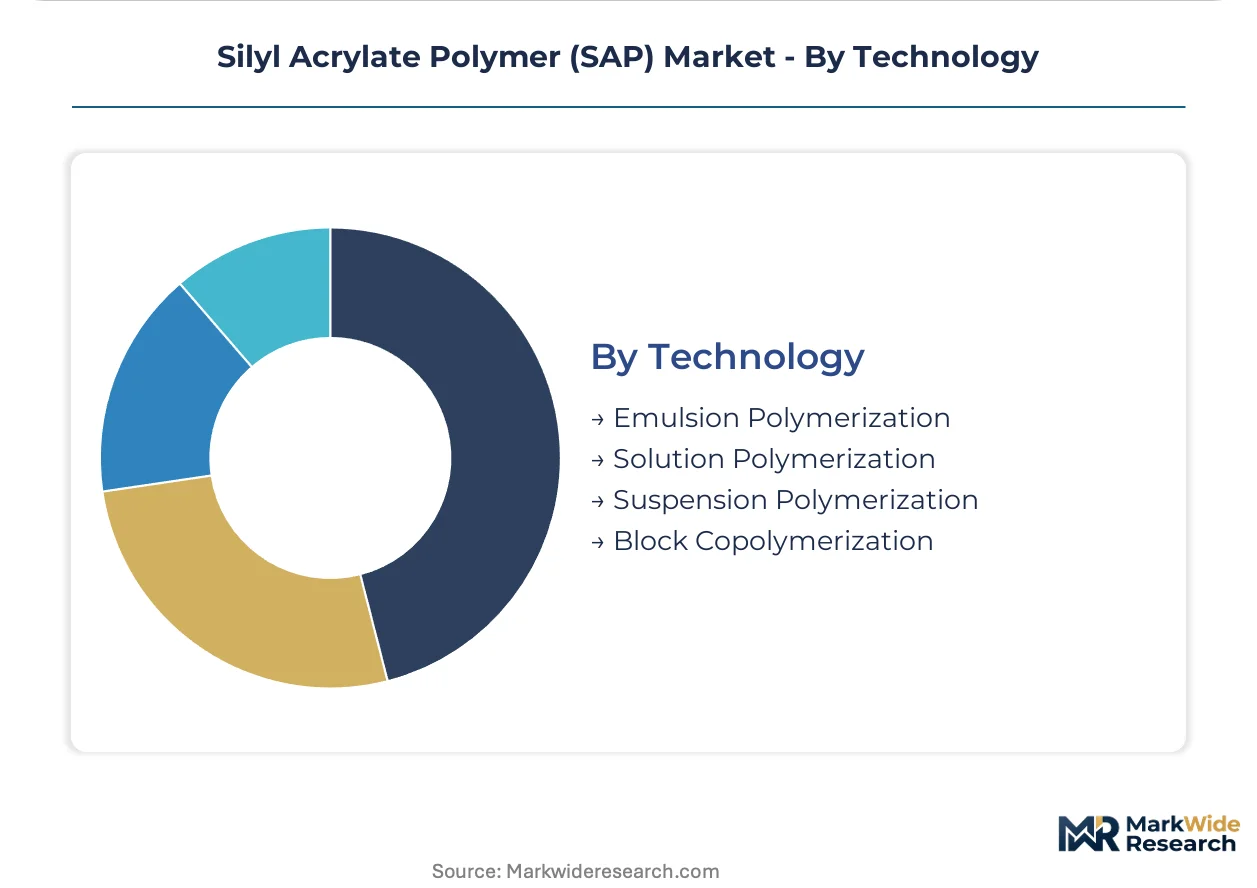
Capital investment thresholds and polymer architecture control separate emulsion-based volume production from solution polymerization precision.
- Emulsion Polymerization:Aqueous-phase radical polymerization of acrylate monomers with silane-containing comonomers or post-grafting delivers cost-scalable waterborne resins. Regional blenders across East Asian coating clusters favor this technology for lower capital barriers and flexible batch sizing.
- Solution Polymerization:Organic-phase synthesis enables precise molecular weight control and block copolymer architectures for naval erosion-rate specifications.
- Suspension Polymerization:Bead-form silyl acrylate resins serve specialty adhesive and powder coating applications.
- Block Copolymerization:Controlled radical techniques produce segmented silyl acrylate architectures with tunable phase separation.
Emulsion technology anchors commercial volume; Block Copolymerization shows steepest expansion trajectory in high-performance specification channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Chinese and South Korean shipyards exhibit high price elasticity for standardized waterborne formulations, while German and Dutch operators prioritize performance specifications over cost, creating divergent procurement patterns across major maritime economies.
China
Domestic drydock operators at Dalian, Shanghai, and Guangzhou drive waterborne silyl acrylate consumption as fleet renewal accelerates. MEE emission standards enforcement at major port facilities compels reformulation away from solventborne systems. Yangtze River Delta coating clusters now supply formulated systems to Southeast Asian shipyards seeking compliant import sources.
South Korea
Busan and Ulsan mega-yards specify single-component moisture-cure silyl acrylate binders for labor efficiency in high-throughput operations. KSA certification requirements for hull coatings push technical service integration into procurement contracts. Daegu-Gyeongbuk resin producers emulsion polymerization capacity serves both domestic formulators and Chinese blenders seeking quality imports.
Germany
Deep-sea vessel operators at Hamburg and Bremerhaven yards demand solution-grade silyl acrylate resins for extended static immersion protection. REACH authorization timelines for biocidal actives compress reformulation cycles at coating headquarters in North Rhine-Westphalia. Bavarian chemical producers supply precision-controlled silane precursors to integrated marine formulators.
United States
Gulf Coast ship repair facilities face FIFRA registration delays for new biocide-binder combinations, extending product development timelines. EPA regional enforcement at Houston and New Orleans drydocks tightens VOC compliance for in-yard application. Pacific Northwest naval specification channels favor block copolymer architectures from domestic solution polymerization specialists.
Netherlands
Rotterdam and Amsterdam port authorities mandate lifecycle assessment documentation for hull coatings under EU Green Deal marine strategy implementation. Randstad-based formulators bundle REACH-registered binder-biocide systems for export to Nordic markets. Eindhoven region emulsion technology providers serve mid-scale European blenders lacking captive silane supply.
Silyl Acrylate Polymer (SAP) Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, with integrated resin producers commanding molecular architecture control while regional blenders compete on formulation flexibility and local technical service. The market structure bifurcates between silane precursor-integrated majors and procurement-dependent specialists. Three archetypes dominate: backward-integrated chemical conglomerates with captive organosilicon supply, marine-focused coating houses with specialized antifouling R&D pipelines, and regional emulsion producers serving price-sensitive drydock clusters. Competitive moves concentrate on strategic partnerships for biocide registration coordination and geographic expansion through technical service deployment.
Among marine coating specialists, AkzoNobel N.V., Hempel A/S, and Jotun A/S exemplify distinct strategic positioning within the value chain. The Dutch entity represents backward-integrated resin production with silane precursor control. The Danish firm occupies a position emphasizing specialized antifouling research pipelines. The Norwegian company anchors its competitive stance through direct technical service relationships with shipyard networks. These three entities collectively illustrate how geographic origin and corporate structure correlate with divergent approaches to silyl acrylate polymer commercialization.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| Chugoku Marine Paints, Ltd. |
| Hempel A/S |
| Jotun A/S |
| PPG Industries Inc. |
| Nippon Paint Holdings Co., Ltd. |
| KCC Corporation |
| Arkema SA |
| BASF SE |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between South Korean shipyards and integrated resin producers lock in silane precursor supply while anchoring price visibility across volatile organosilicon feedstock cycles. These arrangements insulate drydock operators from spot market swings in trialkoxysilane costs while committing formulators to volume minimums that shape capacity planning at Daegu-Gyeongbuk production clusters.
Pricing Analysis
Technical service bundling drives lifetime value for marine coating formulators, with Scandinavian and Southeast Asian shipyards now paying premium rates for direct application support embedded in resin procurement contracts. Three-tier pricing structure across premium, standard, and economy levels separates REACH-registered systems from basic waterborne grades and commodity solventborne alternatives. Cost compression in standard-tier emulsion polymers is intensifying because Chinese domestic producers expand MEE-compliant capacity at Yangtze River Delta clusters. Price sensitivity concentrates among regional blenders serving price-sensitive emerging maritime economies, while integrated majors commanding captive silane supply face minimal margin pressure.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for German and Dutch formulators sourcing silane precursors from East Asian chemical clusters. Production gravity centers on China, South Korea, and Germany, with each hub serving distinct specification tiers from waterborne volume grades to solution-polymerized naval systems. Raw material flows draw from organosilicon intermediates, acrylate monomer feedstocks, and REACH-registered biocide actives. Single-source vulnerability concentrates in trialkoxysilyl functional group supply where non-integrated blenders lack backward integration into silane synthesis. Distribution runs through technical service-integrated direct contracts rather than traditional distributor intermediaries, particularly at South Korean mega-yard operations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate sustained substitution pressure from copper-based antifouling systems that retain cost advantages in price-sensitive regional fleets, forcing simultaneous defense of premium specification channels and selective cost-down initiatives for emerging market penetration.
For Market Incumbents: Secure captive silane precursor supply through backward integration or long-term offtake commitments with Bavarian and Daegu-Gyeongbuk chemical producers, insulating margin structures from organosilicon feedstock volatility that compresses non-integrated blenders. Deepen technical service deployment at Southeast Asian shipyards to lock in single-source procurement relationships that displace distributor intermediaries and create switching costs against copper-based system substitution.
For New Entrants and Emerging Players: Lead with UV-curable silyl acrylate grades targeting compressed drydock windows at Southeast Asian shipyards, where radiation-cured binder technologies remain underpenetrated relative to established moisture-cure systems. Establish formulation partnerships with regional emulsion producers lacking organosilicon synthesis expertise, licensing trialkoxysilyl grafting technology to access waterborne volume tiers without capital-intensive solution polymerization infrastructure.
For Investors and Strategic Acquirers: Naval specification solution polymerization specialists with block copolymer architecture capabilities represent the most defensible acquisition targets, given NATO-aligned defense procurement standards that demand controlled erosion rates and extended qualification timelines. Monitor ECHA biocidal product authorization timelines as the critical inflection signal; accelerated sunset dates for existing actives will force reformulation cycles that favor acquirers with REACH-registered binder-biocide bundles already validated for substitute active ingredients.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silane Precursors | AkzoNobel's captive organosilicon supply controls raw material cost volatility across marine formulations. |
| Technical Service Partnership Deployment | Jotun's direct Scandinavian and Southeast Asian shipyard relationships displace distributor intermediaries. |
| REACH-Registered Biocide Convergence | ECHA-approved active ingredient pipelines enable European formulators to bundle compliant export systems. |
| UV-Curable Grade Development | Radiation-cured binders address compressed drydock windows at Southeast Asian shipyards. |
| Naval Specification Channel Entry | Solution polymerization capabilities align with NATO defense procurement standards for controlled erosion rates. |
Methodological Framework
The analysis maps waterborne emulsion polymers, solventborne solution grades, UV-curable acrylated macromers, and hot melt reactive systems, each validated through coating formulators, drydock procurement managers, resin plant operators, and regulatory affairs specialists at ECHA and EPA. Primary interviews with marine coating R&D directors and shipyard technical service teams combined with secondary validation from customs trade data, Cefic chemical industry reports, SEC 10-K filings, and ECHA biocidal product registration databases. Bottom-up volume modeling triangulates against top-down value estimates across the projection horizon.
Consistency checks validated volume and value outputs against external benchmarks including regional shipbuilding order books, drydock throughput metrics, and coating consumption coefficients per vessel tonnage. Segmentation dimensions span product type, end-use industry, formulation architecture, and polymerization technology, with CAGRs derived from regression analysis of historical price-volume relationships and forward projection of regulatory compliance cost trajectories. Forecast inputs incorporate MEE emission standard enforcement timelines, REACH authorization sunset schedules, and fleet renewal program announcements at major East Asian shipyards.
The analysis sits within stated boundaries; outcomes outside sustained East Asian shipbuilding activity, stable organosilicon feedstock availability, and coordinated biocide registration timelines would require recalibration. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and substitution elasticity between silyl acrylate and legacy antifouling systems. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Styrenic Block Copolymer (SBC) Market
Polymers & Resins
Polyether Ketone (PEK) Market
Polymers & Resins
Polytetramethylene Ether Glycol (PTMEG) Market
Polymers & Resins
Europe Polyvinylpyrrolidone (PVP) Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Polyphenylene Sulfide Market
Polymers & Resins
Middle East Polyethylene Terephthalate (PET) Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Europe Fluoropolymer Market
Polymers & Resins
PP Homopolymer Market
Polymers & Resins
Middle East Engineering Plastics Market
Polymers & Resins
Mixed-Mode Chromatography Resin Market
Polymers & Resins
Packaging Resins Market
Polymers & Resins
North America Linear Low-Density Polyethylene Market
Polymers & Resins
South America Epoxy Resins Market