
 South America Epoxy Resins Market | 2026-2036
South America Epoxy Resins Market Size, Share, and Industry Trends Forecast 2026-2036
South America Epoxy Resins Market Analytics
Buyer concentration among wind turbine OEMs and their blade suppliers is expanding across Brazil and Argentina, pulling volume toward fewer large-scale procurement contracts. Huntsman International LLC leverages its formulated systems expertise to anchor long-term supply relationships with composite fabricators in the region. Covestro AG competes through backward integration into bisphenol feedstocks, sustaining margin control despite raw material volatility. Hexion specializes in custom curing agent packages that differentiate its offerings for marine coating applicators along Argentina's Atlantic coast.
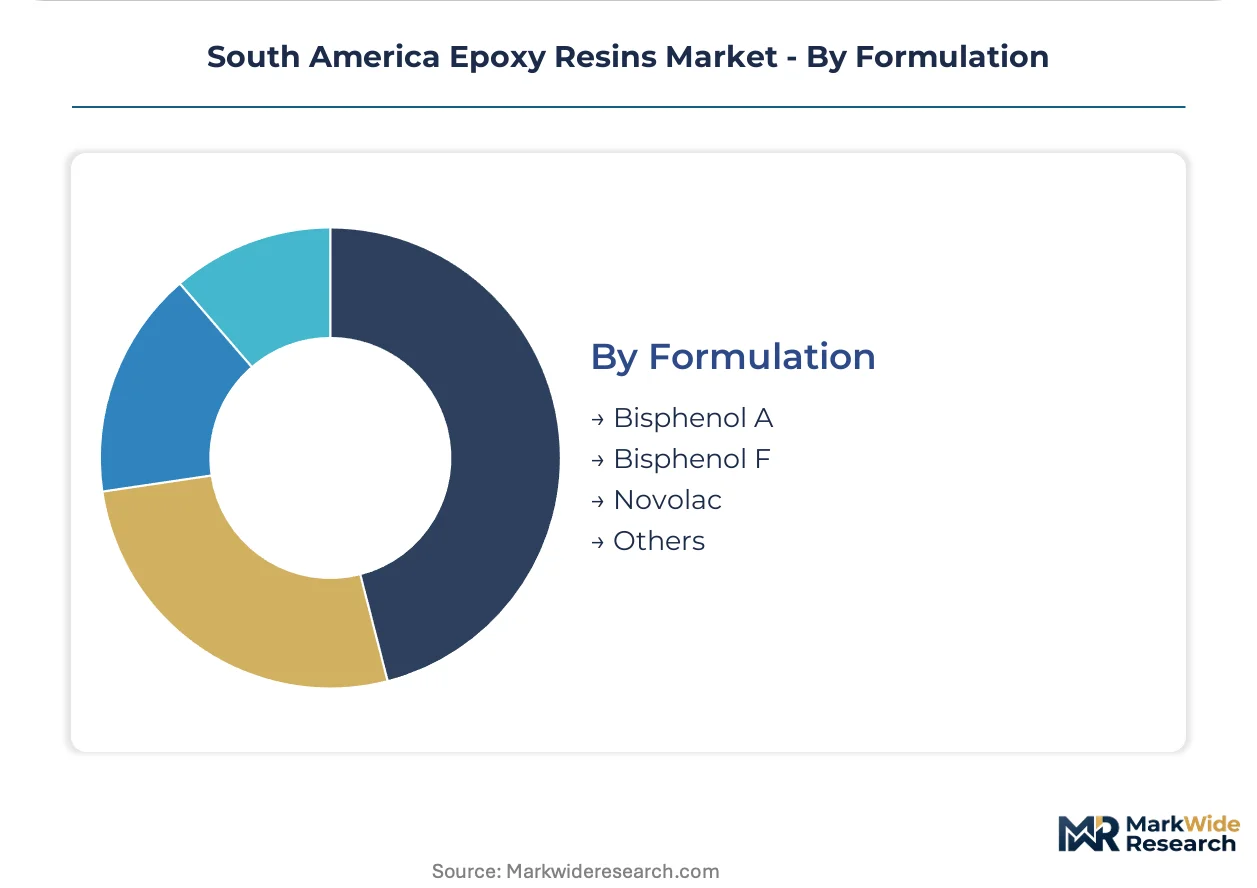
Epoxy resins comprise thermosetting polymers formed through the reaction of epichlorohydrin with bisphenol compounds, yielding cross-linked networks that withstand mechanical stress, chemical attack, and thermal cycling from negative forty degrees Celsius to above one hundred eighty degrees Celsius. Liquid epoxy formulations dominate volume consumption across South American coatings and adhesive applications due to their ease of handling and ambient temperature cure compatibility. Solid epoxy grades command premium positioning in powder coating segments where zero-VOC compliance drives specification in Brazilian automotive finishing lines. Bisphenol A-based formulations maintain the largest share of regional consumption, though novolac variants are capturing faster growth in corrosion-resistant industrial coatings for offshore oil platforms.
ANVISA governs chemical substance registration and toxicological evaluation for epoxy hardeners and diluents entering Brazilian manufacturing channels, while Argentina's national chemical regulator enforces parallel notification requirements that extend product approval timelines. REACH-equivalent frameworks under Mercosur harmonization discussions are pressuring formulators to consolidate ingredient disclosure documentation across both jurisdictions. Stakeholders must monitor regulatory divergence between Brazilian state-level environmental agencies and federal chemical policies to anticipate compliance cost shifts that could reshape sourcing strategies.
Market Dynamics
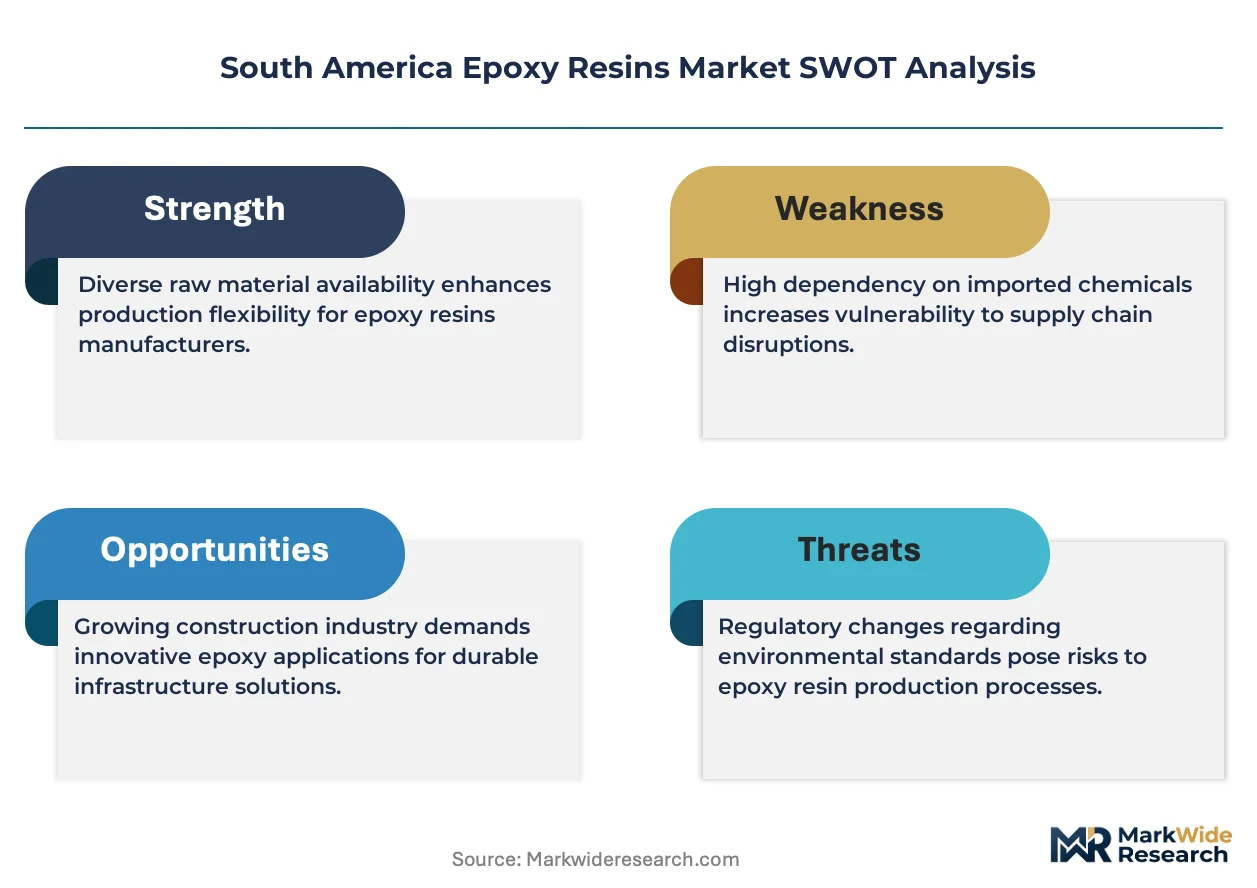
Wind turbine OEM consolidation across Brazil and Argentina is compressing supplier margins while simultaneously locking in multi-year epoxy formulation contracts that favor technically integrated partners over commodity traders.
Growth Catalysts
- ANVISA registration harmonization:Brazil's chemical substance registry is pushing domestic blenders toward pre-approved imported hardeners, accelerating formal supply relationships with certified foreign formulators.
- Offshore platform coatings:Novolac epoxy variants are displacing conventional marine protection systems on Brazil's pre-salt rig maintenance schedules due to superior thermal shock resistance.
- São Paulo industrial corridor:Powder coating line conversions at Brazilian automotive plants are pulling solid epoxy resin volumes away from liquid formulation demand.
Market Restraints
- Bisphenol feedstock volatility:Covestro's captive phenol supply insulates it from spot market swings that punish non-integrated South American compounders.
- Argentina import licensing:The national chemical regulator's parallel notification requirements extend hardener approval timelines by eight to fourteen months versus Brazilian clearances.
- Vinyl ester substitution:Marine fabricators on Argentina's Atlantic coast are specifying vinyl ester resins for hull laminates where epoxy once dominated due to faster cure cycles.
Strategic Opportunities
- Uruguay wind development:The country's nascent onshore wind pipeline lacks established blade supply chains, creating first-mover positioning for epoxy system integrators.
- Mercosur REACH-equivalent frameworks:Harmonized toxicological disclosure requirements will advantage formulators with existing EU-REACH dossiers over local competitors.
- UV-curable epoxy hybrids:Convergence of cationic photopolymerization with conventional amine curing is opening industrial wood coating segments previously closed to thermal-cure epoxies.
Industry Challenges
- Formulation chemist scarcity:Brazilian universities produce insufficient polymer science graduates to staff technical service labs at expanding adhesive compounders.
- State-federal regulatory divergence:São Paulo's environmental agency enforces VOC limits stricter than ANVISA federal baselines, forcing dual-compliance testing for coatings sold across state lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Epoxy Resins Market |
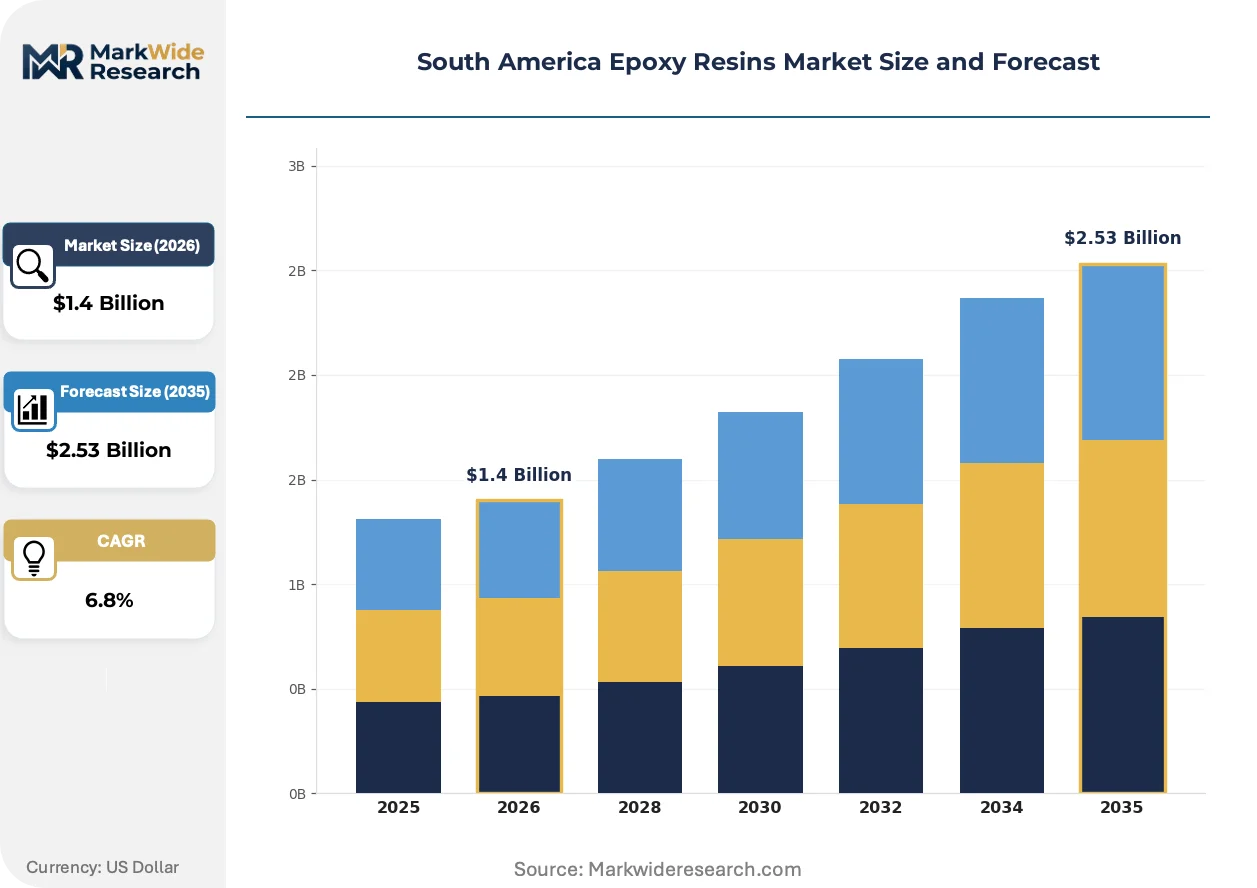
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Solid, Powder, Emulsion Application: Aerospace, Automotive, Marine, Electronics End User: Construction, Coatings, Adhesives, Composites Formulation: Bisphenol A, Bisphenol F, Novolac, Others |
| Companies Covered | 3M, Covestro AG, Hexion, Huntsman International LLC, Olin Corporation, BASF SE, DuPont de Nemours, Inc., Aditya Birla Chemicals, Daicel Corporation, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Epoxy Resins Market Evolving Landscape
Bio-based feedstock substitution and curing chemistry advances are fragmenting the traditional bisphenol-epichlorohydrin supply architecture while regulatory pressure on substance toxicity is rewriting formulation disclosure requirements across the value chain.
Waterborne epoxy dispersions are absorbing volume from solvent-borne systems in Brazilian protective coatings. Industrial maintenance contractors in Minas Gerais mining operations are specifying these emulsions for tank linings where flammability restrictions previously blocked conventional epoxies. The technology is absorbing market share fastest in high-humidity application environments where solvent flash-off is unreliable.
ANVISA's 2025 toxicological evaluation deadline for existing chemical substances is forcing reformulation of legacy amine hardeners. Brazilian coatings manufacturers are accelerating substitution of cycloaliphatic alternatives ahead of the compliance window. Marine coating applicators along Argentina's coast face parallel pressure from the national chemical regulator's substance notification requirements.
Direct procurement relationships between wind blade fabricators and epoxy formulators are displacing distributor intermediaries. Large-scale OEMs in Brazil's southeastern corridor now negotiate multi-year supply agreements with technical service commitments. This pattern concentrates most visibly among turbine manufacturers sourcing pre-preg systems for blade root assemblies.
South America Epoxy Resins Market Segmentation
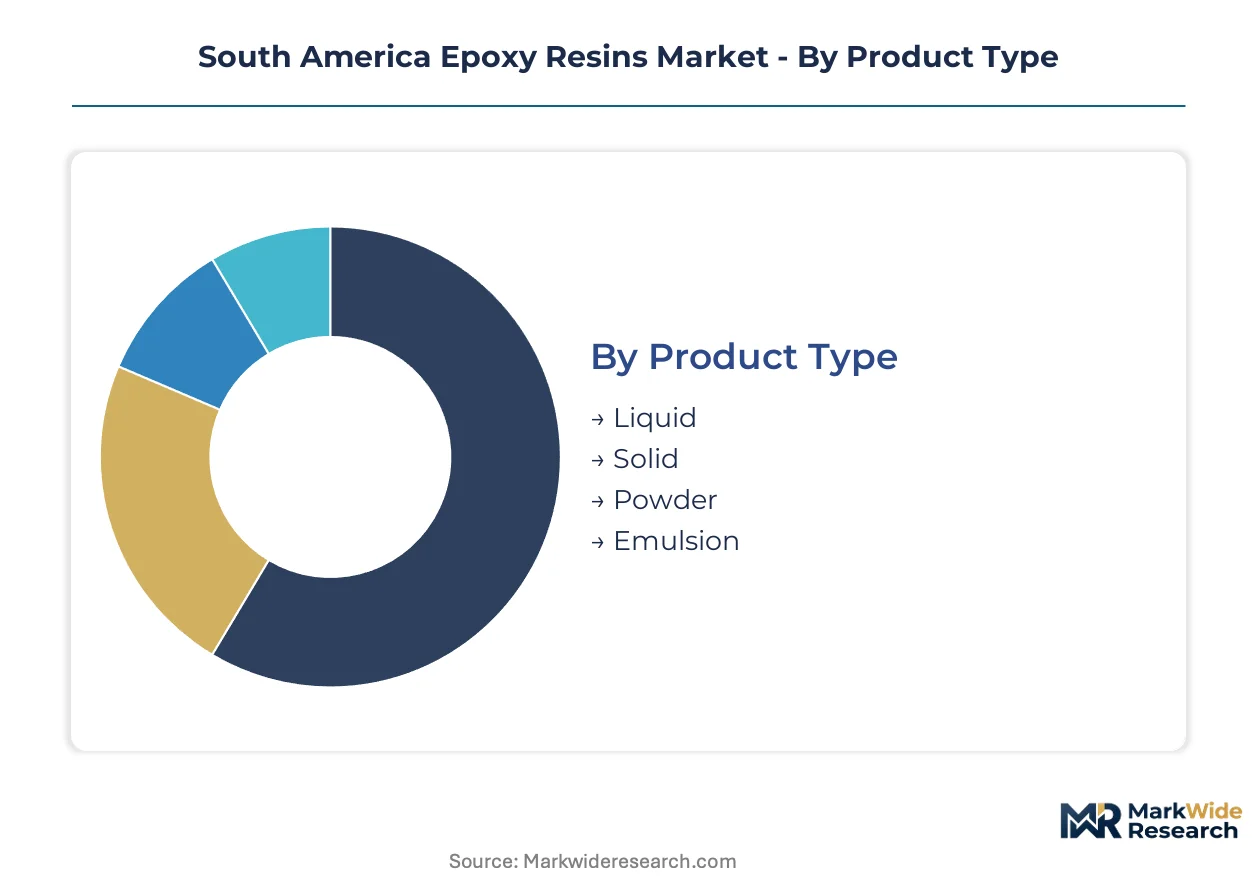
Epoxy resin specifications diverge sharply across South American industrial applications, with formulation chemistry and physical state determining compatibility with Brazil's ANVISA compliance frameworks and Argentina's import licensing protocols. Segmentation clarity enables suppliers to align technical service resources with the concentrated demand clusters in São Paulo's automotive corridor and Minas Gerais mining operations.
Product Type:
Supply concentration among Brazilian formulators favors liquid systems, while powder and emulsion technologies require specialized import partnerships or captive blending investments.
- Liquid:Ambient-temperature cure compatibility dominates coatings and adhesive applications across Brazil's southeastern industrial corridor. São Paulo-based automotive refinishing shops and Minas Gerais tank lining contractors specify these grades for humidity-tolerant application protocols.
- Solid:Zero-VOC compliance drives specification in Brazilian powder coating lines, particularly at automotive OEM finishing facilities converting from liquid systems. ANVISA registration requirements for imported solid grades compress supplier options to pre-certified formulators.
- Powder:Specialized curing agent integration supports high-temperature bake schedules at Brazilian appliance manufacturers.
- Emulsion:Waterborne dispersions penetrate protective coatings in high-humidity mining environments where solvent flash-off is unreliable.
Liquid formulations absorb the bulk of installed capacity; emulsion technologies are expanding most quickly.
Application:
Cost tier differentiation separates aerospace-qualified systems from commodity marine coatings, with certification overhead determining viable supplier participation.
- Marine:Novolac epoxy variants displace conventional protection systems on Brazil's pre-salt rig maintenance schedules due to superior thermal shock resistance. Argentina's Atlantic coast hull fabricators specify these grades for offshore platform corrosion barriers.
- Automotive:Solid epoxy powder coatings command premium positioning at Brazilian OEM finishing lines where VOC compliance is non-negotiable. São Paulo state environmental agencies enforce limits stricter than ANVISA federal baselines.
- Aerospace:Pre-preg system integration requires technical service commitments from qualified formulators with ANVISA-certified hardener portfolios.
- Electronics:Encapsulation grades serve Brazilian appliance manufacturers with thermal cycling specifications.
Marine applications anchor volume commitments; automotive coatings are climbing the fastest.
End User:
Customer type fragmentation concentrates procurement leverage among wind turbine OEMs, while construction and coatings segments sustain distributor intermediaries.
- Composites:Wind blade fabricators in Brazil's southeastern corridor negotiate direct multi-year supply agreements with epoxy system integrators, displacing traditional distribution channels. Pre-preg formulations for blade root assemblies concentrate demand among technically integrated partners.
- Construction:Adhesive compounders in São Paulo and Minas Gerais face formulation chemist scarcity as Brazilian universities produce insufficient polymer science graduates for technical service expansion.
- Coatings:Industrial maintenance contractors specify waterborne emulsions for tank linings under flammability restrictions.
- Adhesives:Structural bonding applications in Brazilian infrastructure projects require customized curing agent packages.
Composites command the steepest expansion trajectory; construction maintains the broadest geographic spread.
Formulation:
Margin structures favor bisphenol A-based systems, while novolac variants capture value through performance differentiation in corrosive environments.
- Bisphenol A:Largest share of regional consumption supports volume-scale procurement across coatings and adhesive applications. Brazilian blenders leverage pre-approved imported hardeners to manage ANVISA compliance costs.
- Novolac:Faster growth trajectory in corrosion-resistant industrial coatings for offshore oil platforms and marine maintenance schedules. Superior chemical resistance justifies premium positioning against conventional bisphenol systems.
- Bisphenol F:Lower viscosity profiles suit high-solids coatings formulations for Brazilian protective coatings contractors.
- Others:Bio-based feedstock substitution and specialty hardener combinations serve niche specification requirements.
Bisphenol A formulations dominate installed capacity; novolac systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wind turbine OEMs and blade fabricators concentrate procurement leverage in Brazil's southeastern corridor, while Argentine marine coaters and Chilean mining contractors sustain diversified demand pockets across the continent.
Brazil
Pre-salt offshore platform maintenance schedules drive novolac epoxy consumption for corrosion-resistant coatings. ANVISA's 2025 toxicological evaluation deadline forces reformulation of legacy amine hardeners ahead of the compliance window. São Paulo state's environmental agency enforces VOC limits stricter than federal baselines, compelling dual-compliance testing for coatings sold across state lines.
Argentina
Atlantic coast hull fabricators specify marine-grade systems for offshore platform corrosion barriers despite vinyl ester substitution pressure. The national chemical regulator's parallel notification requirements extend hardener approval timelines by eight to fourteen months versus Brazilian clearances. Buenos Aires province industrial zones concentrate procurement for protective coatings serving agricultural machinery manufacturers.
Chile
Copper mining operations in the Atacama Desert specify waterborne epoxy emulsions for tank linings under strict flammability restrictions. The country's national chemical regulator enforces substance registration protocols aligned with OECD guidelines. Antofagasta region maintenance contractors drive volume for high-solids protective coatings in ore processing facilities.
Colombia
Oilfield service companies in the Llanos Basin anchor demand for pipeline coating systems resistant to tropical humidity cycles. The national environmental licensing authority mandates chemical substance disclosure for imported formulations. Bogotá industrial corridors concentrate adhesive compounders serving infrastructure construction projects.
Uruguay
Nascent onshore wind development lacks established blade supply chains, creating first-mover positioning for epoxy system integrators. The country's chemical substance registry operates under Mercosur harmonization frameworks pending full implementation. Montevideo port logistics zones attract distributors positioning inventory for regional re-export to Brazilian and Argentine markets.
South America Epoxy Resins Market Competitive Landscape
European and North American producers anchor the premium-formulation tier; Asian specialists hold commodity-grade positioning through cost-optimized supply chains. The vendor base splits between integrated petrochemical conglomerates with captive bisphenol feedstocks and independent formulators competing on curing-agent customization. Three archetypes dominate: backward-integrated resin manufacturers, formulated-systems integrators with technical-service capabilities, and regional distributors with ANVISA-certified import portfolios. Competitive moves concentrate on multi-year supply agreements with wind turbine OEMs and pre-emptive ANVISA registration of hardener portfolios ahead of regulatory deadlines.
Within the integrated-manufacturer tier, Covestro AG exemplifies upstream control over phenol supply chains that insulate margin structures from feedstock volatility. Huntsman International LLC anchors the formulated-systems archetype through technical-service relationships with composite fabricators. Hexion occupies a specialist position in custom curing-agent packages for marine coating applicators. These three entities represent distinct competitive vectors: feedstock security, application engineering, and formulation chemistry respectively.
| Leading Market Players |
|---|
| 3M |
| Covestro AG |
| Hexion |
| Huntsman International LLC |
| Olin Corporation |
| BASF SE |
| DuPont de Nemours, Inc. |
| Aditya Birla Chemicals |
| Daicel Corporation |
| Others |
Value Network & Pricing Analysis
Bisphenol A spot price volatility cascades through South American epoxy resin value chains, compressing margins for non-integrated compounders while amplifying pricing power for backward-integrated manufacturers with captive phenol supply. ANVISA registration costs for imported hardeners add fixed compliance layers that stratify pricing tiers between certified formulators and commodity traders.
Pricing Analysis
Volume commitments separate liquid formulation contracts from solid-grade premiums in Brazilian automotive powder coating lines. Three-tier pricing structure across certified-system, standard-grade, and economy-blend levels reflects ANVISA registration status and technical service bundling. Cost compression in commodity liquid epoxies is intensifying because Asian import volumes are pressuring regional blenders. Wind turbine OEMs exhibit lowest price sensitivity due to performance guarantees, while construction adhesive compounders face acute margin pressure from specification-grade alternatives.
Supply Chain Analysis
Single-source vulnerability sits with German and US specialty chemical producers dominating pre-certified hardener portfolios for ANVISA compliance. Epichlorohydrin and bisphenol feedstocks draw from Middle Eastern and Asian petrochemical complexes, exposing Brazilian formulators to freight rate volatility and currency fluctuation. Regulatory restriction through Argentina's extended approval timelines creates inventory positioning risk for cross-border distributors. Distribution runs through São Paulo-based technical distributors with ANVISA-certified import licenses, consolidating last-mile access to Minas Gerais mining and southeastern automotive corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American epoxy resins constitute a vertical-integration race where control over bisphenol feedstocks and ANVISA-certified hardener portfolios determines margin sustainability. Players are pursuing backward integration into phenol supply chains to insulate pricing power from commodity volatility.
For Market Incumbents: To counter vinyl ester substitution in Argentine marine hull fabrication, Covestro and Huntsman should deepen captive feedstock positions and lock multi-year technical service agreements with Brazilian wind blade OEMs. ANVISA registration acceleration for novolac curing agent portfolios will preempt 2025 compliance deadlines and freeze out non-certified competitors. For New Entrants and Emerging Players: Uruguayan wind farm developers without established blade supply chains represent the most penetrable buyer archetype for epoxy system integrators willing to front technical service investments. First-mover positioning in Montevideo port logistics zones enables regional re-export arbitrage into Brazilian and Argentine markets. Partner with European formulators possessing existing REACH dossiers to shortcut Mercosur harmonization pathways. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap Brazilian compounders with ANVISA-certified import portfolios and stranded technical service capacity in São Paulo state. Long-term viability hinges on feedstock integration completion and wind energy demand persistence. Monitor ANVISA substance evaluation rulings on cycloaliphatic amines as inflection indicators for formulation chemistry winners.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Supply | Covestro's captive feedstock control insulates margin structures from bisphenol spot volatility. |
| ANVISA Hardener Portfolio Registration | Pre-approved imported formulations accelerate supply relationships with certified wind blade fabricators. |
| Long-term Supply Agreement with Wind OEMs | Multi-year technical service contracts displace distributor intermediaries in Brazil's southeastern corridor. |
| Joint Venture in Uruguay Wind Supply Chain | First-mover positioning captures nascent onshore blade demand lacking established formulator relationships. |
| Green Manufacturing Transition to Bio-based Feedstocks | Epichlorohydrin substitution from glycerol sources addresses regulatory pressure on substance toxicity profiles. |
Research Methodology
Multi-period observation of bisphenol feedstock pricing, ANVISA registration timelines, and wind turbine installation rates anchored the trend analysis, supplemented by interviews with epoxy formulator technical directors, Brazilian automotive procurement leads, Argentine marine coating applicators, and Minas Gerais mining maintenance contractors. Secondary validation drew from customs trade data, ACC regional chemical reports, SEC 10-K disclosures from listed producers, and ANVISA substance registry filings. Bottom-up volume modeling triangulated against top-down macroeconomic projections across the analysis window.
Input-output matrices mapped epoxy resin consumption by formulation chemistry, physical state, end-use industry, and regional regulatory cluster throughout the forecast period. CAGRs were derived from segmented demand elasticity modeling and supply-side capacity announcements. Forecast inputs incorporated wind energy capacity expansion pipelines, automotive OEM finishing line conversion schedules, and pre-salt offshore platform maintenance cycles.
Revisions become necessary when ANVISA regulatory deadlines shift, Mercosur harmonization frameworks stall, or vinyl ester substitution accelerates in Argentine marine applications. Forecasts reflect documented assumptions about feedstock price correlation and certification timeline standardization. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Polyethylene Glycol Market
Polymers & Resins
PEG 3500 Market
Polymers & Resins
Antiviral Polymers for Packaging Market
Polymers & Resins
Expanded Polypropylene (EPP) Foam Market
Polymers & Resins
Brazil Engineering Plastics Market
Polymers & Resins
Resorcinol Formaldehyde Resin Market
Polymers & Resins
Cellulosic Polymers Market
Polymers & Resins
Polyether Amine Market
Polymers & Resins
Global Opaque Polymers Market
Polymers & Resins
Bio-Based Thermoplastic Elastomer Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
Europe Chromatography Resins Market
Polymers & Resins
Polyvinyl Butyral (PVB) Market
Polymers & Resins
Plastisols Market
Polymers & Resins
Hair Styling Biopolymers Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market