
 Europe Fluoropolymer Market | 2026-2036
Europe Fluoropolymer Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Fluoropolymer Market Insights
CE marking under the EU Construction Products Regulation is unwinding competitive access for non-EU fluoropolymer compounders. Solvay anchors its position through backward integration into hydrogen fluoride and fluorspar sourcing across Belgium and France. Arkema differentiates via specialty PVDF grades for battery binders and water filtration membranes. HaloPolymer competes on price-positioned PTFE volumes delivered through established distributor networks in Eastern Europe.
Fluoropolymers comprise carbon-fluorine backbone polymers such as polytetrafluoroethylene, fluorinated ethylene propylene, and perfluoroalkoxy alkanes, synthesized via free-radical polymerization of fluorinated monomers at elevated pressures to achieve thermal stability exceeding 260°C and near-universal chemical inertness. PTFE dominates volume flows across Europe due to its established supply base and lowest unit cost among fluorinated polymers, though PFA captures expanding margin pools in semiconductor fabrication and pharmaceutical fluid handling where extractable limits tighten. Industrial grade materials retain the largest revenue share within grade segmentation, while pharmaceutical grade specifications accelerate fastest as bioprocessing equipment manufacturers in Ireland and Switzerland upgrade purity certifications.
The European Chemicals Agency enforces REACH registration and restriction protocols for per- and polyfluoroalkyl substances, directly reshaping reformulation investments and substitution timelines across the value chain. The EU F-Gas Regulation and MDR framework for medical devices jointly determine which fluoropolymer grades qualify for long-term supply contracts in climate-control and implantable component applications. Stakeholders must monitor ECHA's ongoing PFAS restriction proposal to anticipate which polymer chemistries will retain lawful production status and plan qualification transitions accordingly.
Market Dynamics
REACH registration protocols and the ECHA PFAS restriction proposal are forcing compounders to accelerate reformulation timelines and secure alternative feedstock pathways before 2025 regulatory milestones.
Growth Catalysts
- EU F-Gas Regulation phase-down:Tightening schedules for virgin fluorinated gases are driving chemical processors in Germany and France toward fluoropolymer-lined vessels as containment solutions.
- Battery-grade PVDF demand:Electric vehicle cell manufacturing expansion across Hungary and Poland is pulling specialty binder materials into qualification pipelines.
- Semiconductor fabrication:High-purity PFA tubing systems are displacing conventional materials in Irish and Swiss bioprocessing equipment as extractable limits tighten.
Market Restraints
- Hydrogen fluoride supply concentration:Captive fluorspar sourcing in Belgium and France limits third-party compounder access to critical feedstock.
- REACH compliance costs:Registration dossier preparation for per- and polyfluoroalkyl substances consumes 18-24 month timelines and six-figure investments.
- Mechanical property limitations:PTFE cold-flow characteristics restrict load-bearing applications, ceding structural polymer markets to PEEK and PPS.
Strategic Opportunities
- Water filtration membranes:Specialty PVDF grades for municipal and industrial treatment plants in Spain and Italy offer margin expansion beyond commodity PTFE.
- EU Green Deal procurement mandates:Public infrastructure projects are embedding circular material requirements that favor regional compounders with recycling capabilities.
- Medical device convergence:MDR framework alignment between fluoropolymer suppliers and implantable component manufacturers in Switzerland accelerates long-term contract capture.
Industry Challenges
- Fluoropolymer processing expertise:Sintering and compression molding skill gaps constrain expansion of qualified technical workforce across Eastern European manufacturing zones.
- Multi-grade certification timelines:Pharmaceutical and aerospace qualification protocols require 24-36 month validation cycles that delay revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Fluoropolymer Market |
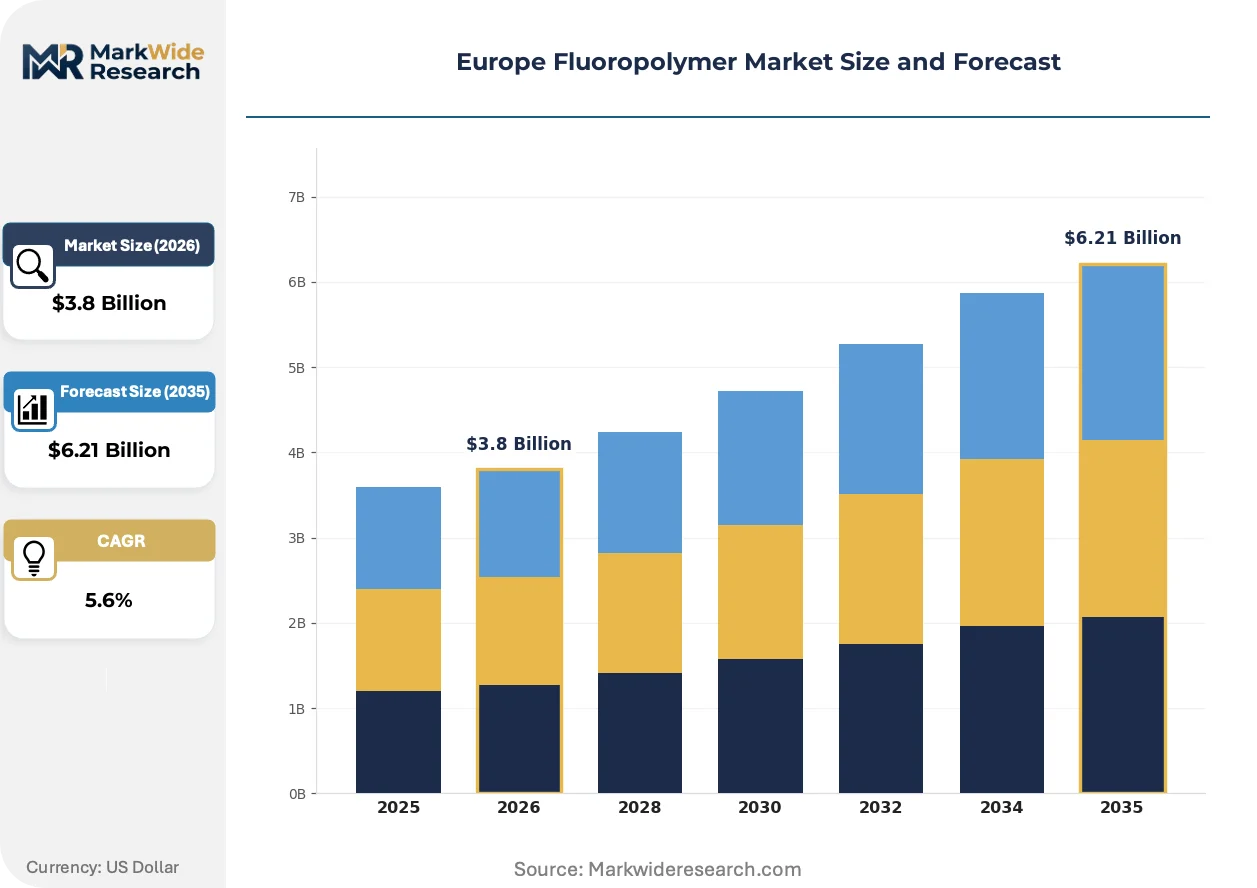
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PTFE, FEP, PFA, ETFE Application: Electrical Insulation, Coating, Sealing, Gaskets End User: Aerospace, Automotive, Chemical Processing, Oil & Gas Grade: Industrial, Pharmaceutical, Food Grade, Low-Friction |
| Companies Covered | AGC Inc., HaloPolymer, 3M, Kureha Corporation, Gujarat Fluorochemicals Limited, Arkema, Solvay, Saint-Gobain, The Chemours Company, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Fluoropolymer Market Trends and Innovations
Material science advances and regulatory chemistry restrictions are splitting the European fluoropolymer landscape into high-purity premium grades and industrial commodity volumes.
Modified PTFE with improved creep resistance is bifurcating the sealing applications market. Automotive powertrain engineers in Germany specify these grades for transmission systems operating above 150°C. The technology is compressing margins on conventional PTFE while expanding addressable load-bearing applications previously closed to fluoropolymers.
ECHA's ongoing PFAS restriction proposal is forcing compounders to segment their product portfolios into polymers of low concern versus substances facing sunset dates. Industrial-grade FEP and ETFE manufacturers are accelerating dossier submissions to secure registry continuity. Battery and semiconductor end-users are demanding supply-chain documentation proving polymer backbone chemistry falls outside restriction scopes.
Specification-driven procurement is consolidating buyer power among original equipment manufacturers in Ireland and Switzerland. Distributor networks in Eastern Europe are losing technical specification influence as direct compounder-engineering relationships deepen. Spain and Italy exhibit the most compressed switching cycles, with aerospace contractors qualifying multiple PFA tubing sources simultaneously to mitigate supply risk.
Europe Fluoropolymer Market Segmentation
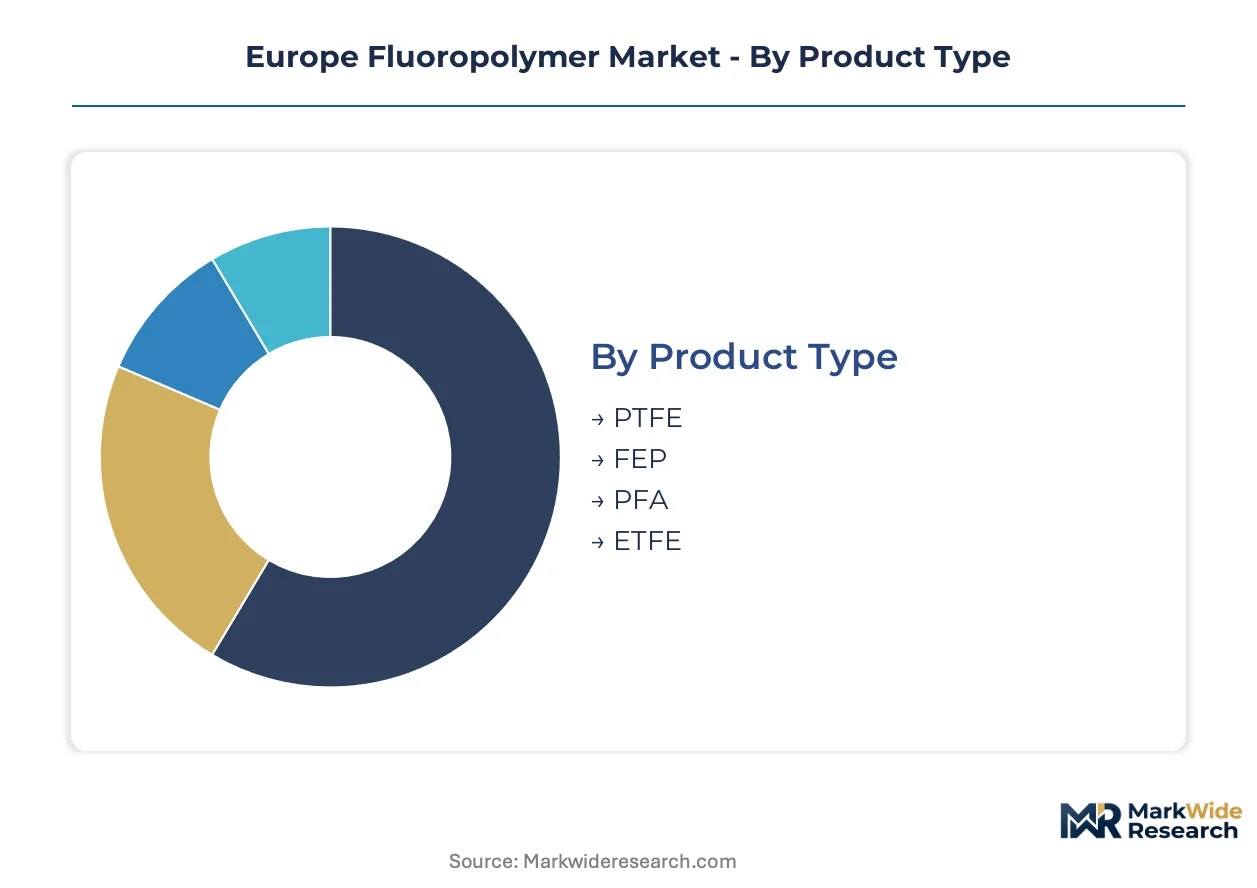
Margin distribution across Europe's fluoropolymer market tracks closely to certification intensity and end-use criticality. Product chemistry and purity specifications determine pricing power, while application complexity shapes procurement relationships between compounders and OEMs.
Product Type:
Profit pools concentrate in high-purity grades serving semiconductor and pharmaceutical end-users, while commodity volumes flow through industrial distribution channels.
- PTFE:Polytetrafluoroethylene comprises carbon-fluorine backbone chains synthesized via free-radical polymerization, delivering thermal stability above 260°C and near-universal chemical inertness. Chemical processing plants across Germany and France specify PTFE-lined vessels as the EU F-Gas Regulation tightens containment requirements for virgin fluorinated gases.
- PFA:Perfluoroalkoxy alkanes combine melt-processability with PTFE-equivalent chemical resistance, enabling extruded tubing and injection-molded components. Semiconductor fabrication facilities in Ireland and Switzerland are accelerating qualification timelines for high-purity PFA fluid handling systems as extractable limits tighten.
- FEP:Fluorinated ethylene propylene offers lower processing temperatures than PTFE with comparable dielectric performance for wire insulation applications.
- ETFE:Ethylene tetrafluoroethylene copolymer balances mechanical toughness with chemical resistance for architectural membrane and cable jacketing applications.
PTFE holds installed capacity. PFA is rotating up the share rankings.
Application:
Specification intensity varies sharply across use cases, with aerospace and semiconductor procurement demanding full supply-chain documentation under REACH protocols.
- Sealing:Gaskets, O-rings, and packings exploit PTFE's compressibility and chemical inertness to contain aggressive process fluids. Automotive powertrain engineers in Germany specify modified PTFE grades with improved creep resistance for transmission systems operating above 150°C.
- Electrical Insulation:Dielectric films and wire coatings leverage fluoropolymer thermal stability and low dissipation factors for high-frequency signal transmission. Aerospace harness manufacturers in Italy and Spain are qualifying FEP and ETFE insulation for next-generation avionics as operating temperatures rise.
- Coating:Non-stick and corrosion-resistant surface treatments apply PTFE dispersions to process equipment and consumer goods.
- Gaskets:Static sealing elements for flanged connections in chemical processing and oil & gas infrastructure.
Sealing commands the steepest expansion trajectory. Electrical insulation maintains qualification backlog advantages.
End User:
Customer concentration patterns split between project-driven capital equipment procurement and recurring consumables for maintenance operations.
- Chemical Processing:Reactor linings, heat exchanger coatings, and pump seals demand industrial-grade PTFE and FEP for sulfuric acid and chlorine dioxide exposure. Procurement teams at BASF and Arkema sites are expanding fluoropolymer-lined vessel orders ahead of EU F-Gas Regulation phase-down milestones.
- Aerospace:Fuel system components, wire insulation, and sealing elements require lot-traceable materials with full material certification. Contractors in Italy and Spain are qualifying multiple PFA tubing sources simultaneously to mitigate supply risk in fluid conveyance systems.
- Automotive:Powertrain seals, fuel line coatings, and battery component insulation drive specification volumes.
- Oil & Gas:Downhole packings, valve seals, and pipeline coatings for corrosive production environments.
Chemical processing anchors volume demand. Aerospace is climbing the fastest on value per kilogram metrics.
Grade:
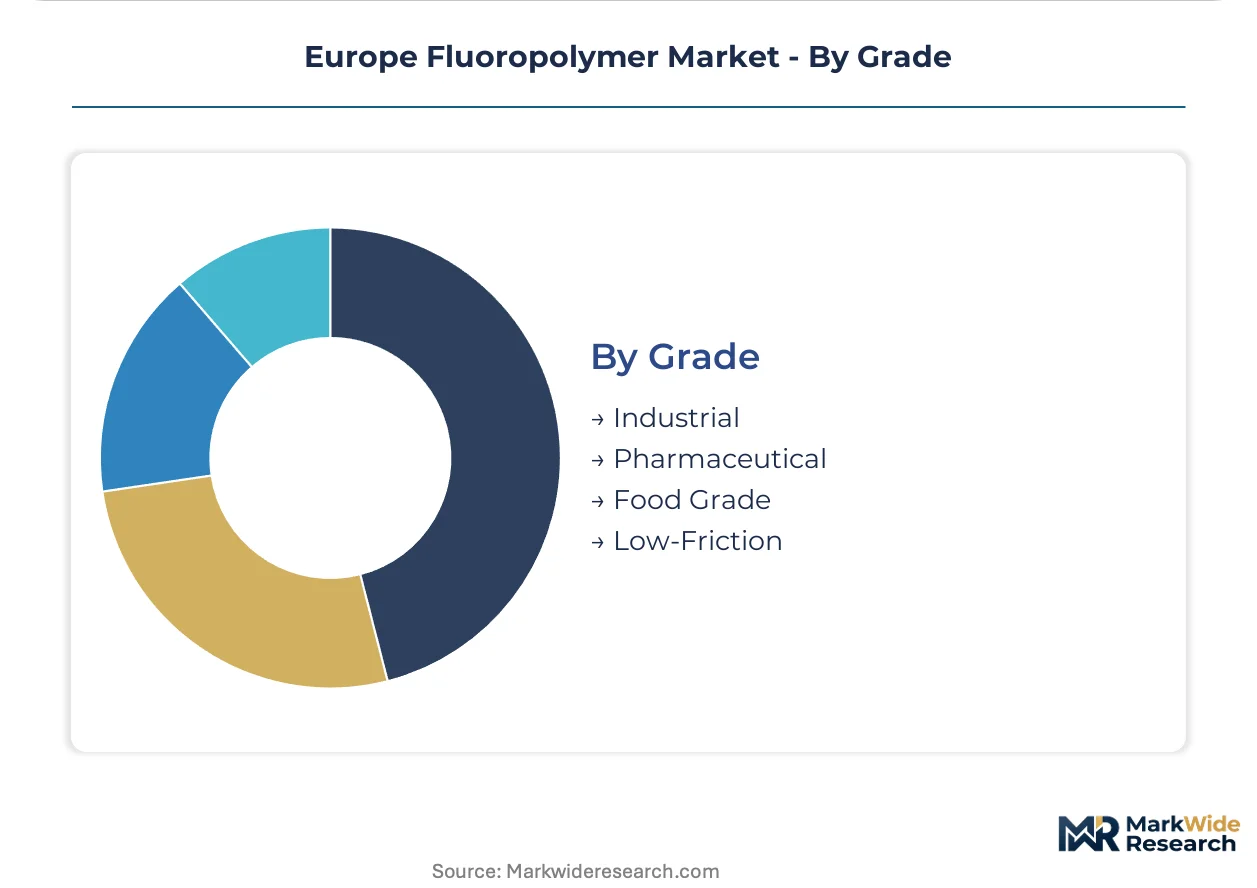
Certification tier determines accessible end-use markets and pricing power, with pharmaceutical and food contact grades requiring dedicated production lines and audit protocols.
- Industrial:Standard purity specifications for chemical processing, automotive, and general sealing applications where extractable limits remain unspecified. This grade captures the largest revenue share within European segmentation as established supply bases and lowest unit costs sustain volume flows.
- Pharmaceutical:USP Class VI and EP 3.1 compliance for bioprocessing equipment, single-use systems, and implantable component manufacturing. Bioprocessing equipment manufacturers in Ireland and Switzerland are upgrading purity certifications, accelerating this grade's expansion.
- Food Grade:FDA and EFSA compliance for processing equipment contact surfaces in dairy, beverage, and prepared food applications.
- Low-Friction:Modified PTFE formulations with fillers for bearing and wear applications requiring controlled coefficient of friction.
Industrial grade retains capacity dominance. Pharmaceutical grade is gaining share fastest on margin expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation's accelerated phase-down schedule is redistributing fluoropolymer demand across European industrial clusters. Chemical processors in Germany and France are expanding fluoropolymer-lined vessel procurement ahead of containment mandates. Battery manufacturers in Central Europe are pulling specialty PVDF grades into qualification pipelines.
Germany
Automotive powertrain engineers specify modified PTFE grades with improved creep resistance for transmission systems operating above 150°C. The EU F-Gas Regulation drives BASF and other chemical processors to expand fluoropolymer-lined vessel orders. Industrial concentration centers on the Ruhr region and Bavaria, where sealing and coating applications dominate procurement volumes.
France
Aerospace contractors accelerate qualification timelines for high-purity PFA tubing systems in fluid conveyance applications. ECHA's PFAS restriction proposal forces compounders to segment portfolios into polymers of low concern versus substances facing sunset dates. The Lyon-Grenoble corridor anchors specialty PVDF development for battery binders and water filtration membranes.
Switzerland
Bioprocessing equipment manufacturers upgrade pharmaceutical-grade purity certifications for single-use systems and implantable components. The MDR framework for medical devices determines which fluoropolymer grades qualify for long-term supply contracts. Basel and Zurich host concentrated OEM procurement teams demanding full supply-chain documentation under REACH protocols.
Ireland
Semiconductor fabrication facilities displace conventional materials with high-purity PFA fluid handling systems as extractable limits tighten. Specification-driven procurement consolidates buyer power among original equipment manufacturers. Cork and Dublin clusters exhibit compressed switching cycles, with contractors qualifying multiple PFA tubing sources simultaneously to mitigate supply risk.
Italy
Aerospace harness manufacturers qualify FEP and ETFE insulation for next-generation avionics as operating temperatures rise. The EU Green Deal embeds circular material requirements in public infrastructure projects. Milan-Turin industrial zones concentrate electrical insulation demand, while Southern Italian municipalities deploy specialty PVDF membranes in water treatment plants.
Europe Fluoropolymer Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive fluorspar sourcing and backward integration into hydrogen fluoride production. Market structure concentrates around three to four compounders controlling critical feedstock pathways, while specialty distributors serve price-sensitive industrial volumes in Eastern Europe. Strategic archetypes include vertically integrated feedstock owners, specialty-grade formulators, and regional volume distributors. Dominant competitive moves encompass capacity expansion in battery-grade PVDF and strategic partnerships with semiconductor OEMs for high-purity qualification.
Among Belgium and France-based integrated producers, Solvay anchors the feedstock-secured tier through hydrogen fluoride and fluorspar sourcing control. Arkema exemplifies the specialty-grade formulator archetype with differentiated PVDF positions. HaloPolymer occupies a price-positioned volume role through established distributor networks in Eastern Europe. These three represent distinct competitive vectors: feedstock security, application specialization, and regional cost leadership.
| Leading Market Players |
|---|
| AGC Inc. |
| HaloPolymer |
| 3M |
| Kureha Corporation |
| Gujarat Fluorochemicals Limited |
| Arkema |
| Solvay |
| Saint-Gobain |
| The Chemours Company |
| Others |
Pricing and Supply Chain Analysis
REACH registration protocols and the EU F-Gas Regulation phase-down schedule operate as dual gatekeepers, simultaneously determining which compounders qualify for supply contracts and how pricing power stratifies across certification tiers. Hydrogen fluoride feedstock concentration in Belgium and France creates asymmetric cost positions that compounders translate into tiered margin structures, while pharmaceutical-grade specifications in Ireland and Switzerland command substantial premia over industrial volumes.
Pricing Analysis
Long-term offtake contracts with fluorspar indexation dominate procurement between integrated producers and chemical processors in Germany and France. Price differentiation rests on certification grade—pharmaceutical USP Class VI specifications versus industrial standard—and captive hydrogen fluoride sourcing versus merchant market dependence. Cost compression in commodity PTFE intensifies as modified grades with improved creep resistance capture automotive powertrain applications above 150°C. Project-driven buyers in aerospace exhibit lowest price sensitivity, while maintenance procurement through Eastern European distributor networks faces acute margin pressure.
Supply Chain Analysis
Strategic stockpiling of fluorspar and hydrogen fluoride prevails among integrated compounders, while specialty distributors maintain lean just-in-time inventories of finished PTFE resins. Supply concentrates in Belgium, France, and Germany through backward integration into mine-mouth fluorspar operations and captive hydrogen fluoride production. Raw material dependencies encompass fluorspar ore, sulfuric acid for HF conversion, and fluorinated monomer feedstocks. Single-source vulnerability around Belgian fluorspar deposits exposes third-party compounders to supply interruption. Distribution runs through direct compounder-OEM relationships for high-purity grades and established distributor networks for industrial volumes in Eastern Europe.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's fluoropolymer market sits in early-cycle expansion as battery-grade PVDF demand from Hungarian and Polish cell manufacturing accelerates qualification pipelines and pulls specialty capacity into dedicated production lines.
For Market Incumbents: Consolidate feedstock security through captive fluorspar sourcing agreements or hydrogen fluoride offtake positions before 2025 regulatory milestones tighten supply access. Expand pharmaceutical-grade certification capabilities in Switzerland and Ireland to capture MDR-aligned medical device contracts as qualification timelines compress. Battery binder specialization represents the priority capacity allocation lever against commodity PTFE margin erosion. For New Entrants and Emerging Players: Technical service gaps in fluoropolymer processing expertise across Eastern European manufacturing zones offer white-space entry points where incumbent compounders under-serve qualified workforce development. Water filtration membrane applications in Southern Italy and Spain present the most penetrable segment, with municipal procurement cycles shorter than aerospace or semiconductor qualification protocols. A technical partnership model with regional engineering firms accelerates sintering and compression molding capability deployment without captive feedstock investment. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core fluoropolymer units amid ECHA PFAS restriction uncertainty. Five-to-ten year viability hinges on portfolio positioning toward polymers of low concern versus substances facing sunset date exposure. Specialty-grade formulators with battery or semiconductor qualification pipelines represent the acquisition archetype with defensive characteristics. The signal to watch is ECHA's final PFAS restriction scope determination, which would trigger accelerated qualification transitions and stranded asset risk for non-compliant chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Hydrogen Fluoride | Secures feedstock continuity for Belgian and French compounders facing EU F-Gas phase-down constraints. |
| Pharmaceutical Grade Certification Investment | Unlocks MDR-aligned supply contracts with Swiss and Irish bioprocessing equipment manufacturers. |
| Battery-Grade PVDF Capacity Expansion | Captures qualification pipelines from Hungarian and Polish electric vehicle cell manufacturing clusters. |
| Long-term Supply Agreement with Semiconductor OEMs | Locks in high-purity PFA tubing demand from Irish and Swiss fabrication facilities as extractable limits tighten. |
| Joint Venture for Eastern European Distribution | Extends technical service reach into price-sensitive industrial markets through established local networks. |
Research Methodology
A standing panel of plant managers at German and French chemical processing facilities, procurement leads at battery cell manufacturers in Hungary and Poland, and technical R&D directors at Belgian fluoropolymer compounders provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH registration databases, EU F-Gas Regulation implementation reports, Cefic chemical industry statistics, and customs trade flow data for fluorinated polymer categories. Bottom-up demand modeling across end-use applications triangulated against top-down supply capacity assessments.
Consistency checks against external benchmarks validated volume and value outputs across the analysis window. The analytical framework segmented demand by grade tier, end-use industry, and regional production hub, with additional dimensioning by certification intensity. CAGRs were derived from installed capacity expansion schedules, qualification timeline assumptions, and substitution elasticity parameters for competing materials like PEEK and PPS in load-bearing applications.
Forecasts assume regulatory continuity in REACH registration protocols and the EU F-Gas Regulation phase-down schedule; material policy shifts would require re-modeling of feedstock access and substitution timelines. Specific risk factors encompass ECHA's final PFAS restriction scope, fluorspar supply disruption from Belgian mining operations, and accelerated battery chemistry transitions away from PVDF binders. Revision becomes warranted when hydrogen fluoride spot pricing volatility or regulatory restriction announcements cross threshold levels that invalidate base-case supply assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Ethylene Vinyl Acetate (EVA) Market
Polymers & Resins
Lactic Acid and Polylactic Acid Market
Polymers & Resins
India Epoxy Resins Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
North America Flame Retardant Thermoplastics Market
Polymers & Resins
Plastic Compounding Market
Polymers & Resins
Global Hydroxypropyl Cellulose Market
Polymers & Resins
Polytetrafluoroethylene (PTFE) Market
Polymers & Resins
Global Polyphenylene Market
Polymers & Resins
Polyurethane (PU) Microspheres Market
Polymers & Resins
Acrylonitrile Styrene Acrylate (ASA) Market
Polymers & Resins
Closed Cell Polyurethane Foam Market
Polymers & Resins
Global Ion Exchange Resin Market
Polymers & Resins
Global Blow Molding Resins Market
Polymers & Resins
Polyether Block Amide Market