
 Organosilicon Electrolyte Market | 2026-2036
Organosilicon Electrolyte Market Size, Share, and Industry Trends Forecast 2026-2036
Organosilicon Electrolyte Market Outlook
The capital-intensity divergence between integrated chemical conglomerates and specialty electrolyte developers is unwinding competitive dynamics across the organosilicon supply chain. Shin-Etsu Chemical Co., Ltd. leverages its captive silicone monomer production to anchor cost positions in organosilicon precursor supply. Silatronix Inc. specializes in molecular architectures that extend cycle life for silicon-anode lithium-ion configurations. BASF SE competes through formulated electrolyte portfolios that integrate organosilicon co-solvents with conventional carbonate systems.
Organosilicon electrolytes incorporate silicon-containing functional groups—typically siloxane, silane, or silyl ester moieties—into lithium-ion battery electrolyte formulations to enhance thermal stability and suppress gas generation above four volts versus lithium metal. Liquid Electrolyte formulations currently dominate commercial deployment, though Solid Electrolyte segments are attracting disproportionate R&D investment as solid-state battery timelines compress. Battery Systems applications command the largest absolute demand, while Supercapacitors represent a faster-growing but smaller volume outlet for organosilicon additives.
The US EPA and NHTSA coordinate chemical safety review with vehicle electrification mandates that indirectly elevate electrolyte performance standards. China's SAMR enforces GB standards that specify silicon-based additive thresholds for domestic battery certification. Japan's METI funds organosilicon electrolyte development through its green innovation program. Stakeholders must monitor how divergent national battery testing protocols reshape formulation requirements before committing to regional capacity.
Market Dynamics
High-nickel cathode chemistry adoption is forcing electrolyte formulators to develop thermal suppression capabilities that conventional carbonate systems cannot deliver, restructuring procurement relationships between battery cell manufacturers and specialty chemical suppliers.
Growth Catalysts
- GB Standard Tightening:China's SAMR mandates stricter silicon-based additive thresholds for domestic lithium-ion battery certification, compelling cell producers to reformulate electrolyte portfolios.
- Silicon-Anode Proliferation:Battery systems incorporating silicon-dominant anodes require organosilicon co-solvents to manage volume expansion and solid-electrolyte interphase stability.
- South Korean Cluster Concentration:Cell manufacturing around Ulsan and Gwangju is concentrating demand for organosilicon precursors, anchoring regional supply chain investments.
Market Restraints
- Silicone Monomer Supply Concentration:Captive production of chlorosilane feedstock resides with integrated chemical conglomerates, limiting independent electrolyte developer cost control.
- Fluorinated Solvent Substitution:Partial functional overlap with fluorinated carbonate additives creates formulation competition in high-voltage cell architectures.
- REACH Registration Burden:ECHA compliance timelines for novel organosilicon molecules extend commercialization cycles for European market entry.
Strategic Opportunities
- India PLI Scheme Alignment:Production-linked incentives for advanced chemistry cell manufacturing create electrolyte formulation partnerships with domestic battery projects.
- Solid-State Convergence:Hybrid solid-liquid electrolyte architectures combining organosilicon polymers with sulfide ceramics open intermediate commercialization pathways.
- Supercapacitor Channel Expansion:Direct supply relationships with energy storage system integrators bypass traditional battery chemical distribution tiers.
Industry Challenges
- Electrochemist Talent Scarcity:Formulation expertise spanning silicon chemistry and lithium-ion interfacial science commands premium compensation and extended hiring cycles.
- Dual Certification Complexity:Simultaneous GB standard compliance for China and UN 38.3 transport testing creates parallel validation requirements for global product launches.
- Legacy Carbonate Integration:Retrofitting existing electrolyte blending equipment for organosilicon co-solvent handling requires capital expenditure on corrosion-resistant infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Organosilicon Electrolyte Market |
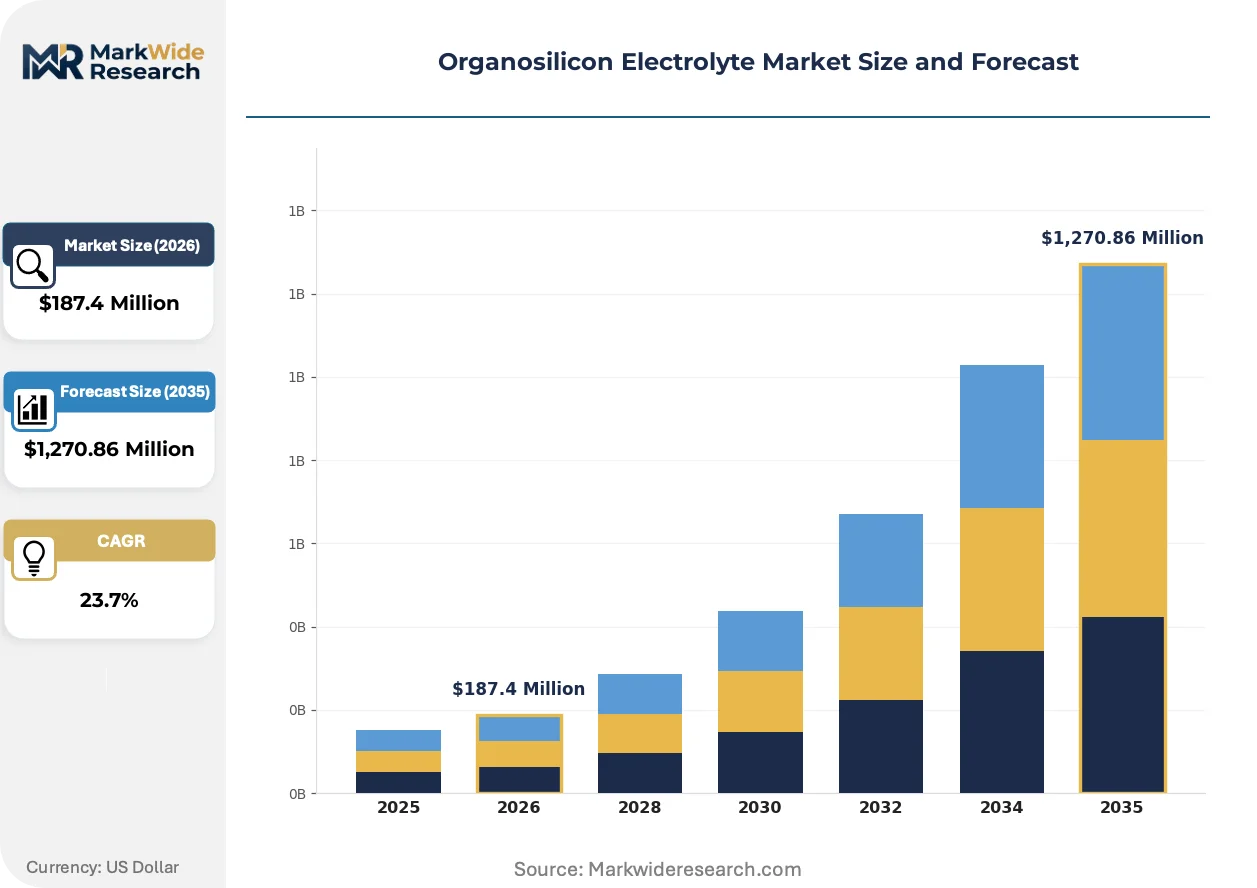
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,270.86 Million |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Electrolyte, Solid Electrolyte, Gel Electrolyte, Hybrid Electrolyte End User: Automotive, Consumer Electronics, Energy Storage, Industrial Applications Formulation: Polymer-Based, Ionic Liquid, Organic Solvent, Composite Electolyte Application: Battery Systems, Supercapacitors, Fuel Cells, Energy Harvesting |
| Companies Covered | Silatronix Inc., Orbia, Shin-Etsu Chemical Co., Ltd., Mitsubishi Chemical Group Corporation, UBE Corporation, 3M Co., Solvay S.A., BASF SE, NEI Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Organosilicon Electrolyte Market Strategic Shifts
Formulation chemistry is pivoting from incremental additive loading toward molecular architecture redesign, with siloxane backbone engineering emerging as the central technical battleground for next-generation electrolyte performance.
Silatrane-functionalized siloxanes are supplanting conventional linear siloxane additives in high-voltage formulations. Electric vehicle cell producers in South Korea and China are accelerating qualification timelines for these cyclic architectures. The transition is compressing competitive differentiation around molecular design capabilities rather than commodity blending scale.
Japan's METI green innovation program is channeling public R&D funding into organosilicon solid-state electrolyte development. Grants prioritize sulfide-siloxane composite systems with ionic conductivity targets exceeding conventional liquid benchmarks. Japanese battery developers are restructuring consortium participation to capture this funding stream.
Cell manufacturers are consolidating electrolyte procurement under long-term offtake agreements with specified performance tiers. Tier-one battery producers in China are displacing spot-market purchasing with formulation partnerships locked to cathode chemistry roadmaps. The shift is most visible in NCM 811 and 9-series cell supply chains where thermal runaway liability concentrates supplier selection authority.
Organosilicon Electrolyte Market Segmentation
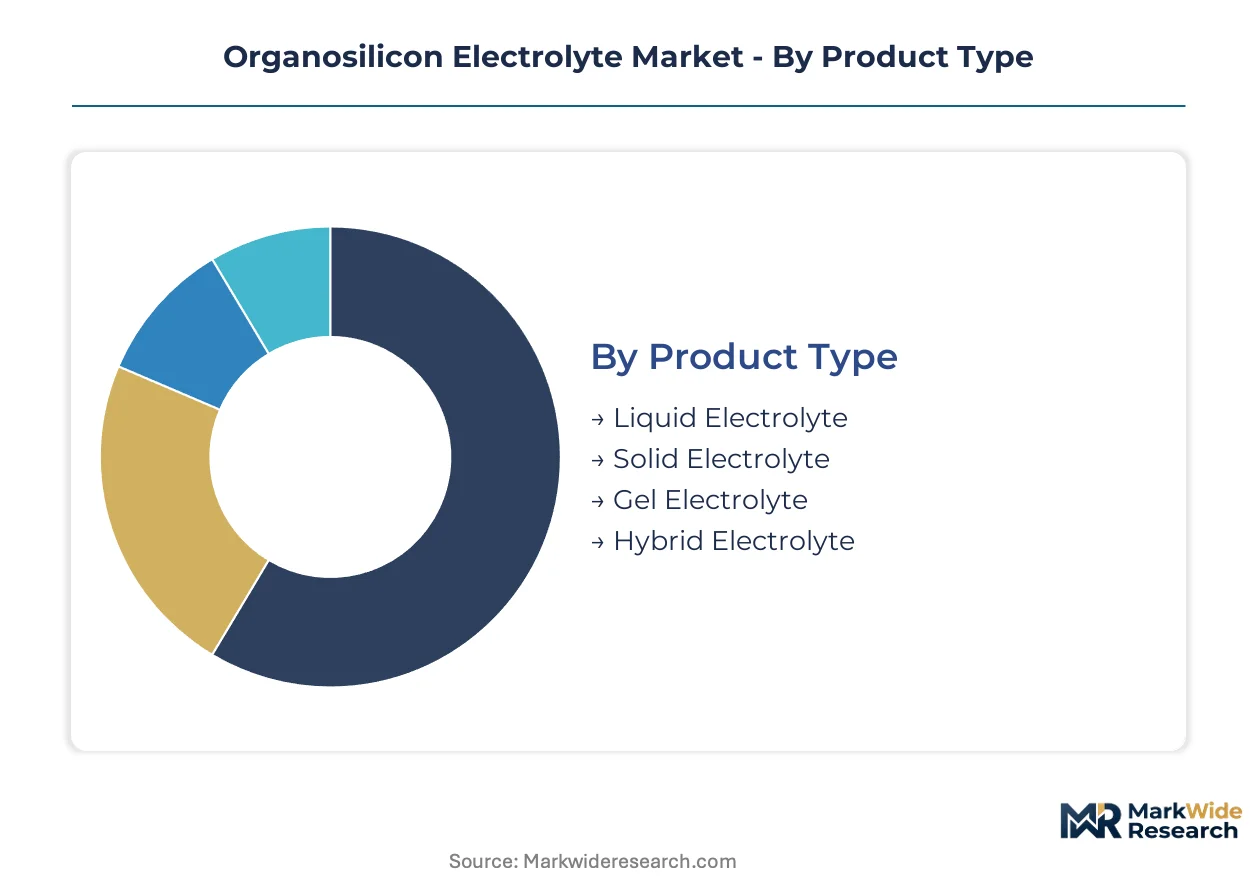
Organosilicon electrolyte procurement patterns diverge sharply across product architectures and end-use specifications. Regulatory mandates from China's SAMR, South Korea's MFDS, and the US EPA are fragmenting formulation requirements by application, forcing suppliers to maintain parallel certification tracks.
Product Type:
China's GB standards impose differential silicon-based additive thresholds across physical states, with liquid formulations facing distinct certification timelines from solid-state alternatives.
- Liquid Electrolyte:Conventional carbonate systems incorporating siloxane or silyl ester functional groups dominate current procurement volumes. Automotive cell manufacturers in South Korea's Ulsan cluster specify these formulations for NCM 811 cathode configurations under MFDS safety protocols.
- Solid Electrolyte:Sulfide-siloxane composite architectures attract METI-funded R&D investment in Japan. Solid-state battery developers prioritize these systems for silicon-anode compatibility, though commercial deployment lags liquid alternatives by several qualification cycles.
- Gel Electrolyte:Semi-solid polymer matrices with organosilicon plasticizers serve niche consumer electronics applications requiring flexible form factors.
- Hybrid Electrolyte:Dual-phase liquid-solid systems bridge performance gaps in intermediate-generation cell designs.
Established volume favors Liquid Electrolyte; emerging adoption favors Solid Electrolyte.
End User:
Cost tier differentiation separates premium automotive specifications from mass-market consumer electronics grades.
- Automotive:Electric vehicle manufacturers command the largest absolute demand, with procurement concentrated around thermal runaway suppression for high-nickel cathode cells. China's SAMR mandates stricter additive thresholds for automotive certification than consumer applications.
- Consumer Electronics:Portable device producers prioritize cycle life extension over thermal stability, driving specification divergence from automotive tiers.
- Energy Storage:Grid-scale battery integrators specify organosilicon additives for long-duration cycling stability under FERC-interfaced safety standards.
- Industrial Applications:Material handling and stationary power systems represent fragmented demand with customized formulation requirements.
Automotive procurement anchors current revenue; Energy Storage applications are climbing the fastest.
Formulation:
Supply concentration in chlorosilane feedstock favors integrated chemical conglomerates in polymer-based and organic solvent categories.
- Polymer-Based:Siloxane backbone architectures dominate molecular engineering investment. Silatrane-functionalized variants supplant linear siloxanes in high-voltage formulations qualified by South Korean cell producers.
- Ionic Liquid:Non-flammable organosilicon-ionic liquid hybrids address transport safety requirements under UN 38.3 testing protocols.
- Organic Solvent:Conventional carbonate co-solvent systems with organosilicon additives retain cost advantages in volume applications.
- Composite Electrolyte:Multi-phase formulations combining ceramic and organosilicon components target solid-state transition architectures.
Polymer-Based formulations command premium positioning; Composite Electrolyte development is gaining share fastest.
Application:
Customer type fragmentation separates tier-one battery producers from emerging energy storage system integrators.
- Battery Systems:Lithium-ion cell manufacturing consumes the dominant share of organosilicon additive supply. Long-term offtake agreements with specified performance tiers are displacing spot-market purchasing among Chinese tier-one producers.
- Supercapacitors:Energy storage system integrators represent a faster-growing but smaller volume outlet, with direct supply relationships bypassing traditional battery chemical distribution tiers.
- Fuel Cells:Proton exchange membrane systems utilize organosilicon electrolytes for humidity management in specialized transport applications.
- Energy Harvesting:Low-power IoT and sensor networks drive micro-scale demand for stable electrolyte formulations.
Battery Systems anchor absolute demand; Supercapacitor channel expansion offers the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in South Korea and China demonstrate low price elasticity as thermal runaway liability concentrates supplier selection authority, while procurement teams in Europe and North America face steeper cost constraints under REACH registration burdens and fluorinated solvent competition.
China
Electric vehicle manufacturers in the Yangtze River Delta and Pearl River Delta are accelerating procurement of organosilicon additives for NCM 811 and 9-series cathode configurations. SAMR enforces GB standards that mandate stricter silicon-based additive thresholds for domestic battery certification than import markets require. Cell production clusters around Shenzhen and Ningbo are displacing spot-market purchasing with long-term formulation partnerships locked to cathode chemistry roadmaps.
South Korea
Battery producers specify organosilicon electrolytes primarily for thermal suppression in high-nickel cells bound for European and North American automotive OEMs. MFDS safety protocols govern additive loading requirements for cells manufactured in the Ulsan-Gwangju corridor. The Busan-Ulsan industrial belt anchors regional demand concentration, with electrolyte formulators establishing dedicated technical service laboratories to support qualification timelines.
Japan
Solid-state battery developers prioritize sulfide-siloxane composite systems for silicon-anode compatibility under METI's green innovation program funding. JIS standards for next-generation cell architectures incorporate organosilicon electrolyte performance benchmarks that exceed current liquid system specifications. The Kanto region around Tokyo hosts the dominant share of public R&D consortium participation targeting ionic conductivity targets.
United States
EPA and NHTSA coordinate chemical safety review with vehicle electrification mandates that indirectly elevate electrolyte performance standards for domestic battery assembly. FERC-interfaced safety standards apply to grid-scale energy storage integrators specifying organosilicon additives for long-duration cycling stability. The Pacific Northwest and Southeast manufacturing corridors attract electrolyte blending capacity investments serving automotive and stationary power applications.
Germany
Automotive cell producers face ECHA compliance timelines for novel organosilicon molecules that extend commercialization cycles relative to Asian competitors. REACH registration burdens favor incumbent chemical conglomerates with existing silicone monomer production over independent electrolyte developers. The North Rhine-Westphalia and Bavaria industrial regions concentrate formulation partnerships between domestic chemical suppliers and European battery gigafactory projects.
Organosilicon Electrolyte Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with molecular architecture specialists commanding premium positioning while integrated chemical conglomerates anchor volume supply through captive feedstock control. The market structure tiers across three participant categories: silicone monomer producers with backward integration into chlorosilane supply, formulation specialists designing siloxane backbones for high-voltage applications, and diversified chemical suppliers blending organosilicon co-solvents with conventional carbonate systems. Dominant competitive moves include long-term offtake agreements tied to cathode chemistry roadmaps and regional capacity expansion to serve qualified battery cell clusters.
Among integrated Japanese chemical conglomerates, Shin-Etsu Chemical Co., Ltd. exemplifies the captive production archetype, while Silatronix Inc. represents the molecular architecture specialist tier focused on cycle life extension. BASF SE occupies a position bridging formulated electrolyte portfolios with conventional carbonate system integration. These three anchors illustrate the competitive divergence between upstream feedstock control, downstream formulation partnership depth, and hybrid portfolio breadth.
| Leading Market Players |
|---|
| Silatronix Inc. |
| Orbia |
| Shin-Etsu Chemical Co., Ltd. |
| Mitsubishi Chemical Group Corporation |
| UBE Corporation |
| 3M Co. |
| Solvay S.A. |
| BASF SE |
| NEI Corporation |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day qualification timelines for silatrane-functionalized siloxanes concentrate pricing power with molecular architecture specialists while compressing margins for commodity carbonate blenders. Chlorosilane feedstock concentration in Japanese and German integrated chemical conglomerates anchors cost positions for organosilicon precursor supply, forcing independent electrolyte developers to absorb margin pressure or surrender formulation partnership slots.
Pricing Analysis
After-sales technical service contracts spanning multi-year cathode chemistry roadmaps capture lifetime value exceeding initial formulation sales. Long-term offtake agreements with tier-one battery producers in China and South Korea dominate the pricing structure, separating premium molecular-design partnerships from standard additive supply contracts. Cost compression in standard-grade siloxane additives intensifies as fluorinated carbonate substitutes gain traction in high-voltage cells. Spot-market purchasers in European energy storage applications exhibit the highest price sensitivity, while automotive cell producers under GB and MFDS mandates demonstrate minimal elasticity.
Supply Chain Analysis
Inventory buffers for chlorosilane monomers rarely exceed thirty days across the Ulsan-Gwangju battery corridor, exposing formulators to upstream disruption. Captive production of silicone feedstock concentrates in Japan, Germany, and China, drawing from petroleum coke and metallurgical-grade silicon inputs. Single-source vulnerability in high-purity chlorosilane supply threatens qualification timelines for novel organosilicon molecules. Distribution runs through direct technical-service relationships with cell manufacturers, bypassing traditional chemical distribution tiers for qualified formulations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organosilicon electrolyte procurement is shifting toward platform-economics dynamics where formulation partnerships lock to cathode chemistry roadmaps, creating interoperability premiums for suppliers with validated siloxane architectures.
For Market Incumbents: Secure long-term chlorosilane supply agreements before capacity constraints tighten in the Kanto and North Rhine-Westphalia industrial belts. Expand technical-service laboratory footprints in Shenzhen and Busan to compress customer qualification cycles. Fluorinated solvent substitution in European high-voltage cells threatens premium positioning; defend through silatrane-functionalized siloxane patent clusters.
For New Entrants and Emerging Players: Formulation partnerships for India's PLI-linked advanced chemistry cell projects represent the most penetrable entry vector, with domestic battery developers seeking electrolyte co-development relationships. Target supercapacitor channel expansion where direct supply relationships bypass entrenched battery chemical distribution tiers. Lead with sulfide-siloxane composite expertise to capture METI-funded solid-state consortium participation.
For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical platform play because organosilicon molecular architectures are becoming the interoperability standard for next-generation cell chemistries. Acquisition targets should display captive silicone monomer production or validated silatrane formulation libraries. Watch for GB standard threshold revisions as the signal for demand inflection in premium additive tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chlorosilane Feedstock | Captive silicone monomer production anchors cost positions against fluorinated solvent competition. |
| Long-term Formulation Partnership Agreements | Multi-year offtake contracts with NCM 811 cell producers lock revenue to cathode roadmaps. |
| Regional Technical-Service Laboratory Expansion | Dedicated facilities in Ulsan and Shenzhen compress qualification timelines for silatrane variants. |
| Silatrane-Functionalized Siloxane Patent Development | Cyclic siloxane architectures command premium positioning under tightening GB additive thresholds. |
| Sulfide-Siloxane Composite R&D Consortium Participation | METI green innovation funding accelerates solid-state electrolyte commercialization pathways. |
Study Parameters
A standing panel of electrolyte formulation chemists, cell manufacturer procurement directors, and chlorosilane plant managers provided ongoing calibration across the study period. Primary interviews with technical R&D directors at South Korean battery producers, SAMR regulatory affairs specialists, and distribution channel partners in the Busan-Ulsan corridor combined with secondary validation from customs/trade data, SEC 10-K filings, and METI green innovation program disclosures. Bottom-up electrolyte volume estimates triangulated against top-down cathode chemistry deployment projections.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation dimensions spanning physical state, end-use application, formulation chemistry, and regional regulatory cluster. CAGRs derived from electrolyte loading assumptions per cell chemistry generation, silicon-anode penetration curves, and GB standard compliance timelines. Forecast inputs incorporated SAMR certification phase-in schedules and METI R&D funding disbursement patterns.
Underlying assumptions cover sustained high-nickel cathode adoption, stable chlorosilane feedstock availability, and gradual solid-state battery transition, with deviation risk concentrated in fluorinated solvent substitution rates and REACH registration timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Dimethylolpropionic Acid (DMPA) Market
Specialty Chemicals
Colloidal Gold Suspension Market
Specialty Chemicals
Chromium Polynicotinate Market
Specialty Chemicals
Solar Cell Front Side Silver Paste Market
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Global Acrylic Processing Aid Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Polycarboxylate Ethers (Pces) Market
Specialty Chemicals
Structure Directing Agents Market
Specialty Chemicals
Diindolylmethane Market
Specialty Chemicals
Eitelite Market
Specialty Chemicals
AEA Salicylic Acid Market
Specialty Chemicals
Global Silanes Market
Specialty Chemicals
Security Ink Market
Specialty Chemicals
Metominostrobin Market
Specialty Chemicals
UV Light Stabilizers Market