
 Acrylic Styrene Acrylonitrile Resin Market | 2026-2036
Acrylic Styrene Acrylonitrile Resin Market Size, Share, and Industry Trends Forecast 2026-2036
Acrylic Styrene Acrylonitrile Resin Market Outlook
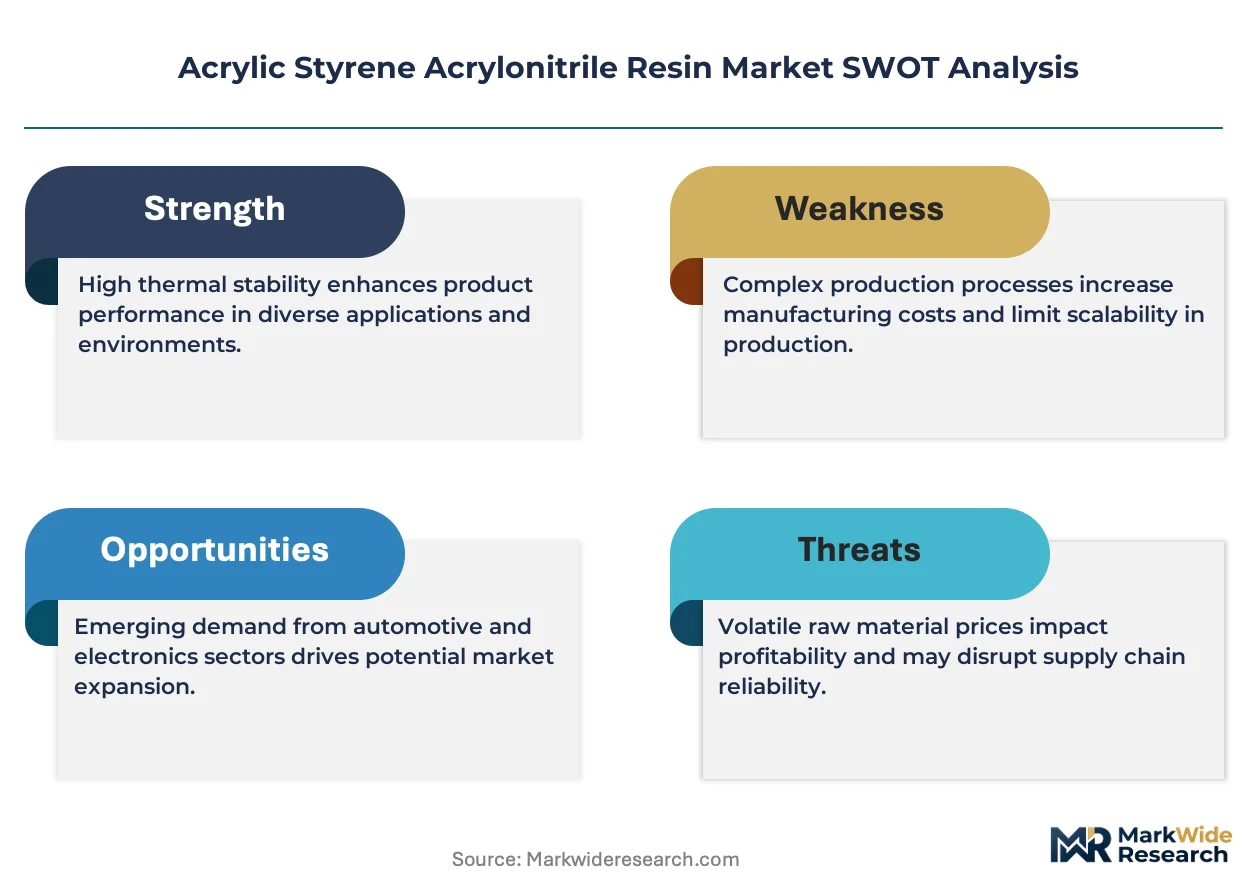
Specialty chemical distribution networks serving tier-two compounders is reconfiguring as resin producers bypass traditional distributors to secure direct relationships with automotive OEMs. LG Chem leverages its integrated petrochemical complex in Yeosu to control feedstock costs for acrylonitrile and styrene monomers. INEOS Styrolution anchors European supply through its Ludwigshafen operations, sustaining just-in-time delivery to German automotive suppliers.
Acrylic styrene acrylonitrile resin is a terpolymer synthesized through emulsion or mass polymerization, typically containing 15-35% acrylonitrile content, engineered for exceptional weather resistance and surface gloss retention in outdoor applications. High heat resistant grades command premium positioning as under-the-hood automotive applications expand thermal performance requirements, while general purpose formulations occupy commoditized building and construction segments where cost competition intensifies. Electronics end use applications for ASA films and sheets are gaining structural momentum as consumer device manufacturers seek alternatives to painted surfaces.
REACH registration requirements in Europe and EPA emissions standards in the United States constrain formulation chemistries, compelling producers to validate alternative stabilizer packages and low-VOC processing aids. China's SAMR enforces GB standards for plastic weatherability in automotive applications, creating compliance thresholds that favor producers with certified testing infrastructure. Stakeholders must monitor evolving automotive lightweighting mandates and polymer recycling directives that will determine which ASA formulations retain market access.
Market Dynamics
Automotive OEMs are consolidating resin procurement around certified suppliers capable of meeting GB weatherability standards, compressing the supplier base and elevating technical qualification barriers for compounders serving exterior component applications.
Growth Catalysts
- Automotive lightweighting mandates:Under-the-hood thermal management applications are expanding procurement of high-heat ASA grades as vehicle electrification intensifies material performance requirements.
- REACH registration pathways:ECHA compliance frameworks for polymer stabilizers are creating certified supply advantages for European producers with validated low-VOC formulation packages.
- East Asian manufacturing concentration:Shanghai and Busan industrial clusters are anchoring demand density for mirror housings and radiator grilles, driving localized compounding capacity expansion.
Market Restraints
- Acrylonitrile feedstock volatility:Propylene-ammonia cost pass-through mechanics constrain margin predictability for non-integrated compounders lacking captive monomer supply.
- Polypropylene substitution in construction:Commoditized building applications face displacement from lower-cost olefins where surface gloss retention is not specification-critical.
- SAMR certification timelines:China's GB standard testing protocols extend qualification cycles for new automotive grade introductions, delaying revenue recognition.
Strategic Opportunities
- Consumer electronics surface applications:Unpainted ASA films are penetrating laptop and tablet housings as device manufacturers abandon painted metal finishes for weight and process efficiency.
- EU Green Deal circularity requirements:Ecodesign directives for automotive recyclability are creating specification pull for mechanically recyclable ASA formulations with validated closed-loop pathways.
- Direct OEM engagement models:Resin producers bypassing distributor networks to secure specification-in positions at tier-one automotive suppliers capture margin otherwise captured by intermediaries.
Industry Challenges
- Stabilizer chemistry reformulation:EPA emissions constraints on traditional UV absorber packages are forcing validation of alternative hindered amine light stabilizers with unproven long-term weathering databases.
- Polymerization scale-up complexity:Mass polymerization technology transfers from pilot to commercial scale require specialized reactor engineering expertise concentrated at legacy petrochemical complexes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Acrylic Styrene Acrylonitrile Resin Market |
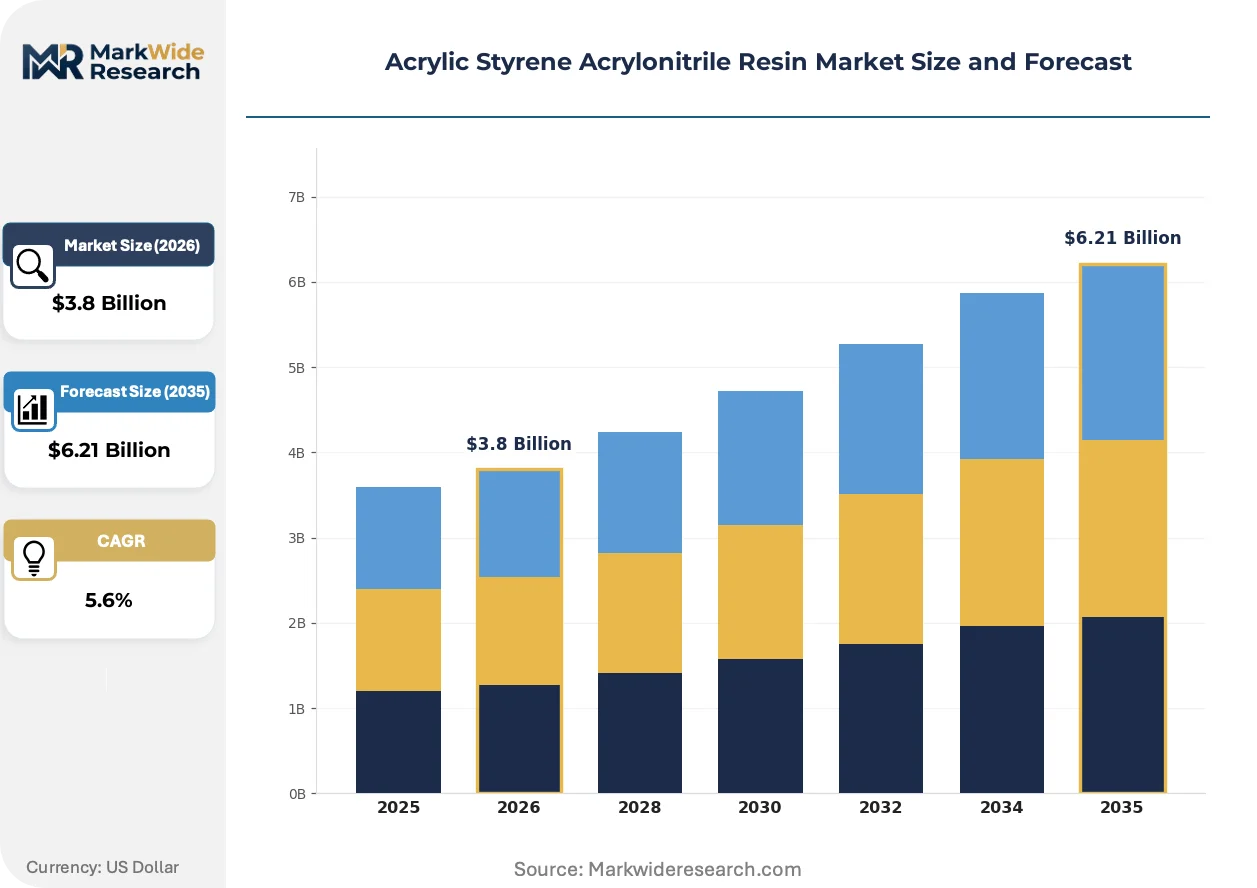
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.21 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
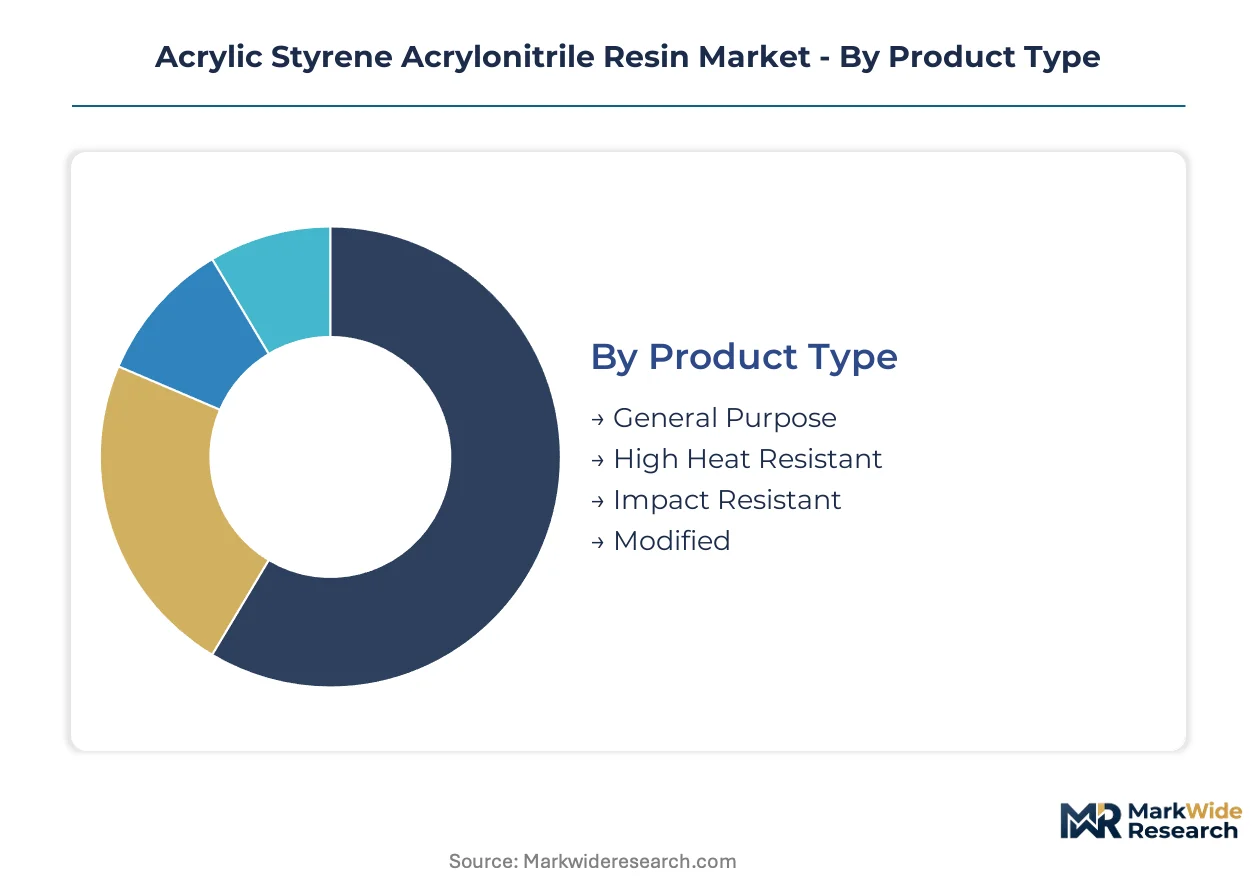
| Segmentation | Product Type: General Purpose, High Heat Resistant, Impact Resistant, Modified End Use Industry: Automotive, Electronics, Consumer Goods, Medical Form: Granules, Powders, Films, Sheets Application: Pipes, Molded Parts, Coatings, Adhesives |
| Companies Covered | LG Chem, Chi Mei Corporation, INEOS Styrolution, SABIC, BASF SE, Toray Industries, Trinseo, Kumho Petrochemical, Asahi Kasei, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Acrylic Styrene Acrylonitrile Resin Market Strategic Shifts
Formulation science and supply chain configuration are converging around weatherability certification and direct procurement models, displacing traditional distributor-mediated relationships and elevating technical service capabilities as competitive differentiators.
ASA-PC alloys is hybridizing across automotive exterior applications, combining acrylonitrile-styrene-acrylate weather resistance with polycarbonate impact performance. Tier-one suppliers in Germany and Japan are qualifying these materials for A-surface body panels previously reserved for painted steel or standalone PC blends. The technology is compressing the traditional segmentation between structural and decorative polymers.
REACH Annex XVII restrictions on persistent organic pollutants are tightening acceptable stabilizer chemistries for outdoor-grade polymers. ECHA evaluation of halogenated flame retardants is compelling reformulation of building construction grades around phosphorus-based alternatives. European compounders with in-house regulatory affairs capabilities are securing faster market access than competitors reliant on external consultants.
Specification-driven procurement is consolidating around automotive OEM technical centers with centralized material approval authority. Traditional regional purchasing autonomy is contracting as Volkswagen, BMW, and Hyundai Motor Group implement global resin qualification databases. This concentration is most visible in German and South Korean supply chains where mirror housing specifications now originate from headquarters engineering functions rather than local plant buyers.
Acrylic Styrene Acrylonitrile Resin Market Segmentation
ASA resin grades diverge sharply in procurement velocity, with automotive specifications cycling every 3-4 years versus construction applications holding formulations for 7-10 years. Segmentation discipline separates high-margin specification-driven tiers from commodity volumes competing on feedstock pass-through efficiency.
Product Type:
Cycle times compress from 18 months for modified specialty grades to 6-8 years for established general purpose formulations, creating distinct inventory and technical service models across the portfolio.
- General Purpose:Standard 15-25% acrylonitrile content formulations serve building fascia and construction profiles where weatherability requirements are moderate. Procurement concentrates in Chinese provincial construction bureaus purchasing through annual tender cycles, with margin pressure from polypropylene substitution in non-critical surface applications.
- High Heat Resistant:Engineered with elevated acrylonitrile content and thermal stabilizer packages for under-the-hood automotive applications. Demand clusters around Shanghai and Stuttgart automotive technical centers as electrification intensifies thermal management material specifications, with qualification cycles extending 24-36 months.
- Impact Resistant:Rubber-modified terpolymer variants balancing weatherability with ductility for exterior mirror housings and radiator grilles. Specifications originate from Hyundai Motor Group and Volkswagen centralized material databases rather than regional purchasing.
- Modified:Custom-compounded grades incorporating flame retardants, color concentrates, or fiber reinforcement for electronics and medical device housings. Batch sizes run 10-50 tons with 6-12 week lead times, contrasting with general purpose truckload economics.
General Purpose dominates installed base tonnage. High Heat Resistant is where expansion concentrates.
End Use Industry:
Margin structures stratify across customer sophistication, with automotive OEMs paying 15-25% premiums for certified supply chains versus medical device producers prioritizing batch traceability over unit economics.
- Automotive:Exterior component manufacturers specify ASA for mirror housings, radiator grilles, and A-surface body panels. China's GB standards for weatherability are tightening performance benchmarks, compressing the supplier base around certified compounders with in-house testing infrastructure.
- Electronics:Consumer device manufacturers are abandoning painted metal finishes for unpainted ASA films in laptop and tablet housings. Procurement is shifting toward direct resin producer relationships to secure specification-in positions at tier-one contract manufacturers.
- Consumer Goods:Lawn furniture, recreational vehicle components, and outdoor signage applications where surface gloss retention competes against lower-cost ABS and painted alternatives. Demand cycles with North American and European residential construction seasonality.
- Medical:Device housings and equipment enclosures requiring USP Class VI biocompatibility and gamma sterilization stability. Batch sizes are small but specification stickiness creates 10-15 year product lifecycles with minimal price elasticity.
Automotive commands revenue concentration. Electronics is climbing the fastest as unpainted surface adoption accelerates.
Form:
Processing economics favor granules for high-volume injection molding while films and sheets capture value-added differentiation in surface applications.
- Granules:Pelletized resin for injection molding and extrusion compounding. Automotive exterior parts and construction profiles represent the demand anchor, with just-in-time delivery requirements from German and South Korean tier-one suppliers.
- Powders:Fine particle grades for rotational molding and powder coating applications. Niche volumes serve tank and container manufacturers with batch processing economics distinct from continuous extrusion.
- Films:Calendered and extruded sheet for thermoforming and lamination. Electronics surface applications are gaining structural momentum as device manufacturers seek alternatives to painted finishes for weight reduction.
- Sheets:Thick-gauge extruded product for signage, architectural glazing, and thermoformed components. Weatherability certification creates regional supply advantages for European and East Asian producers with validated long-term testing databases.
Granules dominate installed base. Films is where expansion concentrates.
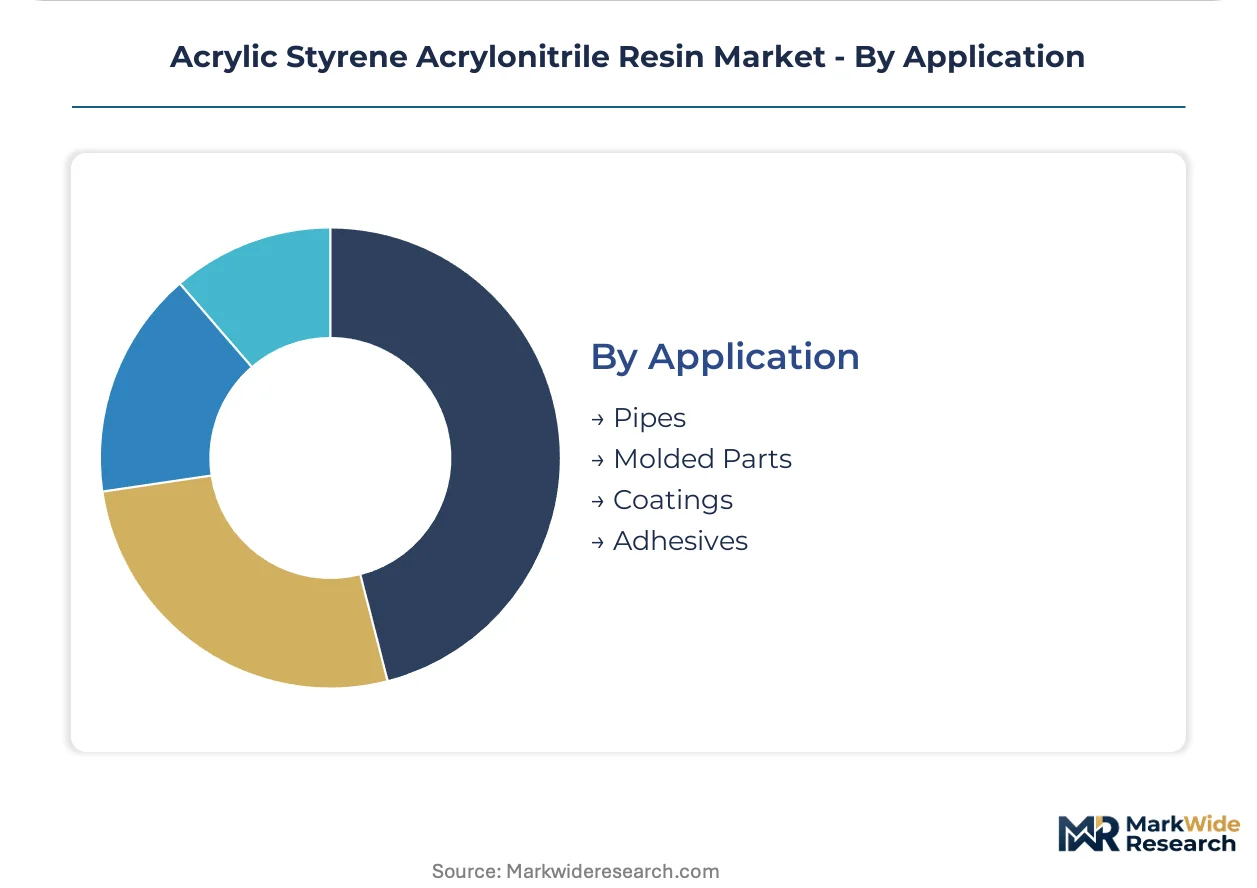
Application:
Specification authority varies sharply, with automotive OEMs controlling molded parts approvals versus construction contractors delegating pipe material selection to regional distributors.
- Pipes:Corrugated drainage and conduit applications where UV resistance extends service life versus PVC alternatives. Chinese infrastructure spending and European building renovation cycles drive regional demand variation.
- Molded Parts:Injection-molded automotive exterior components, appliance housings, and power tool enclosures. Centralized OEM technical qualification is displacing regional purchasing autonomy in German and South Korean supply chains.
- Coatings:Powder coating formulations and protective layers for metal substrates. Smaller volume segment with formulation complexity concentrated at specialty compounders serving industrial equipment manufacturers.
- Adhesives:Modified ASA dispersions and hot-melt formulations for automotive assembly and construction bonding. Niche application with technology overlap to acrylic adhesive specialists.
Molded Parts dominates installed base. Coatings is gaining share fastest as functional surface applications expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangshan deep-water port infrastructure anchors China's dominance in acrylic styrene acrylonitrile resin throughput, handling monomer feedstock imports that supply compounding operations throughout the Yangtze River Delta manufacturing corridor.
China
Automotive exterior component demand concentrates around Shanghai's automotive technical centers as BYD and SAIC Motor expand electric vehicle production. SAMR enforces GB standards for plastic weatherability that compress supplier qualification timelines. Ningbo and Taizhou industrial clusters host specialized compounders serving mirror housing and radiator grille specifications for domestic OEMs.
Germany
Volkswagen and BMW centralized material databases now govern resin specifications previously managed at regional plant level. ECHA REACH Annex XVII restrictions on halogenated stabilizers compel reformulation of outdoor-grade polymers around phosphorus-based alternatives. Ludwigshafen chemical complex operations sustain just-in-time delivery to tier-one automotive suppliers across Baden-Württemberg and Bavaria.
United States
EPA emissions standards constrain traditional UV absorber packages in building construction applications, forcing validation of alternative hindered amine light stabilizers. Detroit automotive technical centers specify high-heat ASA grades for under-the-hood thermal management in electrified powertrains. Gulf Coast petrochemical infrastructure provides captive acrylonitrile supply for integrated compounders serving North American OEMs.
South Korea
Hyundai Motor Group headquarters engineering functions now originate mirror housing specifications rather than regional purchasing departments. MFDS maintains pharmaceutical-grade polymer standards that create specification stickiness for medical device housing applications. Busan-Ulsan industrial corridor hosts compounding capacity expansion serving export-oriented automotive component manufacturers.
Japan
METI industrial policy supports development of mechanically recyclable ASA formulations aligned with circular economy directives. Nagoya automotive supplier clusters qualify ASA-PC alloys for A-surface body panels previously reserved for painted steel. Osaka-based electronics manufacturers specify unpainted ASA films for laptop and tablet housing applications.
Acrylic Styrene Acrylonitrile Resin Market Competitive Environment
On the supply side, the industry is consolidating around certified compounders capable of meeting automotive OEM technical qualification requirements, compressing the vendor base serving exterior component applications. Three strategic archetypes dominate: integrated petrochemical producers with captive monomer supply, specialized compounders with in-house regulatory affairs capabilities, and regional distributors being bypassed as resin producers pursue direct OEM relationships. Capacity expansion and strategic partnerships represent the dominant competitive moves, with producers securing specification-in positions at tier-one automotive suppliers.
Within the integrated producer tier, LG Chem anchors East Asian supply through its Yeosu petrochemical complex operations, while INEOS Styrolution exemplifies European producers sustaining just-in-time delivery frameworks. Among diversified chemical conglomerates, BASF SE occupies a position spanning multiple polymer categories with regulatory compliance infrastructure across major automotive manufacturing regions.
| Leading Market Players |
|---|
| LG Chem |
| Chi Mei Corporation |
| INEOS Styrolution |
| SABIC |
| BASF SE |
| Toray Industries |
| Trinseo |
| Kumho Petrochemical |
| Asahi Kasei |
| Others |
Value Chain & Pricing Dynamics
Yeosu petrochemical complex concentration in South Korea funnels acrylonitrile and styrene monomer cost advantages toward integrated producers, compressing margin pools for non-integrated compounders forced to absorb propylene-ammonia volatility through spot market exposure.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement frameworks. High-heat automotive grades certified to GB weatherability standards command 15-25% premiums over general-purpose construction formulations. Price differentiation rests on certification grade and volume scale, with automotive OEMs least sensitive due to specification stickiness while provincial construction bureaus in China exhibit acute price elasticity. Cost compression in commoditized building segments is intensifying because polypropylene substitution erodes specification-critical applications.
Supply Chain Analysis
Acrylonitrile feedstock availability centers on South Korea, China, and Germany as anchor production nodes. Raw material dependencies span propylene-ammonia synthesis, styrene monomer purification, and specialized UV stabilizer packages. Single-source vulnerability concentrates around hindered amine light stabilizer suppliers facing EPA emissions constraints. Distribution runs through direct OEM engagement models displacing traditional specialty chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive OEM technical center consolidation around centralized material databases has shifted procurement leverage toward buyers, fragmenting regional purchasing autonomy into headquarters-controlled qualification protocols.
For Market Incumbents: Entrench specification-in positions at tier-one automotive suppliers by securing GB weatherability certification infrastructure and anchoring just-in-time delivery frameworks near Shanghai and Stuttgart technical centers. Threat of polypropylene substitution in construction applications demands backward integration into captive monomer supply or exit from commoditized fascia segments. For New Entrants and Emerging Players: Establish a beachhead in consumer electronics surface applications where unpainted ASA films displace painted metal finishes in laptop and tablet housings. Medical device housing specifications offer white-space penetration with 10-15 year product lifecycles and minimal price elasticity, accessed through USP Class VI biocompatibility investment and gamma sterilization validation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty compounders lacking in-house regulatory affairs capabilities required for ECHA REACH Annex XVII compliance. Long-term viability hinges on circular economy positioning for mechanically recyclable formulations aligned with EU Green Deal ecodesign directives. Watch for SAMR certification timeline acceleration as inflection indicator for Chinese automotive grade market access.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Monomer Supply | Yeosu and Ludwigshafen complexes anchor cost control for integrated producers serving automotive OEMs. |
| GB Weatherability Certification Investment | SAMR-compliant testing infrastructure compresses supplier bases around certified compounders in Ningbo clusters. |
| Direct OEM Engagement Model | Resin producers bypass distributors to capture margin at Volkswagen and Hyundai Motor Group technical centers. |
| ASA-PC Alloy Qualification | Tier-one suppliers in Germany and Japan validate hybrid materials for A-surface body panel applications. |
| Phosphorus-Based Stabilizer Reformulation | ECHA restrictions on halogenated flame retardants compel European compounders to secure faster market access. |
Study Parameters
A standing panel of automotive procurement directors, construction materials specifiers, electronics device engineers, and regulatory affairs managers provided ongoing calibration across the analysis window. Primary interviews with tier-one supplier technical centers and downstream OEM compounders combined with secondary validation from customs trade data, SEC 10-K filings, ACC industry reports, and SAMR GB standard documentation. Bottom-up segment sizing and top-down demand triangulation anchored volume estimates.
Scenario-bracketing framed analytical approaches across the modeling period, with CAGRs derived from regression analysis against automotive production forecasts and electrification penetration curves. Segmentation dimensions modeled include product grade tier, end-use industry concentration, form factor, and regional regulatory cluster. Forecast inputs incorporated acrylonitrile feedstock cost pass-through mechanics and SAMR certification timeline assumptions.
Sensitivities concentrate around propylene-ammonia price volatility, ECHA stabilizer chemistry restrictions, and SAMR weatherability testing protocol changes. Quarterly review of automotive OEM specification database updates and REACH Annex XVII amendment proposals is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Styrene Acrylonitrile (SAN) Market
Polymers & Resins
Asia-Pacific Thermoplastics Market
Polymers & Resins
Polyolefin Foam Market
Polymers & Resins
Global Alkyd Resin Market
Polymers & Resins
Poly Propylene Glycol Market
Polymers & Resins
Automotive Thermoplastic Polymer Composites Market
Polymers & Resins
Cast Polymers Market
Polymers & Resins
Global Polybutene Market
Polymers & Resins
Polymer Colloids Market
Polymers & Resins
North America Super Absorbent Polymers (SAP) Market
Polymers & Resins
Waterborne Polyurethane Dispersions for Automotive Synthetic Leather Market
Polymers & Resins
Polypropylene Powder Market
Polymers & Resins
Seed Polymers Market
Polymers & Resins
Methyl Silicone Resins Market
Polymers & Resins
Fluorinated Ethylene Propylene (FEP) Market
Polymers & Resins
Acrylic Resins Market