
 North America Linear Low-Density Polyethylene Market | 2026-2036
North America Linear Low-Density Polyethylene Market Size, Share, and Industry Trends Forecast 2026-2036
North America Linear Low-Density Polyethylene Market Intelligence
ASTM D4976 resin classification is collapsing the supplier field into fewer qualified producers capable of meeting lot-to-lot consistency requirements. Dow leverages its integrated ethane-cracking position across the Texas-Louisiana corridor to sustain cost-advantaged LLDPE output. Exxon Mobil Corporation anchors its market presence through metallocene catalyst technology leadership, while LyondellBasell Industries Holdings B.V. competes via differentiated octene-based copolymer grades targeting premium film applications.
Linear low-density polyethylene is a thermoplastic polymer produced through copolymerization of ethylene with alpha-olefins such as butene, hexene, or octene, yielding a density range of 0.915–0.925 g/cm³ and a molecular structure with short-chain branching that imparts superior puncture resistance and tensile strength compared to low-density polyethylene. Its primary commercial purpose centers on thin-gauge film production for packaging, where dart impact strength and sealability reduce material usage without sacrificing performance. Film applications dominate volume consumption across the region, while flexible packaging segments capture disproportionate margin pools due to food-contact certification requirements and just-in-time supply contracts with major consumer brands. Injection molding grades occupy a mature growth trajectory, serving durable goods and industrial pails where stiffness and environmental stress crack resistance command technical premiums over commodity alternatives.
The EPA oversees emissions compliance at Gulf Coast production facilities, while OSHA mandates process safety management standards that shape capital allocation for plant expansions. The Department of Commerce tariff frameworks on imported resin further condition competitive dynamics for domestic producers versus offshore supply. Stakeholders must monitor feedstock cost spreads between ethane and naphtha cracking economics, as these differentials determine regional export competitiveness and capacity utilization decisions across the North American manufacturing base.
Market Dynamics
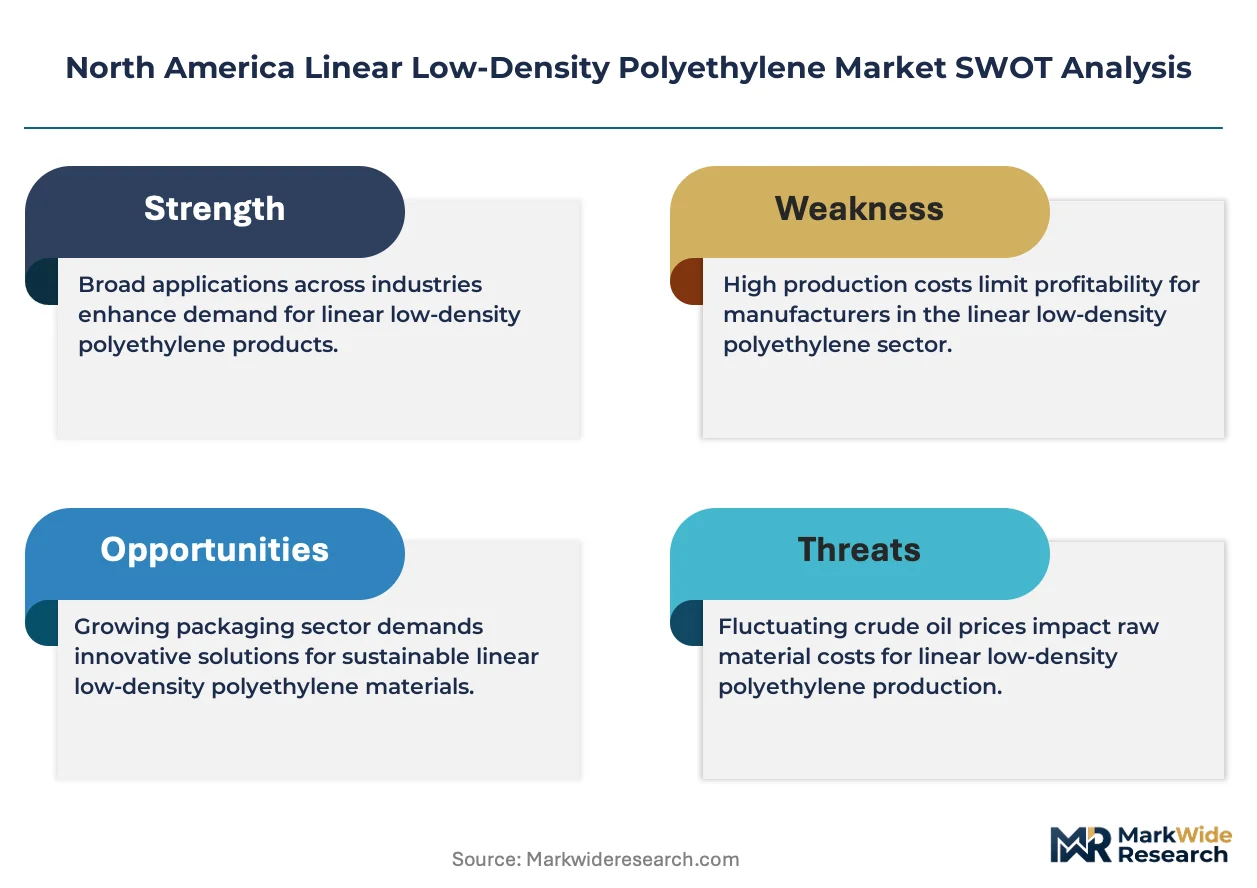
EPA recycled content mandates are compressing the qualified supplier base as flexible packaging converters demand lot-to-lot consistency certifications that only integrated Gulf Coast producers can reliably deliver.
Growth Catalysts
- Butene Copolymer Grades:Puncture-resistant film specifications for fresh produce packaging are pulling hexene and octene copolymer demand across US Midwest food processing corridors.
- US Gulf Coast Ethane Access:Abundant shale-derived feedstock sustains cost-advantaged cracking economics that underpin regional export competitiveness.
- OSHA Process Safety Standards:Stringent capital allocation requirements for plant expansions favor incumbent producers with established compliance infrastructure.
Market Restraints
- Ethane-Naphtha Spread Volatility:Feedstock cost differentials between US shale gas and European/Asian naphtha cracking create margin instability for export-dependent volumes.
- Metallocene Catalyst Concentration:Proprietary single-site catalyst technology remains concentrated among three integrated majors, limiting new entrant participation.
- Mechanical Recycling Contamination:Post-consumer film streams carry adhesive and ink residues that degrade mechanical properties in closed-loop applications.
Strategic Opportunities
- Canadian Prairie Agriculture:Underpenetrated silage and grain bagging applications in Alberta and Saskatchewan offer white-space expansion for UV-stabilized film grades.
- Chemical Recycling Integration:Pyrolysis partnerships with waste management operators enable food-contact certified circular resins bypassing mechanical degradation limits.
- Department of Commerce Tariff Shelters:Anti-dumping frameworks on Southeast Asian resin imports protect domestic margin pools for qualified suppliers.
Industry Challenges
- ASTM D4976 Certification Timelines:Lot-to-lot consistency validation for food-contact film specifications extends qualification cycles by 12-18 months.
- Control Systems Integration:Legacy distributed control systems at Texas-Louisiana corridor plants require capital-intensive upgrades to meet real-time emissions monitoring mandates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Linear Low-Density Polyethylene Market |
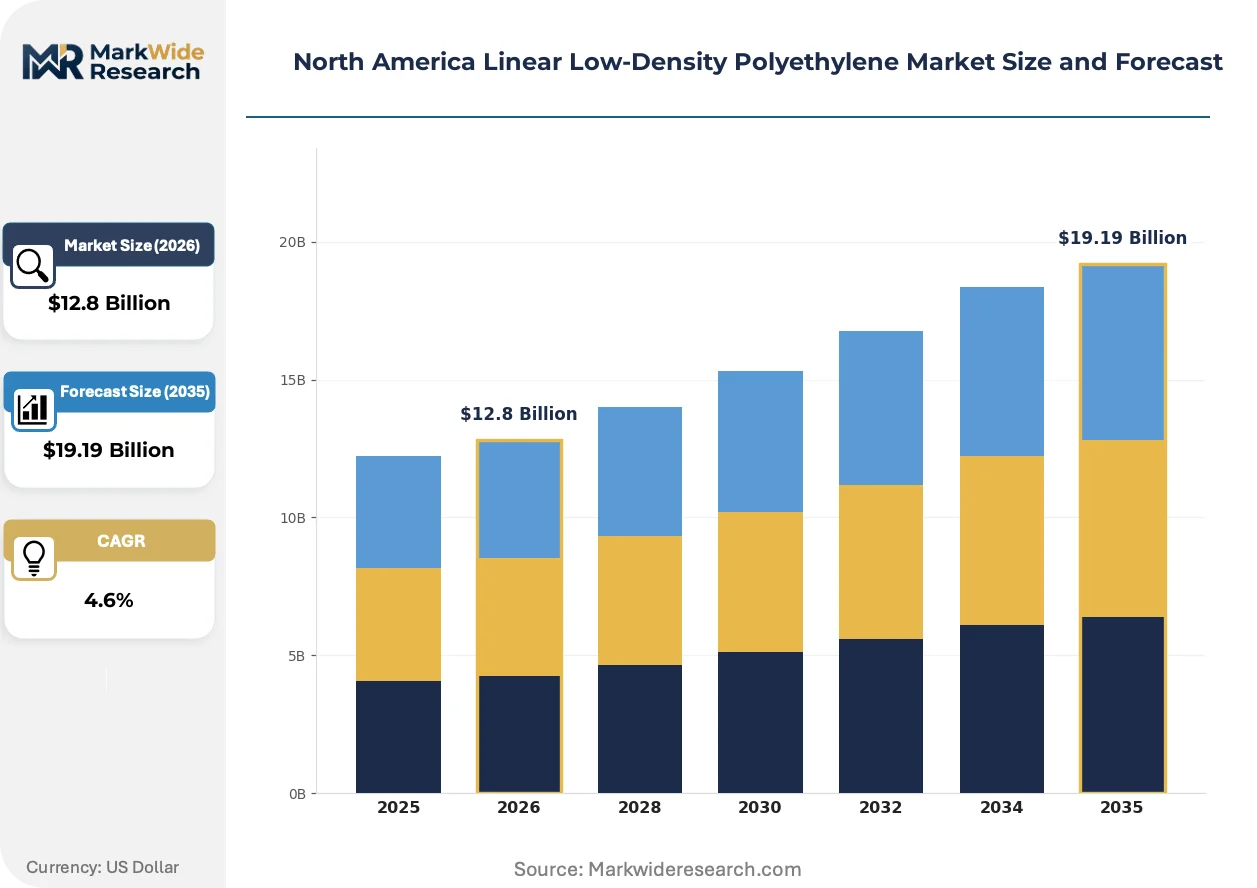
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $19.19 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Film, Injection Molding, Coatings, Sheets End User: Packaging, Automotive, Consumer Goods, Construction Technology: Extrusion, Blown Film, Compression Molding, Thermoforming Application: Rigid Packaging, Flexible Packaging, Agriculture, Bins |
| Companies Covered | Westlake Corporation, Formosa Plastics Corporation, Exxon Mobil Corporation, Arkema, INEOS MOLDS PVT. LTD, Dow, Chevron Phillips Chemical Company LLC, Borealis AG, LyondellBasell Industries Holdings B.V., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Linear Low-Density Polyethylene Market Strategic Shifts & Innovations
Metallocene catalyst systems and post-consumer recycled content integration are bifurcating the supplier landscape into technology leaders and commodity followers across North American flexible packaging.
Single-site metallocene catalyst technology is supplanting conventional Ziegler-Natta systems in premium film applications where dart impact strength and optical clarity specifications command technical premiums. Major brand owners in fresh produce and frozen food segments are mandating metallocene-grade seal layers for downgauging initiatives that reduce material usage without performance sacrifice. This transition is compressing margins for commodity butene copolymer producers unable to fund catalyst research programs.
The EPA's evolving recycled content mandates for food-contact applications are forcing resin qualification protocol revisions that extend supplier onboarding timelines. Domestic producers with integrated chemical recycling pilot plants are securing preferred supplier status with converters facing brand owner sustainability commitments. Gulf Coast facilities with mass balance certification infrastructure are capturing disproportionate share of premium film contracts.
Converter procurement is consolidating toward direct mill relationships with integrated producers, displacing traditional resin distribution intermediaries in high-volume film segments. Major flexible packaging groups are negotiating three-to-five-year offtake agreements with ethane-cracking operators to lock in feedstock cost visibility. This concentration is most visible in the US Southeast, where export terminal proximity enables just-in-time inventory management for multinational brand owners.
North America Linear Low-Density Polyethylene Market Segmentation
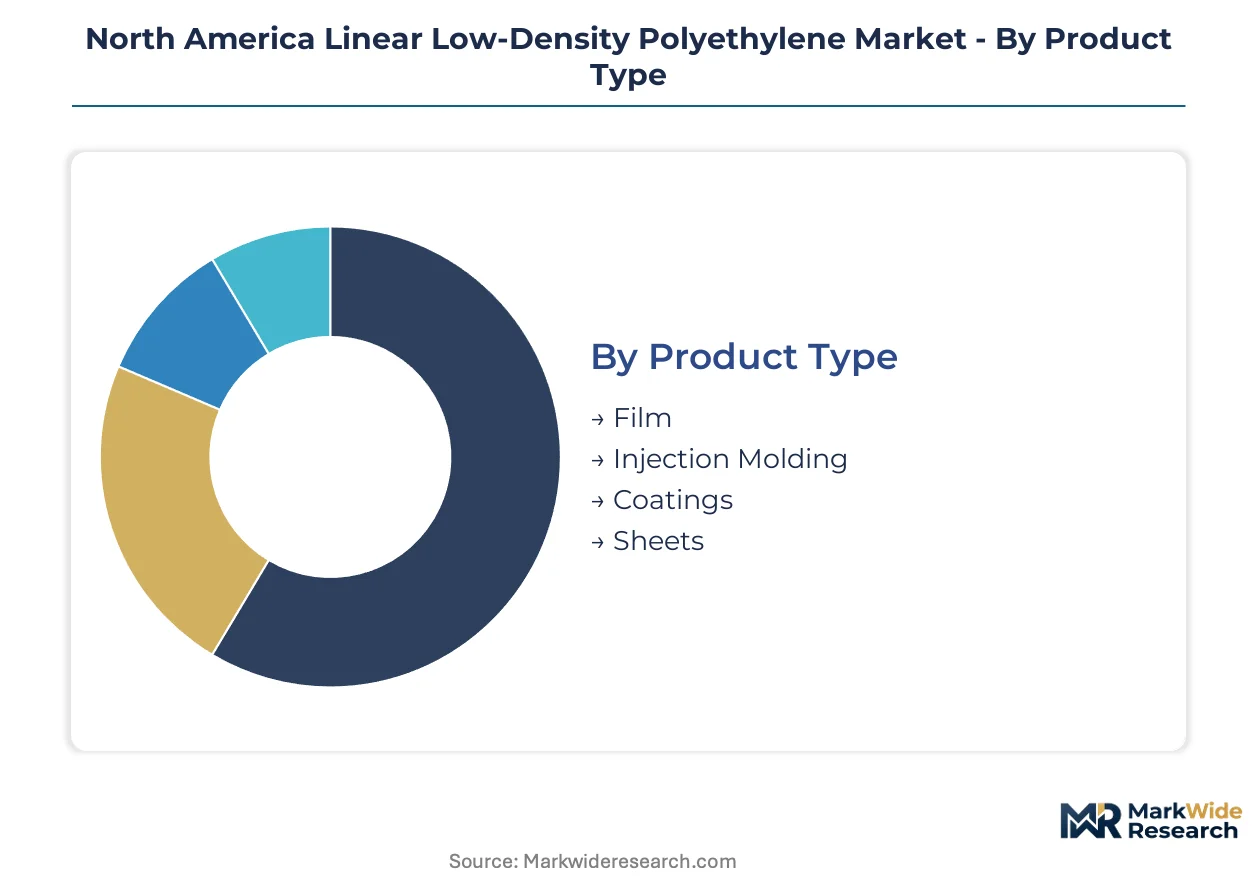
Segmentation in the North American LLDPE market reveals how resin specifications, processing technologies, and end-use certifications create distinct procurement channels. Each dimension shapes converter qualification requirements and supplier margin structures differently.
Product Type:
Film grades flow through flexible packaging distributors with food-contact certification infrastructure, while molding and sheet grades move via technical resin specialists serving industrial compounders.
- Film:Thin-gauge formulations dominate volume consumption, with metallocene-catalyzed grades commanding technical premiums for downgauged fresh produce applications. US Gulf Coast integrated producers capture disproportionate share through direct mill relationships with major converter groups.
- Injection Molding:Higher-melt-index grades serve durable goods and industrial pails where stiffness and environmental stress crack resistance differentiate performance. Midwest automotive and appliance molding corridors concentrate demand for lot-to-lot consistency certifications.
- Coatings:Specialty extrusion-coating grades target paper and foil lamination for liquid packaging.
- Sheets:Thermoforming feedstock for industrial totes and recreational vehicle components.
By volume, Film leads. By growth pace, Injection Molding is gaining share fastest as automotive lightweighting specifications expand.
End User:
Cost tier stratification separates commodity film converters from premium medical and food-contact certified applications requiring extended supplier validation cycles.
- Packaging:Flexible food-contact films represent the largest value pool, with EPA recycled content mandates reshaping resin qualification protocols. Major brand owners in frozen food and snack segments mandate mass-balance-certified circular content.
- Automotive:Underhood components and interior trim leverage LLDPE toughness and chemical resistance for weight reduction versus conventional materials. Detroit Three supplier qualification programs favor domestic producers with IATF certification infrastructure.
- Consumer Goods:Housewares and personal care containers drive steady demand for clarified copolymer grades.
- Construction:Geomembranes and vapor barriers utilize UV-stabilized sheet grades for infrastructure applications.
Packaging captures the widest margin spreads. Automotive shows the steepest expansion trajectory as electrification redesigns material specifications.
Technology:
Processing method determines equipment capital intensity and converter scale economics, with blown film infrastructure concentrating among large integrated packaging groups.
- Extrusion:Cast film and sheet production lines serve high-volume commodity applications with scale-driven unit economics. Texas-Louisiana corridor producers optimize for continuous extrusion throughput with ethane-advantaged feedstock.
- Blown Film:Bubble process technology dominates premium flexible packaging where biaxial orientation and seal strength specifications command technical premiums. Multilayer coextrusion capabilities favor converters with direct mill partnerships for metallocene seal-layer supply.
- Compression Molding:Rotational and blow molding of industrial containers and intermediate bulk containers.
- Thermoforming:Sheet-fed forming of rigid packaging and durable goods components.
Blown Film commands the highest technical barriers. Extrusion maintains the broadest geographic footprint across regional converter bases.
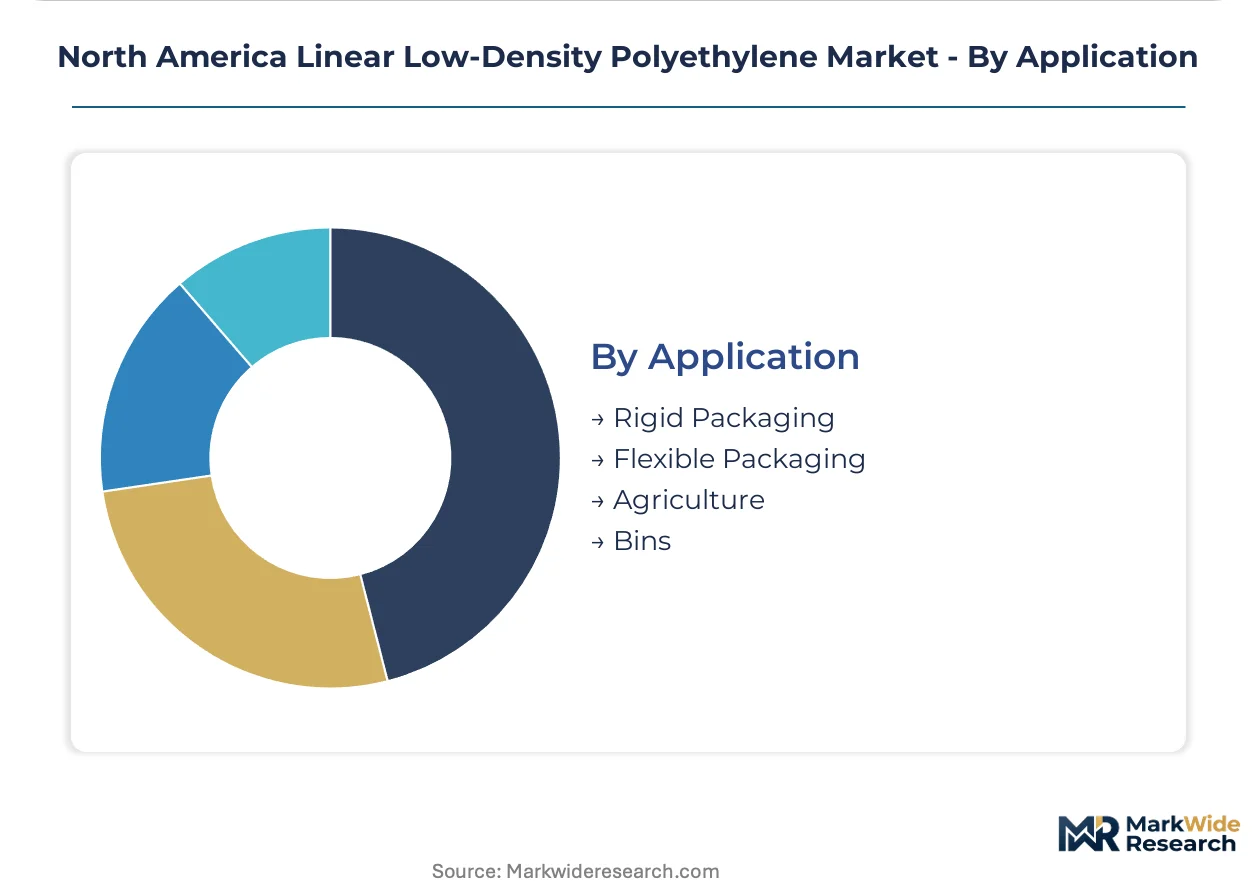
Application:
Customer type segmentation separates multinational brand owners with sustainability mandates from regional converters serving price-sensitive industrial segments.
- Flexible Packaging:Primary film applications for food, beverage, and personal care products carry the most stringent certification requirements. Canadian Prairie agriculture and US Southeast export corridors drive differentiated demand for UV and puncture-resistant formulations.
- Rigid Packaging:Bottles, caps, and closures serve dairy and juice segments where sealability and stress-crack resistance differentiate performance. Midwest dairy processing clusters concentrate procurement among qualified domestic suppliers.
- Agriculture:Silage bags, grain storage, and greenhouse films utilize UV-stabilized grades for seasonal durability.
- Bins:Industrial containers and totes for logistics and material handling applications.
Flexible Packaging leads by revenue contribution. Agriculture climbs the fastest as Prairie province adoption of silage film technology accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA recycled content mandates are redrawing procurement geography across North America as flexible packaging converters seek qualified suppliers with integrated Gulf Coast infrastructure and mass balance certification capabilities.
United States
Fresh produce packaging specifications and frozen food downgauging initiatives pull hexene and octene copolymer demand through the US Midwest processing corridor. OSHA process safety management standards shape capital allocation for Texas-Louisiana corridor plant expansions. The US Gulf Coast petrochemical cluster concentrates ethane-advantaged cracking capacity where Dow and Exxon Mobil Corporation anchor integrated production.
Canada
Underpenetrated silage and grain bagging applications in Alberta and Saskatchewan create white-space expansion for UV-stabilized film grades. Health Canada food-contact regulations align with EPA mandates on recycled content traceability for cross-border supply chains. Ontario's automotive molding corridor concentrates demand for lot-to-lot consistency certifications serving Detroit Three supplier programs.
Mexico
Export-oriented flexible packaging growth near Mexico City and Monterrey drives resin qualification for US brand owner supply chains. The country's national environmental regulator enforces emissions compliance at petrochemical facilities serving the Bajío manufacturing region. Nuevo León's industrial corridor attracts direct mill relationships as converters seek tariff-advantaged supply versus Asian imports.
North America Linear Low-Density Polyethylene Market Key Industry Players
Listed leaders compete with private specialists across integrated versus merchant supply positions. The supplier base concentrates around ethane-cracking operators with Gulf Coast infrastructure, compressing the qualified field to producers capable of ASTM D4976 lot-to-lot consistency. Three archetypes dominate: integrated majors with catalyst technology leadership, regional compounders serving industrial molding segments, and specialty distributors bridging qualification gaps for smaller converters. Capacity expansion and direct mill relationship formation represent the dominant competitive moves as converters consolidate procurement.
Among integrated majors, Dow and Exxon Mobil Corporation exemplify the technology-leader archetype through metallocene catalyst positions and ethane-advantaged Gulf Coast infrastructure. LyondellBasell Industries Holdings B.V. occupies the differentiated-grade tier with octene-based copolymer capabilities targeting premium film specifications. Chevron Phillips Chemical Company LLC represents the merchant-supply specialist position with Texas-Louisiana corridor access serving converters without integrated offtake agreements.
| Leading Market Players |
|---|
| Westlake Corporation |
| Formosa Plastics Corporation |
| Exxon Mobil Corporation |
| Arkema |
| INEOS MOLDS PVT. LTD |
| Dow |
| Chevron Phillips Chemical Company LLC |
| Borealis AG |
| LyondellBasell Industries Holdings B.V. |
| Others |
Cost & Logistics Intelligence
Ethane-for-naphtha feedstock substitution across the Texas-Louisiana corridor is simultaneously concentrating supply geography around Gulf Coast crackers and compressing pricing premiums for integrated producers versus European naphtha-dependent competitors. This feedstock arbitrage redraws procurement economics as converters lock in long-term offtake agreements to capture cost visibility.
Pricing Analysis
Certification level — ASTM D4976 food-contact grade versus industrial commodity tier — creates the primary spread between lot-to-lot consistency premiums and spot-market butene copolymer pricing. Three-tier pricing structure across metallocene premium, hexene standard, and butene economy levels reflects catalyst technology differentiation and converter qualification timelines. Cost compression in commodity grades is intensifying because mechanical recycling contamination limits closed-loop supply expansion. Regional converters serving price-sensitive industrial pails exhibit highest price sensitivity, while multinational flexible packaging groups with brand owner sustainability mandates show lowest.
Supply Chain Analysis
Just-in-time inventory preferences among major flexible packaging converters are displacing strategic stockpiling as ethane-advantaged Gulf Coast producers offer reliable lot-to-lot consistency without buffer stock requirements. Supply concentrates in the United States, Canada, and Mexico, with raw material dependencies spanning shale-derived ethane, alpha-olefin comonomers, and metallocene catalyst systems. Single-source vulnerability runs through proprietary catalyst technology held by three integrated majors. Distribution runs through direct mill relationships with integrated producers, bypassing traditional resin distribution intermediaries in high-volume film segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated flexible packaging converters negotiating multi-year offtake agreements, fragmenting the supplier field into qualified integrated producers and displaced merchant distributors.
For Market Incumbents: Shield margin pools by accelerating mass balance certification infrastructure for food-contact circular resins before EPA recycled content mandates harden qualification barriers. Deepen backward integration into chemical recycling partnerships with waste management operators to bypass mechanical degradation limits. Capacity addition in Alberta and Saskatchewan addresses underpenetrated Prairie agriculture demand. For New Entrants and Emerging Players: Differentiate on UV-stabilized silage film formulations for Canadian Prairie grain bagging applications where incumbent producers lack regional distribution density. Target Alberta and Saskatchewan agriculture cooperatives with seasonal procurement patterns ill-served by Gulf Coast supply chains. Go-to-market through technical service partnerships with regional equipment distributors. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed compounders holding automotive molding qualifications but lacking ethane-cracking integration. Long-term viability hinges on feedstock cost visibility across the analysis window. Watch ethane-naphtha spread compression as inflection indicator for regional export competitiveness erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Gulf Coast ethane crackers add metallocene film-grade output to capture EPA-mandated recycled content premiums. |
| Backward Integration | Converters acquire chemical recycling pilot plants to secure mass balance certification for brand owner contracts. |
| Long-term Supply Agreement | Three-to-five-year offtake contracts lock in ethane feedstock visibility for Midwest flexible packaging corridors. |
| Joint Venture | Pyrolysis partnerships with waste operators enable food-contact circular resins bypassing mechanical contamination limits. |
| Green Manufacturing Transition | Mass balance certification infrastructure captures premium film contracts from sustainability-committed brand owners. |
Research Approach
Operator-level perspectives from plant managers at ethane-cracking facilities, procurement leads at flexible packaging converters, distribution channel partners, and technical R&D directors anchored the qualitative base. Primary interviews combined with secondary validation against customs/trade data, ACC reports, SEC 10-K filings, and EPA emissions disclosures. Bottom-up resin grade demand modeling and top-down petrochemical capacity analysis provided triangulation.
Sensitivity analysis tested forecast robustness across ethane-naphtha spread scenarios and recycled content mandate implementation timelines. Segmentation dimensions spanned copolymer grade tier, end-use industry, processing technology, and regional production hub. CAGRs derived from ethylene feedstock cost curve projections and converter capacity utilization assumptions across the analysis window. Industry-specific inputs included metallocene catalyst adoption rates and mechanical recycling contamination coefficients.
Material uncertainties — feedstock cost spread volatility, EPA mandate enforcement timing, and chemical recycling yield rates — sit outside the modeled envelope. Forecasts reflect documented assumptions about ethane supply elasticity and converter qualification cycle durations. Revision becomes warranted when ethane-naphtha spread compression crosses thresholds that erode Gulf Coast export competitiveness.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Green Polyols Market
Polymers & Resins
Medical Grade Liquid Crystal Polymer Market
Polymers & Resins
United States Geopolymer Market
Polymers & Resins
Expanded Thermoplastic Polyurethane Market
Polymers & Resins
GCC Vinyl Flooring Market
Polymers & Resins
PA66 Market
Polymers & Resins
Natural Oil Polyols (NOP) Market
Polymers & Resins
Thermoplastic Polyurethane (TPU) Market
Polymers & Resins
Orthophthalic Resins Market
Polymers & Resins
Polychlorotrifluoroethylene (PCTFE) Market
Polymers & Resins
Europe Cyclic Olefin Copolymer Market
Polymers & Resins
Fire Resins Market
Polymers & Resins
Bio Based Resin Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Polycarbonate Glazing Market
Polymers & Resins
Southeast Asia Modified Polypropylene Market