
 Global Opaque Polymers Market | 2026-2036
Global Opaque Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Opaque Polymers Market Foresight
The capital-intensity divergence between integrated petrochemical giants and specialty additive producers is unwinding competitive stability in opaque polymers. BASF leverages its backward integration into acrylic monomers to control emulsion polymer cost structures. Arkema anchors its position through fluoropolymer-derived opacity technologies that command premium positioning in high-performance coatings. Croda International differentiates via bio-based surfactant stabilization systems for waterborne emulsions.
Opaque polymers are synthetic resin particles engineered with internal void structures that scatter visible light, typically measuring 0.3 to 0.6 micrometers in diameter and delivering titanium dioxide displacement ratios of 1:1 to 2:1 by dry film weight. Their primary commercial purpose is to reduce raw material costs in waterborne paints and coatings while maintaining hiding power and film integrity. Emulsion polymers occupy the dominant volume position due to direct compatibility with latex paint manufacturing infrastructure, while powdered polymers are gaining traction in powder coating segments where liquid delivery is impractical. Specialty polymers capture concentrated margin pools in automotive refinish and industrial OEM applications demanding weatherability and chemical resistance.
EPA regulations under TSCA and the EU's REACH framework restrict residual monomer content and mandate hazard communication for nano-scale voided particles, elevating compliance costs for non-integrated producers. China's MEE enforces dual carbon-aligned VOC limits that favor waterborne emulsion systems over solvent-borne alternatives in architectural coatings. India's BIS certification requirements for construction chemicals create additional testing barriers for imported specialty grades. Stakeholders must monitor evolving polymer classification thresholds under ECHA's nanoform registry and prepare formulation documentation for emerging bio-based content mandates.
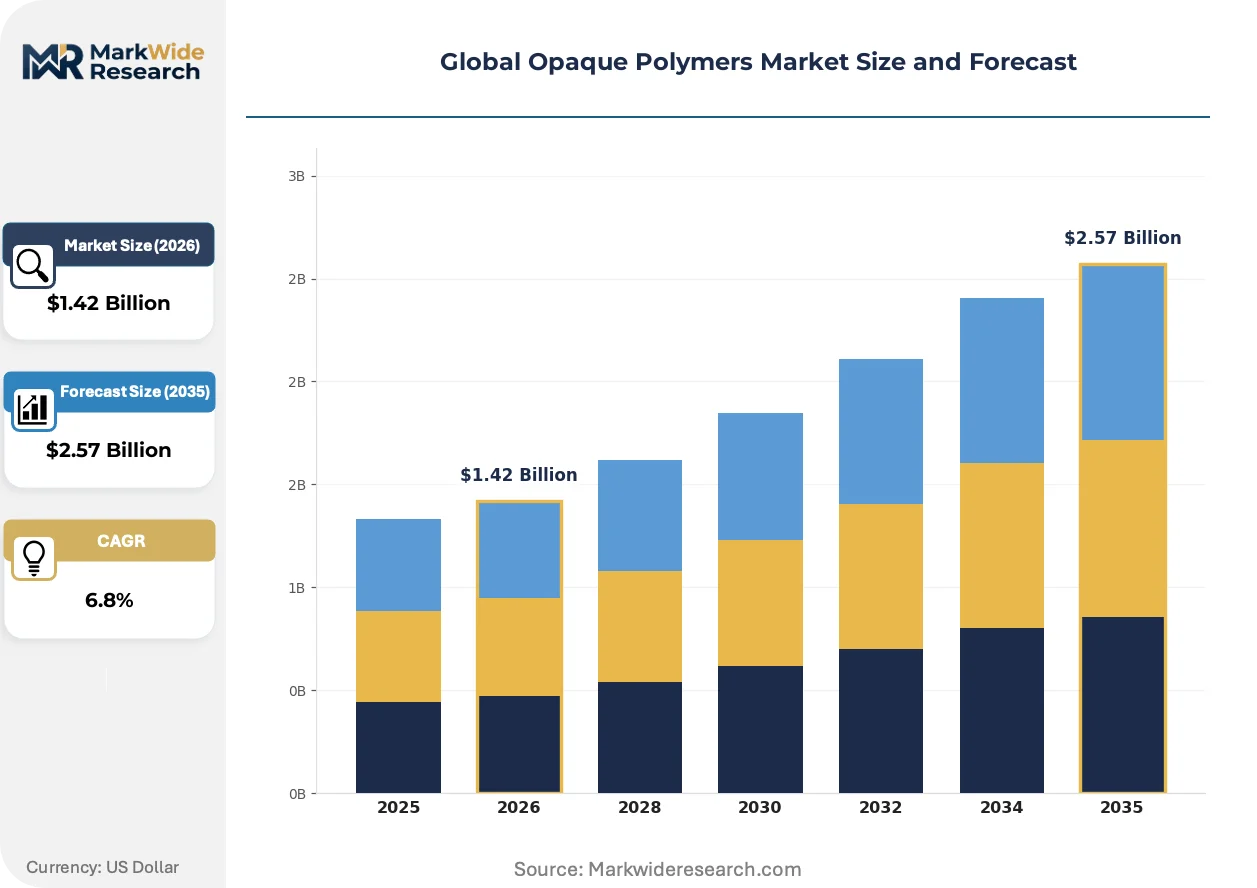
Market Dynamics
China's dual carbon goals and REACH compliance in Europe are forcing formulators to replace titanium dioxide with voided latex particles, rewiring raw material sourcing across architectural coatings value chains.
Growth Catalysts
- China's MEE VOC limits:Dual carbon-aligned thresholds favor waterborne emulsion systems over solvent-borne alternatives in construction coatings.
- Architectural coatings volume:Waterborne paint production clusters in India and Southeast Asia absorb expanded opaque polymer volumes as manufacturing scales.
- Titanium dioxide displacement:Voided latex particles deliver 1:1 to 2:1 hiding power substitution ratios, reducing raw material costs for formulators.
Market Restraints
- Acrylic monomer supply concentration:Backward-integrated petrochemical giants control emulsion polymer cost structures, squeezing non-integrated additive producers.
- ECHA nanoform registry:Evolving polymer classification thresholds elevate compliance documentation burdens for specialty grade importers.
- Residual monomer thresholds:EPA TSCA restrictions and REACH hazard communication mandates increase testing costs for voided particle formulations.
Strategic Opportunities
- India's BIS certification gaps:Construction chemical testing barriers for imported specialty grades create white space for domestic production partnerships.
- Powder coating segments:Liquid delivery limitations in industrial OEM applications favor powdered polymer format expansion.
- Automotive refinish convergence:Weatherability and chemical resistance requirements drive fluoropolymer-derived opacity technology adoption.
Industry Challenges
- Emulsion stabilization expertise:Bio-based surfactant formulation for waterborne systems requires specialized polymer science talent pools concentrated at integrated chemical majors.
- Multi-jurisdiction filing complexity:Cross-border registration under EPA TSCA, REACH, and China's MEE creates divergent documentation timelines for global product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Opaque Polymers Market |
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.57 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Emulsion Polymers, Powdered Polymers, Thermoplastic Polymers, Specialty Polymers Application: Coatings, Adhesives, Plastics, Inks End Use Industry: Construction, Automotive, Packaging, Consumer Goods Form: Liquid, Solid, Paste, Granular |
| Companies Covered | BASF, Dow Chemical Company, Arkema, Evonik Industries, DuPont de Nemours, LyondellBasell Industries, Ashland, Croda International, Formosa Plastics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Opaque Polymers Market Shifts & Advancements
Formulation chemistry and regulatory chemistry are converging to compress titanium dioxide dependence while expanding performance-grade polymer portfolios across industrial applications.
Voided latex emulsion technology is displacing conventional TiO2 loading in mid-tier architectural coatings. Asian formulators in China and India are accelerating adoption as local paint production scales. This displacement is compressing commodity pigment demand while expanding specialty polymer margin pools.
REACH framework amendments are tightening residual monomer content thresholds and mandating expanded hazard communication for nano-scale voided particles. European coating manufacturers face elevated compliance costs and reformulation documentation requirements. Specialty grade producers are responding by consolidating registration filings through ECHA's centralized portal.
Buyer procurement patterns are compressing supplier qualification cycles as waterborne paint manufacturers consolidate vendor bases. Regional formulators in Southeast Asia are unbundling after-sales technical service from material supply contracts. This behavioral shift is most visible in Vietnam and Indonesia where local production clusters prioritize direct mill integration over distributor intermediation.
Global Opaque Polymers Market Segmentation
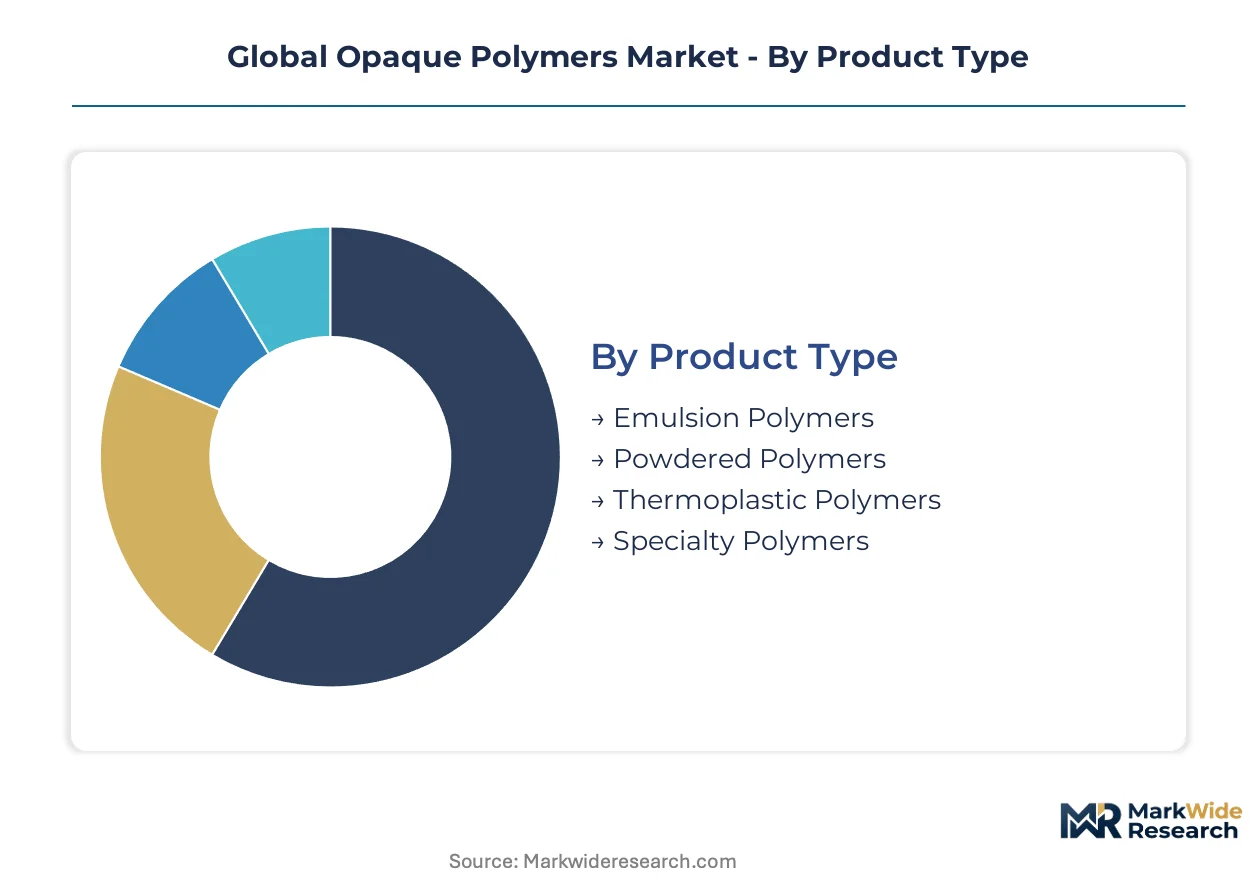
Opaque polymer selection hinges on manufacturing infrastructure compatibility and end-use performance thresholds. Formulators balance titanium dioxide displacement efficiency against application-specific hiding power and film integrity requirements across divergent industrial processes.
Product Type:
Emulsion polymers dominate domestic production clusters in China and India where waterborne paint manufacturing scales rapidly. Powdered polymers concentrate in export-oriented specialty coating operations serving industrial OEM markets in Germany and Japan.
- Emulsion Polymers:Aqueous dispersions of voided acrylic or styrene-acrylic particles engineered for direct integration into latex paint manufacturing lines. Demand concentrates in Chinese and Indian architectural coating plants where MEE VOC limits and BIS certification requirements favor waterborne systems over solvent-borne alternatives.
- Specialty Polymers:Fluoropolymer-derived or hybrid core-shell architectures delivering weatherability and chemical resistance for automotive refinish and industrial maintenance applications. Japanese and German formulators absorb expanded volumes as performance specifications tighten for exterior durability.
- Powdered Polymers:Spray-dried or coacervated voided particles for powder coating segments where liquid delivery is impractical.
- Thermoplastic Polymers:Melt-processable opacity additives for extrusion and injection molding applications in packaging and consumer goods.
Emulsion polymers command the established base. The steepest expansion runs through specialty polymers.
Application:
Cost tier stratification separates commodity architectural coatings from premium industrial formulations. Mid-tier waterborne paints absorb the highest opaque polymer volumes while adhesive and ink applications concentrate in specialized additive portfolios.
- Coatings:Architectural, automotive, and industrial formulations leveraging voided particles for titanium dioxide displacement. Waterborne architectural coatings in Vietnam and Indonesia absorb expanded volumes as local manufacturing clusters scale production.
- Plastics:Extruded and molded polymer applications requiring melt stability and dispersion uniformity. Packaging converters in South Korea and Thailand integrate opacity additives for lightweight container applications.
- Adhesives:Pressure-sensitive and construction adhesive formulations where hiding power complements bonding performance.
- Inks:Flexographic and gravure printing systems demanding fine particle dispersion for uniform opacity.
Coatings anchor volume concentration. Plastics are climbing the fastest as packaging lightweighting accelerates across Asian manufacturing hubs.
End Use Industry:
Customer procurement patterns diverge between project-driven construction sectors and specification-controlled automotive OEM supply chains. Construction formulators prioritize cost displacement while automotive tiers demand certified performance documentation.
- Construction:Architectural coating formulators replacing titanium dioxide with voided latex particles in interior and exterior paint systems. Indian and Chinese construction chemical manufacturers scale absorption as urban residential and commercial building activity concentrates in Mumbai, Shanghai, and Jakarta corridors.
- Automotive:OEM and refinish coatings requiring weatherability, gloss retention, and chip resistance. German and Japanese automotive coating suppliers specify fluoropolymer-derived opacity technologies for premium vehicle finishes.
- Packaging:Food and consumer goods containers where opacity meets regulatory compliance for migration limits.
- Consumer Goods:Appliance and furniture coatings where aesthetic hiding power balances manufacturing cost constraints.
Construction holds the volume base. Automotive is gaining share fastest as refinish specification tightening spreads from European to Asian premium markets.
Form:
Supply concentration favors liquid emulsion formats where integrated petrochemical producers control monomer-to-dispersion value chains. Solid and paste formats serve niche applications where logistics or handling constraints override manufacturing efficiency.
- Liquid:Pumpable aqueous dispersions with 30-50% solids content for direct mill addition in paint manufacturing. Chinese and Indian waterborne coating plants standardize on liquid delivery for continuous production integration.
- Solid:Spray-dried or freeze-dried powders for powder coating and plastics compounding where moisture sensitivity prohibits aqueous systems. Japanese industrial OEM coating operations favor solid formats for electrostatic spray applications.
- Paste:High-solids concentrated dispersions for specialized adhesive and sealant formulations.
- Granular:Free-flowing particulate forms for automated dosing in extrusion and molding operations.
Liquid formats dominate manufacturing integration. Solid forms are expanding most quickly as powder coating adoption accelerates in European and East Asian industrial finishing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price-sensitive formulators in India and Southeast Asia absorb commodity-grade volumes aggressively, while German and Japanese automotive coating specialists pay premiums for certified performance documentation. This elasticity divergence is concentrating margin capture among integrated suppliers serving specification-controlled tiers.
China
Architectural coating plants in Shanghai and the Yangtze River Delta absorb expanded emulsion polymer volumes as waterborne paint manufacturing scales. The Ministry of Ecology and Environment enforces dual carbon-aligned VOC limits that favor voided latex systems over solvent-borne alternatives. Formulators in the Pearl River Delta are replacing titanium dioxide with opacity additives to meet tightening environmental thresholds.
India
Construction chemical manufacturers in Mumbai and Gujarat scale absorption as urban residential building activity accelerates. The Bureau of Indian Standards certification requirements for imported specialty grades create testing barriers that favor domestic production partnerships. Waterborne coating plants in the Delhi-NCR corridor are standardizing on liquid emulsion formats for continuous mill integration.
Germany
Automotive OEM and refinish coating suppliers specify fluoropolymer-derived opacity technologies for premium vehicle finishes. The European Chemicals Agency's nanoform registry mandates expanded hazard communication documentation for voided particle formulations. Industrial finishing operations in Bavaria and North Rhine-Westphalia are accelerating powder coating adoption, expanding demand for solid-format polymers.
United States
Mid-tier architectural coating formulators leverage titanium dioxide displacement ratios to compress raw material costs. The Environmental Protection Agency's TSCA restrictions on residual monomer content elevate compliance testing burdens for non-integrated producers. Manufacturing clusters in Texas and the Ohio River Valley prioritize direct mill integration over distributor intermediation.
Japan
Industrial OEM coating operations favor solid polymer formats for electrostatic spray applications where moisture sensitivity prohibits aqueous systems. The Ministry of Economy, Trade and Industry oversees standards alignment with international performance specifications. Specialty coating producers in the Kansai and Chubu regions absorb expanded fluoropolymer-derived volumes as exterior durability requirements tighten.
Global Opaque Polymers Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. The market consolidates around integrated petrochemical majors controlling monomer-to-dispersion value chains and specialty additive producers commanding premium positioning through formulation expertise. Three archetypes dominate: backward-integrated resin producers, fluoropolymer technology specialists, and bio-based surfactant innovators. Competitive moves concentrate on capacity expansion in Asian manufacturing clusters and strategic partnerships to secure distribution in emerging markets.
Within the integrated petrochemical tier, BASF and Dow Chemical Company exemplify archetypes leveraging captive acrylic monomer supply to control emulsion cost structures. Arkema occupies a position representing fluoropolymer-derived opacity technology for high-performance applications. Croda International sits within the specialty surfactant tier, anchoring bio-based stabilization systems for waterborne formulations.
| Leading Market Players |
|---|
| BASF |
| Dow Chemical Company |
| Arkema |
| Evonik Industries |
| DuPont de Nemours |
| LyondellBasell Industries |
| Ashland |
| Croda International |
| Formosa Plastics Corporation |
| Others |
Supply & Pricing Matrix
Capacity utilization at integrated petrochemical complexes in Germany and China establishes cost floors that specialty additive producers struggle to match. BASF's captive acrylic monomer supply anchors price discipline across emulsion polymer tiers. Non-integrated formulators face margin compression as backward-integrated competitors leverage scale economies in monomer-to-dispersion value chains.
Pricing Analysis
After-sales technical service bundling drives lifetime value capture for specialty grade suppliers serving automotive OEM specifications. Three-tier pricing structure across premium, standard, and economy levels separates fluoropolymer-derived opacity technologies from commodity emulsion grades. Cost compression in mid-tier architectural coatings intensifies because Indian and Southeast Asian formulators prioritize titanium dioxide displacement ratios over performance documentation. Construction chemical buyers in Mumbai and Jakarta corridors exhibit highest price sensitivity. German automotive coating specialists demonstrate lowest sensitivity, paying premiums for ECHA nanoform registry compliance and certified weatherability data.
Supply Chain Analysis
Just-in-time liquid emulsion delivery dominates Chinese and Indian waterborne paint manufacturing clusters where continuous mill integration minimizes working capital. Raw material sourcing draws from Saudi Arabia and South Korea for acrylic monomer feedstocks, with styrene supply anchored in Singapore and Thailand. Single-source vulnerability concentrates in specialty fluoropolymer resin supply from Japanese chemical complexes. Distribution runs through direct mill integration partnerships in Vietnam and Indonesia, bypassing traditional distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards defensive moats built on regulatory entrenchment. ECHA nanoform registry compliance and REACH documentation requirements create switching costs that lock in qualified suppliers.
For Market Incumbents: Consolidate registration filings through ECHA's centralized portal to streamline multi-jurisdiction compliance. Deepen backward integration into bio-based surfactant stabilization systems to defend against Croda International's specialty positioning. Capacity addition in Gujarat and Maharashtra industrial corridors captures BIS certification-constrained import substitution demand.
For New Entrants and Emerging Players: BIS certification fast-track partnerships with Indian construction chemical manufacturers unlock white space in Mumbai-Delhi residential building corridors. Target powder coating segments in Bavaria and North Rhine-Westphalia where solid format polymer demand outpaces established supply. Go-to-market through direct mill integration contracts bypasses entrenched distributor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated petrochemical majors with captive monomer supply and long-term offtake agreements with Asian paint manufacturers. Five-to-ten year viability favors backward-integrated resin producers over formulation-only specialists. Watch for inflection when China's MEE tightens VOC thresholds beyond current dual carbon-aligned limits, accelerating titanium dioxide displacement adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomers | BASF leverages captive supply to control emulsion polymer cost structures against non-integrated competitors. |
| Fluoropolymer Technology Licensing | Arkema extends premium positioning into Asian automotive refinish markets demanding weatherability certification. |
| Bio-based Surfactant R&D Partnership | Croda International anchors differentiation in waterborne emulsion stabilization systems for REACH-compliant formulations. |
| Capacity Expansion in Gujarat Corridor | Domestic production partnerships circumvent BIS certification barriers for imported specialty grades. |
| ECHA Nanoform Registry Consolidation | Centralized filing reduces documentation burden for cross-border launches under divergent regulatory timelines. |
Research Methodology
A standing panel of plant managers at waterborne coating facilities, procurement leads at downstream paint manufacturers, distribution channel partners, and technical R&D directors provided ongoing calibration. Primary interviews combined with secondary validation from customs/trade data, ACC and Cefic industry reports, SEC 10-K filings, and ECHA registration databases. Bottom-up capacity and consumption estimates triangulated against top-down value chain reconstructions.
Consistency checks validated volume and value outputs against external benchmarks across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry cluster, packaging format, and regional production hub. CAGRs derived from slope-intercept analysis of historical trajectory and forward-looking capacity announcements. Industry-specific forecast inputs incorporated MEE VOC limit enforcement timelines and BIS certification processing rates.
Underlying assumptions cover sustained dual carbon policy enforcement in China and REACH framework stability in Europe, with deviation risk concentrated in regulatory threshold acceleration or trade restriction implementation. Revision becomes warranted when titanium dioxide price volatility crosses thresholds that alter displacement economics for voided latex particles.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Solid Masterbatches Market
Polymers & Resins
Global Colored PU Foams Market
Polymers & Resins
Polycide Market
Polymers & Resins
Global Amorphous Polyalphaolefin (APAO) for Hot Melt Market
Polymers & Resins
Flame Retardant Thermoplastics Market
Polymers & Resins
Polyolefin Wax Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Asia-Pacific Polyethylene Wax Market
Polymers & Resins
Synthetic and Bio Emulsion Polymers Market
Polymers & Resins
Chlorinated Polyolefins Market
Polymers & Resins
Photocurable Resins Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Polymer Alloys Market
Polymers & Resins
Europe Polyolefin Market
Polymers & Resins
Polydicyclopentadiene (Pdcpd) Market
Polymers & Resins
High-Density Polyethylene (HDPE) Resins Market