
 Silver Sulfadiazine Market | 2026-2036
Silver Sulfadiazine Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Sulfadiazine Market Analytics
Pre-filled single-use cream sachets paired with non-adherent dressings is hardening as the standard configuration for hospital burn protocols. Sun Pharmaceutical Industries leverages its generic manufacturing scale to supply multi-market cream formulations at competitive unit economics. Fresenius Kabi anchors its position through hospital-centric distribution that reaches acute care settings directly. Teva Pharmaceutical Industries competes on regulatory dossier breadth, sustaining approvals across North American and European jurisdictions.
Silver sulfadiazine is a sulfonamide-derived topical antimicrobial agent containing one percent silver salt in a water-miscible cream base, functioning through sustained silver ion release that disrupts bacterial cell membranes and DNA replication in burn wounds and infected dermal lesions. The cream segment dominates current volume due to established compendial monographs and ease of application in inpatient settings, while gel formulations represent the fastest-growing configuration as clinicians seek improved patient adherence and reduced dressing change frequency. Burn wound care applications command the largest share of clinical demand, though surgical wound management is expanding as hospitals adopt silver-based prophylaxis for high-risk operative sites.
FDA antimicrobial drug guidance and USP sterility testing standards govern product quality and batch release for silver sulfadiazine preparations marketed in the United States, while the EMA's quality guidelines for topical antibiotics shape European market access requirements. India's CDSCO mandates bioequivalence documentation for generic cream formulations under its New Drugs and Clinical Trials Rules, influencing export-oriented manufacturers. Stakeholders must monitor evolving antimicrobial stewardship protocols that restrict silver agent use to culture-confirmed infections rather than empirical prophylaxis.
Market Dynamics
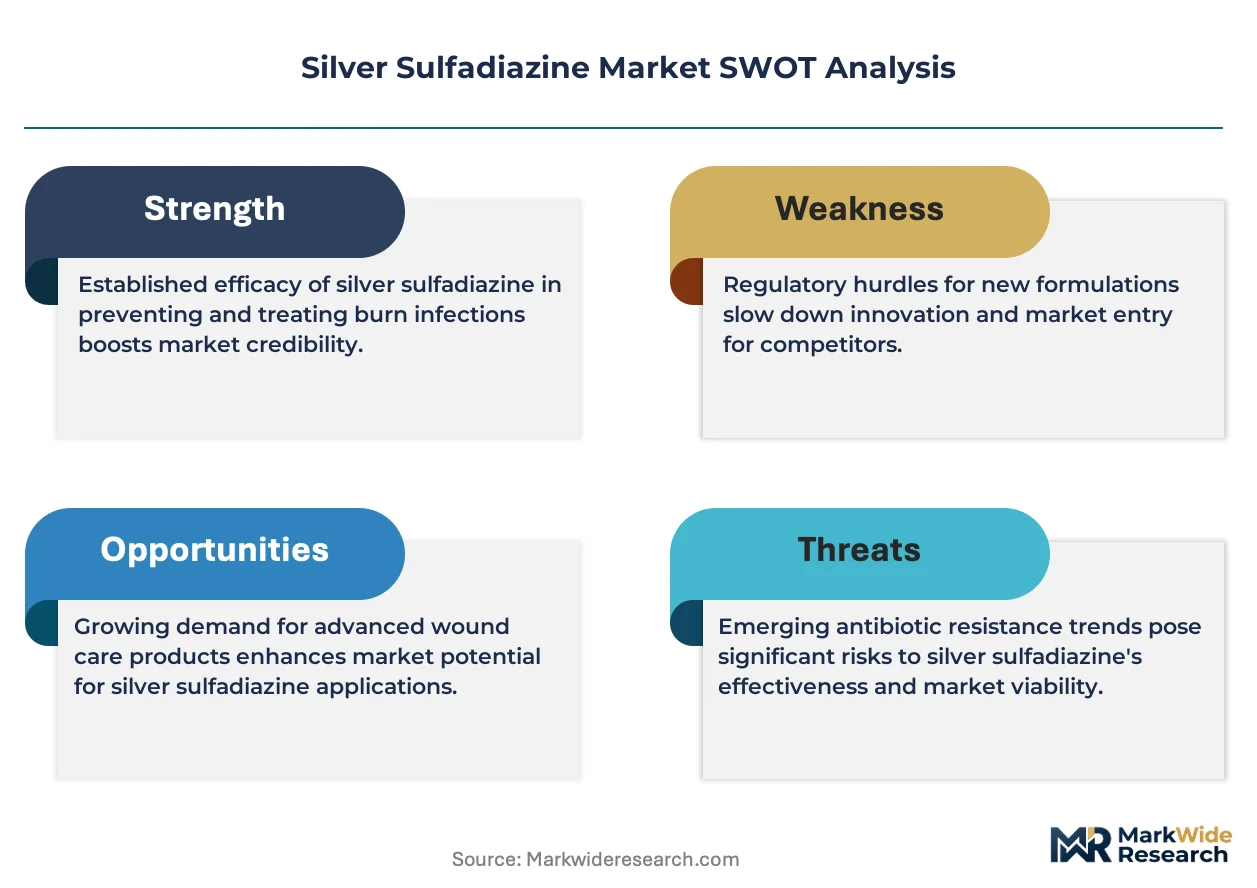
FDA antimicrobial drug guidance is tightening purity thresholds for silver-based actives, forcing manufacturers to revalidate batch release protocols and upgrade analytical testing infrastructure across cream and gel production lines.
Growth Catalysts
- Hospital burn center expansion:Tertiary care networks in the United States are scaling dedicated wound management programs that standardize topical antimicrobial dressings for partial-thickness protocols.
- EMA quality guidelines:European market access requirements for topical antibiotics are harmonizing dossier standards, reducing regulatory friction for multi-jurisdiction filings.
- Silver ion release technology:Sustained-release formulations are extending dressing change intervals, improving inpatient throughput and reducing nursing labor allocation.
Market Restraints
- Silver price volatility:Precious metal commodity swings compress margin predictability for cream manufacturers dependent on silver salt feedstock.
- Antimicrobial stewardship protocols:Culture-confirmed infection requirements are restricting empirical prophylaxis use in surgical wound management.
- Alternative topical agents:Silver-impregnated hydrofiber dressings and iodine-based solutions are capturing protocol share in outpatient burn care.
Strategic Opportunities
- CDSCO bioequivalence pathway:India's streamlined generic approval framework under New Drugs and Clinical Trials Rules offers export-oriented manufacturers accelerated market entry.
- Gel formulation white space:Patient adherence advantages and reduced dressing change frequency are driving clinician preference shifts away from traditional cream bases.
- Single-use sachet configuration:Pre-filled unit-dose packaging paired with non-adherent dressings addresses hospital infection control priorities.
Industry Challenges
- USP sterility testing timelines:Enhanced batch release requirements are extending quality control cycles and compressing production scheduling flexibility.
- Cross-functional talent scarcity:Formulation chemists with combined expertise in sulfonamide stability and silver ion kinetics command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Sulfadiazine Market |
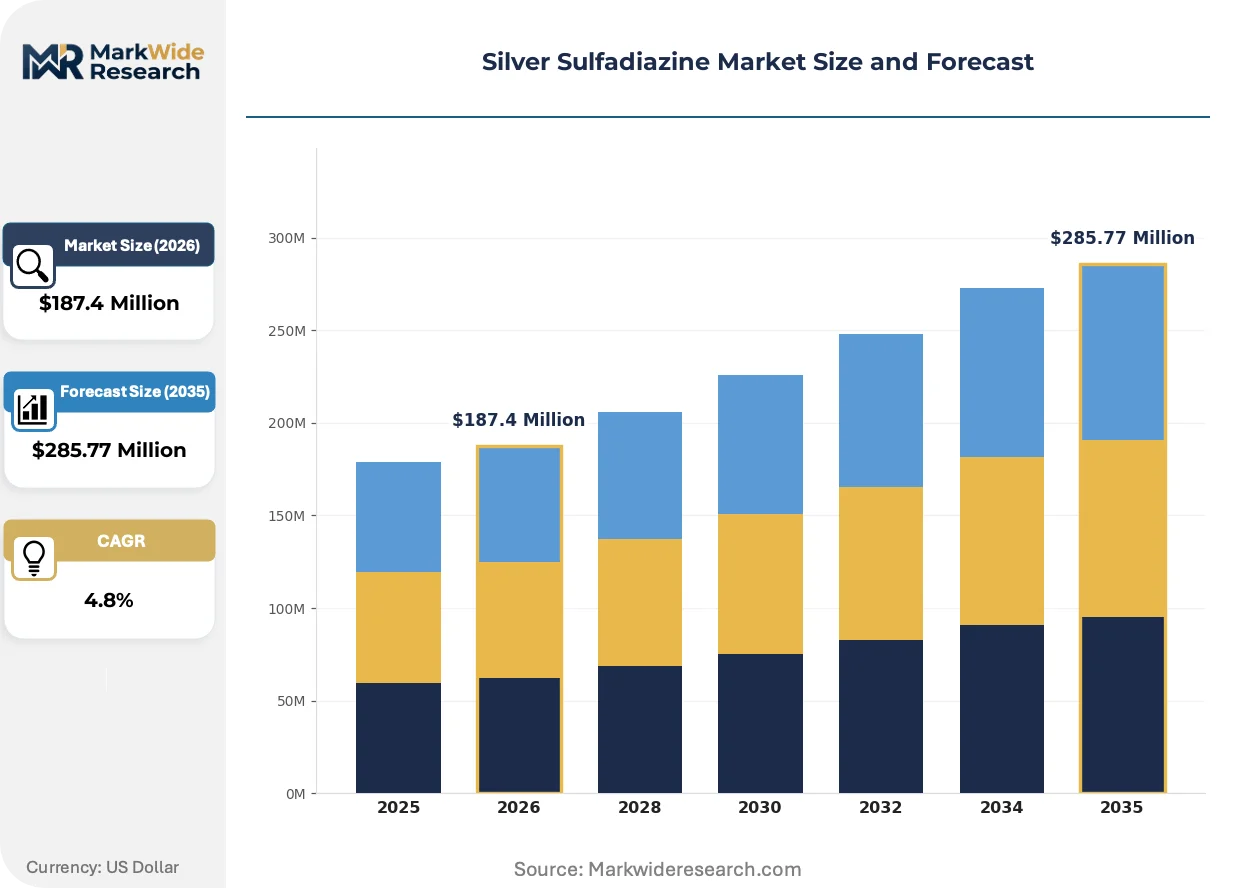
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Cream, Ointment, Powder, Spray, Gel Application: Burn Wound Care, Ulcer Treatment, Surgical Wound Management, Skin Infection Control, Dermatology Procedures End User: Burn Centers, Clinics, Ambulatory Surgical Centers, Homecare Providers, Pharmaceutical Hospitals Distribution Channel: Pharmacies, Online Retailers, Hospitals, Medical Supply Stores, Direct Sales |
| Companies Covered | Sun Pharmaceutical Industries, Fresenius Kabi, Teva Pharmaceutical Industries, Lusochimica SpA, Zydus Cadila, Sandoz, Aurobindo Pharma, Macsen Drugs, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Sulfadiazine Market Evolving Landscape
Formulation science and packaging engineering are converging to reshape how silver sulfadiazine reaches acute care settings, with patient adherence and nursing efficiency emerging as design priorities.
Hydrogel carrier systems with embedded silver sulfadiazine are electrifying the topical antimicrobial category by enabling sustained drug release over 72-hour intervals. Burn centers in the United States are piloting these configurations for outpatient partial-thickness management. The technology is electrifying competitive positioning by collapsing the traditional dressing change frequency from twice-daily to every three days.
EMA's quality guidelines for topical antibiotics are tightening impurity profiling requirements for sulfonamide-derived actives, mandating expanded analytical method validation. European manufacturers are responding by investing in high-resolution mass spectrometry capabilities for batch release testing. Gel formulations face heightened scrutiny due to complex polymer-silver ion interaction matrices.
Hospital procurement departments are consolidating vendor relationships around full-protocol suppliers capable of delivering cream, dressing, and irrigation solutions under single-source contracts. This concentration is displacing fragmented purchasing across separate pharmacy and wound care budgets. The shift is most visible in North American tertiary care networks with dedicated burn center accreditation.
Silver Sulfadiazine Market Segmentation
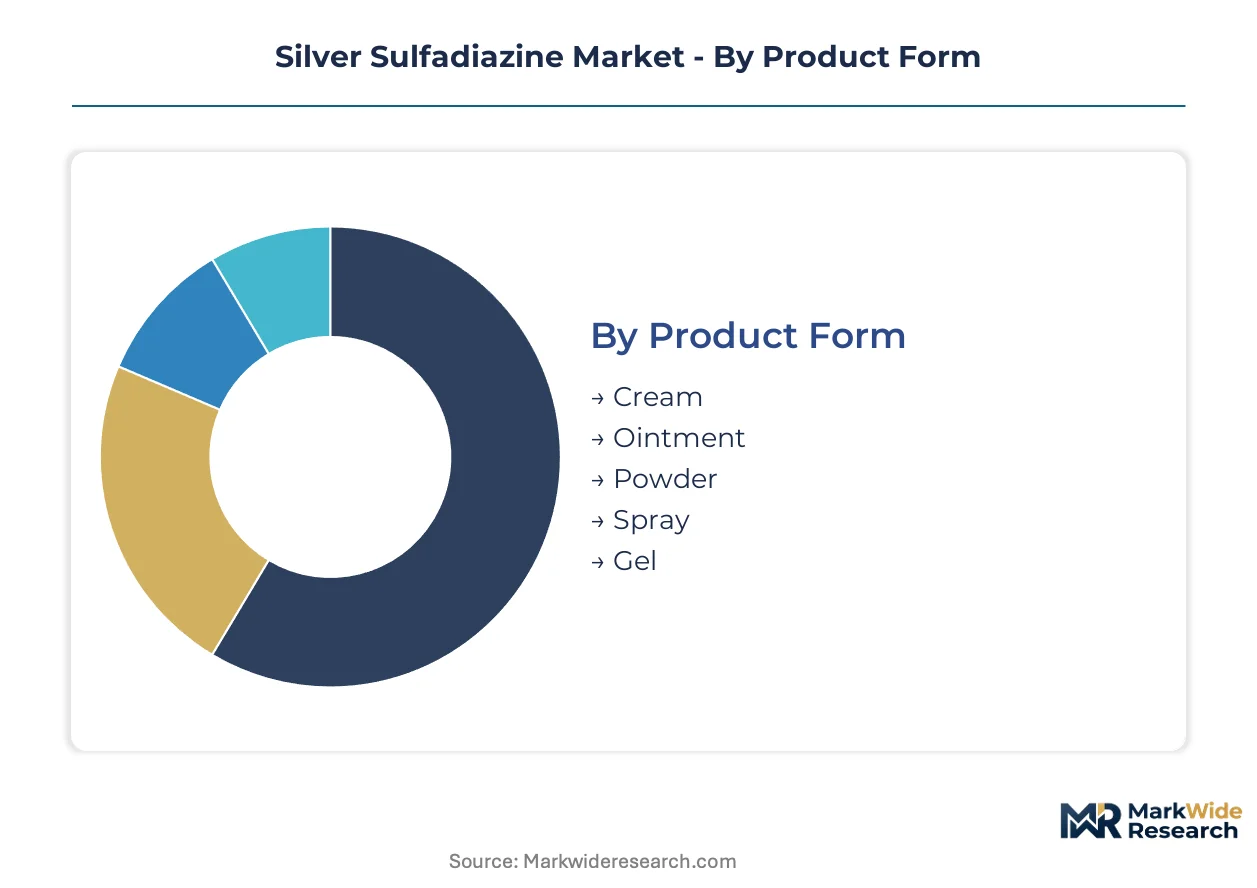
Silver sulfadiazine formulations vary sharply in clinical utility based on wound type, care setting, and dosing precision requirements. Each segmentation axis reveals distinct procurement patterns and margin structures that shape manufacturer positioning.
Product Form:
Hospital formularies differentiate purchasing based on application frequency, dressing compatibility, and nursing labor intensity.
- Cream:Water-miscible base with one percent silver salt concentration enables direct wound bed application and established USP compendial standards. United States burn centers anchor procurement volumes through standardized partial-thickness protocols, though FDA antimicrobial guidance is tightening purity thresholds for batch release.
- Gel:Hydrogel carrier systems embed silver sulfadiazine for sustained 72-hour ion release, collapsing dressing change intervals from twice-daily to every three days. Outpatient burn management in tertiary care networks is driving clinician preference shifts toward this configuration for adherence advantages.
- Ointment:Petroleum-based vehicles offer occlusive properties for dry eschar coverage in select surgical wound protocols.
- Powder:Lyophilized formulations serve niche irrigation applications in operative site preparation.
- Spray:Aerosolized delivery targets large surface area burns where mechanical application risks patient trauma.
Cream leads volumes today; gel is gaining share fastest.
Application:
Clinical demand concentrates where silver ion prophylaxis demonstrates measurable infection rate reduction against culture-confirmed pathogens.
- Burn Wound Care:Partial-thickness and full-thickness thermal injuries command the largest share of institutional procurement, with United States hospital burn centers standardizing topical antimicrobial dressings for admission protocols. EMA quality guidelines for topical antibiotics shape European access requirements for sulfonamide-derived actives in this category.
- Surgical Wound Management:High-risk operative sites—particularly abdominal and orthopedic procedures—are expanding silver-based prophylaxis adoption as hospitals track surgical site infection metrics. Antimicrobial stewardship protocols restricting empirical use to culture-confirmed infections are constraining volume growth in this segment.
- Ulcer Treatment:Diabetic foot and pressure ulcers in long-term care settings generate recurring prescription demand.
- Skin Infection Control:Secondary bacterial colonization of dermatologic conditions drives outpatient pharmacy dispensing.
- Dermatology Procedures:Post-ablative laser and chemical peel protocols utilize silver sulfadiazine for barrier protection.
Burn wound care dominates current value; surgical wound management is expanding most quickly.
End User:
Care setting determines packaging requirements, unit dosing preferences, and infection control stringency.
- Hospital Burn Centers:Dedicated wound management programs in United States tertiary care networks standardize pre-filled single-use sachets paired with non-adherent dressings. These facilities consolidate vendor relationships around full-protocol suppliers capable of delivering cream, dressing, and irrigation solutions under single-source contracts.
- Pharmaceutical Hospitals:Acute care institutions with captive pharmacies anchor demand through direct distribution relationships with manufacturers like Fresenius Kabi, bypassing wholesale intermediaries for inventory velocity.
- Ambulatory Surgical Centers:Outpatient procedural volumes are rising for partial-thickness burn management, with gel formulations preferred for reduced follow-up visit frequency.
- Clinics:Primary and urgent care settings generate prescription volume for minor burn and infection presentations.
- Homecare Providers:Post-discharge wound management is shifting toward patient-administered gel configurations for adherence.
Hospital burn centers command the largest share; ambulatory surgical centers are climbing the fastest.
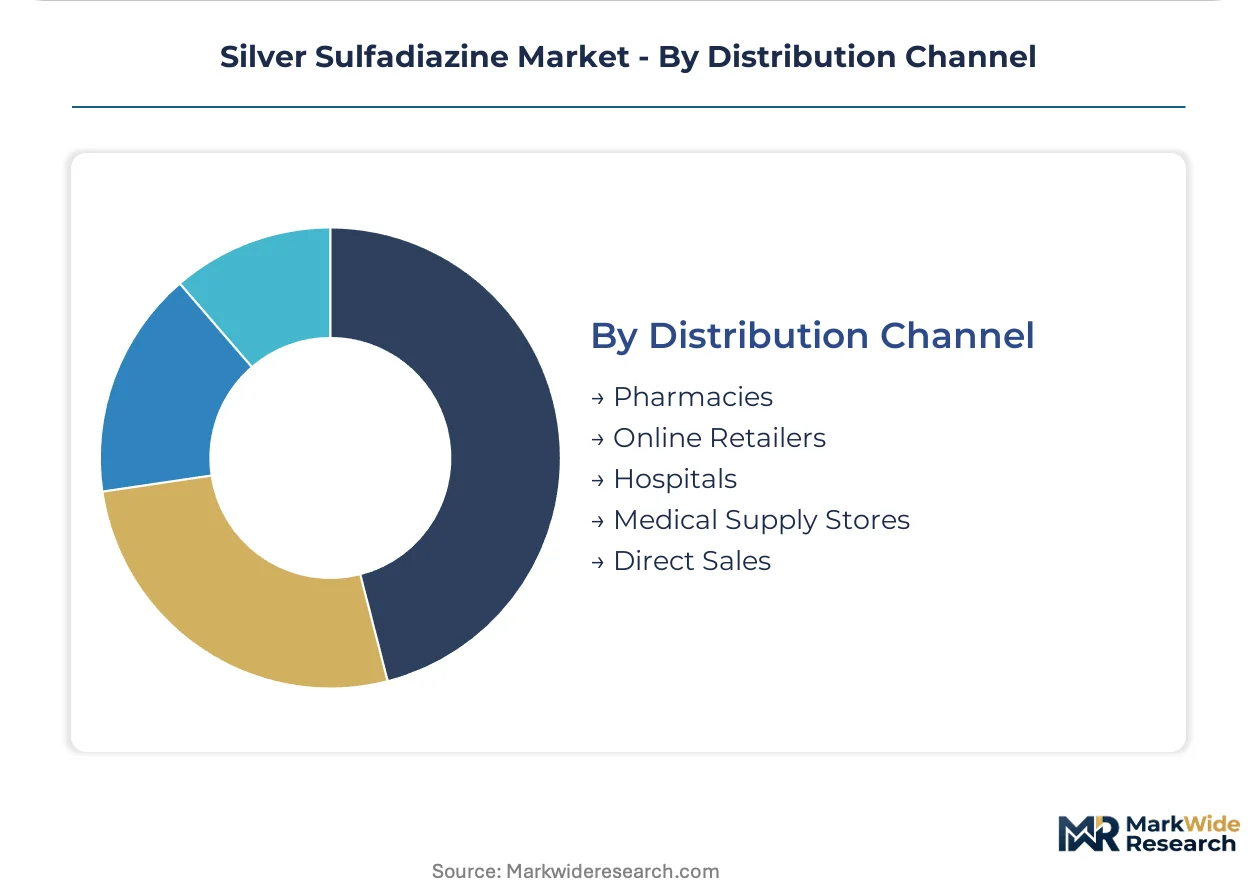
Distribution Channel:
Channel selection reflects institutional procurement consolidation trends and regulatory compliance burdens.
- Hospitals:Direct contracting with manufacturers captures the majority of United States institutional volume, with procurement departments consolidating around vendors offering sterile unit-dose packaging and batch documentation aligned with USP sterility testing standards.
- Pharmacies:Retail and outpatient hospital pharmacies dispense prescription volumes for post-discharge and minor wound indications, with generic manufacturers like Sun Pharmaceutical Industries competing on unit economics.
- Medical Supply Stores:Durable medical equipment distributors serve homecare and long-term care segments with bulk cream configurations.
- Online Retailers:E-commerce penetration remains limited by prescription requirements and cold chain considerations for gel formulations.
- Direct Sales:Manufacturer field forces target burn center accreditation programs for protocol inclusion.
Hospitals dominate channel value; medical supply stores are expanding most quickly in homecare adjacencies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silver sulfadiazine achieved commercial scale in the United States during the 1960s following FDA approval for burn wound management, establishing the country as the foundational market for topical silver antimicrobial protocols. The historical concentration of tertiary burn centers in North America shaped early formulation standards and regulatory benchmarks that subsequently diffused to European and Asian markets.
United States
Hospital burn centers in tertiary care networks drive institutional procurement through standardized partial-thickness wound protocols. FDA antimicrobial drug guidance tightens purity thresholds for silver-based actives, forcing manufacturers to revalidate batch release testing. The Southwest and Southeast regions concentrate dedicated wound management programs with single-source vendor contracting.
Germany
EMA quality guidelines for topical antibiotics harmonize dossier standards across member states, reducing regulatory friction for sulfonamide-derived actives. German hospital procurement departments consolidate around full-protocol suppliers capable of delivering cream, dressing, and irrigation solutions. The North Rhine-Westphalia region anchors acute care distribution networks reaching Central European markets.
India
CDSCO mandates bioequivalence documentation for generic cream formulations under New Drugs and Clinical Trials Rules, shaping export-oriented manufacturing strategies. Domestic demand concentrates in government hospital burn units and private tertiary facilities. Gujarat and Maharashtra host formulation facilities supplying regulated markets in North America and Europe.
United Kingdom
NHS procurement frameworks prioritize unit-dose packaging configurations aligned with infection control protocols in acute care settings. The Medicines and Healthcare products Regulatory Agency enforces sterility testing standards for topical antimicrobial batch release. Greater London and the Midlands concentrate hospital pharmacy purchasing for burn center networks.
Japan
PMDA quality guidelines govern sulfonamide stability requirements for topical antimicrobial products marketed in domestic hospital channels. Demand concentrates in university-affiliated burn centers with dedicated wound management accreditation. The Kanto region around Tokyo anchors distribution infrastructure serving high-volume acute care institutions.
Silver Sulfadiazine Market Competitive Landscape
The competitive structure tilts toward generic pharmaceutical manufacturers with established regulatory dossier breadth across multiple jurisdictions. Market concentration reflects scale advantages in batch manufacturing and analytical testing infrastructure required by tightening USP and EMA standards. Two archetypes dominate: multinational generic houses with hospital-centric distribution networks, and regional specialists leveraging cost-competitive feedstock sourcing. Competitive moves center on formulation diversification into gel configurations and single-use sachet packaging paired with non-adherent dressings.
Among multinational generic manufacturers, Sun Pharmaceutical Industries, Fresenius Kabi, and Teva Pharmaceutical Industries occupy positions reflecting distinct strategic emphases. Sun Pharmaceutical exemplifies scale-driven supply to multi-market cream formulations. Fresenius Kabi anchors hospital-centric distribution reaching acute care settings directly. Teva Pharmaceutical represents regulatory dossier breadth sustaining approvals across North American and European jurisdictions.
| Leading Market Players |
|---|
| Sun Pharmaceutical Industries |
| Fresenius Kabi |
| Teva Pharmaceutical Industries |
| Lusochimica SpA |
| Zydus Cadila |
| Sandoz |
| Aurobindo Pharma |
| Macsen Drugs |
| Pfizer |
| Others |
Value Network & Pricing Analysis
Formulation-grade purity divergence between USP-certified batch release and standard compendial compliance splits procurement economics in silver sulfadiazine manufacturing. FDA antimicrobial guidance tightening thresholds for silver salt feedstock concentrates pricing power with analytical-testing-capable suppliers while compressing margins for commodity-grade producers dependent on spot silver purchases.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments silver sulfadiazine procurement by certification grade and sterility assurance depth. Premium tiers command differential pricing through validated USP sterility documentation and single-use sachet configurations, while economy positioning targets bulk cream dispensing in long-term care. Cost compression in standard-grade cream manufacturing intensifies because silver commodity volatility feeds directly into formulation economics. Hospital burn centers exhibit lowest price sensitivity given protocol standardization requirements, whereas ambulatory surgical centers negotiate aggressively on per-unit gel pricing.
Supply Chain Analysis
Domestic-content mandates under India's PLI scheme for pharmaceutical manufacturing are reshaping sourcing patterns for export-oriented silver sulfadiazine producers. Active pharmaceutical ingredient production draws from India, China, and the United States as primary concentration points, with silver salt refinement anchored in precious metal processing clusters. Sulfonamide base chemical supply rests on petrochemical feedstock flows from Gulf Coast and Northeast Asian production hubs. Single-source vulnerability in silver nitrate purification creates exposure to commodity price spikes. Distribution runs through hospital-centric direct contracting networks in North America and European tender-based procurement systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silver sulfadiazine manufacturing economics favor geographic arbitrage between Indian bulk API production and North American formulation finishing, exploiting CDSCO's streamlined bioequivalence pathway against FDA's tightening purity enforcement.
For Market Incumbents: Deepen analytical testing infrastructure investments to defend batch release capabilities against USP sterility timeline extensions. Secure captive silver salt supply through backward integration into precious metal refining or long-term offtake agreements with primary refiners. Counter gel formulation displacement threats by accelerating hydrogel carrier technology licensing from specialty polymer suppliers. For New Entrants and Emerging Players: Sustained-release hydrogel technology offers entry leverage into outpatient burn management protocols underserved by incumbent cream-focused suppliers. Target ambulatory surgical center networks in United States tertiary care regions where dressing change interval reduction drives formulary preference. Pursue CDSCO bioequivalence filings first to establish manufacturing credibility before EMA and FDA dossier submissions. For Investors and Strategic Acquirers: Consolidation pressure builds where analytical testing scale advantages intersect with tightening regulatory thresholds for sulfonamide-derived actives. Five-to-ten-year viability favors acquisition of regional specialists with validated gel formulation capabilities and hospital GPO contract relationships. Monitor antimicrobial stewardship protocol adoption rates as inflection signal for empirical prophylaxis restriction severity.| Strategic Initiative | Industry Significance |
|---|---|
| USP Sterility Testing Infrastructure Expansion | FDA batch release compliance secures hospital procurement contracts against quality-barred competitors. |
| Hydrogel Formulation Development | Seventy-two-hour release profiles capture outpatient protocol share from traditional cream configurations. |
| Single-Use Sachet Packaging Launch | Unit-dose configurations align with infection control priorities in United States burn center accreditation. |
| Silver Salt Supply Integration | Captive refining or long-term offtake buffers margin compression from precious metal commodity volatility. |
| CDSCO Bioequivalence Pathway Execution | Accelerated Indian approval enables export manufacturing credibility for regulated market dossier filings. |
Research Methodology
Multiple input streams — regulatory filing databases, hospital procurement contract records, and precious metal commodity tracking — were reconciled through structured primary interviews with formulation development executives, regulatory affairs leads, hospital procurement managers, and GPO contracts specialists. Secondary validation drew from FDA antimicrobial guidance documents, EMA quality guidelines for topical antibiotics, USP compendial monographs, and CDSCO New Drugs and Clinical Trials Rules. Bottom-up volume modeling across cream, gel, ointment, powder, and spray configurations was cross-referenced against top-down market sizing from manufacturer distribution disclosures.
Historical shipment patterns were cross-referenced against panel input from burn center pharmacy directors and wound care protocol committees to establish baseline demand trajectories. Segmentation modeling incorporated product form, application type, end user setting, and distribution channel dimensions alongside regional regulatory cluster differentiation. CAGRs were derived from regression analysis of volume trends against hospital burn center expansion rates and antimicrobial stewardship protocol adoption curves. Forecast inputs included silver price volatility scenarios and USP sterility testing timeline elasticity assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FDA purity threshold evolution, EMA impurity profiling requirement expansion, and silver commodity price regime shifts. Forecasts reflect documented assumptions regarding hospital procurement consolidation velocity and gel formulation preference acceleration. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pharmaceutical Ingredients
Antipyretic Analgesic Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Antibiotics API Market
Pharmaceutical Ingredients
Albumin (As Excipient) Market
Pharmaceutical Ingredients
Saudi Arabia Active Pharmaceutical Ingredients (API) Market
Pharmaceutical Ingredients
Immunosuppressants Market
Pharmaceutical Ingredients
Pharmaceutical Fine Chemicals Market
Pharmaceutical Ingredients
Diclofenac Sodium API Market
Pharmaceutical Ingredients
North America Active Pharmaceutical Ingredients Market
Pharmaceutical Ingredients
Taxifolin Market
Pharmaceutical Ingredients
Pharmaceutical Desiccants Market
Pharmaceutical Ingredients
Large Molecule Drug Substance CDMO Market
Pharmaceutical Ingredients
Global Pharmaceutical Excipients Market
Pharmaceutical Ingredients
Oxycodone Drugs Market
Pharmaceutical Ingredients
Quinoline Market
Pharmaceutical Ingredients
Small-Molecule Injectable Drugs Market
Pharmaceutical Ingredients
Hyaluronic Acid Raw Material Market