
 Dead Sea Mineral Market | 2026-2036
Dead Sea Mineral Market Size, Share, and Industry Trends Forecast 2026-2036
Dead Sea Mineral Market Insights
Biomimetic extraction technology is narrowing the gap between artisanal harvesting and industrial-scale output, enabling consistent mineral concentrations across batches. AHAVA Dead Sea Laboratories leverages direct shoreline extraction rights to control raw material quality from source to formulation. Dead Sea Works sustains one of the world's largest solar evaporation operations, supplying bulk potassium chloride and bromine to industrial buyers across three continents. Seacret specializes in direct-to-consumer channel control, bypassing traditional retail markups through kiosk networks and subscription models.
Dead Sea minerals comprise evaporite deposits rich in magnesium, potassium, calcium, sodium, and bromine ions, typically harvested through solar evaporation ponds followed by fractional crystallization to separate individual salts. These minerals serve therapeutic and cosmetic functions primarily through osmotic skin interaction and trace-element supplementation in topical formulations. Cosmetics applications dominate value capture due to premium pricing of mud masks and salt scrubs, while therapeutics segments show faster volume growth driven by psoriasis clinic protocols and rheumatology spa prescriptions. Bulk bags remain the packaging standard for ingredient suppliers, though glass jars command higher margins in finished-goods channels targeting luxury consumers.
Israel's Ministry of Health and Jordan's Food and Drug Administration enforce divergent cosmetic labeling standards, creating compliance complexity for cross-border mineral processors. REACH registration requirements in Europe restrict bromine compound imports unless full toxicological dossiers accompany shipments, favoring established exporters with regulatory affairs capacity. Stakeholders must monitor evolving extraction quotas under the Dead Sea Basin multinational water agreements, as mineral yield directly ties to permitted evaporation surface area.
Market Dynamics
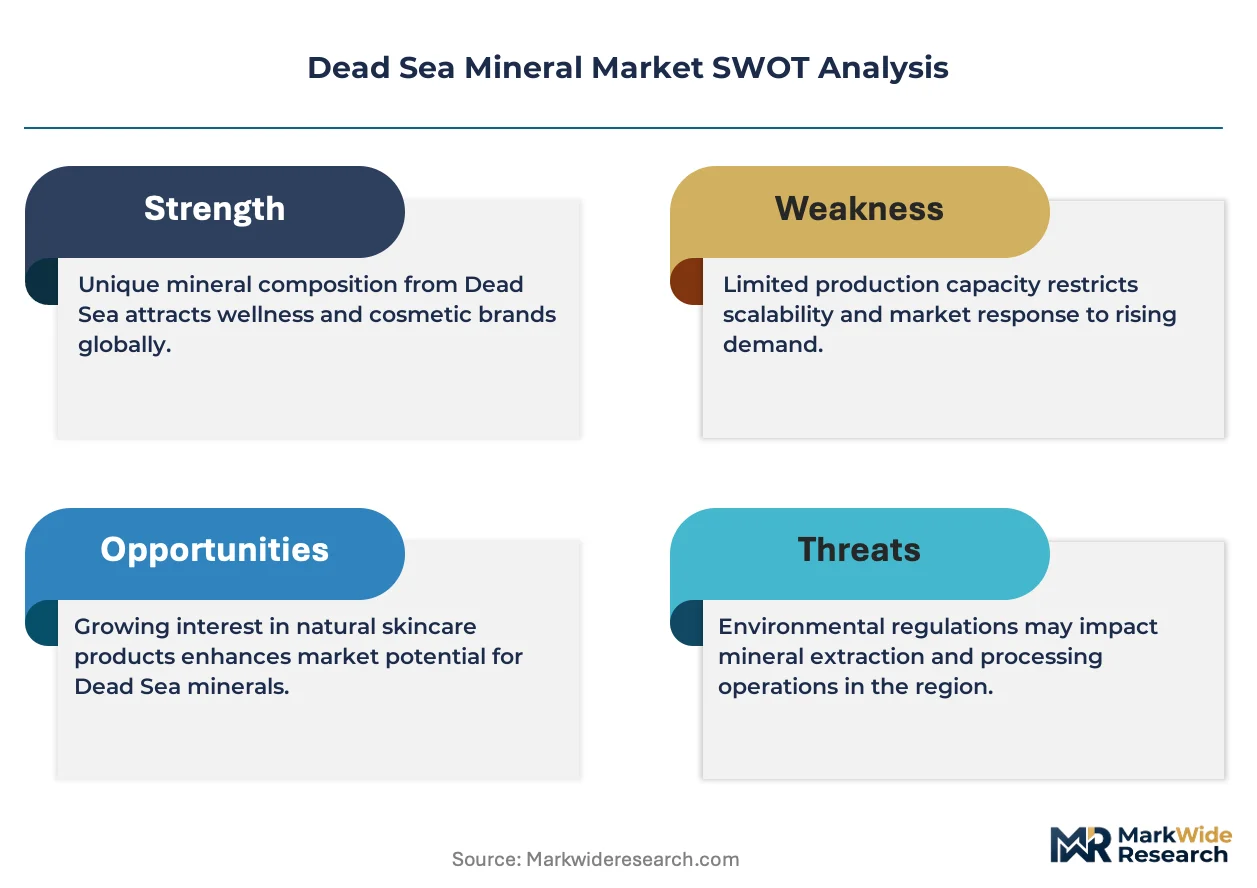
Extraction quota negotiations under the Dead Sea Basin multinational water agreements are compressing permitted evaporation surface area, directly constraining mineral yield and forcing processors toward efficiency technologies.
Growth Catalysts
- Cosmetic ingredient disclosure mandates:Israel's Ministry of Health tightened labeling rules, pushing brands toward verified mineral sourcing that rewards established Dead Sea processors with compliance infrastructure already in place.
- Psoriasis clinic protocols:Dermatology spa prescriptions for Dead Sea mud therapy are expanding patient volume through rheumatology networks in Germany and France.
- Solar evaporation optimization:Biomimetic extraction technology is narrowing batch-to-batch mineral concentration variance, enabling cosmetic formulators to standardize product efficacy claims.
Market Restraints
- Evaporation surface quotas:Dead Sea Basin water agreements cap permitted pond area, hard-limiting potassium chloride and bromine yield regardless of price signals.
- REACH registration barriers:ECHA toxicological dossier requirements for bromine compounds block new European entrants, entrenching Dead Sea Works and established exporters with regulatory affairs capacity.
- Halite substitution in de-icing:Rock salt from Utah and Chilean caliche deposits undercuts Dead Sea sodium chloride on freight costs for North American road maintenance contracts.
Strategic Opportunities
- Subscription direct-to-consumer channels:Kiosk networks bypassing traditional retail markups are capturing margin expansion in mud mask and salt scrub segments.
- EU Green Deal chemical sustainability criteria:Solar-evaporated mineral certification aligns with CSRD scope 3 reporting requirements for cosmetic brand supply chains.
- API-grade magnesium chloride:Pharmaceutical compounding standards for injectable solutions open premium pricing tiers beyond cosmetic applications.
Industry Challenges
- Fractional crystallization technician shortage:Solar pond management and selective precipitation expertise concentrates among retiring operators at Sodom and Ein Gedi facilities.
- Cross-border labeling divergence:Israel's Ministry of Health and Jordan's Food and Drug Administration enforce incompatible cosmetic disclosure formats, forcing dual packaging runs for shoreline processors serving both markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dead Sea Mineral Market |
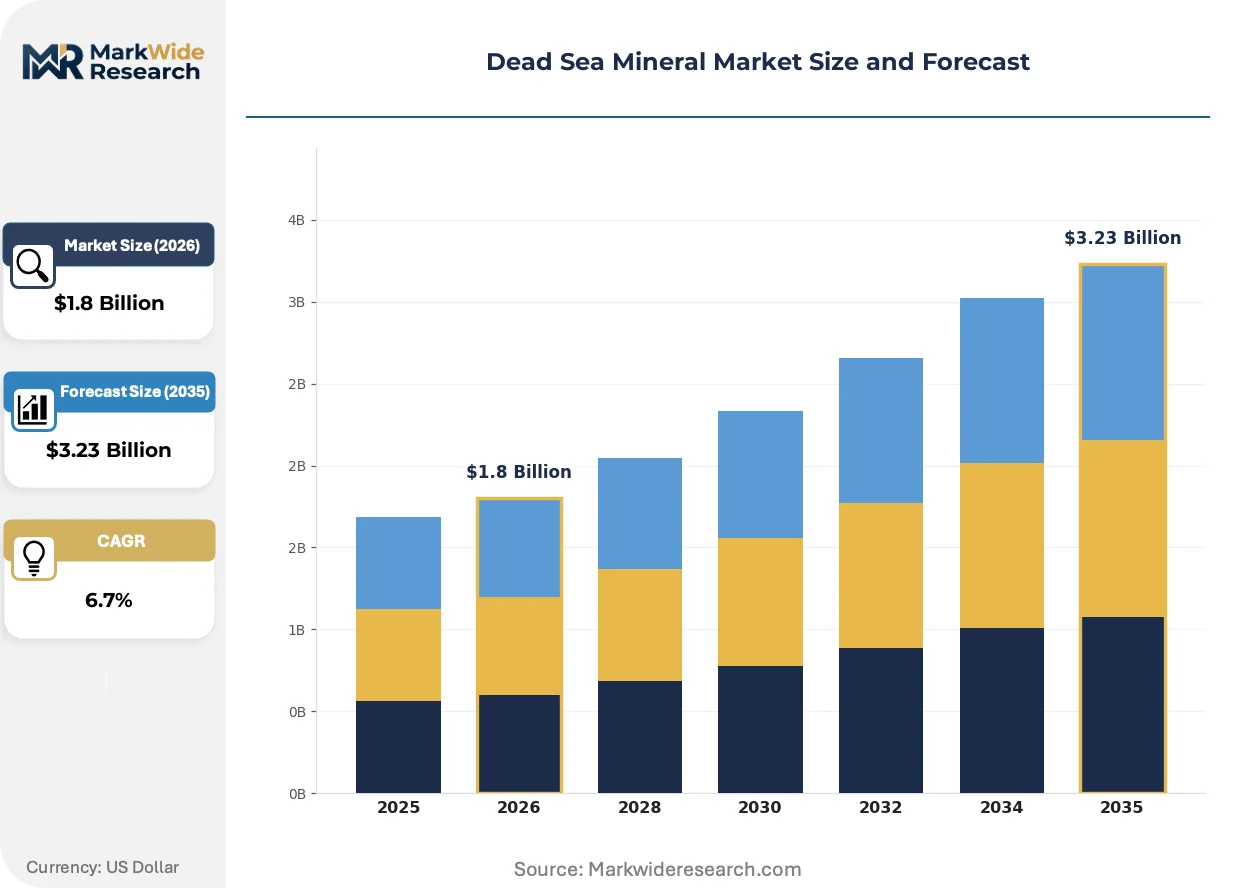
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Potassium Chloride, Magnesium Sulfate, Calcium Bromide, Sodium Chloride, Bromine Application: Cosmetics, Therapeutics, Spa Treatments, Personal Care, Dietary Supplements End User: Skin Care Brands, Wellness Centers, Pharmaceutical Firms, Nutraceutical Companies, Beauty Salons Packaging Type: Bulk Bags, Plastic Containers, Glass Jars, Sachets, Drum Barrels |
| Companies Covered | AHAVA Dead Sea Laboratories, Dead Sea Works, Aroma Dead Sea Spa and Cosmetics, Kawar Cosmetics, H&B Health and Beauty, Seacret, Premier Dead Sea, Biscol Investments, AVANI Supreme, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dead Sea Mineral Market Trends and Innovations
Biomimetic processing and regulatory disclosure mandates are compressing artisanal-mining margins while rewarding integrated extraction-to-formulation operators with quality-verification premiums.
Membrane filtration pre-concentration is collapsing the yield gap between artisanal harvesting and industrial-scale solar evaporation. Cosmetic formulators in France and Germany are adopting this hybrid approach to secure consistent magnesium-to-potassium ratios. The technology is collapsing minimum viable scale thresholds, enabling mid-tier brands to bypass bulk commodity markets and negotiate direct shoreline offtake agreements.
REACH authorization requirements for bromine compounds are tightening toxicological scrutiny on Dead Sea-derived inputs entering European cosmetic and pharmaceutical supply chains. ECHA's expanded substance evaluation program now demands full exposure scenario documentation for dermal applications. German and Dutch formulators are responding by segregating bromine-free mineral lines for EU distribution while maintaining standard formulations for Middle Eastern markets.
Certification-driven procurement now dominates premium cosmetic sourcing decisions, with ISO 16128 natural origin criteria and BDIH organic certification displacing price-based supplier selection. Brand R&D teams in Milan and Paris are rewriting technical specifications to mandate third-party mineral provenance verification. This shift is most visible in prestige mud mask launches where packaging now features QR-linked extraction coordinates rather than generic Dead Sea origin claims.
Dead Sea Mineral Market Segmentation
Dead Sea mineral processors navigate divergent demand cycles across product categories. Cosmetic formulations turn inventory rapidly while industrial bulk salts move through annual contracting rhythms. Understanding these temporal patterns shapes working capital allocation and extraction scheduling.
Product Type:
Potassium chloride and bromine rotate through inventory fastest due to continuous industrial offtake, whereas specialty magnesium salts sit longer in cosmetic ingredient pipelines. Solar evaporation batch timing directly governs which mineral dominates processor revenue in any given quarter.
- Potassium Chloride:Standard-grade KCl crystals serve fertilizer compounders and oilfield drilling fluid manufacturers. Dead Sea Works ships bulk quantities to Brazilian agribusiness buyers through long-term supply agreements tied to seasonal planting windows.
- Magnesium Sulfate:Epsom salt grades command premium pricing in therapeutic soaking applications. German dermatology clinics prescribe Dead Sea-derived magnesium sulfate for atopic eczema protocols, creating stable demand through reimbursement frameworks.
- Calcium Bromide:Clear-brine completion fluids for oil and gas drilling dominate offtake. Texas and Oklahoma shale operators specify calcium bromide density ranges for well control.
- Sodium Chloride:Halite fractions compete with rock salt in de-icing markets. Jordanian processors undercut Chilean caliche on Middle East regional freight.
- Bromine:Elemental bromine and organobromine intermediates feed flame retardant and pharmaceutical synthesis chains. REACH registration requirements restrict European market entry to established Israeli exporters.
Potassium chloride dominates installed base. Bromine is where expansion concentrates.
Application:
Cosmetic applications capture margin premiums through branded ingredient stories, while therapeutics segments expand volume through clinic reimbursement codes. Spa treatments occupy the middle ground with seasonal demand peaks.
- Cosmetics:Mud masks and salt scrubs leverage mineral origin claims for pricing power. French and Italian formulators specify magnesium-to-potassium ratios in technical agreements with Dead Sea processors.
- Therapeutics:Psoriasis balneotherapy protocols at Ein Gedi and Jordanian shore clinics drive patient volume. German rheumatology networks refer patients to Dead Sea facilities under statutory health insurance coverage.
- Spa Treatments:Wellness resorts incorporate mineral mud wraps and flotation therapy. Dubai and Abu Dhabi hotel spas source bulk salts for treatment room operations.
- Personal Care:Bath salts and body lotions distribute through retail and direct-to-consumer channels. Seacret kiosk networks bypass traditional wholesale markups.
- Dietary Supplements:Magnesium and potassium tablets target mineral deficiency markets. Nutraceutical brands require heavy metal testing certificates exceeding cosmetic-grade standards.
Therapeutics commands the steepest expansion trajectory. Cosmetics retains the widest margin spread.
End User:
Skin care brands rotate formulations seasonally, whereas pharmaceutical firms lock in multi-year mineral supply contracts with audit requirements. Wellness centers fall between these extremes with annual membership-driven purchasing.
- Skin Care Brands:AHAVA and competing formulators specify harvest coordinates for marketing claims. ISO 16128 natural origin certification now gates supplier qualification.
- Wellness Centers:Destination spas and day spas purchase bulk mud and salt for treatment protocols. German medical spa operators require GMP-adjacent documentation.
- Pharmaceutical Firms:API-grade magnesium chloride for injectable solutions demands pharmacopeia compliance. Compounding pharmacies in Switzerland and Germany specify monograph purity levels.
- Nutraceutical Companies:Mineral supplement manufacturers source food-grade salts. US FDA facility registration requirements add compliance overhead for Israeli exporters.
- Beauty Salons:Independent operators purchase smaller sachet and jar quantities. Regional distributors in France and Italy aggregate salon demand.
Skin care brands dominate installed base. Pharmaceutical firms concentrate where premium pricing opens.
Packaging Type:
Bulk bags turn fastest through industrial channels while glass jars sit in cosmetic inventory awaiting seasonal promotional cycles. Drum barrels occupy intermediate velocity serving mid-scale processors.
- Bulk Bags:One-ton flexible intermediate bulk containers serve potassium chloride and sodium chloride shipments. Dead Sea Works loads bulk bags directly at Sodom evaporation ponds for export.
- Plastic Containers:Polypropylene jars and tubs package cosmetic mud and salt scrubs. Italian packaging converters supply Dead Sea processors with custom-molded containers.
- Glass Jars:Premium cosmetic positioning demands amber and clear glass with silk-screened origin branding. French perfumery packaging houses provide finishing services.
- Sachets:Single-use packets serve hotel amenity and travel retail channels. UAE hospitality procurement specifies sachet dimensions for in-room presentation.
- Drum Barrels:Steel and fiber drums contain liquid bromine and brine concentrates. UN-certified drum specifications govern hazardous material ocean freight.
Bulk bags dominate installed base. Glass jars concentrate where margin expansion matters most.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Israel exports processed Dead Sea minerals to German dermatology clinics and French cosmetic formulators, while Jordanian processors supply bulk salts to UAE wellness resorts and Saudi spa operators.
Israel
German rheumatology networks refer psoriasis patients to Ein Gedi clinics under statutory health insurance coverage. Israel's Ministry of Health tightened cosmetic ingredient disclosure rules in 2023, mandating harvest coordinate verification for mineral origin claims. The Sodom evaporation pond complex sustains the world's largest solar mineral extraction operation.
Jordan
UAE hospitality procurement teams source bulk Dead Sea mud for Dubai hotel spa operations. Jordan's Food and Drug Administration enforces cosmetic labeling standards that diverge from Israeli requirements, forcing dual packaging runs for cross-border processors. The Dead Sea shoreline industrial zone near Sweimeh concentrates extraction and primary processing infrastructure.
Germany
German dermatology clinics prescribe Dead Sea balneotherapy protocols reimbursed through statutory health insurance frameworks. ECHA REACH registration requirements restrict bromine compound imports unless full toxicological dossiers accompany shipments. Cologne and Düsseldorf formulators specify magnesium-to-potassium ratios in technical agreements with Israeli suppliers.
United States
Texas and Oklahoma shale operators specify calcium bromide density ranges for oilfield completion fluids. US FDA facility registration requirements add compliance overhead for Israeli nutraceutical exporters seeking food-grade mineral certification. Houston petrochemical distributors aggregate Dead Sea bromine offtake for regional drilling contractors.
France
French perfumery packaging houses provide amber glass finishing services for premium cosmetic mud masks. ANSM cosmetic safety regulations require full exposure scenario documentation for dermal applications of bromine-containing formulations. Paris-based formulators are segregating bromine-free mineral lines for EU distribution while maintaining standard formulations for Middle Eastern markets.
Dead Sea Mineral Market Competitive Landscape
On the supply side, the industry is bifurcated between integrated extraction-to-formulation operators and commodity bulk processors serving industrial buyers. Shoreline extraction rights concentrate among entities with decades-long government concessions. Three archetypes dominate: vertically integrated cosmetic brands, solar evaporation bulk commodity suppliers, and direct-to-consumer channel specialists. Competitive moves center on regulatory compliance infrastructure investment and membrane filtration technology licensing.
Within the integrated extraction-to-formulation tier, AHAVA Dead Sea Laboratories and Dead Sea Works exemplify divergent strategic positions. AHAVA occupies the premium cosmetic archetype through direct shoreline extraction rights that enable harvest coordinate verification for marketing claims. Dead Sea Works represents the industrial-scale commodity vector, anchoring bulk potassium chloride and bromine supply to agribusiness and petrochemical buyers across three continents. Seacret sits within the direct-to-consumer channel control archetype, bypassing traditional retail markups through captive kiosk networks and subscription models.
| Leading Market Players |
|---|
| AHAVA Dead Sea Laboratories |
| Dead Sea Works |
| Aroma Dead Sea Spa and Cosmetics |
| Kawar Cosmetics |
| H&B Health and Beauty |
| Seacret |
| Premier Dead Sea |
| Biscol Investments |
| AVANI Supreme |
| Others |
Pricing and Supply Chain Analysis
The Sodom evaporation pond complex anchors global Dead Sea mineral capacity, and its solar evaporation batch timing directly governs quarterly pricing power for potassium chloride and bromine offtake contracts.
Pricing Analysis
Biomimetic extraction technology versus legacy solar pond methods versus membrane filtration pre-concentration creates a three-tier pricing structure across premium, standard, and economy levels. Certification grade and volume scale drive price differentiation, with ISO 16128-verified mineral lines commanding substantial premiums over uncertified bulk salts. Pricing pressure stems from halite substitution in North American de-icing markets, where Utah rock salt undercuts Dead Sea sodium chloride on freight economics. Industrial fertilizer compounders exhibit highest price sensitivity, while French cosmetic formulators show lowest sensitivity due to origin-story marketing requirements.
Supply Chain Analysis
REACH authorization requirements for bromine compounds restrict European mineral flows to established Israeli exporters with full ECHA toxicological dossiers. Supply concentrates in Israel and Jordan, with extraction rights clustering along the Dead Sea shoreline at Sodom and Sweimeh industrial zones. The supply chain draws from solar evaporation ponds, fractional crystallization facilities, and membrane filtration pre-concentration units. Single-source vulnerability runs through shoreline extraction concessions controlled by decades-long government agreements. Distribution runs through bulk bag shipments for industrial buyers, glass jar finishing through French packaging houses for cosmetic channels, and kiosk networks for direct-to-consumer segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dead Sea mineral demand is accelerating through regulatory disclosure mandates that reward verified sourcing infrastructure. Israel's Ministry of Health tightened cosmetic ingredient rules, creating a compliance moat for established processors.
For Market Incumbents: Build regulatory compliance infrastructure as a defensive moat. Invest in ISO 16128 certification capacity to capture premium pricing from French and Italian formulators. Expand membrane filtration licensing to counter artisanal-harvester competition. Threat substitution from synthetic mineral alternatives demands proactive harvest coordinate verification systems.
For New Entrants and Emerging Players: German dermatology clinic networks present underpenetrated white-space for API-grade magnesium chloride supply. Target pharmaceutical compounding pharmacies in Switzerland with pharmacopeia-compliant mineral lines. Seize subscription direct-to-consumer channels bypassing traditional retail markups through captive kiosk networks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated extraction-to-formulation operators with shoreline concession security. Long-term viability hinges on extraction quota stability under Dead Sea Basin multinational water agreements. Acquisition targets should demonstrate regulatory affairs capacity for REACH registration and ECHA compliance. Watch for membrane filtration technology licensing deals as inflection indicators of competitive positioning shifts.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shoreline Extraction | AHAVA's direct concession control enables harvest coordinate verification for marketing claims. |
| Membrane Filtration Technology Licensing | Biomimetic pre-concentration collapses minimum viable scale thresholds for mid-tier cosmetic brands. |
| ISO 16128 Certification Investment | Natural origin verification gates supplier qualification for Milan and Paris formulators. |
| Direct-to-Consumer Channel Expansion | Seacret's kiosk networks bypass traditional retail markups in mud mask and salt scrub segments. |
| API-Grade Pharmaceutical Compliance | Injectable magnesium chloride standards open premium pricing tiers beyond cosmetic applications. |
Research Methodology
A spread of perspectives from solar pond operations managers, cosmetic formulator procurement leads, Dead Sea basin regulatory affairs directors, and German dermatology clinic administrators converged on the working assumptions. Primary interviews combined with secondary validation from Jordan Food and Drug Administration filings, Israel Ministry of Health disclosure mandates, ECHA REACH registration databases, and customs trade data. Bottom-up mineral volume modeling triangulated against top-down market value estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include mineral product type, application category, end-user industry, and packaging format. CAGRs derived from historical extraction quota trajectories, solar evaporation yield coefficients, and cosmetic formulation adoption curves. Industry-specific inputs incorporated psoriasis clinic referral volumes through German statutory health insurance frameworks and membrane filtration technology penetration rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by synthetic mineral substitute developers or sudden extraction quota reductions under Dead Sea Basin agreements would shift outcomes. Material shifts in ECHA bromine compound authorization timelines or Israel-Jordan cross-border labeling harmonization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Californium Market
Metals & Minerals
Cobalt Carbonate Market
Metals & Minerals
Gregoryite Market
Metals & Minerals
Steel Powder Market
Metals & Minerals
Ilmenite Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Andalusite Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
North America and EMEA Ferrosilicon Market
Metals & Minerals
Iron Ore Pellets Market
Metals & Minerals
Metal and Metal Ores Market
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Global Fabricated Metal Products Market
Metals & Minerals
Zellerite Market
Metals & Minerals
Boron Ore Market