
 Colloidal Silver Market | 2026-2036
Colloidal Silver Market Size, Share, and Industry Trends Forecast 2026-2036
Colloidal Silver Market Analysis
North American colloidal silver production capacity is realigning toward pharmaceutical-grade output. Natural Immunogenics leverages its Health Canada approvals to anchor premium positioning in cross-border distribution. American Biotech Labs sustains R&D intensity through dedicated antimicrobial formulation labs in Utah. Sovereign Silver competes on retail shelf presence with broad pharmacy channel control across the United States and Canada.
Colloidal silver consists of nanoscale silver particles suspended in purified water, typically at concentrations between 10 and 500 parts per million, functioning as a broad-spectrum antimicrobial agent in topical and oral applications. The liquid product type dominates volume sales through pharmacy and homecare channels, while gel and spray formats command margin premiums in hospital wound care protocols. Medical devices and wound care applications lead value generation, whereas dietary supplement positioning faces tighter regulatory scrutiny that constrains marketing claims and distribution expansion.
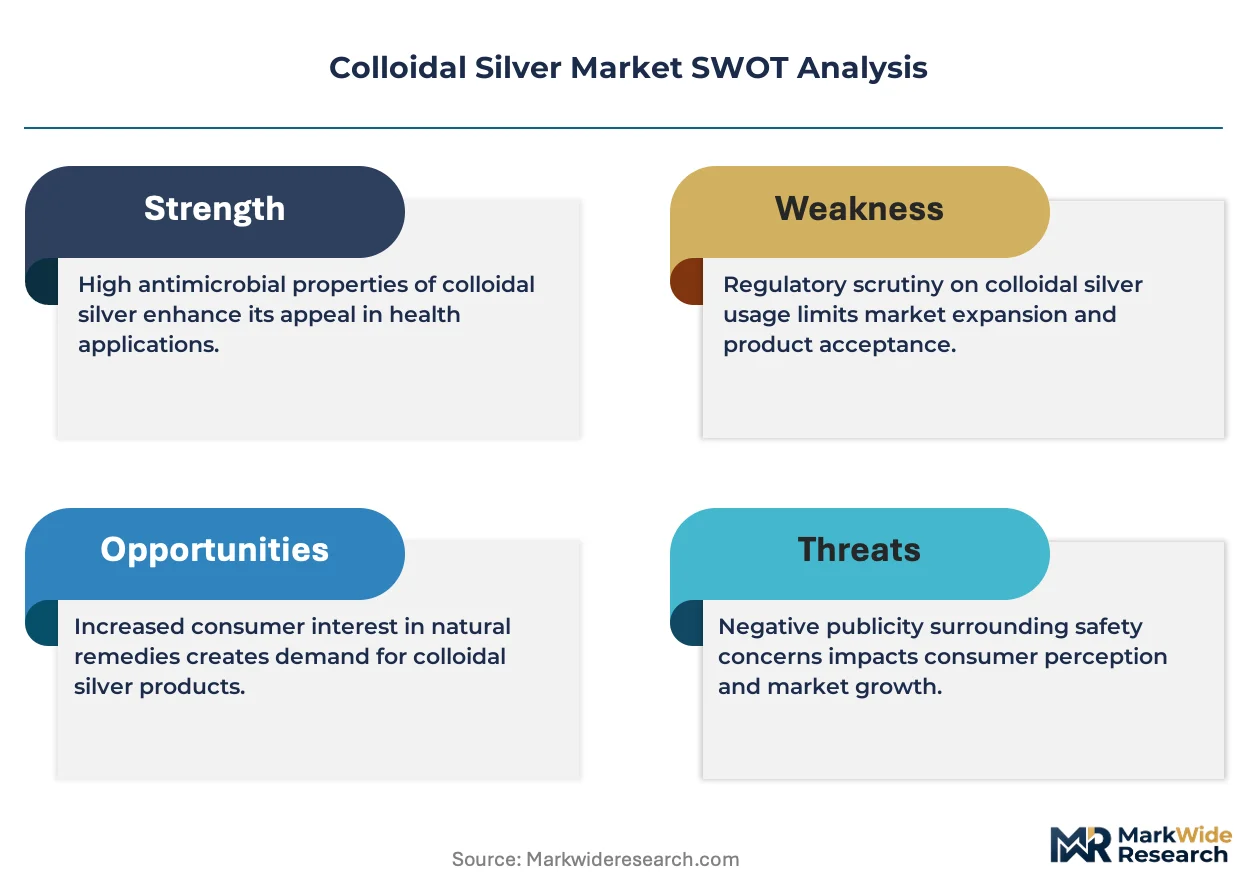
The FDA regulates colloidal silver products sold as dietary supplements under DSHEA while reserving drug approval pathways for antimicrobial medical claims, and Health Canada requires Natural Product Number licensing for all silver-containing natural health products. These frameworks shape demand by bifurcating the market between compliant medical-grade suppliers and restricted consumer wellness channels. Stakeholders must monitor enforcement intensity around antimicrobial claim language to determine whether product development resources shift toward device-class regulatory pathways or retreat to cosmetic and general wellness positioning.
Market Dynamics
The FDA's tightening purity mandates for dietary supplements containing colloidal silver are bifurcating production capacity toward pharmaceutical-grade compliance, forcing manufacturers to choose between medical device pathways and restricted wellness positioning.
Growth Catalysts
- German hospital procurement:Healthcare facilities in Germany are expanding silver-based wound dressing adoption through centralized medical device tenders, creating volume anchors for compliant suppliers.
- DSHEA regulatory clarity:The FDA's framework distinction between drug and supplement pathways allows medical-grade producers to capture antimicrobial claim premiums while restricting competitors.
- Electrolytic production methods:Advanced electrolysis systems producing sub-20 nanometer particle sizes are displacing older chemical reduction processes in premium manufacturing.
Market Restraints
- Silver price volatility:London Bullion Market Association silver spot fluctuations compress margin predictability for producers lacking forward purchase agreements.
- Health Canada NPN backlog:Natural Product Number licensing delays of 12-18 months constrain new entrant speed-to-market for oral supplement formats.
- Antibiotic stewardship substitution:Hospital infection control committees increasingly prioritize systemic antibiotics over topical silver for deep tissue infections.
Strategic Opportunities
- Veterinary wound care:Companion animal clinics in the United States represent an underpenetrated channel with lower regulatory barriers than human medical devices.
- Cosmetic antimicrobial positioning:Skin care formulators are integrating colloidal silver into preservative-free product lines, bypassing drug classification entirely.
- ISO 13485 certification:Medical device quality management system adoption opens EU MDR conformity assessment pathways for wound dressing manufacturers.
Industry Challenges
- Nanoparticle characterization expertise:Transmission electron microscopy and dynamic light scattering competency gaps constrain in-house quality assurance scale-up.
- 510(k) predicate navigation:FDA substantial equivalence determinations for novel silver concentrations require extensive clinical literature synthesis and predicate device analysis.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colloidal Silver Market |
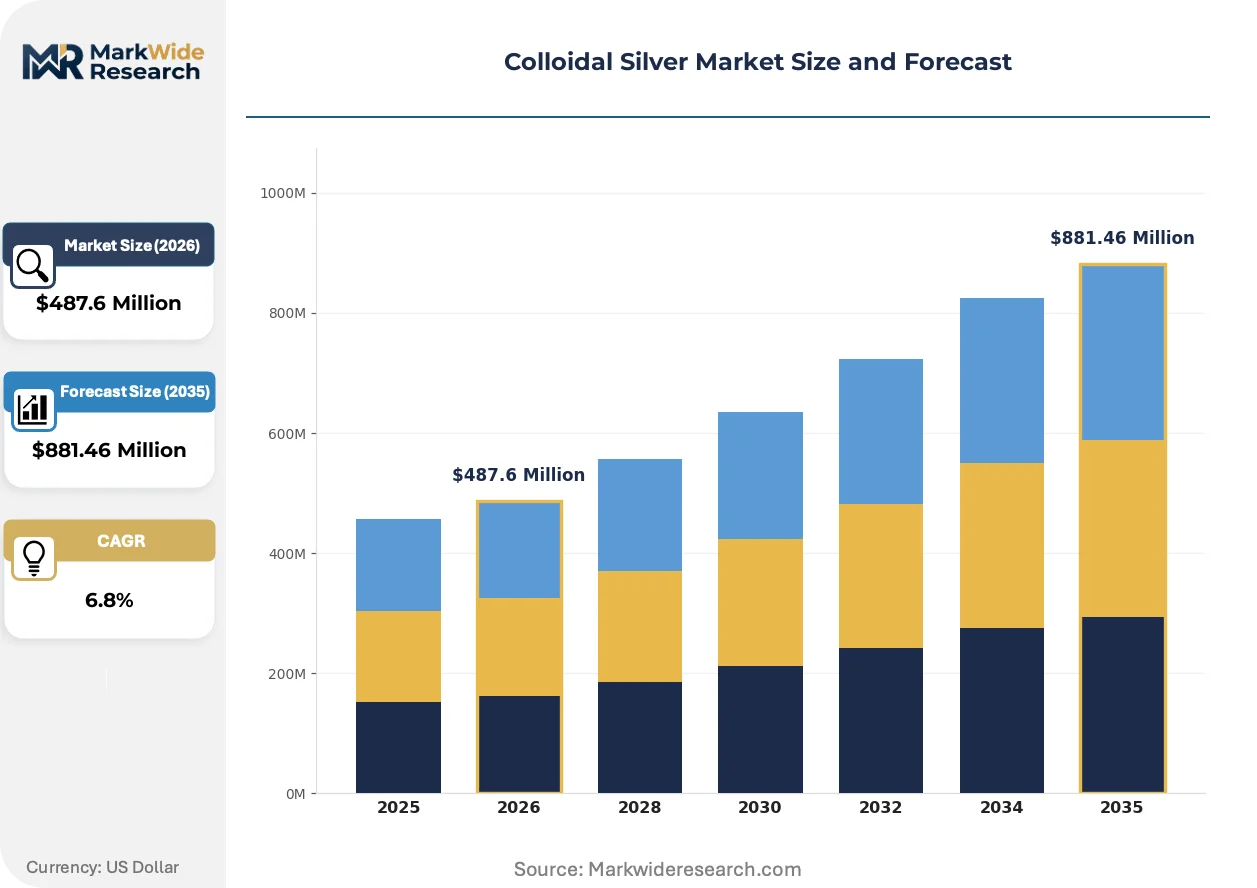
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid, Gel, Spray, Cream Application: Wound Care, Skin Treatment, Dietary Supplement, Medical Devices End User: Hospitals, Clinics, Homecare, Pharmacies Distribution Channel: Online, Retail, Direct Sales, Distributors |
| Companies Covered | Natural Immunogenics, American Biotech Labs, Sovereign Silver, Colloidal Science Laboratory, Purest Colloids, MesoSilver, Silver Biotics, Heritage Store, Silver Wings, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colloidal Silver Market Emerging Trajectories
Colloidal silver manufacturing is pivoting from commodity wellness positioning toward regulated medical device classification, with particle engineering and purity verification becoming primary competitive differentiators rather than marketing claims.
Low-voltage electrolytic generators producing monodisperse 5-10 nanometer silver particles are overtaking batch chemical reduction methods in premium production facilities. Wound care contract manufacturers in Utah and Ontario are retrofitting cleanroom lines to accommodate these continuous-flow systems. The technology is overtaking legacy equipment investments by enabling real-time particle size monitoring that satisfies FDA process analytical technology guidelines.
REACH nanomaterial registration requirements in Europe are forcing importers to submit full toxicological dossiers for silver particle concentrations above 0.1% by weight. German and French distributors are consolidating supplier bases to those with existing registration numbers, compressing channel diversity. Oral supplement sellers without REACH compliance are retreating to North American e-commerce channels exclusively.
Homecare consumers are migrating from multi-level marketing networks toward pharmacy-shelf verification, demanding third-party assay certificates visible at point-of-purchase. Independent pharmacies in California and Texas are responding with locked-display case positioning and staff training on ppm concentration interpretation. This behavioral shift concentrates volume with retailers capable of sustaining trained personnel rather than automated checkout environments.
Colloidal Silver Market Segmentation
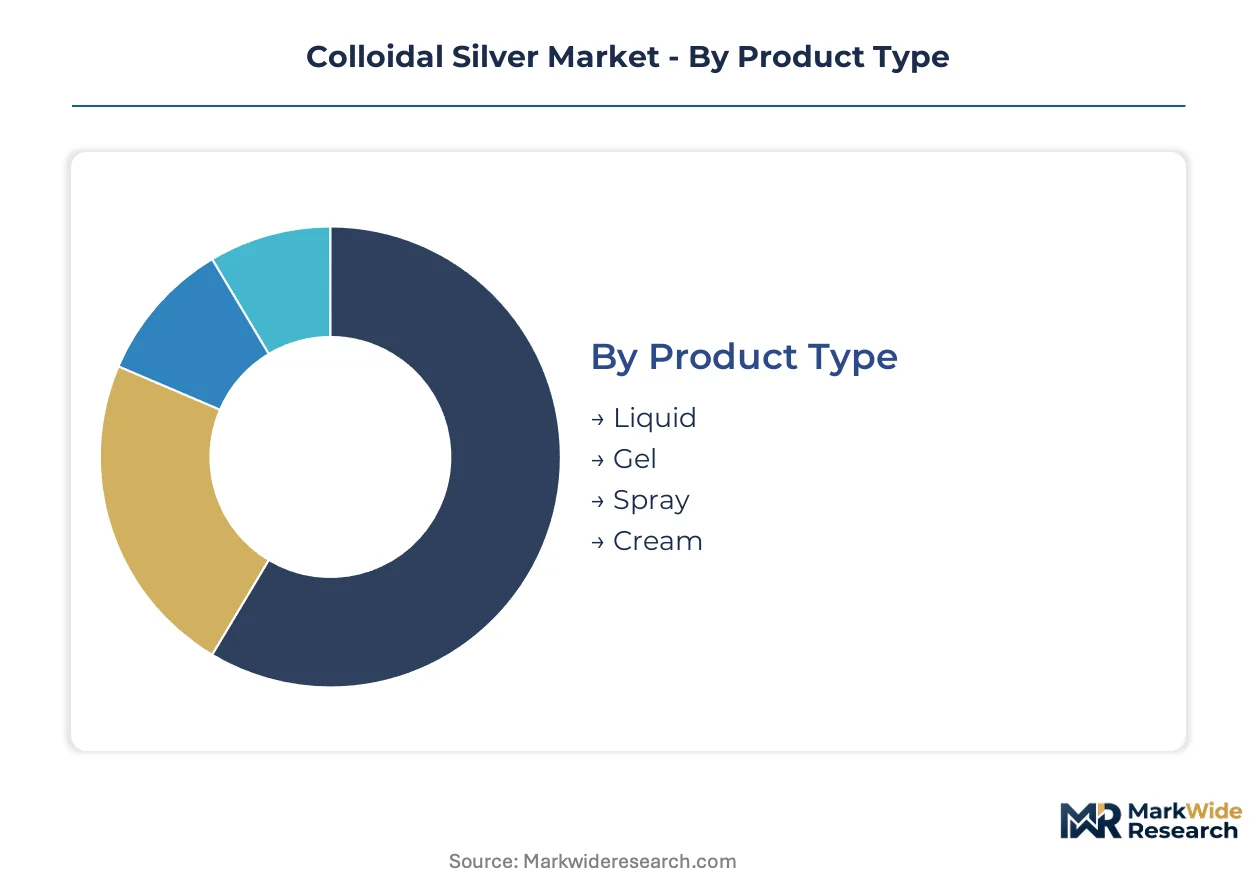
Particle size specifications and formulation chemistry determine regulatory pathway eligibility and pricing power across colloidal silver categories. Manufacturers align production capacity with specific segment purity requirements to avoid cross-contamination between medical device and dietary supplement classifications.
Product Type:
Electrolytic production systems differentiate output quality across liquid, gel, spray, and cream formats, with particle size distribution dictating antimicrobial efficacy claims.
- Liquid:Aqueous suspensions of 10-500 ppm silver concentration dominate pharmacy and homecare volume through oral and topical delivery. German hospital procurement tenders favor liquid formats for irrigation protocols in chronic wound management.
- Gel:Thickened matrices incorporating 20-50 nanometer particles achieve extended skin contact time in burn unit protocols. Margin premiums concentrate in hospital formulary approvals where gel viscosity meets specific wound bed adherence requirements.
- Spray:Atomized delivery systems target large surface area applications in veterinary and athletic settings. Health Canada NPN licensing for spray formats encounters additional inhalation exposure assessment delays.
- Cream:Emulsion-based carriers integrate colloidal silver with lipid phases for cosmetic antimicrobial positioning. REACH nanomaterial registration thresholds apply to cream formulations exceeding 0.1% silver by weight in European distribution.
Liquid leads on scale; gel leads on momentum.
Application:
Regulatory claim boundaries segment demand between device-class antimicrobial positioning and restricted wellness marketing.
- Wound Care:FDA 510(k) predicate navigation dominates value capture through silver-impregnated dressing classifications. ISO 13485 certification opens EU MDR conformity assessment for manufacturers targeting German and French centralized tenders.
- Skin Treatment:Cosmetic preservative-free positioning bypasses drug classification entirely in North American retail channels. California independent pharmacies deploy locked-display positioning with third-party assay certificate verification at point-of-purchase.
- Dietary Supplement:DSHEA framework restricts antimicrobial claim language while permitting general wellness positioning. FDA purity mandate tightening bifurcates production capacity toward pharmaceutical-grade compliance or restricted e-commerce channels.
- Medical Devices:Substantial equivalence determinations require extensive clinical literature synthesis for novel silver concentrations. Utah and Ontario contract manufacturers retrofit cleanroom lines for continuous-flow electrolytic systems satisfying FDA process analytical technology guidelines.
Wound care anchors revenue concentration; skin treatment climbs the fastest.
End User:
Procurement sophistication and regulatory scrutiny intensity vary sharply across institutional and consumer access points.
- Hospitals:Infection control committees prioritize topical silver for superficial wound protocols while substituting systemic antibiotics for deep tissue infections. Centralized medical device tenders in Germany create volume anchors for compliant suppliers.
- Clinics:Companion animal veterinary channels in the United States present underpenetrated demand with lower regulatory barriers than human medical devices. Staff training requirements concentrate volume with retailers sustaining trained personnel.
- Homecare:Consumer migration from multi-level marketing networks toward pharmacy-shelf verification demands visible third-party assay certificates. ppm concentration interpretation competency separates premium positioning from automated checkout environments.
- Pharmacies:Cross-border distribution leverages Health Canada approvals for premium positioning in United States markets. Locked-display case positioning responds to staff training investments in California and Texas.
Homecare dominates unit volume; hospitals command value per transaction.
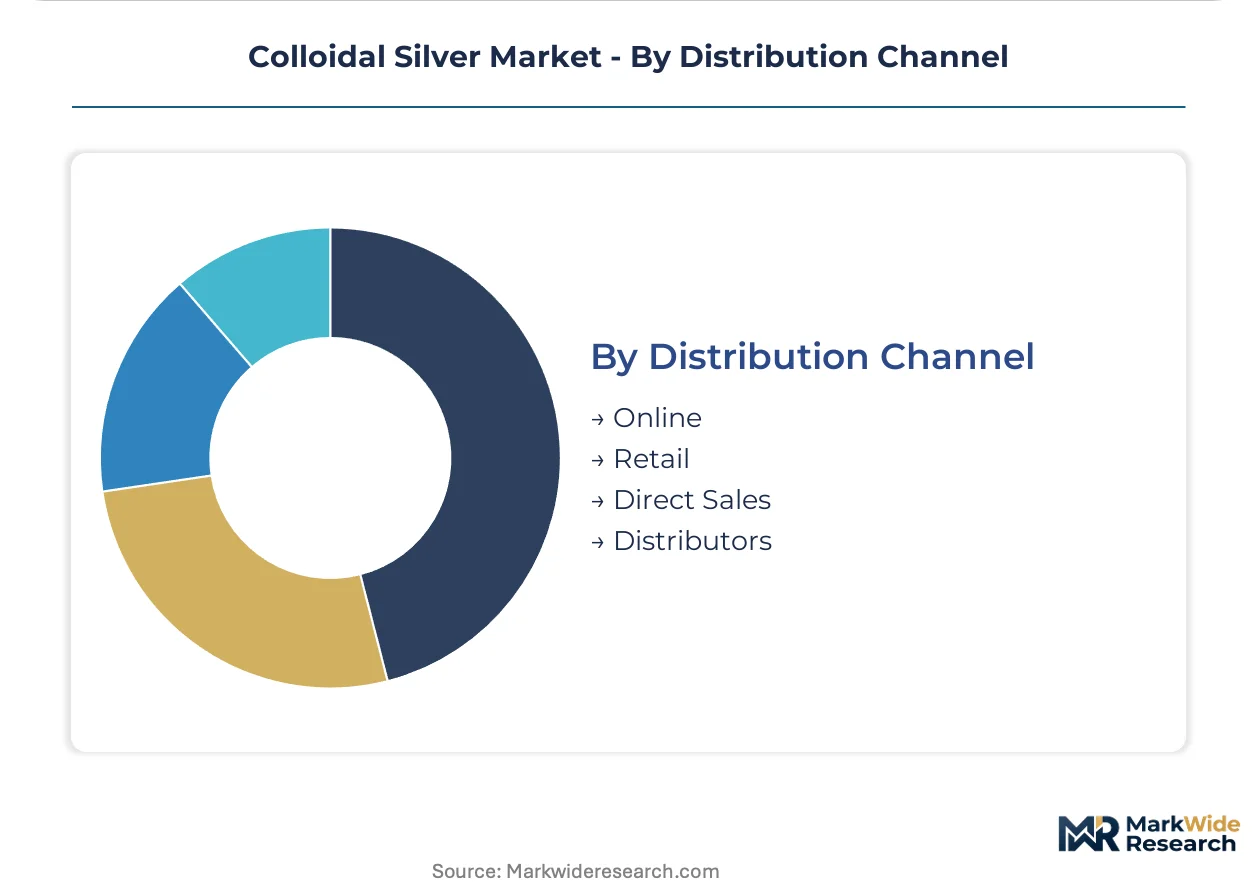
Distribution Channel:
Channel control determines margin capture and regulatory enforcement exposure for antimicrobial claim language.
- Online:E-commerce retreat concentrates oral supplement sellers without REACH compliance in North American channels exclusively. Real-time particle size monitoring documentation satisfies digitally-native consumer verification demands.
- Retail:Pharmacy shelf presence requires broad channel control across United States and Canada for competitive positioning. Staff training on concentration interpretation creates differentiation against automated checkout alternatives.
- Direct Sales:Multi-level marketing network contraction shifts volume toward verified retail environments with assay certificate visibility. Consumer behavioral migration concentrates demand with transparent documentation standards.
- Distributors:German and French consolidation around REACH-registered suppliers compresses channel diversity for importers. Full toxicological dossier submission requirements filter supplier bases to established registration holders.
Retail captures margin premiums; online expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting colloidal silver production toward jurisdictions with streamlined medical device pathways, as manufacturers seek to minimize compliance costs while accessing premium hospital procurement channels.
United States
FDA 510(k) predicate navigation attracts wound care specialists seeking antimicrobial claim authorization, with Utah hosting concentrated electrolytic production facilities serving hospital formulary channels. DSHEA framework distinctions between drug and supplement pathways allow compliant producers to capture premium positioning while restricting competitors to wellness marketing. California independent pharmacies deploy locked-display positioning with staff training on ppm concentration interpretation, concentrating consumer verification demand in trained-retail environments.
Germany
Centralized medical device tenders through university hospital procurement networks create volume anchors for REACH-registered suppliers with ISO 13485 certification. EU MDR conformity assessment requirements filter supplier bases to established registration holders, compressing channel diversity for importers. Bavarian wound care contract manufacturers retrofit cleanroom lines for continuous-flow electrolytic systems, satisfying process analytical technology guidelines for silver-impregnated dressing classifications.
Canada
Health Canada Natural Product Number licensing requirements constrain oral supplement speed-to-market, with 12-18 month approval delays favoring incumbents with existing registration portfolios. Cross-border distribution leverages Health Canada approvals for premium positioning in United States pharmacy channels. Ontario-based producers anchor North American supply for compliant medical-grade output, capitalizing on regulatory recognition downstream.
France
ANSM oversight of nanomaterial-containing products enforces stringent toxicological dossier requirements for silver particle concentrations above registration thresholds. REACH compliance filters distributor supplier bases, consolidating procurement around established registration holders. Paris-region distributors are retreating from oral supplement channels toward medical device classifications, aligning with EU MDR conformity assessment priorities for wound care applications.
Australia
TGA regulation of silver-containing therapeutic goods bifurcates market access between listed medicines and medical device pathways, with wound care classifications commanding premium hospital procurement. Sydney and Melbourne pharmacy chains deploy third-party assay certificate verification at point-of-purchase, responding to consumer migration from direct sales networks toward transparent retail environments. Local contract manufacturers pursue ISO 13485 certification to access EU MDR-aligned export channels.
Colloidal Silver Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue veterinary and cosmetic antimicrobial positioning with lower regulatory barriers. The market structure concentrates around three archetypes: Health Canada-approved suppliers leveraging cross-border premium positioning, Utah-based electrolytic specialists serving hospital formulary channels, and direct-to-consumer brands retreating toward verified retail environments. Dominant competitive moves include ISO 13485 certification pursuit for EU MDR access and cleanroom line retrofitting for continuous-flow production systems.
Within the regulatory-approval tier, Natural Immunogenics and Sovereign Silver exemplify positioning strategies anchored in Health Canada licensing and broad pharmacy channel control respectively. American Biotech Labs occupies the production-technology vector, representing electrolytic specialization through dedicated antimicrobial formulation infrastructure. These three entities illustrate how compliance depth and geographic production clustering determine competitive access to premium hospital and pharmacy procurement channels.
| Leading Market Players |
|---|
| Natural Immunogenics |
| American Biotech Labs |
| Sovereign Silver |
| Colloidal Science Laboratory |
| Purest Colloids |
| MesoSilver |
| Silver Biotics |
| Heritage Store |
| Silver Wings |
| Others |
Supply Flow & Price Mechanics
Captive electrolytic production in Utah and Ontario anchors supply positions for medical-grade colloidal silver, with in-house particle engineering conferring pricing power over contract-manufactured wellness alternatives. This integration choice bifurcates margin capture between FDA 510(k) predicate holders commanding hospital formulary premiums and supplement sellers exposed to silver spot volatility.
Pricing Analysis
Distributor margin layering concentrates value capture with REACH-registered suppliers serving German hospital tenders, while direct-to-consumer channels absorb compressed markups from assay certificate verification costs. Three-tier pricing structure across pharmaceutical-grade, Health Canada-approved, and general wellness levels differentiates by certification tier and particle size documentation. Pricing pressure stems from London Bullion Market Association silver spot fluctuations eroding margin predictability for producers lacking forward purchase agreements. Homecare consumers demonstrate highest price sensitivity, whereas German infection control committees prioritize formulary compliance over unit cost.
Supply Chain Analysis
EU MDR local-content requirements are reshaping sourcing toward ISO 13485-certified contract manufacturers in Bavaria and Ontario with existing registration portfolios. Silver bullion supply concentrates in Mexico, Peru, and Australia as primary mining jurisdictions, with electrolytic production equipment anchored in Germany and Japan. Raw material dependencies span high-purity silver shot, pharmaceutical-grade water systems, and transmission electron microscopy calibration standards. Single-source vulnerability characterizes sub-20 nanometer particle engineering expertise concentrated in Utah facilities. Distribution runs through Health Canada-approved cross-border channels for premium positioning and REACH-registered EU distributors for hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory-arbitrage dynamics position Ontario and Utah production clusters against REACH compliance costs in Europe, with Health Canada approval timelines creating 12-18 month entry barriers that favor incumbent consolidation.
For Market Incumbents: Deepen ISO 13485 certification coverage to capture EU MDR conformity assessment pathways for German wound dressing tenders. Fortify electrolytic production capacity in Utah against silver spot volatility through forward purchase agreements with London Bullion Market Association suppliers. Consolidate pharmacy channel control in California and Texas through locked-display investments that replicate staff training differentiation.
For New Entrants and Emerging Players: Capture companion animal veterinary channels in the United States where regulatory barriers fall below human medical device thresholds. Penetrate cosmetic antimicrobial positioning for preservative-free skin care lines that bypass drug classification entirely. Deploy direct-to-clinic sales models with assay certificate transparency rather than multi-level marketing network structures.
For Investors and Strategic Acquirers: Roll-up economics work for Health Canada NPN portfolio holders because approval backlogs constrain new entrant speed-to-market and create captive revenue streams. Target electrolytic specialists with existing FDA 510(k) predicate navigation capabilities. Watch FDA enforcement intensity around antimicrobial claim language as the inflection signal determining whether development resources shift toward device-class pathways or retreat to cosmetic positioning.
| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Pursuit | Opens EU MDR conformity assessment for German hospital tender participation. |
| Electrolytic Production Scale-Up | Enables real-time particle monitoring satisfying FDA process analytical technology guidelines. |
| REACH Nanomaterial Registration | Filters European distributor supplier bases to established registration holders exclusively. |
| Veterinary Channel Entry | Accesses underpenetrated companion animal clinics with lower regulatory barriers than human devices. |
| Cross-Border Distribution Leverage | Health Canada approvals anchor premium positioning in United States pharmacy channels. |
Methodological Framework
Bottom-up wound care procurement modeling reconciled against top-down electrolytic production capacity tracking forms the analytical core. Primary interviews with hospital infection control committees, GPO contracts managers, biomedical engineers, and Health Canada regulatory affairs specialists combined with secondary validation from FDA 510(k) filings, ECHA REACH registrations, EU MDR conformity assessment databases, and German hospital tender documentation. Triangulation between supply-side facility audits and demand-side formulary analysis ensures segmentation integrity.
Historical trendline analysis of silver-based wound dressing adoption patterns across German university hospital networks informs projection modeling. Segmentation dimensions include product format, regulatory pathway classification, particle size tier, and end-user procurement sophistication. CAGRs derive from elasticity-adjusted volume trajectories calibrated against electrolytic production capacity expansion announcements. Forecast inputs incorporate Health Canada NPN approval velocity and FDA purity mandate enforcement intensity.
Silver price volatility, REACH registration delays, and antibiotic stewardship substitution are the dominant revision risks. Forecasts reflect documented assumptions regarding regulatory pathway bifurcation and hospital procurement centralization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Global Caffeic Acid Market
Specialty Chemicals
Nucleotides Market
Specialty Chemicals
1 - 4 - Cyclohexanedimethanol Dibenzoate Market
Specialty Chemicals
Chevron Seals Market
Specialty Chemicals
Ricinoleic Acid Market
Specialty Chemicals
Vulcanization Accelerators Market
Specialty Chemicals
Free-From Titanium Dioxide Market
Specialty Chemicals
Pyrrolidone Market
Specialty Chemicals
Asia-Pacific Niacinamide Market
Specialty Chemicals
Global Non-Phthalate Plasticizers Market
Specialty Chemicals
Global Benzoyl Peroxide Market
Specialty Chemicals
Cellulose Derivatives Market
Specialty Chemicals
Erucic Acid Market
Specialty Chemicals
Copper (I) Hexafluoroacetylacetonate 1, 5- Cyclooctadiene Market
Specialty Chemicals
Preparative Chromatography Market
Specialty Chemicals
Fatliquoring Agents Market