
 Laminated Steel Market | 2026-2036
Laminated Steel Market Size, Share, and Industry Trends Forecast 2026-2036
Laminated Steel Market Foresight
Chinese integrated steel producers is shifting laminated steel capacity toward thin-gauge electrical grades serving EV traction motor laminations. Tata Steel leverages its European cold-rolling network to sustain premium non-oriented electrical steel supply for automotive Tier-1 stampers. ArcelorMittal anchors Atlantic basin laminated steel flows through its Belgian and Brazilian mills, while Nippon Steel Corporation dominates ultra-thin gauge precision rolling for high-efficiency motor cores.
Laminated steel consists of multiple thin steel sheets bonded through organic or metallic coatings, typically ranging from 0.35 mm to 1.0 mm in finished thickness, engineered to reduce eddy current losses in electromagnetic applications while providing corrosion-resistant surface protection. Cold rolled laminated grades occupy the largest volume share due to dimensional precision requirements in rotating electrical equipment, while galvanized steel laminates are gaining fastest in outdoor electrical infrastructure where salt spray resistance determines procurement specifications. Thin-gauge segments below 0.5 mm concentrate margin pools because stamping yield rates and core loss performance command pricing premiums from motor manufacturers.
EPA emissions standards and OSHA workplace exposure limits govern volatile organic compound releases from coating lines at US laminated steel facilities, while REACH substance restrictions in Europe constrain certain resin-based interlayer chemistries. China's MEE enforces dual carbon compliance thresholds on energy intensity per ton of coated flat steel, pushing producers toward hydrogen-reduced feedstock trials. Stakeholders must monitor how divergent carbon border adjustment mechanisms reshape competitive access across Atlantic and Pacific supply corridors.
Market Dynamics
Thin-gauge electrical steel capacity is concentrating in East Asian manufacturing clusters as automotive OEMs requalify supply chains for EV traction motor laminations, compressing lead times and tightening specification windows for cold-rolled precision grades.
Growth Catalysts
- EV Motor Core Demand:Automotive OEMs are expanding laminated steel procurement for electric motor laminations and battery housings, pulling capacity toward sub-0.5 mm gauge precision grades.
- REACH Compliance:European substance restrictions on resin-based interlayer chemistries are accelerating qualification of alternative coating systems that reduce volatile organic compound emissions.
- Dual Carbon Goals:China's MEE enforcement of energy intensity thresholds per ton of coated flat steel is pushing integrated producers toward hydrogen-reduced feedstock trials.
Market Restraints
- Silicon Steel Input Volatility:Fluctuations in high-grade silicon electrical steel billet costs compress margin pools for cold-rolling operations serving motor core stampers.
- East Asian Supply Concentration:Thin-gauge precision rolling capability clusters around Shanghai and Busan, creating single-source risk for Atlantic basin automotive Tier-1s.
- Amorphous Metal Substitution:Non-crystalline alloy cores are displacing laminated silicon steel in select high-frequency transformer applications.
Strategic Opportunities
- US IRA Manufacturing Credits:Domestic content incentives for clean energy component production are opening qualification pathways for North American laminated steel re-rolling capacity.
- Offshore Wind Infrastructure:Salt-spray resistant galvanized laminates are penetrating marine transformer and subsea cable armoring applications.
- Digital Coil Tracking:Blockchain-enabled provenance verification is emerging as a procurement differentiator for automotive OEMs auditing Scope 3 emissions.
Industry Challenges
- Precision Rolling Skill Gap:Ultra-thin gauge rolling mill operators with sub-10 micrometer thickness tolerance expertise are scarce across Atlantic basin facilities.
- Interlayer Adhesion Certification:Multi-year qualification timelines for new organic coating chemistries delay product launches for REACH-compliant European supply.
- Legacy Stamping Equipment Retrofit:Tier-1 motor core stampers face capital intensity upgrading progressive die systems for thinner, harder electrical steel grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laminated Steel Market |
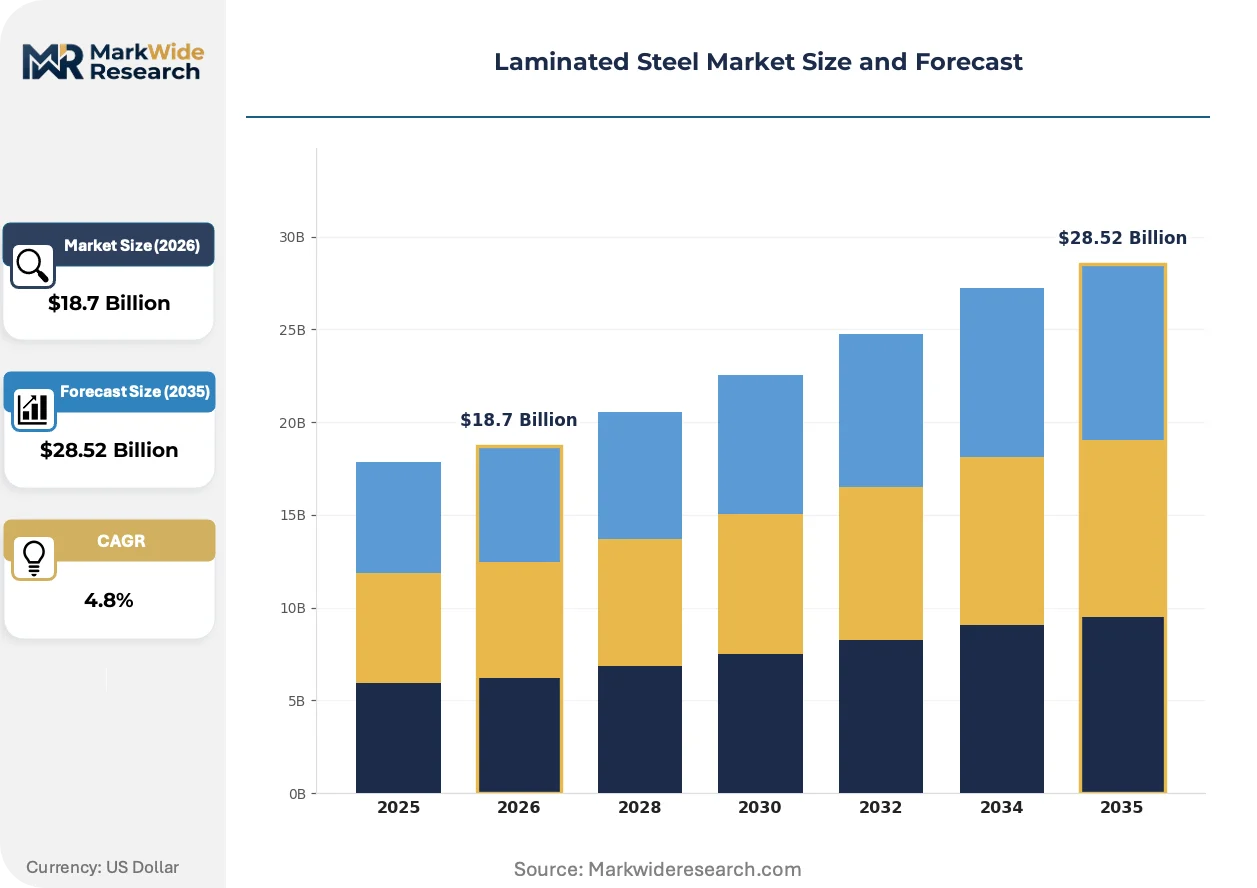
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $28.52 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cold Rolled, Hot Rolled, Galvanized Steel, Coated Steel End User: Construction, Automotive, Electrical, Industrial Equipment Thickness: Thin, Medium, Thick, Ultra-Thin Finish: Painted, Polished, Textured, Laminated |
| Companies Covered | Tata Steel, ThyssenKrupp AG, ArcelorMittal, China Ansteel Group Corporation Limited, Toyo Kohan Co., Ltd., Nippon Steel Corporation, JFE Steel Corporation, LIENCHY LAMINATED METAL CO., LTD., POSCO, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laminated Steel Market Shifts & Advancements
Laser-scribed grain orientation and in-line coating thickness monitoring are compressing core loss specifications while tightening supply chain qualification windows for high-efficiency electrical steel.
Laser surface texturing of grain-oriented electrical steel is rewriting the performance frontier for transformer core laminations. Major power equipment manufacturers in Germany and Japan are adopting these grades for ultra-high-voltage transmission infrastructure. The technology is compressing the competitive gap between conventional cold-rolled silicon steel and domain-refined premium grades.
REACH substance restrictions on certain epoxy-based interlayer bonding systems are forcing coating line retrofits across European flat steel facilities. Producers are qualifying waterborne and UV-cured alternatives that maintain punchability while eliminating restricted aromatic amine hardeners. Cold-rolled non-oriented electrical steel for automotive traction motors faces the steepest requalification burden.
Automotive OEMs are consolidating laminated steel suppliers into single-source framework agreements with embedded volume commitments and joint specification development. Long-term contracting is displacing spot market procurement for EV motor core grades. This concentration is most visible in German and South Korean automotive supply chains.
Laminated Steel Market Segmentation
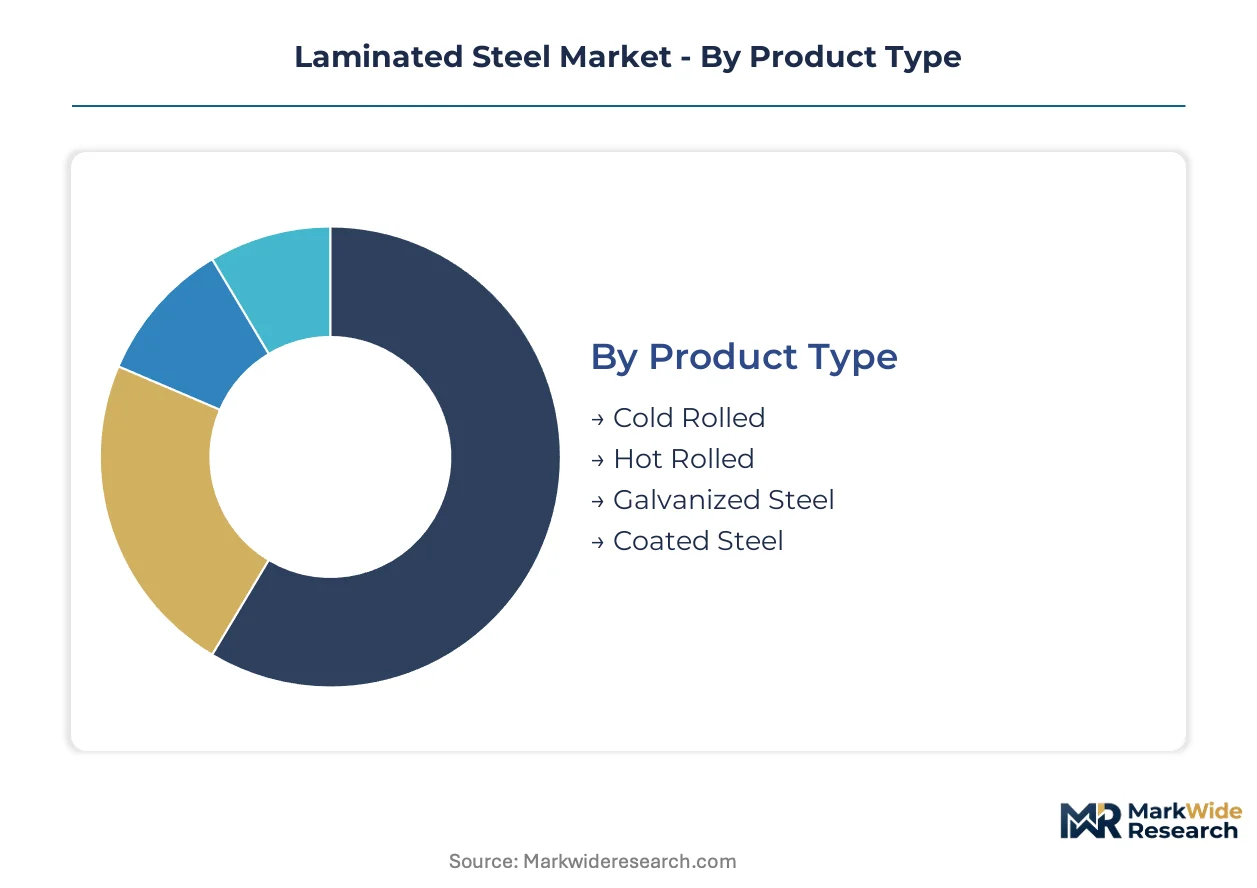
Laminated steel procurement decisions hinge on electromagnetic performance specifications, corrosion resistance requirements, and stamping compatibility with downstream manufacturing systems. Buyers segment supply by product metallurgy, thickness tolerance, and coating chemistry to match application-specific duty cycles and environmental exposure conditions.
Product Type:
Cost tier determines supplier qualification pathways, with premium grades commanding dedicated rolling mill capacity and extended lead times.
- Cold Rolled:Dimensional precision within sub-10 micrometer tolerances enables high-efficiency motor core laminations where eddy current losses must be minimized. Automotive OEMs in Germany and South Korea specify cold-rolled grades exclusively for EV traction motor stampings, compressing supplier qualification windows to 18-24 months.
- Galvanized Steel:Zinc-aluminum coating systems deliver salt-spray resistance exceeding 1,000 hours for offshore transformer housings and marine cable armoring. Demand concentrates around Busan and Shanghai manufacturing clusters serving Pacific basin wind infrastructure projects.
- Hot Rolled:Thicker gauge structural laminates serve heavy industrial equipment frames where magnetic shielding requirements are secondary to mechanical load-bearing capacity.
- Coated Steel:Organic interlayer systems including epoxy and phenolic resins bond multiple steel sheets for specialized electromagnetic applications requiring adjustable permeability.
Volume sits with cold-rolled precision grades; growth tilts toward galvanized corrosion-resistant variants.
End User:
Application-specific certification regimes reshape competitive access, with automotive and electrical sectors imposing the most stringent qualification protocols.
- Automotive:EV motor core laminations and battery housings drive sub-0.5 mm gauge demand, with REACH-compliant coating chemistries becoming mandatory for European supply. OEMs in Stuttgart and Seoul are consolidating suppliers into single-source frameworks with embedded volume commitments.
- Electrical:Power transformer and distribution equipment manufacturers specify grain-oriented grades for ultra-high-voltage infrastructure, with laser-scribed variants gaining traction in German and Japanese transmission projects.
- Construction:Building envelope and structural applications prioritize cost efficiency over electromagnetic performance, absorbing medium-gauge hot-rolled supply.
- Industrial Equipment:General machinery and appliance manufacturers represent stable demand for standard non-oriented electrical steel grades with moderate core loss specifications.
Procurement intensity clusters in automotive traction motor grades; specification evolution runs fastest in electrical transmission infrastructure.
Thickness:
Margin pools concentrate at gauge extremes where stamping yield rates and core loss performance command pricing premiums.
- Ultra-Thin:Sub-0.35 mm grades enable highest-efficiency motor cores for aerospace and premium automotive applications, with Nippon Steel Corporation dominating precision rolling capacity. Supply scarcity across Atlantic basin facilities creates single-source risk for European Tier-1 stampers.
- Thin:0.35-0.5 mm segments balance electromagnetic performance with stamping processability, capturing the largest volume share in EV motor production.
- Medium:0.5-0.8 mm gauges serve industrial motors and power transformers where efficiency requirements are less stringent than traction applications.
- Thick:Above-0.8 mm laminates address heavy-duty industrial equipment and structural magnetic shielding with minimal eddy current sensitivity.
Capacity investment flows toward ultra-thin precision grades; medium-thickness segments face substitution pressure from amorphous metal cores in high-frequency transformer applications.
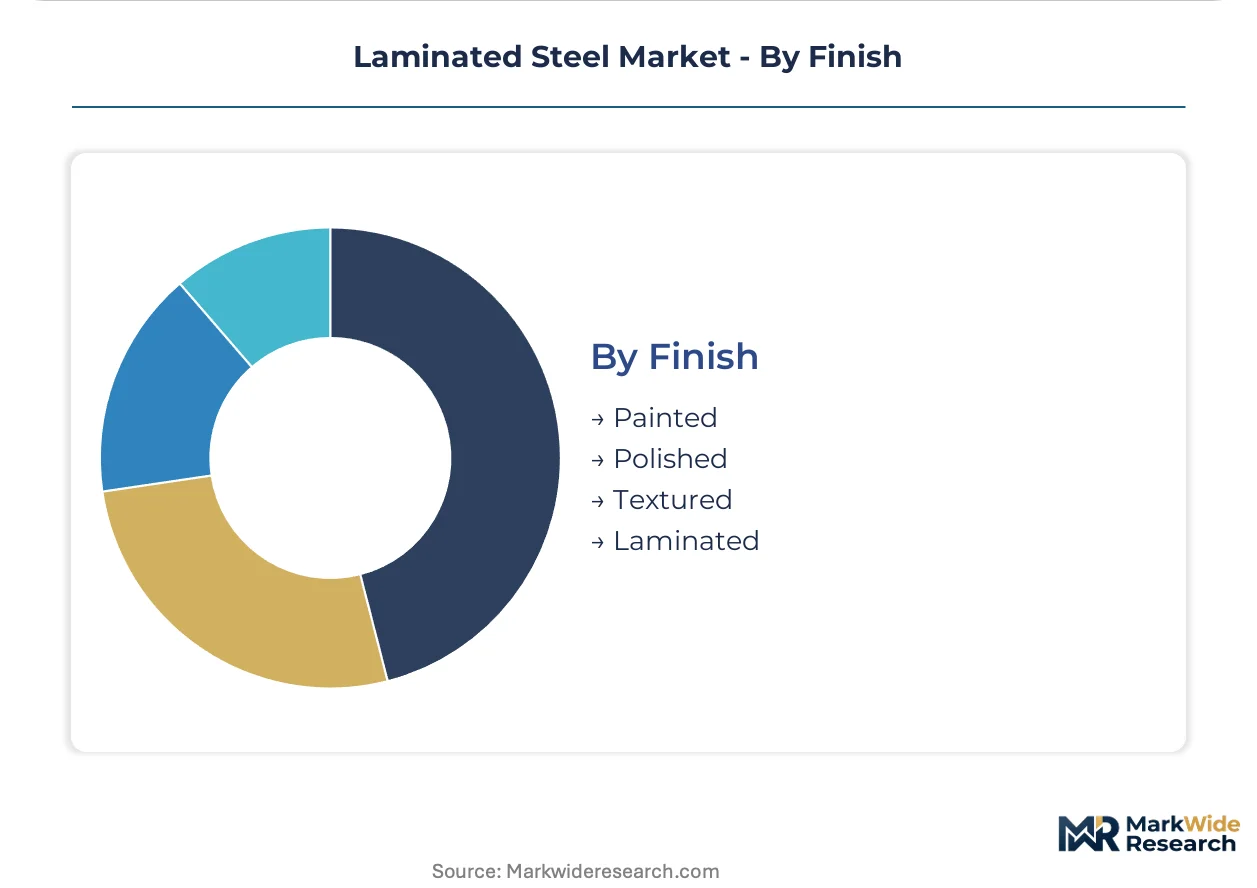
Finish:
Surface treatment chemistry determines interlayer adhesion properties and environmental durability in finished assemblies.
- Laminated:Multi-layer bonded construction with organic or metallic interlayers provides tunable magnetic properties and electrical insulation between sheets.
- Painted:Coil-coated organic finishes deliver color consistency and UV resistance for visible architectural applications.
- Polished:Smooth surface finishes reduce friction in progressive die stamping operations, improving tool life and dimensional repeatability.
- Textured:Laser surface texturing of grain-oriented steel rewrites performance benchmarks for transformer core laminations, compressing the competitive gap against domain-refined premium grades.
Specification adoption favors laminated bonded construction; textured surface treatments are climbing fastest in ultra-high-voltage power equipment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Iron ore deposits in Western Australia and the Pilbara anchor raw material flows for laminated steel production across Pacific basin markets. Integrated producers in East Asia and Europe convert these feedstocks into thin-gauge electrical grades serving automotive and power equipment demand.
China
EV traction motor laminations and battery housing stampings pull capacity toward sub-0.5 mm precision grades in the Yangtze River Delta. MEE enforcement of dual carbon compliance thresholds accelerates hydrogen-reduced feedstock trials at integrated mills. Shanghai manufacturing clusters concentrate thin-gauge rolling capability serving domestic automotive OEMs.
Japan
Ultra-high-voltage transformer infrastructure and aerospace motor cores sustain demand for laser-scribed grain-oriented grades. METI efficiency standards for power transmission equipment tighten core loss specifications. Nagoya and Tokyo industrial corridors host precision rolling facilities with sub-10 micrometer thickness tolerance expertise.
Germany
Automotive OEMs in Stuttgart consolidate laminated steel suppliers into single-source frameworks with embedded volume commitments for EV motor production. REACH substance restrictions on epoxy-based interlayer chemistries force coating line retrofits across flat steel facilities. Ruhr Valley mills anchor Atlantic basin supply for European Tier-1 stampers.
South Korea
Busan manufacturing clusters serve Pacific basin wind infrastructure projects with salt-spray resistant galvanized laminates for marine transformers. Domestic automotive OEMs requalify supply chains for EV traction motor laminations, compressing lead times. MFDS workplace exposure standards govern volatile organic compound releases from coating operations.
United States
IRA manufacturing credits for clean energy component production open qualification pathways for North American laminated steel re-rolling capacity. EPA emissions standards and OSHA workplace exposure limits govern coating line operations at domestic facilities. Midwest industrial corridors host cold-rolling capacity serving automotive and electrical equipment manufacturers.
Laminated Steel Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue adjacent specialty coating and digital provenance services. The vendor base stratifies across three capability tiers: integrated steel majors with captive cold-rolling capacity, precision rolling specialists serving automotive qualification protocols, and regional re-rollers supplying construction and industrial equipment segments. Strategic archetypes include upstream-integrated feedstock controllers, qualification-heavy automotive specialists, and infrastructure-focused corrosion-resistant grade suppliers. Competitive moves center on capacity expansion in ultra-thin gauge rolling and strategic partnerships for blockchain-enabled coil tracking.
Among Japanese integrated producers, Nippon Steel Corporation and JFE Steel Corporation exemplify the precision-tier archetype with sub-0.35 mm rolling expertise. Tata Steel occupies a position bridging European automotive qualification networks with emerging market capacity. ArcelorMittal anchors Atlantic basin supply flows through Belgian and Brazilian mill assets. These named entities represent the geographic and capability diversity structuring competitive access across Pacific and Atlantic corridors.
| Leading Market Players |
|---|
| Tata Steel |
| ThyssenKrupp AG |
| ArcelorMittal |
| China Ansteel Group Corporation Limited |
| Toyo Kohan Co., Ltd. |
| Nippon Steel Corporation |
| JFE Steel Corporation |
| LIENCHY LAMINATED METAL CO., LTD. |
| POSCO |
| Others |
Supply & Pricing Matrix
Silicon electrical steel billet costs cascade through three distinct pricing tiers as cold-rolling operations serving automotive Tier-1 stampers absorb raw material volatility while precision-grade premiums widen against commodity construction laminates.
Pricing Analysis
Warranty-backed certification bundles separate premium automotive-grade supply from unbundled commodity construction material. Three-tier pricing structure across premium, standard, and economy levels reflects qualification burden: EV motor core grades with REACH-compliant coatings and sub-10 micrometer tolerances command dedicated rolling mill access, while industrial equipment laminates trade on spot-market silicon steel indices. Cost compression in thin-gauge precision grades is intensifying because Nippon Steel Corporation and Shanghai-area clusters dominate sub-0.35 mm capacity, squeezing margin pools for Atlantic basin re-rollers. Construction and industrial equipment buyers exhibit highest price sensitivity, accepting wider thickness tolerances and standard organic interlayers; automotive OEMs in Stuttgart and Seoul show lowest sensitivity, embedding long-term volume commitments into single-source frameworks.
Supply Chain Analysis
Single-source vulnerability sits with ultra-thin gauge precision rolling capability concentrated in Japan, China, and South Korea. Raw material flows draw from Western Australian iron ore deposits, high-grade silicon steel billets from integrated Asian mills, and zinc-aluminum coating alloys from Korean smelters. Logistics chokepoint risk concentrates at Busan and Shanghai port clusters handling coated coil exports to Atlantic basin automotive Tier-1s. Distribution runs through mill-direct framework agreements for automotive grades, regional steel service centers for construction supply, and specialized electrical equipment distributors for power transformer laminations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as producers pursue captive cold-rolling capacity to lock in automotive qualification pathways and escape silicon steel billet margin volatility.
For Market Incumbents: To counter amorphous metal substitution in high-frequency transformer applications, ArcelorMittal and Tata Steel should deepen backward integration into hydrogen-reduced direct reduced iron feedstocks while expanding Belgian and UK cold-rolling assets to serve REACH-compliant European automotive demand. Certification investment in laser-scribed grain orientation technology preserves pricing power against domain-refined premium grades in ultra-high-voltage infrastructure. For New Entrants and Emerging Players: Enter via blockchain-enabled coil tracking services as a procurement differentiator for automotive OEMs auditing Scope 3 emissions, targeting North American re-rolling capacity gaps exposed by IRA manufacturing credits. White-space sits with salt-spray resistant galvanized laminates for Atlantic basin offshore wind projects, where Busan-area supply chains face tariff exposure. Go-to-market through joint specification development with Midwest electrical equipment manufacturers bypasses entrenched Asian mill relationships. For Investors and Strategic Acquirers: First-mover hydrogen-reduced feedstock trials at Chinese integrated mills is the leading indicator that carbon border adjustment mechanisms will reshape competitive access across Atlantic and Pacific corridors. Long-term viability favors precision rolling specialists with automotive qualification networks over commodity construction-grade re-rollers facing amorphous substitution. Watch for EPA emissions enforcement tightening at US coating facilities as signal for domestic capacity investment windows.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Ultra-Thin Gauge Rolling | Nippon Steel Corporation's sub-0.35 mm expertise anchors premium motor core supply for aerospace and automotive traction applications. |
| Backward Integration into Hydrogen-Reduced Feedstock | China's MEE dual carbon compliance thresholds push integrated producers toward decarbonized ironmaking trials ahead of carbon border adjustments. |
| REACH-Compliant Coating Line Retrofit | European flat steel facilities qualify waterborne and UV-cured interlayer systems eliminating restricted aromatic amine hardeners. |
| Blockchain-Enabled Provenance Verification | Automotive OEMs in Germany and South Korea embed coil tracking into single-source framework agreements for Scope 3 emissions auditing. |
| Long-Term Supply Agreement with Offshore Wind Developers | Salt-spray resistant galvanized laminates penetrate marine transformer and subsea cable armoring projects around Busan manufacturing clusters. |
Research Methodology
Multi-period observation of silicon steel billet pricing spreads, coating line capacity utilization, and automotive OEM qualification timelines anchored the trend analysis, supplemented by interviews with cold-rolling mill operators, Tier-1 motor core stamper procurement leads, REACH compliance consultants, and power equipment manufacturer technical directors. Secondary validation drew from SEC 10-K filings of listed steel producers, ECHA substance restriction updates, IEA power transmission investment databases, and customs trade data for coated flat steel flows. Bottom-up coil consumption estimates by end-use application triangulated against top-down capacity announcements from integrated mill expansions.
Input-output matrices mapped silicon steel feedstock costs through cold-rolling yield rates to finished laminate pricing across the analysis window, with segmentation dimensions covering product metallurgy, thickness tolerance bands, coating chemistry families, and regional regulatory clusters. CAGRs were derived from trend extrapolation of EV motor core laminations demand, offshore wind infrastructure procurement, and transformer replacement cycles. Industry-specific forecast inputs incorporated METI efficiency standard revisions for Japanese power equipment and IRA domestic content credit qualification thresholds for North American supply.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated amorphous metal substitution, sudden REACH substance restriction expansions, or disruptive hydrogen-reduced feedstock cost breakthroughs. Forecasts reflect documented assumptions about automotive electrification penetration, carbon border adjustment implementation timing, and coating chemistry qualification timelines. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Cesium Market
Metals & Minerals
Gemstones Market
Metals & Minerals
Wegscheiderite Market
Metals & Minerals
Compacted Graphite Iron Market
Metals & Minerals
Silver Salt Market
Metals & Minerals
Zinc Sulphate Market
Metals & Minerals
Global Mining Metals Market
Metals & Minerals
Tantalum Pentoxide Market
Metals & Minerals
Prefab Iron Market
Metals & Minerals
USA and Canada Copper Market
Metals & Minerals
Recycled Lead Market
Metals & Minerals
Global Magnesium Carbonate Minerals Market
Metals & Minerals
Coalingite Market
Metals & Minerals
Recycled Copper Market
Metals & Minerals
India CRNO Steel Lamination Market
Metals & Minerals
Global Base Metal Mining Market