
 Sodium Tungstate Market | 2026-2036
Sodium Tungstate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Tungstate Market Analysis
Electronics end-use demand is shifting toward advanced electrolyte formulations in battery and semiconductor applications, altering traditional consumption patterns for sodium tungstate. HC Starck leverages its European refining infrastructure to supply high-purity grades for specialty electronics. Ganzhou Grand Sea W& Mo Group Co., Ltd. anchors global supply through its integrated tungsten ore-to-chemical processing complex in Jiangxi Province. Yuanhang Tungsten differentiates via dedicated crystal-grade production lines serving fluorescent material manufacturers.
Sodium tungstate (Na₂WO₄) is an inorganic sodium salt of tungstic acid, typically appearing as colorless or white crystalline solids with solubility in water exceeding 70% at standard temperature; manufacturers produce it via alkaline digestion of scheelite or wolframite ores followed by purification and crystallization. The compound serves primarily as a precursor for tungsten metal reduction, catalytic systems, and functional coatings requiring controlled oxidation states. Powder and crystal product types dominate volume throughput, though solution formulations capture disproportionate margin pools in electronics electrolyte applications. Catalyst and coatings applications lead absolute demand, while fluorescent materials represents the fastest-expanding application segment driven by LED phosphor development.
REACH registration requirements in Europe mandate full substance dossiers for sodium tungstate import and manufacture, elevating compliance costs for non-EU suppliers. China's MEE enforces wastewater discharge standards on tungsten smelters that constrain raw material availability during environmental inspection cycles. The US EPA maintains reporting thresholds under TSCA Section 8(a) that shape import documentation burdens. Stakeholders must monitor regulatory divergence between jurisdictions to optimize supply chain routing and product certification investments.
Market Dynamics
China's dominance in tungsten ore processing concentrates raw material control in Jiangxi Province, while REACH compliance and MEE wastewater standards force reformulation investments across European and Chinese supply chains.
Growth Catalysts
- LED phosphor development:Fluorescent materials manufacturers are scaling crystal-grade sodium tungstate procurement for advanced phosphor formulations in solid-state lighting.
- REACH registration:European ECHA substance dossier requirements for sodium tungstate create certified-supplier premiums that reward compliant producers with preferential channel access.
- Battery electrolyte expansion:Electronics manufacturers are integrating sodium tungstate-derived compounds into next-generation electrolyte systems for energy density improvements.
Market Restraints
- Input cost volatility:Scheelite and wolframite ore price swings transmit directly to sodium tungstate production economics, compressing margin predictability for non-integrated processors.
- Supply concentration risk:China's Jiangxi Province controls over 80% of global tungsten ore-to-chemical processing capacity, creating single-point vulnerability for downstream buyers.
- Substitution pressure:Molybdate compounds compete in select catalytic applications where tungsten price spikes trigger formulation switches by cost-sensitive chemical processors.
Strategic Opportunities
- India industrial chemicals:BIS certification pathways and PLI scheme incentives for specialty chemicals create entry vectors for sodium tungstate suppliers targeting domestic catalyst manufacturing.
- Semiconductor coatings:Atomic layer deposition processes for tungsten nitride barrier layers represent an emerging high-purity application segment with premium pricing potential.
- EU Green Deal alignment:CSRD reporting requirements and sustainable supply chain mandates favor sodium tungstate producers with verified low-carbon processing and transparent ore sourcing.
Industry Challenges
- Specialized metallurgical expertise:Tungsten ore digestion and crystallization process engineering requires skills concentrated in legacy mining regions, constraining capacity expansion outside China.
- Multi-jurisdiction certification timelines:Parallel REACH, TSCA Section 8(a), and GB standards compliance creates 18-24 month product registration cycles that delay market entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Tungstate Market |
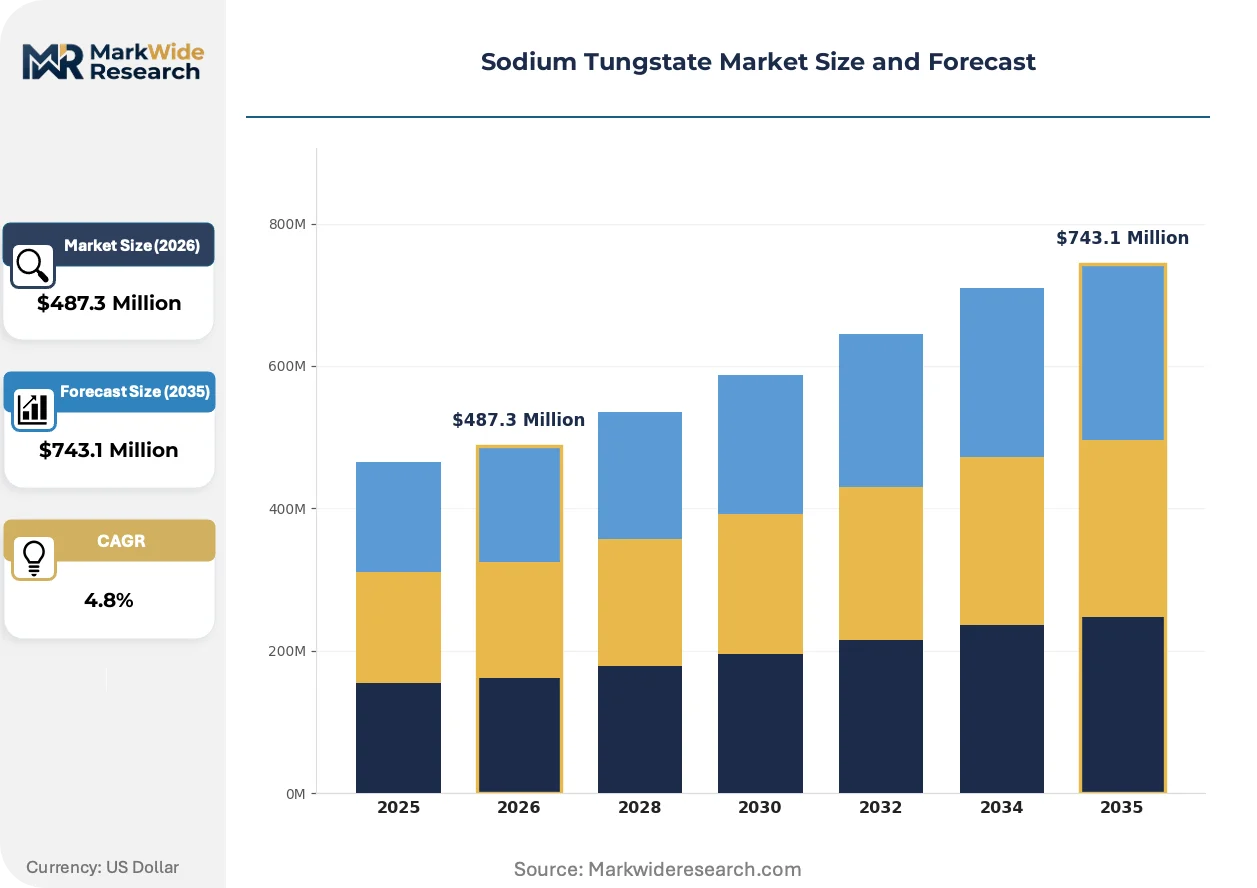
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $743.1 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Crystals, Solution Application: Catalysts, Coatings, Electrolytes, Fluorescent Materials End User: Chemical Industry, Electronics, Glass Manufacturing, Metal Processing Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | Ganzhou Grand Sea W& Mo Group Co., Ltd., HC Starck, Yuanhang Tungsten, Taizhou BangDe, Alpha Chem, Anchor Chemicals, Ningxiang Changyi, Kat-Chem Ltd., Sigma-Aldrich, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Tungstate Market Emerging Trajectories
Process intensification and regulatory digitization are compressing traditional production timelines, while end-use specifications bifurcate between commodity catalyst grades and ultra-high-purity electronics formulations.
Solvent extraction and ion exchange purification systems are replacing legacy precipitation methods for sodium tungstate production. Specialty electronics manufacturers in Japan and South Korea are adopting these refined grades for semiconductor barrier layer applications. The technology is absorbing margin compression from energy-intensive crystallization by reducing reagent consumption and waste volumes.
China's MEE wastewater discharge standards for tungsten smelters are tightening permissible heavy metal limits in effluent streams. Jiangxi-based processors are retrofitting closed-loop water systems and solid waste recovery units to maintain operating licenses. Crystal-grade production lines face the steepest compliance costs due to higher purity water requirements.
Long-term offtake agreements are displacing spot market transactions for electronics-grade material. Korean and Japanese battery manufacturers are locking multi-year supply contracts directly with Ganzhou refiners, bypassing traditional chemical distributors. This concentration is visible most acutely in the semiconductor capital equipment supply chain, where qualification timelines favor relationship-based procurement over price competition.
Sodium Tungstate Market Segmentation
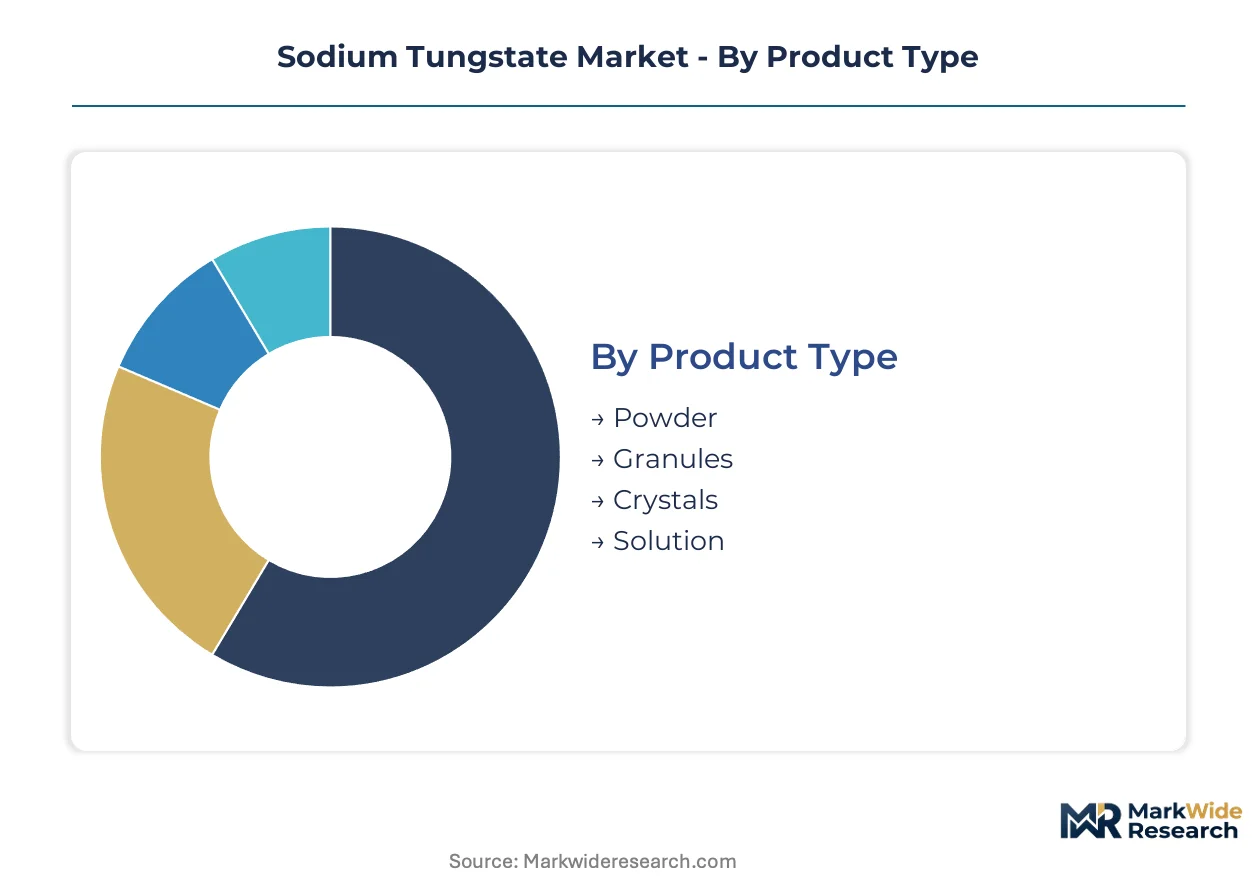
Sodium tungstate specifications diverge sharply between commodity catalyst grades and ultra-high-purity electronics formulations. Procurement patterns track these technical boundaries, with volume buyers negotiating long-term contracts while specialty consumers pay certified-supplier premiums.
Product Type:
Customization intensity rises from bulk powder through precision crystal grades, with solution formulations occupying a hybrid position between standardization and bespoke blending.
- Powder:Fine particulate sodium tungstate with particle size distributions optimized for catalyst bed loading and thermal spray coating applications. Chemical processors in India and Germany consume powder grades for fixed-bed catalytic systems where surface area governs reaction efficiency.
- Crystals:High-purity monoclinic or orthorhombic crystal structures with controlled lattice parameters for phosphor host matrices. LED phosphor manufacturers in Japan and South Korea source crystal grades exclusively from REACH-registered suppliers to meet ECHA substance dossier requirements for downstream electronics.
- Granules:Agglomerated forms with controlled porosity for fluidized bed reactors and metal reduction furnaces.
- Solution:Aqueous formulations with precise concentration specifications for electroplating baths and electrolyte precursor blending.
Most installed capacity flows through Powder. Expansion is steepest in Crystals.
Application:
Margin capture potential separates mature industrial uses from emerging electronics applications, with coating technologies bridging both value tiers.
- Catalysts:Tungsten-based heterogeneous catalysts for hydrodesulfurization and selective oxidation processes. Refineries in the US Gulf Coast and Rotterdam chemical clusters specify sodium tungstate precursors for cobalt-tungsten sulfide catalyst manufacturing.
- Fluorescent Materials:Crystal-grade sodium tungstate serves as a host lattice for europium and terbium dopants in LED conversion phosphors. Solid-state lighting manufacturers in Taiwan and mainland China are scaling procurement for high-CRI white LED formulations.
- Coatings:Thermal barrier and wear-resistant tungsten carbide coatings via chemical vapor deposition and plasma spray routes.
- Electrolytes:Sodium tungstate-derived additives for lithium-ion battery electrolyte stability and tungsten oxide thin films.
Volume concentrates in Catalysts. Value growth is climbing fastest in Fluorescent Materials.
End User:
Technical sophistication and regulatory exposure distinguish electronics buyers from commodity chemical processors, with glass manufacturers occupying intermediate specification territory.
- Chemical Industry:Catalyst manufacturers and fine chemical synthesizers purchasing technical-grade material under bulk supply agreements. BASF and Evonik procurement teams in Ludwigshafen specify sodium tungstate for petrochemical catalyst production.
- Electronics:Semiconductor and battery material suppliers demanding ppb-traceability and full supply chain documentation. Samsung SDI and LG Chem qualification protocols require 18-month vendor approval cycles for electrolyte-grade material.
- Metal Processing:Tungsten metal and alloy producers using sodium tungstate as a reduction feedstock.
- Glass Manufacturing:Specialty glass producers incorporating tungsten oxides for refractive index modification and UV absorption.
Chemical Industry channels the largest tonnage. Electronics is scaling procurement most aggressively.
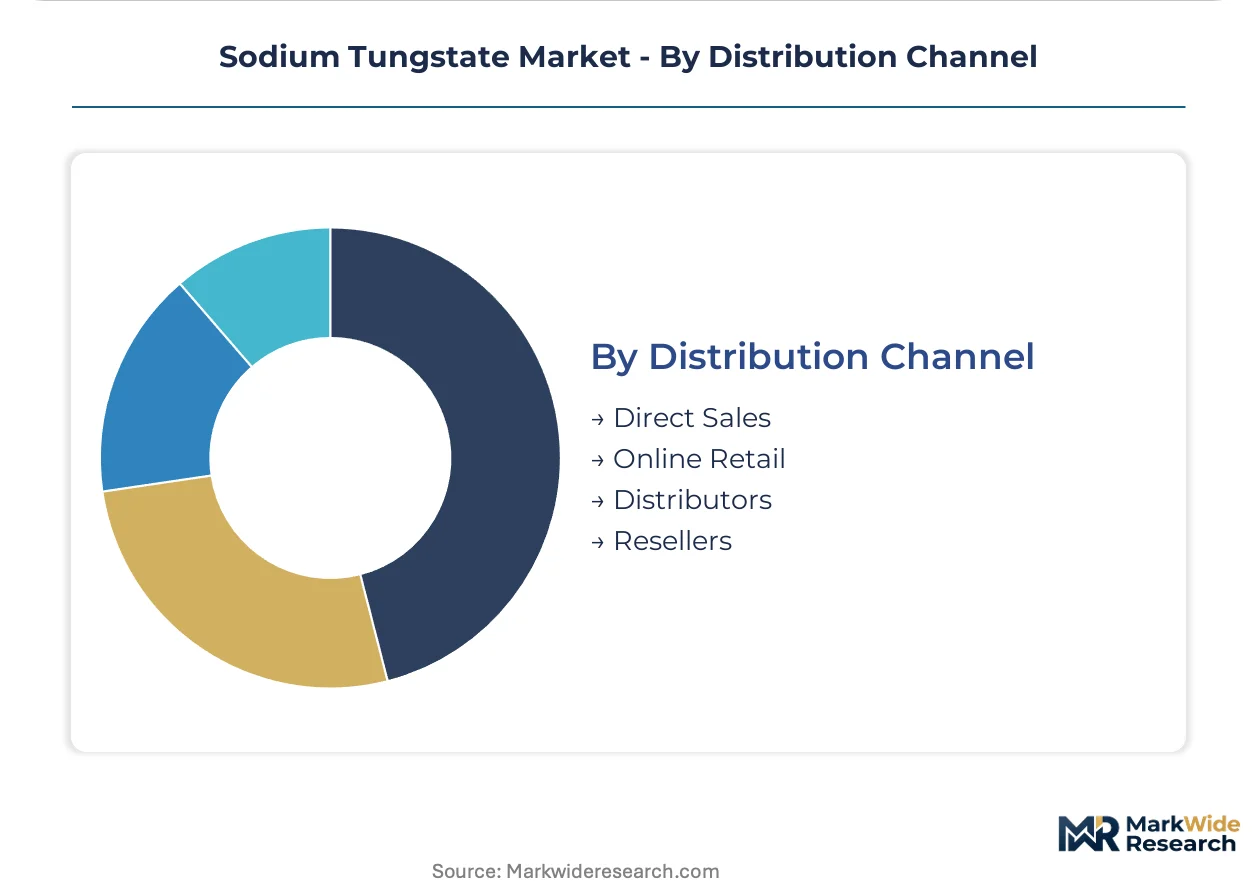
Distribution Channel:
Relationship intensity and technical service requirements shape channel selection, with direct engagement dominating specification-critical applications.
- Direct Sales:Long-term offtake contracts between refiners and qualified end-users with joint formulation development. Ganzhou Grand Sea W& Mo Group maintains direct supply relationships with Japanese phosphor houses bypassing distributor markups.
- Distributors:Regional chemical distributors stocking technical grades for mid-volume catalyst and coating customers. Univar Solutions and Brenntag maintain sodium tungstate inventories in Antwerp and Singapore for European and Southeast Asian chemical processors.
- Online Retail:E-commerce platforms serving research quantities and small-batch specialty chemical buyers.
- Resellers:Independent traders arbitraging spot price differentials between Chinese domestic and export markets.
Direct Sales handles the majority of electronics-grade volume. Distributors are capturing share fastest in catalyst applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangxi Province concentrates the bulk of global tungsten ore-to-chemical processing capacity. Sodium tungstate demand patterns diverge sharply across major economies based on end-use specialization and regulatory exposure.
China
Ganzhou-based refiners supply crystal-grade material for LED phosphor manufacturers. MEE wastewater discharge standards enforce heavy metal limits on smelter effluent streams. Jiangxi processors retrofit closed-loop water systems to maintain operating licenses during environmental inspection cycles.
Germany
Ludwigshafen chemical clusters specify sodium tungstate precursors for cobalt-tungsten sulfide catalyst manufacturing. REACH registration requirements mandate full ECHA substance dossiers for import and manufacture. Leverkusen-based distributors stock technical grades for mid-volume European catalyst customers.
United States
Gulf Coast refineries procure sodium tungstate for hydrodesulfurization catalyst production. EPA reporting thresholds under TSCA Section 8(a) shape import documentation burdens. Houston chemical distributors arbitrage spot differentials between domestic and export markets.
Japan
Osaka and Nagoya phosphor houses source crystal grades exclusively from REACH-registered suppliers. METI industrial standards govern traceability requirements for electronics-grade material. Kyushu-based LED manufacturers scale procurement for high-CRI white LED formulations.
South Korea
Samsung SDI and LG Chem qualification protocols require extended vendor approval cycles for electrolyte-grade material. MFDS chemical safety regulations align with international substance registration frameworks. Seoul-based battery manufacturers lock multi-year supply contracts directly with Chinese refiners.
Sodium Tungstate Market Vendor Landscape
Capacity expansion dominates the current landscape as integrated processors scale crystal-grade production lines. The vendor base separates into three distinct tiers: ore-to-chemical integrators controlling Jiangxi supply corridors, European refiners leveraging REACH-registered status for specialty electronics access, and regional distributors managing spot inventories for catalyst customers. Strategic archetypes include backward-integrated miners with captive smelting assets, purity-focused specialists serving semiconductor qualification protocols, and volume traders arbitraging Chinese domestic-export price spreads. Competitive moves center on long-term offtake contracting with Korean and Japanese electronics manufacturers, plus M&A activity targeting tungsten ore reserves in Africa and Central Asia.
Among Jiangxi-based integrators, Ganzhou Grand Sea W& Mo Group Co., Ltd. anchors the ore-to-chemical processing tier with its integrated refining complex. HC Starck exemplifies the European specialist archetype, leveraging continental infrastructure to supply high-purity grades. Yuanhang Tungsten occupies a position within the crystal-grade specialist segment, serving fluorescent material manufacturers through dedicated production lines. These three entities represent distinct competitive positioning vectors: scale-driven raw material control, regulatory-certified specialty access, and application-specific purity engineering.
| Leading Market Players |
|---|
| Ganzhou Grand Sea W& Mo Group Co., Ltd. |
| HC Starck |
| Yuanhang Tungsten |
| Taizhou BangDe |
| Alpha Chem |
| Anchor Chemicals |
| Ningxiang Changyi |
| Kat-Chem Ltd. |
| Sigma-Aldrich |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in Jiangxi Province anchor supply-side discipline through state-supported ore-to-chemical complexes, translating captive tungsten concentrate access into pricing power over downstream crystal-grade and powder formulations. Ganzhou Grand Sea W& Mo Group leverages this structure to enforce long-term offtake premiums with Korean and Japanese electronics manufacturers, while European REACH-registered specialists extract certification-tier margins from phosphor houses unwilling to accept regulatory risk.
Pricing Analysis
Distributor margins compress most acutely in technical-grade powder transactions, where Univar Solutions and Brenntag arbitrage spot differentials between Chinese export and domestic European pricing. Contract-based long-term offtake dominates electronics-grade procurement, with price differentiation driven by REACH registration status and ppb-traceability certification. Cost compression in catalyst-grade powder is intensifying because Indian and German chemical processors negotiate volume aggregations against fragmented distributor inventories. Catalyst manufacturers exhibit highest price sensitivity due to molybdate substitution options, while semiconductor barrier-layer buyers accept premium positioning with minimal negotiation leverage.
Supply Chain Analysis
Refurbishment flows remain negligible in sodium tungstate given chemical purity degradation risks, though Jiangxi smelters recover tungsten values from spent catalyst leachates through secondary digestion circuits. Supply concentrates in China, with South Korea and Japan as downstream qualification hubs. Raw material flows draw from scheelite and wolframite concentrates, sulfuric acid for alkaline digestion, and high-purity sodium carbonate for crystallization. Single-source vulnerability persists through Jiangxi Province's 80% control of ore-to-chemical capacity. Distribution runs through direct sales for electronics-grade material and regional chemical distributors for catalyst applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium tungstate functions as a regulatory compounder where ECHA REACH dossier completion deadlines and China's MEE wastewater enforcement cycles synchronize to reward certified-supplier premiums. These compliance milestones concentrate procurement authority among registrants with verified low-carbon processing and transparent ore sourcing documentation.
For Market Incumbents: Deepen backward integration into African and Central Asian tungsten ore reserves to offset Jiangxi concentration risk and secure captive concentrate supply against MEE inspection cycle disruptions. Lock multi-year direct supply relationships with Samsung SDI and LG Chem before Korean battery manufacturers complete alternative qualification cycles with secondary Chinese refiners. Prioritize crystal-grade capacity expansion over powder commoditization to defend margin position against Ganzhou Grand Sea W& Mo Group's scale advantages. For New Entrants and Emerging Players: Specialty chemical distributors in India represent the most penetrable channel partner type for BIS-certified sodium tungstate entry, given PLI scheme incentives for domestic catalyst manufacturing and limited incumbent REACH-registered presence. Target semiconductor coatings for atomic layer deposition applications where qualification timelines exceed 18 months and relationship-based procurement favors new entrants with dedicated purity engineering. Pursue joint formulation development with Taiwanese LED phosphor houses as a go-to-market angle bypassing established Ganzhou supply corridors. For Investors and Strategic Acquirers: Valuations sit cheapest among European REACH-registered refiners with underutilized high-purity production lines and stranded continental infrastructure awaiting Korean electronics qualification. Long-term viability over the next decade hinges on CSRD-aligned supply chain transparency and verified carbon intensity disclosures securing EU Green Deal procurement preferences. Watch for Korean battery manufacturer direct contracting announcements with non-Jiangxi Chinese refiners as the inflection signal indicating qualification protocol relaxation and incumbent pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ore Reserves | Secures captive tungsten concentrate supply against MEE environmental inspection disruptions in Jiangxi Province. |
| REACH Registration Completion | Unlocks preferential channel access to Japanese and South Korean phosphor manufacturers requiring ECHA dossier compliance. |
| Crystal-Grade Capacity Expansion | Captures LED phosphor demand growth with premium pricing unavailable in commoditized catalyst-grade powder. |
| Closed-Loop Water System Retrofit | Maintains Jiangxi operating licenses under tightening MEE wastewater discharge standards for heavy metal limits. |
| Direct Long-Term Offtake Contracting | Bypasses distributor markups and locks Korean battery manufacturer procurement through Samsung SDI and LG Chem qualification protocols. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tungsten smelter plant managers, procurement leads at catalyst and phosphor manufacturers, specialty chemical distribution partners, and technical R&D directors at electronics-grade refiners with secondary validation against Chinese customs export data, Jiangxi provincial environmental disclosure filings, ECHA REACH registration databases, and SEC 10-K filings from publicly traded chemical processors. Bottom-up capacity assessments and top-down end-use consumption estimates were triangulated to constrain forecast variance.
Historical reference periods spanning ore price volatility cycles and regulatory enforcement waves anchored the projection horizon across the analysis window. The analytical framework modeled segmentation dimensions including product grade tier, end-use industry application, regional production hub concentration, and certification status. CAGRs were derived from slope-log regression of normalized consumption trajectories, with forecast inputs incorporating MEE inspection cycle frequency and Korean battery manufacturer qualification pipeline status.
Revisions become necessary when Chinese environmental enforcement intensity exceeds baseline assumptions or when Korean electronics manufacturers accelerate alternative supplier qualification timelines beyond historical 18-month patterns. Forecasts reflect documented assumptions regarding Jiangxi capacity utilization rates and REACH registration completion schedules. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals & Minerals
Global Ferrous Scrap Recycling Market
Metals & Minerals
20MnCr5 Steel Market
Metals & Minerals
Global Artificial Rutile Market
Metals & Minerals
Zinc Sulfate Market
Metals & Minerals
Middle-East and Africa Sodium Sulfide Market
Metals & Minerals
Silver Salt Market
Metals & Minerals
Global Base Metal Mining Market
Metals & Minerals
Rare Earth Elements Recycling Market
Metals & Minerals
Colored Gemstones Market
Metals & Minerals
Moissanite Market
Metals & Minerals
India Colored Gemstones Market
Metals & Minerals
Global Chromium Salt Market
Metals & Minerals
Zinc Hydroxide Market
Metals & Minerals
Electrolytic Manganese Dioxide Market
Metals & Minerals
Nickel Mining Market
Metals & Minerals
Laminated Steel Market