
 Polyethylene Terephthalate (PET) Shrink Films Market | 2026-2036
Polyethylene Terephthalate (PET) Shrink Films Market Size, Share, and Industry Trends Forecast 2026-2036
Polyethylene Terephthalate (PET) Shrink Films Market Analytics
A skilled polymer processing labor shortage across Asia-Pacific is unwinding capacity expansion timelines for several PET shrink film producers. Amcor leverages its integrated resin-to-film operations across multiple continents to sustain supply security for beverage clients. Polyplex Corporation anchors South Asian demand through specialized biaxial orientation lines serving domestic label converters. Klöckner Pentaplast differentiates via pharmaceutical-grade cleanroom extrusion capabilities that command premium positioning in healthcare packaging.
Polyethylene terephthalate shrink films are biaxially oriented polyester sheets engineered with controlled shrink ratios between 40% and 80% in the transverse direction, activated at temperatures of 65°C to 85°C to conform tightly to contoured containers. Their primary purpose is to deliver 360-degree printed decoration, tamper-evident sealing, and unitized multipack bundling across consumer goods distribution. Multilayer films incorporating EVOH or PVDC barrier layers capture the highest margin pools in oxygen-sensitive food applications, while monolayer formulations dominate volume in standard beverage labeling where recyclability mandates are tightening. Heat-shrinkable films above 100 microns thickness are gaining share in industrial pallet bundling as warehouses phase out polyethylene stretch wrap for load stability.
The FDA regulates PET shrink films in direct food contact applications under 21 CFR 177.1315, while the EPA tracks volatile organic compound emissions from solvent-based printing inks used on sleeve labels. Europe's REACH restrictions on phthalate plasticizers and the EU Packaging and Packaging Waste Regulation are redirecting formulation investments toward mono-material PET solutions. Stakeholders must monitor how California's SB 54 extended producer responsibility rules and emerging state-level recycled content mandates reshape specification requirements for North American beverage contracts.
Market Dynamics
Beverage bottlers across Southeast Asia are dismantling PVC label inventories and retooling shrink-labeling equipment for PET mono-material compatibility, compressing procurement timelines and rewiring supplier qualification criteria.
Growth Catalysts
- REACH and F-Gas Regulation:Europe's chemical safety and fluorinated gas restrictions are phasing out multi-layer barrier films containing PVDC, redirecting formulation R&D toward recyclable mono-material PET shrink sleeves.
- Automated shrink-labeling equipment:Vietnam and Indonesia are commissioning high-speed sleeve applicators at new bottling plants, creating concentrated demand spikes for thin-gauge PET films with precise shrink curves.
- Carbonated soft drink bottlers:Major beverage brands are mandating PET label substrates to meet corporate recyclability pledges, pulling volume away from PVC and OPS alternatives.
Market Restraints
- Ethylene glycol price volatility:Purified terephthalic acid and ethylene glycol feedstock costs swing with crude oil derivatives, squeezing film extrusion margins and complicating long-term contract pricing.
- Specialized biaxial orientation equipment scarcity:Capacity expansion timelines stretch 24-36 months due to limited suppliers of precision tenter frame systems, concentrating supply risk with German and Japanese machinery builders.
- EVOH barrier layer substitution:Oxygen-sensitive food applications still require ethylene vinyl alcohol coextrusion for shelf-life extension, complicating mono-material recyclability claims and creating regulatory friction with EU Packaging and Packaging Waste Regulation targets.
Strategic Opportunities
- Pharmaceutical-grade cleanroom extrusion:Healthcare packaging demands ultra-low particulate PET films for unit-dose blister overwrap, commanding premium pricing from contract manufacturers serving FDA-regulated drug distribution.
- Industrial pallet bundling above 100 microns:Warehouse operators are phasing out polyethylene stretch wrap in favor of heat-shrinkable PET for load stability, opening volume opportunities outside traditional beverage labeling.
- California SB 54 extended producer responsibility:State-level recycled content mandates are reshaping North American beverage contract specifications, creating first-mover advantage for suppliers with verified post-consumer PET sourcing.
Industry Challenges
- Polymer processing labor shortage:Skilled technicians for biaxial orientation line operation and quality control are scarce across Asia-Pacific, unwinding commissioning schedules for greenfield extrusion facilities.
- FDA 21 CFR 177.1315 compliance timelines:Food contact notification reviews for novel copolyester formulations extend 12-18 months, delaying commercialization of modified shrink films with enhanced clarity or barrier performance.
- Legacy solvent-based printing ink integration:Converting shrink sleeve decorators from toluene-based gravure systems to water-based or UV-cured alternatives requires capital-intensive drying equipment retrofits and color matching recalibration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polyethylene Terephthalate (PET) Shrink Films Market |
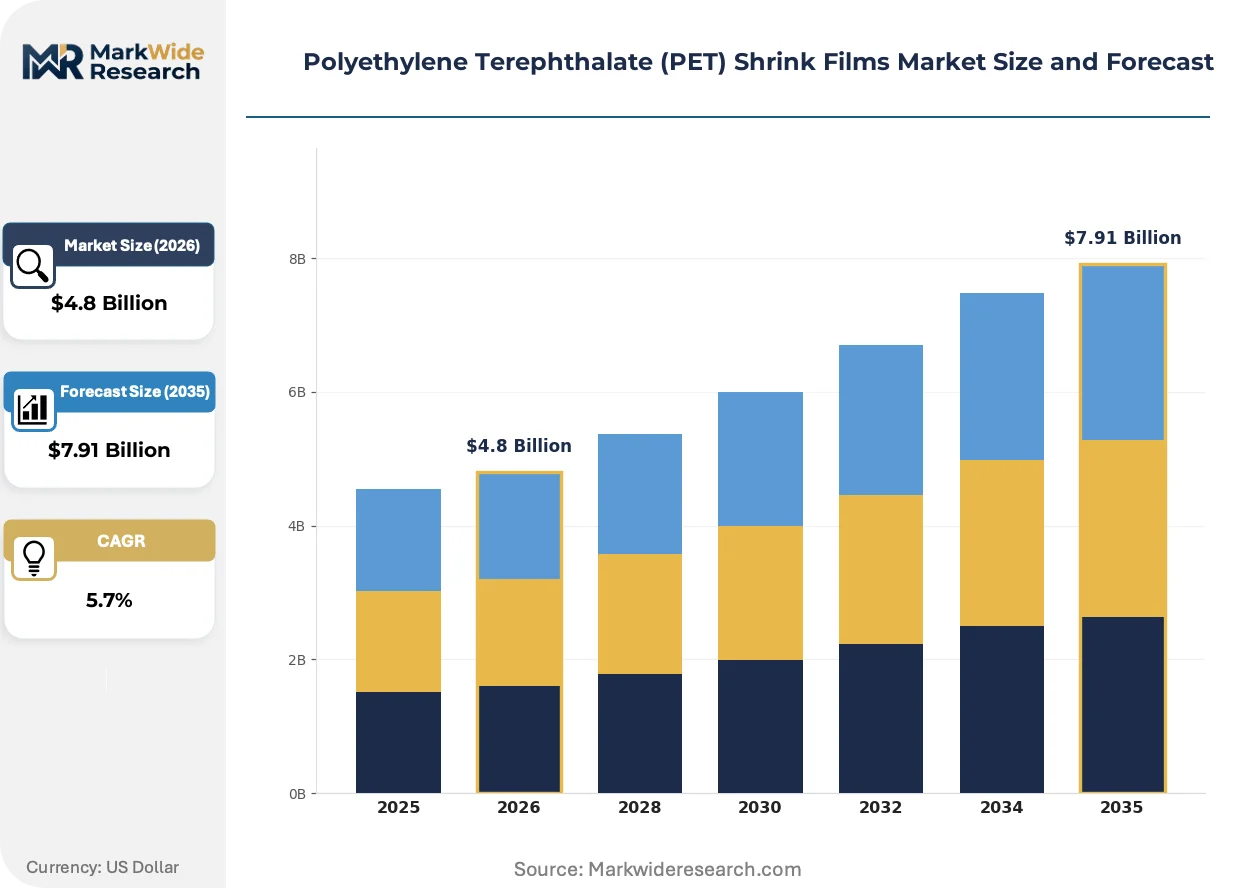
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
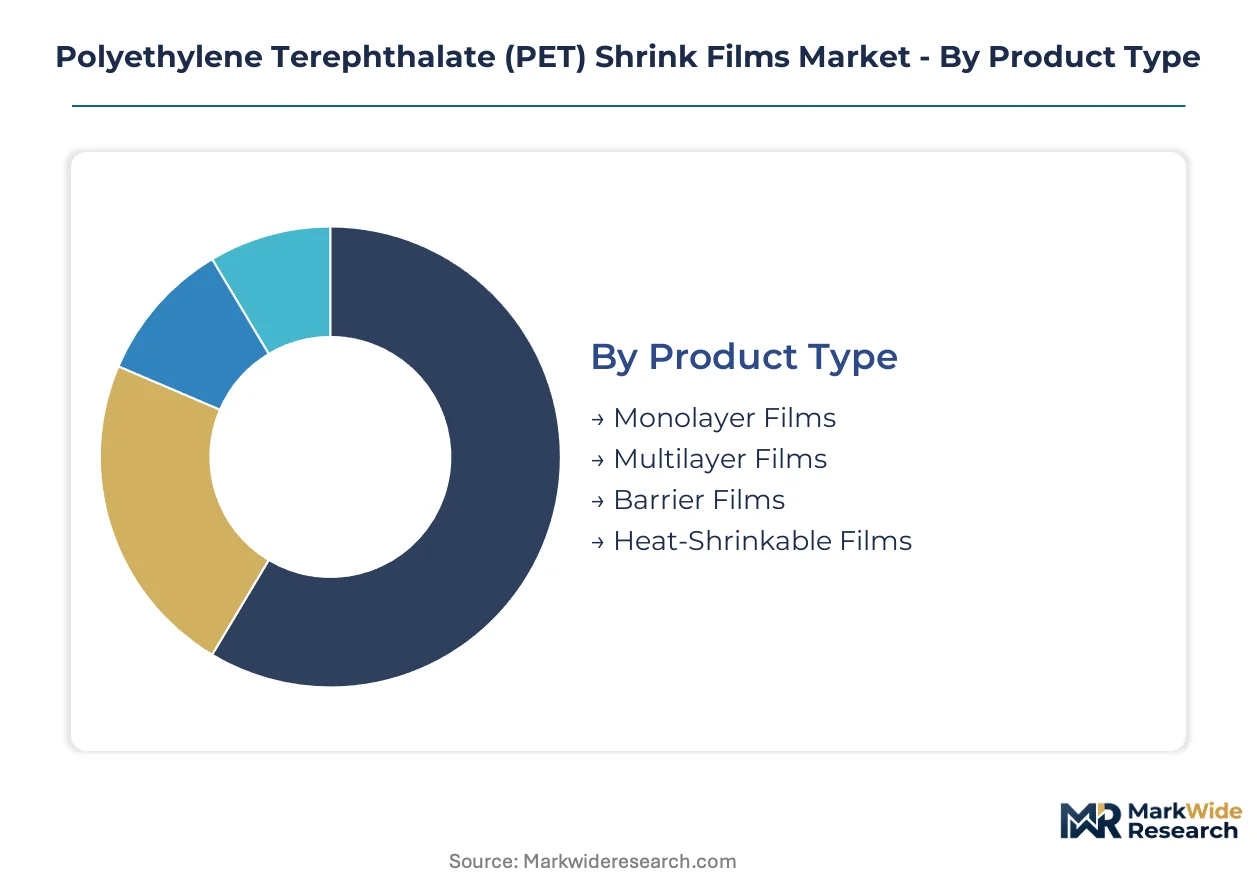
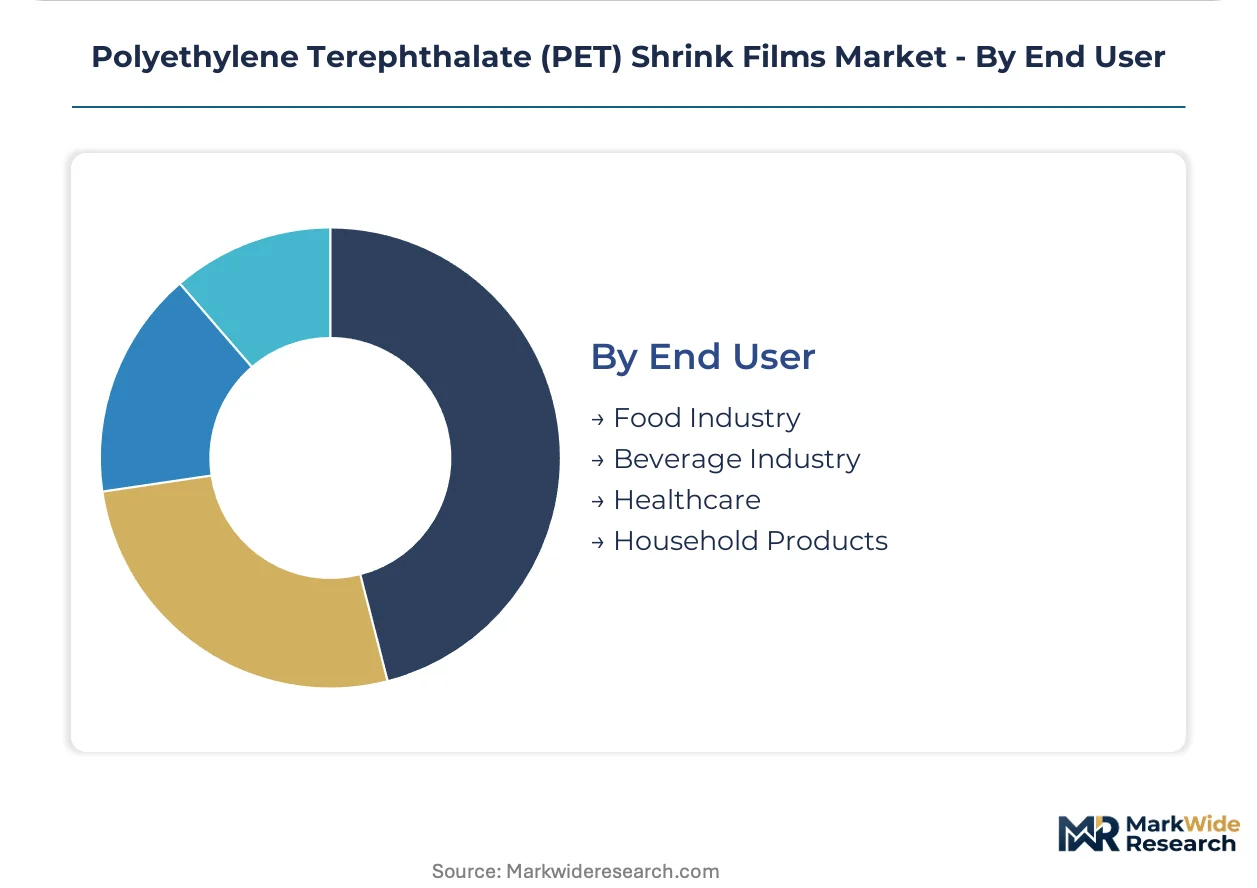
| Segmentation | Product Type: Monolayer Films, Multilayer Films, Barrier Films, Heat-Shrinkable Films Application: Food Packaging, Beverage Packaging, Consumer Goods, Industrial Packaging Thickness: Below 50 Microns, 50-100 Microns, 100-150 Microns, Above 150 Microns End User: Food Industry, Beverage Industry, Healthcare, Household Products |
| Companies Covered | Sealed Air, Amcor, Polyplex Corporation, Jindal Poly Films Limited, Cosmo Films Limited, Klöckner Pentaplast, CCL Industries, Uflex Limited, Berry Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polyethylene Terephthalate (PET) Shrink Films Market Evolving Landscape
Mono-material PET shrink films are capturing specification share from multi-layer constructions as recyclability mandates harden across beverage and personal care packaging. Equipment makers and resin suppliers are co-developing next-generation formulations with controlled shrink activation temperatures.
Digital shrink sleeve printing is supplanting traditional rotogravure for short-run promotional campaigns and SKU proliferation. Craft beverage brands and regional cosmetic marketers are adopting electrophotographic and inkjet systems with sub-5,000 unit minimums. This technology is compressing prepress lead times from weeks to hours and enabling variable data personalization that gravure cylinders cannot replicate.
Europe's F-Gas Regulation is accelerating phase-out of hydrofluorocarbon blowing agents in foam label substrates. Film extruders are reformulating with carbon dioxide or hydrocarbon expansion systems to maintain dimensional stability. Pharmaceutical and chilled dairy segments are most affected, as these categories require tamper-evident sleeve labels with precise shrink performance across refrigerated supply chains.
Brand owners are consolidating sleeve label suppliers to capture volume pricing and simplify sustainability auditing. Procurement teams at multinational beverage corporations are reducing qualified vendor lists from twenty-plus converters to fewer than ten with verified chain-of-custody certification. This concentration is most visible in North American carbonated soft drink bottling, where parent company mandates override regional purchasing autonomy.
Polyethylene Terephthalate (PET) Shrink Films Market Segmentation
PET shrink film specifications diverge sharply across procurement channels. Beverage bottlers prioritize thin-gauge mono-material films compatible with high-speed sleeve applicators, while industrial buyers source thicker heat-shrinkable grades through specialized distributors serving warehouse operations.
Product Type:
Channel flow splits between commodity resin distributors supplying standard grades and direct mill relationships for barrier-enhanced formulations.
- Monolayer Films:Single-polyester construction optimized for mechanical recycling streams. Beverage bottlers in Vietnam and Indonesia are consolidating procurement around these grades to meet corporate recyclability pledges and simplify sleeve label recovery.
- Multilayer Films:Coextruded constructions bonding PET with tie layers and functional skins. Oxygen-sensitive food applications still specify these despite EU Packaging and Packaging Waste Regulation friction, as shelf-life extension outweighs mono-material compliance targets in premium segments.
- Barrier Films:EVOH or PVDC coextrusion for modified atmosphere packaging. REACH restrictions on fluorinated compounds are compressing addressable market for PVDC-containing constructions.
- Heat-Shrinkable Films:High-shrink-force formulations activated at 65°C to 85°C. Warehouse operators phasing out polyethylene stretch wrap are pulling volume through industrial packaging distributors.
By volume, Monolayer Films leads. By growth pace, Heat-Shrinkable Films is expanding most quickly.
Application:
Cost tier segmentation separates premium barrier-enhanced specifications from standard decoration-grade procurement.
- Food Packaging:Modified atmosphere and vacuum skin applications requiring oxygen transmission rates below 1 cc/m²/day. Chilled dairy and processed meat processors in Europe are migrating from PVDC-containing multilayer films to EVOH-barrier PET to align with F-Gas Regulation phase-out timelines.
- Beverage Packaging:360-degree sleeve labels for carbonated soft drinks, bottled water, and functional beverages. Southeast Asian bottlers are dismantling PVC label inventories and retooling applicator equipment, compressing procurement timelines for thin-gauge mono-material PET.
- Consumer Goods:Tamper-evident shrink bands and multipack bundling for personal care and household products. Specification diversity here fragments procurement across regional converters.
- Industrial Packaging:Pallet unitization and load stabilization above 100 microns thickness. This segment channels through packaging distributors rather than direct mill relationships.
Food Packaging commands premium pricing per square meter. Beverage Packaging generates the highest absolute tonnage.
Thickness:
Volume concentration sits in thin-gauge specifications compatible with automated beverage labeling equipment, while margin pools concentrate in thicker industrial grades.
- Below 50 Microns:Ultra-thin constructions for high-speed sleeve applicators running above 600 bottles per minute. New bottling plants in Indonesia and Vietnam are commissioning equipment optimized for these gauges.
- 50-100 Microns:Standard beverage and consumer goods decoration grades. This band captures the majority of carbonated soft drink label procurement.
- 100-150 Microns:Medium-duty industrial bundling and heavier tamper-evident applications. Warehouse operators favor this range for pallet stability.
- Above 150 Microns:Heavy-gauge formulations for industrial load containment and specialized pharmaceutical overwrap. Cleanroom extrusion capabilities command premium positioning here.
Below 50 Microns dominates unit volume. Above 150 Microns delivers the steepest margin expansion.
End User:
Customer type segmentation separates regulated pharmaceutical procurement from commodity beverage and food processing.
- Food Industry:Processors of chilled ready-meals, fresh produce, and processed proteins. REACH compliance timelines are forcing reformulation away from legacy multilayer constructions.
- Beverage Industry:Carbonated soft drink, bottled water, and alcoholic beverage bottlers. Parent company sustainability mandates are overriding regional purchasing autonomy, consolidating supplier lists.
- Healthcare:Pharmaceutical manufacturers requiring FDA 21 CFR 177.1315 compliance and ultra-low particulate specifications. Cleanroom extrusion capabilities create supply scarcity.
- Household Products:Cleaners, detergents, and air care brands using shrink sleeves for shelf differentiation. This segment tolerates wider specification variance.
Beverage Industry generates the highest film consumption. Healthcare delivers the strongest pricing power per kilogram.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Vietnam consumes PET shrink films almost exclusively for beverage sleeve labeling, while Germany and the United States deploy substantial volumes in pharmaceutical cleanroom packaging and industrial pallet bundling. This consumption-mix differential reflects divergent manufacturing bases and regulatory stringency across geographies.
United States
Beverage bottlers in California and Texas are dismantling PVC label inventories under state-level extended producer responsibility mandates. FDA 21 CFR 177.1315 compliance timelines extend 12-18 months for novel copolyester formulations, delaying modified shrink film commercialization. The Midwest industrial corridor around Chicago is pulling thicker heat-shrinkable grades above 100 microns for warehouse pallet unitization.
Germany
Pharmaceutical manufacturers in Baden-Württemberg demand ultra-low particulate PET films for unit-dose blister overwrap. REACH restrictions on phthalate plasticizers and the EU Packaging and Packaging Waste Regulation are redirecting formulation investments toward mono-material solutions. The Rhine-Main packaging cluster around Frankfurt anchors premium barrier film development for oxygen-sensitive food applications.
Vietnam
New carbonated soft drink bottling plants in Ho Chi Minh City and Binh Duong province are commissioning automated shrink-labeling equipment optimized for thin-gauge mono-material films. Corporate recyclability pledges from multinational beverage parent companies are overriding regional purchasing autonomy. Skilled polymer processing labor scarcity is unwinding capacity expansion timelines for greenfield extrusion facilities.
Indonesia
High-speed sleeve applicators running above 600 bottles per minute are being installed at Jakarta and Surabaya bottling facilities, creating concentrated demand spikes for sub-50 micron constructions. The country's national food safety regulator enforces packaging material notification requirements that compress supplier qualification criteria. Java's manufacturing belt is consolidating procurement around verified post-consumer PET sourcing to meet brand owner sustainability auditing.
India
Specialized biaxial orientation lines in Maharashtra and Gujarat serve domestic label converters with precise shrink curve specifications. BIS certification requirements for food contact materials add regulatory friction to import substitution strategies. The Delhi-NCR industrial corridor is experiencing procurement timeline compression as beverage brands mandate PET substrates over PVC alternatives.
Polyethylene Terephthalate (PET) Shrink Films Market Competitive Landscape
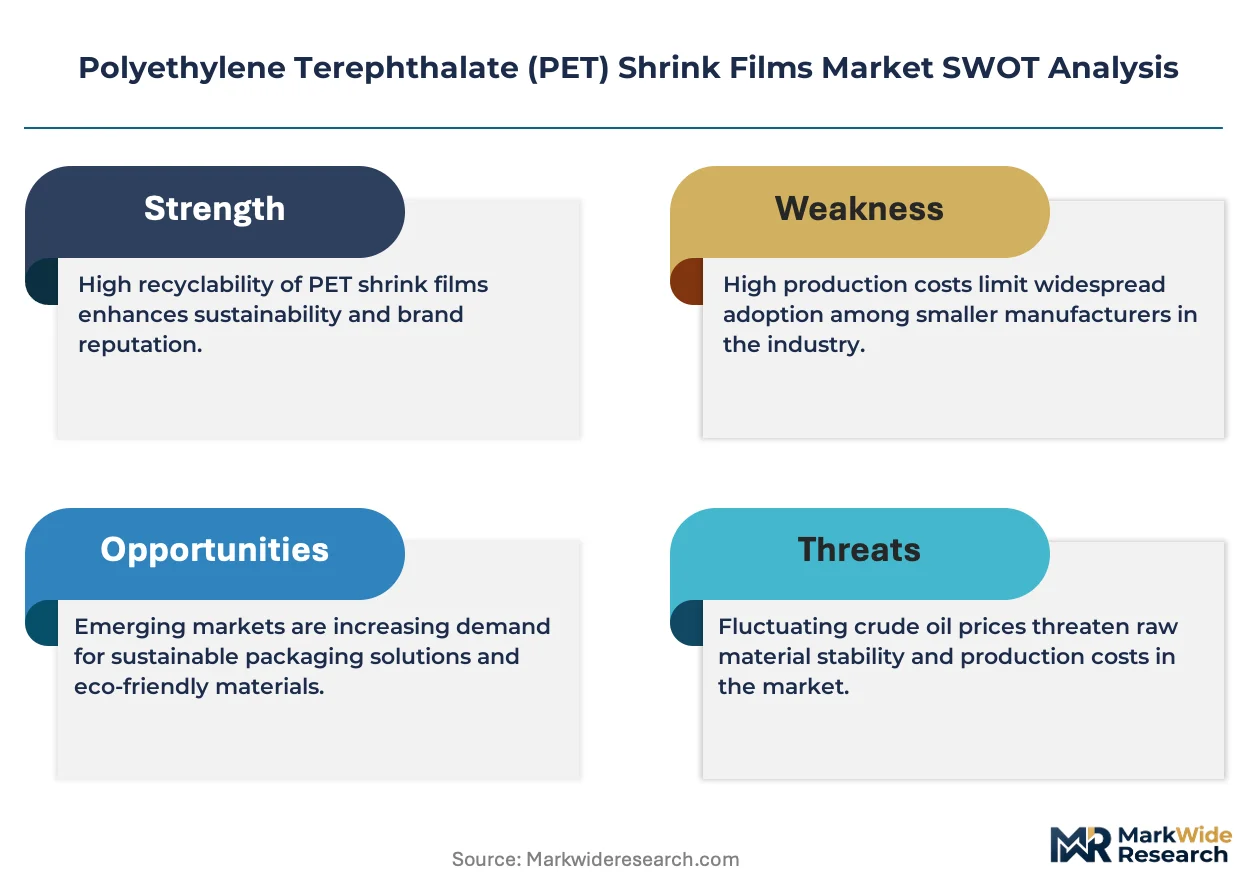
A small set of integrated leaders sits above a broader specialist tier, with backward integration into resin production separating volume players from converter-dependent competitors. The market structure concentrates supply risk with German and Japanese machinery builders for precision tenter frame systems. Three archetypes dominate: integrated multinational resin-to-film operators, regional biaxial orientation specialists, and pharmaceutical-grade cleanroom extrusion niche players. Capacity expansion and verified post-consumer PET sourcing represent the two dominant competitive moves reshaping contract positioning.
Among integrated multinational operators, Amcor exemplifies the resin-to-film archetype with captive supply security across multiple continents. Polyplex Corporation anchors South Asian demand through specialized biaxial orientation capabilities. Klöckner Pentaplast occupies a position within the premium pharmaceutical tier, with cleanroom extrusion commanding pricing power in FDA-regulated drug distribution channels.
| Leading Market Players |
|---|
| Sealed Air |
| Amcor |
| Polyplex Corporation |
| Jindal Poly Films Limited |
| Cosmo Films Limited |
| Klöckner Pentaplast |
| CCL Industries |
| Uflex Limited |
| Berry Global |
| Others |
Value Network & Pricing Analysis
Scale economies in biaxial orientation line operation concentrate pricing power among integrated resin-to-film operators with captive purified terephthalic acid supply, while smaller converter-dependent competitors face compressed margins when ethylene glycol feedstock costs swing with crude oil derivatives. Beverage bottlers in Vietnam and Indonesia are leveraging volume consolidation to extract thin-gauge mono-material PET film pricing concessions from suppliers scrambling to fill new automated sleeve-labeling equipment.
Pricing Analysis
Long-term offtake contracts dominate procurement between multinational beverage parent companies and integrated film producers, with spot market activity confined to distressed inventory and specification mismatches. Three-tier pricing structure across pharmaceutical-grade cleanroom extrusion, standard beverage decoration grades, and commodity industrial bundling reflects certification burden and particulate control requirements. Cost compression in standard beverage grades is intensifying because parent company sustainability mandates are consolidating supplier lists to fewer than ten qualified vendors. Small regional label converters exhibit highest price sensitivity, while pharmaceutical contract manufacturers accept premium positioning for FDA 21 CFR 177.1315 compliance.
Supply Chain Analysis
Precision tenter frame system availability from German and Japanese machinery builders acts as the critical capacity chokepoint, stretching greenfield extrusion facility commissioning timelines and concentrating supply risk with this limited equipment supplier base. Manufacturing gravity centers on India, Vietnam, and Germany, with each node serving distinct specification tiers from commodity beverage labels to pharmaceutical cleanroom grades. Feedstock supply rests on purified terephthalic acid and ethylene glycol derived from crude oil derivatives, plus specialized barrier resins for oxygen-sensitive applications. Single-source vulnerability runs through the concentrated precision machinery builder tier. Distribution runs through direct mill relationships for barrier-enhanced formulations and commodity resin distributors for standard grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biaxial orientation technician scarcity across Asia-Pacific is fragmenting capacity expansion timelines and creating acquisition opportunities for operators with verified training pipelines and equipment commissioning expertise.
For Market Incumbents: Consolidate backward integration into purified terephthalic acid production to insulate margins from ethylene glycol price volatility, while capturing verified post-consumer PET sourcing certification to defend contract positioning against California SB 54 recycled content mandates. Capacity addition in Vietnam and Indonesia addresses concentrated demand spikes from new bottling plant commissioning. Certification investment in pharmaceutical-grade cleanroom extrusion commands premium pricing power in healthcare packaging. For New Entrants and Emerging Players: Anchor in industrial pallet bundling above 100 microns thickness, where warehouse operators phasing out polyethylene stretch wrap create white-space demand outside beverage labeling saturation. Digital shrink sleeve printing equipment for short-run promotional campaigns offers penetrable entry against gravure-dependent incumbents. Go-to-market angle targets craft beverage brands and regional cosmetic marketers with sub-5,000 unit minimums and variable data personalization capabilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated resin-to-film operators with captive supply security over converter-dependent competitors exposed to feedstock margin compression. Long-term viability over the projection horizon hinges on verified post-consumer PET sourcing infrastructure and pharmaceutical-grade certification capabilities. Acquisition target archetype includes regional biaxial orientation specialists with installed equipment bases and underutilized capacity. Signal to watch is California SB 54 implementation pace and emerging state-level recycled content mandate adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Purified Terephthalic Acid | Insulates margin compression from ethylene glycol feedstock volatility tied to crude oil derivatives. |
| Pharmaceutical-Grade Cleanroom Certification | Captures premium pricing from FDA-regulated drug distribution channels demanding ultra-low particulate specifications. |
| Verified Post-Consumer PET Sourcing | Secures first-mover positioning under California SB 54 extended producer responsibility recycled content mandates. |
| Digital Shrink Sleeve Printing Deployment | Enables short-run promotional campaigns with sub-5,000 unit minimums for craft beverage and cosmetic brands. |
| Industrial Heat-Shrinkable Film Capacity Expansion | Addresses warehouse operator demand above 100 microns thickness phasing out polyethylene stretch wrap. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, combining extrusion line managers and beverage procurement leads with secondary validation through customs and trade data, SEC filings from listed packaging corporations, and regulatory notification databases from FDA and ECHA. Plant managers at biaxial orientation facilities, procurement directors at multinational beverage bottlers, technical R&D directors at resin suppliers, and distribution channel partners in industrial packaging provided operational perspective. Bottom-up capacity modeling triangulated against top-down demand aggregation from end-use consumption patterns.
Across the analysis window, the quantitative framework modeled volume and value trajectories through product type segmentation by monolayer versus multilayer construction, application tier across beverage and pharmaceutical end-uses, thickness specifications from sub-50 micron to above 150 micron grades, and geographic production hub clustering. CAGRs were derived from installed capacity expansion timelines, equipment utilization assumptions, and feedstock cost pass-through elasticity. Industry-specific forecast inputs incorporated REACH compliance phase-out schedules for PVDC-containing constructions and F-Gas Regulation implementation pace for barrier film reformulation.
Decision-makers should treat outputs as directional under base assumptions of sustained beverage bottler PET substrate conversion and REACH timeline adherence; material deviation in regulatory implementation or feedstock cost volatility would warrant model refresh. Practitioners should keep alternative scenarios live as California SB 54 enforcement intensity and skilled polymer processing labor availability evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Brazil Plastic Packaging Films Market
Poly film
In-Mould Label Film Market
Poly film
PET Lidding Films Market
Poly film
China BOPP Film Market
Poly film
PCR Bubble Films Market
Poly film
Biaxially Oriented Polypropylene (BOPP) Films Market
Poly film
Americas Polypropylene (PP) Films Market
Poly film
MOPP Packaging Films Market
Poly film
Polycoated Packaging Market
Poly film
Latin America Plastic Packaging Films Market
Poly film
Poland Plastic Packaging Films Market
Poly film
Peelable and Resealable Films Market
Poly film
Light Reflective Film Market
Poly film
Global Polycarbonate Sheets and Films Market
Poly film
Silicone Release Films Market
Poly film
Silicone-Coated PET Films Market