
 Resealable Films Market | 2026-2036
Resealable Films Market Size, Share, and Industry Trends Forecast 2026-2036
Resealable Films Market Analytics
Southeast Asia is tilting toward resealable film capacity as Vietnam and Thailand expand blown film extrusion parks to serve ASEAN processed-food exporters. Amcor leverages its integrated resin-to-film operations across multiple continents to secure long-term supply agreements with multinational snack brands. Berry Global sustains competitive intensity through deep specialization in high-barrier coextruded structures for protein packaging. Sealed Air anchors its position in automated packaging lines where resealable films must interface precisely with form-fill-seal equipment.
Resealable films are multilayer flexible substrates incorporating pressure-sensitive adhesives or cohesive peel-reseal coatings, typically ranging from 40 to 150 microns in total caliper, engineered to permit repeated opening and closing without compromising barrier integrity. Their primary commercial purpose centers on extending product freshness intervals while eliminating secondary storage containers for consumers. Polyethylene formulations dominate volume production due to superior heat-seal compatibility and emerging mono-material recyclability credentials, whereas nylon structures command premium positioning in modified-atmosphere meat and cheese applications where oxygen transmission rates below 5 cc/m²/day prove essential. Stand-up pouches represent the fastest-growing application vector as beverage and pet food brands abandon rigid formats, while lidding films concentrate margin pools through specialized die-cut precision and anti-fog performance requirements.
FDA food-contact substance notifications govern adhesive migration limits in US resealable food packaging, directly influencing formulation choices between solvent-based and water-based coating systems. REACH compliance across Europe restricts certain phthalate plasticizers and mandates disclosure of Substances of Very High Concern in adhesive layers, compelling reformulation investments. China's GB standards for composite food packaging materials impose parallel barrier and migration testing protocols that exporters must satisfy for market access. Stakeholders must monitor evolving extended producer responsibility frameworks and adhesive chemistry restrictions, as regulatory divergence between jurisdictions threatens to fragment formulation standardization and inflate compliance costs for global film suppliers.
Market Dynamics
Mono-material polyethylene structures are displacing legacy multilayer laminates as EU Packaging and Packaging Waste Regulation recyclability mandates harden, forcing converters to reformulate barrier coatings without sacrificing oxygen transmission performance.
Growth Catalysts
- EU Regulatory Mandates:The EU Packaging and Packaging Waste Regulation compels brand owners to specify recyclable resealable structures, accelerating converter investment in mono-material extrusion lines.
- Fresh Produce Retail:North American supermarket chains specify resealable lidding to reduce shrink and extend shelf appearance intervals for berries and leafy greens.
- Stand-Up Pouch Conversion:Beverage and pet food brands abandon rigid formats for flexible resealable pouches, driving blown film capacity expansion across ASEAN processing hubs.
Market Restraints
- Adhesive Input Volatility:Pressure-sensitive adhesive formulations depend on petroleum-derived tackifier resins subject to crack spread fluctuations.
- Barrier Performance Trade-Offs:Mono-material polyethylene structures cannot achieve sub-5 cc/m²/day oxygen transmission rates without nylon or EVOH coextrusion layers.
- Migration Testing Burden:China's GB standards for composite food packaging impose parallel testing protocols that extend product qualification timelines for exporters.
Strategic Opportunities
- ASEAN Processing Hub Expansion:Vietnam and Thailand blown film extrusion parks can capture processed-food exporter demand from Indonesia and Philippines brand owners.
- Automated Packaging Line Integration:Form-fill-seal equipment OEMs require precision-matched resealable film specifications, creating specification lock-in for qualified suppliers.
- Extended Producer Responsibility Tailwinds:Germany's packaging ordinance imposes strict recyclability quotas that favor domestic converters with established mono-material capabilities.
Industry Challenges
- Coextrusion Die Engineering Scarcity:Seven- and nine-layer blown film die design expertise concentrates among aging specialist engineers in Germany and Austria.
- REACH Compliance Reformulation Costs:Substances of Very High Concern disclosure mandates in adhesive layers force iterative migration testing that consumes 18-24 month development cycles.
- Legacy Equipment Retrofit Friction:Solvent-based coating lines require VOC abatement investments to meet EPA National Emission Standards for Hazardous Air Pollutants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Resealable Films Market |
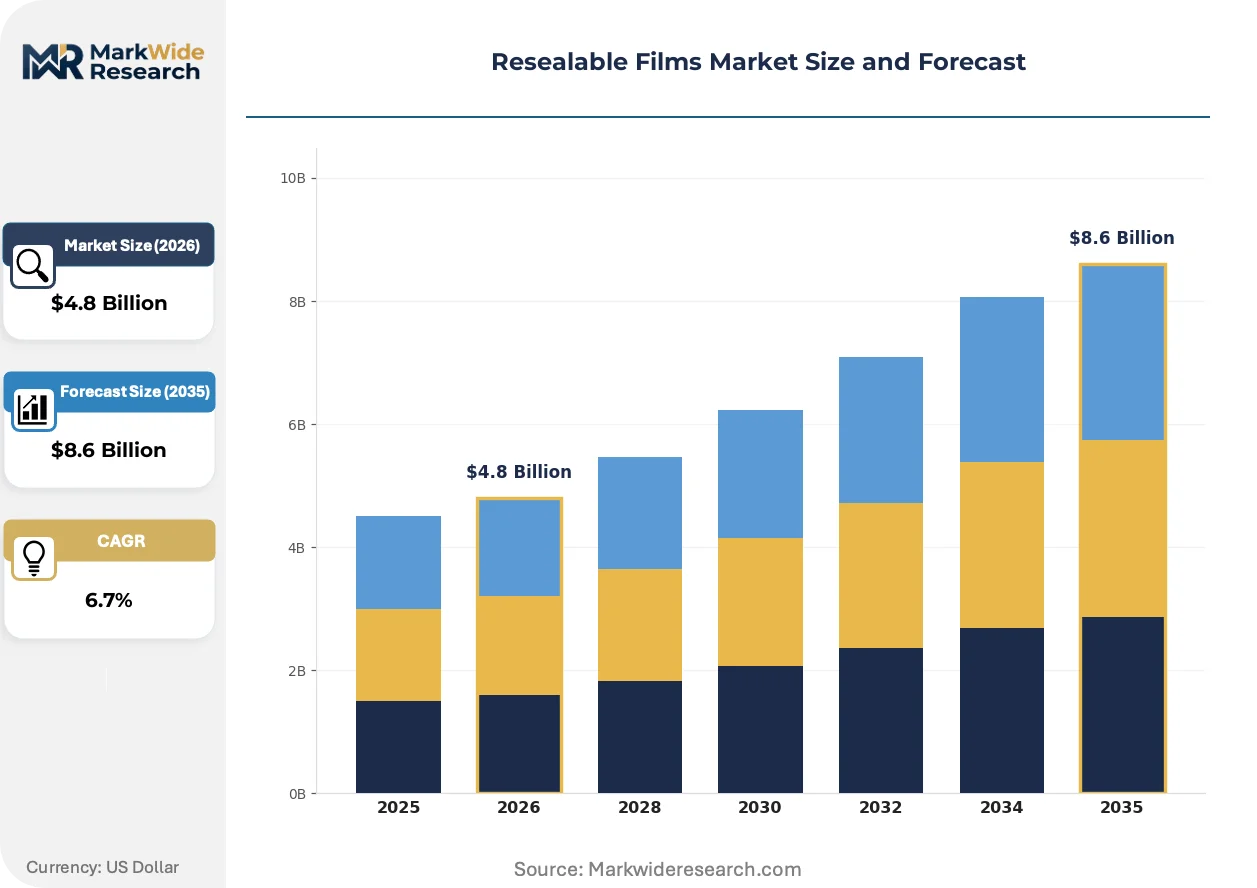
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Nylon, Paper End Use Industry: Food Packaging, Personal Care, Healthcare, Consumer Goods Formulation Type: Solvent-Based, Water-Based, Hot Melt, Pressure Sensitive Application: Stand-Up Pouches, Lidding Films, Shrink Films, Wraps |
| Companies Covered | Amcor, Berry Global, Sealed Air, Mondi Group, Coveris, Winpak Ltd, Constantia Flexibles, Huhtamaki, Dow, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Resealable Films Market Evolving Landscape
Digital printing and inline inspection systems are compressing minimum order quantities while enabling mass customization of resealable graphics, fundamentally altering converter economics and brand owner procurement patterns.
Laser-scored easy-open features paired with cohesive peel-reseal coatings are digitizing quality control protocols across high-speed packaging lines. Snack food manufacturers in the United States deploy machine vision systems to verify seal integrity at 600 pouches per minute. This sensor integration is digitizing defect detection, collapsing rejection response times from hours to milliseconds.
REACH restrictions on phthalate plasticizers and ECHA disclosure mandates for Substances of Very High Concern are compelling adhesive suppliers to migrate toward water-based coating systems. European converters face reformulation investments exceeding seven figures per product line. Modified-atmosphere meat and cheese packaging segments absorb these costs fastest due to premium positioning and price elasticity.
Direct-to-retail procurement models are consolidating specification authority among multinational snack and pet food brand technical teams. Regional distributors lose influence as buyers centralize film qualification at corporate headquarters in Chicago and Rotterdam. This concentration is most visible in North American protein packaging, where three brand owners now dictate barrier specifications for two-thirds of resealable lidding volume.
Resealable Films Market Segmentation
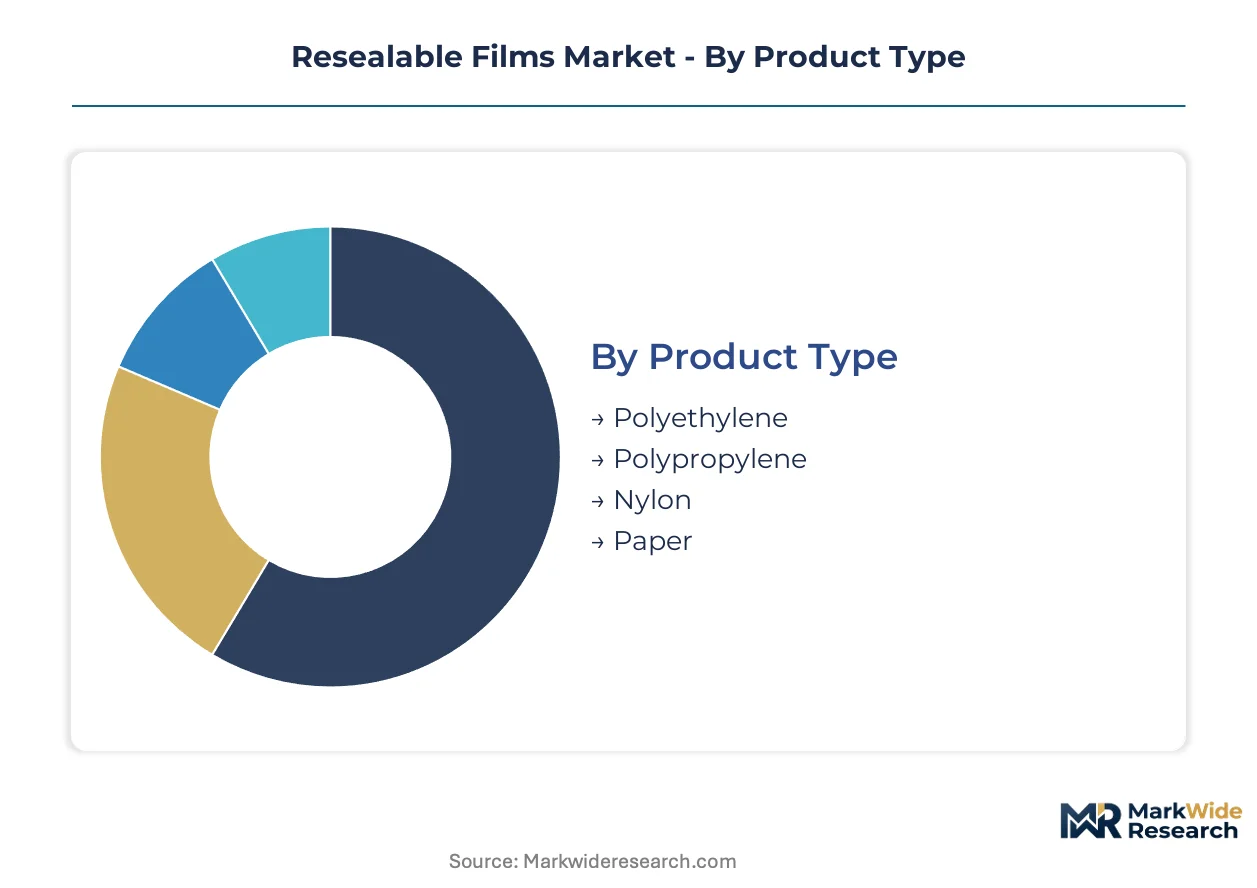
Resealable films serve heterogeneous performance requirements across barrier sensitivity, seal integrity cycles, and regulatory exposure. Segmentation reveals where formulation investments concentrate versus where commodity substitution pressures dominate.
Product Type:
Polyethylene formulations turn inventory fastest due to standardized mono-material specifications, while nylon structures sit longer in qualification pipelines for modified-atmosphere applications.
- Polyethylene:Dominates blown film extrusion through superior heat-seal compatibility and emerging recyclability credentials under EU Packaging and Packaging Waste Regulation mandates. Fresh produce lidding across Germany and North American supermarket chains absorbs the highest volumes as retailers specify extended shelf appearance intervals.
- Nylon:Commands premium positioning in coextruded structures achieving oxygen transmission rates below 5 cc/m²/day. Modified-atmosphere meat and cheese packaging in European protein processing facilities depends on nylon's barrier performance where EVOH coextrusion layers prove cost-prohibitive.
- Polypropylene:Offers higher temperature resistance for hot-fill applications and retort pouches. Personal care wipe packaging in ASEAN processing hubs specifies biaxially oriented polypropylene for stiffness and moisture barrier.
- Paper:Serves sustainability-positioned premium brands requiring fiber-based substrates with resealable functional coatings. Organic grocer private labels in France and Switzerland specify paper-based lidding for shelf differentiation.
Polyethylene anchors the volume base while nylon gains share at the steepest rate among premium barrier applications.
End Use Industry:
Food packaging commands the steepest margin tiers through migration testing burdens and barrier precision requirements, whereas consumer goods tolerates broader specification variance.
- Food Packaging:Concentrates specification authority among multinational brand technical teams in Chicago and Rotterdam. Snack food, fresh produce, and protein segments drive qualification cycles exceeding 18 months for adhesive migration compliance under FDA and REACH frameworks.
- Personal Care:Wipe and cosmetic brands specify resealable lidding for moisture retention and dispensing convenience. Water-based adhesive formulations dominate this segment due to lower barrier requirements and faster regulatory approval timelines.
- Healthcare:Medical device and pharmaceutical packaging demands sterile barrier validation and traceable adhesive chemistry. FDA 21 CFR Part 177 compliance for indirect food additives parallels healthcare migration testing protocols.
- Consumer Goods:Household product brands adopt resealable formats for concentrated refills and storage convenience. Price elasticity permits broader adhesive formulation variance compared to food-contact applications.
Food packaging absorbs the dominant revenue share while personal care climbs fastest on wet wipe format conversion.
Formulation Type:
Water-based systems accelerate through regulatory tailwinds as solvent-based coatings face VOC abatement retrofit costs.
- Solvent-Based:Legacy coating infrastructure across older European and North American converter facilities depends on petroleum-derived tackifier resins. EPA National Emission Standards for Hazardous Air Pollutants impose capital-intensive abatement investments that compress margins.
- Water-Based:REACH restrictions on phthalate plasticizers and ECHA Substances of Very High Concern disclosure mandates propel migration toward aqueous adhesive systems. European converters absorb seven-figure reformulation investments per product line.
- Hot Melt:Delivers immediate tack without solvent drying stages, suiting high-speed form-fill-seal lines. Automated packaging equipment in Vietnam and Thailand processing hubs specifies hot melt compatibility for throughput optimization.
- Pressure Sensitive:Enables repeated open-close cycles without heat reactivation. Berry Global and Sealed Air concentrate proprietary formulation expertise in this segment for protein and snack applications.
Solvent-based formulations retain installed base dominance while water-based alternatives expand most quickly on regulatory compliance tailwinds.
Application:
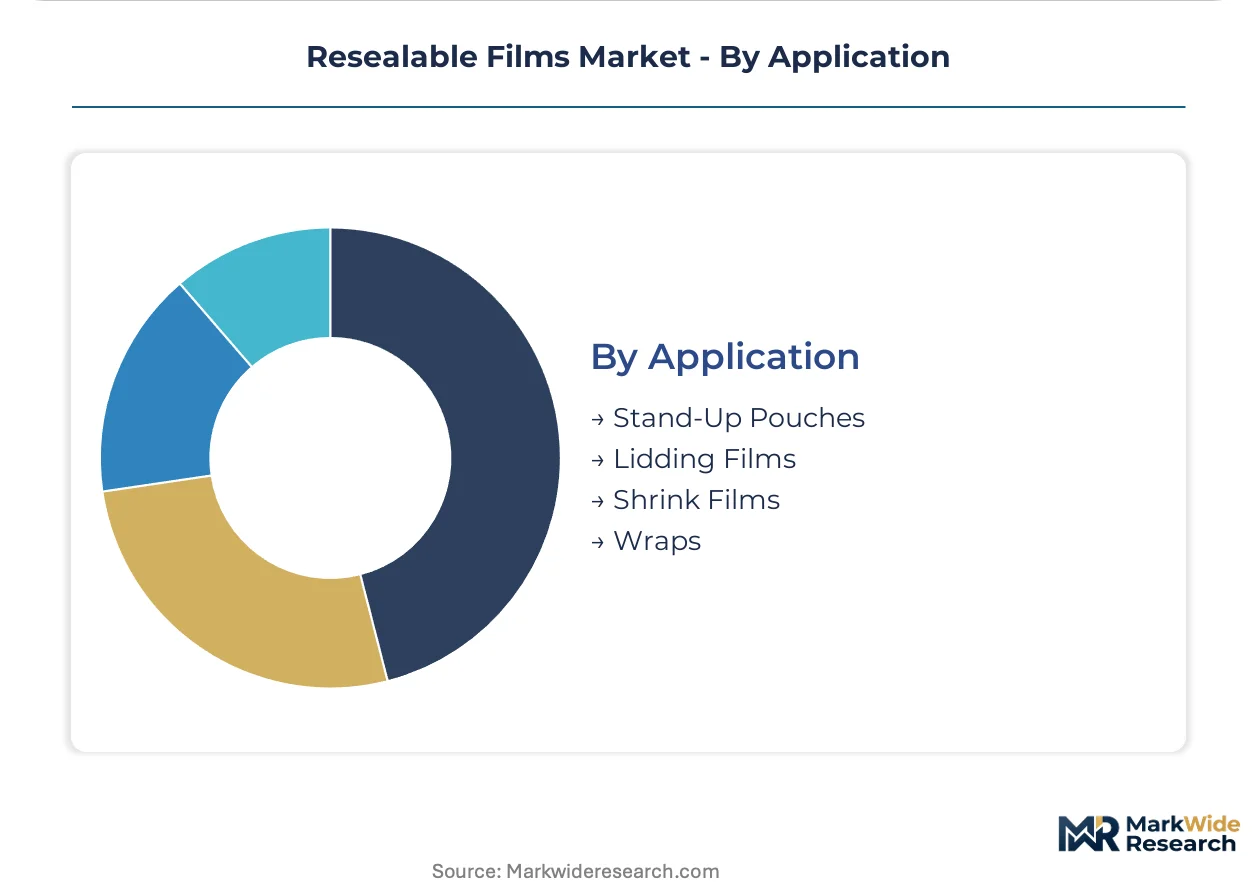
Stand-up pouches compress design-to-production cycles through digital printing integration, whereas lidding films extend timelines through die-cut precision requirements.
- Stand-Up Pouches:Beverage and pet food brands abandon rigid formats for flexible resealable structures. ASEAN blown film capacity expansion in Vietnam and Thailand targets this application vector for regional processed-food exporters.
- Lidding Films:Require specialized die-cut precision and anti-fog performance for retail shelf visibility. German organic grocers and North American supermarket chains specify resealable lidding for berry and leafy green packaging to reduce shrink.
- Shrink Films:Combine resealable features with secondary bundling functionality for multi-pack collation. Beverage multipacks in Mexico and Brazil specify shrink formats with easy-open resealable tabs.
- Wraps:Serve fresh meat and cheese counter applications where retail staff apply resealable overwrap at point of sale. Modified-atmosphere specifications in French and Italian retail chains drive barrier coating complexity.
Lidding films capture the highest margin concentration while stand-up pouches demonstrate the steepest volume expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's container throughput anchors European flexible packaging distribution, while Vietnam's Cai Mep-Thi Vai deepwater port complex underwrites ASEAN blown film export capacity expansion.
United States
North American supermarket chains specify resealable lidding for berries and leafy greens to reduce retail shrink. FDA food-contact substance notifications govern adhesive migration limits, directly influencing solvent-versus-water-based formulation choices. Chicago anchors multinational brand technical teams that centralize film qualification authority for protein packaging specifications.
Germany
German organic grocers and discount retailers drive mono-material polyethylene adoption for extended shelf appearance. The national packaging ordinance imposes strict recyclability quotas under extended producer responsibility frameworks. Bavarian and North Rhine-Westphalian converter clusters concentrate seven- and nine-layer blown film die engineering expertise.
Vietnam
ASEAN processed-food exporters source blown film capacity from Vietnam's expanding extrusion parks for stand-up pouch conversion. The country's national standards body enforces composite food packaging testing protocols parallel to GB standards for export market access. Ho Chi Minh City industrial zones attract form-fill-seal equipment integration projects serving Indonesian and Philippine brand owners.
China
Domestic snack and beverage brands abandon rigid formats for flexible resealable structures at scale. GB standards for composite food packaging materials impose barrier and migration testing that extends qualification timelines for converters. Yangtze River Delta manufacturing clusters house resin-to-film integrated operations supplying both domestic demand and export markets.
Thailand
Thai processing hubs serve regional pet food and beverage exporters converting to stand-up pouch formats. The national industrial standards institute aligns with ASEAN harmonized protocols for food-contact materials. Bangkok and Eastern Economic Corridor extrusion facilities expand hot-melt adhesive coating capacity for high-speed automated packaging lines.
Resealable Films Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material supply and precision coating. The vendor base concentrates among resin-integrated multinationals and regional blown film specialists, with tiering based on barrier formulation depth and equipment integration capability. Three archetypes dominate: integrated resin-to-film platforms, high-barrier coextrusion specialists, and automated packaging line integrators. Competitive moves center on mono-material extrusion line investments and strategic partnerships with form-fill-seal equipment OEMs.
Among integrated packaging platforms, Amcor leverages captive resin operations across multiple continents, while Berry Global occupies a position in high-barrier coextruded structures. Sealed Air anchors the automated packaging integration tier where film specifications must interface precisely with form-fill-seal equipment. These three represent distinct competitive archetypes: upstream material control, barrier performance specialization, and downstream equipment synchronization.
| Leading Market Players |
|---|
| Amcor |
| Berry Global |
| Sealed Air |
| Mondi Group |
| Coveris |
| Winpak Ltd |
| Constantia Flexibles |
| Huhtamaki |
| Dow |
| Others |
Value Network & Pricing Analysis
Petroleum-derived tackifier resin volatility determines both pricing tier spreads and supply chain shape across resealable film manufacturing, forcing converters to balance long-term adhesive contracts against spot-market exposure while EU recyclability mandates reshape raw material sourcing geography.
Pricing Analysis
Volume-discount tiering structures stratify across premium, standard, and economy levels in resealable films. Three-tier pricing separates high-barrier nylon coextrusions for modified-atmosphere meat packaging from commodity polyethylene lidding and basic hot-melt formulations for consumer goods. Price differentiation hinges on oxygen transmission certification tiers and migration testing completion under FDA and REACH frameworks. Cost compression in standard-grade polyethylene is intensifying because ASEAN capacity expansion feeds oversupply into export markets. Private-label supermarket chains exhibit highest price sensitivity, while pharmaceutical and medical device packaging buyers absorb premium tiers due to sterile barrier validation requirements.
Supply Chain Analysis
Export-control restrictions on advanced coextrusion die technology limit flows of seven- and nine-layer blown film engineering expertise from Germany and Austria to emerging Asian markets. Manufacturing concentrates in Germany, Vietnam, and Thailand, with German converters feeding EU recyclability mandates and ASEAN hubs serving processed-food exporters. Raw material dependencies draw from Saudi Arabian polyethylene resin, South Korean EVOH barrier polymers, and Malaysian petroleum-derived tackifier resins. Single-source vulnerability concentrates in specialized die engineering talent pools. Distribution runs through Rotterdam's container terminals for European flexible packaging and Cai Mep-Thi Vai for ASEAN export capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Resealable films represent a platform-economics inflection where form-fill-seal equipment OEMs are consolidating specification authority, creating interoperability lock-in that favors converters with embedded automation partnerships over standalone film suppliers.
For Market Incumbents: Pre-empt specification consolidation by embedding technical teams directly with form-fill-seal equipment OEMs in Chicago and Rotterdam. Deepen captive resin operations to offset petroleum-derived tackifier volatility. Secure long-term supply agreements with multinational snack brands before ASEAN capacity fully ramps.
For New Entrants and Emerging Players: Build out water-based adhesive coating capabilities to capture reformulation demand from European converters facing REACH compliance costs. Target German organic grocer private labels with paper-based resealable lidding solutions. Lead with sustainability certifications rather than price competition.
For Investors and Strategic Acquirers: EU Packaging and Packaging Waste Regulation enforcement reshapes the acquisition landscape toward mono-material polyethylene specialists with established recyclability credentials. Five-to-ten-year viability favors converters with backward integration into resin operations and embedded equipment partnerships. Monitor ECHA Substances of Very High Concern disclosure expansion as the signal for accelerated adhesive chemistry migration costs.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Extrusion Line Investment | EU recyclability mandates under the Packaging and Packaging Waste Regulation compel converter capital allocation toward polyethylene-only structures. |
| Water-Based Adhesive Reformulation | REACH restrictions on phthalate plasticizers force seven-figure product line investments to maintain European market access. |
| Form-Fill-Seal Equipment Partnership | Precision-matched film specifications create specification lock-in with OEMs in Ho Chi Minh City and Bangkok industrial zones. |
| Backward Integration into Resin Operations | Captive polyethylene supply hedges petroleum-derived input volatility and secures long-term multinational brand agreements. |
| ASEAN Processing Hub Expansion | Vietnam and Thailand blown film parks capture regional processed-food exporter demand from Indonesian and Philippine brand owners. |
Research Methodology
A standing panel of blown film extrusion engineers, adhesive formulation chemists, supermarket category buyers, and form-fill-seal equipment OEM technical directors provided ongoing calibration. Primary interviews with resin procurement managers at multinational snack brands and migration testing specialists at European certification bodies combined with secondary validation from EU Packaging and Packaging Waste Regulation implementation documents, FDA food-contact substance notification databases, ECHA Substance of Very High Concern candidate lists, and ASEAN harmonized food-contact material standards. Bottom-up capacity and demand modeling triangulated against top-down trade flow analysis.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning material type, formulation chemistry, end-use industry, application format, and regional regulatory cluster. CAGRs derived from installed capacity expansion schedules, brand owner procurement pattern shifts, and equipment OEM order backlogs. Forecast inputs incorporated mono-material extrusion line commissioning timelines and REACH compliance reformulation cycle durations.
Practitioners should monitor EU extended producer responsibility quota tightening and ECHA disclosure list expansion for early signals of accelerated industry restructuring. Forecasts reflect assumptions regarding adhesive chemistry migration timelines and ASEAN capacity ramp schedules. Material shifts in EU recyclability mandate enforcement stringency or petroleum resin crack spread volatility would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Poly film
Light Reflective Film Market
Poly film
Polycoated Packaging Market
Poly film
Poly Coated Paper Market
Poly film
Cast Stretch Packaging Films Market
Poly film
Recyclable Lidding Films Market
Poly film
Nylon Films Market
Poly film
Isotropic Film Market
Poly film
Global Sound Insulation PVB Film Market
Poly film
North America Shrink and Stretch Film Market
Poly film
Nylon Films for Liquid Packaging Market
Poly film
Global Specialty Films Polymer Market
Poly film
Easy Peel Film Packaging Market
Poly film
Polyester Film Market
Poly film
Thermoforming Films Market
Poly film
Blown Film Extruder Market
Poly film
Japan Plastic Packaging Film Market